
 Advanced Satellite Market | 2026-2036
Advanced Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Satellite Market Insights
Direct-to-device service channels are reshaping how satellite capacity reaches end users, bypassing traditional ground infrastructure and terminal resellers. SpaceX leverages its Starship manufacturing scale to drive launch cost curves downward for constellation replenishment. Lockheed Martin Corporation anchors classified government demand through specialized geostationary platforms with hardened payloads. Boeing Satellite Systems competes in the high-throughput GEO segment where margin pools remain concentrated among three contractors.
Advanced satellites encompass spacecraft operating across geostationary, low Earth, medium Earth, and highly elliptical orbits, typically incorporating solar array power systems generating 3-25 kilowatts and employing electric or chemical propulsion for station-keeping and orbital transfer maneuvers. These systems serve commercial telecommunications, Earth observation, and precision navigation missions requiring sustained on-orbit presence. Low Earth Orbit platforms now dominate launch manifests as operators pursue reduced latency for broadband services. Communication Transponders represent the largest payload value pool, though Earth Observation Sensors register the fastest end-user demand growth from climate monitoring and agricultural analytics.
The FCC governs spectrum allocation and orbital debris mitigation for US-registered spacecraft, while the FAA regulates launch licensing under revised Part 450 rules that consolidate commercial access procedures. European operators navigate ESA procurement frameworks and ITU coordination mechanisms for shared spectrum assignments. Stakeholders must monitor evolving debris remediation mandates and dual-use export control classifications that determine market access for sensitive payload technologies.
Market Dynamics
Launch cadence acceleration from reusable heavy-lift vehicles is compressing constellation deployment timelines from years to months, forcing incumbent operators to abandon incremental upgrade paths in favor of full architecture replacements.
Growth Catalysts
- FCC Part 25 licensing reforms:Streamlined small-satellite approval processes cut regulatory review periods for commercial operators seeking rapid orbital deployment.
- Defense procurement acceleration:NATO member states are expanding secure communication constellation orders to replace legacy geostationary assets with proliferated low Earth orbit architectures.
- Direct-to-device service expansion:Smartphone-integrated satellite connectivity eliminates ground terminal intermediaries, opening consumer mass markets previously blocked by hardware cost barriers.
Market Restraints
- Launch supply concentration:Heavy reliance on single-provider reusable launch infrastructure creates bottleneck vulnerability for constellation replenishment schedules.
- Solar array input cost volatility:Gallium arsenide and triple-junction cell supply chains face price pressure from competing terrestrial photovoltaic demand.
- Orbital debris remediation mandates:Emerging post-mission disposal requirements impose propulsion mass penalties that reduce payload capacity or extend mission development timelines.
Strategic Opportunities
- Climate monitoring analytics:Earth observation sensor demand from agricultural and insurance verticals remains underpenetrated relative to telecommunications applications.
- India's space sector liberalization:Private launch participation reforms and spectrum allocation clarity create entry pathways for foreign constellation operators.
- Electric propulsion convergence:Hall-effect thruster advances combined with on-orbit refueling concepts enable extended mission lifespans beyond chemical propulsion limits.
Industry Challenges
- Propulsion systems engineering scarcity:Specialized expertise in electric orbit-raising maneuvers and station-keeping optimization commands premium compensation that strains mid-tier operator budgets.
- ITU coordination timeline compression:Accelerated filing deadlines for spectrum priority rights force premature architectural commitments before payload technologies mature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Satellite Market |
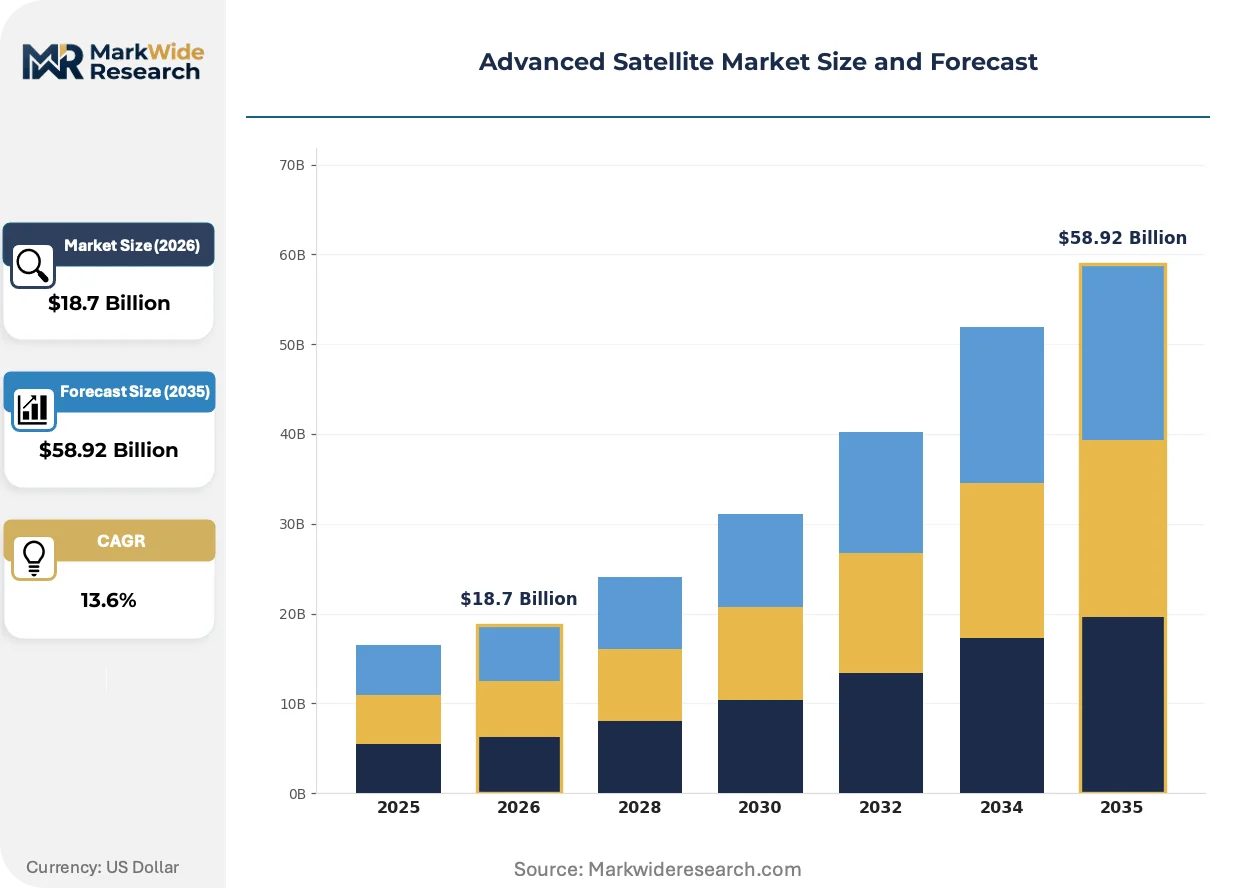
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Geostationary, Low Earth Orbit, Medium Earth Orbit, Highly Elliptical Orbit Payload Type: Communication Transponders, Earth Observation Sensors, Scientific Instruments, Navigation Modules Application: Telecommunications, Remote Sensing, Scientific Research, Positioning & Navigation End User: Government Agencies, Telemetry Operators, Space Research Institutes, Commercial Enterprises |
| Companies Covered | SpaceX, Lockheed Martin Corporation, Airbus Defence and Space, Northrop Grumman, Thales Alenia Space, Boeing Satellite Systems, Maxar Technologies, L3Harris Technologies, Planet Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Satellite Market Trends and Innovations
Constellation operators are abandoning monolithic spacecraft architectures in favor of standardized small-satellite platforms that enable rapid technology refresh cycles and distributed risk profiles across orbital planes.
Phased-array antenna systems with electronic beam-steering capabilities are replacing mechanically steered dish antennas on user terminals. Maritime and aviation integrators are adopting these flat-panel units for mobility applications where form factor constraints previously blocked satellite service penetration. This transition is rendering obsolete the ground terminal reseller networks that historically managed installation complexity for enterprise customers.
The EU's CSRD sustainability disclosure requirements are extending to space hardware supply chains, mandating carbon footprint documentation for launch services and on-orbit operations. European constellation operators must now integrate life-cycle assessment protocols into procurement specifications. This pressure is most acute for geostationary platform manufacturers serving ESA frameworks, where environmental criteria now factor alongside technical performance in bid evaluations.
Enterprise buyers are unbundling satellite capacity procurement from managed service contracts, preferring direct access to raw transponder or beam capacity through software-defined networking interfaces. This disintermediation pressures traditional service providers who previously captured margin through integrated ground segment operations. The shift is most visible in North American energy and mining verticals, where in-house network engineering capabilities now support self-managed connectivity solutions.
Advanced Satellite Market Segmentation
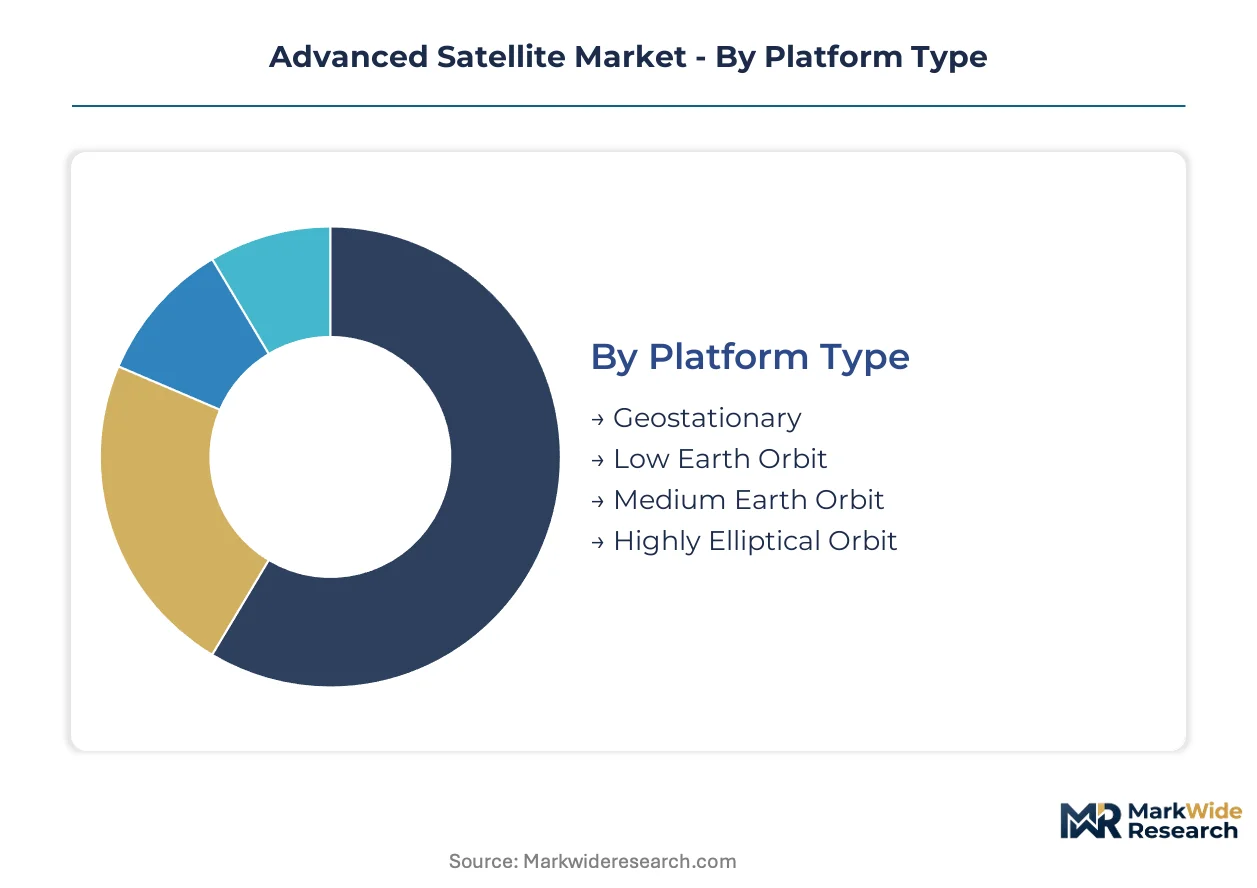
Segmentation reveals how satellite operators align platform architectures with payload economics and procurement patterns. Each dimension exposes distinct margin structures and service intensity requirements that shape vendor strategies.
Platform Type:
After-sales service intensity varies dramatically across orbital regimes, with geostationary platforms demanding continuous station-keeping support while proliferated low Earth constellations require rapid replenishment logistics.
- Geostationary:Fixed orbital position at 35,786 kilometers enables persistent regional coverage with minimal ground tracking infrastructure. Defense procurement agencies in the United States anchor demand for hardened GEO platforms carrying classified payloads, though launch mass constraints limit technology refresh cycles to decade-long intervals.
- Low Earth Orbit:Altitudes below 2,000 kilometers reduce signal latency for broadband services but require dense constellation architectures. SpaceX and Amazon's Project Kuiper drive manufacturing scale economics through standardized small-satellite production in the United States.
- Medium Earth Orbit:Intermediate altitude band optimizes navigation constellation geometry with fewer satellites than LEO equivalents. GPS and Galileo systems occupy this regime.
- Highly Elliptical Orbit:Elongated orbital paths deliver extended dwell time over high latitudes where geostationary coverage degrades. Russian Molniya heritage informs current Arctic communication applications.
Geostationary platforms hold the largest share; momentum sits with Low Earth Orbit architectures.
Payload Type:
Payload economics stratify by semiconductor content and calibration complexity, with sensor arrays commanding premium service contracts versus commoditized transponder capacity.
- Communication Transponders:Radio frequency repeaters with bent-pipe or regenerative processing architectures generate the dominant revenue pool across commercial and defense applications. Direct-to-device service expansion in the United States is reshaping transponder specifications toward smartphone-compatible power levels.
- Earth Observation Sensors:Multispectral, hyperspectral, and synthetic aperture radar instruments capture reflected or emitted electromagnetic signatures. Agricultural analytics firms and climate monitoring agencies in the United States and European Union drive demand for sub-meter resolution capabilities.
- Scientific Instruments:Specialized payloads for astrophysics, heliophysics, and planetary science missions. NASA and ESA procurement frameworks dominate this segment.
- Navigation Modules:Atomic clock payloads and inter-satellite ranging equipment enable precision positioning services. Dual-use military-civilian applications constrain export control classifications.
Communication Transponders hold the largest share; Earth Observation Sensors are expanding most quickly.
Application:
Application segmentation tracks how end users bundle ground infrastructure with orbital capacity, with telecommunications buyers increasingly self-managing network operations.
- Telecommunications:Broadband trunking, direct-to-home broadcast, and mobile backhaul services constitute the foundational commercial application. FCC Part 25 licensing reforms in the United States accelerate deployment timelines for constellation operators.
- Remote Sensing:Earth imaging and signal intelligence collection for agriculture, insurance, and defense verticals. Maritime domain awareness applications concentrate demand in coastal United States and European Union markets.
- Scientific Research:Space weather monitoring, gravitational mapping, and astronomical observation missions. NASA and ESA anchor procurement through competed mission opportunities.
- Positioning & Navigation:Precision timing and location services enabling financial transactions, aviation routing, and autonomous vehicle operations. Critical infrastructure dependency drives government ownership of core constellation assets.
Telecommunications holds the largest share; Remote Sensing gains share fastest.
End User:
End user segmentation distinguishes procurement authority structures, with government agencies mandating domestic supply chain content while commercial enterprises prioritize unit economics.
- Government Agencies:Defense and civilian space organizations with classified mission requirements and sovereign capability mandates. NATO member states are accelerating secure communication constellation orders.
- Telemetry Operators:Commercial ground station networks selling tracking, data relay, and command services to constellation owners. Ground segment specialization enables asset-light satellite business models.
- Space Research Institutes:Academic and nonprofit organizations accessing orbital platforms through rideshare or hosted payload arrangements. Technology demonstration missions dominate this category.
- Commercial Enterprises:Energy, mining, maritime, and aviation verticals procuring connectivity or imagery as operational inputs. North American energy sector buyers increasingly unbundle capacity procurement from managed service contracts.
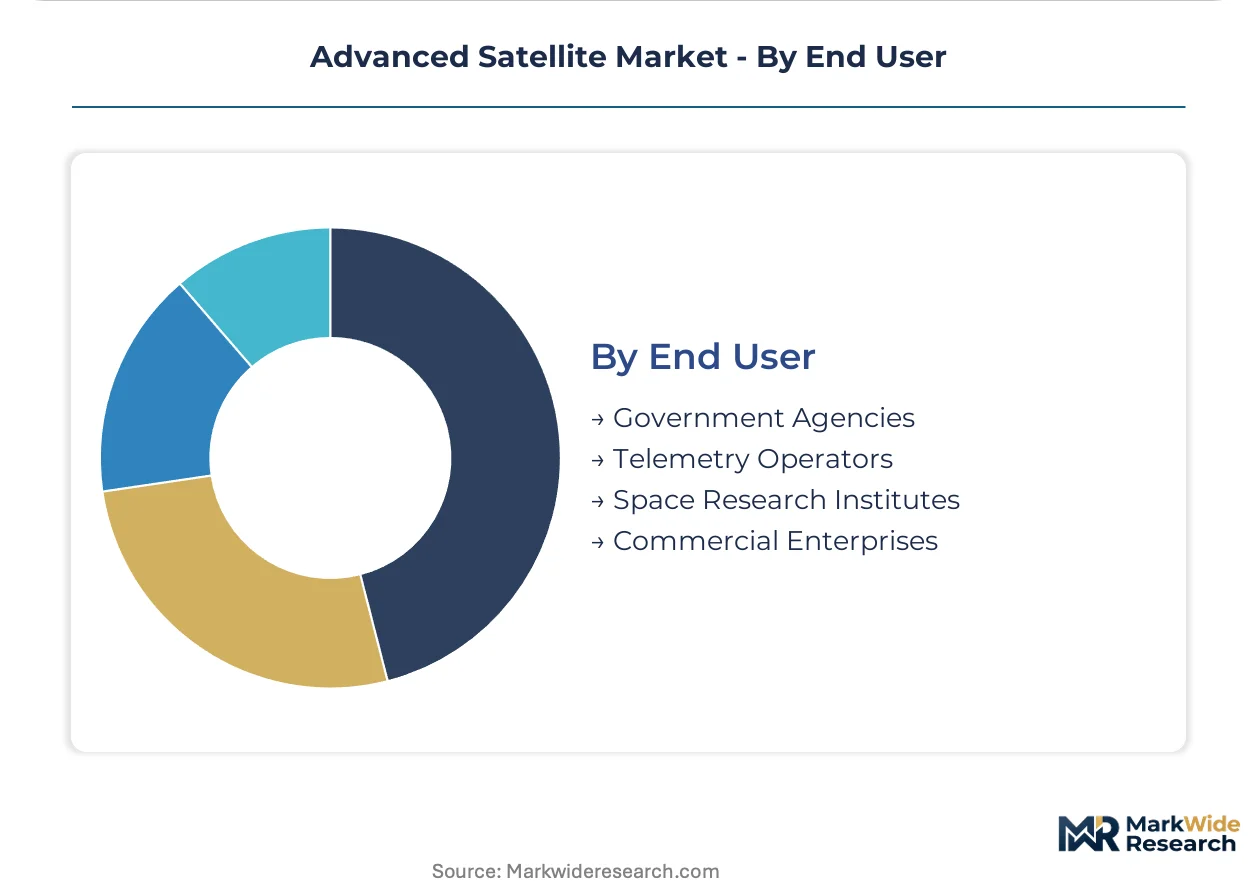
Government Agencies hold the largest share; Commercial Enterprises show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement programs and streamlined licensing frameworks are concentrating satellite manufacturing and launch activity in select national markets. Spectrum allocation reforms and sovereign capability mandates are reshaping where operators establish design centers and ground infrastructure.
United States
SpaceX and Amazon's Project Kuiper anchor national broadband infrastructure strategies through proliferated low Earth orbit architectures. The FCC's Part 25 licensing reforms compress regulatory review periods for commercial constellation deployment. Southern California and Texas host concentrated manufacturing campuses where Starship production lines and small-satellite integration facilities operate at scale.
China
State-backed constellation programs target domestic broadband coverage and remote sensing capabilities through vertically integrated supply chains. MIIT spectrum coordination mechanisms prioritize national satellite internet initiatives under dual carbon goals compliance frameworks. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate spacecraft bus manufacturing and solid-fuel launch vehicle production.
France
Thales Alenia Space and Airbus Defence and Space anchor European geostationary platform production for commercial and defense applications. ESA procurement frameworks mandate domestic supply chain content for Earth observation and navigation missions. Toulouse and Cannes host specialized payload integration facilities serving both institutional and export markets.
United Kingdom
Surrey Satellite Technology heritage and emerging launch sites at Cornwall and SaxaVord drive small-satellite manufacturing and orbital access capabilities. UK Space Agency funding programs target Earth observation analytics and in-orbit servicing demonstrators. Harwell Space Cluster concentrates downstream data processing ventures and satellite application startups.
India
ISRO's commercial arm Antrix and emerging private launch operators are expanding domestic constellation deployment capacity following space sector liberalization reforms. IN-SPACe registration pathways and revised FDI guidelines create entry frameworks for foreign satellite operators. Bengaluru and Ahmedabad host spacecraft integration facilities and ground station networks serving regional remote sensing demand.
Advanced Satellite Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: heavy-lift launch providers with reusable vehicle architectures, geostationary platform specialists serving defense procurement agencies, and small-satellite constellation operators driving manufacturing scale economics. Strategic archetypes include vertically integrated launch-to-service providers, heritage defense contractors with classified payload expertise, and asset-light analytics platforms aggregating third-party sensor data. Competitive moves concentrate on launch cost reduction through vehicle reuse and rapid constellation replenishment logistics.
Among vertically integrated launch and constellation operators, SpaceX exemplifies the scale-driven archetype through Starship manufacturing and Starlink deployment velocity. Lockheed Martin Corporation and Northrop Grumman occupy positions within the classified government demand tier, anchoring specialized geostationary platform procurement through hardened payload capabilities. These three entities represent distinct strategic postures: rapid commercial constellation expansion, legacy defense technology integration, and hybrid civil-military mission architectures.
| Leading Market Players |
|---|
| SpaceX |
| Lockheed Martin Corporation |
| Airbus Defence and Space |
| Northrop Grumman |
| Thales Alenia Space |
| Boeing Satellite Systems |
| Maxar Technologies |
| L3Harris Technologies |
| Planet Labs |
| Others |
Pricing and Supply Chain Analysis
Launch supply concentration creates asymmetric pricing power that compresses constellation deployment margins while forcing operators toward captive manufacturing investments. This single-source vulnerability determines both the spread between premium defense-grade platforms and commoditized small-satellite tiers and the geographic clustering of solar array and propulsion subsystem suppliers.
Pricing Analysis
Certification level (ITU-coordinated spectrum rights and FCC Part 25 licensing status) creates the primary spread between premium geostationary platforms and standardized low Earth orbit batches. Three-tier pricing structure across premium, standard, and economy levels stratifies by payload complexity and orbital regime, with hardened government-grade assets commanding substantial premiums over commercial broadband units. Cost compression in the commercial small-satellite tier is intensifying because SpaceX and Amazon's Project Kuiper are driving manufacturing scale economics that erode incumbent margins. Commercial enterprises show the highest price sensitivity as they increasingly unbundle capacity procurement from managed service contracts, while defense procurement agencies remain least sensitive due to sovereign capability mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for gallium arsenide solar cell inputs and rare earth magnet components. Manufacturing concentrates in the United States (SpaceX Starship production, Lockheed Martin GEO platforms), France (Thales Alenia Space and Airbus Defence and Space payload integration), and China (state-backed constellation vertical integration). Raw material dependencies center on triple-junction photovoltaic cells, Hall-effect thruster propulsion units, and phased-array antenna substrates. Distribution runs through prime contractor-led procurement frameworks for defense applications and direct constellation operator contracts for commercial broadband deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against terrestrial 5G network expansion that threatens to capture latency-sensitive applications previously dependent on satellite connectivity. Incumbents must demonstrate orbital service reliability that ground infrastructure cannot replicate.
For Market Incumbents: Entrench classified payload expertise through hardened geostationary platform investments that emerging players cannot replicate without decade-long security clearance timelines. Deepen backward integration into electric propulsion manufacturing to offset Hall-effect thruster engineering scarcity that strains mid-tier operator budgets. Lockheed Martin Corporation and Northrop Grumman anchor this defensive posture through specialized government demand capture.
For New Entrants and Emerging Players: Climate monitoring analytics for agricultural and insurance verticals represents the most penetrable entry point given underpenetrated demand relative to telecommunications applications. India's space sector liberalization offers regulatory clarity through IN-SPACe registration pathways that reduce entry friction for foreign constellation operators. Target direct-to-device service partnerships with smartphone manufacturers to bypass ground terminal reseller networks that historically blocked consumer market access.
For Investors and Strategic Acquirers: Asset-light Earth observation analytics platforms aggregating third-party sensor data present the most viable acquisition archetype given their scalable software margins and minimal orbital capital requirements. Long-term viability hinges on differentiation through proprietary algorithm development rather than constellation ownership. Watch ITU coordination timeline compression for early signals of spectrum priority rights scarcity that would advantage incumbents with established filings.
| Strategic Initiative | Industry Significance |
|---|---|
| On-Orbit Refueling Demonstration | Hall-effect thruster advances combined with refueling concepts extend mission lifespans beyond chemical propulsion limits. |
| Direct-to-Device Partnership | Smartphone-integrated satellite connectivity eliminates ground terminal intermediaries and opens consumer mass markets. |
| Electric Propulsion Scale-Up | Standardized Hall-effect thruster production reduces propulsion systems engineering scarcity premiums for mid-tier operators. |
| Climate Analytics Platform Launch | Agricultural and insurance verticals drive Earth observation sensor demand that remains underpenetrated relative to telecommunications. |
| India Market Entry Framework | IN-SPACe registration pathways and revised FDI guidelines create entry frameworks for foreign constellation operators. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with satellite manufacturing executives, defense procurement officers, FCC regulatory affairs leads, and commercial constellation operators; and secondary validation through FCC Part 25 licensing databases, ESA procurement frameworks, ITU satellite network filings, and launch manifest records. Bottom-up unit economics modeling across orbital regimes triangulated against top-down market sizing from government space agency budget disclosures and commercial operator capex trajectories.
Forecast inputs span platform type segmentation (geostationary, low Earth orbit, medium Earth orbit, highly elliptical), payload category stratification (communication transponders, Earth observation sensors, navigation modules, scientific instruments), and end-user procurement patterns (government agencies, commercial enterprises, telemetry operators, space research institutes) across the analysis window. CAGRs derive from deployment timeline modeling that incorporates launch cadence acceleration from reusable heavy-lift vehicles and regulatory review period compression under streamlined licensing frameworks.
Practitioners should monitor ITU coordination deadline acceleration, orbital debris remediation mandate evolution, and solar array input cost volatility for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Japan Satellite Imagery Services Market
Satellite
Europe Satellite IoT Market
Satellite
Middle East Satellite Communications Market
Satellite
Satellite GPS Receivers Market
Satellite
Satellite Data Analytics Services Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Satellite Internet Market
Satellite
4K Satellite Broadcasting Market
Satellite
India Satellite Connectivity Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Nano and Microsatellite Market
Satellite
Satellite Antenna Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Indonesia Satellite Communications Market
Satellite
China Satellite Imagery Services Market
Satellite
South Korea Satellite Connectivity Market