
 North America Satellite IoT Market | 2026-2036
North America Satellite IoT Market Size, Share, and Industry Trends Forecast 2026-2036
North America Satellite IoT Market Insights
Multi-source procurement for satellite modems and ground station access is consolidating around a smaller pool of qualified vendors with proven L-band and Ku-band capabilities. Iridium Communications leverages its completed NEXT constellation to sustain coverage advantages across Alaska and the Canadian Arctic. ORBCOMM anchors its position through dual-mode cellular-satellite terminals that dominate freight rail and container shipping applications. Viasat competes on higher-throughput Ka-band services for energy sector customers requiring video and telemetry convergence.
North America Satellite IoT encompasses networked endpoints that communicate through orbiting relay infrastructure rather than terrestrial cell towers, typically operating in sub-1 GHz or L-band spectrum with link budgets engineered for foliage penetration and non-line-of-sight conditions. These systems serve industries where cellular dead zones are structural rather than temporary, enabling continuous asset visibility across oceans, mountain ranges, and agricultural hinterlands. Communication modules command the strongest margin pools due to ASIC certification costs and spectrum licensing barriers that limit new entrants. Maritime end users represent the fastest-expanding demand segment as commercial fishing fleets and offshore wind operators face mandatory safety reporting requirements. Cloud-based deployment architectures are displacing on-premises ground segments among mid-sized agricultural cooperatives seeking to avoid capital-intensive hub ownership.
FCC Part 25 licensing governs earth station and space station operations, while the FAA integrates satellite IoT into unmanned aircraft system corridors under Beyond Visual Line of Sight rules. The Canadian Radio-television and Telecommunications Commission coordinates cross-border spectrum use through bilateral agreements with the FCC, particularly for shared L-band maritime channels. Mexico's Federal Telecommunications Institute has streamlined non-terrestrial network authorizations to attract constellation operators seeking southern hemisphere coverage gaps. Stakeholders must weigh the capital intensity of dedicated spectrum holdings against the flexibility of managed service arrangements as constellation refresh cycles compress and interoperability standards mature.
Market Dynamics
Constellation operators face compressed refresh cycles as low-earth orbit satellites require replacement every five to seven years, forcing capital reallocation toward ground segment automation and software-defined radios that extend hardware utility across multiple orbital generations.
Growth Catalysts
- FCC Part 25 Reauthorization:Streamlined earth station licensing for non-terrestrial networks accelerates deployment timelines for oilfield services in the Permian Basin.
- Dual-Mode Terminal Adoption:Cellular-satellite hybrid devices eliminate coverage gaps for freight rail operators traversing cellular dead zones across the Canadian Shield.
- Alaska Arctic Coverage Mandates:Remote community connectivity requirements drive sovereign infrastructure investment in polar-orbiting relay capacity.
Market Restraints
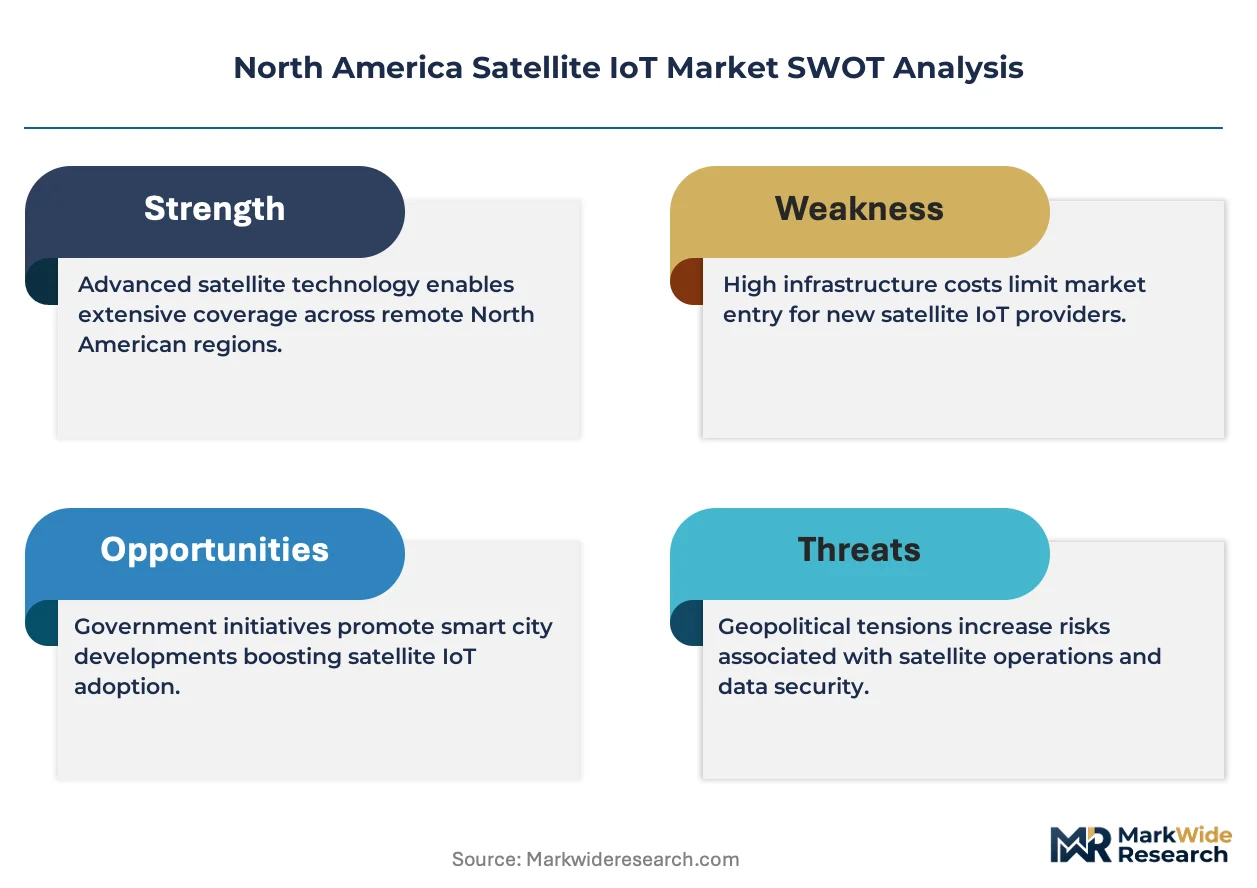
- ASIC Certification Costs:Custom modem chip validation cycles consume eighteen to twenty-four months, freezing design iterations for specialized frequency bands.
- L-Band Spectrum Congestion:Maritime safety channels face interference pressure from proliferating fishing fleet trackers in the Gulf of Mexico.
- Ground Station Capital Intensity:Gateway infrastructure concentration in the southwestern United States creates single-point vulnerability for continental backhaul.
Strategic Opportunities
- Mexico Southern Hemisphere Gap:Federal Telecommunications Institute streamlining invites constellation operators seeking coverage below the Tropic of Cancer.
- Offshore Wind Telemetry Convergence:Ka-band video and sensor fusion creates bundled service demand from Atlantic coast energy developers.
- Cloud-Native Ground Segments:Mid-sized agricultural cooperatives in Saskatchewan bypass hub ownership through managed service architectures.
Industry Challenges
- RF Engineering Talent Scarcity:Link budget optimization for foliage penetration requires specialized expertise concentrated among legacy military contractors.
- Legacy SCADA Integration:Decades-old industrial control protocols resist seamless handoff to IP-native satellite backhaul without middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Satellite IoT Market |
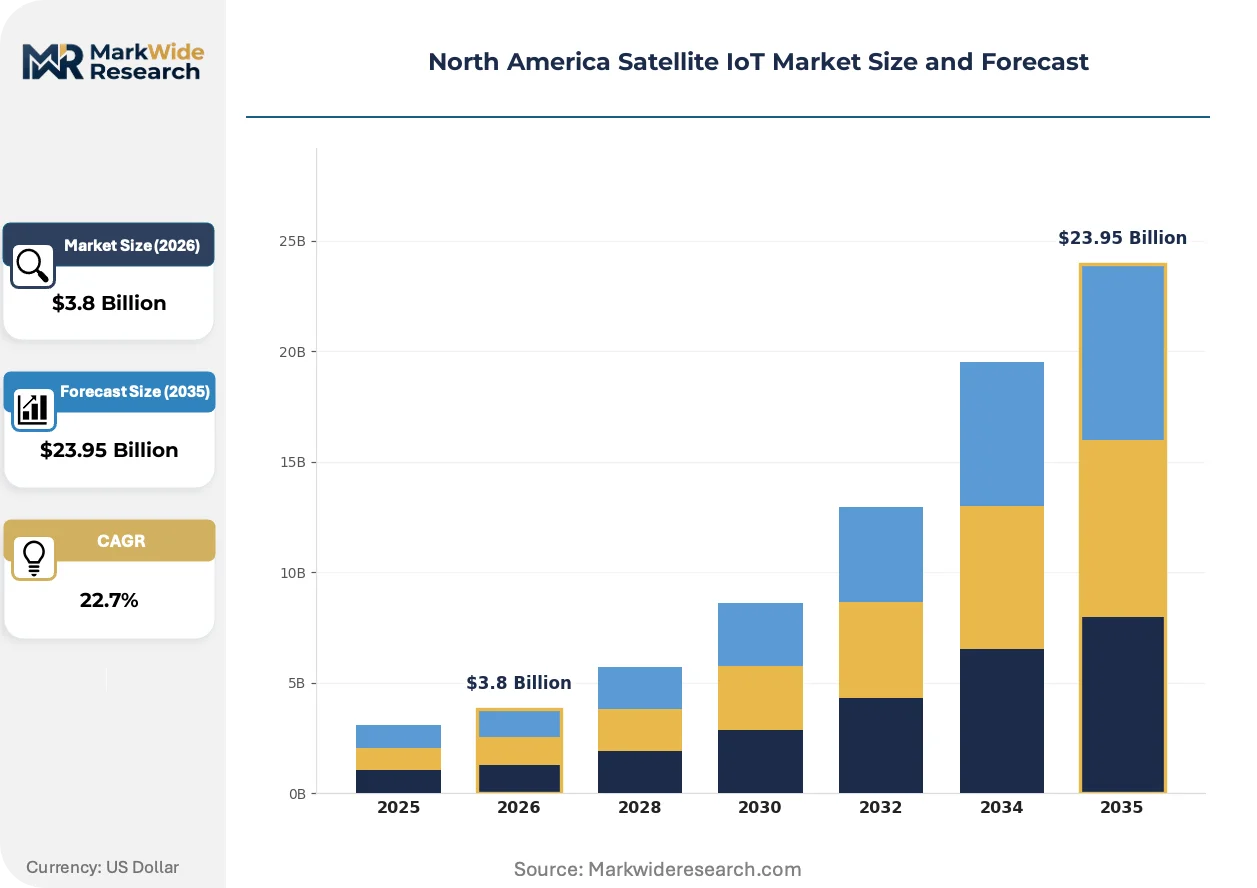
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Sensors, Communication Modules, Tracking Devices, Signal Processors End User: Agriculture, Maritime, Transportation, Energy Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service Technology: LoRaWAN, NB-IoT, Sigfox, Satellite Mesh Networking |
| Companies Covered | Iridium Communications, ORBCOMM, Globalstar, Viasat, Inmarsat, Northrop Grumman Corporation, Swarm Technologies, Kepler Communications, SES, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Satellite IoT Market Trends and Innovations
Software-defined radio architectures are collapsing hardware refresh cycles while expanding multi-constellation interoperability, forcing module vendors to decouple physical layer implementations from orbital service agreements.
Software-defined baseband processing is integrating L-band, Ku-band, and Ka-band protocols onto unified chipsets that auto-negotiate with whichever constellation offers optimal link margin. Energy sector buyers in Texas and New Mexico are piloting these multimode devices for drilling site telemetry. This capability is integrating previously siloed frequency assets into fungible capacity pools that compress vendor lock-in duration.
FAA Beyond Visual Line of Sight corridors now mandate satellite redundancy for unmanned aircraft system command links above five hundred feet AGL. Commercial drone operators in agricultural spraying and pipeline inspection must procure dual-constellation modems to maintain compliance. The rule is concentrating procurement authority among integrators capable of certifying end-to-end airworthiness packages.
Managed connectivity contracts are displacing capital-intensive hub ownership among mid-sized freight rail operators and agricultural cooperatives. Buyers now subscribe to byte-volume tiers rather than procuring dedicated transponder leases. This shift is most visible across the Canadian prairies, where grain elevator networks avoid terrestrial backhaul buildout through satellite-as-a-service arrangements.
North America Satellite IoT Market Segmentation
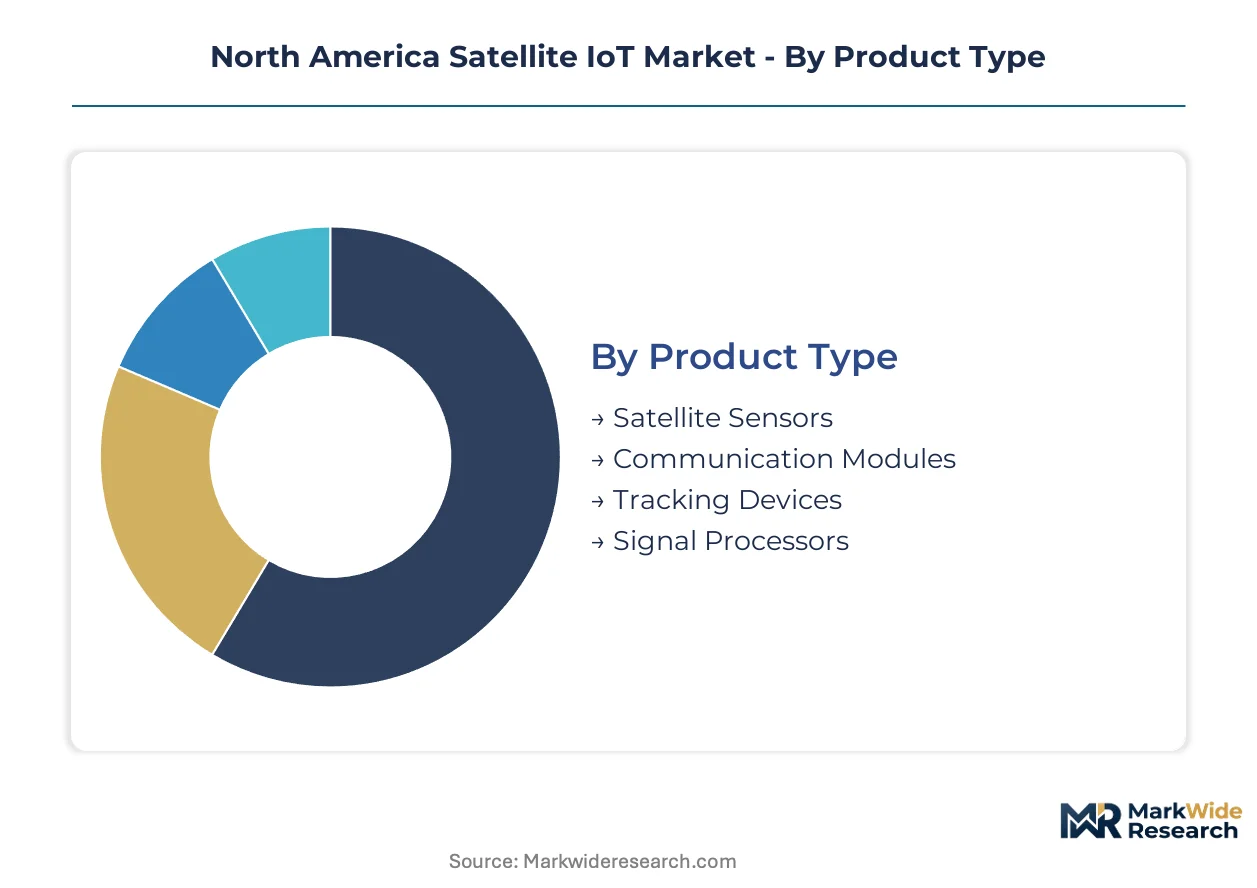
Satellite IoT deployments fragment across hardware layers, connectivity modes, and operational contexts that dictate integration complexity. Each segment category carries distinct margin profiles and vendor concentration patterns that reshape procurement strategies across energy, agriculture, and maritime verticals.
Product Type:
Standalone devices dominate remote asset monitoring where embedded integration proves technically prohibitive, while embedded modules penetrate OEM supply chains for fleet vehicles and industrial machinery.
- Communication Modules:ASIC-based transceivers certified for L-band and Ku-band operation command premium positioning due to spectrum licensing barriers and multi-constellation interoperability requirements. Demand concentrates in the Texas-New Mexico corridor where oilfield services companies deploy ruggedized units across drilling sites requiring video-telemetry convergence.
- Tracking Devices:Self-contained GPS-satellite hybrid units with integrated power management serve freight rail and container shipping applications traversing cellular dead zones across the Canadian Shield. Canadian prairie agricultural cooperatives are expanding deployments for livestock monitoring and equipment positioning.
- Satellite Sensors:Purpose-built environmental monitors with direct orbital uplink capability bypass terrestrial aggregation infrastructure.
- Signal Processors:Software-defined baseband chips auto-negotiating across frequency bands compress hardware refresh cycles for multimode deployments.
Communication modules lead volumes today; tracking devices are gaining share fastest.
End User:
Capital intensity and coverage requirements create divergent procurement patterns between infrastructure-heavy verticals and mobile asset operators.
- Energy:Offshore wind developers and Permian Basin oilfield services drive Ka-band demand for high-throughput video and sensor fusion. FAA-mandated satellite redundancy for unmanned aircraft system corridors above five hundred feet AGL accelerates dual-constellation modem procurement for pipeline inspection operations.
- Maritime:Commercial fishing fleets and offshore wind operators face mandatory safety reporting requirements that expand fastest among all verticals. Gulf of Mexico operations confront L-band spectrum congestion from proliferating vessel trackers.
- Agriculture:Precision operations across the Canadian prairies leverage satellite IoT for soil moisture monitoring where cellular infrastructure remains uneconomic.
- Transportation:Freight rail operators adopt dual-mode cellular-satellite terminals to eliminate coverage gaps across mountain ranges and remote corridors.
Energy commands the highest revenue per endpoint; maritime is climbing the fastest.
Deployment:
Ownership economics and technical staffing availability determine whether buyers favor capital expenditure or operational expenditure models.
- Managed Service:Byte-volume subscription tiers displace dedicated transponder leases among mid-sized freight rail operators and Saskatchewan grain elevator networks seeking to avoid hub ownership. Cloud-native ground segments bypass terrestrial backhaul buildout requirements.
- Cloud-Based:Fully hosted telemetry aggregation appeals to agricultural cooperatives lacking RF engineering expertise for ground station operation.
- Hybrid:Split architectures retain sensitive processing on-premises while leveraging orbital backhaul for remote site connectivity.
- On-Premises:Dedicated gateway infrastructure persists among sovereign Alaska Arctic coverage mandates requiring polar-orbiting relay capacity under direct control.
Managed service leads new contract signings; cloud-based is expanding most quickly.
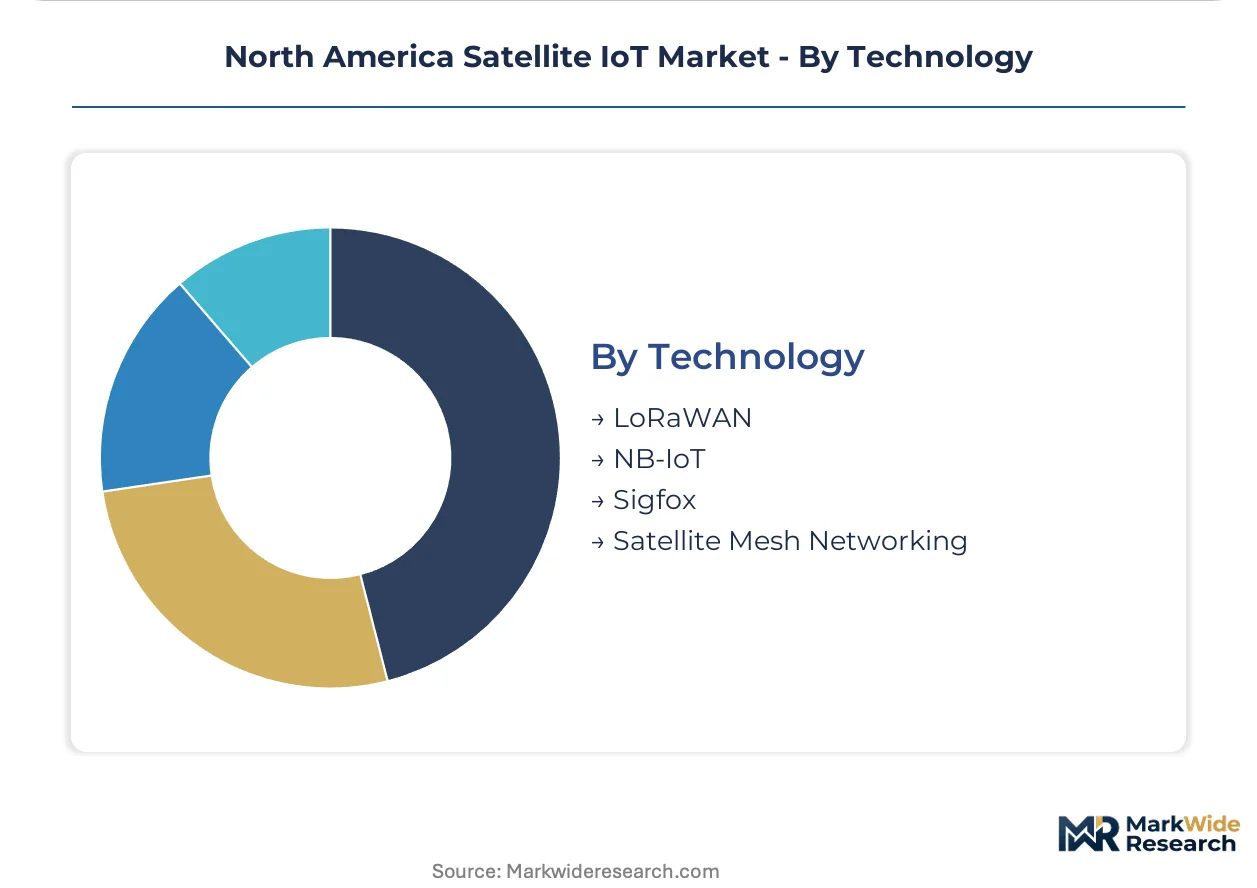
Technology:
Protocol selection hinges on link budget requirements, spectrum availability, and constellation interoperability rather than terrestrial network compatibility alone.
- Satellite Mesh Networking:Distributed relay architectures enable coverage extension beyond direct orbital visibility for foliage-penetrating applications in forested terrain and dense agricultural zones.
- NB-IoT:Narrowband protocols optimized for low-data-rate sensor telemetry achieve power efficiency for remote monitoring endpoints with decade-long battery life requirements.
- LoRaWAN:Long-range unlicensed spectrum aggregation bridges local sensor clusters to satellite backhaul in hybrid terrestrial-satellite deployments.
- Sigfox:Ultra-narrowband legacy installations persist in early maritime tracker deployments though constellation operator support is contracting.
Satellite mesh networking leads technical development investment; NB-IoT is gaining commercial traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-New Mexico corridor anchors North American satellite IoT deployment, with oilfield services companies driving ruggedized device demand across remote drilling sites. FCC spectrum reallocation accelerates licensed access for low-earth orbit constellations. Precision agriculture operations across the Canadian prairies expand soil moisture and livestock monitoring networks.
United States
Energy sector buyers in the Permian Basin pilot multimode devices for drilling site telemetry. FCC Part 25 reauthorization streamlines earth station licensing for non-terrestrial networks. The Texas-New Mexico corridor concentrates Ka-band demand for video and sensor fusion applications.
Canada
Freight rail operators adopt dual-mode cellular-satellite terminals to eliminate coverage gaps across the Canadian Shield. The Canadian Radio-television and Telecommunications Commission coordinates cross-border spectrum use through bilateral agreements with the FCC. Saskatchewan grain elevator networks bypass terrestrial backhaul buildout through satellite-as-a-service arrangements.
Mexico
The Federal Telecommunications Institute streamlines non-terrestrial network authorizations to attract constellation operators. Southern hemisphere coverage gaps below the Tropic of Cancer invite orbital infrastructure investment. Northern border states concentrate early deployment of maritime safety trackers for commercial fishing fleets.
Alaska
Remote community connectivity requirements drive sovereign infrastructure investment in polar-orbiting relay capacity. Arctic coverage mandates retain dedicated gateway infrastructure under direct state control. Energy exploration operations deploy L-band terminals for continuous asset visibility beyond terrestrial reach.
North America Satellite IoT Market Competitive Landscape
Global majors compete with regional champions across constellation coverage and ground segment access. The vendor pool consolidates around qualified suppliers with proven L-band and Ku-band capabilities. Three archetypes dominate: established satellite operators with completed constellations, dual-mode terminal specialists bridging cellular gaps, and cloud-native ground segment providers. Competitive moves center on ground station automation investments and software-defined radio licensing to compress hardware refresh cycles.
Within the constellation operator tier, Iridium Communications exemplifies completed infrastructure deployment with polar coverage advantages, while ORBCOMM anchors dual-mode cellular-satellite positioning for freight applications. Viasat occupies a position in higher-throughput Ka-band services for energy sector convergence requirements. These three represent distinct strategic vectors—orbital coverage completion, hybrid connectivity integration, and bandwidth-intensive vertical specialization—that shape procurement alternatives for end users across energy, agriculture, and maritime segments.
| Leading Market Players |
|---|
| Iridium Communications |
| ORBCOMM |
| Globalstar |
| Viasat |
| Inmarsat |
| Northrop Grumman Corporation |
| Swarm Technologies |
| Kepler Communications |
| SES |
| Others |
Pricing and Supply Chain Analysis
Semiconductor wafer pricing indices cascade through satellite IoT module manufacturing into tiered subscription structures, compressing margins for ASIC vendors while amplifying bargaining power for constellation operators with captive silicon sourcing.
Pricing Analysis
Input-cost pass-through from RF component suppliers drives pricing stratification across premium, standard, and economy tiers. L-band modem modules carrying FCC Part 25 certification command substantial premiums over unlicensed alternatives due to eighteen-to-twenty-four-month validation cycles. Pricing pressure stems from ground station automation investments that reduce operational expenditure for constellation operators. Agricultural cooperatives in Saskatchewan exhibit highest price sensitivity, while Permian Basin oilfield services prioritize reliability over unit cost.
Supply Chain Analysis
ASIC certification and FCC qualification gate vendor participation, concentrating qualified module supply among United States, Taiwan, and South Korean fabricators. RF front-end components draw from gallium arsenide foundries and ceramic substrate suppliers concentrated in East Asian manufacturing clusters. Single-source vulnerability persists for radiation-hardened chip supply serving polar-orbiting relay capacity. Distribution runs through authorized integrators capable of certifying end-to-end airworthiness packages for FAA-mandated deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America Satellite IoT functions as a stable compounder where sovereign Arctic connectivity mandates and offshore wind telemetry requirements generate durable replacement demand across compressed constellation refresh cycles.
For Market Incumbents: Acquire software-defined radio IP portfolios to collapse hardware refresh cycles and extend utility across multiple orbital generations. Consolidate ground station automation capabilities in the southwestern United States to eliminate single-point vulnerability for continental backhaul. Defend against emerging cloud-native ground segment providers by embedding managed service architectures into existing freight rail and maritime contracts. For New Entrants and Emerging Players: Enter via Mexico's streamlined Federal Telecommunications Institute authorization pathway to capture southern hemisphere coverage gaps below the Tropic of Cancer. Target commercial fishing fleets in the Gulf of Mexico confronting L-band spectrum congestion from legacy tracker deployments. Pursue satellite-as-a-service positioning for Saskatchewan grain elevator networks seeking to bypass terrestrial backhaul buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with dual-mode terminal specialists bridging cellular dead zones across the Canadian Shield. Long-term viability rests on constellation operators with completed polar infrastructure and proven L-band maritime certification. Watch for FAA Beyond Visual Line of Sight rule expansions above five hundred feet AGL as inflection indicator for unmanned aircraft system command link demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Licensing | Compresses hardware refresh cycles for multimode L-band and Ka-band deployments. |
| Ground Station Automation | Reduces operational expenditure for constellation operators managing five-to-seven-year satellite replacement. |
| Dual-Constellation Modem Certification | Meets FAA Beyond Visual Line of Sight redundancy mandates for commercial drone operators. |
| Cloud-Native Ground Segment Deployment | Enables Saskatchewan agricultural cooperatives to bypass capital-intensive hub ownership. |
| Mexico Regulatory Authorization | Unlocks southern hemisphere coverage gaps for constellation operators seeking orbital expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with constellation operators, RF module vendors, freight rail procurement officers, and agricultural cooperative technology directors with secondary validation. FCC Part 25 licensing databases, FAA Beyond Visual Line of Sight corridor filings, Canadian Radio-television and Telecommunications Commission spectrum coordination records, and Federal Telecommunications Institute authorization logs anchored regulatory tracking. Bottom-up endpoint deployment estimates triangulated against top-down constellation capacity disclosures.
Segment-weighting approaches distributed value across hardware layers, connectivity modes, and operational contexts. Modeled dimensions included product type, end user vertical, deployment architecture, and protocol technology. CAGRs derived from orbital replacement cycle compression, spectrum reallocation timelines, and vertical adoption curves. Forecast inputs incorporated polar coverage mandate trajectories and offshore wind project development pipelines.
Inputs from constellation operators and ground segment vendors were available through the study window; gaps in proprietary ASIC development cost structures introduce uncertainty bands around module margin estimates. Forecasts reflect documented assumptions regarding FCC reauthorization pacing and bilateral spectrum agreements. A model refresh is warranted upon material change in FAA unmanned aircraft system corridor rulemaking.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Satellite Backhaul Market
Satellite
Global Satellite Modem Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Satellite Transponder Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Satellite Imaging Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Satellite Antenna Market
Satellite
Europe Military Satellite Market
Satellite
LEO and GEO Satellite Market
Satellite
High-Throughput Satellite Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market