
 Sapphire Ingot Market | 2026-2036
Sapphire Ingot Market Size, Share, and Industry Trends Forecast 2026-2036
Sapphire Ingot Market Intelligence
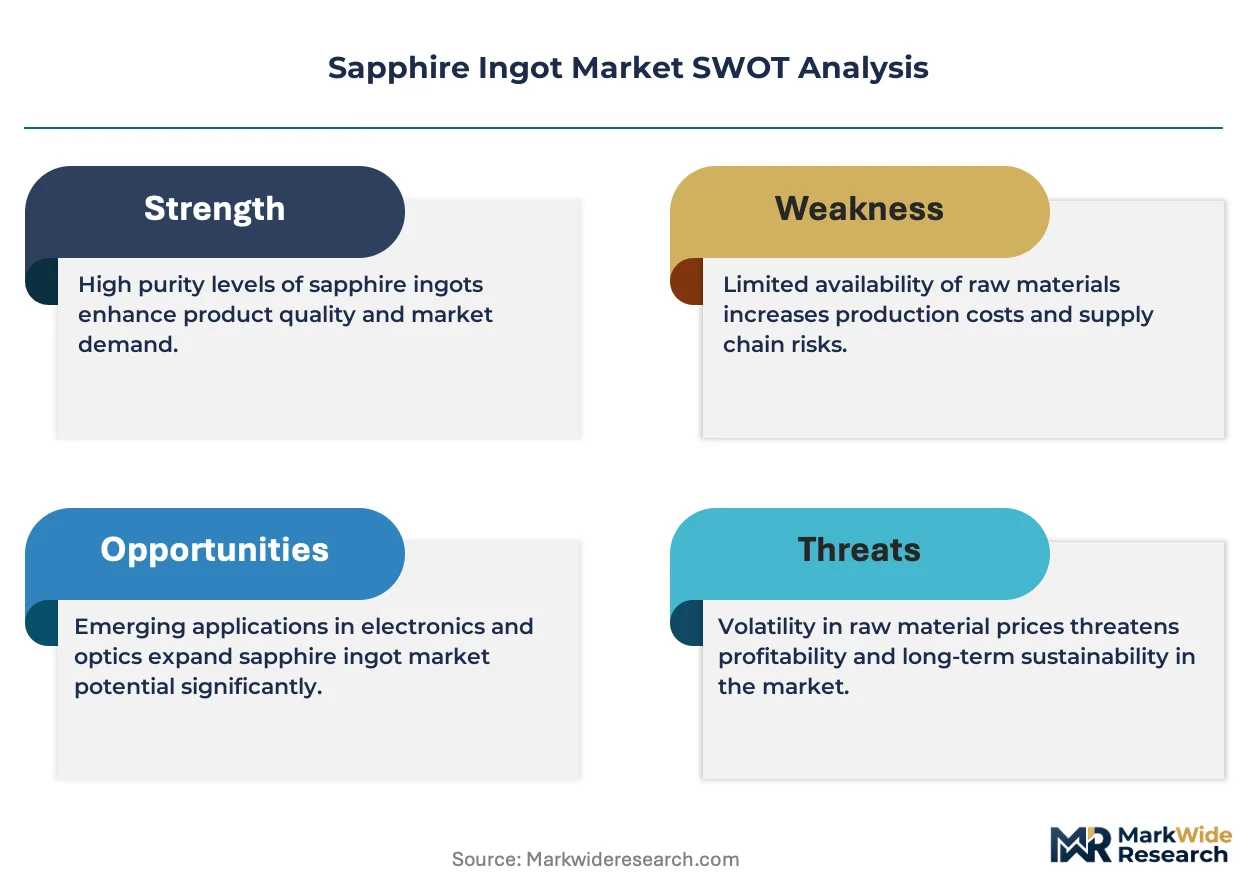
Project finance tied to long-term LED supply agreements is tilting competitive dynamics toward capital-heavy incumbents. Monocrystal leverages its vertically integrated boule-to-substrate chain to sustain margin capture across the value chain. Rubicon Technology anchors North American supply through specialized crystal-growth expertise. Saint-Gobain Crystals competes on scale, operating some of the largest kyropoulos furnaces in Europe.
A sapphire ingot is a cylindrical crystal boule of single-crystal aluminum oxide grown through the kyropoulos, Czochralski, or edge-defined film-fed growth methods, typically achieving purity levels above 99.99% and diameters up to 300 millimeters for subsequent wafer slicing. Its primary purpose is to yield substrates for gallium nitride epitaxy in LEDs, radio-frequency devices, and specialized optical windows. Single crystal ingots command the dominant share of value given their irreplaceable role in high-brightness LED manufacturing, while sapphire wafer and substrate segments concentrate margin pools where polishing and patterning add transformative value. Polycrystalline grades occupy a narrower niche in industrial optics and wear-resistant components where optical clarity matters less than fracture toughness.
The US EPA and FCC regulate sapphire-containing devices through energy-efficiency standards and electromagnetic emissions testing, respectively, while REACH in Europe governs chemical handling during crystal growth and substrate processing. China's GB standards and MIIT directives shape domestic LED supply chain certification requirements, directly influencing ingot import specifications. Stakeholders must monitor how divergent substrate-size roadmaps across these regulatory zones affect equipment amortization and customer lock-in.
Market Dynamics
Energy-efficiency mandates for solid-state lighting are compressing LED substrate procurement cycles and concentrating sapphire ingot demand among vertically integrated boule growers capable of meeting accelerated qualification timelines.
Growth Catalysts
- MIIT Directives:China's domestic LED supply chain certification requirements are tightening substrate specifications, pulling sapphire ingot imports toward higher-purity grades.
- Radio-frequency Device Expansion:5G infrastructure deployment is extending gallium nitride epitaxy demand beyond lighting into telecommunications hardware.
- Kyropoulos Furnace Scaling:Larger-diameter boule growth is reducing wafer-slicing waste rates and improving substrate yield economics.
Market Restraints
- Tungsten Crucible Supply Concentration:Russian and Chinese suppliers dominate high-purity tungsten for kyropoulos furnaces, exposing ingot producers to input cost volatility and geopolitical disruption.
- Silicon Carbide Substitution:Power electronics manufacturers are migrating high-voltage applications to silicon carbide substrates, constraining sapphire's addressable market in RF power devices.
- REACH Chemical Handling:ECHA compliance for aluminum oxide powder processing adds fixed cost layers to European boule-growing operations.
Strategic Opportunities
- India PLI Scheme:India's production-linked incentive framework for LED manufacturing is creating captive sapphire substrate demand without established domestic ingot supply.
- Automotive LiDAR Optics:Autonomous vehicle sensor windows require sapphire's hardness and thermal stability, opening a specification-driven niche outside LED epitaxy.
- Edge-Defined Film-Fed Growth:Convergence of EFG methods with automated diameter control is enabling near-net-shape ribbon production for specialized optical applications.
Industry Challenges
- Crystal-Growth Engineer Scarcity:The specialized metallurgical expertise required for defect-free boule formation is concentrated among aging practitioners in Ukraine and Russia.
- Epitaxy-Ready Certification Timelines:OEM qualification protocols for new ingot suppliers extend 18-24 months, locking out second-tier entrants from high-brightness LED supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sapphire Ingot Market |
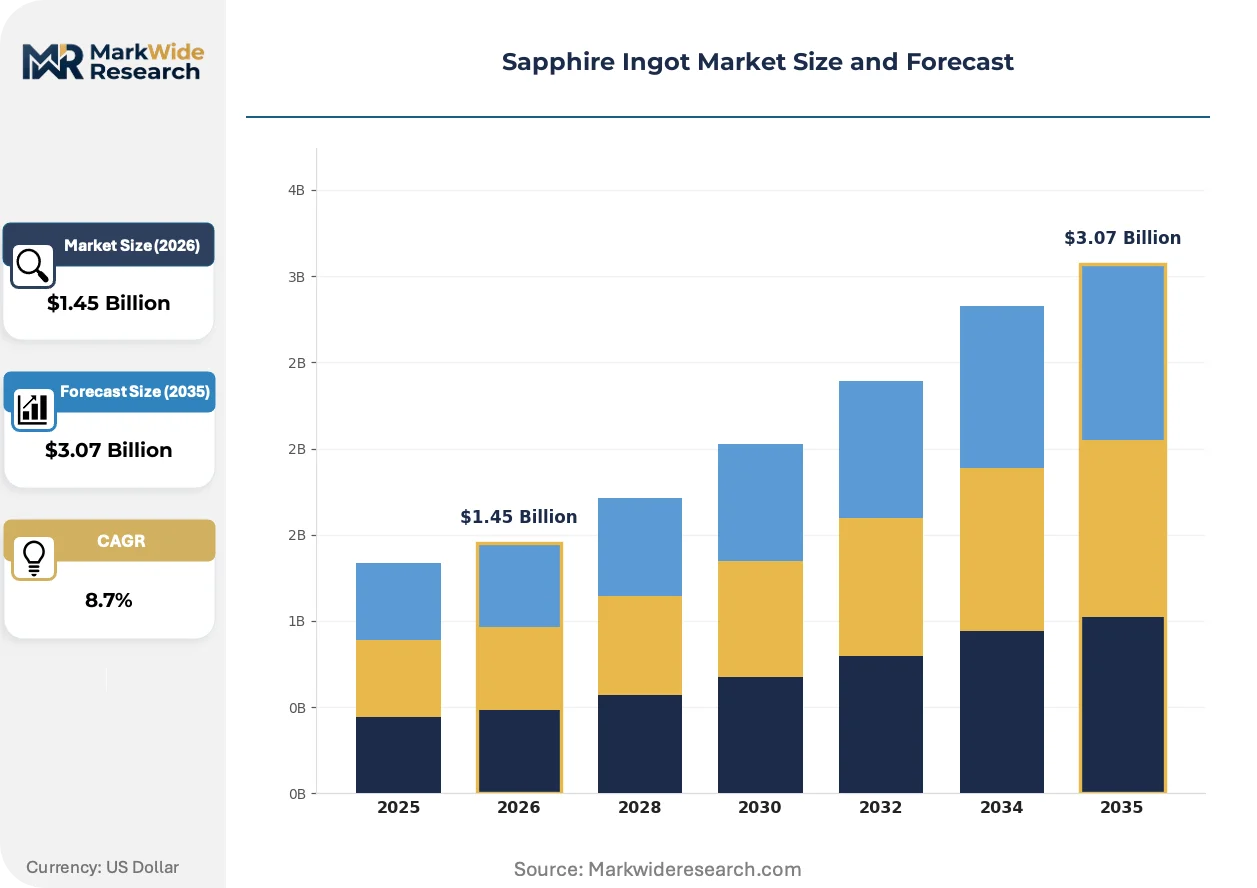
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Polycrystalline, Sapphire Wafer, Sapphire Substrate End User: Electronics, Optics, LED, Telecommunications Application: Laser Systems, Watch Crystals, LED Lighting, Display Technology Size: Small, Medium, Large, Custom |
| Companies Covered | Crystal Systems, GTAT, Rubicon Technology, Exiton, Crystal Q, Monocrystal, Silian, Aurora Optoelectronics, Saint-Gobain Crystals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sapphire Ingot Market Strategic Shifts & Innovations
Process automation and alternative growth geometries are reshaping how sapphire ingot producers compete on yield consistency and diameter scalability. These developments are compressing the traditional advantages of incumbent furnace operators.
Automated kyropoulos seeding and thermal gradient control is rendering obsolete manual furnace-tending practices that required decades of operator experience. LED substrate manufacturers in South Korea and Taiwan are adopting these systems at replacement-cycle pace. The technology is compressing labor cost differentials between established European growers and emerging Asian competitors.
REACH authorization requirements for chromium-doped alumina variants are tightening raw-material traceability obligations across European boule-growing facilities. Manufacturers must now document supply chain provenance for crucible coatings and dopant feedstocks. High-purity undoped grades for semiconductor applications face the steepest compliance cost escalation.
Long-term supply agreements with fixed-price escalators are displacing spot-market purchasing for LED substrate manufacturers. The shift concentrates procurement leverage among capital-heavy ingot producers with proven multi-year delivery track records. East Asian LED fabs are most aggressively locking in boule supply through 2028-2030 contract windows.
Sapphire Ingot Market Segmentation
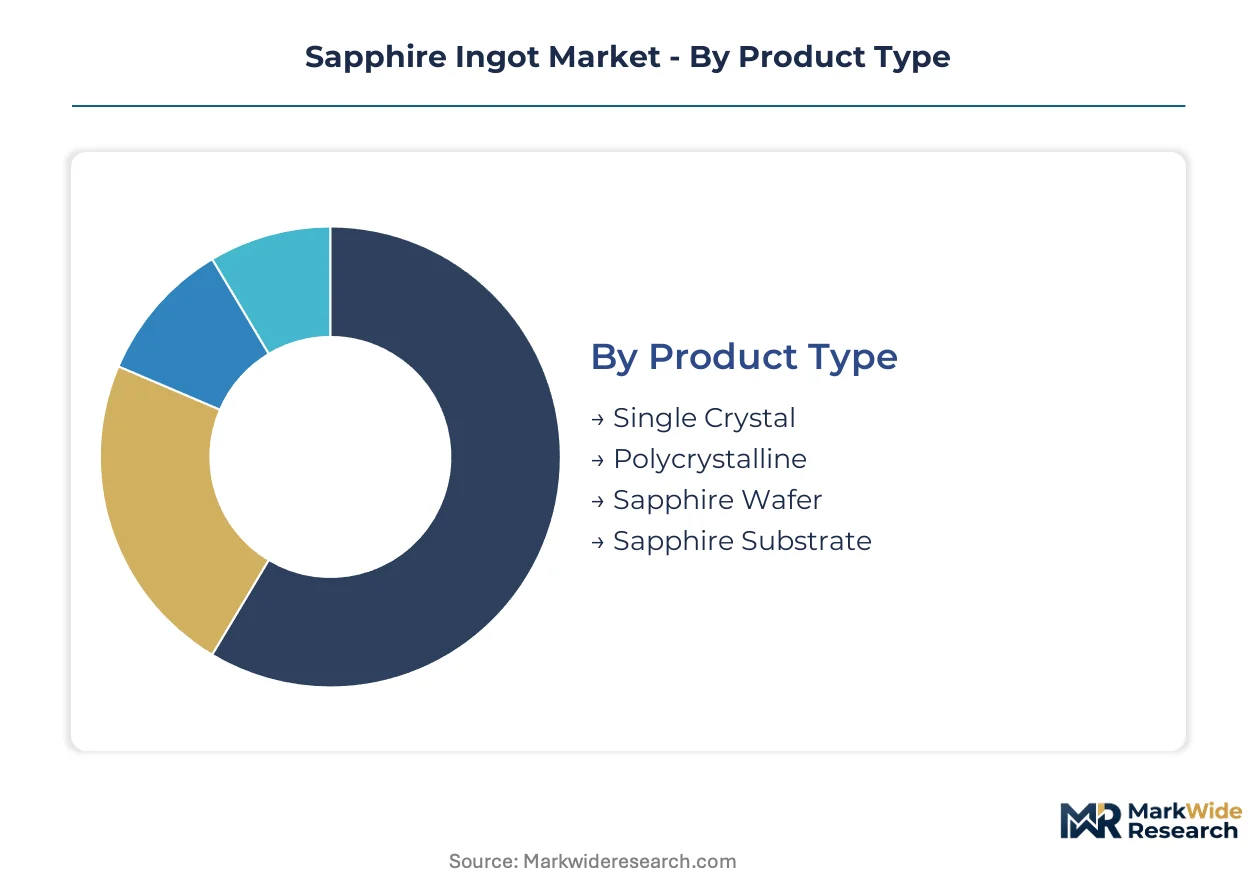
Sapphire ingot segmentation reveals how purity grades, crystal structures, and dimensional specifications map to divergent value capture across LED epitaxy, optical systems, and emerging RF applications. Crystal-growth method and end-use certification requirements create distinct margin tiers that reward specialized furnace configurations.
Product Type:
Use-case spectrum spans semiconductor-grade single crystals commanding premium pricing through optical-grade polycrystalline grades serving industrial durability applications.
- Single Crystal:Kyropoulos-grown boules achieving 99.99%+ purity serve as the non-negotiable foundation for gallium nitride epitaxy in high-brightness LEDs and RF power devices. East Asian LED fabs concentrate procurement here, with MIIT certification requirements tightening impurity tolerances for substrate suppliers serving China's domestic solid-state lighting mandates.
- Sapphire Substrate:Polished wafers with epitaxy-ready surface morphology capture the highest value-add downstream of boule slicing, where patterning and thermal management coatings transform raw crystal into functional semiconductor platforms. Taiwan and South Korean LED manufacturers anchor demand through long-term supply agreements with fixed-price escalators.
- Sapphire Wafer:Intermediate slicing products serve optical window and watch crystal applications where surface finish requirements are less stringent than epitaxy-grade specifications.
- Polycrystalline:Lower-purity grades prioritize fracture toughness and thermal shock resistance over optical clarity, finding placement in industrial wear components and non-imaging optics.
The dominant share belongs to Single Crystal, while Sapphire Substrate is closing the gap fastest.
End User:
Customer-type concentration shows LED fabs consolidating procurement leverage against fragmented optical and telecommunications equipment manufacturers.
- LED:Solid-state lighting manufacturers drive volume demand through energy-efficiency mandates tightening across China, the European Union, and India. Vertically integrated boule-to-substrate producers capture preferential qualification status with fabs seeking multi-year supply security.
- Electronics:RF device and power semiconductor manufacturers extend sapphire substrate requirements into 5G infrastructure and radar systems, though silicon carbide substitution constrains addressable expansion in high-voltage applications.
- Optics:Precision instrument and aerospace window manufacturers prioritize dimensional stability and transmission uniformity over cost minimization.
- Telecommunications:Base station and fiber optic component suppliers represent a emerging demand pocket for sapphire's dielectric properties and thermal management characteristics.
LED commands the volume base, with Electronics expanding most quickly through RF gallium nitride deployment.
Application:
Application maturity splits between established lighting markets and specification-driven niches in autonomous vehicle sensors and advanced display architectures.
- LED Lighting:General illumination and backlighting applications consume the majority of high-purity single-crystal output, with substrate size roadmaps pushing toward 300mm diameter compatibility.
- Display Technology:Transparent conductive layers and protective cover glass for flexible and foldable device architectures create emerging demand for thin-profile sapphire sheets.
- Laser Systems:Optical resonator components and high-energy windows require specialized dopant profiles and birefringence control beyond standard LED substrate specifications.
- Watch Crystals:Scratch-resistant timepiece coverings represent a stable, lower-growth segment where synthetic sapphire competes with coated mineral glass on cost-performance tradeoffs.
LED Lighting retains the largest footprint, though Display Technology is gaining share fastest through foldable device commercialization.
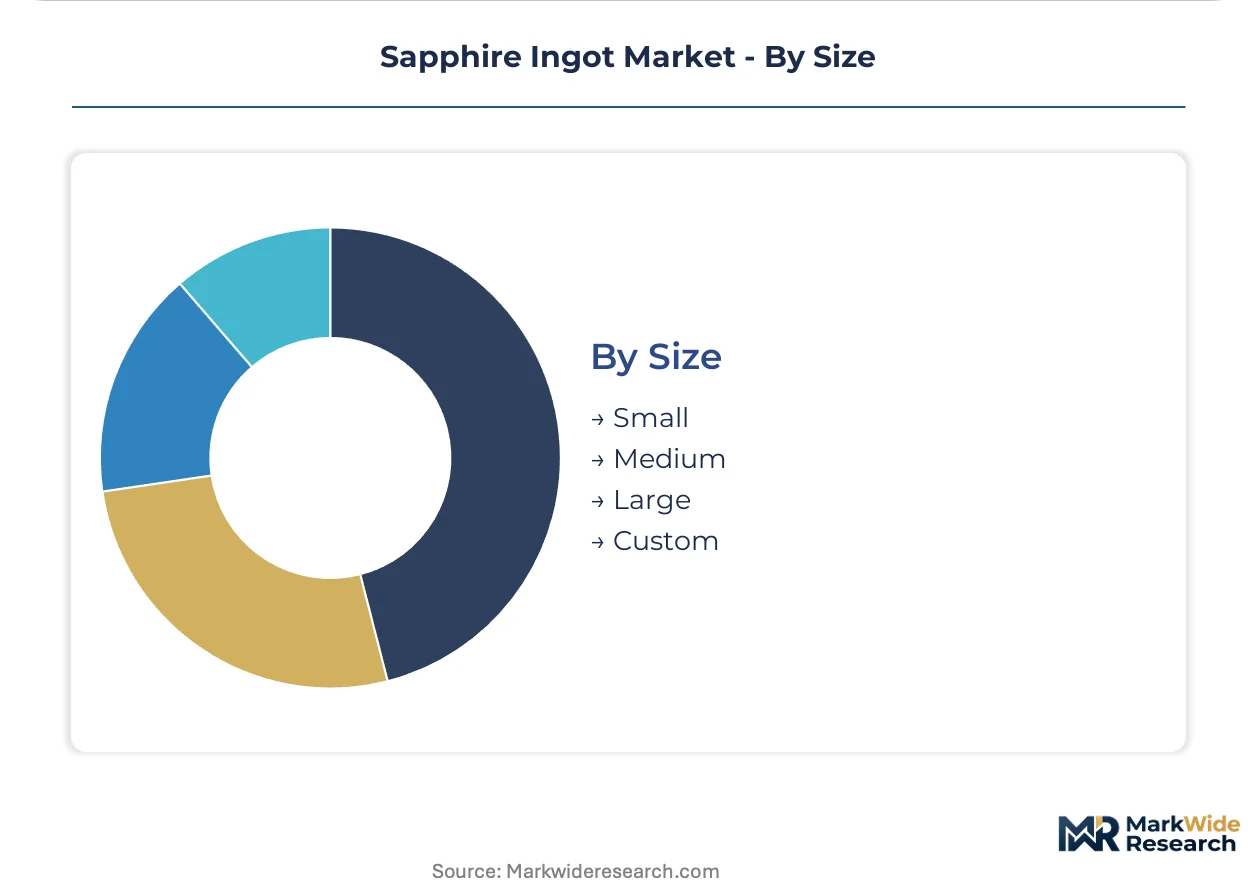
Size:
Dimensional scaling economics favor larger boules where wafer-slicing waste rates decline and furnace throughput per thermal cycle improves.
- Large:200mm and 300mm diameter boules achieve lowest per-wafer manufacturing cost through reduced kerf loss and higher substrate yield per ingot, concentrating investment among capital-heavy incumbents with proven furnace scaling expertise.
- Medium:100mm to 150mm diameters serve specialty RF and optical applications where device architectures have not migrated to larger substrate formats.
- Small:Sub-100mm dimensions persist in legacy LED fabs, research-scale epitaxy systems, and watch crystal production where retooling economics delay format migration.
- Custom:Non-standard geometries and near-net-shape profiles address automotive LiDAR windows and aerospace optical components requiring dimensional precision beyond standard wafer formats.
Large diameters dominate capital deployment, while Custom formats are climbing the fastest through automotive sensor qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with East Asian LED fabs while European crystal growers absorb REACH compliance premiums. Kyocera and Monocrystal have expanded boule-growing capacity to serve regional demand concentration. Divergent substrate-size roadmaps across regulatory zones affect equipment amortization and customer lock-in.
China
MIIT directives tighten domestic LED supply chain certification requirements, pulling sapphire ingot imports toward higher-purity grades. GB standards shape substrate specifications for solid-state lighting mandates. Yangtze River Delta LED fabs concentrate procurement leverage through 2028-2030 contract windows.
United States
EPA energy-efficiency standards and FCC electromagnetic emissions testing regulate sapphire-containing devices. North American LED substrate demand anchors through specialized crystal-growth expertise. Rubicon Technology maintains supply position for gallium nitride epitaxy qualification.
Germany
ECHA REACH compliance for aluminum oxide powder processing adds fixed cost layers to boule-growing operations. Some of the largest kyropoulos furnaces in Europe operate here. Bavarian crystal-growth facilities face steepest raw-material traceability obligations for crucible coatings.
South Korea
LED substrate manufacturers adopt automated kyropoulos seeding systems at replacement-cycle pace. Seoul Capital Area fabs compress labor cost differentials through process automation. Long-term supply agreements with fixed-price escalators displace spot-market purchasing.
India
PLI scheme production-linked incentives create captive sapphire substrate demand without established domestic ingot supply. BIS certification requirements shape import specifications for LED manufacturing. Maharashtra and Gujarat emerging as LED fab investment destinations.
Sapphire Ingot Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in boule-growing and substrate-polishing niches. The vendor base stratifies across capital-heavy incumbents with furnace scaling expertise, vertically integrated boule-to-substrate chains, and specialized optical-grade producers. Three archetypes dominate: furnace operators competing on diameter yield, integrated chains capturing margin across processing steps, and regional specialists serving qualification-constrained LED fabs. Capacity expansion and long-term supply agreement lock-in constitute the dominant competitive moves.
Among the named players, Monocrystal and Rubicon Technology exemplify the integrated and regional-specialist archetypes respectively, while Saint-Gobain Crystals occupies a position on the scale-driven furnace-operator vector. Kyocera represents East Asian capital deployment into boule-growing expansion. These companies anchor the competitive structure without exhaustive profiling of strategic postures.
| Leading Market Players |
|---|
| Crystal Systems |
| GTAT |
| Rubicon Technology |
| Exiton |
| Crystal Q |
| Monocrystal |
| Silian |
| Aurora Optoelectronics |
| Saint-Gobain Crystals |
| Others |
Cost & Logistics Intelligence
Russian and Chinese tungsten crucible suppliers anchor upstream cost structures for kyropoulos furnace operators, concentrating margin capture with boule growers who have secured multi-year feedstock contracts and locked in substrate qualification pathways with East Asian LED fabs.
Pricing Analysis
Configured-to-order pricing for epitaxy-ready substrates commands substantial premiums over standard optical-grade wafers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in medium-diameter tiers is intensifying because automated furnace systems are eroding labor-cost advantages. Emerging Indian LED fabs under the PLI scheme exhibit highest price sensitivity, while South Korean integrated device manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Monocrystal and Saint-Gobain Crystals operating captive boule-to-substrate facilities, while Rubicon Technology maintains specialized North American crystal-growth capacity. Geographic supply concentration centers on Russia and China for high-purity tungsten crucibles, Ukraine for legacy metallurgical expertise, and East Asia for automated furnace system integration. Raw material dependencies draw from aluminum oxide powder feedstocks, rare-earth dopants, and precision thermal insulation components. Single-source vulnerability in tungsten supply exposes ingot producers to geopolitical disruption. Distribution runs through direct long-term supply agreements rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as divergent substrate-size roadmaps across regulatory zones create specification niches that reward specialized furnace configurations rather than scale-alone dominance.
For Market Incumbents: Entrench qualification status through accelerated MIIT and BIS certification investments before 2028-2030 contract windows close. Lock in tungsten crucible supply through backward integration or long-term offtake agreements with Russian and Chinese suppliers to defend against silicon carbide substitution in RF power applications. For New Entrants and Emerging Players: Build out automotive LiDAR optical window capabilities where sapphire's hardness specifications create defensible niches outside LED epitaxy commoditization. Target India's PLI-driven LED fabs with imported ingot supply partnerships, leveraging the absence of domestic boule-growing capacity and BIS certification bottlenecks slowing established entrants. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated boule-to-substrate specialists with proven furnace scaling expertise and locked East Asian qualification status over the next decade. Watch for inflection in silicon carbide substrate pricing as the signal for accelerated sapphire demand compression in high-voltage RF applications.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | East Asian LED fabs lock in boule supply through 2028-2030 contract windows, concentrating procurement leverage. |
| Backward Integration | Tungsten crucible supply control defends against Russian and Chinese supplier concentration and geopolitical disruption. |
| Certification Investment | MIIT and BIS qualification pathways accelerate customer lock-in before replacement-cycle furnace automation spreads. |
| Capacity Expansion | Larger-diameter kyropoulos furnace deployment reduces wafer-slicing waste rates and improves substrate yield economics. |
| Joint Venture | Automotive LiDAR partnerships with sensor OEMs open specification-driven niches outside LED epitaxy commoditization. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with crystal-growth engineers, LED substrate procurement managers, furnace equipment specialists, and ECHA compliance officers; and secondary validation through SEC filings, customs trade data, MIIT directive archives, and patent filings. Bottom-up triangulation across boule-production capacity estimates and top-down cross-check against LED fab substrate consumption models anchored volume forecasts.
Forecast inputs considered crystal-growth method, purity grade tier, diameter specification, end-use application, and regional regulatory cluster across the analysis window. CAGRs emerged from segment-level growth rate reconciliation against macro LED demand projections and RF device deployment trajectories. Industry-specific inputs incorporated furnace automation adoption curves and tungsten supply disruption scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon carbide substrate specialists or alternative wide-bandgap material developers would shift outcomes. Quarterly review of MIIT certification timelines, REACH authorization amendments, and Indian PLI disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Quartz Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Fullerene Market
Semiconductor Material
OLED Materials Market