
 Yttrium Oxide Market | 2026-2036
Yttrium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Yttrium Oxide Market Analytics
Direct supply contracts between rare earth refiners and Japanese electronics manufacturers is reconfiguring procurement relationships across the Yttrium Oxide value chain. China Minmetals Corporation leverages its integrated mining-to-oxide infrastructure to dominate spot availability for high-purity grades. Neo Performance Materials anchors Western supply security through its Estonian separation facility and downstream processing in Estonia. Lynas Rare Earths Ltd competes on Australian feedstock traceability, a positioning that resonates with defense contractors requiring supply chain transparency.
Yttrium oxide, Y₂O₃, is a white crystalline rare earth oxide with a melting point exceeding 2400°C, synthesized primarily through oxalate precipitation or solvent extraction from bastnäsite and monazite concentrates; its exceptional thermal stability and ionic conductivity make it indispensable for thermal barrier coatings, solid oxide fuel cell electrolytes, and LED phosphor matrices. Powder grades command the deepest margin pools due to pharmaceutical and semiconductor polishing specifications that reject granular alternatives. Ceramics applications represent the fastest-expanding consumption vector as aerospace turbine manufacturers adopt yttria-stabilized zirconia for next-generation engine components.
REACH registration requirements in Europe and China's GB rare earth purity standards collectively elevate compliance costs for cross-border traders while filtering out sub-scale producers. Japan's METI designates yttrium among critical minerals, triggering stockpile mandates that buffer domestic manufacturers against supply interruptions. Stakeholders must monitor how export licensing frameworks evolve in major producing jurisdictions, as policy shifts in any single country transmit rapidly through this thinly traded material.
Market Dynamics
China's rare earth processing controls are forcing downstream manufacturers to rebuild supply chains around non-Chinese separation capacity, with Malaysia and Vietnam absorbing redirected investment flows.
Growth Catalysts
- Aerospace turbine adoption:Yttria-stabilized zirconia thermal barrier coatings now penetrate next-generation engine programs, with Rolls-Royce and GE Aviation qualifying new ceramic matrix architectures.
- Japan's METI stockpile mandates:Critical mineral designation triggers inventory builds that buffer domestic ceramics manufacturers against supply interruptions.
- Solid oxide fuel cell commercialization:Electrolyte-grade yttrium oxide demand accelerates as Bloom Energy and Ceres Power scale manufacturing.
Market Restraints
- Bastnäsite concentrate volatility:Rare earth ore prices swing with Chinese export licensing cycles, compressing oxide refiner margins unpredictably.
- Monazite radioactivity handling:Thorium content in heavy mineral sands concentrates requires specialized disposal infrastructure absent in most non-Chinese jurisdictions.
- ISO purity certification costs:Pharmaceutical-grade specifications demand six-nines purity validation that filters out sub-scale producers.
Strategic Opportunities
- Vietnam's emerging separation corridor:Australian feedstock-to-oxide projects leverage the country's rare earth tax incentives and port access to Japanese buyers.
- LED phosphor matrix convergence:Quantum dot-yttrium oxide hybrid architectures open display and medical imaging applications beyond traditional lighting.
- EU Green Deal critical raw materials list:Yttrium inclusion triggers project financing availability for European separation facility development.
Industry Challenges
- Rare earth metallurgy expertise scarcity:Solvent extraction and ion exchange process engineers command premium compensation, constraining capacity expansion timelines.
- REACH registration documentation burden:ECHA substance dossier requirements consume eighteen to twenty-four months for new purity grades, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yttrium Oxide Market |
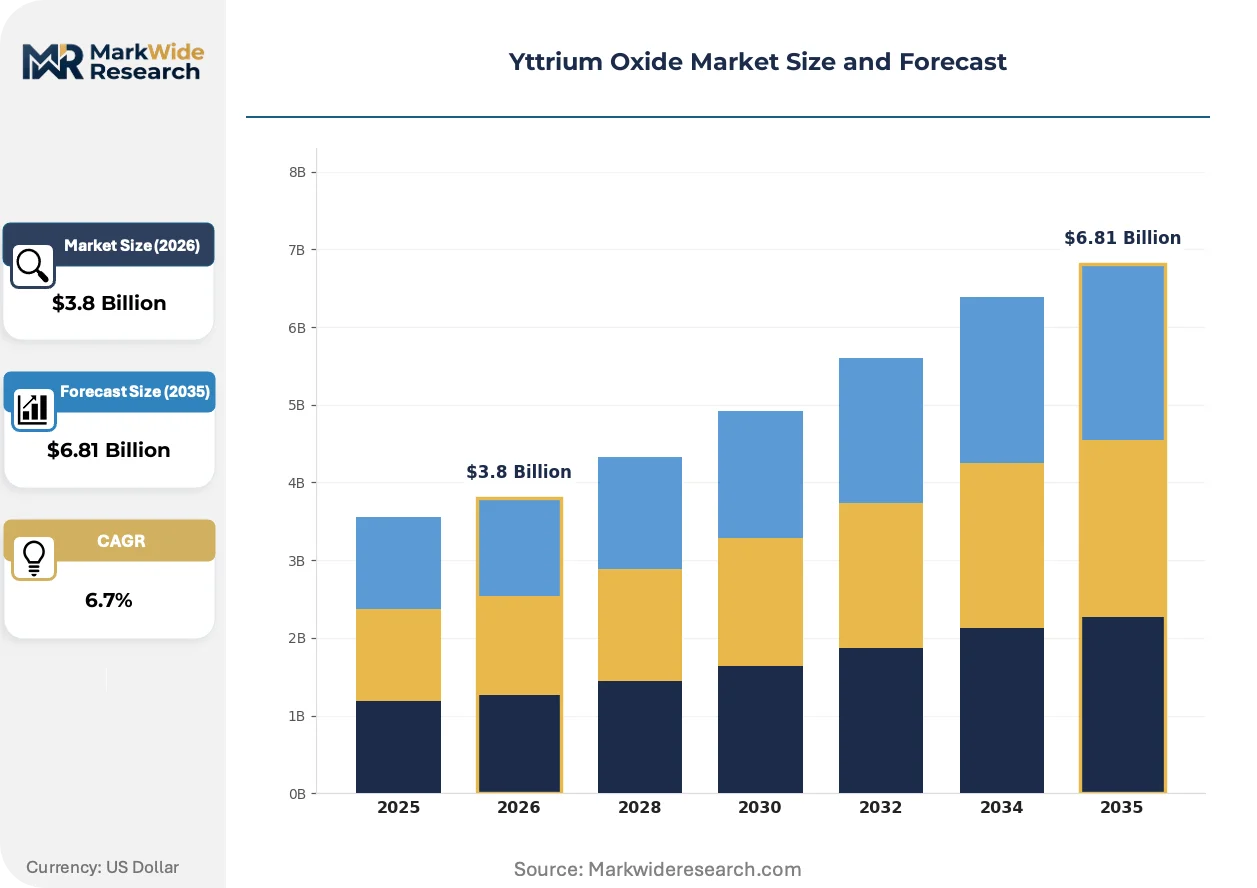
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Coatings, Sputtering Targets Application: Electronics, Phosphors, Glass Manufacturing, Ceramics End User: Manufacturing, Defense, Telecommunications, Healthcare Delivery Mode: Direct Supply, Retail, Online Distribution, Export |
| Companies Covered | China Minmetals Corporation, Neo Performance Materials, Metall Rare Earth Limited, American Elements, Solvay S.A., Shin-Etsu Chemical Co., Ltd., Aluminum Corporation of China (CHINALCO), Nippon Yttrium Co., Ltd., Lynas Rare Earths Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yttrium Oxide Market Evolving Landscape
Digital twin technology is virtualizing quality assurance workflows across rare earth oxide production, compressing batch release cycles while tightening purity verification protocols.
Computational modeling of crystal lattice structures is virtualizing traditional trial-and-error synthesis methods. Japanese ceramics laboratories now simulate yttria-stabilized zirconia phase behavior before physical prototyping. This approach halves development cycles for aerospace-grade thermal barrier formulations.
REACH authorization requirements for persistent organic pollutants now capture certain rare earth extraction reagents, compelling European refiners to substitute solvent systems. ECHA's updated candidate list pressures cross-border traders to requalify supply chains. German and French chemical distributors are consolidating preferred supplier lists to preempt compliance exposure.
Direct refiner-to-manufacturer contracting is displacing spot market purchasing for high-purity grades. Japanese electronics and ceramics producers now negotiate three to five year offtake agreements with Estonian and Australian separation facilities. This pattern is most visible in precision polishing and pharmaceutical applications where batch traceability carries regulatory weight.
Yttrium Oxide Market Segmentation
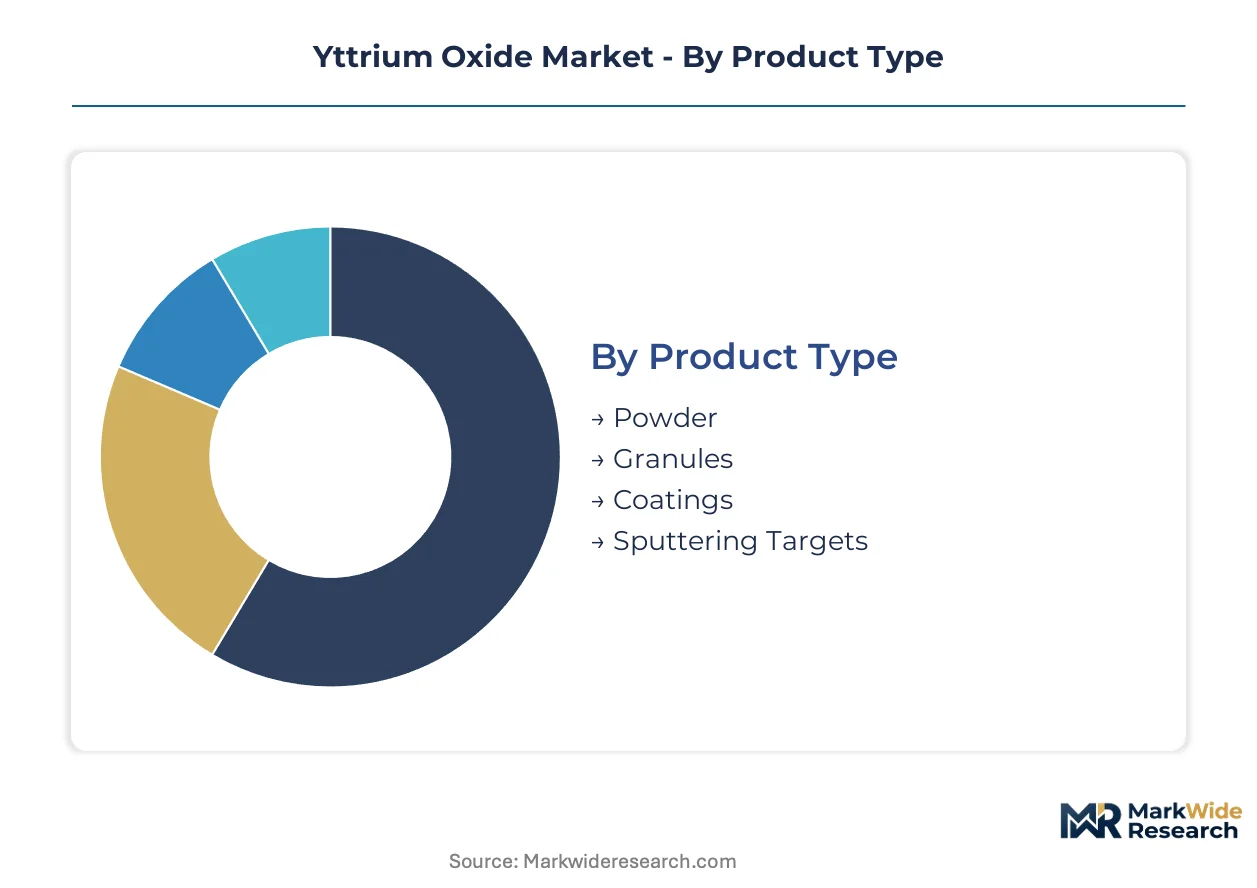
Yttrium oxide specifications diverge sharply across downstream applications, with thermal barrier coatings demanding different morphologies than LED phosphor matrices. Procurement patterns in this market track purity thresholds more closely than volume scale, creating tiered supply relationships that resist commoditization.
Product Type:
Powder grades anchor mature revenue streams while sputtering targets emerge from specialty deposition tooling.
- Powder:Sub-micron spherical morphology achieves six-nines purity for pharmaceutical polishing and semiconductor planarization. Japanese ceramics manufacturers stockpile pharmaceutical-grade powder against METI critical mineral mandates, with direct contracts to Estonian separation facilities displacing spot procurement.
- Granules:Agglomerated forms suit furnace lining and bulk ceramic sintering where surface area matters less than flow characteristics. Chinese environmental processing controls restrict granule export licensing, redirecting European buyers toward Malaysian tolling operations.
- Coatings:Pre-formulated suspensions for thermal spray and electron beam physical vapor deposition reduce customer-side formulation burden.
- Sputtering Targets:High-density planar disks enable thin-film deposition for transparent conducting oxides and dielectric layers.
Powder retains volume leadership; sputtering targets hold the steepest expansion curve.
Application:
Cost tier stratification separates aerospace-qualified ceramics from commodity phosphor blending.
- Ceramics:Yttria-stabilized zirconia thermal barrier coatings withstand turbine inlet temperatures exceeding 1400°C in next-generation engine architectures. Rolls-Royce and GE Aviation qualification protocols now specify Australian feedstock traceability for defense-relevant supply chains.
- Electronics:Solid oxide fuel cell electrolytes exploit yttrium oxide's ionic conductivity at elevated temperatures. Bloom Energy and Ceres Power manufacturing scale-up is concentrating demand in California and South Korean industrial zones.
- Phosphors:LED and display applications utilize europium-doped yttrium oxide for red emission, though quantum dot hybrids are displacing traditional formulations.
- Glass Manufacturing:Optical glass polishing and UV-resistant additives consume lower-purity grades with less stringent certification overhead.
Ceramics commands premium pricing tiers; electronics is expanding most quickly.
End User:
Customer type determines contract structure, with defense procurement mandating multi-year traceability documentation.
- Manufacturing:Advanced ceramics and electronics fabricators dominate volume offtake, negotiating three to five year direct supply agreements with rare earth refiners to bypass volatile spot markets.
- Defense:Aerospace turbine and missile guidance applications require supply chain transparency certifications that Lynas Rare Earths leverages through Australian mine-to-oxide documentation.
- Telecommunications:Optical fiber amplifiers and satellite components utilize specialty grades with lower volume but higher margin profiles.
- Healthcare:Medical imaging phosphors and dental ceramics drive pharmaceutical-grade purity demand with ISO validation requirements that filter out sub-scale suppliers.
Manufacturing retains volume leadership; defense holds the steepest expansion curve.
Delivery Mode:
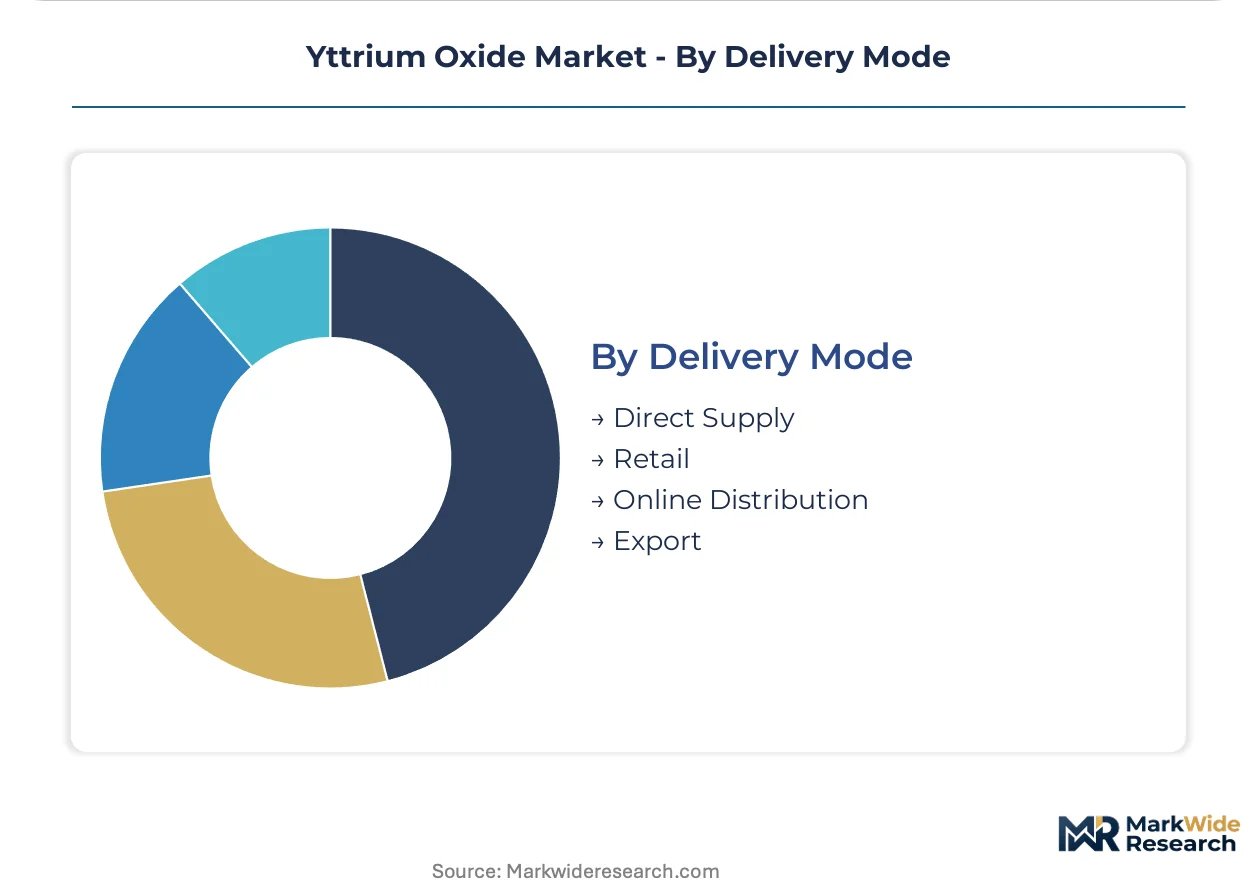
Supply concentration shapes channel selection, with high-purity grades bypassing distribution intermediaries entirely.
- Direct Supply:Refiner-to-manufacturer contracting now dominates pharmaceutical and precision polishing segments where batch traceability carries regulatory weight under REACH and Japan's METI frameworks.
- Export:Cross-border traders face ECHA substance dossier requirements consuming eighteen to twenty-four months for new purity grades, compressing arbitrage opportunities.
- Retail:Laboratory-scale quantities move through chemical distributors with consolidated preferred supplier lists to preempt compliance exposure.
- Online Distribution:Digital platforms capture research-grade and small-batch procurement with limited certification documentation.
Direct supply retains volume leadership; export channels face regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese rare earth processing controls grant domestic refiners substantial pricing leverage over Japanese ceramics manufacturers, while Malaysian separation facilities capture redirected investment flows seeking supply chain diversification.
China
Dual carbon goals and GB rare earth purity standards concentrate high-volume oxide production in state-controlled refining corridors. MEE environmental compliance requirements filter out sub-scale processors, tightening spot availability for export markets. Bayan Obo mining complexes in Inner Mongolia feed integrated oxide infrastructure that dominates global feedstock supply.
Japan
METI critical mineral designation triggers stockpile mandates for domestic ceramics and electronics manufacturers. JIS certification requirements for thermal barrier coating feedstocks elevate procurement standards beyond generic oxide grades. Nagoya industrial clusters host precision ceramics fabricators negotiating direct refiner contracts to bypass volatile spot channels.
United States
Defense contractors demand Australian feedstock traceability for aerospace turbine applications under supply chain transparency protocols. EPA radioactivity handling requirements constrain monazite-derived oxide processing absent specialized disposal infrastructure. California solid oxide fuel cell manufacturers concentrate electrolyte-grade demand as Bloom Energy scales manufacturing.
Germany
ECHA REACH registration documentation consumes eighteen to twenty-four months for new purity grades, compressing market entry timelines for cross-border traders. EU Green Deal critical raw materials list inclusion triggers project financing for European separation facility development. Rhineland chemical distributors consolidate preferred supplier lists to preempt compliance exposure from updated candidate list substances.
Vietnam
Australian feedstock-to-oxide projects leverage rare earth tax incentives and deep-water port access to Japanese buyers. The country's emerging separation corridor absorbs investment redirected from Chinese processing controls. Northern industrial zones near Haiphong develop tolling capacity for European ceramics manufacturers seeking non-Chinese supply origins.
Yttrium Oxide Market Competitive Landscape
State-affiliated mining conglomerates and Western separation specialists split the market along supply chain control vectors. Concentration remains pronounced at the mining-to-oxide interface, where integrated infrastructure commands disproportionate influence over spot availability. Three archetypes dominate: vertically integrated state enterprises, independent Western separation facilities, and specialty chemical distributors serving research-grade segments. Capacity expansion and direct refiner-to-manufacturer contracting represent the dominant competitive moves reshaping procurement relationships.
Among state-affiliated mining enterprises, China Minmetals Corporation and Aluminum Corporation of China exemplify the integrated infrastructure archetype that dominates high-volume oxide supply. Neo Performance Materials occupies a position within the Western separation specialist tier, anchoring non-Chinese supply security through Estonian processing capacity. Lynas Rare Earths Ltd represents the traceability-focused alternative, with Australian mine-to-oxide documentation resonating with defense procurement requirements. Specialty chemical distributors including American Elements and Solvay S.A. sit within the high-purity grade segment, serving pharmaceutical and semiconductor polishing applications where batch certification carries regulatory weight. Japanese and European chemical companies such as Shin-Etsu Chemical Co., Ltd. and Nippon Yttrium Co., Ltd. exemplify regional fabrication specialists with established ceramics industry relationships.
| Leading Market Players |
|---|
| China Minmetals Corporation |
| Neo Performance Materials |
| Metall Rare Earth Limited |
| American Elements |
| Solvay S.A. |
| Shin-Etsu Chemical Co., Ltd. |
| Aluminum Corporation of China (CHINALCO) |
| Nippon Yttrium Co., Ltd. |
| Lynas Rare Earths Ltd |
| Others |
Value Network & Pricing Analysis
Bayan Obo mining complexes in Inner Mongolia anchor global feedstock supply, granting Chinese state refiners substantial leverage over Japanese ceramics manufacturers who face compressed margins when export licensing tightens. Spot availability volatility transmits directly into downstream pricing power, with high-purity grades commanding substantial premiums during supply interruptions.
Pricing Analysis
Configured-to-order pricing spreads widen substantially against standard powder grades, with six-nines purity validation for pharmaceutical applications carrying certification premiums that spot market purchases cannot replicate. Price differentiation rests on ISO purity tiers and Australian feedstock traceability documentation demanded by defense contractors. Pricing pressure intensifies in granule segments as Chinese environmental processing controls restrict export licensing volumes. Research-grade buyers exhibit highest price sensitivity, while aerospace turbine manufacturers absorb premiums for qualified thermal barrier coating feedstocks.
Supply Chain Analysis
Malaysian tolling operations and Vietnamese separation facilities concentrate non-Chinese processing capacity as investment redirects from Beijing's rare earth controls. Bastnäsite concentrates from Australian mines and monazite heavy mineral sands feed oxide production, with thorium radioactivity handling requirements constraining alternative feedstock development. Single-source vulnerability concentrates in Chinese integrated mining-to-oxide infrastructure. Distribution runs through direct refiner-to-manufacturer contracting for high-purity grades, bypassing volatile spot channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rare earth metallurgy expertise commands premium compensation across solvent extraction and ion exchange operations, constraining capacity expansion timelines and creating durable scarcity for qualified process engineers. This capability gap shapes competitive dynamics more fundamentally than capital availability alone.
For Market Incumbents: Build regulatory certification moats by securing REACH dossier approvals for additional purity grades before ECHA candidate list expansions capture new extraction reagents. Deepen Australian feedstock documentation for defense contractor qualifications. Expand Estonian or Malaysian tolling capacity to capture redirected Japanese investment flows seeking non-Chinese supply origins.
For New Entrants and Emerging Players: Vietnam's emerging separation corridor offers the most penetrable geographic entry point, leveraging rare earth tax incentives and deep-water port access to Japanese buyers. Target solid oxide fuel cell electrolyte-grade production where Bloom Energy and Ceres Power manufacturing scale-up concentrates demand. Pursue tolling partnerships with Australian feedstock suppliers rather than greenfield mining investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors separation specialists with established ion exchange infrastructure over upstream mining plays. Long-term viability across the projection horizon hinges on regulatory compliance scalability rather than reserve size alone. Monitor Japanese METI stockpile mandate expansions as inflection signals for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bastnäsite Feedstock | Australian mine-to-oxide documentation satisfies Rolls-Royce and GE Aviation qualification protocols for defense supply chains. |
| REACH Dossier Expansion for New Purity Grades | ECHA substance registration compresses market entry timelines to eighteen months for pharmaceutical-grade specifications. |
| Malaysian Tolling Capacity Addition | Redirected European buyer demand seeks non-Chinese granule processing as Beijing tightens environmental export controls. |
| Direct Refiner-to-Manufacturer Contracting | Three to five year offtake agreements with Japanese ceramics producers displace volatile spot procurement channels. |
| Digital Twin Quality Assurance Implementation | Virtualized batch release cycles tighten purity verification protocols for semiconductor polishing applications. |
Research Methodology
A standing panel of rare earth refinery plant managers, Japanese ceramics procurement leads, aerospace turbine material specialists, and Estonian separation facility technical directors provided ongoing calibration across the study. Primary interviews combined with secondary validation from customs trade data, SEC filings of listed rare earth companies, ECHA substance dossier repositories, and Japan METI critical mineral stockpile disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated solid oxide fuel cell commercialization pathways. Segmentation modeling incorporated purity grade tiers, end-use applications spanning ceramics to electronics, delivery mode structures, and regional production hub concentrations. CAGRs derived from weighted average of historical volume trends and technology adoption curve analysis. Forecast inputs included Bloom Energy manufacturing scale-up disclosures and Japanese METI mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-affiliated mining conglomerates or accelerated Vietnamese separation corridor development would shift outcomes substantially. Quarterly review of ECHA candidate list updates, Japanese stockpile inventory disclosures, and Australian feedstock project financing announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
DCB and AMB Substrate Market