
 Area Sensor Market | 2026-2036
Area Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Area Sensor Market Analysis
Aftermarket service revenue is fragmenting across hardware-software bundles as sensor vendors compete for recurring income streams. Sick AG leverages its European installed base to sustain long-term service contracts. Keyence Corporation anchors premium positioning through direct sales channels and rapid technical support.
An area sensor detects objects within a defined two-dimensional detection zone using active or passive sensing elements, typically operating at response times under 10 milliseconds for industrial safety applications. The device creates an invisible curtain or grid to trigger machine stops, count items, or guide robotic movements without physical contact. Lidar Sensors command the highest unit margins in outdoor and long-range security deployments, while Time-of-Flight technology expands fastest in consumer electronics and automotive cabin monitoring. Industrial Automation absorbs the largest volume share among application segments, though Smart Cities represents the emerging demand frontier for pedestrian and traffic flow analytics.
FDA oversight of diagnostic and surgical robotics indirectly shapes sensor reliability requirements in medical manufacturing environments. OSHA machine guarding standards and ISO 13849-1 safety integrity classifications mandate redundant area sensor configurations in North American and European factories. Stakeholders must monitor how EU AI Act risk classifications and emerging NHTSA pedestrian detection rules reshape sensor fusion architectures and certification burdens.
Market Dynamics
Time-of-Flight sensor architectures are compressing replacement cycles across automotive and electronics manufacturing clusters as ISO 13849-1 safety integrity mandates force redundant detection configurations on assembly lines.
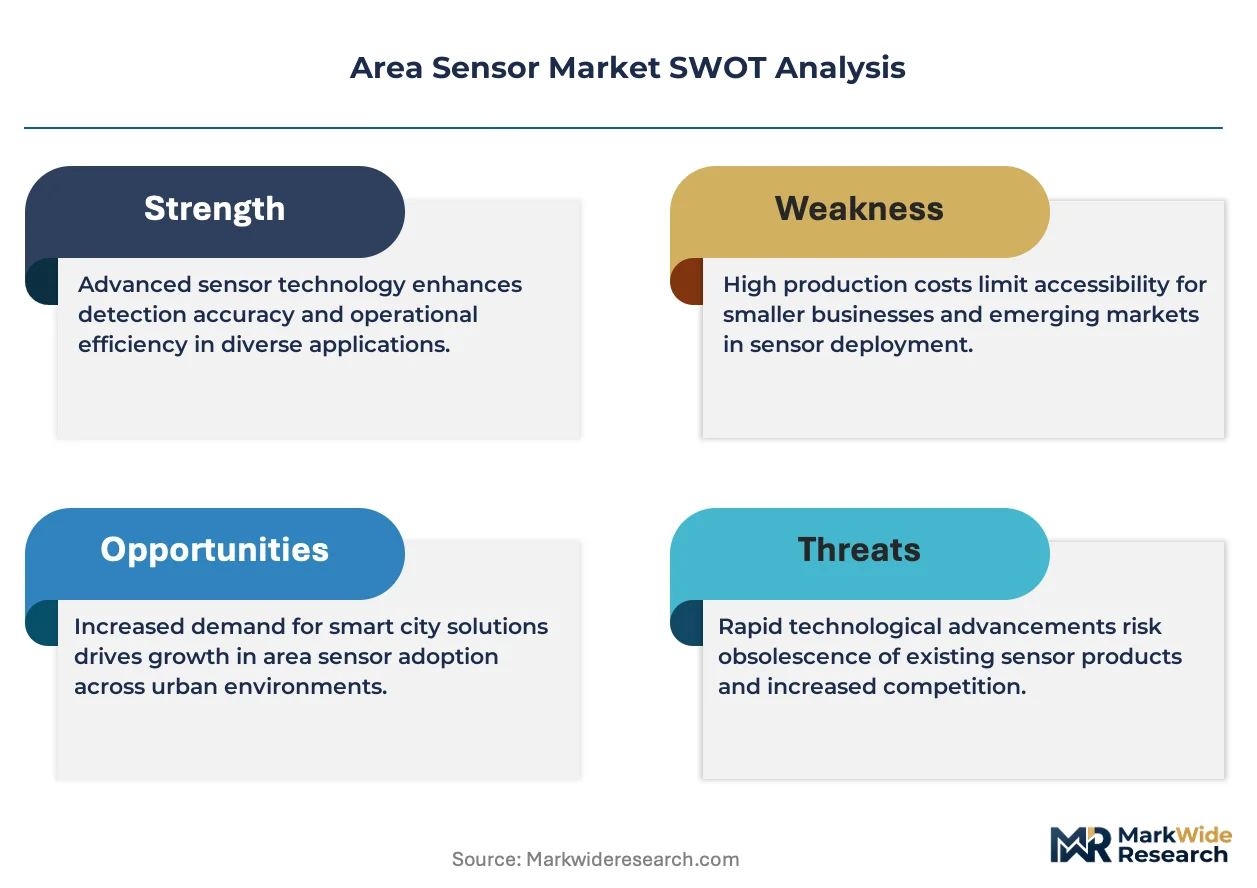
Growth Catalysts
- OSHA Machine Guarding Standards:North American factories must deploy redundant area sensor curtains on robotic cells, creating baseline demand for collision avoidance hardware.
- Automotive Cabin Monitoring:Time-of-Flight arrays enable driver attention tracking and occupant detection, pulling sensor volumes into passenger vehicle electronics.
- German Production Clusters:Stuttgart and Wolfsburg manufacturing density sustains concentrated demand for zone monitoring on automated welding and assembly lines.
Market Restraints
- Indium Gallium Arsenide Supply Concentration:Near-infrared detector materials face sourcing bottlenecks from limited specialty foundry capacity.
- EU AI Act Risk Classification:Safety-critical sensor fusion systems face extended conformity assessment timelines for high-risk AI designations.
- Lidar Substitution in Outdoor Security:Long-range perimeter applications increasingly favor scanning Lidar over fixed area arrays for extended detection ranges.
Strategic Opportunities
- Smart City Pedestrian Analytics:Traffic flow monitoring and crowd density management create new demand for edge-deployed detection grids.
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component production build captive demand for cleanroom and logistics zone sensors.
- Lidar-ToF Convergence:Solid-state scanning architectures blend time-of-flight pixel arrays with beam-steering optics for flexible detection zones.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 13849-1 and IEC 62061 certification expertise remains concentrated among veteran automation specialists.
- Legacy PLC Integration Friction:Decades-old industrial control systems require protocol gateways and signal conditioning hardware for modern sensor interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Area Sensor Market |
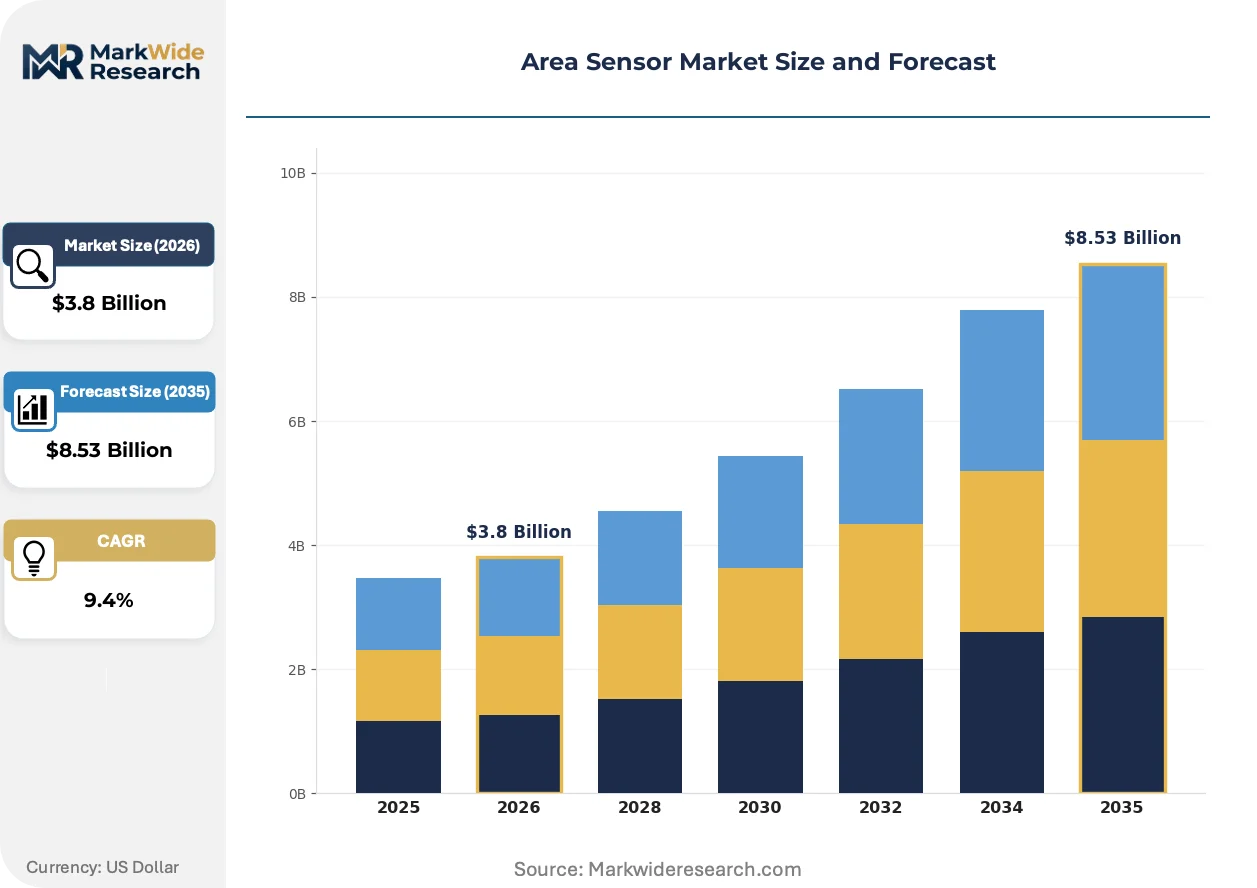
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Ultrasonic Sensors, Lidar Sensors, Microwave Sensors Technology: 2D Imaging, 3D Imaging, Time-of-Flight, Optical Application: Smart Homes, Security Systems, Automotive Safety, Industrial Automation End User: Manufacturing, Retail, Transportation, Smart Cities |
| Companies Covered | Cognex Corporation, Sick AG, Omron Corporation, STMicroelectronics, Rockwell Automation, Keyence Corporation, Banner Engineering, Texas Instruments, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Area Sensor Market Emerging Trajectories
Active sensing architectures are fragmenting into application-optimized variants as automotive, industrial, and consumer electronics buyers diverge on range, resolution, and cost requirements.
Time-of-Flight imagers is hybridizing with structured light patterns to achieve sub-millimeter depth precision for robotic bin-picking and surgical tool tracking. Medical device manufacturers in Switzerland and Germany are qualifying these hybrid modules for sterile field applications. The convergence is compressing price premiums between industrial safety and high-resolution metrology tiers.
EU AI Act risk classifications are forcing sensor vendors to document training data provenance and algorithmic transparency for safety-critical detection systems. Industrial automation OEMs in Bavaria and Lombardy are pre-certifying architectures to avoid deployment delays. The burden falls heaviest on multi-sensor fusion systems where AI-driven object classification triggers machine stops.
Aftermarket service unbundling is separating hardware warranties from calibration and predictive maintenance contracts. Japanese automotive suppliers now specify sensor-as-a-service terms for cabin monitoring deployments. The shift is most advanced in German automotive supply chains where Tier 1 integrators absorb lifecycle cost risk from OEM customers.
Area Sensor Market Segmentation
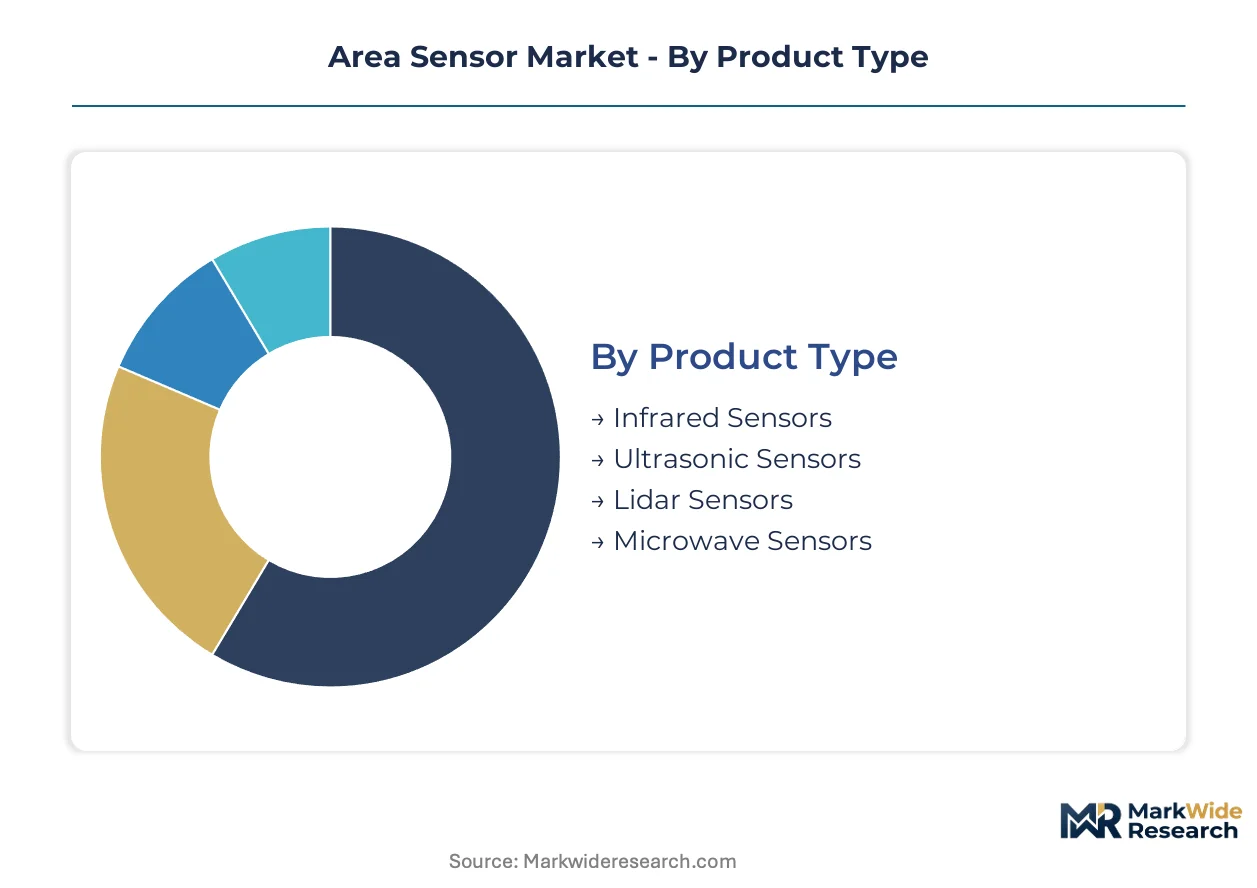
Area sensor procurement splits across four distinct category axes, each reflecting divergent buyer priorities on detection range, safety integrity, and integration complexity. Understanding these segment boundaries clarifies where technology substitution accelerates and where incumbent architectures retain pricing power.
Product Type:
Mature infrared and ultrasonic architectures dominate installed bases, while lidar and microwave variants capture emerging demand for extended-range and all-weather performance.
- Infrared Sensors:Near-infrared emitters paired with photodiode arrays detect thermal signatures and motion within enclosed industrial zones. German automotive suppliers specify these for welding cell perimeter monitoring where ISO 13849-1 mandates redundant detection curtains.
- Ultrasonic Sensors:Piezoelectric transducers emit high-frequency pulses to map proximity in dusty or vapor-laden environments. Japanese electronics manufacturers deploy these for cleanroom personnel tracking where optical contamination risks exclude camera-based alternatives.
- Lidar Sensors:Solid-state scanning modules command premium positioning in outdoor security perimeters.
- Microwave Sensors:Doppler-based architectures penetrate fog and precipitation for port and logistics yard applications.
Infrared sensors handle the majority of throughput; lidar sensors are the fastest mover on share.
Technology:
Cost tier separation runs deepest here, with 2D and optical variants anchoring economy positioning while 3D and Time-of-Flight architectures extract premiums for depth precision.
- 2D Imaging:Conventional camera sensors with edge-detection algorithms provide planar object recognition at lowest unit cost. Retail loss-prevention systems in US big-box chains standardize on these for aisle monitoring where depth data adds minimal value.
- 3D Imaging:Stereo vision and structured light systems reconstruct volumetric scenes for robotic bin-picking. Swiss medical device manufacturers qualify these architectures for surgical tool tracking in sterile fields.
- Time-of-Flight:Direct time-of-flight pixel arrays measure photon travel time for sub-centimeter depth accuracy. Automotive cabin monitoring in Stuttgart and Wolfsburg production clusters drives fastest volume expansion here.
- Optical:Passive photodetector arrays without active illumination serve ambient-light-dependent detection roles.
Optical technology handles the majority of throughput; Time-of-Flight is expanding most quickly on share.
Application:
Volume concentrates in industrial and automotive safety deployments, while smart home and security applications pull lower-specification units through consumer electronics channels.
- Smart Homes:Low-resolution presence detection modules enable lighting automation and HVAC occupancy triggers. US residential construction integrators specify these for new-build energy code compliance.
- Security Systems:Perimeter beam arrays and volumetric detectors protect commercial facilities. German banking and data center operators mandate redundant configurations under BSI technical guidelines.
- Automotive Safety:Cabin-monitoring ToF arrays and exterior proximity sensors satisfy NHTSA pedestrian detection proposals and Euro NCAP occupant classification requirements.
- Industrial Automation:Safety-rated light curtains and laser scanners enforce machine guarding on robotic cells. OSHA enforcement in Michigan and Ohio automotive supplier parks sustains replacement demand for legacy curtain installations.
Industrial automation handles the majority of throughput; automotive safety is climbing the fastest on share.
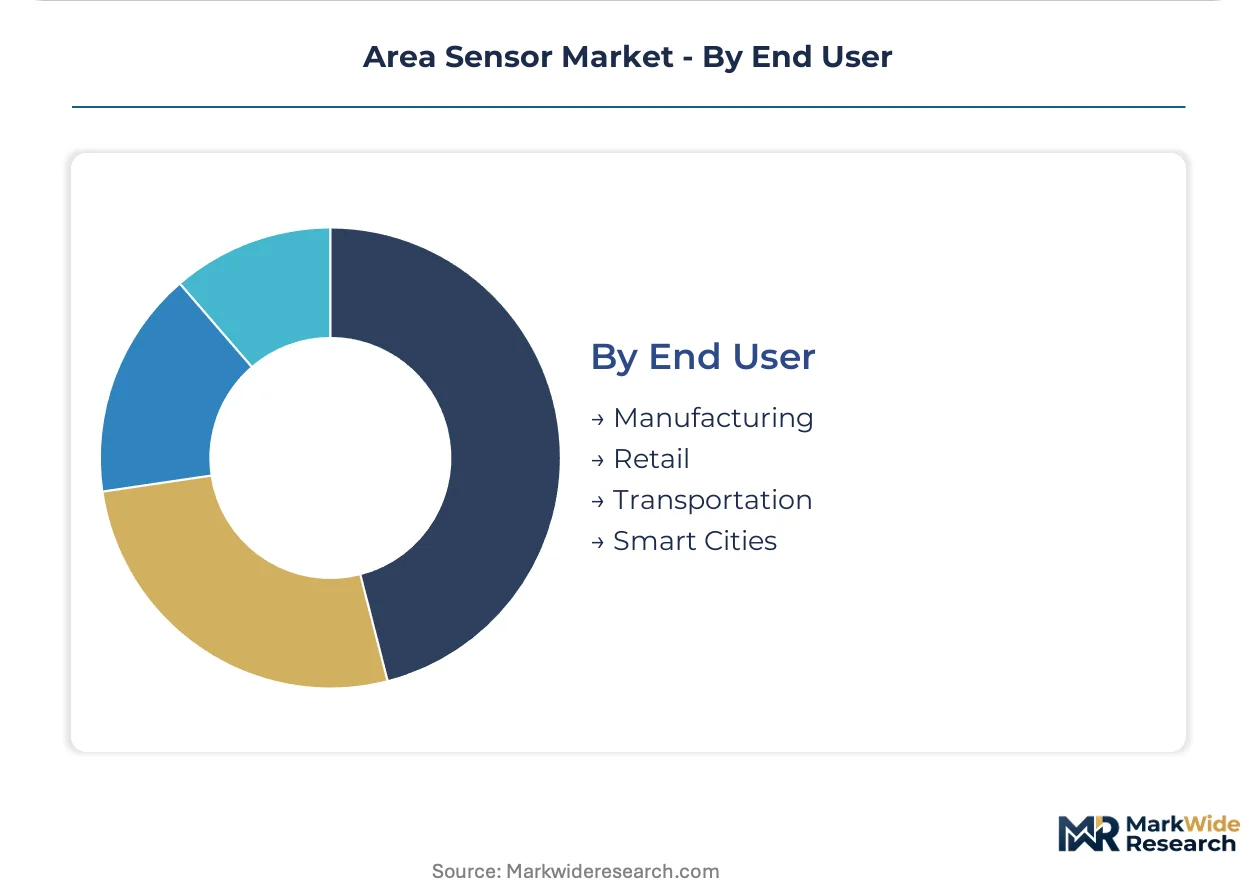
End User:
Customer type determines procurement sophistication, with manufacturing buyers demanding functional safety certification while retail and smart city adopters prioritize cost-per-detection-point metrics.
- Manufacturing:Tier 1 automotive and electronics producers specify SIL-rated sensors with documented mean time to dangerous failure data. Bavarian and Lombardy automation OEMs pre-certify architectures to compress deployment timelines.
- Retail:Footfall analytics and loss prevention drive demand for overhead people-counting arrays. Japanese convenience store chains deploy edge-processed detection grids to optimize staffing schedules.
- Transportation:Airport baggage handling and port crane systems require extended-range detection with vibration tolerance.
- Smart Cities:Traffic intersection monitoring and pedestrian flow analytics create demand for edge-deployed detection grids. Indian municipal corporations under Smart Cities Mission specifications trial these for congestion pricing enforcement.
Manufacturing handles the majority of throughput; smart cities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive factories consume area sensors primarily for redundant safety curtains, while Japanese electronics plants favor ultrasonic architectures in cleanroom environments. Indian PLI scheme beneficiaries are building fresh demand for logistics zone monitoring. US OSHA enforcement sustains replacement cycles in Midwest supplier parks.
United States
OSHA machine guarding standards mandate redundant sensor configurations on robotic welding cells in Michigan and Ohio automotive supplier corridors. NHTSA pedestrian detection proposals pull Time-of-Flight volumes into exterior proximity systems. Detroit-area Tier 1 integrators absorb lifecycle cost risk through sensor-as-a-service contracts with cabin monitoring deployments.
Germany
ISO 13849-1 safety integrity classifications force redundant detection curtains in Stuttgart and Wolfsburg production clusters. EU AI Act conformity assessment timelines extend for multi-sensor fusion systems triggering machine stops. Bavarian automation OEMs pre-certify architectures to compress deployment timelines for welding cell perimeter monitoring.
Japan
METI industrial automation incentives sustain concentrated demand for zone monitoring in Nagoya and Osaka electronics manufacturing belts. JIS standards govern cleanroom personnel tracking where optical contamination risks exclude camera-based alternatives. Japanese convenience store chains deploy edge-processed detection grids to optimize staffing schedules.
China
MIIT smart manufacturing directives accelerate sensor fusion adoption in Yangtze River Delta electronics assembly plants. GB standards for machine safety create baseline demand analogous to ISO frameworks elsewhere. Shenzhen and Dongguan component producers specify SIL-rated sensors with documented mean time to dangerous failure data.
India
PLI scheme incentives for semiconductor and component production build captive demand for cleanroom and logistics zone sensors. BIS certification requirements extend deployment timelines for imported safety-rated architectures. Karnataka and Tamil Nadu electronics manufacturing clusters trial edge-deployed detection grids for congestion pricing enforcement under Smart Cities Mission specifications.
Area Sensor Market Vendor Landscape
Capability concentration sits with specialized safety automation vendors; scale advantage sits with diversified electronics conglomerates. The vendor base stratifies across three tiers: functional safety specialists with ISO 13849-1 certification expertise, broad-line automation suppliers leveraging installed base relationships, and semiconductor fabricators pushing discrete sensor components. Dominant competitive moves include backward integration into photodetector foundry capacity and geographic expansion through direct sales channel establishment.
Within the functional safety specialist tier, Sick AG and Keyence Corporation exemplify divergent go-to-market architectures. Sick AG leverages its European installed base to sustain long-term service contracts, while Keyence Corporation anchors premium positioning through direct sales channels and rapid technical support. Cognex Corporation occupies a position bridging machine vision and area detection applications. These three represent the archetypal competitive positions: service-anchored incumbency, premium direct-sales aggression, and vision-to-safety extension.
| Leading Market Players |
|---|
| Cognex Corporation |
| Sick AG |
| Omron Corporation |
| STMicroelectronics |
| Rockwell Automation |
| Keyence Corporation |
| Banner Engineering |
| Texas Instruments |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Indium gallium arsenide foundry concentration in Taiwan and Japan concentrates margin capture with photodetector suppliers, pushing downstream sensor integrators toward long-term offtake contracts to secure volume allocation.
Pricing Analysis
Long-term offtake agreements dominate procurement for automotive Tier 1 suppliers, while spot purchasing persists in smart city and retail deployments. Three-tier pricing structure across safety-certified premium, industrial standard, and economy consumer tiers reflects ISO 13849-1 certification burden and response time specifications. Cost compression in the economy tier is intensifying because Chinese module producers are scaling Time-of-Flight pixel output. Manufacturing buyers in Germany exhibit lowest price sensitivity due to liability exposure, while Indian municipal smart city tenders drive aggressive per-detection-point benchmarking.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for infrared emitter and photodiode sourcing. Component supply concentrates in Taiwan, Japan, and South Korea for near-infrared detector die, while final module assembly clusters in China, Mexico, and Vietnam. Raw material dependencies include indium phosphide substrates, gallium arsenide epiwafers, and specialty glass optics. Single-source vulnerability persists at the epiwafer tier. Distribution runs through direct OEM channels for automotive and industrial safety volumes, with electronics distributors handling smart home and retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Area sensor penetration remains early-cycle in smart city pedestrian analytics and India electronics manufacturing, with Time-of-Flight cost curves enabling first-time adoption in price-sensitive municipal and consumer segments.
For Market Incumbents: Harden installed base retention by embedding predictive maintenance contracts into safety-rated sensor deployments, countering emerging sensor-as-a-service entrants. Deepen backward integration into photodetector foundry capacity to secure indium gallium arsenide supply allocation against fabless competitors. Prioritize ISO 13849-1 pre-certification investments to compress EU AI Act conformity timelines for multi-sensor fusion architectures. For New Entrants and Emerging Players: Build out cleanroom zone monitoring capabilities for India PLI scheme beneficiaries in Karnataka and Tamil Nadu, where captive demand is forming without entrenched incumbent relationships. Target smart city pedestrian analytics in Indian municipal deployments as the most penetrable geography, leveraging edge-processing cost advantages against legacy centralized systems. Pursue channel partnerships with industrial automation distributors rather than direct sales investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed functional safety specialists holding ISO 13849-1 certification expertise but lacking photodetector foundry control. Long-term viability hinges on defensible sensor fusion software stacks and recurring service revenue attachment rates. Watch NHTSA pedestrian detection rule finalization as inflection signal for automotive cabin monitoring volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photodetector Foundry Acquisition | Captive indium gallium arsenide supply secures margin against specialty material bottlenecks. |
| Sensor-as-a-Service Launch | Predictive maintenance bundling transforms transactional hardware sales into recurring revenue streams. |
| EU AI Act Pre-Certification | Documented algorithmic transparency compresses deployment timelines for safety-critical fusion systems. |
| India Direct Sales Expansion | PLI scheme electronics clusters create first-mover advantage before incumbent channel establishment. |
| Lidar-ToF Hybrid Development | Solid-state scanning architectures blend depth precision with flexible detection zone configuration. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry association disclosures. Interviews with plant engineers, OEM procurement teams, aftermarket service heads, and functional safety certification specialists informed demand-side validation. Secondary sources include OSHA enforcement records, EU AI Act implementation guidance, MIIT smart manufacturing directives, and SEC filings from listed automation suppliers. Bottom-up unit demand estimates triangulated against top-down market value reconstruction.
Forecast inputs span product type, technology tier, application vertical, and end-user procurement sophistication across the projection horizon. Modeled dimensions include detection range specifications, safety integrity levels, integration complexity, and regional regulatory cluster adoption patterns. CAGRs were derived from segment-level volume build-ups calibrated to macroeconomic drivers and replacement cycle dynamics. Industry-specific inputs include ISO 13849-1 certification penetration rates and Time-of-Flight cost curve trajectories.
Stress conditions across indium gallium arsenide supply disruption, EU AI Act timeline extension, and NHTSA rule implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution rates and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
MEMS Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Seismic Monitoring Equipment Market