
 Quartz Market | 2026-2036
Quartz Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Market Intelligence
ISO 9001:2015 certification cycles for raw material traceability is unwinding the competitive landscape for smaller quartz processors. Sibelco leverages its vertically integrated mining-to-distribution network across multiple continents. Cosentino Group anchors its position through captive engineered stone production and direct retail channel control. Jiangsu Pacific Quartz Co., Ltd specializes in semiconductor-grade crucible manufacturing, competing on purity thresholds that exceed standard industrial specifications.
Quartz is a crystalline silica mineral composed of silicon dioxide (SiO₂) with a Mohs hardness of 7, formed through igneous, metamorphic, and hydrothermal geological processes; its thermal stability up to 1,470°C and piezoelectric properties make it indispensable for frequency control devices, optical systems, and extreme-temperature industrial applications. Engineered stone dominates value capture in residential and commercial construction, while quartz sand and powder segments feed solar cell and glass manufacturing with thinner margin profiles. The countertops application commands premium pricing through brand-driven distribution, whereas solar cell demand pulls volume through polysilicon crucible consumption.
REACH registration requirements in Europe, China's GB standards for semiconductor materials enforced by SAMR, and the EPA's silica exposure limits in the United States collectively elevate compliance costs and consolidate supplier lists toward certified producers. The EU F-Gas Regulation indirectly pressures quartz demand by accelerating heat-pump deployment, which relies on precision frequency-control components. Stakeholders must monitor purity standard escalation in East Asian electronics supply chains and assess backward integration into high-grade ore reserves before qualification windows narrow.
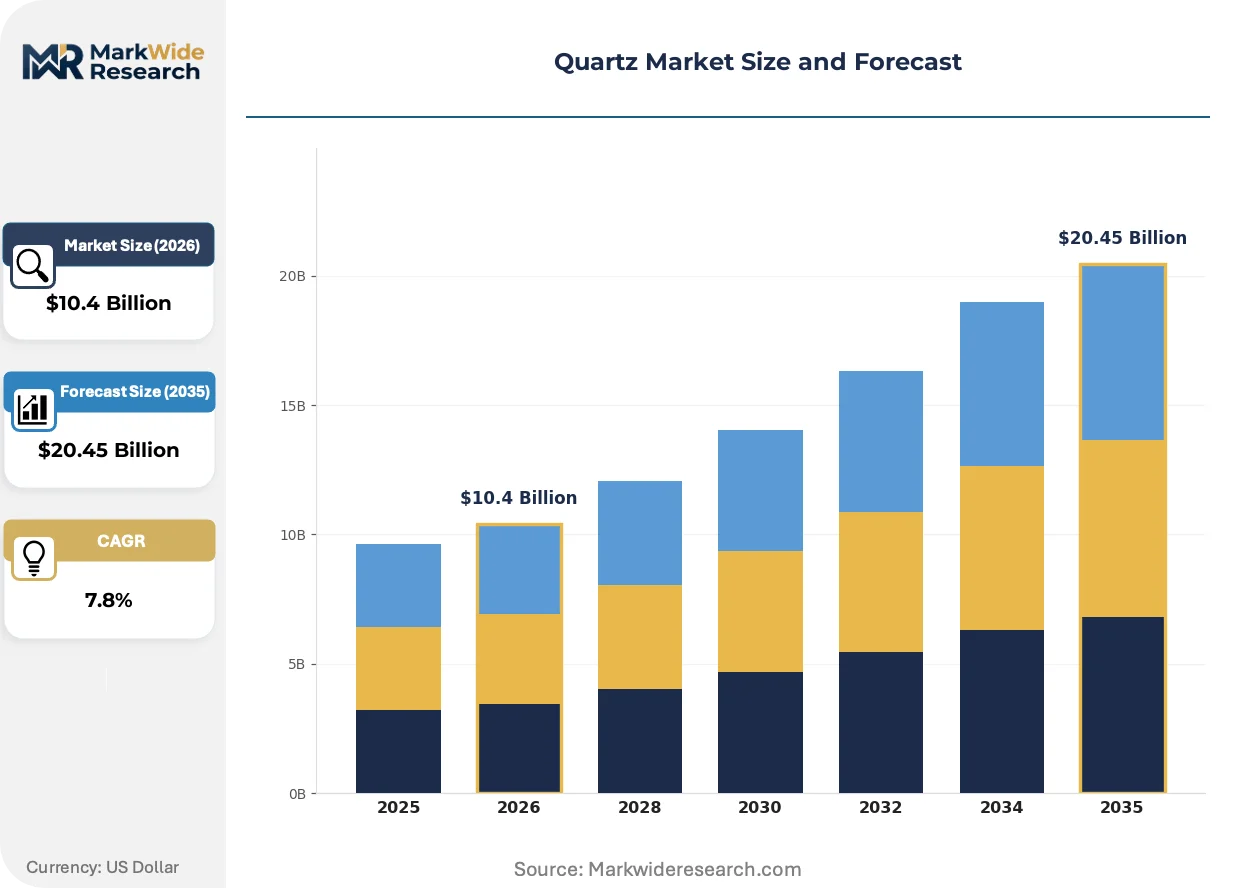
Market Dynamics
Semiconductor fabrication is concentrating demand for ultra-high-purity quartz crucibles around East Asian foundry clusters, tightening supplier qualification windows and compressing procurement cycles for legacy industrial-grade processors.
Growth Catalysts
- Semiconductor-grade purity thresholds:Foundries in South Korea and Taiwan now require crucible SiO₂ content exceeding 99.999% for polysilicon production, pulling investment toward specialized refining capacity.
- EU F-Gas Regulation:Accelerated heat-pump deployment across Germany and France is expanding demand for precision frequency-control components that rely on synthetic quartz resonators.
- China's dual carbon goals:Solar cell manufacturing expansion in Jiangsu and Anhui provinces is consuming record volumes of quartz sand for polysilicon crucibles.
Market Restraints
- High-purity ore concentration:Mineable deposits exceeding 99.95% SiO₂ concentrate in limited geographies, creating supply vulnerability for semiconductor-grade processors.
- REACH compliance costs:European processors face escalating registration and testing burdens for crystalline silica under ECHA guidelines, squeezing mid-tier competitors.
- Synthetic quartz substitution:Hydrothermal growth techniques for oscillator-grade material are displacing natural crystal in telecommunications applications.
Strategic Opportunities
- Indian solar manufacturing:PLI scheme subsidies for domestic photovoltaic cell production are opening crucible demand as the country builds polysilicon capacity.
- Quartz fiber optics:Medical laser systems and semiconductor inspection equipment are adopting pure silica fibers for ultraviolet transmission.
- Direct-to-fabricator channels:Engineered stone producers are bypassing distributor networks to secure slab supply through long-term offtake agreements with quartz processors.
Industry Challenges
- Metallurgical certification timelines:Semiconductor foundry qualification protocols now extend 18-24 months, locking out uncertified suppliers from high-margin segments.
- Specialized furnace engineering:Arc-fusion and electric-arc equipment for crucible production requires capital deployment that smaller processors cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Market |
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $20.45 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Stone, Natural Quartz, Quartz Sand, Quartz Powder End Use Industry: Construction, Electronics, Optical Components, Jewelry Application: Countertops, Flooring, Solar Cells, Glass Manufacturing Form: Granules, Slabs, Powders, Shapes |
| Companies Covered | Australian Silica Quartz Group Ltd, Caesarstone Ltd, The Quartz Corp., Hunter Quartz, Cosentino Group, Sibelco, Russian Quartz LLC, Hoshine Silicon Industry Co., Ltd, Jiangsu Pacific Quartz Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Market Strategic Shifts & Innovations
Quartz processing technology is diverging into two distinct technical tracks serving radically different purity specifications and end-use requirements.
Synthetic quartz crystal growth via hydrothermal methods is bifurcating the frequency-control component market. Telecommunications equipment manufacturers in Japan and South Korea now specify cultured material for 5G base station oscillators, compressing natural crystal demand to legacy automotive and industrial timing applications. This split is forcing raw material suppliers to choose between capital-intensive synthetic production or volume-focused natural stone processing.
REACH registration deadlines for crystalline silica are tightening purity documentation requirements across European supply chains. ECHA enforcement is compelling processors to implement batch-level traceability systems, with engineered stone fabricators facing the steepest compliance costs. German and Italian countertop manufacturers are consolidating supplier lists toward certified producers with in-house analytical laboratories.
Long-term offtake contracting is displacing spot-market purchasing among solar cell manufacturers. Polysilicon producers in China and Southeast Asia now secure multi-year crucible supply agreements directly with quartz processors, eliminating distributor intermediaries. This pattern concentrates procurement power with tier-one solar manufacturers while marginalizing smaller cell producers dependent on secondary supply channels.
Quartz Market Segmentation
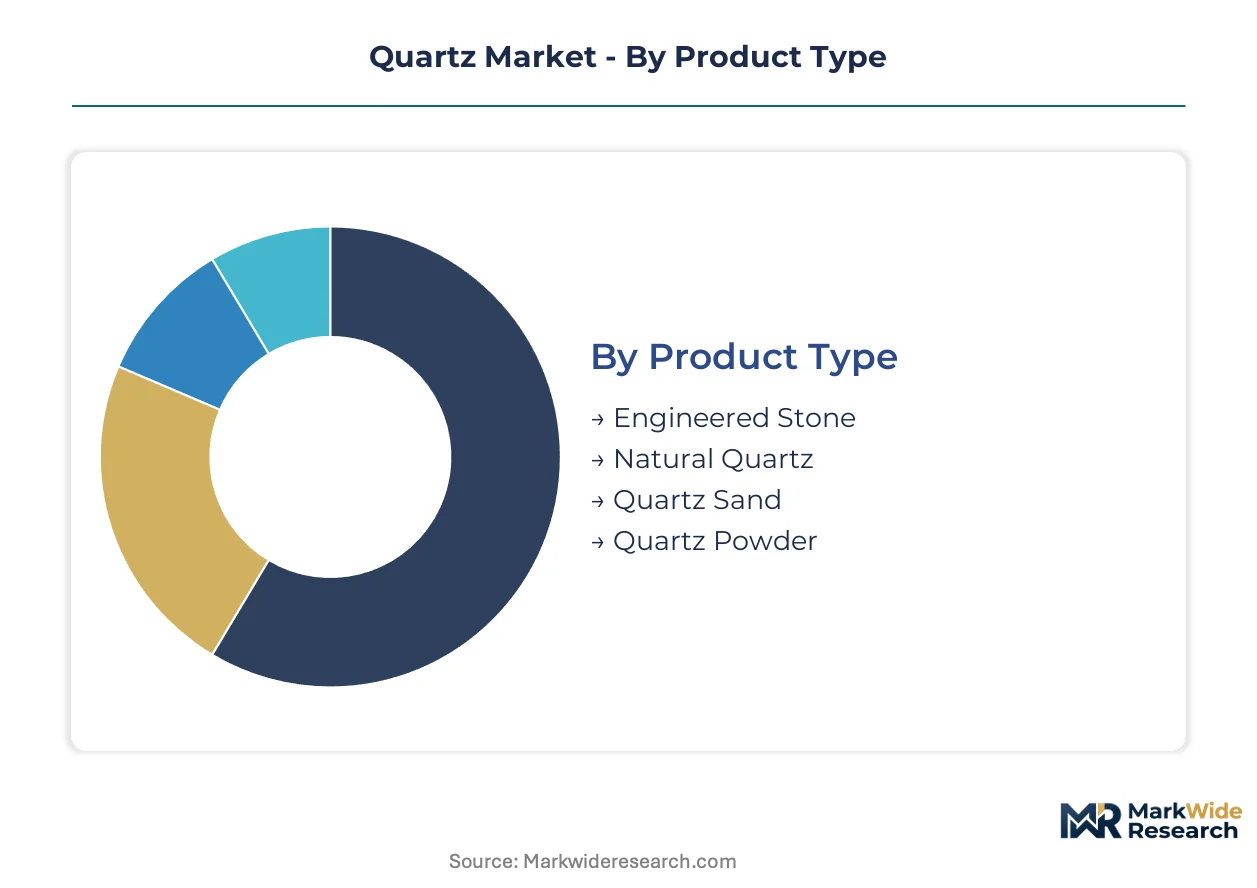
Quartz segmentation tracks divergent purity requirements across semiconductor fabrication, residential construction, and solar energy conversion. Each category isolates distinct margin pools shaped by certification barriers, ore grade scarcity, and end-use specification intensity.
Product Type:
Engineered stone and semiconductor-grade refined products command the widest margin spreads due to brand premiums and purity thresholds that exclude commodity processors.
- Engineered Stone:Polymer-resin bound quartz aggregate formed under vacuum vibration into slabs. Cosentino Group and Cambria anchor demand through captive retail distribution in North American and European kitchen renovation markets. REACH compliance costs for crystalline silica documentation are consolidating European supplier lists toward certified producers with in-house laboratories.
- Natural Quartz:Raw crystalline SiO₂ mined from pegmatite and hydrothermal vein deposits. Brazil and Madagascar host the largest mineable reserves of optical-grade material. Jewelry and precision optics manufacturers specify inclusion-free crystals that command 10-20x premiums over industrial grades.
- Quartz Sand:Crushed and washed silica aggregate with SiO₂ content typically ranging from 95% to 99.5%. Foundry and glass manufacturers in China and India consume volume through container glass and construction-grade production.
- Quartz Powder:Micronized silica flour serving ceramic glazes, refractory linings, and filler applications. Paint and coatings formulators in Germany and Japan specify controlled particle size distributions.
Engineered stone holds installed capacity. Quartz powder is rotating up the share rankings as ceramic and coatings formulators seek controlled particle distributions.
End Use Industry:
Electronics manufacturing concentrates the highest purity premiums, while construction absorbs volume through lower-specification engineered stone and glass feedstocks.
- Construction:Residential and commercial building applications spanning countertops, cladding, and flooring. US and Chinese real estate cycles drive demand volatility, with engineered stone substitution accelerating against granite and marble in urban kitchen renovations.
- Electronics:Semiconductor crucible manufacturing, frequency-control oscillators, and photovoltaic polysilicon production. South Korean and Taiwanese foundries now require crucible SiO₂ content exceeding 99.999%, pulling investment toward specialized refining capacity in East Asia.
- Optical Components:Lenses, prisms, and windows for ultraviolet lithography and laser systems. Synthetic quartz growth via hydrothermal methods is displacing natural crystal in telecommunications applications.
- Jewelry:Cut and polished crystalline specimens for ornamental use. Artisan cutters in Brazil and Arkansas serve collector markets with inclusion-free specimens.
Electronics holds installed capacity. Construction is rotating up the share rankings as urban renovation cycles accelerate engineered stone penetration.
Application:
Solar cell manufacturing is climbing the fastest as polysilicon capacity expansion in China and India pulls crucible demand, while countertops maintain revenue concentration through brand-premium distribution.
- Countertops:Engineered stone slabs fabricated into residential and commercial surface installations. Direct-to-fabricator channels are bypassing distributor networks through long-term offtake agreements with quartz processors.
- Flooring:Terrazzo and tile applications using quartz aggregate as decorative and wear-resistant filler. Commercial specification in airports and hospitals favors slip-resistant engineered surfaces.
- Solar Cells:Polysilicon production crucibles consuming high-purity quartz sand and synthetic silica. China's dual carbon goals are expanding manufacturing in Jiangsu and Anhui provinces, while India's PLI scheme subsidies open crucible demand for domestic photovoltaic capacity.
- Glass Manufacturing:Container, flat, and specialty glass production using quartz sand as primary silica feedstock. Float glass producers in Germany and the United States face energy cost pressures that favor lower-purity local sand over imported high-grade material.
Countertops holds installed capacity. Solar cells is rotating up the share rankings as polysilicon capacity expansion accelerates crucible consumption.
Form:
Slabs and shapes concentrate value-added processing, while granules and powders serve commodity volume markets with thinner margin profiles.
- Granules:Sized crushed quartz serving filtration, foundry mold, and abrasive blasting applications. Water treatment plants in France and Japan specify uniform grain distributions for pressure filter media.
- Slabs:Engineered stone and natural quartz blocks cut into dimensional panels for architectural surfacing. Italian and Spanish fabricators dominate value-added finishing for European luxury residential markets.
- Powders:Micronized silica for ceramic, rubber, and paint formulations. BIS certification requirements in India are tightening quality documentation for import substitution programs.
- Shapes:Custom-machined quartz components including crucibles, wafer carriers, and optical blanks. Semiconductor foundry qualification protocols now extend 18-24 months, locking out uncertified suppliers from high-margin segments.
Slabs holds installed capacity. Shapes is rotating up the share rankings as semiconductor equipment manufacturers specify custom-machined high-purity components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundry procurement teams and solar cell manufacturers drive regional demand concentration, with East Asian electronics corridors commanding premium-grade supply and European engineered stone fabricators shaping certification requirements.
China
Polysilicon crucible consumption in Jiangsu and Anhui provinces is accelerating under Beijing's dual carbon goals, while SAMR enforces GB standards for semiconductor-grade purity. The Yangtze River Delta cluster around Shanghai anchors domestic high-purity quartz refining capacity for foundry supply.
South Korea
Samsung and SK Hynix foundries now specify crucible SiO₂ content exceeding 99.999%, compressing supplier qualification windows toward certified processors. MFDS oversight of industrial chemical registration is tightening documentation requirements for imported quartz components. The Seoul Capital Area concentrates demand for frequency-control resonators in 5G base station manufacturing.
Germany
Heat-pump deployment across Bavaria and North Rhine-Westphalia is expanding demand for precision oscillator components under the EU F-Gas Regulation. ECHA enforcement of REACH registration for crystalline silica is consolidating supplier lists toward certified producers with in-house analytical laboratories. The Eindhoven-adjacent corridor (cross-border with Netherlands) serves precision optics fabrication.
United States
Engineered stone countertop demand in Texas and Florida renovation markets is pulling volume through direct-to-fabricator channels. EPA silica exposure limits under OSHA enforcement are elevating compliance costs for domestic processors. The Southeast manufacturing belt is absorbing quartz sand feedstock for container glass production.
India
PLI scheme subsidies for domestic photovoltaic cell production are opening crucible demand as polysilicon capacity builds in Gujarat and Rajasthan. BIS certification requirements are tightening quality documentation for import substitution programs. The Maharashtra industrial corridor is attracting quartz powder processors serving ceramic glaze formulators.
Quartz Market Key Industry Players
Player mix skews toward vertically integrated mining-to-refining conglomerates and specialized semiconductor-grade processors, with mid-tier industrial sand suppliers facing margin compression from purity standard escalation. Strategic archetypes include captive ore reserve holders, synthetic crystal growth specialists, and engineered stone brand owners. Dominant competitive moves center on backward integration into high-grade ore reserves and long-term offtake contracting with solar cell manufacturers.
Among Asia-Pacific-based refiners, Jiangsu Pacific Quartz Co., Ltd and Hoshine Silicon Industry Co., Ltd exemplify the semiconductor-grade specialization archetype, while Sibelco represents the geographically diversified mining conglomerate model. Cosentino Group anchors the engineered stone vertical through captive retail channel control. These three entities occupy positions that reflect the market's bifurcation between purity-driven electronics supply and brand-premium construction materials.
| Leading Market Players |
|---|
| Australian Silica Quartz Group Ltd |
| Caesarstone Ltd |
| The Quartz Corp. |
| Hunter Quartz |
| Cosentino Group |
| Sibelco |
| Russian Quartz LLC |
| Hoshine Silicon Industry Co., Ltd |
| Jiangsu Pacific Quartz Co., Ltd |
| Others |
Cost & Logistics Intelligence
Synthetic quartz hydrothermal growth displacing natural crystal in telecommunications oscillators simultaneously redraws supply geography toward Japan and South Korea while compressing natural stone pricing power in legacy timing markets. This substitution dynamic concentrates high-margin frequency-control supply in East Asian crystal growth facilities while forcing natural quartz processors toward volume-driven solar and construction segments with thinner margin profiles.
Pricing Analysis
Cost-plus contracts indexed to high-purity ore spot prices dominate semiconductor-grade crucible procurement, with South Korean foundries layering qualification premiums atop base material costs. Price differentiation separates 99.999% SiO₂ semiconductor crucibles from 99.5% solar-grade material through SAMR certification tiers and 18-24 month foundry approval timelines. Cost compression in engineered stone runs through REACH compliance documentation burdens that marginalize uncertified European processors. Solar cell manufacturers exhibit highest price sensitivity due to polysilicon margin pressures, while semiconductor foundries prioritize purity guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of high-purity ore reserves distinguishes qualified semiconductor suppliers from just-in-time industrial sand processors exposed to spot volatility. Mineable deposits exceeding 99.95% SiO₂ concentrate in Brazil, Madagascar, and select US Appalachian veins, creating geographic supply vulnerability for crucible manufacturers. Raw material sourcing draws from pegmatite mining, hydrothermal vein extraction, and synthetic crystal growth feedstock. Single-source vulnerability intensifies around East Asian foundry clusters dependent on limited qualified crucible suppliers. Distribution runs through direct-to-fabricator long-term offtake agreements displacing spot-market intermediaries in solar and engineered stone channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where SAMR semiconductor-grade certification and REACH crystalline silica registration create switching costs that lock buyers into qualified supplier relationships.
For Market Incumbents: Shield market position through captive high-grade ore reserve acquisition in Brazil and Madagascar before qualification windows narrow further. Accelerate in-house analytical laboratory investment to meet ECHA batch-level traceability requirements. Synthetic quartz substitution in telecommunications threatens natural crystal demand; pivot refining capacity toward solar crucible growth. Backward integration into ore reserves remains the priority defensive lever against supply concentration risk.
For New Entrants and Emerging Players: Anchor in Indian solar manufacturing corridors where PLI scheme subsidies are building polysilicon capacity without entrenched crucible supply relationships. Target quartz fiber optics for medical laser and semiconductor inspection equipment as a penetrable high-purity niche outside foundry qualification barriers. Pursue direct-to-fabricator engineered stone offtake agreements in Texas and Florida renovation markets bypassing distributor networks. Technical partnership with established ore reserve holders offers the most viable go-to-market path.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mining-to-refining specialists with certified semiconductor-grade capacity. Long-term viability over the next decade hinges on positioning ahead of purity standard escalation in East Asian electronics supply chains. Acquisition targets should display captive ore reserves, in-house analytical capabilities, and active foundry qualification pipelines. Watch for SAMR enforcement intensity and ECHA REACH registration deadline acceleration as inflection indicators that would compress uncertified supplier viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Grade Ore Reserves | Secures supply security for SAMR-qualified semiconductor crucible production against deposit scarcity. |
| In-House Analytical Laboratory Investment | Enables ECHA-compliant batch-level traceability for engineered stone REACH registration requirements. |
| Long-Term Offtake Agreement with Solar Manufacturers | Locks volume commitment from Jiangsu and Anhui polysilicon producers building under dual carbon goals. |
| Synthetic Quartz Hydrothermal Growth Capacity | Captures 5G base station oscillator demand from Japanese and South Korean telecommunications equipment manufacturers. |
| Direct-to-Fabricator Channel Bypass | Eliminates distributor margin extraction in North American engineered stone countertop markets. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with semiconductor foundry procurement directors, engineered stone fabricator supply chain managers, solar cell manufacturer material planners, and quartz processor plant engineers; alongside secondary validation through SAMR GB standard filings, ECHA REACH registration databases, SEC 10-K disclosures from listed processors, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across purity tiers and end-use segments.
Across the analysis window, the forecasting framework modeled segmentation by product type, end-use industry, application, and form factor. CAGRs derived from trend extrapolation of foundry capacity expansion, solar installation deployment, and residential renovation cycle intensity. Industry-specific inputs included polysilicon crucible consumption coefficients per gigawatt of photovoltaic capacity and semiconductor wafer start volumes by foundry location.
Decision-makers should treat outputs as directional under assumptions of continued East Asian electronics manufacturing concentration and stable ore deposit accessibility; material deviation would warrant model refresh. Specific risks that could revise trajectories include SAMR purity standard escalation beyond current 99.999% thresholds, ECHA REACH enforcement intensity variation, and synthetic quartz substitution acceleration in frequency-control applications. Revision becomes warranted when synthetic crystal growth cost curves cross natural material parity in telecommunications oscillator specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Polysilicon Market