
 Silicon Carbide (Sic) Coating Market | 2026-2036
Silicon Carbide (Sic) Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Carbide (Sic) Coating Market Analytics
Chinese chemical vapor deposition capacity is shifting toward larger-diameter reactor platforms for semiconductor-grade SiC coatings. Mersen Group leverages vertical integration from graphite substrates to finished coated components, sustaining quality control across its French and US manufacturing footprint. Tokai Carbon dominates isotropic graphite precursor supply for CVD processes, while SGL Carbon competes through specialized carbon-carbon composite substrates optimized for thermal shock resistance in aerospace applications.
Silicon carbide coating refers to thin ceramic layers deposited onto base materials to impart extreme hardness, thermal conductivity exceeding 120 W/m·K, and oxidation resistance above 1,600°C for protective and functional surfaces. CVD technology leads in semiconductor device applications where epitaxial SiC film uniformity determines power module performance, while spray coating occupies cost-sensitive energy-sector segments for large-area heat sink protection. Bulk coatings command premium pricing in aerospace wear-resistant parts where thickness tolerance directly impacts component fatigue life.
EPA emissions standards constrain solvent-based spray coating formulations in US manufacturing facilities, while REACH chemical registration requirements in Europe elevate compliance costs for PVD precursor materials. Japan's METI supports domestic CVD equipment development through industrial technology grants, reinforcing local supply chain resilience for power electronics. Stakeholders must monitor divergence between EPA and EU Green Deal carbon intensity benchmarks as coating process energy consumption becomes a procurement differentiator for automotive OEMs.
Market Dynamics
CVD reactor scaling toward 300mm wafer compatibility is compressing coating uniformity tolerances while EPA emissions enforcement tightens solvent-based process economics. Semiconductor power module manufacturers now specify sub-micron thickness control as a procurement gate, forcing coating suppliers to integrate metrology into production lines.
Growth Catalysts
- EPA emissions rules:Solvent-based spray coating restrictions in US manufacturing facilities accelerate CVD equipment replacement cycles. Semiconductor fabs in Texas and Arizona prioritize zero-emission deposition processes to secure environmental permits.
- Power electronics:Electric vehicle inverter manufacturers specify SiC-coated heat spreaders for thermal management above 200°C junction temperatures. Automotive OEM procurement contracts now mandate 10-year coating adhesion warranties.
- German precision ceramics clusters:Concentrated supplier ecosystems around Stuttgart and Munich enable rapid prototyping for aerospace turbine blade coatings. Local technical universities feed specialized CVD process engineering talent directly into coating facilities.
Market Restraints
- Isotropic graphite precursor concentration:Tokai Carbon controls over 60% of semiconductor-grade graphite substrate supply for CVD processes. Japanese earthquake exposure creates single-source vulnerability for European and North American coating manufacturers.
- Trichlorosilane feedstock volatility:Chlorosilane prices fluctuate with polysilicon production cycles, compressing coating margins during solar manufacturing demand spikes. Spot market exposure affects smaller CVD operators without long-term chemical supply contracts.
- Thickness uniformity limitations:Spray coating processes cannot achieve the sub-5% thickness variation required for epitaxial semiconductor applications. This technical ceiling excludes spray methods from power module substrate production regardless of cost advantage.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor manufacturing attract CVD equipment investment toward Gujarat and Karnataka. Domestic coating service providers can capture value from imported wafer processing equipment installation.
- EU Green Deal carbon intensity benchmarking:Coating process energy consumption becomes a procurement differentiator for automotive OEM supplier selection. Low-carbon CVD facilities in France and Germany gain preferred supplier status.
- Plasma-enhanced CVD and atomic layer deposition convergence:Hybrid deposition techniques enable conformal coating of complex 3D heat exchanger geometries. Industrial gas turbine aftermarket maintenance contracts specify these advanced methods for blade refurbishment.
Industry Challenges
- CVD process engineering talent scarcity:Specialized reactor optimization skills concentrate among aging technicians at established semiconductor equipment manufacturers. University programs in materials science lack practical deposition system training modules.
- AS9100D aerospace certification timelines:Coating suppliers face 18-24 month qualification periods for new deposition processes on flight-critical components. Boeing and Airbus supplier audits require extensive thermal cycling test documentation.
- Legacy spray coating asset strandedness:US facilities with substantial solvent-based equipment investment face write-down pressure under EPA Maximum Achievable Control Technology enforcement. Capital recovery timelines conflict with regulatory compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Carbide (Sic) Coating Market |
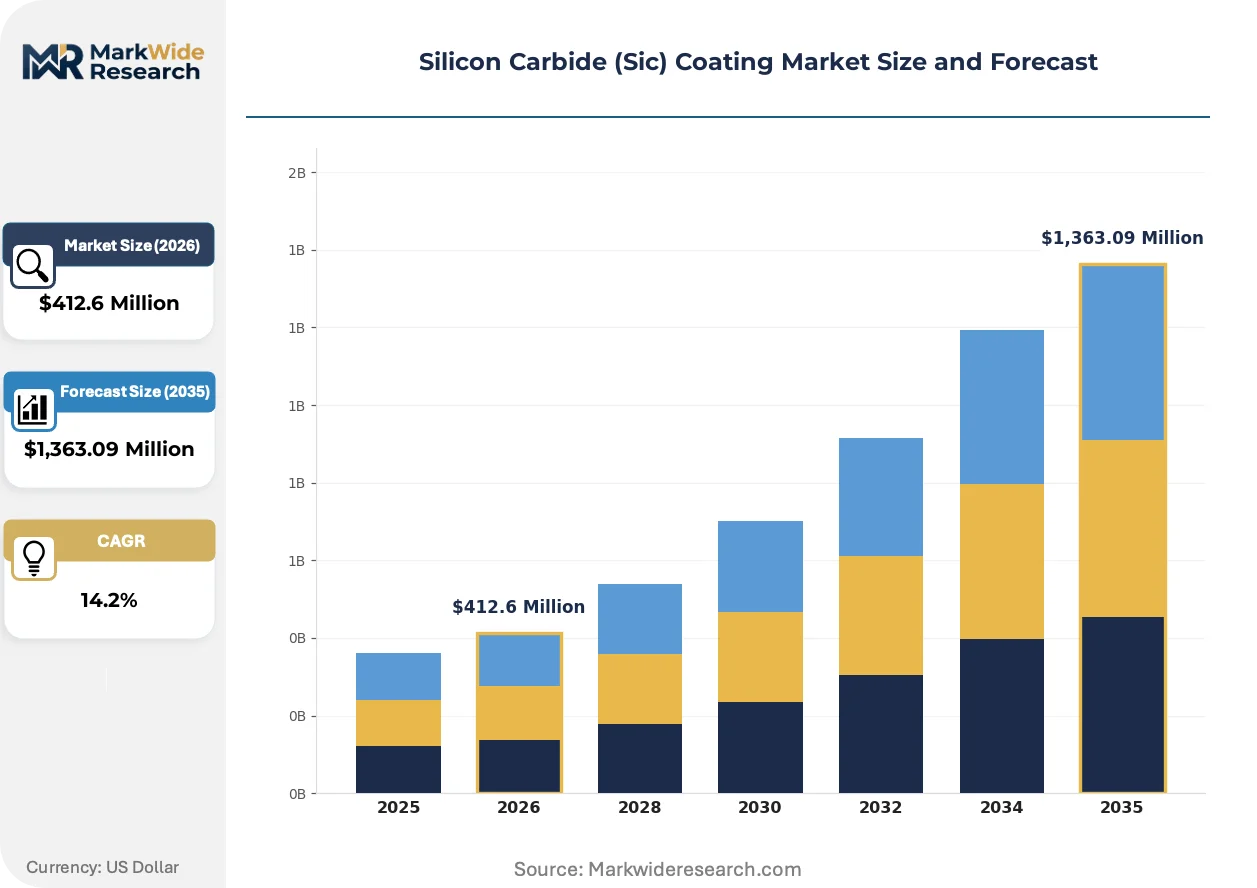
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Films, Bulk Coatings, Composite Coatings, Ceramic Coatings End User: Aerospace, Automotive, Electronics, Energy Application: Wear-Resistant Parts, Heat Sinks, Power Modules, Semiconductor Devices Technology: CVD, PVD, Spray Coating, Sol-Gel |
| Companies Covered | Mersen Group, Tokai Carbon, Toyo Tanso, SGL Carbon, CoorsTek, Morgan Advanced Materials, Ferrotec, AGC, Edgetech Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Carbide (Sic) Coating Market Evolving Landscape
Deposition technology diversification is fragmenting the coating equipment supply base while regulatory carbon accounting forces process energy transparency. Equipment buyers now evaluate total cost of ownership across electricity consumption, precursor utilization rates, and waste treatment requirements.
Plasma-enhanced chemical vapor deposition is decentralizing thermal management coating production from centralized mega-fabs toward regional service centers. Mid-size automotive suppliers in Michigan and Bavaria now operate in-house PECVD systems for heat sink finishing. This distributed model compresses logistics costs and enables just-in-time coating sequences synchronized with machining operations.
REACH chemical registration requirements in Europe are elevating precursor material compliance costs for PVD coating operations. ECHA substance evaluation dossiers now cover chlorosilane derivatives used in semiconductor-grade deposition. Coating suppliers serving German automotive OEMs must maintain full supply chain substance documentation to retain preferred supplier status under CSRD extended reporting mandates.
Automotive OEM technical specifications are consolidating coating qualification requirements across multiple component categories. Tier-1 suppliers now face unified thermal conductivity and adhesion test protocols replacing previously fragmented OEM-specific standards. This specification harmonization concentrates coating procurement among suppliers with multi-OEM approved processes, particularly visible in German and Japanese supply chain restructuring.
Silicon Carbide (Sic) Coating Market Segmentation
Coating thickness tolerances and deposition uniformity requirements fragment procurement specifications across semiconductor fabs, aerospace OEMs, and energy infrastructure operators. Each end-use imposes distinct technical gatekeepers that filter supplier eligibility.
Product Type:
Supply concentration in CVD reactor platforms favors manufacturers with integrated precursor-to-coating control.
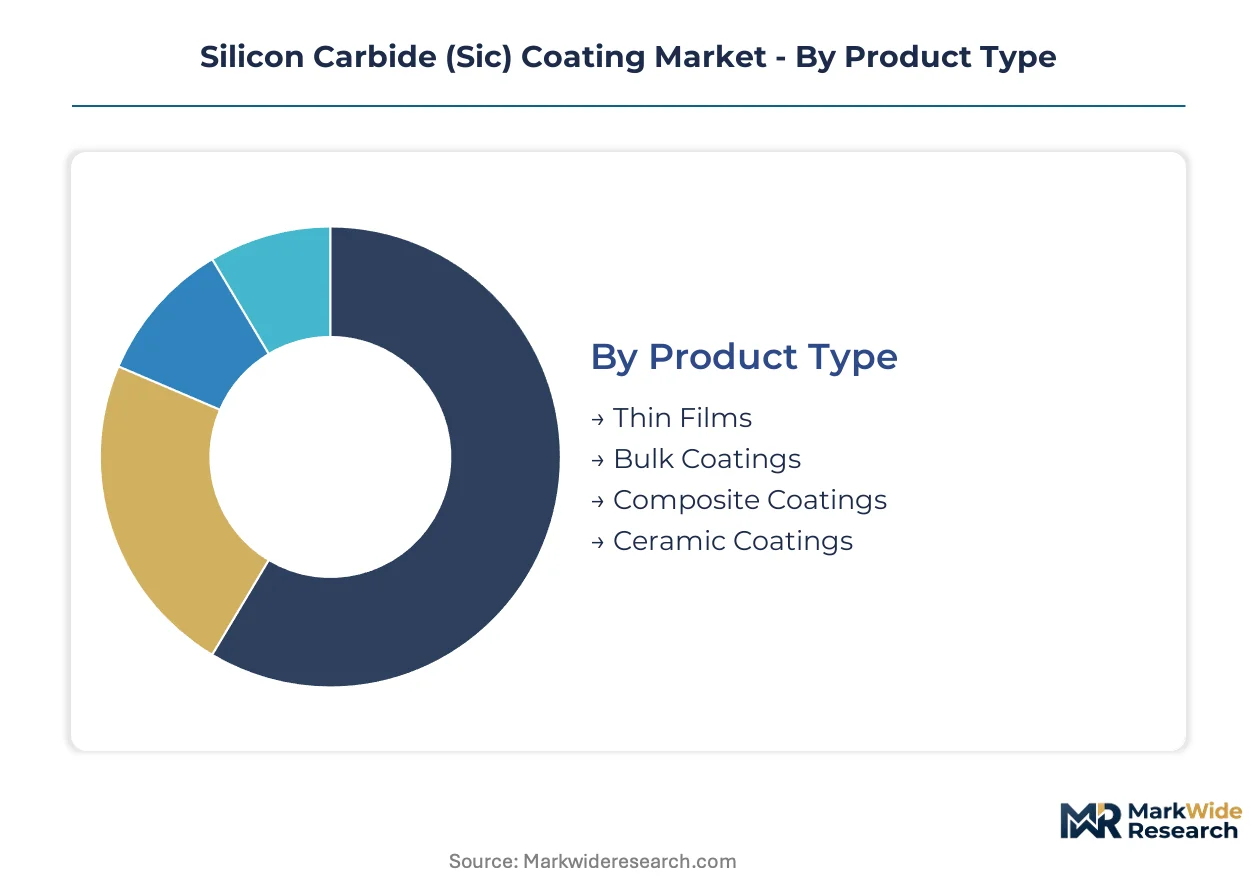
- Thin Films:Epitaxial layers below 10 micrometers dominate semiconductor device manufacturing where sub-micron thickness uniformity gates power module performance. Automotive inverter suppliers in Germany and Japan specify these coatings for 200°C junction temperature operation.
- Bulk Coatings:Millimeter-thick deposits protect aerospace turbine blades from thermal fatigue and particle erosion. Thickness tolerance directly impacts component fatigue life, commanding premium pricing from AS9100D-certified suppliers.
- Composite Coatings:Hybrid ceramic-matrix systems optimize carbon-carbon substrates for thermal shock resistance.
- Ceramic Coatings:Oxidation-resistant layers above 1,600°C protect industrial gas turbine hot-section components.
Thin films absorb the bulk of installed capacity; bulk coatings are expanding most quickly in aerospace aftermarket maintenance.
End User:
Customer procurement power concentrates among automotive OEMs consolidating supplier bases under unified technical specifications.
- Electronics:Semiconductor device manufacturers specify CVD-deposited SiC for power module substrates. EPA emissions enforcement in US fabrication facilities accelerates zero-emission deposition process adoption.
- Automotive:Electric vehicle inverter procurement mandates 10-year coating adhesion warranties on heat spreaders. OEM technical specifications harmonize thermal conductivity test protocols across German and Japanese supply chains.
- Aerospace:Boeing and Airbus supplier audits require 18-24 month AS9100D qualification timelines for flight-critical components.
- Energy:Heat sink protection for grid-scale power electronics favors cost-sensitive spray coating methods.
Electronics commands the dominant share of precision deposition capacity; automotive is climbing the fastest as EV inverter volumes scale.
Application:
Functional requirements stratify deposition technology selection between precision CVD and cost-driven spray methods.
- Semiconductor Devices:Epitaxial film uniformity determines power module electrical performance. Sub-5% thickness variation requirements exclude spray coating from this segment entirely.
- Power Modules:Thermal management substrates integrate SiC-coated heat spreaders for high-temperature operation. METI industrial technology grants reinforce Japanese domestic CVD equipment supply chain resilience.
- Wear-Resistant Parts:Aerospace blade coatings withstand particle erosion and thermal cycling degradation.
- Heat Sinks:Large-area protection for energy-sector equipment prioritizes deposition economics over precision.
Semiconductor devices anchor CVD equipment utilization; power modules are gaining share fastest with automotive electrification.
Technology:
Process energy consumption and precursor utilization rates determine total cost of ownership in equipment procurement decisions.
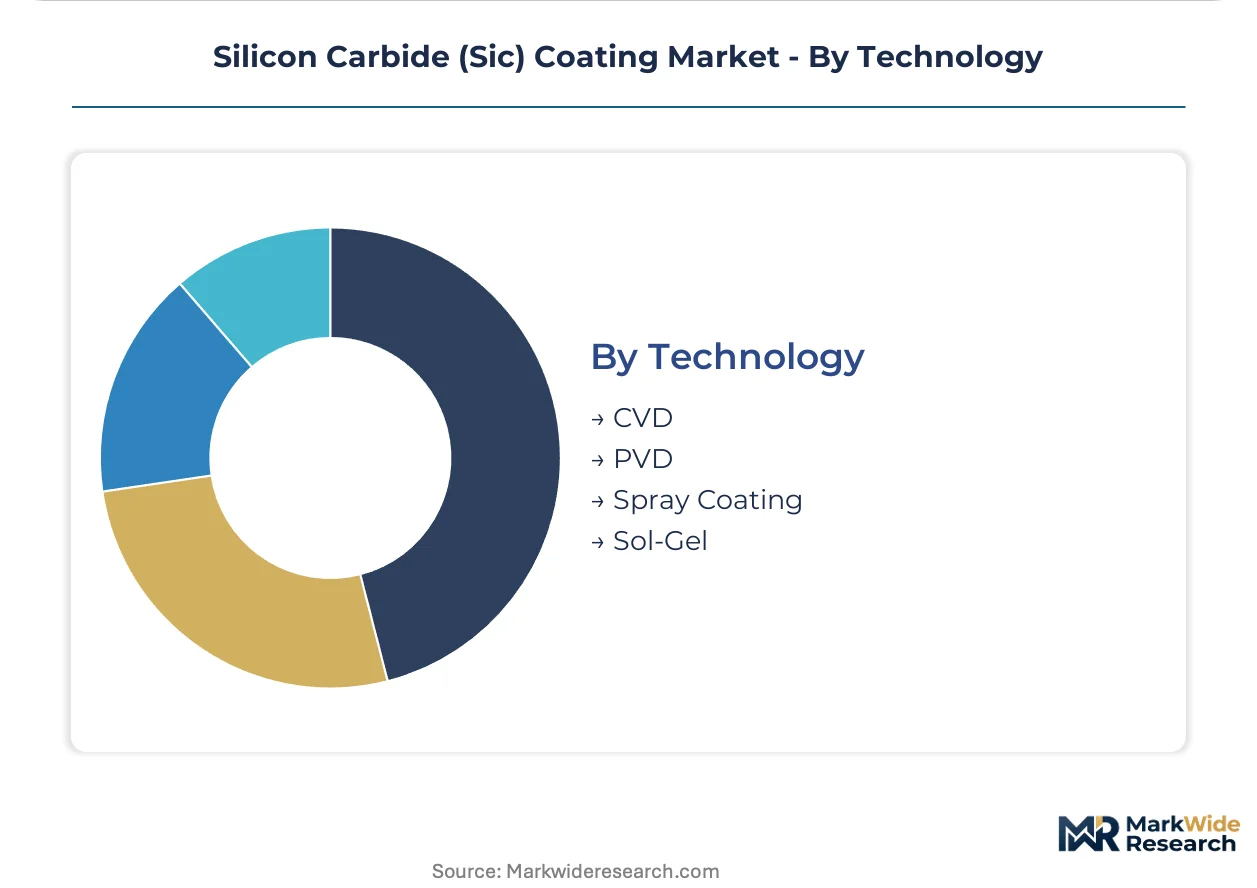
- CVD:Chemical vapor deposition achieves epitaxial film uniformity required for semiconductor applications. Reactor scaling toward 300mm wafer compatibility compresses coating tolerance specifications.
- Spray Coating:Solvent-based formulations face EPA Maximum Achievable Control Technology enforcement pressure in US facilities. Legacy equipment strandedness accelerates capital write-downs.
- PVD:Physical vapor deposition serves specialized aerospace coating requirements with REACH compliance cost elevation in Europe.
- Sol-Gel:Low-temperature ceramic formation suits temperature-sensitive substrate materials.
CVD holds the dominant installed base; plasma-enhanced CVD variants are expanding most quickly for distributed automotive supplier operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isotropic graphite precursor supply from Japanese manufacturers anchors CVD coating capacity distribution across major semiconductor fabrication hubs. EPA emissions enforcement and EU Green Deal carbon intensity benchmarks reshape facility investment decisions in established manufacturing corridors.
United States
Texas and Arizona semiconductor fabs accelerate zero-emission CVD equipment procurement to secure environmental permits under EPA Maximum Achievable Control Technology rules. The IRA clean energy manufacturing credits support domestic coating service expansion for EV inverter supply chains. Detroit-area automotive suppliers operate distributed PECVD systems for just-in-time heat sink finishing.
Germany
Precision ceramics clusters around Stuttgart and Munich enable rapid prototyping for aerospace turbine blade coatings under REACH chemical registration requirements. The EU Green Deal carbon intensity benchmarking elevates low-carbon CVD facilities in preferred supplier selection. Technical universities feed specialized process engineering talent directly into Baden-Württemberg coating facilities.
Japan
METI industrial technology grants reinforce domestic CVD equipment supply chain resilience for power electronics manufacturing. Tokai Carbon's isotropic graphite precursor dominance creates single-source vulnerability for coating manufacturers. Kansai and Kyushu regions concentrate semiconductor-grade substrate production with earthquake exposure risk.
China
Chemical vapor deposition capacity shifts toward larger-diameter reactor platforms for semiconductor-grade SiC coatings under MIIT industrial upgrading directives. Yangtze River Delta fabrication hubs integrate coating operations with domestic wafer processing equipment. Dual carbon goals pressure energy-intensive deposition facilities toward process efficiency investments.
India
PLI scheme production-linked incentives for semiconductor manufacturing attract CVD equipment investment toward Gujarat and Karnataka. Domestic coating service providers capture value from imported wafer processing equipment installation. Maharashtra and Telangana technical institutes develop practical deposition system training modules to address process engineering talent scarcity.
Silicon Carbide (Sic) Coating Market Competitive Landscape
Global majors compete with regional champions across precursor supply and deposition technology integration. Market structure tilts toward consolidated upstream substrate supply with fragmented downstream coating service provision. Three archetypes dominate: integrated graphite-to-coating manufacturers, specialized CVD equipment operators, and aerospace-certified precision ceramics fabricators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as automotive OEMs consolidate supplier bases.
Among integrated manufacturers, Mersen Group exemplifies vertical control from graphite substrates through finished coated components. Tokai Carbon occupies a position as the dominant isotropic graphite precursor supplier anchoring CVD process economics. SGL Carbon represents the specialized carbon-carbon composite substrate tier competing on thermal shock resistance credentials for aerospace applications.
| Leading Market Players |
|---|
| Mersen Group |
| Tokai Carbon |
| Toyo Tanso |
| SGL Carbon |
| CoorsTek |
| Morgan Advanced Materials |
| Ferrotec |
| AGC |
| Edgetech Industries |
| Others |
Value Network & Pricing Analysis
CVD reactor scaling toward 300mm wafer compatibility compresses coating uniformity tolerances while simultaneously concentrating capital requirements among fewer equipment suppliers capable of delivering precision deposition platforms. This technological transition elevates upfront investment thresholds for coating service providers while locking in long-term supply relationships with reactor manufacturers in Germany and Japan.
Pricing Analysis
Warranty bundling separates premium coating suppliers from commodity competitors, with automotive OEM 10-year adhesion warranties commanding substantial price premiums over unguaranteed energy-sector spray coatings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with AS9100D aerospace qualification adding significant margin over industrial heat sink protection. Price differentiation stems from thickness uniformity guarantees, with sub-5% variation specifications restricting premium tier access to CVD specialists. Cost compression in spray coating intensifies because EPA Maximum Achievable Control Technology compliance adds waste treatment overhead. Energy infrastructure operators exhibit highest price sensitivity, prioritizing deposition economics over precision for large-area heat sink protection.
Supply Chain Analysis
Freight costs for isotropic graphite substrates from Japan elevate total landed costs for European and North American CVD operators, incentivizing regional precursor inventory buffers. Supply concentrates in Japan, Germany, and the United States, with Tokai Carbon anchoring semiconductor-grade graphite substrate availability. Chlorosilane feedstock, high-purity carrier gases, and specialized reactor components constitute critical input dependencies. Single-source vulnerability from Japanese earthquake exposure threatens coating manufacturer production continuity. Distribution runs through direct technical sales relationships for semiconductor fabs, with aerospace aftermarket services utilizing authorized distributor networks for maintenance contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SiC coating market functions as a vertical-integration race where upstream control over isotropic graphite precursor supply and downstream captive coating service capacity determine margin capture. Players pursuing backward integration into substrate manufacturing gain pricing power against fragmented equipment-only competitors.
For Market Incumbents: Cement supply security through long-term isotropic graphite offtake agreements with Japanese precursor manufacturers, insulating against earthquake-driven supply interruptions. Expand CVD reactor capacity in Texas and Arizona to capture IRA-supported EV inverter coating demand while EPA emissions enforcement accelerates zero-emission process adoption. Acquire specialized aerospace certification capabilities to defend premium tier positioning against emerging PECVD specialists targeting automotive heat spreader applications.
For New Entrants and Emerging Players: Capture value from India's PLI scheme semiconductor manufacturing buildup by establishing coating service operations in Gujarat and Karnataka alongside imported wafer processing equipment installation. Target energy-sector spray coating replacement demand as US facilities face stranded asset pressure under EPA enforcement timelines. Pursue joint development agreements with regional automotive suppliers seeking distributed PECVD capacity for just-in-time heat sink finishing in Michigan and Bavaria.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated graphite-to-coating manufacturers with demonstrated AS9100D qualification track records and established automotive OEM warranty relationships. Long-term viability favors operators with captive precursor supply and multi-OEM approved processes across the 5-10 year electrification investment cycle. Monitor divergence between EPA and EU Green Deal carbon intensity benchmarks as procurement differentiator adoption signals coating process energy transparency valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captures margin from Tokai Carbon's isotropic graphite dominance while reducing earthquake exposure risk. |
| Zero-Emission CVD Capacity Expansion | Secures environmental permits under EPA Maximum Achievable Control Technology rules for Texas and Arizona fabs. |
| AS9100D Certification Investment | Unlocks Boeing and Airbus supplier status for flight-critical turbine blade coating contracts with 18-24 month qualification timelines. |
| Plasma-Enhanced CVD Technology Adoption | Enables distributed automotive supplier operations for just-in-time heat spreader finishing in Michigan and Bavaria. |
| India PLI Scheme Market Entry | Captures value from Gujarat and Karnataka semiconductor manufacturing equipment installation demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across CVD equipment engineering directors, semiconductor fab procurement managers, aerospace coating qualification specialists, automotive Tier 1 supplier technical buyers, and industrial gas turbine aftermarket service heads. SEC 10-K disclosures from graphite substrate manufacturers, EPA enforcement action records, METI industrial technology grant documentation, and EU ETS carbon intensity benchmarking reports supplied quantitative validation. Bottom-up coating capacity estimates triangulated against top-down semiconductor wafer processing equipment shipment data.
Granularity-level modeling captured deposition technology splits, coating thickness tier specifications, end-use industry demand patterns, and regional regulatory framework variations across the projection horizon. Segment-level CAGRs derived from equipment installation forecasts, OEM procurement contract visibility, and aftermarket maintenance cycle analysis. Chlorosilane feedstock price volatility assumptions, reactor scaling adoption curves, and automotive electrification content-per-vehicle trajectories informed sensitivity scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Japanese seismic event frequency, EPA enforcement intensity evolution, and automotive OEM supplier consolidation pace. Forecasts reflect documented assumptions regarding precursor supply continuity, qualification timeline stability, and carbon accounting methodology harmonization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Indium Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Germanium Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Semiconductor Materials Market