
 Lamps and Lighting Market | 2026-2036
Lamps and Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Lamps and Lighting Market Insights
The EU Green Deal is hardening efficiency benchmarks across European commercial building stock, compelling wholesale lamp replacements before end-of-life. Signify Holding leverages its Interact connected lighting platform to capture recurring software revenue alongside hardware sales. Acuity Brands anchors North American specification-grade projects through its Atrius IoT architecture. ams-OSRAM sustains leadership in automotive-grade LED emitters while extending its industrial UV-C portfolio.
Lamps and lighting encompass electrically powered devices that convert energy into visible illumination through incandescent filaments, gas discharge, or solid-state semiconductor junctions, typically measured in lumens per watt for efficacy and color rendering index for quality. LED segments now dominate value generation due to their 50,000-hour lifespans and sub-10-watt equivalence to legacy 60-watt incandescent sources. Smart lighting technology captures accelerating margin pools as building operators prioritize occupancy-based dimming and daylight harvesting. Fluorescent applications face structural contraction as mercury-content regulations tighten across multiple jurisdictions.
The US Department of Energy enforces ENERGY STAR certification and minimum efficacy standards through federal appliance regulations, while China's GB standards and MIIT circular economy mandates shape both domestic consumption and export manufacturing requirements. India's BIS compulsory registration scheme blocks non-compliant imports, forcing suppliers to establish local testing partnerships. Stakeholders must monitor how converging efficiency mandates and embedded connectivity requirements reshape product development roadmaps and certification budgets.
Market Dynamics
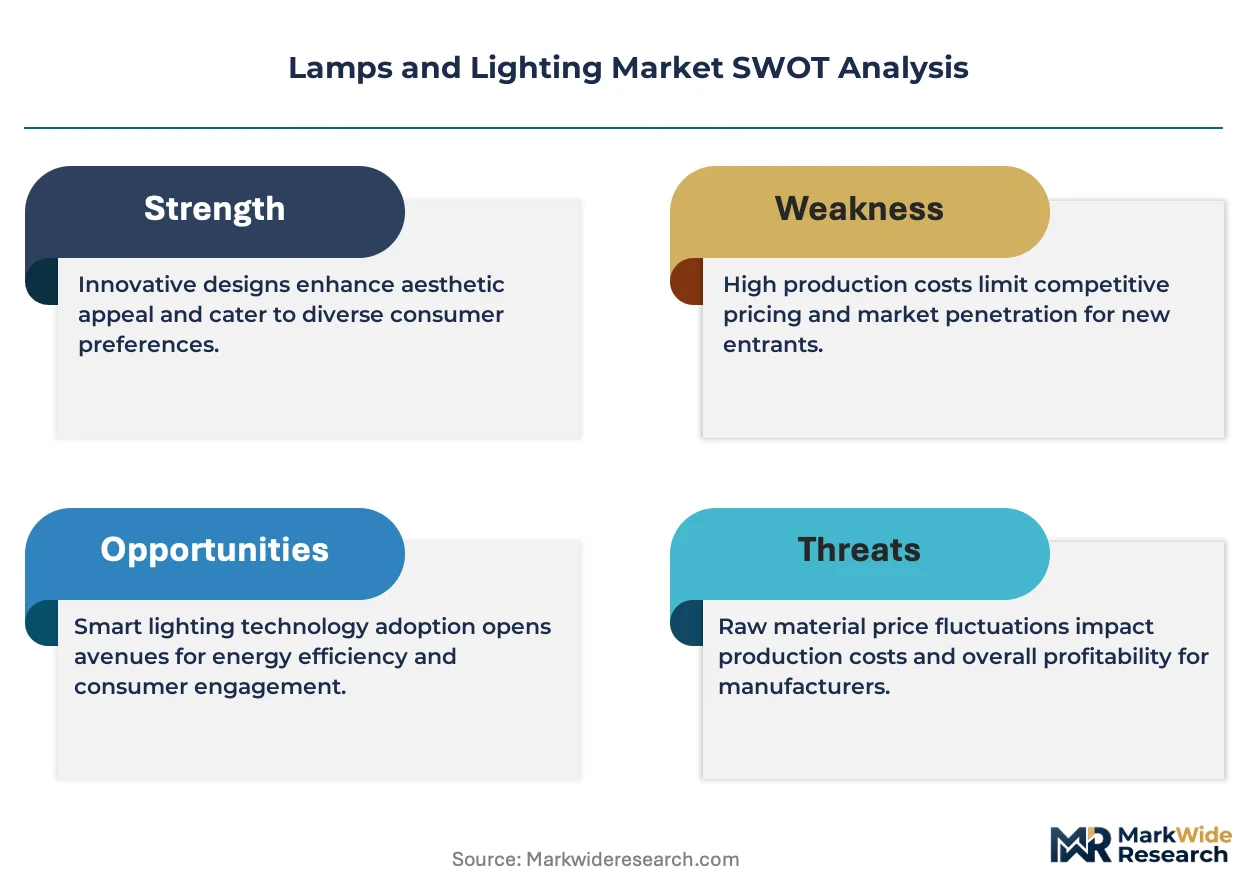
LED retrofits across commercial building stock are compressing replacement cycles while EU Ecodesign Directive mandates force premature fluorescent phase-outs, creating a dual-velocity market where regulatory compliance and energy economics pull in the same direction.
Growth Catalysts
- EU Green Deal efficiency mandates:Hardening benchmarks across European commercial building stock compel wholesale lamp replacements before natural end-of-life, accelerating hardware refresh demand.
- China's municipal smart streetlight programs:Scale deployment of connected outdoor luminaires drives both domestic consumption and manufacturing capacity expansion for export markets.
- UV-C LED industrial sterilization:Post-pandemic persistent demand for germicidal applications extends LED emitter value chains beyond general illumination into healthcare and food processing environments.
Market Restraints
- Rare earth phosphor supply concentration:Dependence on Chinese-processed yttrium and europium creates input cost volatility and geopolitical exposure for high-CRI LED manufacturers.
- Mercury-containing lamp disposal infrastructure:RoHS-compliant fluorescent recycling capacity lags behind phase-out timelines, creating compliance friction for facility managers with legacy installed base.
- Incandescent nostalgia segments:Decorative and hospitality applications retain filament preference for aesthetic warmth, capping LED penetration in premium residential and boutique commercial niches.
Strategic Opportunities
- India's BIS compulsory registration scheme:Testing partnership requirements create defensible positions for early-compliant suppliers as import barriers tighten against uncertified competitors.
- Human-centric lighting (HCL) convergence:Circadian-tunable systems integrating IoT sensors with tunable-white LED engines open specification-grade healthcare and education verticals.
- Light-as-a-Service (LaaS) contracting:Outcome-based models transferring ownership risk from building operators to lighting vendors capture recurring revenue streams and lock in long-term maintenance relationships.
Industry Challenges
- Embedded firmware cybersecurity certification:Connected luminaires face escalating pre-market testing timelines as EN 303 645 and IEC 62443 standards harden against IoT exploitation vectors.
- Legacy DALI-1 integration complexity:Interoperability gaps between first-generation digital addressable lighting interfaces and DALI-2/Wireless DALI create commissioning friction in mixed-vintage retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lamps and Lighting Market |
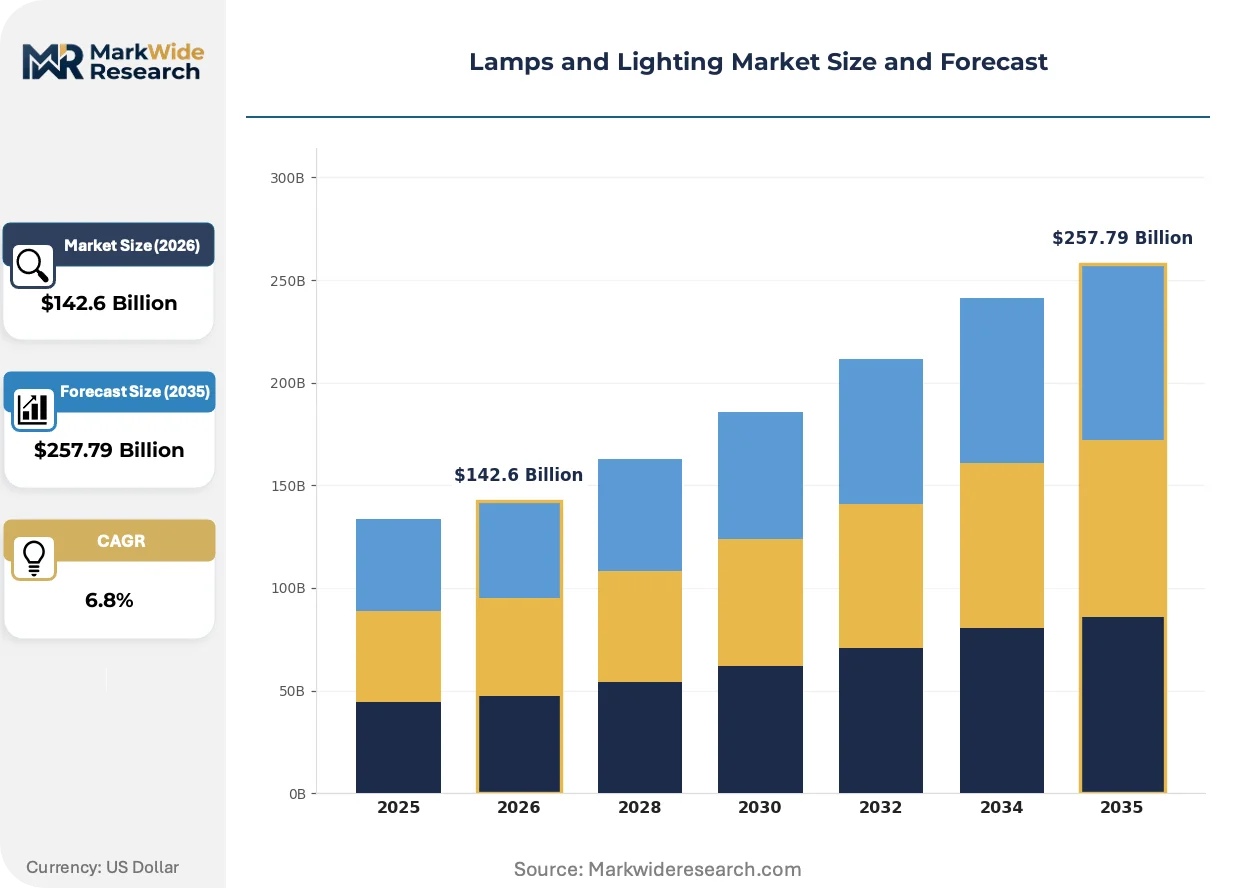
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Fluorescent, Incandescent Technology: Smart Lighting, Conventional, Solar-Powered, Dimming Solutions Application: Residential, Commercial, Outdoor, Industrial Distribution Channel: Online Retail, Specialty Stores, Home Improvement Centers, Wholesale |
| Companies Covered | Signify Holding, Acuity Brands, ams-OSRAM, Cree Lighting, Eaton, Zumtobel Group, GE Current, Hubbell Lighting, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lamps and Lighting Market Trends and Innovations
Solid-state lighting is absorbing software-defined functionality while efficiency regulations compress hardware margins, forcing vendors to differentiate through data services rather than lumen output alone.
Mini-LED and chip-scale packaging (CSP) architectures are rewriting optical design constraints for compact luminaire form factors. Architectural fixture manufacturers are adopting these emitters for sub-5mm edge-lit panels and linear coves previously served by conventional mid-power packages. The technology is compressing the distinction between decorative and functional lighting categories as thermal and optical performance converge in smaller footprints.
REACH restrictions on persistent organic pollutants and RoHS substance thresholds are tightening material compliance burdens across European supply chains. Manufacturers face reformulation of solder alloys, phosphor binders, and potting compounds to maintain market access. The directives are forcing Asian contract manufacturers to establish EU-based testing partnerships and documentation workflows, raising effective barriers to opportunistic exporters.
Facility managers are unbundling lighting maintenance from bundled mechanical-electrical contracts and contracting directly with OEM service arms or certified integrators. This disintermediation of traditional facilities management firms concentrates specification authority with end-users and accelerates technology refresh decisions. The pattern is most visible in US Class A office and German industrial portfolios where ESG reporting requirements demand granular energy attribution.
Lamps and Lighting Market Segmentation
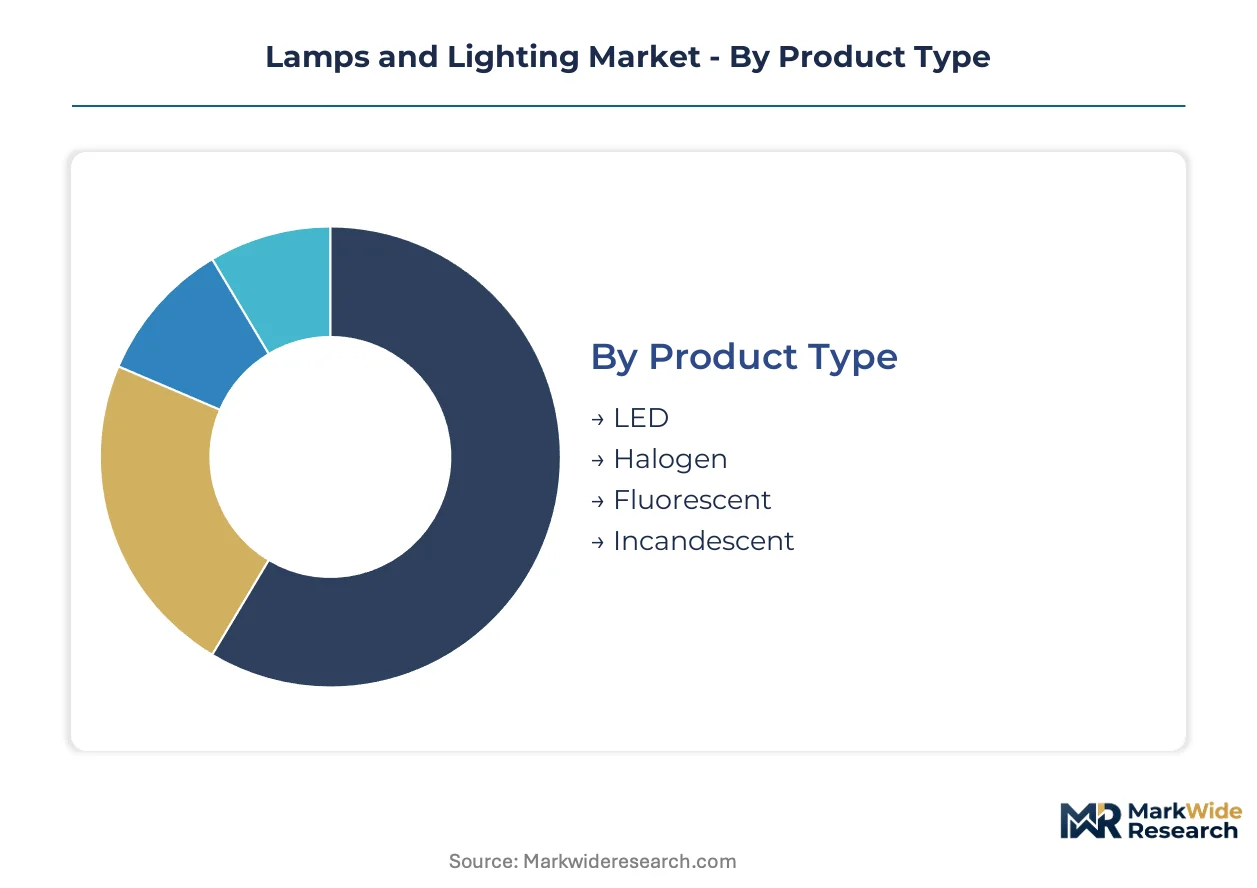
Segmentation reveals how LED solid-state platforms now dominate hardware economics while smart lighting software captures recurring service revenue. The technology-application matrix determines procurement authority, with facility managers controlling commercial volumes and homeowners driving residential replacement cycles.
Product Type:
Supply concentration in LED emitter manufacturing has collapsed cost curves and compressed replacement cycles across all downstream form factors.
- LED:Semiconductor junction devices converting electrons to photons with efficacy exceeding 150 lumens per watt. Commercial real estate developers in Germany and China are accelerating LED retrofits across Class A office portfolios as EU Ecodesign Directive mandates force premature fluorescent phase-outs.
- Fluorescent:Gas-discharge lamps using mercury vapor and phosphor coatings to produce visible light. Facility managers face structural contraction as RoHS restrictions on mercury-containing lamps tighten across European jurisdictions, creating compliance friction for legacy installed base disposal.
- Halogen:Tungsten-filament lamps with halogen regenerative cycle extending lifespan versus conventional incandescent. Automotive headlamp applications retain specification preference for precise beam control.
- Incandescent:Resistive filament devices producing continuous spectrum illumination. Decorative and hospitality segments in France and Italy retain filament preference for aesthetic warmth, capping LED penetration in premium residential niches.
LED absorbs the bulk of installed capacity; fluorescent is contracting fastest under regulatory pressure.
Technology:
Margin pools are shifting from lumen output toward data services as embedded connectivity requirements reshape product development roadmaps.
- Smart Lighting:Networked luminaires integrating occupancy sensors, daylight harvesting algorithms, and cloud-connected control platforms. Building operators in US Class A offices prioritize human-centric lighting systems with circadian-tunable white LED engines for healthcare and education verticals.
- Dimming Solutions:Phase-cut or 0-10V control interfaces enabling continuous lumen adjustment. Hospitality designers in Dubai and Singapore specify dimming compatibility for ambient scene setting in luxury residential developments.
- Conventional:Hardwired switching without networked control or sensor feedback. Emerging market residential construction in India and Brazil retains conventional specification for cost-sensitive volume housing.
- Solar-Powered:Off-grid luminaires with integrated photovoltaic panels and battery storage. Rural electrification programs in Kenya and Nigeria deploy solar streetlighting where grid extension remains uneconomical.
Smart lighting commands the steepest expansion trajectory; conventional maintains volume dominance in price-sensitive construction.
Application:
Procurement authority fragments across stakeholder types, with ESG reporting requirements concentrating specification decisions in institutional asset ownership.
- Commercial:Office, retail, and hospitality environments requiring specification-grade performance and extended operational lifespans. German industrial portfolios are unbundling lighting maintenance from bundled mechanical-electrical contracts, contracting directly with OEM service arms for granular energy attribution.
- Outdoor:Street, roadway, and area illumination exposed to environmental stressors. China's municipal smart streetlight programs scale deployment of connected outdoor luminaires, driving domestic consumption and export manufacturing capacity.
- Residential:Single-family and multi-family dwelling illumination with aesthetic and functional requirements. US homeowners are accelerating LED retrofit purchases through utility rebate programs and ENERGY STAR certification awareness.
- Industrial:Manufacturing, warehousing, and hazardous location lighting demanding extreme durability. Food processing environments in the Netherlands are specifying UV-C LED industrial sterilization for post-pandemic persistent germicidal applications.
Commercial application absorbs dominant revenue share; outdoor is gaining share fastest through municipal infrastructure digitization.
Distribution Channel:
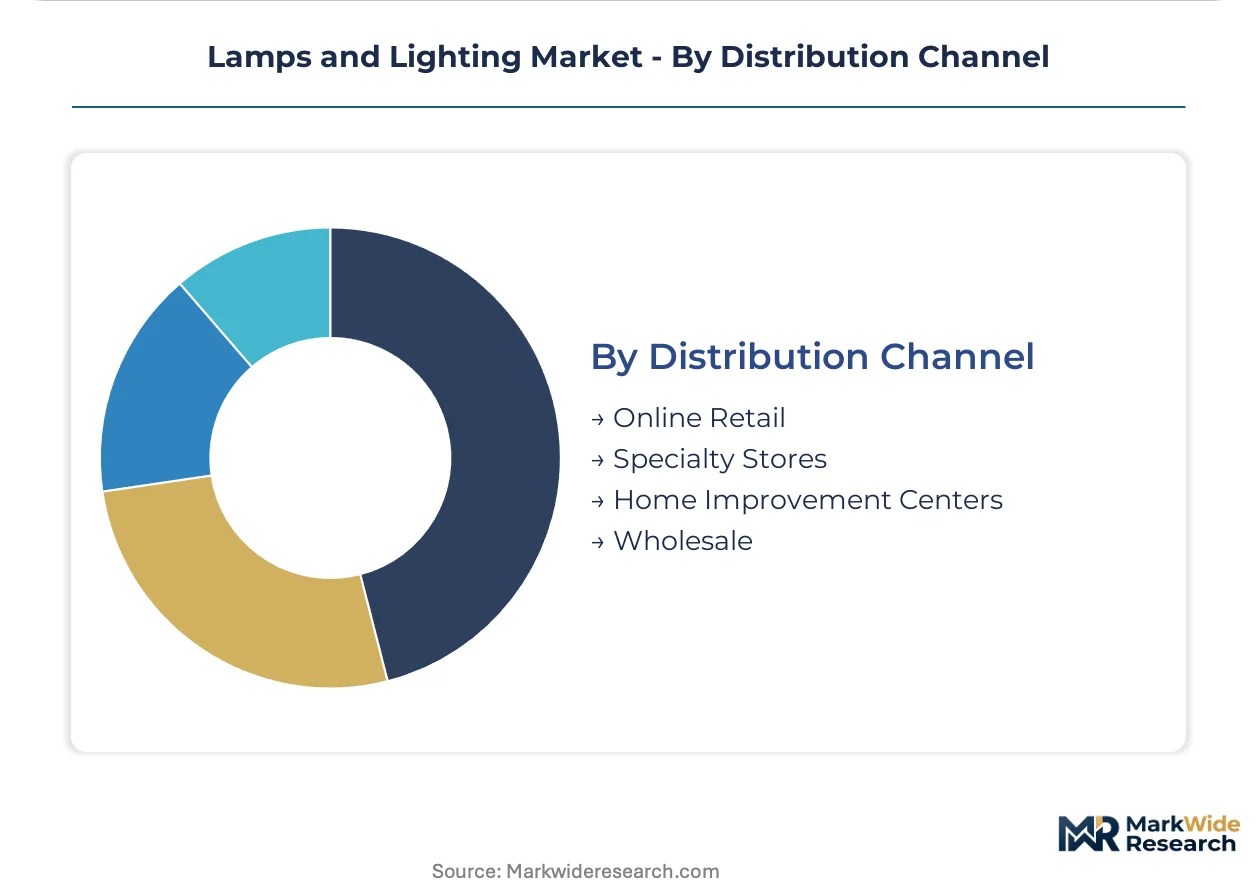
Channel configuration determines margin capture, with direct contracting disintermediating traditional wholesale relationships in large-scale deployment.
- Wholesale:Business-to-business volume distribution serving electrical contractors and commercial specifiers. US electrical distributors maintain inventory depth for specification-grade project support and same-day fulfillment.
- Online Retail:E-commerce platforms enabling direct consumer and small commercial procurement. Amazon and Alibaba marketplaces are capturing residential replacement cycle volume through price transparency and review aggregation.
- Specialty Stores:Dedicated lighting showrooms offering design consultation and custom specification. Italian architectural lighting brands leverage Milan showrooms for hospitality and luxury residential project development.
- Home Improvement Centers:Big-box retailers with broad SKU assortments for DIY installation. Lowe's and Home Depot dominate US residential retrofit volume through contractor loyalty programs and in-store pickup convenience.
Wholesale retains institutional project dominance; online retail is climbing the fastest in residential replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the global LED supply chain through concentrated emitter manufacturing and smart streetlight deployment, while regulatory divergence across major economies fragments certification requirements and shapes regional competitive dynamics.
China
Municipal smart streetlight programs in Guangdong and Jiangsu provinces drive domestic LED consumption while MIIT circular economy mandates reshape export manufacturing compliance. GB standards enforcement tightens material documentation for phosphor binders and solder alloys. The Yangtze River Delta corridor concentrates contract manufacturers establishing EU-based testing partnerships to maintain market access.
Germany
Industrial portfolio managers unbundle lighting maintenance from mechanical-electrical contracts to secure granular energy attribution for ESG reporting. The EU Ecodesign Directive forces premature fluorescent phase-outs across commercial building stock. Bavaria's manufacturing belt hosts specification-grade fixture producers serving healthcare and education verticals with circadian-tunable systems.
United States
Class A office developers accelerate LED retrofits through utility rebate programs and ENERGY STAR certification requirements. The Department of Energy enforces minimum efficacy standards through federal appliance regulations. Pacific Northwest utilities pioneer connected outdoor luminaire deployments with integrated daylight harvesting algorithms.
India
Domestic LED consumption expands through municipal streetlight tenders and residential replacement cycles in Maharashtra and Gujarat. BIS compulsory registration schemes block non-compliant imports and force testing partnerships with local laboratories. Tamil Nadu's electronics manufacturing clusters absorb contract assembly migrating from higher-cost Asian origins.
United Arab Emirates
Hospitality developers in Dubai specify dimming-compatible fixtures for luxury residential ambient scene setting. MOHAP and municipal regulators enforce efficiency benchmarks for new construction permits. Abu Dhabi's Masdar City district serves as a testbed for solar-powered off-grid luminaires with integrated battery storage.
Lamps and Lighting Market Competitive Landscape
Premium-margin players sit above commodity-margin players across connected-platform capabilities and specification-grade project access, creating a tiered structure where software-defined functionality separates recurring-revenue vendors from hardware-only suppliers. The vendor base concentrates around three strategic archetypes: integrated platform providers capturing service revenue, component specialists dominating automotive and industrial emitters, and specification-grade fixture houses serving architectural channels. Dominant competitive moves include direct contracting with facility managers to disintermediate wholesale relationships and portfolio diversification into UV-C germicidal applications.
Among integrated platform providers, Signify Holding and Acuity Brands occupy positions emphasizing connected-control software, while ams-OSRAM exemplifies the component-specialist archetype with concentrated emitter manufacturing. These three entities represent distinct strategic vectors within the competitive structure.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| ams-OSRAM |
| Cree Lighting |
| Eaton |
| Zumtobel Group |
| GE Current |
| Hubbell Lighting |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
Class A office developers and municipal procurement authorities concentrate buying power through multi-year retrofit contracts and smart streetlight tenders, anchoring pricing around lifecycle cost-per-lumen rather than upfront hardware expenditure. This buyer concentration shifts vendor economics toward service-embedded models where recurring software revenue offsets compressed hardware margins.
Pricing Analysis
Value-based pricing tied to energy savings guarantees and uptime commitments anchors premium tiers, with Signify's Interact platform and Acuity's Atrius commanding subscription premiums against transactional hardware competitors. Price differentiation separates ENERGY STAR-certified specification-grade fixtures from uncertified economy imports, while customization for circadian-tunable healthcare applications sustains mid-tier positioning. Cost compression in conventional LED retrofit hardware intensifies as Chinese manufacturing scale floods export markets with sub-dollar-per-watt emitters. Price sensitivity concentrates in emerging market residential construction, where procurement officers prioritize first-cost minimization over lifecycle returns.
Supply Chain Analysis
Ocean freight rate volatility from Yangtze River Delta ports to Rotterdam and Long Beach reshapes landed cost calculations for European and North American distributors sourcing finished luminaires. Emitter manufacturing concentrates in China, phosphor processing in Japan, and precision optics in Germany, creating multi-country dependencies for high-CRI specification products. Rare earth supply from Chinese-processed yttrium and europium sources rests on geopolitical exposure absent diversified mining partnerships. Single-source vulnerability in automotive-grade LED die supply from ams-OSRAM and Nichia creates qualification bottlenecks for tier-2 fixture assemblers. Distribution runs through Shenzhen-based contract manufacturers to regional electrical distributors, with direct OEM contracting disintermediating wholesale layers in large-scale commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign Directive enforcement and RoHS mercury restrictions are compressing viable supplier counts, favoring consolidated platforms with compliance infrastructure over fragmented hardware assemblers.
For Market Incumbents: Deepen vertical control over emitter supply through captive manufacturing or long-term offtake agreements with Yangtze River Delta foundries, insulating against rare earth phosphor volatility while RoHS documentation requirements eliminate opportunistic competitors. Expand EU-based testing partnerships to exploit compliance friction blocking Asian exporters from specification-grade healthcare and education verticals. For New Entrants and Emerging Players: The mid-market price gap between premium connected-platform vendors and economy retrofit suppliers offers white-space for solar-powered off-grid luminaires in Kenyan and Nigerian rural electrification programs, plus UV-C sterilization emitters for Dutch food processing environments. Target India's BIS compulsory registration scheme through Tamil Nadu laboratory partnerships, establishing defensible import compliance ahead of tightening enforcement. For Investors and Strategic Acquirers: The window for entry favors component-specialist emitters with automotive qualification and specification-grade fixture houses serving circadian-tunable healthcare verticals, as integrated platform providers consolidate recurring-revenue market share. Monitor EN 303 645 cybersecurity certification timelines as an inflection signal—vendors with pre-qualified firmware stacks will capture accelerated connected-lighting procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Signify's Interact and Acuity's Atrius architectures lock facility managers into recurring software revenue streams. |
| Backward Integration | ams-OSRAM's captive emitter manufacturing insulates automotive and industrial portfolios from phosphor supply volatility. |
| Regulatory Certification Investment | Early EN 303 645 and IEC 62443 compliance creates procurement preference as cybersecurity hardens. |
| Geographic Manufacturing Footprint | Tamil Nadu assembly clusters absorb contract manufacturing migrating from higher-cost Asian origins for India market access. |
| Technology Licensing | UV-C LED germicidal patent portfolios extend value capture beyond general illumination into healthcare and food processing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with lighting OEM product managers, electrical distributor procurement directors, facility management executives, and municipal streetlight program officers. Secondary sources incorporated ENERGY STAR certification databases, EU Ecodesign Directive implementation reports, China MIIT circular economy filings, and India BIS registration records. Bottom-up emitter volume estimates and top-down luminaire value assessments were cross-validated against utility rebate program disclosures and commercial real estate retrofit permit data.
Segment-level modeling applied product-type, technology, application, and distribution channel dimensions at country-specific resolution, with CAGRs derived from fitted growth curves across the analysis window. Smart lighting connectivity penetration, UV-C industrial sterilization adoption rates, and fluorescent phase-out compliance timelines served as industry-specific demand drivers. Supply-side constraints incorporated rare earth phosphor processing capacity, semiconductor foundry allocation, and EU-based testing laboratory throughput.
Inputs from OEM financial disclosures and municipal tender databases were available through the study window; gaps in real-time connected-lighting deployment metrics and cybersecurity certification pipeline status introduce uncertainty bands around smart segment forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Specialty Lighting Market
Lighting
Global Lighting Control System Market
Lighting
Cleanroom Lighting Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Lighting Product Market
Lighting
Lighting Control Components Market
Lighting
High-End Lighting Market
Lighting
Global Work Lights Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Circadian Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
North America Smart Lighting Market
Lighting
Street Lighting Market
Lighting
Dimmer and Color Tunable Market
Lighting
Industrial UV-C Disinfection Lighting Market