
 Global Semiconductor Gallium Oxide Market | 2026-2036
Global Semiconductor Gallium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Gallium Oxide Market Outlook
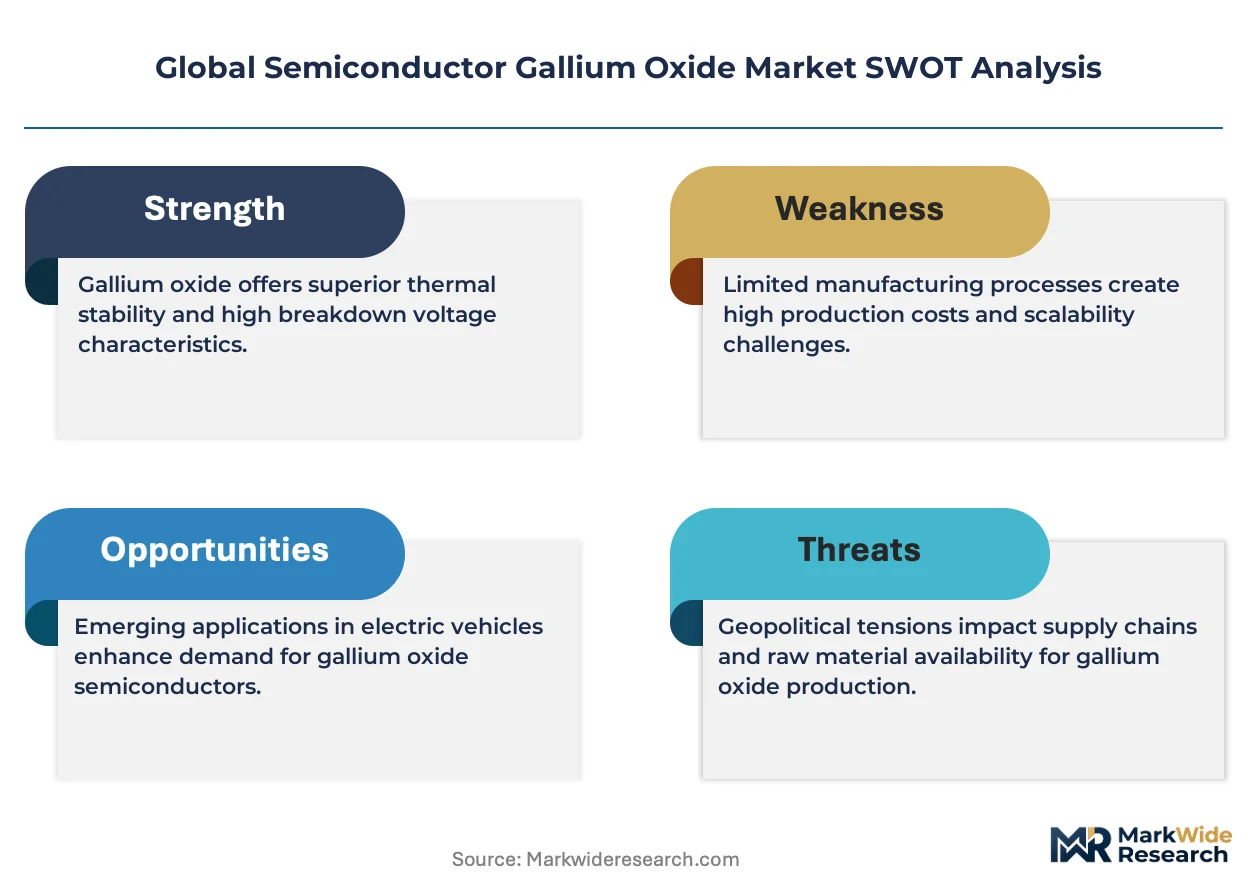
Gallium oxide is broadening its addressable market as a silicon carbide alternative in high-voltage power electronics, driven by lower substrate costs and superior bandgap properties. Novel Crystal Technology, Inc. dominates Japan's substrate supply chain through proprietary melt-growth techniques. FLOSFIA Inc. leverages spray-assisted deposition to reduce manufacturing thermal budgets. Sumitomo Electric Industries, Ltd. anchors industrial demand through integrated power module development.
Semiconductor gallium oxide refers to beta-phase Ga2O3 crystals and epitaxial films engineered with bandgaps near 4.8 eV, enabling breakdown fields above 8 MV/cm for 650V to kilovolt-class switching applications. Substrate fabrication employs edge-defined film-fed growth or Czochralski methods to produce single crystals with controlled doping profiles. Power Devices command the largest revenue share due to traction inverter and grid-tied converter procurement, while RF Devices represent the fastest-expanding category as 5G base station deployments intensify demand for high-efficiency amplification. HVPE technology leads production scale, though MBE competes for specialized defense and aerospace qualifications where interface precision commands premium positioning.
FDA device regulations and EPA chemical handling standards shape U.S. market entry pathways for gallium oxide power modules, while Japan's METI and China's MIIT coordinate rival national substrate development programs. The EU Green Deal and REACH chemical registration requirements influence European supply chain localization decisions for wide-bandgap material sourcing. Stakeholders must monitor which regulatory jurisdiction first certifies automotive-grade gallium oxide reliability standards, as this determination will concentrate early commercial volume and intellectual property licensing leverage.
Market Dynamics
Substrate crystal growth capability concentration in Japanese and Chinese fabrication clusters is fragmenting supply security for power electronics manufacturers seeking gallium oxide qualification for electric vehicle drivetrains.
Growth Catalysts
- Japan's METI funding framework:Direct subsidies for next-generation wide-bandgap semiconductor substrate development compress commercialization timelines for 6-inch and 8-inch gallium oxide wafers.
- Electric vehicle powertrain electrification:Traction inverter procurement from tier-1 automotive suppliers creates qualified demand pools for 650V to 1200V switching devices with superior efficiency thresholds.
- HVPE manufacturing scale-up:Hydride vapor phase epitaxy reactor throughput improvements at Asian foundries reduce unit economics toward silicon carbide parity.
Market Restraints
- Substrate diameter limitations:Current 2-inch and 4-inch wafer formats impose die-yield penalties that inflate effective cost-per-ampere versus silicon carbide alternatives.
- Single-source supply risk:Novel Crystal Technology's proprietary edge-defined film-fed growth process concentrates critical substrate supply within one Japanese entity.
- EPA chemical handling compliance:Gallium precursor material classification under TSCA Section 5 new chemical review creates import friction for U.S. device fabrication.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentive allocations for compound semiconductor fabs create first-mover substrate qualification pathways outside East Asian supply clusters.
- 5G base station RF amplification:Millimeter-wave infrastructure deployment in South Korea and Japan generates demand for high-efficiency power amplifiers operating above 28 GHz.
- MBE-ELOG convergence:Molecular beam epitaxy combined with epitaxial lateral overgrowth techniques enables defect reduction for defense-aerospace qualification premiums.
Industry Challenges
- Crystal growth specialist scarcity:Expertise in Czochralski melt-growth parameter control for ultra-wide bandgap materials resides within limited academic and industrial laboratories.
- Automotive AEC-Q101 certification timelines:Extended qualification protocols for power discrete reliability under thermal cycling and humidity stress delay OEM design-win conversion.
- Legacy silicon IGBT design-in persistence:Established supplier relationships and proven field reliability data create switching friction for gallium oxide substitution in industrial motor drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Gallium Oxide Market |
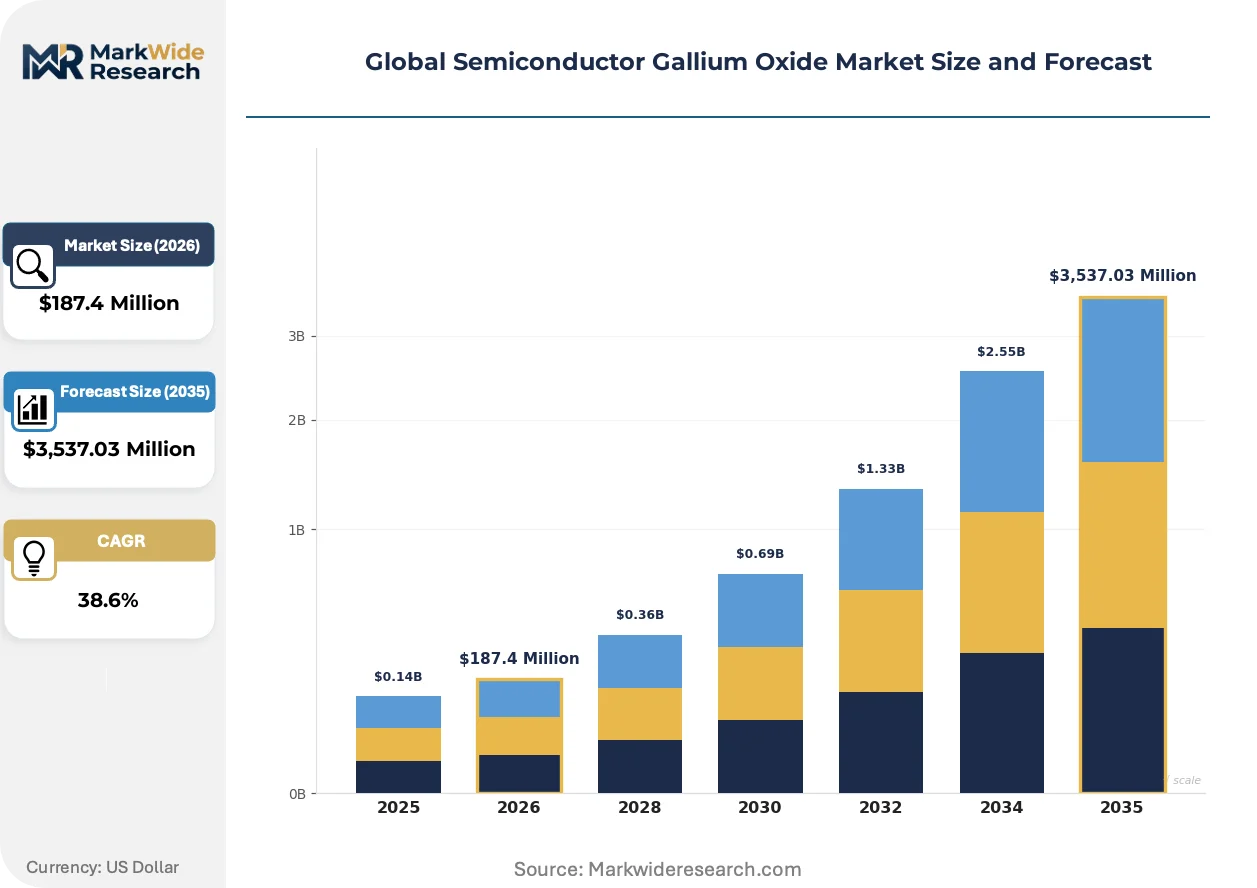
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Devices, Optical Devices, RF Devices, Sensors End User: Telecommunications, Automotive, Consumer Electronics, Industrial Technology: HVPE, MBE, CVD, Epitaxy Application: Power Conversion, RF Amplification, Display Technology, Photovoltaics |
| Companies Covered | Novel Crystal Technology, Inc., FLOSFIA Inc., Aluminum Corporation of China Limited, Sumitomo Electric Industries, Ltd., Kyma Technologies, Nanjing Jinmei Gallium Co., Ltd., Saint-Gobain, Vital Materials Co., Limited, Neo Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Gallium Oxide Market Strategic Shifts
Epitaxial deposition technique diversification and national semiconductor sovereignty programs are restructuring competitive access to qualified substrate supply. Process innovation cycles compress as equipment vendors adapt reactor platforms from established III-V materials.
HVPE reactor throughput scaling is rewriting cost structures for drift layer formation on native substrates. Automotive tier-1 suppliers in Germany and Japan are accelerating device evaluation timelines from 36-month to 18-month qualification windows. This compression is enabling foundry partnerships that bypass traditional captive substrate strategies.
REACH chemical registration requirements for gallium compounds are reshaping European supply chain localization decisions. ECHA substance evaluation dossiers for gallium oxide nanoparticle classifications impose additional testing burdens on importers. Power module assemblers in France and Germany are responding by qualifying Japanese substrate sources with pre-registered chemical safety documentation.
Direct procurement relationships between automotive OEMs and substrate growers are displacing traditional distributor-mediated component sourcing. Tier-1 inverter manufacturers in Detroit and Stuttgart are establishing technical audit programs at Japanese crystal growth facilities. This channel consolidation is most visible in North American electric vehicle programs targeting 2027 platform launches.
Global Semiconductor Gallium Oxide Market Segmentation
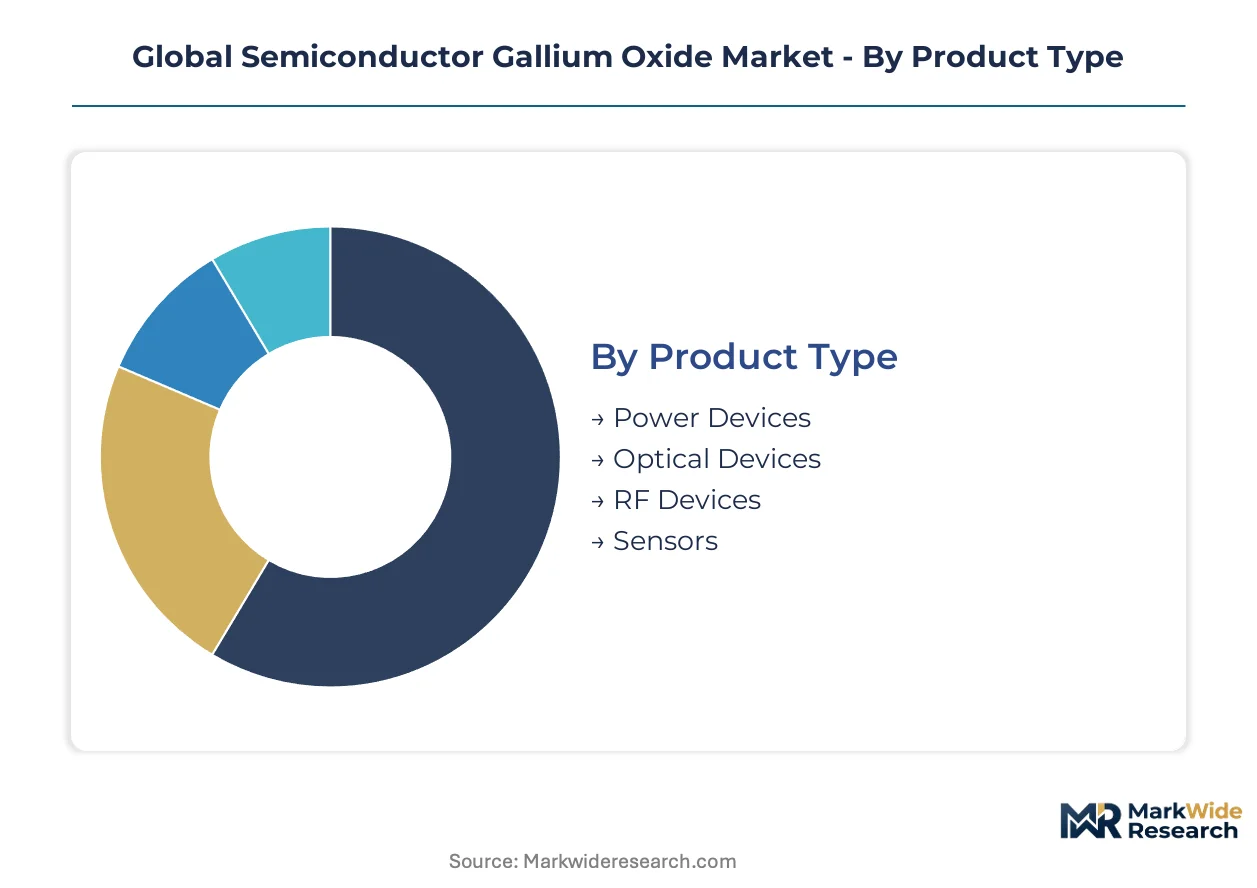
Gallium oxide market segmentation reveals how technical specifications map to distinct value capture opportunities across power electronics, optical systems, and wireless infrastructure. Category boundaries are fluid as substrate manufacturers pivot between automotive qualification and defense-aerospace premiums.
Product Type:
Standardized substrate formats dominate high-volume procurement, while custom epitaxial specifications command premiums in defense and satellite applications.
- Power Devices:These encompass vertical Schottky barrier diodes and metal-oxide-semiconductor field-effect transistors engineered for breakdown fields exceeding 8 MV/cm. Traction inverter procurement from automotive OEMs in Stuttgart and Detroit concentrates demand for 650V to 1200V-rated discrete devices. Japanese foundries in Yamagata prefecture anchor supply for this segment through proprietary drift layer optimization.
- RF Devices:High-electron-mobility transistor structures and millimeter-wave power amplifiers exploit gallium oxide's saturation velocity advantages above 28 GHz. Base station deployments in South Korea and Japan's Kanto region are driving qualification timelines for sub-6 GHz and mmWave amplification modules. This segment is gaining share fastest as 5G infrastructure densification accelerates.
- Optical Devices:Deep-ultraviolet photodetectors and transparent conductive films leverage the material's tunable bandgap transparency.
- Sensors:Gas sensing and radiation detection applications exploit surface reactivity and radiation hardness for industrial safety and nuclear monitoring.
Most installed capacity flows through Power Devices. Expansion is steepest in RF Devices.
End User:
Volume concentration sits with automotive electrification programs, while margin capture favors telecommunications infrastructure with extended qualification cycles.
- Automotive:Tier-1 inverter manufacturers specify AEC-Q101-qualified discrete devices for 800V architecture electric vehicle platforms. German and Japanese OEM technical audit programs at substrate growth facilities are consolidating procurement channels outside traditional distribution.
- Telecommunications:Network equipment vendors in Seoul and Tokyo prioritize efficiency metrics for macro cell and small cell amplification. South Korea's spectrum auctions for 28 GHz and 39 GHz bands are accelerating device evaluation timelines from 36 months to 18 months.
- Consumer Electronics:Fast-charging adapter modules and compact power supplies exploit gallium oxide's thermal conductivity advantages.
- Industrial:Motor drive inverters and welding equipment represent retrofit opportunities against entrenched silicon IGBT incumbent suppliers.
Automotive claims the dominant revenue position. Telecommunications shows the steepest expansion trajectory.
Technology:
Cost-per-layer economics favor high-throughput vapor deposition, while interface precision requirements sustain molecular beam alternatives for specialized qualifications.
- HVPE:Hydride vapor phase epitaxy achieves drift layer growth rates exceeding 10 micrometers per hour on native substrates. Asian foundries in Hefei and Tsukuba are scaling reactor throughput toward silicon carbide cost parity for 6-inch wafer formats.
- MBE:Molecular beam epitaxy enables monolayer precision for defense-aerospace interface engineering where defect densities below 10^8 per square centimeter command premium positioning.
- CVD:Chemical vapor deposition routes explore alternative precursors for reduced thermal budget processing.
- Epitaxy:Generalized epitaxial growth services bridge prototype and production volumes for fabless design houses.
HVPE dominates commercial scale. MBE captures the highest margin per wafer.
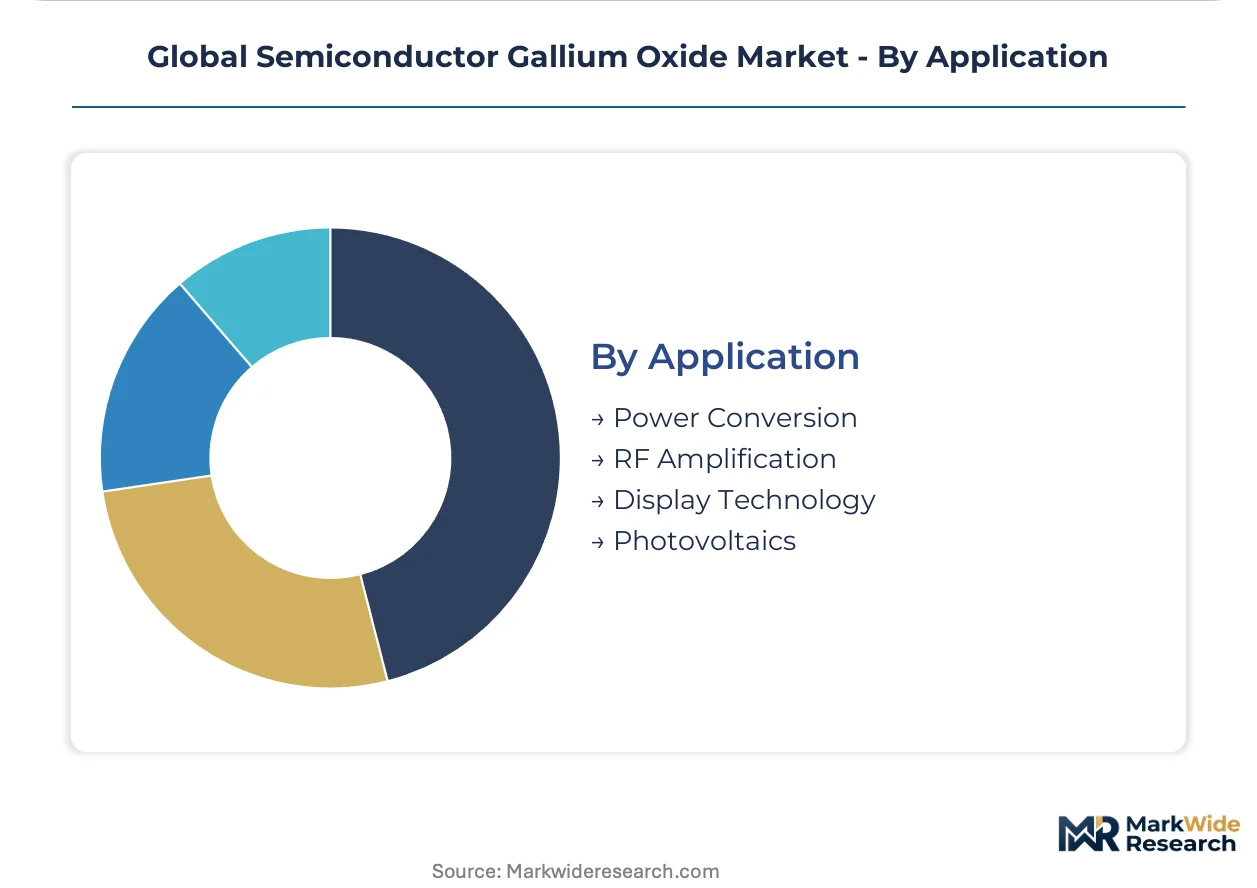
Application:
Functional performance requirements segment the market between efficiency-critical power switching and frequency-critical signal amplification.
- Power Conversion:On-board chargers, DC-DC converters, and grid-tied inverters exploit the material's Baliga figure-of-merit advantages over silicon carbide at equivalent voltage ratings. China's State Grid demonstration projects for next-generation solid-state transformers are creating reference installations.
- RF Amplification:Macro base stations and phased array radar systems demand output power densities above 5 W/mm at millimeter-wave frequencies. Japan's MIC spectrum allocation for 2027 commercial 6G trials is accelerating device architecture roadmaps.
- Display Technology:Transparent thin-film transistors for active-matrix addressing in high-brightness panels.
- Photovoltaics:Buffer layers and transparent contacts for cadmium telluride and perovskite tandem cell architectures.
Power Conversion absorbs the majority of substrate output. RF Amplification is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yamagata Prefecture's crystal growth corridor concentrates the most advanced substrate fabrication capabilities for beta-phase Ga2O3 wafers. National semiconductor sovereignty programs across four major economies are redrawing procurement geography for power electronics manufacturers.
Japan
Automotive OEM technical audit programs and METI's next-generation wide-bandgap semiconductor subsidies compress commercialization timelines for 6-inch and 8-inch wafer formats. METI coordinates direct funding for substrate development through its national project framework. Yamagata Prefecture hosts Novel Crystal Technology's proprietary melt-growth operations, where edge-defined film-fed growth techniques achieve controlled doping profiles for 650V to kilovolt-class devices.
China
State Grid demonstration projects for solid-state transformers and MIIT's compound semiconductor development roadmap create qualified demand pools for power conversion applications. MIIT prioritizes indigenous substrate crystal growth capabilities through national technology programs. Hefei's fabrication cluster scales HVPE reactor throughput toward silicon carbide cost parity, while Tsukuba-equivalent capabilities emerge in Yangtze River Delta research corridors.
United States
Detroit-based tier-1 inverter manufacturers establish direct procurement relationships with Japanese substrate growers, bypassing traditional distributor channels for 2027 electric vehicle platform launches. EPA's TSCA Section 5 new chemical review classification for gallium precursors creates import friction for device fabrication. Southeast Michigan's automotive electronics corridor concentrates technical audit programs and qualification timelines for AEC-Q101-certified discrete devices.
Germany
Stuttgart OEMs accelerate device evaluation timelines from 36-month to 18-month qualification windows for 800V architecture traction inverters. EU Green Deal and REACH chemical registration requirements for gallium compounds reshape supply chain localization decisions. Bavaria's power module assemblers qualify Japanese substrate sources with pre-registered chemical safety documentation to circumvent ECHA substance evaluation burdens.
South Korea
Spectrum auctions for 28 GHz and 39 GHz bands intensify demand for millimeter-wave power amplifiers with efficiency metrics above 5 W/mm. National 6G trials scheduled for 2027 accelerate RF device architecture roadmaps under MIC coordination. Seoul's network equipment vendors compress procurement cycles for macro cell and small cell amplification modules.
Global Semiconductor Gallium Oxide Market Competitive Environment
Global majors compete with regional champions across substrate crystal growth techniques and epitaxial deposition platforms. The vendor base stratifies between proprietary melt-growth specialists, spray-assisted deposition innovators, and diversified industrial conglomerates with captive power module development. Three archetypes dominate: substrate purists controlling crystal growth IP, foundry-integrated device manufacturers, and materials conglomerates leveraging backward integration into gallium refining. Capacity expansion and strategic technology licensing constitute the primary competitive vectors as qualification timelines compress.
Within the substrate purist tier, Novel Crystal Technology, Inc. and FLOSFIA Inc. occupy positions defined by proprietary process differentiation. Sumitomo Electric Industries, Ltd. anchors the foundry-integrated archetype through power module development. These three exemplify how Japanese industrial concentration shapes competitive access to qualified supply, with each representing distinct technical bets on melt-growth versus vapor-phase approaches.
| Leading Market Players |
|---|
| Novel Crystal Technology, Inc. |
| FLOSFIA Inc. |
| Aluminum Corporation of China Limited |
| Sumitomo Electric Industries, Ltd. |
| Kyma Technologies |
| Nanjing Jinmei Gallium Co., Ltd. |
| Saint-Gobain |
| Vital Materials Co., Limited |
| Neo Performance Materials |
| Others |
Value Chain & Pricing Dynamics
Gallium precursor feedstock costs cascade through substrate fabrication into three-tier pricing structure across premium, standard, and economy levels, with 6-inch wafer premiums reflecting Yamagata Prefecture's crystal growth specialization and EPA import friction adding landed cost layers for Detroit-based automotive buyers.
Pricing Analysis
Input-cost pass-through from proprietary melt-growth equipment depreciation and gallium metal spot volatility shapes contract pricing for native substrates. Price differentiation separates AEC-Q101-qualified automotive tiers from industrial-grade specifications, with certification investment recovery driving 40-60 point spreads. Cost compression in standard-grade 2-inch formats is intensifying because Hefei foundries are scaling HVPE throughput toward silicon carbide parity. Automotive OEM procurement teams show highest price sensitivity, while defense-aerospace buyers absorb premiums for MBE precision.
Supply Chain Analysis
Dual-sourcing requirements from Detroit and Stuttgart inverter manufacturers are forcing qualification of secondary substrate suppliers beyond Novel Crystal Technology's single-source dominance. Geographic supply concentrates in Japan, China, and South Korea, where edge-defined film-fed growth and HVPE reactor platforms anchor output. Raw material dependencies span high-purity gallium metal, iridium crucibles, and hydrogen chloride precursors. Single-source vulnerability persists in proprietary melt-growth IP concentration. Distribution runs through direct technical audit relationships displacing traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge where METI-subsidized Japanese substrate costs diverge from EPA-constrained U.S. fabrication economics, rewarding qualification pathways that bypass import friction through pre-registered chemical documentation.
For Market Incumbents: Anticipate silicon carbide price convergence by accelerating 8-inch wafer roadmap execution before 2027 platform design freezes lock in competing architectures. Consolidate backward integration into gallium refining to secure precursor supply against spot volatility. METI subsidy expiration timelines threaten margin compression for non-integrated substrate specialists. For New Entrants and Emerging Players: Enter via India's PLI scheme for compound semiconductor fabs, where production-linked incentives offset capital intensity for first-mover substrate qualification outside East Asian clusters. Target RF amplification for 5G base station deployments in South Korea, where 18-month compressed evaluation timelines bypass entrenched automotive qualification barriers. Partner with Seoul network equipment vendors for reference design integration. For Investors and Strategic Acquirers: Consolidation pressure builds where crystal growth specialist scarcity concentrates proprietary parameter control within limited academic and industrial laboratories. Five-to-ten year viability favors acquisition targets with captive melt-growth IP and automotive certification progress rather than pure-play epitaxial service models. Signal to watch: first AEC-Q101 qualification completion for 1200V-rated discrete devices, which would trigger OEM design-win conversion acceleration and licensing leverage concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Diameter Scale-Up | 6-inch and 8-inch wafer qualification reduces die-yield penalties for automotive procurement. |
| HVPE Reactor Throughput Expansion | Hefei and Tsukuba foundry scaling achieves cost parity with silicon carbide alternatives. |
| Automotive Certification Investment | AEC-Q101 qualification completion unlocks Detroit and Stuttgart OEM design-win conversion. |
| Direct Procurement Channel Development | Technical audit programs at Yamagata crystal growth facilities displace distributor mediation. |
| Defense-Aerospace MBE Specialization | Monolayer precision for interface engineering commands premium positioning above commercial tiers. |
Study Parameters
Direct dialogue with substrate crystal growth engineers, automotive tier-1 inverter procurement managers, RF device foundry operators, and national semiconductor program officials grounded qualitative assessment. Secondary validation drew from METI funding disclosure documents, EPA TSCA Section 5 chemical review filings, ECHA REACH substance evaluation dossiers, and SEC 10-K filings from diversified industrial conglomerates. Bottom-up wafer capacity estimates and top-down power electronics demand projections were triangulated against HVPE reactor installation counts and automotive platform electrification roadmaps.
Segmented outputs across the analysis window reflect product type, end user industry, epitaxial deposition technology, and regional fabrication cluster dimensions. CAGRs were derived from substrate diameter adoption curves and foundry utilization trajectories. Industry-specific inputs included AEC-Q101 qualification timeline distributions, 5G base station deployment schedules from South Korea's spectrum auction outcomes, and solid-state transformer demonstration project milestones from China's State Grid.
Inputs from Japanese and Chinese national semiconductor program disclosures were available through the study window; gaps in proprietary melt-growth yield data introduce uncertainty bands around substrate cost trajectory assumptions. Forecasts reflect documented assumptions regarding HVPE throughput scaling and automotive OEM technical audit program expansion. Deviation in EPA chemical handling classification enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Silicone Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Indium Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Asia Pacific Graphene Market