
 Chalcocite-Digenite Group Market | 2026-2036
Chalcocite-Digenite Group Market Size, Share, and Industry Trends Forecast 2026-2036
Chalcocite-Digenite Group Market Analysis
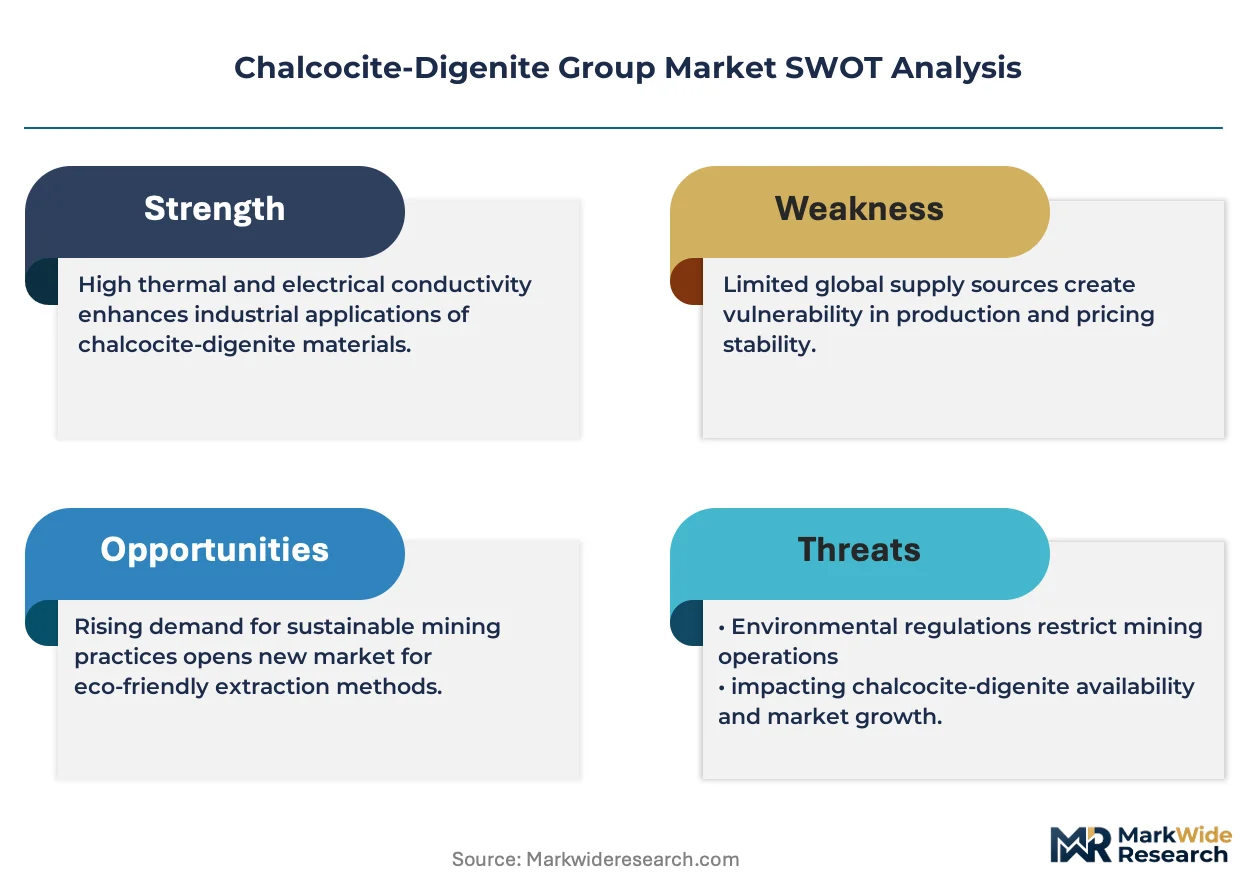
The Chalcocite-Digenite Group is pivoting along a widening fault line between ultra-high-purity material bound for semiconductor plating and standard-grade concentrate feeding traditional smelters. Rio Tinto Group leverages its Mongolian Oyu Tolgoi underground expansion to secure bornite-rich polymetallic feedstock. BHP Group anchors its South Australian Olympic Dam complex as a digenite-dominant source for specialized metallurgy. Freeport-McMoRan Inc. competes through its Indonesian Grasberg block cave, where supergene blankets yield exceptional chalcocite grades.
Chalcocite-digenite group minerals comprise copper sulfide phases with variable Cu:S ratios ranging from Cu₂S to Cu₁.₈S, forming through supergene enrichment or hypogene hydrothermal alteration and serving as primary feedstock for cathode production and specialty chemical synthesis. The purity grade dimension concentrates margin pools at the ultra-high-purity tier, where semiconductor and advanced catalyst manufacturers pay premiums for trace-metal control below 10 ppm. The application dimension shows electronics plating and battery interconnects outpacing legacy metallurgical offtake, though mining-sector direct ore sales still dominate absolute volume.
China's MEE enforces GB standards on smelter SO₂ intensity that elevate processing costs for low-grade sulfide feed, while Chile's environmental regulator tightens mine water discharge rules affecting supergene deposit extraction economics. The EU's REACH framework and RoHS directives constrain arsenic and selenium content in copper chemicals destined for European electronics supply chains. Stakeholders must track how carbon border adjustments and traceability mandates reshape competitive access to premium purity segments.
Market Dynamics
Supergene enrichment zone depletion in Chile's Atacama copper belt is forcing miners to process deeper, lower-grade hypogene ore, elevating energy intensity and reagent consumption across the chalcocite-digenite supply chain.
Growth Catalysts
- Renewable energy infrastructure buildout:Solar and wind farm developers in Chile and Australia are locking long-term copper concentrate offtake agreements to secure cathode supply for grid-scale battery storage interconnects.
- REACH RoHS compliance mandates:European electronics manufacturers are rejecting arsenic-bearing copper chemicals, pulling ultra-high-purity chalcocite-digenite derivatives into semiconductor plating supply chains.
- Direct solvent extraction-electrowinning (SX-EW):Hydrometallurgical refiners in Arizona and Peru are retrofitting facilities to process supergene oxide-sulfide transitional ore, bypassing traditional smelter bottlenecks.
Market Restraints
- Water scarcity in Atacama extraction:Chile's environmental regulator has tightened mine water discharge permits, forcing operators to deploy costly seawater desalination for heap leach operations.
- Natural gas price volatility:Smelters in Zambia and the Democratic Republic of Congo face unstable thermal energy costs, compressing margins on low-grade sulfide concentrate processing.
- Arsenic substitution in electronics:Gallium arsenide interconnects in RF semiconductors are ceding share to silicon-germanium alloys, reducing specialty copper chemical demand in certain wafer fabrication steps.
Strategic Opportunities
- Mongolian polymetallic expansion:Oyu Tolgoi's underground block cave is ramping bornite-rich output, offering feedstock diversification beyond Chilean supergene dependence.
- South Australian Olympic Dam complex:BHP's digenite-dominant resource base supports specialized metallurgy for nuclear-grade copper applications with trace-metal specifications below 5 ppm.
- Indonesian Grasberg supergene blankets:Freeport-McMoRan's block cave operations yield exceptional chalcocite grades suitable for direct shipping ore to Chinese smelters under tightened GB emission standards.
Industry Challenges
- Geometallurgical modeling complexity:Variable Cu:S ratios across supergene enrichment profiles require real-time ore sorting and blending optimization to maintain smelter feed consistency.
- Carbon border adjustment compliance:EU importers must document Scope 3 emissions from Chilean and Peruvian mining operations, creating certification timeline bottlenecks for spot concentrate sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chalcocite-Digenite Group Market |
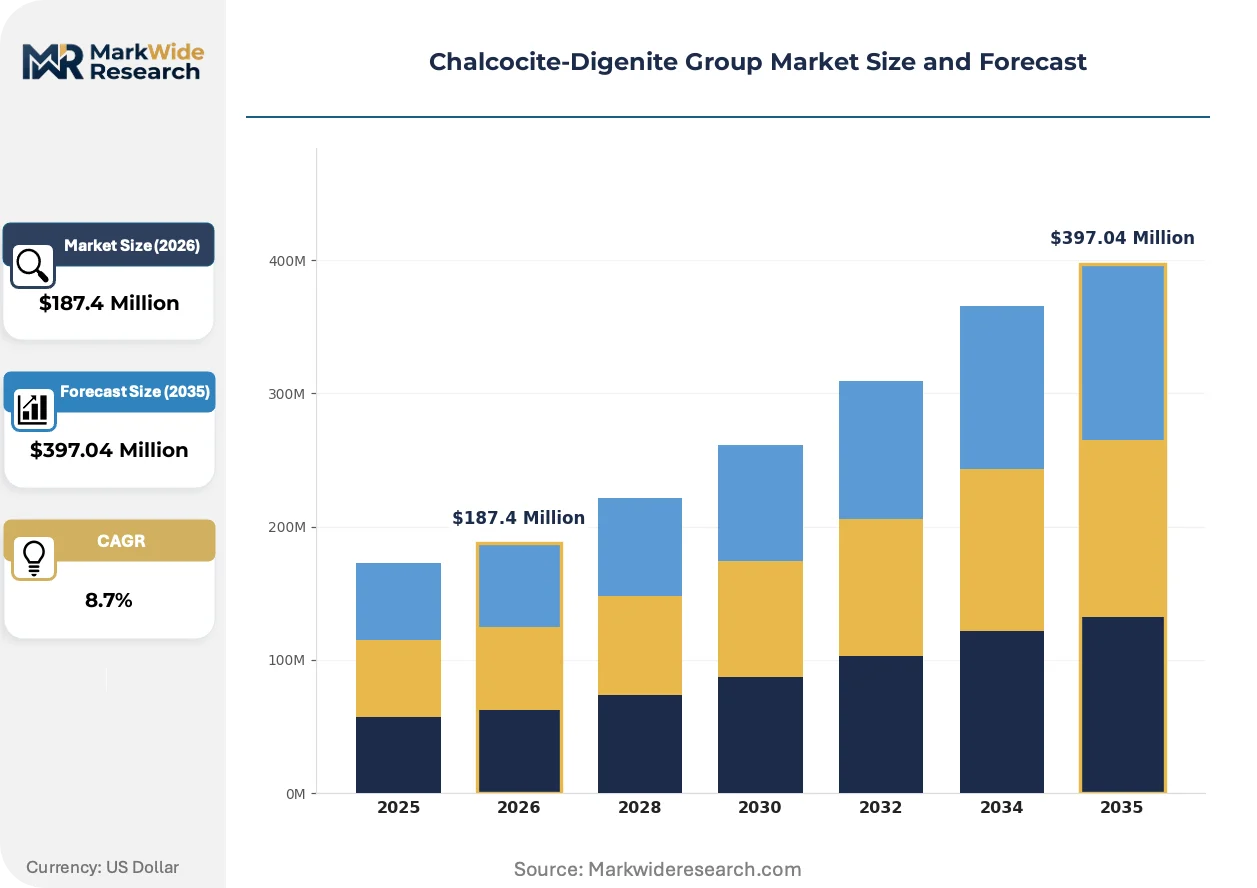
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chalcocite, Digenite, Bornite, Covellite Application: Electronics, Metallurgy, Mining, Catalysts End User: Manufacturers, Mining Companies, Research Institutions, Recycling Centers Purity Grade: Standard, High Purity, Ultra High Purity, Technical Grade |
| Companies Covered | Rio Tinto Group, Vale S.A., BHP Group, Freeport-McMoRan Inc., Antofagasta plc, Glencore plc, Codelco, Southern Copper Corporation, KGHM Polska Miedź S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chalcocite-Digenite Group Market Emerging Trajectories
Electrochemical processing advances and purity-grade bifurcation are compressing traditional smelter economics while opening premium tiers for semiconductor-qualified material.
Sensor-based ore sorting using X-ray transmission and laser-induced breakdown spectroscopy is absorbing variability in run-of-mine chalcocite-digenite grades. Chilean operators at Escondida and Collahuasi are deploying real-time particle discrimination to separate high-grade supergene fragments from hypogene waste. This technology is absorbing margin pressure from declining head grades by reducing downstream reagent consumption and tailings volume.
China's MEE enforcement of GB 25467-2010 smelter SO₂ intensity limits is accelerating capital deployment in acid plants and sulfur recovery units. The regulation forces independent smelters in Jiangxi and Anhui to reject high-sulfur concentrate or pay penalties, redirecting procurement toward Australian and Mongolian low-sulfur feedstock. Copper chemical exporters to the EU are simultaneously navigating REACH registration deadlines for chalcocite-derived intermediates.
Long-term offtake contracting is displacing spot market liquidity as renewable energy developers and battery manufacturers seek supply security. Tier-1 cathode producers in Japan and South Korea are locking five-year concentrate agreements with Chilean miners, squeezing merchant traders from premium-grade lanes. This behavioral shift concentrates price discovery in lower-purity segments and compresses working capital cycles for integrated mining-smelting operations.
Chalcocite-Digenite Group Market Segmentation
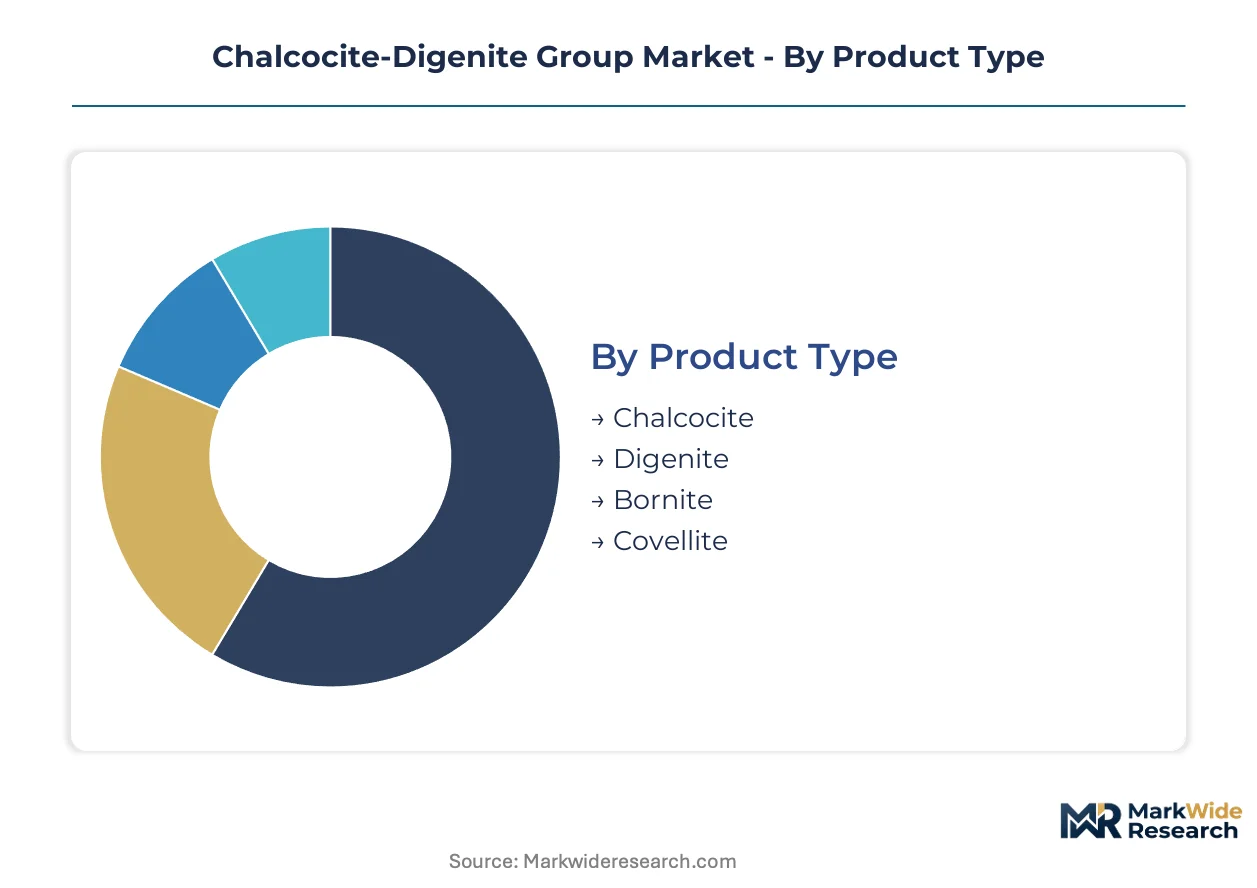
Segmentation in the chalcocite-digenite group market separates margin pools from commodity flows. Purity grades determine qualification for semiconductor plating versus smelter feed, while application splits reveal where renewable energy infrastructure is redirecting concentrate procurement.
Product Type:
Certification burdens fall heaviest on bornite and chalcocite shipments to European electronics supply chains, where REACH registration and RoHS arsenic limits apply. Digenite and covellite face lighter documentation for metallurgical offtake.
- Chalcocite:Cu₂S composition delivers the highest copper content among supergene sulfides, with Cu:S ratios near stoichiometric purity. Solar farm developers in Chile's Atacama belt are locking long-term offtake for grid-scale battery storage interconnects, bypassing spot market volatility. Chalcocite sits at the top of the volume ranking, with bornite climbing the fastest.
- Bornite:Cu₅FeS₄ structure carries iron substitution that complicates acid plant balance in smelter circuits. Rio Tinto's Oyu Tolgoi expansion in Mongolia is ramping bornite-rich polymetallic output, offering feedstock diversification beyond Chilean supergene dependence.
- Digenite:Cu₁.₈S non-stoichiometry creates variable processing responses in electrowinning circuits. BHP's Olympic Dam complex in South Australia anchors specialized metallurgy for nuclear-grade applications.
- Covellite:CuS phase with layered crystal structure requires modified flotation chemistry. Limited commercial extraction concentrates supply in Peruvian supergene deposits.
Chalcocite dominates absolute concentrate volume, while bornite gains share fastest on Mongolian supply expansion.
Application:
Cost tiers separate electronics plating from bulk metallurgical consumption, with purity premiums widening the spread between qualified and unqualified material.
- Electronics:Semiconductor plating and battery interconnects demand ultra-high-purity material with trace metals below 10 ppm. Japanese and South Korean cathode producers are locking five-year concentrate agreements, squeezing merchant traders from premium lanes. Electronics commands the steepest price tier, with catalysts expanding most quickly.
- Metallurgy:Traditional smelter feed for cathode production tolerates higher arsenic and selenium content. China's MEE enforcement of GB 25467-2010 SO₂ intensity limits is redirecting procurement toward Australian and Mongolian low-sulfur feedstock.
- Mining:Direct ore sales from supergene enrichment zones supply Chinese smelters under tightened emission standards. Freeport-McMoRan's Grasberg block cave yields exceptional grades suitable for direct shipping ore.
- Catalysts:Specialty chemical synthesis for petrochemical and environmental applications requires controlled particle morphology. REACH registration deadlines constrain European market access for intermediate derivatives.
Metallurgy retains volume leadership, though electronics captures margin concentration.
End User:
Customer type determines contract structure, with integrated miners preferring long-term offtake and merchant traders defending spot market liquidity in lower-purity segments.
- Manufacturers:Tier-1 cathode producers and copper chemical processors dominate ultra-high-purity procurement. Procurement is concentrating in direct mill-to-smelter arrangements that compress working capital cycles.
- Mining Companies:Integrated operators blend supergene and hypogene ore to maintain smelter feed consistency. Real-time ore sorting at Escondida and Collahuasi is absorbing grade variability.
- Research Institutions:Limited volume demand for reference materials and geochemical standards. Specifications focus on documented provenance and certified composition.
- Recycling Centers:Secondary copper recovery from electronic waste and industrial residues. EU carbon border adjustments create certification timeline bottlenecks for spot concentrate sales.
Manufacturers anchor premium-tier demand, with mining companies controlling upstream supply concentration.
Purity Grade:
Margin pools concentrate at the ultra-high-purity tier, where semiconductor and advanced catalyst manufacturers pay premiums for trace-metal control below 10 ppm.
- Standard:Conventional smelter feed with arsenic and selenium levels acceptable for metallurgical processing. Natural gas price volatility in Zambia and DRC compresses margins on low-grade sulfide concentrate processing.
- High Purity:Reduced trace metals for battery interconnect and specialty chemical applications. China's dual carbon goals and GB standards for smelter emissions are tightening feedstock specifications.
- Ultra High Purity:Trace metals below 5 ppm for semiconductor plating and nuclear-grade copper. BHP's Olympic Dam complex supports this tier with digenite-dominant resources.
- Technical Grade:Intermediate specification for industrial catalyst and pigment manufacturing. Water scarcity in Chile's Atacama is forcing costly seawater desalination for heap leach operations serving this segment.
Standard grade retains volume dominance, while ultra-high-purity gains share fastest on electronics supply chain qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining engineers and metallurgists with supergene deposit expertise cluster in Chile's Atacama Desert, Australia's Olympic Dam corridor, and Mongolia's Gobi copper belt. These talent concentrations anchor the three dominant supply geographies for chalcocite-digenite group minerals.
Chile
Atacama copper belt supergene enrichment zones supply high-grade chalcocite ore to Chinese smelters under tightened GB emission standards. Chile's environmental regulator has tightened mine water discharge permits, forcing operators at Escondida and Collahuasi to deploy seawater desalination for heap leach operations. Calama and Antofagasta host the concentrated mining infrastructure serving this feedstock.
Australia
Solar and wind farm developers are locking long-term copper concentrate offtake agreements to secure cathode supply for grid-scale battery storage interconnects. The country's national environmental regulator enforces stringent tailings management protocols affecting Olympic Dam's digenite-dominant processing economics. South Australia's Gawler Craton anchors specialized metallurgy for nuclear-grade copper applications.
China
Semiconductor and advanced catalyst manufacturers pay premiums for ultra-high-purity material with trace metals below 10 ppm. MEE enforcement of GB 25467-2010 smelter SO₂ intensity limits redirects procurement toward Australian and Mongolian low-sulfur feedstock. Jiangxi and Anhui provinces concentrate the independent smelter capacity facing these compliance pressures.
Mongolia
Bornite-rich polymetallic output from underground block cave operations offers feedstock diversification beyond Chilean supergene dependence. The country's mining regulator oversees environmental impact assessments for Gobi Desert extraction projects. Oyu Tolgoi's South Gobi location positions Mongolian supply for overland rail shipment to Chinese smelters.
Indonesia
Supergene blankets yield exceptional chalcocite grades suitable for direct shipping ore under tightened emission standards. The national mineral and coal directorate regulates export licensing for copper concentrate shipments. Papua's Grasberg mining district concentrates the block cave operations feeding this high-grade supply stream.
Chalcocite-Digenite Group Market Vendor Landscape
Capital-heavy producers compete with asset-light traders across a bifurcated structure where integrated miners control premium-grade supply and merchant houses defend spot market liquidity in lower-purity segments. The vendor base separates into three strategic archetypes: diversified majors with polymetallic portfolios, copper-dominant specialists with supergene assets, and state-owned enterprises with sovereign resource access. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, displacing spot market price discovery.
Among diversified majors, Rio Tinto Group and BHP Group exemplify the polymetallic archetype spanning Mongolian bornite and Australian digenite resources. Freeport-McMoRan Inc. occupies a position within the copper-dominant specialist tier, anchored by Indonesian supergene operations. These three entities represent the scale-driven end of competitive positioning, each leveraging distinct geological endowments to serve differentiated purity-grade demand.
| Leading Market Players |
|---|
| Rio Tinto Group |
| Vale S.A. |
| BHP Group |
| Freeport-McMoRan Inc. |
| Antofagasta plc |
| Glencore plc |
| Codelco |
| Southern Copper Corporation |
| KGHM Polska Miedź S.A. |
| Others |
Supply Flow & Price Mechanics
Chinese smelter procurement teams under MEE's GB 25467-2010 enforcement are rejecting high-sulfur concentrates and demanding certified low-emission feedstock, forcing Chilean and Australian miners to absorb desalination and acid plant capital costs that compress spot market premiums while elevating long-term contract pricing power for qualified suppliers.
Pricing Analysis
Long-term offtake contracting dominates premium-grade transactions, separating spot commodity sales from multi-year supply agreements with fixed escalators. Price differentiation rests on trace-metal certification below 10 ppm for semiconductor plating versus standard smelter feed tolerances. Cost compression in standard-grade concentrate runs through Chilean water scarcity and Zambian energy volatility. Merchant traders show highest price sensitivity, while Japanese cathode producers accept premiums for supply security.
Supply Chain Analysis
Dual-sourcing mandates from European electronics manufacturers and Chinese state smelters require qualified suppliers in Chile, Australia, and Mongolia to maintain parallel certification pathways. Raw material flows draw from Atacama supergene deposits, Olympic Dam digenite resources, and Oyu Tolgoi bornite output. Single-source vulnerability concentrates in Chilean water-dependent heap leach operations. Distribution runs through integrated miner-smelter direct arrangements and concentrated merchant trading houses in Singapore and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chalcocite-digenite group market represents a late-cycle quality story as semiconductor plating specifications harden trace-metal ceilings below 5 ppm, disqualifying legacy smelter feed and concentrating margin pools with certified ultra-high-purity producers.
For Market Incumbents: Extend certification coverage into nuclear-grade copper specifications below 5 ppm at Olympic Dam-type deposits to capture premium tier expansion. Deepen upstream control over Mongolian bornite supply as Chilean supergene depletion accelerates. Defend against hydrometallurgical SX-EW bypass technologies by locking renewable developer offtake with embedded carbon accounting. For New Entrants and Emerging Players: Begin with Indonesian supergene blanket deposits offering exceptional chalcocite grades suitable for direct shipping ore under tightened Chinese emission standards. Target technical-grade catalyst applications where REACH registration burdens deter established suppliers. Pursue joint qualification programs with Japanese cathode producers seeking supply diversification beyond Chilean dependence. For Investors and Strategic Acquirers: Asymmetric upside sits with polymetallic deposit operators holding bornite-digenite resources in jurisdictions with rail access to Chinese smelters. Five-to-ten year viability favors integrated mining-metallurgy assets with captive water solutions. Watch for EU carbon border adjustment implementation timelines as the inflection signal for premium-grade price tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Japanese cathode producers lock five-year concentrate contracts with Chilean miners, compressing merchant trader participation. |
| Backward Integration | Chinese smelters acquire Mongolian rail infrastructure to secure bornite-rich feedstock bypassing spot market volatility. |
| Green Certification Program | EU carbon border adjustments require documented Scope 3 emissions from Atacama mining operations. |
| Capacity Expansion | Oyu Tolgoi's underground block cave ramps output to diversify supply beyond Chilean supergene dependence. |
| Joint Venture | Sensor-based ore sorting partnerships at Escondida reduce downstream reagent consumption and tailings volume. |
Methodological Framework
Direct dialogue with copper concentrate procurement managers, smelter metallurgists, semiconductor plating specialists, and environmental compliance officers anchored qualitative findings. Secondary validation drew from Chinese MEE enforcement notices, Chilean environmental regulator discharge permits, EU REACH registration databases, and SEC 10-K filings from diversified mining majors. Bottom-up volume modeling across purity grades and applications triangulated with top-down macroeconomic demand projections.
Segmented outputs across the projection horizon reflect disaggregated modeling by mineral phase, purity tier, end-use application, and regional production cluster. CAGRs emerged from weighted average growth across these dimensions, incorporating copper intensity coefficients for renewable energy infrastructure buildout and semiconductor wafer fabrication capacity expansion. Forecast inputs included Chinese dual carbon policy implementation trajectories and supergene enrichment zone depletion curves from Chilean geological surveys.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to GB smelter standards, abrupt shifts in gallium arsenide versus silicon-germanium RF semiconductor market share, and geopolitical disruption to Mongolian rail corridors. Deviation in EU carbon border adjustment enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Rhenium Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
ITO Nanoparticles Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Silicon Germanium Material Market