
 Silicon Tetrachloride Market | 2026-2036
Silicon Tetrachloride Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Tetrachloride Market Outlook
China's polysilicon corridor is reconfiguring upstream chemical supply chains as domestic capacity targets for solar-grade silicon multiply. Wacker Chemie AG leverages its integrated siloxane-to-chlorosilane platform to sustain cost leadership in European specialty grades. Tokuyama Corporation anchors Japanese supply for semiconductor precursor applications through ultra-high-purity refining capabilities. Shin-Etsu Chemical Co., Ltd. dominates merchant sales across Asia-Pacific with captive chlorosilane output tied to its silicone polymers division.
Silicon tetrachloride is a colorless, fuming liquid with formula SiCl4, produced via chlorination of silicon or ferrosilicon at temperatures exceeding 400°C, serving primarily as a precursor to high-purity polysilicon and fumed silica. The precursor product type commands premium pricing tied to semiconductor epitaxy requirements, while intermediate grades face margin compression from solar polysilicon commoditization. Electronics applications lead value capture due to stringent purity thresholds, though chemicals processing represents the largest volume outlet through silicone resin synthesis.
China's MEE enforces chlorosilane emissions caps that force retrofitting of vent gas recovery systems, while REACH in Europe mandates registration and hazard communication for SiCl4 imports. Japan's METI coordinates national stockpile policies for critical semiconductor feedstocks including high-purity chlorosilanes. Stakeholders must monitor divergence between solar-grade oversupply and semiconductor-grade tightness when committing to purification capacity investments.
Market Dynamics
Semiconductor fabs in Jiangsu province and the Yangtze River Delta are consolidating procurement around ultra-high-purity silicon tetrachloride specifications, forcing chlorosilane producers to decouple solar-grade and electronics-grade purification lines.
Growth Catalysts
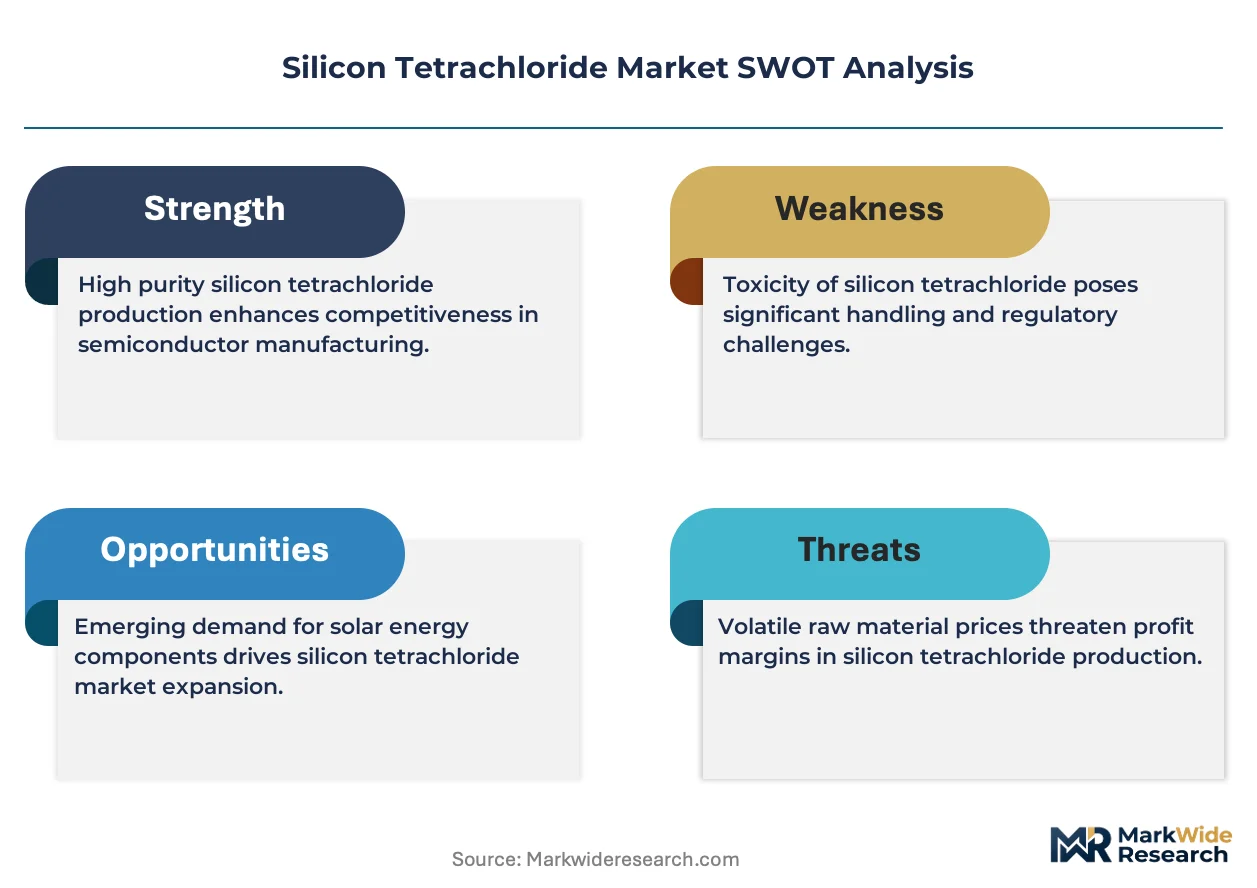
- MEE Emissions Caps:China's tightening chlorosilane vent gas standards are accelerating retrofit investments in closed-loop recovery systems, tightening supply discipline among marginal producers.
- Polysilicon Feedstock Expansion:East Asian semiconductor fabs are scaling epitaxial silicon precursor procurement to support advanced node production, concentrating demand in high-purity grades.
- Dual Carbon Policy Framework:Beijing's carbon neutrality mandates are redirecting state support toward integrated chlorosilane-to-polysilicon complexes with captive energy supply.
Market Restraints
- Ferrosilicon Input Volatility:Metallurgical-grade silicon feedstock costs fluctuate with Chinese steel sector demand, compressing margins for non-integrated chlorosilane producers.
- Jiangsu Supply Concentration:Over half of domestic high-purity capacity sits within a single province, creating geographic risk exposure to regional environmental enforcement actions.
- Trichlorosilane Substitution:Solar polysilicon producers are shifting feedstock chemistry toward trichlorosilane-based Siemens processes, displacing silicon tetrachloride in volume applications.
Strategic Opportunities
- Fumed Silica Derivatives:Pyrogenic silica manufacturers are qualifying semiconductor-grade silicon tetrachloride for specialty coating applications, opening premium pricing tiers outside polysilicon.
- Closed-Loop Recycling Infrastructure:Spent chlorosilane recovery systems are creating service revenue streams for equipment vendors serving China's tightening MEE compliance deadlines.
- Silicone Resin Convergence:Hybrid silicone polymer formulations are integrating electronics-grade chlorosilane precursors for high-temperature insulation in electric vehicle powertrains.
Industry Challenges
- Purification Engineering Talent:The scarcity of process engineers capable of designing 9N+ purity distillation systems is extending commissioning timelines for new semiconductor-grade capacity.
- REACH Registration Burden:European chemical importers face extended hazard communication documentation requirements for silicon tetrachloride volumes, slowing market entry for Asian producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Tetrachloride Market |
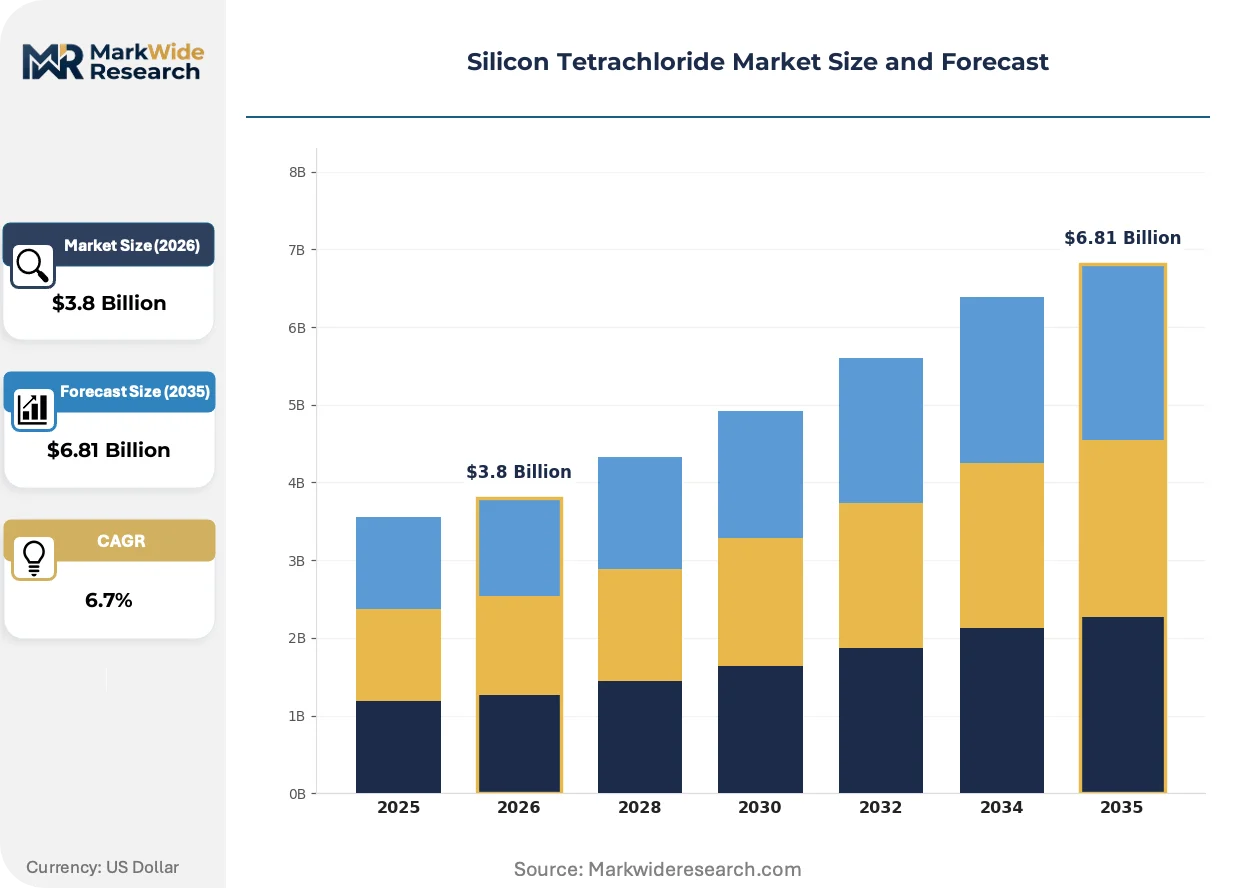
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent, Intermediate, Solvent, Precursor Application: Silicon Production, Electronics, Coatings, Chemicals End User: Semiconductor Industry, Chemical Manufacturing, Solar Cells, Pharmaceuticals Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Dow Inc., Evonik Industries AG, Wacker Chemie AG, Linde plc, Merck KGaA, Tokuyama Corporation, Hemlock Semiconductor, OCI Company Ltd., Shin-Etsu Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Tetrachloride Market Strategic Shifts
Digital twin modeling and closed-loop process control are compressing yield variance in chlorosilane purification, enabling real-time specification adjustments that previously required batch reprocessing.
Plasma-enhanced chemical vapor deposition feedstock qualification is virtualizing traditional wet chemistry testing protocols for silicon tetrachloride purity validation. Semiconductor fabs in Taiwan and South Korea are adopting spectroscopic inline monitoring to bypass lengthy laboratory certification cycles. This compression of quality assurance timelines is virtualizing the competitive moat that legacy analytical laboratories previously held over merchant suppliers.
REACH in Europe is mandating updated safety data sheets and exposure scenario documentation for chlorosilane imports, forcing Asian exporters to maintain dedicated regulatory affairs functions. The industrial consequence is a bifurcation between integrated producers with in-house compliance capabilities and trading houses dependent on third-party registration agents. Specialty chemical distributors in Germany and the Netherlands are most affected, responding by consolidating their supplier panels to reduce documentation overhead.
Consignment inventory arrangements are displacing spot purchasing for high-purity silicon tetrachloride among Yangtze River Delta semiconductor fabs. Original equipment manufacturers are absorbing working capital requirements to lock in specification-tailored supply, displacing traditional merchant distributors from premium account relationships. This shift is most visible in Jiangsu province, where tier-one polysilicon consumers now maintain 90-day rolling forecasts with sole-source chlorosilane partners.
Silicon Tetrachloride Market Segmentation
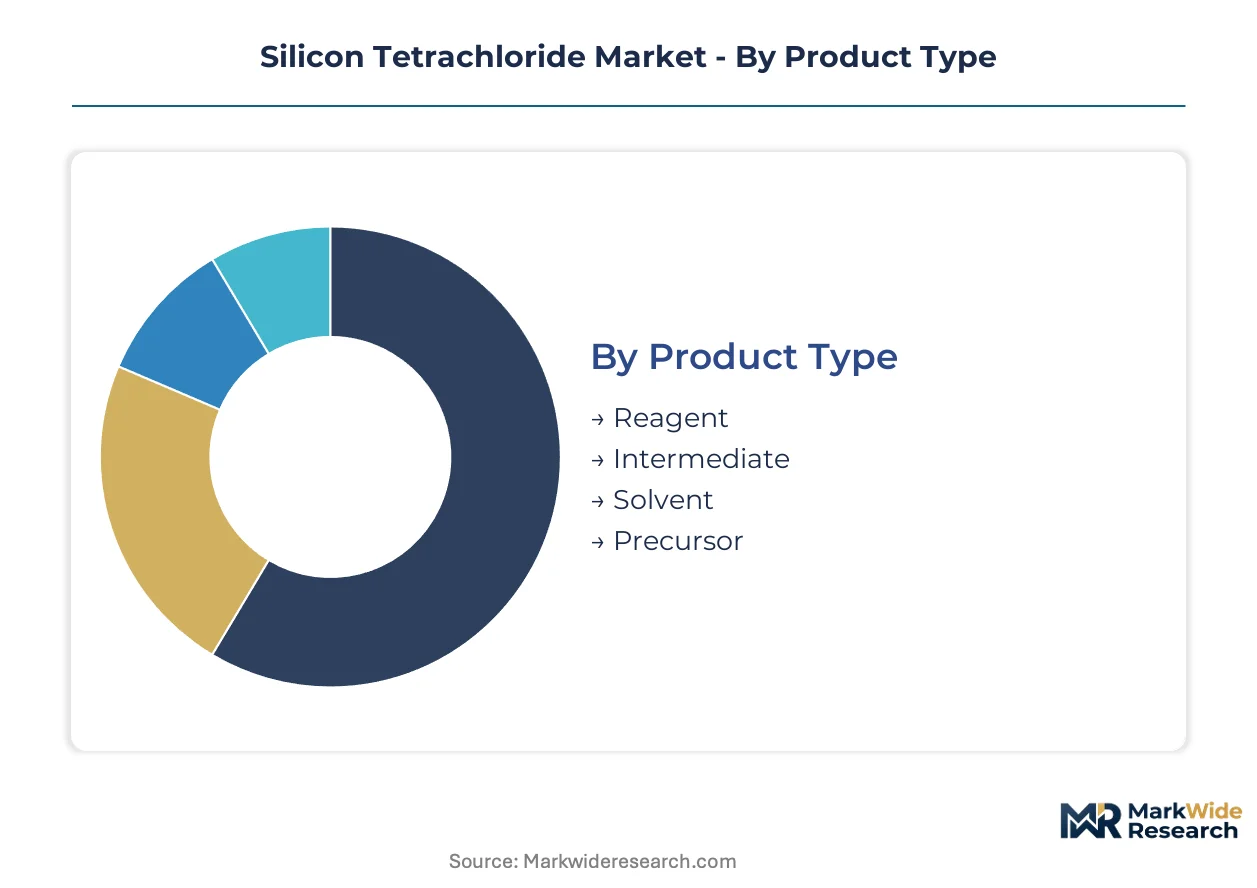
Silicon tetrachloride procurement cycles vary dramatically across segments, from quarterly spot contracts in commodity chemicals to multi-year sole-source agreements for semiconductor precursors. Understanding these velocity differentials helps suppliers align working capital deployment with margin capture potential.
Product Type:
Reagent grades turn inventory fastest due to standardized specifications, while precursor products lock in capital through extended qualification timelines.
- Precursor:Ultra-high-purity material meeting 9N+ specifications for epitaxial silicon deposition in advanced node semiconductor fabs. Procurement concentrates in Jiangsu province semiconductor clusters where fabs mandate vendor-specific qualification protocols that extend sales cycles to 18-24 months.
- Intermediate:Technical-grade chlorosilane feeding polysilicon production and silicone resin synthesis. Demand clusters in the Yangtze River Delta manufacturing belt where integrated chemical complexes consume volumes through pipeline transfer rather than packaged delivery.
- Reagent:Laboratory and analytical-grade material for R&D and quality control applications.
- Solvent:Process solvent applications in specialty chemical synthesis and extraction operations.
Precursor anchors the volume base while intermediate gains share at the steepest rate as solar polysilicon capacity expands.
Application:
Cost tier stratification separates specification-intensive electronics applications from price-sensitive chemical processing volumes.
- Electronics:Epitaxial silicon deposition and chemical vapor deposition feedstocks for semiconductor device fabrication. Specification requirements from Taiwan and South Korean fabs concentrate demand around sub-ppb metallic impurity thresholds that command 3-4x pricing premiums over solar-grade material.
- Chemicals:Silicone resin, silane coupling agent, and fumed silica production. Volume consumption centers on integrated siloxane producers in Germany and Japan who backward-integrate chlorosilane production to control silicone polymer feedstock costs.
- Silicon Production:Polysilicon feedstock for photovoltaic and semiconductor-grade silicon manufacturing.
- Coatings:Specialty surface treatment and thin-film deposition applications.
Chemicals anchors the volume base while electronics climbs the fastest on semiconductor capacity expansion.
End User:
Customer concentration patterns separate fragmented pharmaceutical procurement from consolidated semiconductor direct sourcing.
- Semiconductor Industry:Integrated device manufacturers and foundries consuming high-purity precursor for epitaxial wafer production. Procurement is consolidating around consignment inventory arrangements in the Yangtze River Delta where fabs absorb working capital to secure specification-tailored supply.
- Solar Cells:Polysilicon producers operating Siemens and fluidized bed reactor processes. Feedstock chemistry is shifting toward trichlorosilane-based processes in Chinese solar corridors, displacing silicon tetrachloride in volume applications.
- Chemical Manufacturing:Silicone polymer, resin, and specialty silane producers.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and intermediates production.
Chemical manufacturing anchors the volume base while semiconductor industry expands most quickly on advanced node investments.
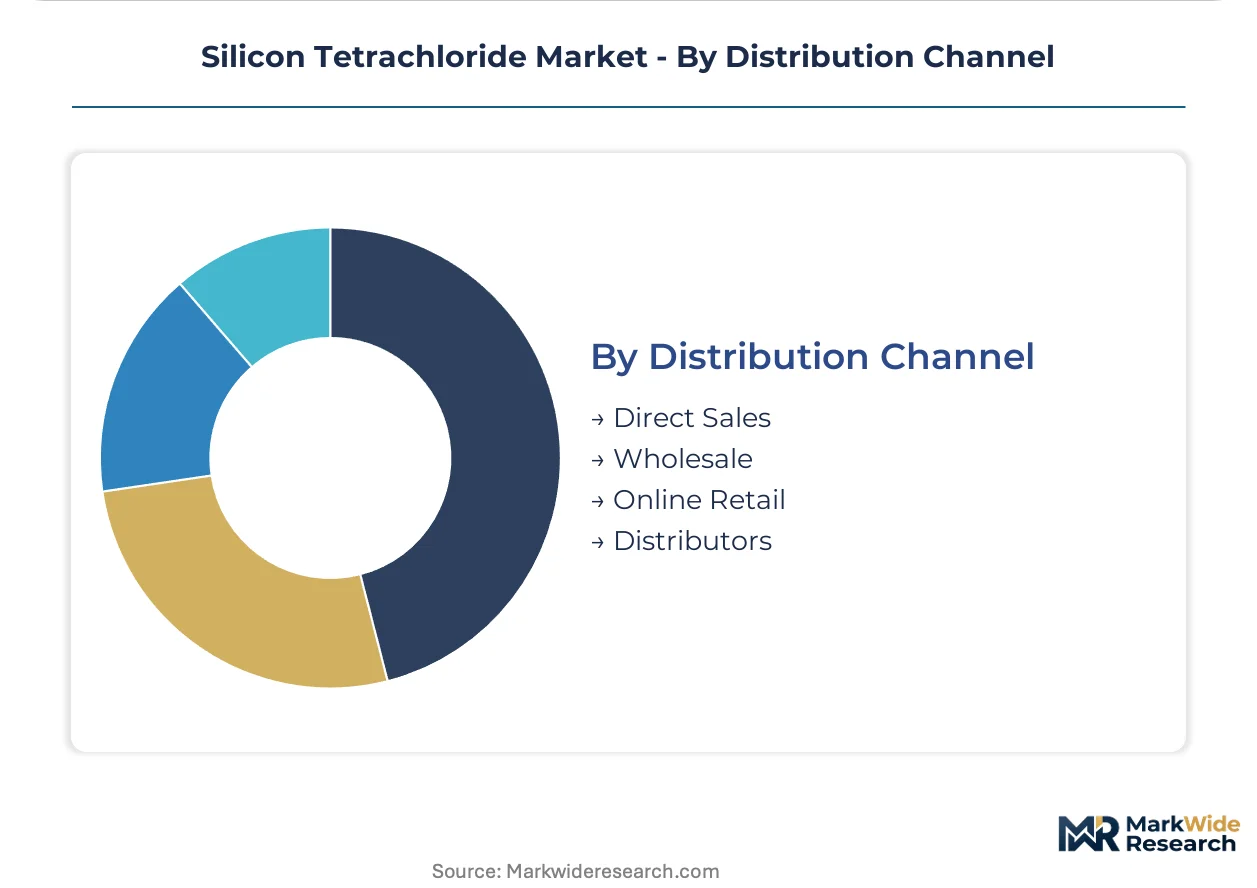
Distribution Channel:
Supply chain configuration separates asset-heavy direct sales from working-capital-light distributor models.
- Direct Sales:Producer-to-consumer supply for high-purity semiconductor and solar-grade material. Contracts specify 90-day rolling forecasts with sole-source arrangements displacing spot purchasing among Jiangsu province polysilicon consumers.
- Distributors:Specialty chemical distributors serving fragmented pharmaceutical and coatings end-users. REACH registration burdens in Europe are forcing consolidation of supplier panels among German and Dutch distributors to reduce documentation overhead.
- Wholesale:Bulk volume transactions for intermediate-grade material.
- Online Retail:Small-package reagent sales for laboratory and R&D applications.
Wholesale anchors the volume base while direct sales gains share fastest on semiconductor fab consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorosilane purification capacity clusters in East Asian manufacturing corridors where semiconductor fabs and polysilicon producers co-locate. Regulatory pressure on emissions and carbon intensity is reshaping investment geography across the major producing zones.
China
Jiangsu province semiconductor fabs drive ultra-high-purity precursor procurement while Yangtze River Delta polysilicon corridors consume intermediate grades. MEE emissions caps force retrofitting of vent gas recovery systems among chlorosilane producers. Xuzhou and Nanjing host the densest concentration of purification assets serving both solar and electronics supply chains.
Japan
Epitaxial silicon deposition for advanced node chips anchors demand from Kyushu and Kansai semiconductor clusters. METI coordinates national stockpile policies for critical semiconductor feedstocks including high-purity chlorosilanes. Tokuyama anchors domestic supply through ultra-high-purity refining capabilities serving Osaka-Tokyo electronics corridors.
Germany
Integrated siloxane-to-chlorosilane platforms sustain European specialty grade production for silicone polymer feedstocks. REACH mandates registration and hazard communication for SiCl4 imports, filtering market entry for non-compliant Asian exporters. Bavarian chemical complexes around Burghausen represent the continent's densest chlorosilane purification infrastructure.
South Korea
Memory and logic foundries in Gyeonggi province scale epitaxial precursor procurement for sub-7nm process nodes. MFDS chemical control regulations align with semiconductor material traceability requirements. Pyeongtaek and Hwaseong semiconductor clusters concentrate demand for 9N+ specification material with vendor-locked qualification protocols.
United States
Domestic polysilicon revival and onshored semiconductor fabs drive precursor demand in Arizona and Texas manufacturing corridors. EPA air toxics standards govern chlorosilane vent handling and spill response protocols. Phoenix and Austin metro areas attract integrated chlorosilane-to-polysilicon investments tied to captive renewable energy supply.
Silicon Tetrachloride Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in purification and precursor formulation. The vendor base spans diversified chemical conglomerates with captive chlorosilane output and merchant specialists serving semiconductor qualification protocols. Three archetypes dominate: integrated siloxane producers with backward control over feedstock, standalone high-purity refiners with fab-locked contracts, and industrial gas distributors with logistics scale. Competitive moves center on capacity decoupling—separating solar-grade and electronics-grade purification lines—and consignment inventory arrangements that absorb customer working capital.
Among German integrated chemical producers, Wacker Chemie AG exemplifies the siloxane-to-chlorosilane platform archetype with European specialty grade positioning. Tokuyama Corporation anchors Japanese supply for semiconductor precursor applications through ultra-high-purity refining capabilities. Shin-Etsu Chemical Co., Ltd. occupies the merchant sales position across Asia-Pacific with captive chlorosilane output tied to silicone polymers. These three represent distinct competitive vectors: European integration, Japanese purity specialization, and Asian-Pacific merchant scale.
| Leading Market Players |
|---|
| Dow Inc. |
| Evonik Industries AG |
| Wacker Chemie AG |
| Linde plc |
| Merck KGaA |
| Tokuyama Corporation |
| Hemlock Semiconductor |
| OCI Company Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province supply concentration determines both the 3-4x pricing premium spread between semiconductor-grade and solar-grade material and the consignment inventory arrangements displacing spot purchasing among Yangtze River Delta fabs. MEE emissions enforcement tightens supply discipline at the margin, amplifying price volatility when regional environmental actions interrupt production.
Pricing Analysis
REACH registration mandates dictate the pricing tier structure across European imports, forcing Asian producers to absorb compliance overhead or cede share to integrated siloxane platforms. Three-tier pricing structure across 9N+ precursor, technical-grade intermediate, and laboratory reagent levels separates fab-qualified material commanding long-term offtake premiums from commoditized solar feedstock. Cost compression in intermediate grades is intensifying because trichlorosilane substitution in polysilicon corridors erodes volume leverage. Solar cell manufacturers exhibit highest price sensitivity while semiconductor fabs accept premium positioning for vendor-locked qualification protocols.
Supply Chain Analysis
Consignment inventory arrangements at Yangtze River Delta fabs concentrate downstream working capital absorption among original equipment manufacturers rather than merchant distributors. Supply draws from chlorosilane purification assets clustered in China, Japan, and Germany where integrated siloxane producers and standalone refiners co-locate with downstream consumers. Ferrosilicon feedstock costs hinge on Chinese steel sector demand cycles, creating commodity volatility exposure for non-integrated producers. Distribution runs through direct sales channels for high-purity grades and specialty chemical distributors for fragmented pharmaceutical and coatings end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across purification capability tiers creates niche opportunities as semiconductor fabs decouple electronics-grade and solar-grade supply lines, opening specialist positions for qualified entrants.
For Market Incumbents: Build qualification protocol moats by extending 18-24 month fab-specific certification timelines that lock out merchant challengers. Secure backward integration into ferrosilicon or metallurgical-grade silicon feedstock to defend margin position against input volatility. Expand captive chlorosilane-to-polysilicon complex capacity in Jiangsu corridor under state dual carbon policy support. For New Entrants and Emerging Players: Build out fumed silica derivative applications as a penetrable white-space where semiconductor-grade material commands premium pricing outside commoditized polysilicon channels. Target spent chlorosilane recovery system service revenue under tightening MEE compliance deadlines in China. Pursue joint development agreements with pyrogenic silica manufacturers seeking qualification for specialty coating applications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated siloxane-to-chlorosilane platforms with in-house REACH compliance capabilities. Long-term viability centers on purification engineering talent scarcity extending commissioning timelines for new 9N+ capacity, creating durable returns for existing asset bases. Monitor divergence between solar-grade oversupply and semiconductor-grade tightness as inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Decoupling | Separate solar-grade and electronics-grade purification lines to capture divergent margin profiles. |
| Closed-Loop Recycling Infrastructure | MEE compliance deadlines in China create service revenue streams for vent gas recovery system vendors. |
| Consignment Inventory Arrangements | Yangtze River Delta fabs absorb working capital to lock specification-tailored supply from sole-source partners. |
| Digital Twin Implementation | Real-time yield variance compression enables specification adjustments without batch reprocessing delays. |
| Regulatory Affairs Function Buildout | REACH documentation requirements filter market entry for Asian producers lacking in-house compliance. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with chlorosilane plant managers, semiconductor procurement leads at Jiangsu fabs, silicone polymer R&D directors, and specialty chemical distribution partners; and secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical producers, and MEE emissions enforcement records. Bottom-up capacity and consumption modeling triangulated against top-down value chain analysis anchored the segmentation outputs.
Forecast inputs include grade tier stratification across precursor, intermediate, and reagent categories; end-use industry demand from semiconductor, solar, and chemical manufacturing sectors; and regional production hub clustering in East Asian manufacturing corridors. CAGRs were derived from elasticity-adjusted consumption projections across the analysis window, incorporating polysilicon capacity expansion schedules and semiconductor node migration patterns as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by state-supported Chinese chlorosilane-to-polysilicon complexes would shift outcomes beyond modeled supply discipline. Quarterly review of MEE enforcement actions in Jiangsu province, trichlorosilane substitution rates in solar corridors, and semiconductor fab qualification pipeline backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market