
 Global Ferro Liquid Display Market | 2026-2036
Global Ferro Liquid Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ferro Liquid Display Market Analysis
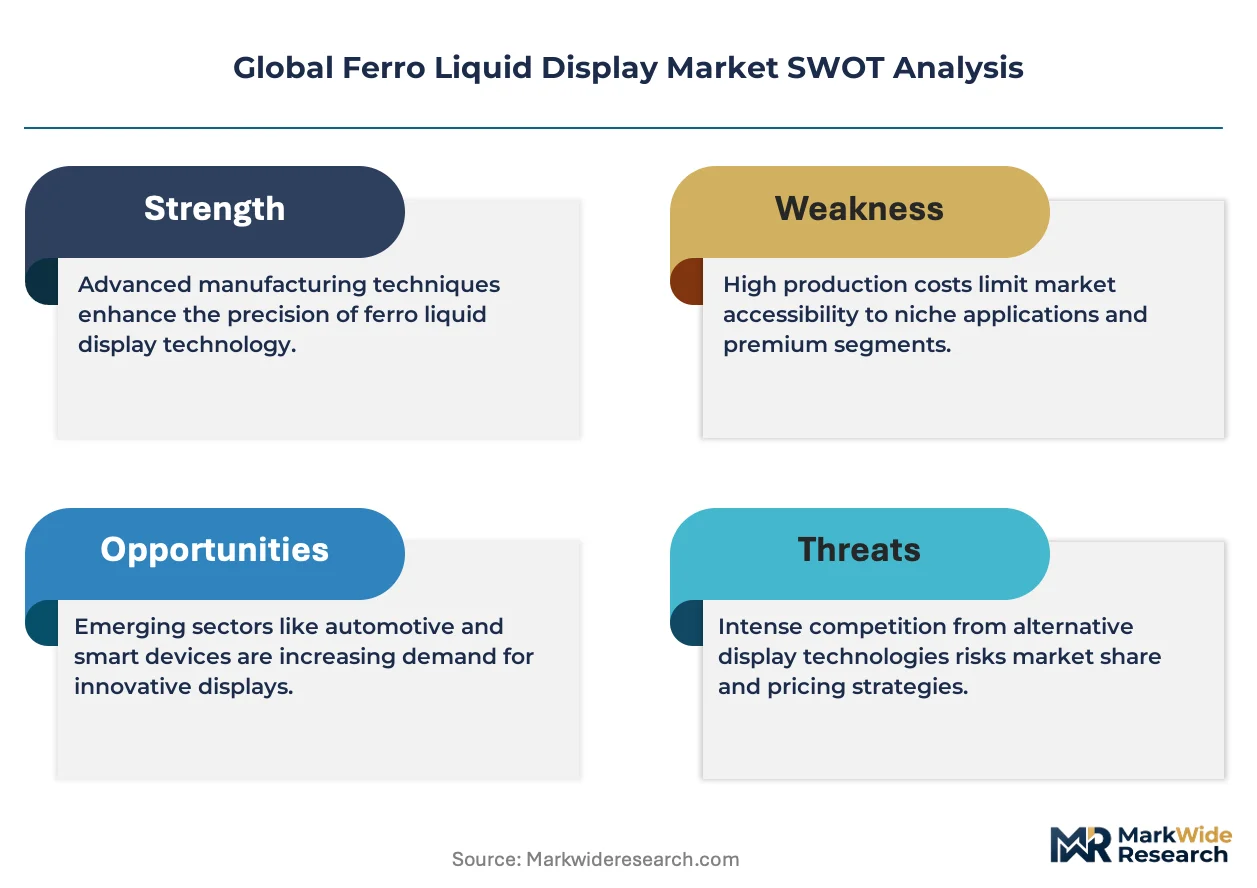
ISO 13406-2 certification for display device quality assurance is redrawing competitive entry barriers. Samsung Electronics leverages captive semiconductor fabrication to sustain cost advantages in ferrofluidic cell production. LG Display anchors its position through vertical control over liquid crystal supply chains. Toshiba Corporation specializes in industrial-grade ferro liquid modules for harsh-environment applications.
Ferro liquid displays utilize suspensions of nanoscale magnetic particles in carrier fluids, manipulated by external magnetic fields to modulate light transmission with response times below ten milliseconds. Their primary commercial purpose centers on adaptive optical systems requiring real-time reconfigurability without mechanical moving parts. The Displays product category dominates value capture due to premium pricing in medical imaging and aerospace instrumentation. Sensors represent the fastest-expanding application segment as industrial automation demands non-contact position sensing. Consumer Electronics channels show mature growth patterns with margin compression from commoditized LCD alternatives.
EMA medical device directives and FDA 21 CFR Part 820 quality system regulations govern ferro liquid display deployment in diagnostic equipment, forcing manufacturers to maintain validated cleanroom protocols. Japan's METI establishes efficiency benchmarks for display component energy consumption, directly influencing product design cycles. South Korea's MFDS enforces biocompatibility standards for ferrofluid materials used in implantable medical interfaces. Stakeholders must monitor evolving magnetic nanoparticle toxicity thresholds across German, Japanese, and South Korean regulatory frameworks to preempt compliance-driven supply disruptions.
Market Dynamics
Automotive display integration is forcing ferro liquid display manufacturers to reconfigure production lines for millisecond-response optical systems, as Tier 1 suppliers demand magnetic-field-modulated panels that eliminate mechanical actuators from heads-up displays.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:Restrictions on fluorinated greenhouse gases are accelerating substitution toward ferrofluid-based cooling and display systems in precision instrumentation across German industrial clusters.
- Medical imaging modality expansion:Real-time reconfigurable optics in MRI-guided surgical suites are pulling demand for nanoscale magnetic particle suspensions that modulate light without mechanical latency.
- Industrial automation sensor densification:Non-contact position sensing in South Korean smart factories is creating pull for ferrofluidic cells that respond to magnetic field variations below ten milliseconds.
Market Restraints
- Carrier fluid cost volatility:Synthetic hydrocarbon and fluorocarbon base liquids face input price swings tied to petrochemical feedstock indices, compressing margin structures for display module assemblers.
- Magnetic nanoparticle supply concentration:Production of iron oxide and cobalt ferrite nanocrystals concentrates in Japanese specialty chemical foundries, creating single-source vulnerability for non-captive manufacturers.
- RoHS material substitution complexity:EU directives restricting hazardous substances force reformulation of ferrofluid stabilizing surfactants, extending qualification timelines for medical device certifications.
Strategic Opportunities
- Aerospace instrumentation retrofit cycles:Commercial aviation maintenance programs in the United States are creating replacement demand for legacy mechanical gauge systems with solid-state ferrofluidic optical modulators.
- Japan METI energy efficiency mandates:Display component consumption benchmarks are incentivizing adoption of field-modulated panels that draw power only during state transitions, not continuous illumination.
- Implantable medical interface biocompatibility:South Korea MFDS standards for ferrofluid materials are opening certified-supplier pathways for diagnostic catheter-integrated displays in cardiovascular applications.
Industry Challenges
- ISO 13406-2 certification timelines:Medical device quality assurance protocols require eighteen-to-twenty-four month validation cycles for cleanroom ferrofluidic cell production, delaying revenue recognition for new entrants.
- Magnetic nanoparticle toxicity threshold harmonization:Divergent occupational exposure limits across German, Japanese, and South Korean regulatory frameworks force parallel compliance documentation, inflating quality system overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ferro Liquid Display Market |
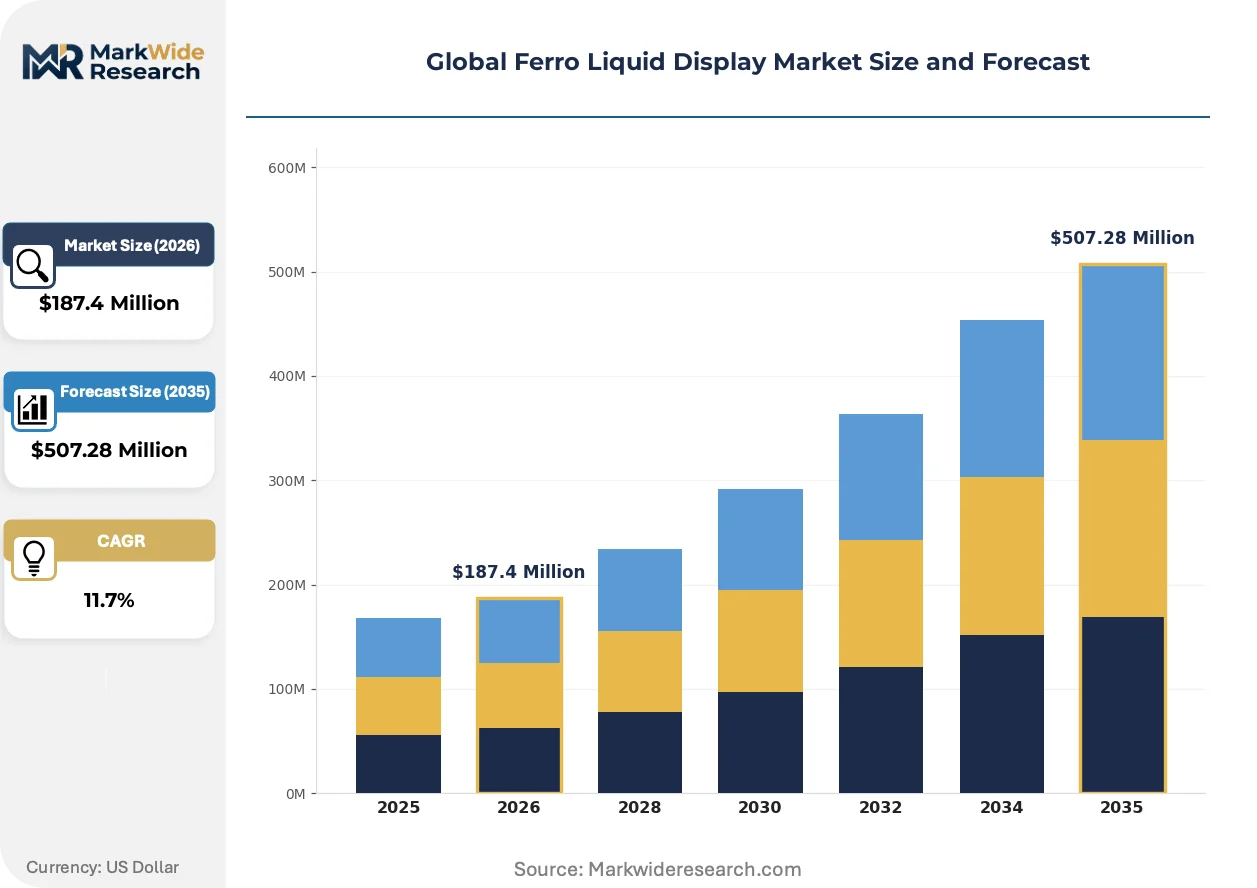
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Sensors, Actuators, Light Sources Application: Consumer Electronics, Automotive Displays, Industrial Equipment, Medical Devices End User: Manufacturers, Retailers, OEMs, End Consumers Technology: LCD, OLED, TFT, E-paper |
| Companies Covered | Samsung Electronics, LG Display, Toshiba Corporation, Fujitsu Limited, NEC Display Solutions, HannStar Display Corporation, Semex, Videocon Industries Limited, AU Optronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ferro Liquid Display Market Emerging Trajectories
Magnetic particle suspension chemistry is undergoing rapid refinement as manufacturers compete to reduce response latency while maintaining optical clarity under thermal cycling stress.
Silica-coated iron oxide nanocrystals with tailored surface charge densities are supplanting uncoated magnetite particles in high-reliability aerospace applications. Defense contractors in the United States are qualifying these encapsulated ferrofluids for heads-up display systems that must operate across negative forty to positive eighty-five Celsius ranges. This material transition is compressing qualification timelines for legacy particle suppliers while opening specification windows for chemical synthesis specialists.
EMA Medical Device Regulation (MDR) Article 10 technical documentation requirements are forcing ferro liquid display manufacturers to maintain electronic systems for post-market surveillance of magnetic nanoparticle leaching rates. Industrial consequence includes mandatory periodic safety update reports for implantable diagnostic interfaces. German notified bodies are now requiring biocompatibility testing under ISO 10993-5 cytotoxicity protocols for all ferrofluid-contacting medical display surfaces.
Hospital procurement departments are consolidating vendor panels for diagnostic imaging equipment, forcing ferro liquid display manufacturers to compete through total-cost-of-ownership frameworks rather than unit pricing. Equipment lessors are displacing direct capital purchases in European radiology departments, compressing upfront margins while extending service revenue streams. This financing pivot is most visible in German university hospital networks, where fifteen-year operational lease structures now dominate MRI-compatible display acquisitions.
Global Ferro Liquid Display Market Segmentation
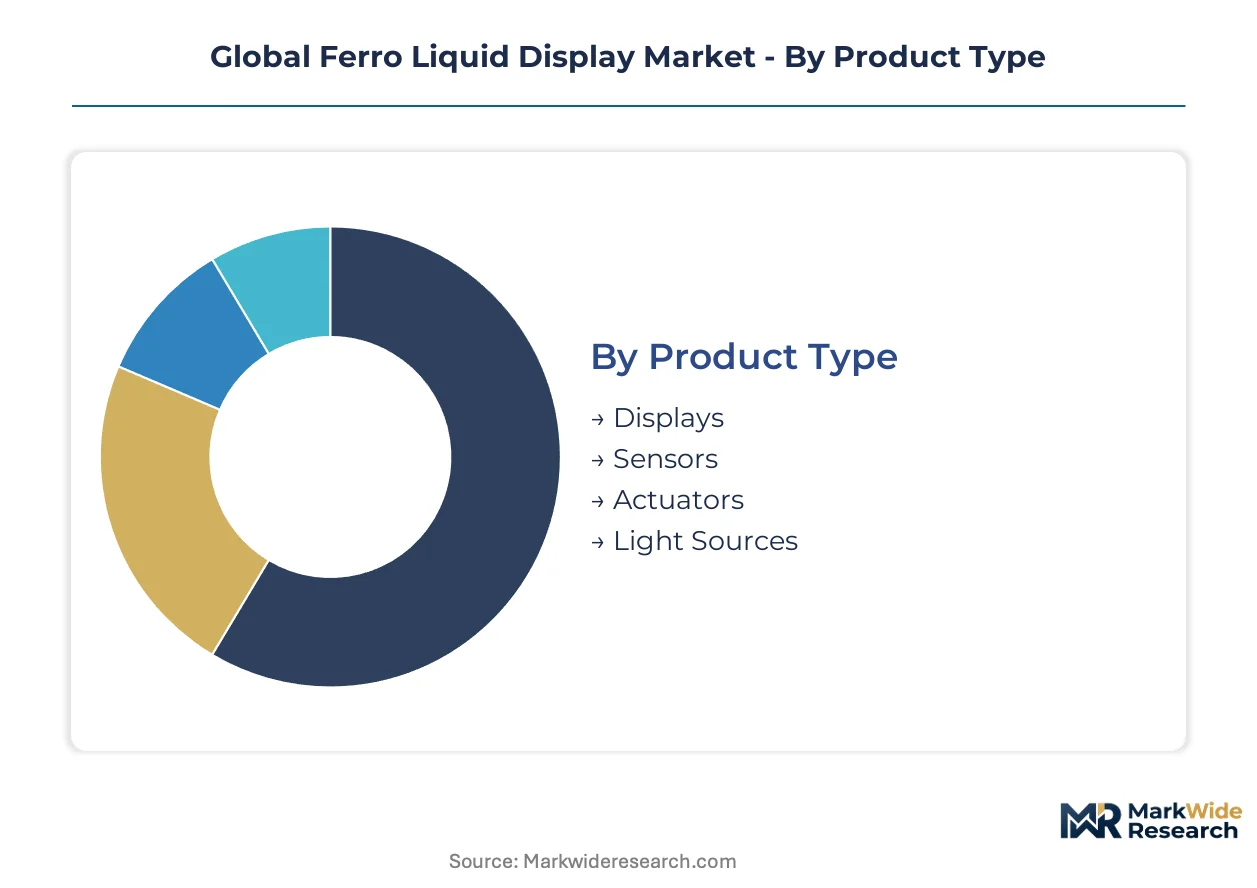
Segmentation in the ferro liquid display market reveals how magnetic nanoparticle suspension technologies align with distinct performance requirements across precision instrumentation sectors. Understanding these divisions exposes where premium pricing power concentrates versus where commoditization pressures dominate.
Product Type:
Displays and Sensors anchor export demand from Japanese and South Korean manufacturing clusters, while Actuators and Light Sources serve more geographically dispersed domestic industrial automation markets.
- Displays:Ferrofluidic cells modulate light transmission through nanoscale magnetic particle suspensions in carrier fluids, achieving sub-ten-millisecond response times without mechanical components. German automotive Tier 1 suppliers and Japanese medical imaging OEMs drive premium demand for these optical systems in heads-up displays and MRI-compatible surgical monitors.
- Sensors:Non-contact position sensing applications exploit magnetic field variations to detect displacement in industrial automation environments. South Korean smart factory deployments and German precision manufacturing clusters are pulling these ferrofluidic cells for real-time feedback loops in robotic assembly systems.
- Actuators:Magnetic field-driven mechanical displacement devices serve aerospace instrumentation retrofit programs and industrial valve control systems.
- Light Sources:Field-modulated illumination systems address specialized medical endoscopy and microscopy applications requiring instantaneous intensity adjustment.
Displays holds the largest share; momentum sits with Sensors.
Application:
Cost tier stratification separates medical and aerospace applications commanding qualification premiums from consumer electronics facing LCD substitution pressure.
- Consumer Electronics:Portable device displays and adaptive optics face margin compression from mature LCD and OLED alternatives, with demand concentrated in mass-market smartphone and tablet manufacturers seeking differentiation through novel form factors.
- Automotive Displays:Heads-up display systems in German premium vehicle platforms and Japanese electric vehicle architectures require millisecond-response optical modulation without mechanical actuators. EU F-Gas Regulation compliance is accelerating ferrofluidic adoption over fluorinated cooling-dependent alternatives.
- Industrial Equipment:Harsh-environment control interfaces and process monitoring displays serve German chemical processing clusters and Japanese semiconductor fabrication facilities.
- Medical Devices:MRI-compatible surgical displays and diagnostic imaging interfaces must satisfy FDA 21 CFR Part 820 and EMA MDR quality system requirements. German university hospital networks now favor fifteen-year operational leases over capital purchases.
Medical Devices commands the highest margins; Automotive Displays is climbing the fastest.
End User:
Volume concentration sits with captive production by integrated display manufacturers, while merchant market sales flow through specialized industrial distributors.
- Manufacturers:Samsung Electronics and LG Display maintain in-house ferrofluidic cell fabrication through captive semiconductor and liquid crystal supply chains, insulating cost structures from nanoparticle supply concentration risks.
- Retailers:Electronics distributors and medical equipment suppliers serve fragmented demand from research laboratories and specialty instrumentation purchasers.
- OEMs:Tier 1 automotive suppliers and medical device contract manufacturers specify ferro liquid display modules for integration into finished diagnostic and vehicular systems.
- End Consumers:Direct procurement remains negligible, limited to specialized research institutions and defense contractors with custom specification authority.
Manufacturers dominates volume; OEMs is gaining share fastest.
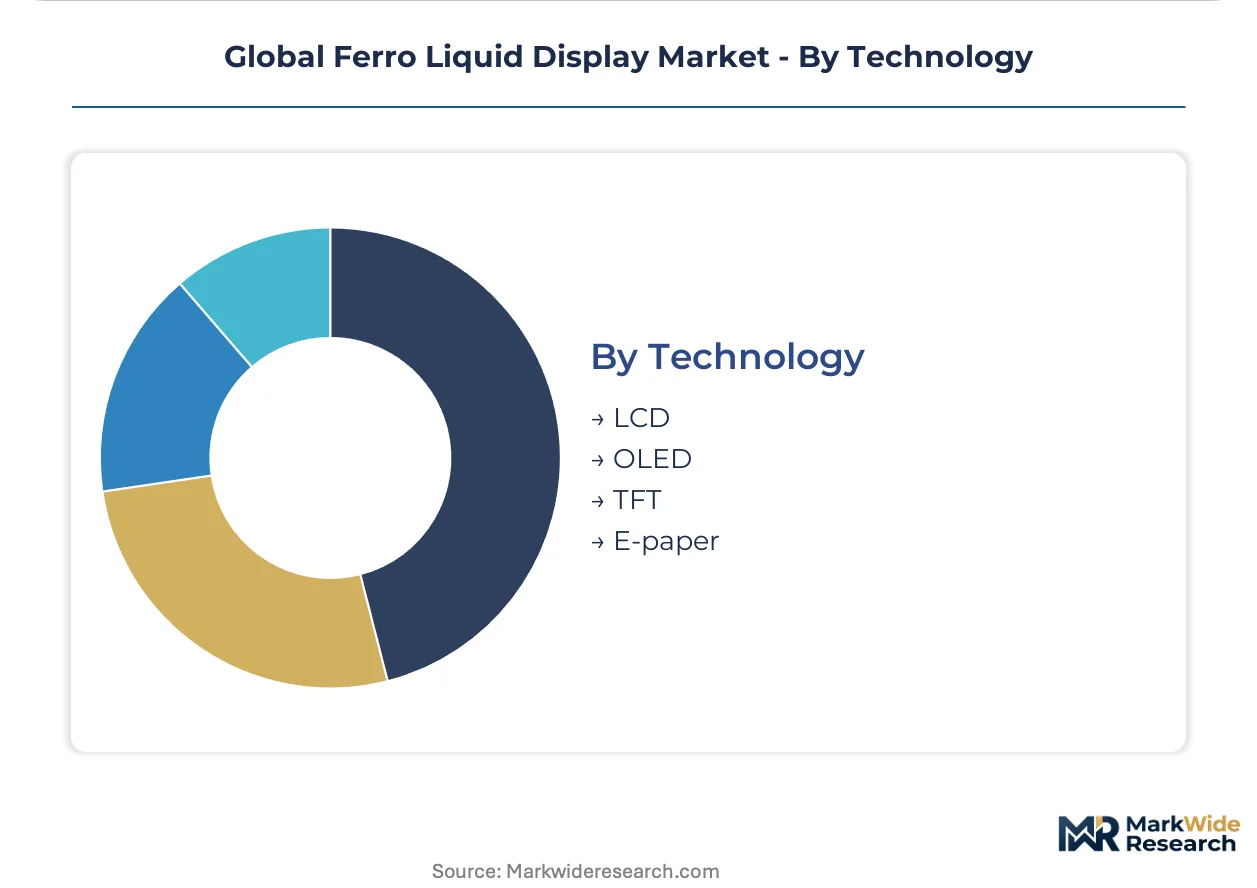
Technology:
Maturity curves diverge sharply, with legacy LCD infrastructure confronting field-modulated ferrofluidic disruption in premium performance tiers.
- LCD:Liquid crystal technologies with ferrofluidic enhancement layers address cost-sensitive industrial applications where response time requirements exceed unmodified LCD capabilities but fall short of full ferro liquid display economics.
- OLED:Organic electroluminescent displays compete directly with ferro liquid systems in medical imaging color fidelity applications, with South Korean panel manufacturers pushing organic alternatives for diagnostic radiology.
- TFT:Thin-film transistor backplanes support active matrix addressing for ferrofluidic cells requiring individual pixel modulation in high-resolution aerospace instrumentation.
- E-paper:Bistable display technologies incorporating ferrofluidic elements target ultra-low-power logistics and retail signage applications.
LCD retains installed base dominance; TFT is expanding most quickly in aerospace qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive Tier 1 suppliers and medical imaging OEMs cluster procurement authority in German, Japanese, and South Korean industrial corridors. This buyer concentration shapes where ferrofluidic cell fabrication capacity expands and where regulatory compliance investments concentrate.
Germany
Automotive heads-up display programs at BMW and Mercedes-Benz pull millisecond-response ferrofluidic optical systems into premium vehicle architectures. The EU F-Gas Regulation phase-down accelerates substitution away from fluorinated cooling-dependent alternatives in precision instrumentation. Stuttgart and Munich industrial clusters host Tier 1 supplier engineering centers specifying magnetic-field-modulated panels.
Japan
METI energy efficiency benchmarks for display component consumption drive adoption of field-modulated panels drawing power only during state transitions. Iron oxide and cobalt ferrite nanocrystal production concentrates in specialty chemical foundries serving captive semiconductor fabricators. Nagoya and Osaka manufacturing corridors anchor industrial-grade ferro liquid module output for harsh-environment applications.
South Korea
Smart factory deployments across Gyeonggi-do and Incheon create pull for non-contact position sensing ferrofluidic cells responding to magnetic field variations below ten milliseconds. MFDS biocompatibility standards for ferrofluid materials open certified-supplier pathways for diagnostic catheter-integrated displays. Samsung Electronics and LG Display maintain in-house ferrofluidic cell fabrication through captive liquid crystal supply chains.
United States
Commercial aviation maintenance programs generate replacement demand for legacy mechanical gauge systems with solid-state ferrofluidic optical modulators. Defense contractors qualify silica-coated iron oxide nanocrystals for heads-up display systems operating across negative forty to positive eighty-five Celsius ranges. Aerospace instrumentation retrofit cycles concentrate engineering activity in Southern California and Texas defense corridors.
United Kingdom
EMA Medical Device Regulation technical documentation requirements force manufacturers to maintain electronic systems for post-market surveillance of magnetic nanoparticle leaching rates. London and Cambridge medical technology clusters drive MRI-compatible surgical display procurement through fifteen-year operational lease structures. British university hospital networks now favor service revenue models over direct capital purchases for diagnostic imaging equipment.
Global Ferro Liquid Display Market Vendor Landscape
Player mix skews toward integrated display manufacturers with captive semiconductor fabrication and liquid crystal supply chains. Tier 1 automotive suppliers and medical device OEMs exert specification authority, compressing margin structures for non-captive module assemblers. Two strategic archetypes dominate: vertically integrated Asian electronics conglomerates controlling nanoparticle-to-panel production, and specialized industrial display houses focusing on harsh-environment certifications. Competitive moves center on cleanroom capacity expansion for ISO 13406-2 medical device qualification and strategic partnerships with aerospace defense contractors.
Among integrated Korean and Japanese fabricators, Samsung Electronics and LG Display occupy positions exemplifying the captive-supply archetype, while Toshiba Corporation anchors the industrial-specialist tier. Samsung Electronics leverages in-house semiconductor fabrication to sustain cost advantages in ferrofluidic cell production. LG Display secures positioning through upstream control over liquid crystal supply chains. Toshiba Corporation concentrates on industrial-grade ferro liquid modules for harsh-environment applications where qualification premiums offset volume constraints.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| Toshiba Corporation |
| Fujitsu Limited |
| NEC Display Solutions |
| HannStar Display Corporation |
| Semex |
| Videocon Industries Limited |
| AU Optronics |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor fabrication capacity in South Korean and Japanese conglomerates compresses cost floors for ferrofluidic cell production while insulating these producers from nanoparticle supply volatility. This scale concentration enables premium pricing in medical imaging applications where ISO 13406-2 certification creates qualification barriers for merchant competitors.
Pricing Analysis
Cost-plus contracts with petrochemical feedstock indexation dominate ferrofluid procurement agreements between Japanese specialty chemical foundries and display module assemblers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13406-2 certified medical tiers from industrial-grade and consumer electronics alternatives. Pricing pressure stems from LCD and OLED substitution in consumer electronics channels where margin compression is most acute. Tier 1 automotive suppliers and medical device OEMs exhibit lowest price sensitivity due to qualification-driven vendor consolidation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German automotive Tier 1 suppliers sourcing ferrofluidic cells. Production of iron oxide and cobalt ferrite nanocrystals concentrates in Japan, South Korea, and Germany, creating geographic clustering around specialty chemical foundries and captive semiconductor fabricators. Synthetic hydrocarbon carrier fluids draw from petrochemical feedstocks anchored in regional refining complexes. Single-source vulnerability for non-captive manufacturers represents the dominant structural risk. Distribution runs through specialized industrial distributors serving medical equipment suppliers and automotive Tier 1 procurement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ferro liquid display market is positioned for cyclical recovery driven by aerospace instrumentation retrofit programs replacing legacy mechanical gauge systems. Defense contractor qualification timelines for silica-coated iron oxide nanocrystals are accelerating demand pull across North American maintenance cycles.
For Market Incumbents: Compound captive supply advantages by deepening in-house nanoparticle synthesis capabilities and expanding cleanroom capacity for ISO 13406-2 medical device certifications. Defend against OLED substitution in diagnostic imaging by anchoring hospital procurement relationships through fifteen-year operational lease structures. Prioritize backward integration into iron oxide nanocrystal production to neutralize Japanese specialty chemical foundry concentration risks.
For New Entrants and Emerging Players: ISO 13406-2 certification fast-tracks through partnerships with German notified bodies offer the most penetrable pathway into MRI-compatible surgical display procurement. Target aerospace instrumentation retrofit programs in the United States where defense contractor qualification windows are opening for silica-coated particle suppliers. Pursue white-label ferrofluidic cell production for industrial automation sensor OEMs in South Korean smart factory deployments as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized industrial display houses with harsh-environment certifications over commodity panel manufacturers facing LCD margin compression. Long-term viability rests on regulatory moats around biocompatibility standards and energy efficiency mandates rather than scale economics alone. Acquisition targets should demonstrate validated cleanroom protocols and existing relationships with German university hospital networks. Monitor Japan METI energy efficiency benchmark revisions as the critical inflection signal for field-modulated panel adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13406-2 Certification Investment | Creates eighteen-to-twenty-four month qualification barriers against merchant competitors in German hospital procurement. |
| Backward Integration into Nanoparticle Synthesis | Neutralizes single-source vulnerability to Japanese iron oxide and cobalt ferrite nanocrystal foundries. |
| Aerospace Defense Contractor Partnership | Opens qualification pathways for silica-coated particles operating across negative forty to positive eighty-five Celsius ranges. |
| Operational Lease Financing Structure | Aligns with German university hospital network procurement shifts away from direct capital purchases. |
| South Korean Smart Factory Channel Development | Captures non-contact position sensing demand from Gyeonggi-do and Incheon industrial automation deployments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, EMA Medical Device Regulation submissions, and METI efficiency benchmark disclosures. Primary interviews engaged ferrofluidic cell engineering directors, Tier 1 automotive supplier procurement managers, hospital biomedical equipment committees, and specialty chemical foundry operations leads. Secondary validation drew from FDA 21 CFR Part 820 quality system documentation, ISO 10993-5 cytotoxicity test reports, and EU F-Gas Regulation phase-down schedules. Bottom-up demand modeling triangulated against top-down industry value chain analysis.
Segmentation dimensions modeled include product type, application, end user, and technology across the projection horizon. The analytical framework incorporated automotive display integration intensity, medical imaging modality expansion rates, and industrial automation sensor densification patterns. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Forecast inputs included EU F-Gas Regulation compliance timelines and Japan METI energy efficiency mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of stable magnetic nanoparticle toxicity threshold harmonization and continued aerospace retrofit program funding; material deviation would warrant model refresh. Specific risk factors encompass RoHS surfactant reformulation delays, carrier fluid petrochemical feedstock volatility, and divergent occupational exposure limit adoption across German, Japanese, and South Korean frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Screenless Display Market
Display Technologies
Global Transparent Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Dot-Matrix LCD Modules Market
Display Technologies
Global Photonic Crystal Displays Market
Display Technologies
Display Glass Substrate Market
Display Technologies
QLED Display Market
Display Technologies
4K Technology Market
Display Technologies
North America Industrial Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
AMOLED Substrate Market
Display Technologies
IGZO Display Market