
 Hafnium Market | 2026-2036
Hafnium Market Size, Share, and Industry Trends Forecast 2026-2036
Hafnium Market Intelligence
The bundling of hafnium with application-specific certification and technical support is pivoting procurement away from purely commodity-based transactions. This shift favors suppliers with deep metallurgical expertise for critical applications. ATI Inc. leverages its integrated capabilities to serve demanding aerospace clients. Framatome Inc. specializes in nuclear-grade material for reactor control rods, while China Nuclear JingHuan Zirconium Industry Co. Ltd. anchors supply within its domestic market.
Hafnium is a silvery-gray transition metal, primarily extracted as a byproduct from zirconium minerals where it occurs at a 50:1 ratio. Its high neutron absorption cross-section and melting point of 2,233 °C make it indispensable for specific industrial uses. The application in nuclear control rods represents a mature, high-value segment. Superalloys for aerospace manufacturers constitute a major source of demand, while high-purity hafnium oxide for semiconductor devices commands premium pricing.
The trade and use of hafnium are influenced by nuclear non-proliferation agreements and national strategic materials policies. In the United States, FAA standards govern its aerospace applications, while in Europe, chemical registration under REACH is mandatory. Chinese GB standards define purity levels for industrial use. Future market dynamics will be determined by the security of zirconium processing supply chains and innovation in advanced reactor technologies.
Market Dynamics
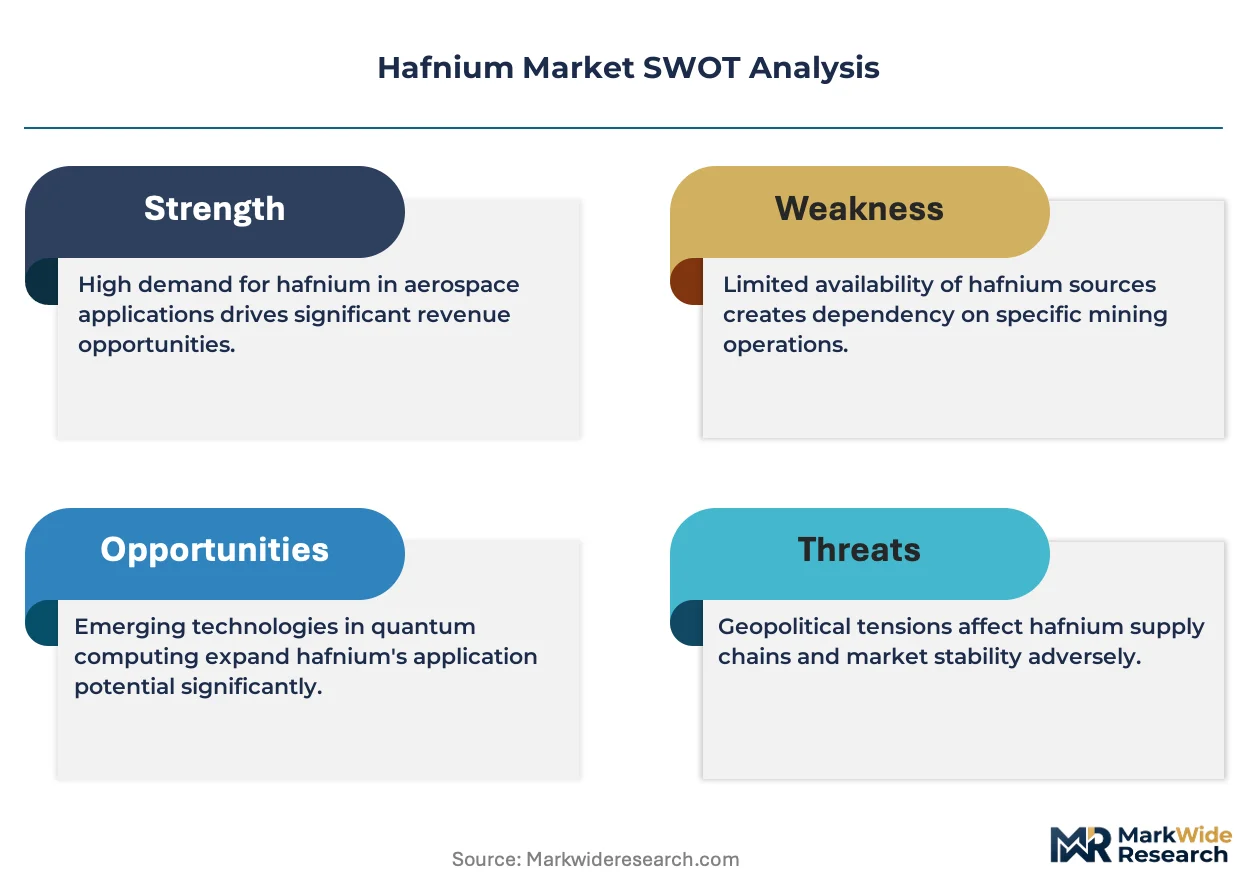
The hafnium market's core dynamic is the tension between its constrained, byproduct-dependent supply from zirconium processing and demand from critical, non-substitutable applications in aerospace and nuclear energy, creating inherent price volatility.
Growth Catalysts
- Advanced Nuclear Reactors:Development of small modular reactors and Generation IV designs, particularly in France and China, provides a significant technology tailwind for hafnium-based control rods.
- Strategic Materials Policies:National initiatives in the United States and China to secure supply chains for defense and semiconductors are directing investment toward critical materials.
- Aerospace Superalloys:The continuous push for higher fuel efficiency in jet engines drives demand for hafnium-bearing nickel-based superalloys for turbine blades.
Market Restraints
- Byproduct Supply Constraint:Production is entirely dependent on zirconium mining, with a natural 50:1 ratio, limiting the ability to scale hafnium output independently.
- Separation Complexity:The chemical similarity between hafnium and zirconium makes their separation a costly, energy-intensive process, acting as a bottleneck on refined supply.
- Nuclear Proliferation Controls:International agreements governing dual-use materials complicate trade flows and add compliance layers for suppliers and users in the nuclear sector.
Strategic Opportunities
- Semiconductor Dielectrics:The use of high-purity hafnium oxide in advanced logic gates presents a high-value opportunity as semiconductor fabrication moves to new transistor architectures.
- Additive Manufacturing:Combining hafnium-containing superalloy powders with 3D printing enables creation of complex, heat-resistant components for next-generation aerospace platforms.
- New Nuclear Programs:Emerging nuclear energy projects in India and the United Kingdom, especially those focused on small modular reactors, represent underpenetrated markets for control rod materials.
Industry Challenges
- Application-Specific Certification:Meeting distinct and rigorous certification requirements for nuclear-grade versus aerospace-grade alloys, such as those from the FAA, is a significant operational hurdle.
- Securing Zirconium Feedstock:Ensuring stable, long-term supply of raw zircon sand is a primary challenge due to the geographic concentration of mining and refining.
- Metallurgical Expertise Scarcity:A shortage of metallurgists with refractory metals expertise hinders new alloy development and the technical support demanded by end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hafnium Market |
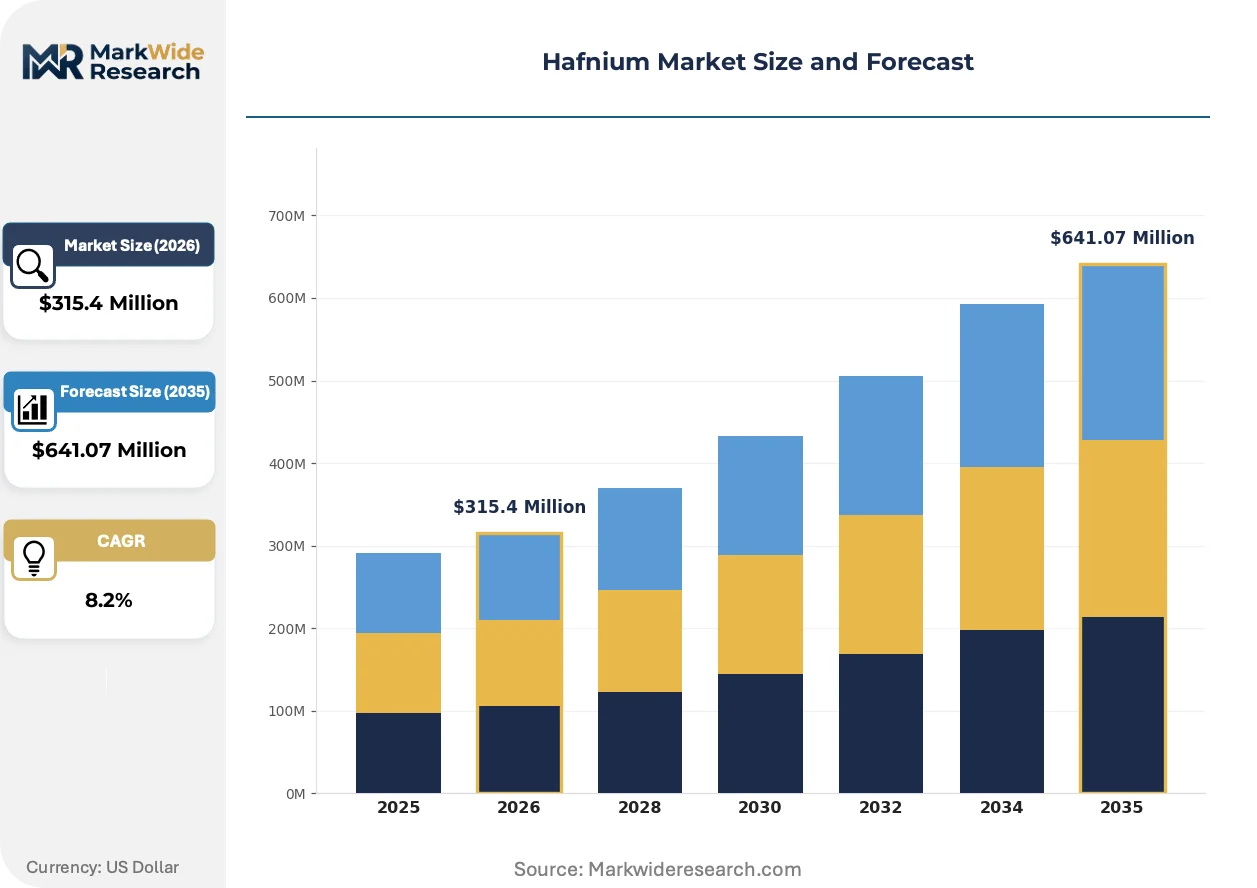
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $641.07 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hafnium Metal, Hafnium Oxide, Hafnium Carbide, Hafnium Nitrate Application: Control Rods, Superalloys, Semiconductor Devices, Nuclear Reactors End User Industry: Aerospace Manufacturers, Electronic Component Makers, Energy Producers, Specialty Chemical Producers Form: Powder, Pellets, Granules, Films |
| Companies Covered | Alkane Resources Ltd., ATI Inc., American Elements, Framatome Inc., China Nuclear JingHuan Zirconium Industry Co. Ltd., Nanjing Youtian Metal Technology Co., Ltd., Neo Performance Materials, Materion Corporation, ACI Alloys Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hafnium Market Strategic Shifts & Innovations
A fundamental re-evaluation of material value is underway, shifting focus from hafnium as a simple commodity to a highly specialized, performance-differentiated material defined by its purity, certification, and application-specific properties.
High-k dielectric materials, primarily hafnium oxide, serve as insulating layers in transistors to prevent current leakage. Leading semiconductor foundries are adopting these materials for advanced logic nodes. The integration of HfO2 in gate-all-around (GAA) designs is electrifying the industry’s roadmap toward sub-3-nanometer chips, enabling unprecedented processing power.
Europe's REACH regulation mandates comprehensive data on the properties and safe use of chemical substances. This policy imposes significant compliance burdens on hafnium producers and importers, requiring extensive documentation for ECHA. The nuclear and specialty chemical sectors are most impacted, redesigning supply chains to meet reporting obligations.
End-users in critical industries are moving toward integrated supply contracts bundling the physical metal with technical support and guaranteed certifications. This model displaces transactional purchasing from the spot market, which cannot provide required material consistency. This preference is most visible within the aerospace engine supply chain in North America and Europe.
Hafnium Market Segmentation
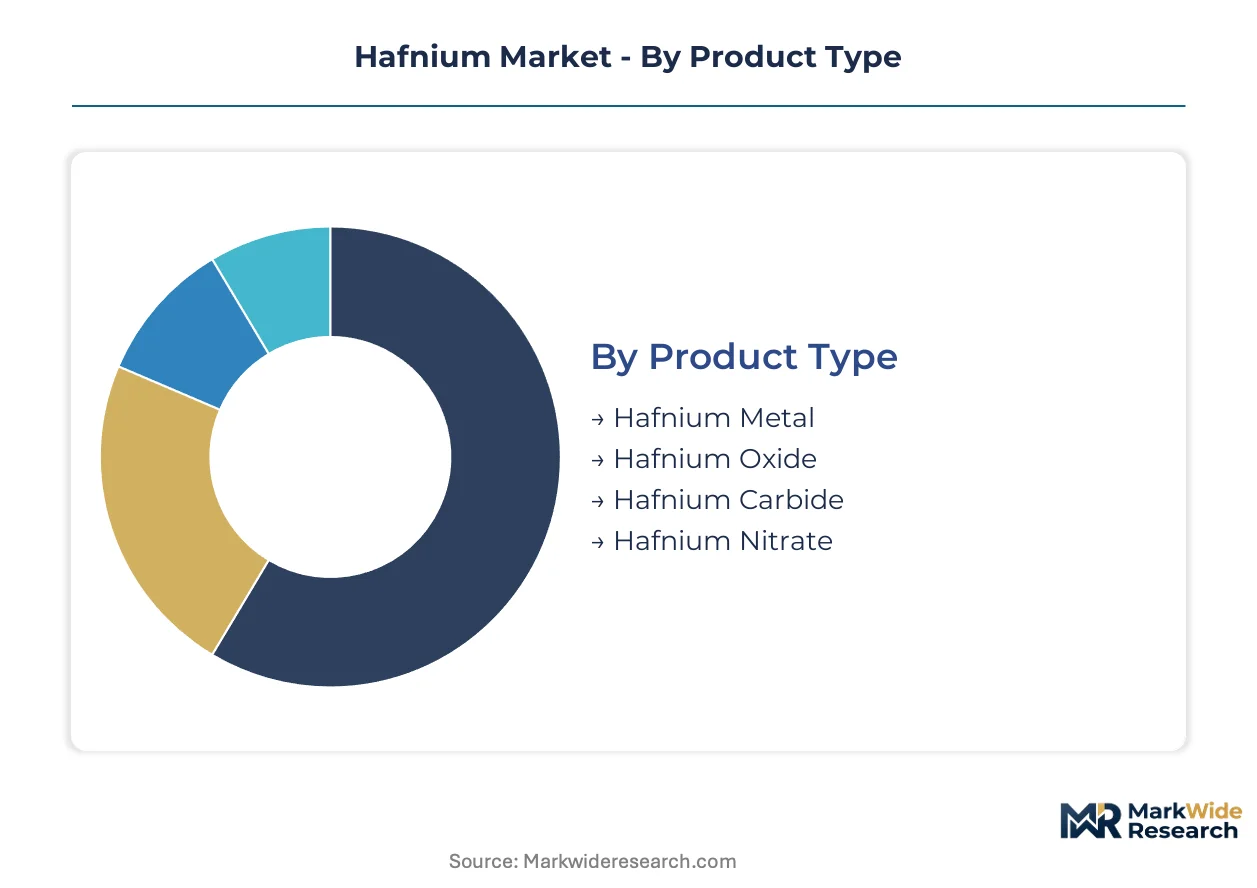
The hafnium market's structural dynamics are best understood through its segmented value chain. Each segment reflects unique material properties, processing demands, and end-use requirements for this critical transition metal. Understanding these distinctions clarifies the varied pricing and supply chain configurations.
Product Type:
The hafnium market delineates its product offerings across a spectrum from high-volume, standard-grade materials to specialized, ultra-high-purity forms commanding significant premiums.
- Hafnium Metal:This silvery-gray transition metal is prized for its high melting point and exceptional neutron absorption capabilities in specific applications. Demand concentrates among aerospace manufacturers in the United States seeking lightweight, heat-resistant superalloys for jet engines.
- Hafnium Oxide:A white ceramic compound, primarily utilized as a high-k dielectric material in advanced semiconductor devices due to its superior insulating properties. Electronic component makers in China drive demand for its use in sub-3-nanometer logic gates.
- Hafnium Carbide:An extremely hard, refractory ceramic, finding niche applications in cutting tools, protective coatings, and high-temperature composites.
- Hafnium Nitrate:This soluble hafnium salt serves as a precursor in chemical vapor deposition processes for synthesizing thin films and other hafnium compounds.
Today's leader: Hafnium Metal. Tomorrow's challenger: Hafnium Oxide.
Application:
Hafnium applications span from mature, established industrial uses to emerging, high-value technological frontiers, each with distinct cost structures.
- Superalloys:Hafnium-containing nickel-based superalloys enhance high-temperature strength, creep resistance, and oxidation protection in critical aerospace components like turbine blades. Aerospace manufacturers in France continuously push demand for these materials to improve engine efficiency.
- Semiconductor Devices:High-purity hafnium oxide functions as a critical high-k dielectric in advanced logic chips, reducing current leakage and enabling smaller transistor geometries. Electronic component makers in South Korea intensify demand for its use in gate-all-around designs.
- Control Rods:Utilized in nuclear reactors, hafnium control rods absorb excess neutrons, effectively regulating the nuclear fission process due to the element's high neutron absorption cross-section.
- Nuclear Reactors:This segment encompasses the broader use of hafnium in reactor components beyond just control rods, including structural elements and fuel cladding materials.
Superalloys represents the largest volume segment, while Semiconductor Devices are expanding most quickly.
End User Industry:
The hafnium market's end-user industries exhibit varied levels of supply chain integration and procurement strategies, influencing material specifications.
- Aerospace Manufacturers:These companies require hafnium for superalloys used in jet engines and structural components, demanding rigorous certification and metallurgical support. Major manufacturers in the United Kingdom prioritize long-term, integrated supply contracts.
- Energy Producers:Nuclear energy producers utilize hafnium for control rods and other reactor components, emphasizing material purity and compliance with nuclear non-proliferation agreements. State-backed entities in India are focusing on new reactor builds.
- Electronic Component Makers:These firms consume high-purity hafnium oxide for advanced logic gates in microprocessors and memory chips, driving demand for ultra-pure materials.
- Specialty Chemical Producers:Involved in synthesizing various hafnium compounds for diverse industrial applications, including catalysts, ceramics, and protective coatings.
Aerospace Manufacturers represent a mature, high-value segment, whereas Electronic Component Makers are driving new growth.
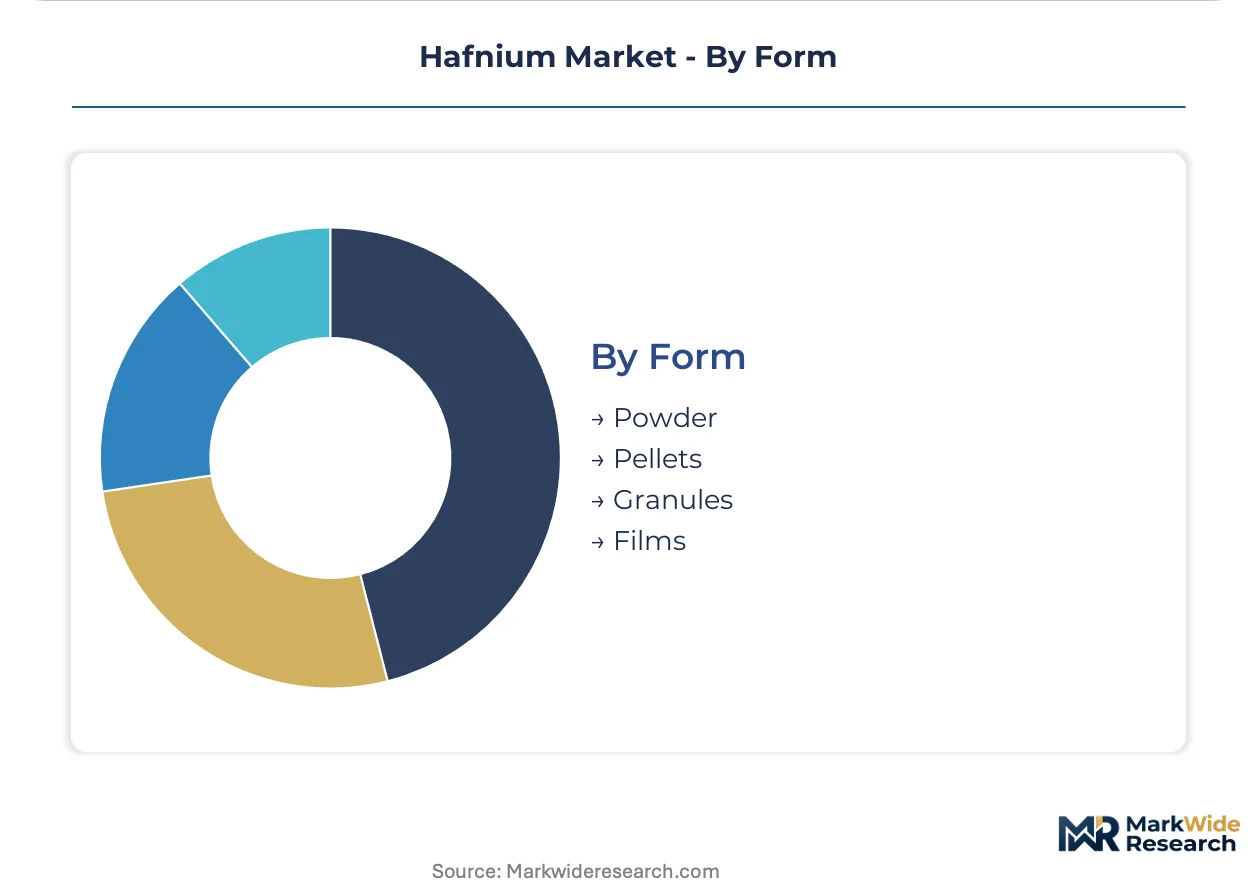
Form:
Hafnium's physical forms reflect distinct processing requirements and impact the final material's performance and associated profit margins.
- Powder:Fine hafnium powder is critical for additive manufacturing of complex superalloy components and high-purity ceramic applications. Manufacturers in Germany increasingly adopt powder for 3D printing aerospace parts.
- Films:Ultra-thin hafnium films, often hafnium oxide, are deposited via atomic layer deposition for semiconductor dielectrics and optical coatings. Semiconductor foundries in Taiwan are expanding their use of these films for advanced nodes.
- Pellets:Compacted hafnium pellets are typically used as raw material for vacuum arc remelting processes or as sputtering targets for thin film deposition.
- Granules:Irregularly shaped hafnium granules serve as alloying additions in various metallurgical processes or as feedstock for specialized melting operations.
Powder forms enable advanced manufacturing techniques, while Films are essential for cutting-edge semiconductor fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hafnium market's origins are deeply intertwined with nuclear energy and high-performance aerospace alloys. Early applications in nuclear control rods established its strategic importance. Today, demand centers in key industrial economies driving power generation and advanced manufacturing.
United States
United States aerospace manufacturers drive significant demand for hafnium metal in high-performance superalloys. FAA standards rigorously govern its use in critical aircraft components. Research hubs in Ohio and Connecticut actively develop next-generation hafnium-containing materials.
France
France's nuclear energy sector, led by Framatome, significantly consumes hafnium for control rods in advanced reactor designs. REACH regulations mandate comprehensive data for chemical substances. Its nuclear facilities in regions like Normandy remain central to hafnium deployment.
China
China's rapid expansion in nuclear power and semiconductor fabrication fuels substantial hafnium demand. GB standards define purity levels for industrial use. Major semiconductor manufacturing centers such as Shanghai are critical for hafnium oxide consumption.
South Korea
South Korea's electronic component makers intensify demand for high-purity hafnium oxide in advanced logic gates. The country's strong semiconductor industry benefits from government support. Major fabrication plants in Gyeonggi Province are crucial for integrating hafnium oxide.
India
India's emerging nuclear energy projects, particularly small modular reactors, create new demand for hafnium control rods. BIS standards ensure material quality for various industrial applications. Nuclear power complexes in states like Tamil Nadu are key sites for future hafnium deployment.
Hafnium Market Key Industry Players
Premium-margin players sit above commodity-margin players across the hafnium market's value chain, differentiated by their metallurgical expertise. The competitive landscape is tiered, ranging from vertically integrated specialists to volume-focused commodity producers. Strategic archetypes include those offering application-specific certification and others prioritizing feedstock security. Companies increasingly pursue capacity expansion and strategic partnerships to secure supply.
Specialists in critical applications, ATI Inc. exemplifies an integrated approach for demanding aerospace clients, emphasizing advanced metallurgical capabilities. Framatome Inc. occupies a position as a key supplier of nuclear-grade material for reactor control rods, reflecting its deep expertise in energy sector requirements. Meanwhile, China Nuclear JingHuan Zirconium Industry Co. Ltd. anchors supply within its domestic market, leveraging its extensive zirconium processing capabilities. These entities represent distinct strategies for value creation, ranging from high-value, certified products to securing national supply chains for strategic materials. Their operational models underscore the market's differentiation based on technical support and application-specific performance.
| Leading Market Players |
|---|
| Alkane Resources Ltd. |
| ATI Inc. |
| American Elements |
| Framatome Inc. |
| China Nuclear JingHuan Zirconium Industry Co. Ltd. |
| Nanjing Youtian Metal Technology Co., Ltd. |
| Neo Performance Materials |
| Materion Corporation |
| ACI Alloys Inc. |
| Others |
Cost & Logistics Intelligence
Europe's REACH regulation, a named environmental mandate, gates qualified hafnium supply, creating premium-tier pricing access for compliant materials. This regulatory framework significantly influences material specifications for nuclear and aerospace applications globally.
Pricing Analysis
Contract-based long-term offtake agreements define hafnium pricing for critical applications. Price differentiation hinges on application-specific certification levels, such as FAA standards for aerospace, and the provision of deep metallurgical technical support. Pricing pressure stems from the high energy costs associated with hafnium-zirconium separation, impacting commodity-grade material. Electronic component makers are highly price-sensitive for high-purity hafnium oxide, while aerospace manufacturers tolerate higher costs for certified superalloys.
Supply Chain Analysis
Single-source vulnerability sits with zirconium processing facilities, particularly in China, given hafnium's byproduct nature. Supply chains draw from zirconium minerals primarily in Australia and South Africa, with refining concentrated in China and France. The chemical similarity between hafnium and zirconium poses a structural risk, limiting independent hafnium output scaling. Distribution runs through a mix of integrated producers directly serving major aerospace and nuclear OEMs, alongside specialty chemical distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hafnium market is a late-cycle quality story, driven by a demand-shift toward ultra-high-purity hafnium oxide for advanced semiconductor applications. This necessitates specialized processing and stringent quality control from suppliers.
For Market Incumbents:Deepen metallurgical expertise and invest in advanced separation technologies to mitigate the byproduct supply constraint. Consolidate smaller processing operations to achieve economies of scale against the threat of rising energy costs. Expand application-specific certification capabilities for both nuclear and aerospace clients. Secure long-term zircon sand feedstock contracts to stabilize input costs.
For New Entrants and Emerging Players:Online B2B marketplaces offer a channel to penetrate niche markets for hafnium carbide and hafnium nitrate, bypassing established supply chains. Target underpenetrated markets in India and the United Kingdom for new nuclear programs, focusing on small modular reactor control rod materials. Develop specialized hafnium powder for additive manufacturing, offering a go-to-market angle through technical collaboration with 3D printing service bureaus.
For Investors and Strategic Acquirers:Roll-up economics work for specialty materials processors because of the fragmented nature of downstream applications and the high barriers to entry for purification. Long-term viability hinges on securing access to stable zirconium feedstock and proprietary separation technologies over the next decade. Target acquisition archetypes include mid-sized refiners with established certification pathways or R&D firms specializing in advanced hafnium compounds. The signal to watch is successful commercialization of new reactor designs, particularly SMRs, which will drive significant demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ensures supply stability for growing aerospace and semiconductor demand. |
| R&D in Advanced Separation | Addresses the fundamental byproduct supply constraint for hafnium. |
| Strategic Partnerships | Secures feedstock access and diversifies downstream application reach. |
| Certification Investment | Meets rigorous quality requirements for nuclear and aerospace end-users. |
| Green Manufacturing Transition | Aligns with global sustainability mandates and reduces operational costs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary data validation. Interviews engaged aerospace procurement managers, nuclear facility engineers, semiconductor R&D leads, and specialty chemical producers. Secondary sources included national geological surveys, trade association reports, and regulatory filings like ECHA REACH documentation. This approach ensured bottom-up market sizing and top-down validation of demand drivers.
Segment-weighting across product type, application, end-user industry, and physical form defined the analytical framework over the projection horizon. Historical compound annual growth rates were derived from past market performance trends and adjusted for future technological shifts. Industry-specific inputs included planned nuclear reactor deployments in France and India, alongside semiconductor fabrication capacity expansions in South Korea and China.
The model assumes a particular technology adoption path; alternative pathways for advanced nuclear reactor designs or semiconductor architectures would alter the outlook. Forecasts reflect assumptions regarding zirconium supply stability and the evolution of non-proliferation agreements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Europium Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Gallium Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Silicon Tetrachloride Market