
 Sapphire Substrate Market | 2026-2036
Sapphire Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Sapphire Substrate Market Outlook
ISO 9001 and IATF 16949 qualification cycles is reorganizing supplier tiers in sapphire substrate manufacturing, raising barriers for uncertified entrants. Kyocera Corporation leverages its vertically integrated ceramic-to-sapphire pipeline to control wafer quality from powder to polish. Monocrystal sustains cost leadership through captive energy supply at its Ukrainian production complex. Saint-Gobain competes on optical-grade precision, dominating specialty plate applications for aerospace windows.
Sapphire substrate consists of single-crystal aluminum oxide (Al₂O₃) grown via the Kyropoulos or edge-defined film-fed growth (EFG) method, typically achieving Mohs hardness of 9 and thermal conductivity near 35 W/m·K at room temperature. Manufacturers produce these boules primarily as mechanical supports for gallium nitride epitaxy in solid-state lighting and power electronics. Single crystal wafers command premium positioning in LED and RF device applications where lattice matching to GaN determines yield. Polycrystalline forms occupy cost-sensitive optical windows and industrial wear components. Wafer-form substrates concentrate margin pools in diameters exceeding six inches as micro-LED fabs scale.
REACH compliance in Europe restricts chromium and cobalt process additives in sapphire polishing slurries, redirecting formulation R&D toward cerium oxide alternatives. China's GB standards and MIIT directives mandate domestic sourcing ratios for defense-grade sapphire in infrared domes and transparent armor. The EU F-Gas Regulation phases down hydrofluorocarbon coolants used in crystal growth furnaces, pressuring European producers to retrofit thermal management systems. Stakeholders must track how qualification timelines for automotive-grade sapphire extend as IATF audits tighten traceability requirements for supply chain resilience.
Market Dynamics
Micro-LED display commercialization is compressing substrate qualification timelines as Seoul and Gumi-based fabs demand larger-diameter wafers with atomic-level surface uniformity, forcing upstream crystal growers to retrofit Kyropoulos furnaces for 8-inch boule production.
Growth Catalysts
- Dual carbon goals:China's MIIT directives enforce energy-efficiency benchmarks that favor sapphire over alternative substrates in high-brightness LED applications, redirecting foundry investment toward domestic boule capacity.
- GaN epitaxy expansion:RF power device manufacturers in defense and telecommunications sectors require lattice-matched single-crystal supports, pulling volume from Kyocera's integrated ceramic-to-sapphire pipeline.
- EFG method refinement:Edge-defined film-fed growth automation reduces kerf loss during wafering, lowering unit economics for polycrystalline optical window producers serving aerospace transparency programs.
Market Restraints
- Energy cost volatility:Ukrainian captive power advantages at Monocrystal's complex face geopolitical disruption, exposing cost structures in European supply chains to electricity price spikes.
- Raw material concentration:High-purity aluminum oxide feedstock production clusters in China's Henan and Shandong provinces, creating single-source dependency for non-integrated substrate vendors.
- Substitute substrate advancement:Silicon carbide and gallium oxide wafers encroach on sapphire's position in power electronics where thermal conductivity requirements exceed 35 W/m·K.
Strategic Opportunities
- Underpenetrated infrared optics:India's defense modernization programs lack domestic sapphire dome suppliers, creating import substitution potential for qualified manufacturers meeting BIS specifications.
- F-Gas retrofit demand:EU F-Gas Regulation phase-down mandates furnace coolant conversion, generating equipment upgrade revenue for thermal management system providers serving European crystal growers.
- Automotive HUD convergence:Windshield-integrated head-up display projects combine sapphire waveguide layers with augmented reality optics, opening new specification tiers beyond traditional LED substrates.
Industry Challenges
- IATF 16949 timeline compression:Automotive-grade sapphire qualification now requires 18-24 month traceability audits, extending cash conversion cycles for suppliers targeting Tier 1 display integrators.
- Polishing chemistry reconfiguration:REACH restrictions on chromium and cobalt slurry additives force immediate formulation shifts to cerium oxide, disrupting established process yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sapphire Substrate Market |
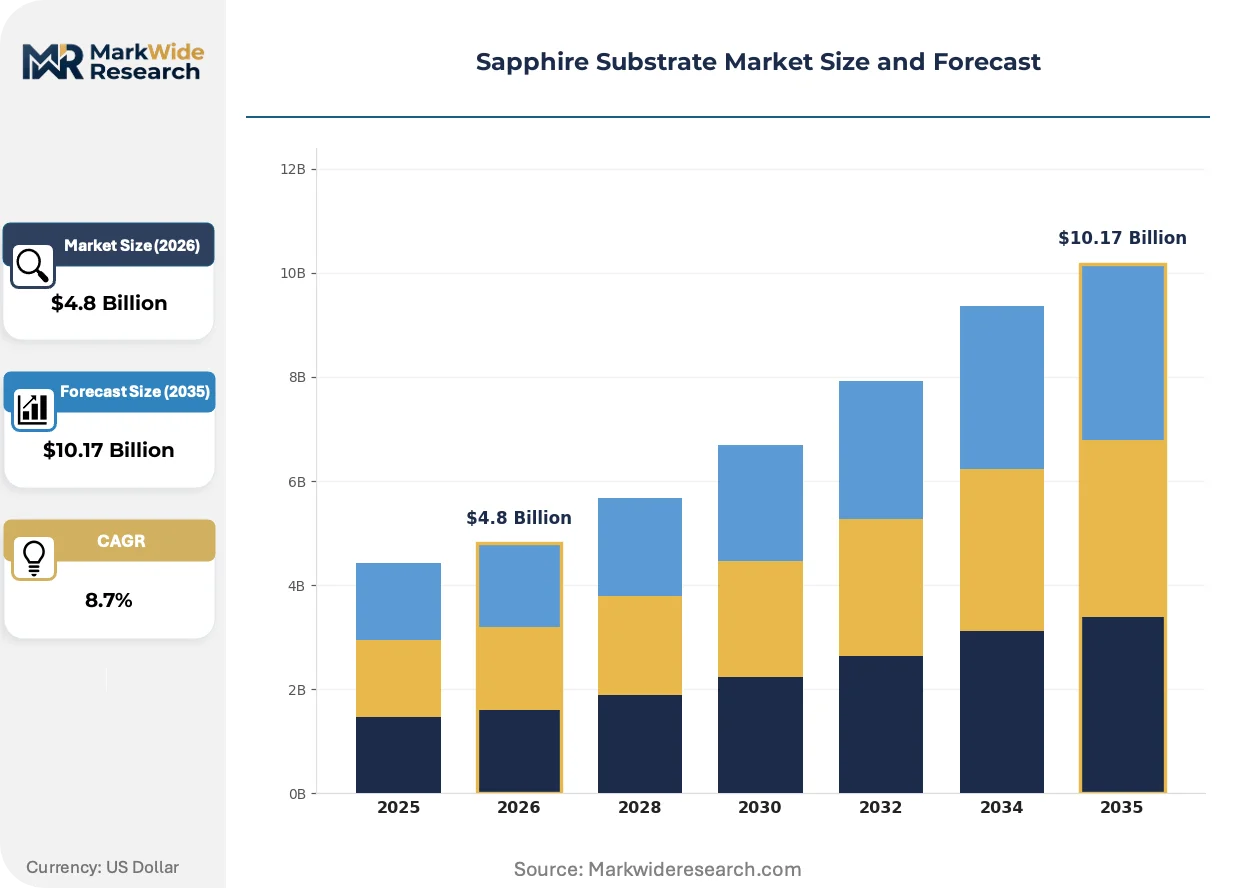
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Polycrystalline, Amorphous, Epitaxial Application: LEDs, RF Devices, Laser Diodes, Optical Windows End User: Electronics, Telecommunications, Aerospace, Defense Form: Wafer, Substrate, Thin Film, Plate |
| Companies Covered | Kyocera Corporation, Rubicon Technology, Monocrystal, Saint-Gobain, Iljin Display Co. Ltd., Meller Optics, Inc., CoorsTek, Cryscore Optoelectronic Limited, Precision Micro-Optics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sapphire Substrate Market Strategic Shifts
Process automation and alternative growth methods are fragmenting traditional substrate economics, separating premium single-crystal specifications from commoditized optical grades while regulatory chemistry bans force immediate capital redeployment.
Micro-LED epitaxy-ready wafers is decomposing the historical premium attached to smaller-diameter LED substrates as display fabs consolidate procurement around 6-inch and 8-inch formats. Samsung Display and related Seoul-cluster manufacturers now specify atomic-step surface morphology that legacy 2-inch and 4-inch production lines cannot achieve. This specification compression is decomposing margin pools across the mid-tier substrate vendor base, concentrating volume with furnace operators capable of Kyropoulos scaling.
EU F-Gas Regulation phase-down mandates are forcing coolant conversion in crystal growth thermal management systems, pressuring Saint-Gobain and European competitors to retrofit or replace hydrofluorocarbon-dependent furnaces. The regulation's 2030 reduction targets compress capital planning horizons. Specialty plate producers serving aerospace transparency programs face the steepest compliance costs given their lower volume throughput relative to LED substrate specialists.
Direct mill relationships are displacing traditional distributor networks for high-volume micro-LED substrate procurement as Seoul and Gumi-based fabs consolidate supplier panels. Long-term supply agreements now specify furnace-level traceability and energy-source documentation. South Korea's display cluster exhibits the most pronounced channel compression, with Samsung Display and LG Display procurement teams mandating quarterly ESG audits alongside IATF certification.
Sapphire Substrate Market Segmentation
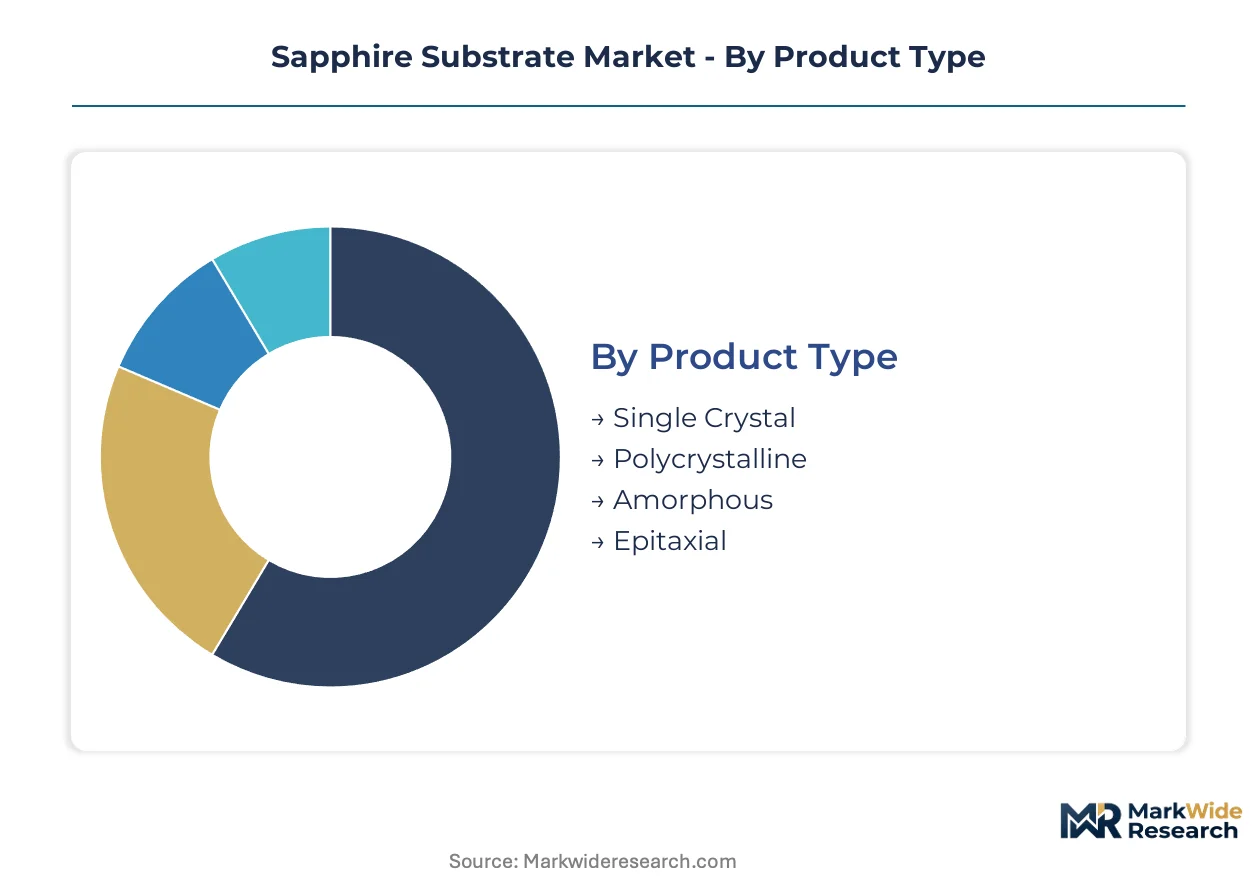
Sapphire substrate procurement fragments across crystal structure, device application, and dimensional form. Each dimension carries distinct qualification barriers and margin profiles that determine supplier competitiveness.
Product Type:
Substitution pressure from silicon carbide and gallium oxide wafers concentrates most intensely on polycrystalline grades where thermal conductivity thresholds matter less.
- Single Crystal:Kyropoulos-grown boules deliver Mohs hardness of 9 and thermal conductivity near 35 W/m·K. Micro-LED fabs in Seoul and Gumi now demand 6-inch and 8-inch formats with atomic-step surface morphology that legacy production lines cannot achieve.
- Polycrystalline:EFG-method material serves cost-sensitive optical windows and industrial wear components. Aerospace transparency programs in France and Germany source these grades for cockpit canopy applications where optical-grade precision is secondary to fracture toughness.
- Amorphous:Non-crystalline aluminum oxide deposits serve specialized coating substrates and temporary carrier wafers.
- Epitaxial:GaN-ready surfaces command premium positioning in RF power devices for telecommunications infrastructure.
Single crystal anchors the volume base while epitaxial grades gain share at the steepest rate as RF device manufacturers consolidate procurement.
Application:
End-use diversification spreads revenue concentration across illumination, communications, and defense systems with divergent certification timelines.
- LEDs:Solid-state lighting and micro-LED displays pull the majority of wafer volume. China's MIIT energy-efficiency mandates favor sapphire over alternatives in high-brightness applications.
- RF Devices:Lattice-matched single-crystal supports enable gallium nitride epitaxy for defense and telecommunications power amplifiers. IATF 16949 qualification cycles now extend to 18-24 months for automotive-grade specifications.
- Laser Diodes:Optical-grade sapphire provides thermal management and mechanical stability for high-power laser systems.
- Optical Windows:Polycrystalline forms dominate aerospace transparency and industrial viewport applications.
LEDs generate the largest revenue pool while RF devices are expanding most quickly as 5G and radar systems scale deployment.
End User:
Customer-type segmentation determines pricing power through qualification intensity and contract duration.
- Electronics:Display manufacturers and LED packagers concentrate procurement in South Korea's Seoul-Gumi corridor with quarterly ESG audit requirements.
- Telecommunications:Base station and satellite communication equipment vendors specify RF-grade single-crystal substrates with documented furnace-level traceability.
- Aerospace:Transparency programs for cockpit canopies and sensor windows demand optical-grade precision from Saint-Gobain and European specialists.
- Defense:Infrared dome and transparent armor applications face China's GB standards mandating domestic sourcing ratios.
Electronics commands the highest volume throughput while defense contracts carry the longest visibility horizons.
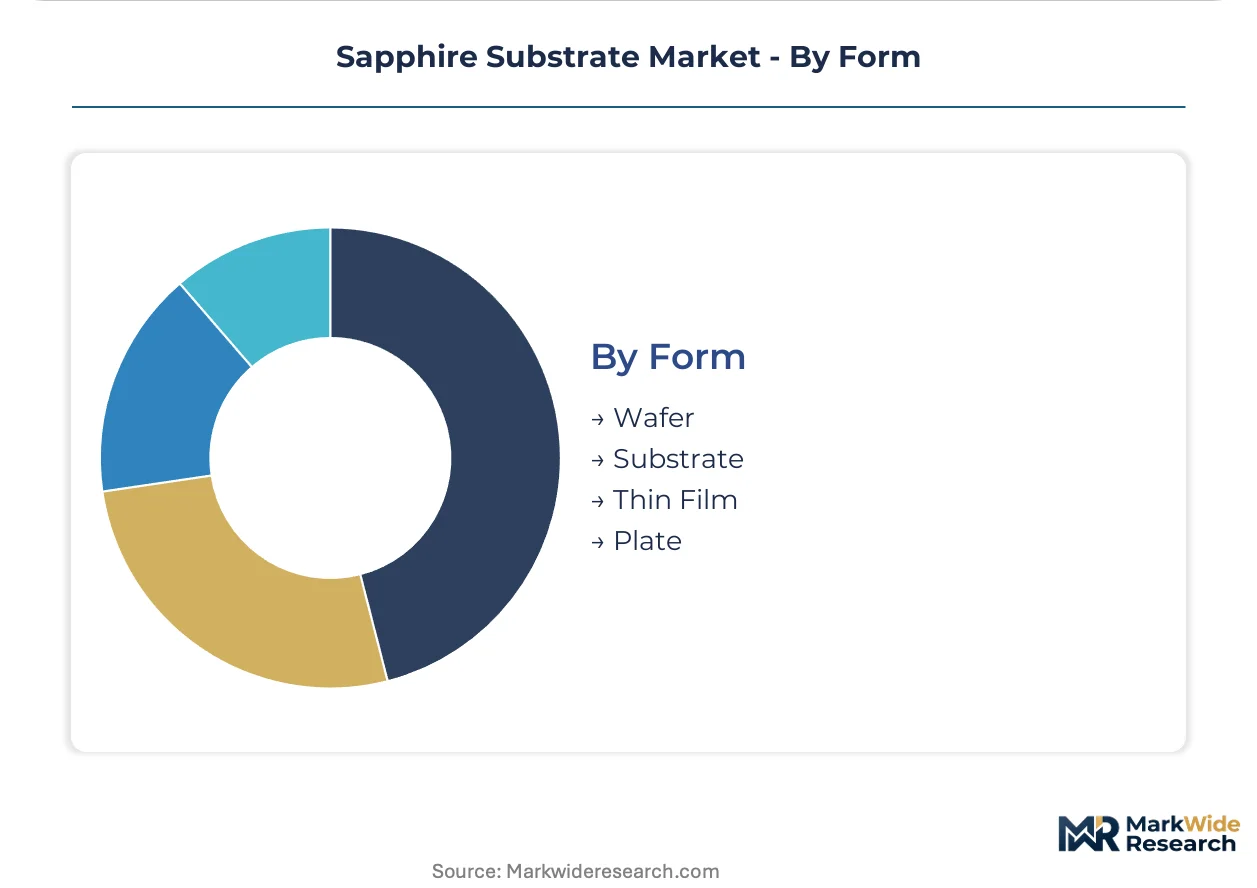
Form:
Dimensional format determines process compatibility and margin capture across epitaxy-ready and mechanical applications.
- Wafer:Diameters exceeding six inches concentrate margin pools as micro-LED fabs scale. EFG automation reduces kerf loss during wafering.
- Substrate:Mechanical supports for GaN epitaxy in solid-state lighting and power electronics represent the baseline commercial form.
- Thin Film:Sub-micron depositions serve specialized optical coating and flexible electronics applications.
- Plate:Specialty plate producers face steep EU F-Gas Regulation compliance costs given lower volume throughput relative to LED substrate specialists.
Wafer formats dominate procurement value while thin film structures are climbing the fastest as flexible and wearable devices emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display manufacturers and LED packagers concentrate procurement across East Asian production clusters, with South Korean fabs driving specification compression toward larger-diameter formats. Energy-efficiency mandates and defense localization programs reshape sourcing patterns in China and India respectively.
China
MIIT energy-efficiency benchmarks favor sapphire substrates in high-brightness LED applications, redirecting foundry investment toward domestic boule capacity. Dual carbon goals enforce stricter power consumption standards across crystal growth operations. Henan and Shandong provinces cluster high-purity aluminum oxide feedstock production, creating concentrated supply dependencies for non-integrated vendors.
South Korea
Samsung Display and LG Display procurement teams mandate quarterly ESG audits alongside IATF certification for substrate suppliers. The Seoul-Gumi corridor compresses supplier panels as micro-LED fabs consolidate procurement around 6-inch and 8-inch wafer specifications. Atomic-step surface morphology requirements now exclude legacy 2-inch and 4-inch production lines from qualification.
Japan
METI directives support domestic production of wide-bandgap semiconductor materials including lattice-matched single-crystal substrates for RF power devices. Kyocera Corporation leverages vertically integrated ceramic-to-sapphire pipelines to control wafer quality from powder to polish. Nagoya and Osaka industrial zones maintain precision manufacturing capabilities for optical-grade specifications.
United States
Defense and telecommunications RF device manufacturers require documented furnace-level traceability for gallium nitride epitaxy supports. FAA transparency standards for aerospace applications sustain demand for specialty plate producers serving cockpit canopy programs. Arizona and California host precision optics fabricators supplying infrared dome and sensor window applications.
India
BIS specifications for defense-grade sapphire create import substitution opportunities as modernization programs expand. The country's national defense procurement guidelines increasingly mandate domestic sourcing ratios for transparent armor and infrared optical components. Gujarat and Tamil Nadu industrial corridors attract substrate qualification investments targeting aerospace and defense contract visibility.
Sapphire Substrate Market Competitive Environment
Player mix skews toward integrated ceramic specialists and captive-energy producers with furnace-level cost control. Market structure exhibits moderate concentration where qualification barriers separate certified suppliers from commodity-grade entrants. Two strategic archetypes dominate: vertically integrated material science conglomerates controlling upstream feedstock, and regional specialists leveraging geographic proximity to display clusters. Competitive moves center on furnace retrofitting for larger-diameter boule production and backward integration into high-purity aluminum oxide refining.
Among Japanese material science conglomerates, Kyocera Corporation anchors the integrated-manufacturing archetype through in-house control of ceramic-to-sapphire pipelines. Ukrainian producer Monocrystal exemplifies the captive-energy model with electricity cost advantages at its production complex. French specialist Saint-Gobain occupies a position in optical-grade precision segments serving aerospace transparency programs. These three companies represent distinct competitive vectors: upstream integration, energy-cost leadership, and specialty-grade differentiation.
| Leading Market Players |
|---|
| Kyocera Corporation |
| Rubicon Technology |
| Monocrystal |
| Saint-Gobain |
| Iljin Display Co. Ltd. |
| Meller Optics, Inc. |
| CoorsTek |
| Cryscore Optoelectronic Limited |
| Precision Micro-Optics Inc. |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen-month qualification timelines for IATF 16949 certification concentrate pricing power with furnace operators capable of atomic-step surface morphology, while Kyocera's ceramic-to-sapphire pipeline and Monocrystal's captive energy complex anchor cost structures at opposite ends of the supplier hierarchy.
Pricing Analysis
Long-term offtake contracts indexed to high-purity aluminum oxide feedstock and electricity tariffs dominate procurement between Seoul-Gumi display fabs and qualified growers. Pricing stratifies across epitaxial-grade single crystal, standard LED substrate, and polycrystalline optical window tiers, with certification level and furnace traceability documentation commanding widening premiums. Cost compression in mid-diameter legacy formats intensifies as micro-LED fabs consolidate procurement around 6-inch and 8-inch specifications. LED packagers exhibit highest price sensitivity given wafer volume exposure, while defense infrared dome programs show lowest sensitivity due to BIS qualification barriers.
Supply Chain Analysis
Ninety-day inventory cycles for high-purity alumina feedstock expose non-integrated substrate vendors to Henan and Shandong supply dependencies. Crystal growth concentrates in China, Ukraine, and Japan, with boule slicing and polishing clustering in South Korea and Germany. Supply chains rest on single-source high-purity aluminum oxide refining, Kyropoulos furnace components, and cerium oxide polishing slurries. Geopolitical disruption at Monocrystal's Ukrainian complex presents acute single-source vulnerability for European LED substrate supply. Distribution runs through direct mill relationships displacing traditional distributor networks for high-volume micro-LED procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sapphire substrate incumbents face sustained substitution pressure from silicon carbide and gallium oxide wafers in power electronics where thermal conductivity thresholds exceed 35 W/m·K, demanding defensive positioning around lattice-matched GaN epitaxy applications where sapphire maintains irreplaceable optical transparency.
For Market Incumbents: Fortify furnace-level traceability documentation and IATF 16949 certification depth to defend Seoul-Gumi supplier panel positions against emerging Chinese boule capacity. Prioritize backward integration into high-purity aluminum oxide refining to offset feedstock concentration in Henan and Shandong provinces. Accelerate Kyropoulos furnace retrofitting for 8-inch boule production before specification compression excludes legacy capacity. For New Entrants and Emerging Players: Lead with India's defense modernization programs as the most penetrable geography, where BIS specifications for infrared domes and transparent armor create import substitution windows absent domestic qualified suppliers. Target Gujarat and Tamil Nadu industrial corridors with qualification investments. Pursue joint venture structures with established European optical-grade specialists to bypass 18-24 month IATF audit timelines. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because qualification barriers and furnace retrofit capital requirements will compress the vendor base to integrated ceramic specialists and captive-energy producers. Monitor EU F-Gas Regulation compliance cost dispersion as the inflection signal separating retrofit-capable incumbents from stranded specialty plate producers.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Retrofit for 8-inch Boule Production | Seoul-Gumi micro-LED fabs now specify atomic-step surface morphology unobtainable from legacy lines. |
| Backward Integration into Alumina Refining | Henan and Shandong feedstock concentration creates margin vulnerability for non-integrated crystal growers. |
| IATF 16949 Certification Acceleration | Automotive HUD convergence extends qualification timelines to 24 months for Tier 1 display integrators. |
| Cerium Oxide Slurry Formulation Shift | REACH chromium and cobalt restrictions force immediate process chemistry reconfiguration disrupting yields. |
| Direct Mill Relationship Consolidation | Samsung Display and LG Display procurement teams now mandate quarterly ESG audits alongside furnace traceability. |
Study Parameters
The analysis maps single-crystal, polycrystalline, epitaxial, and amorphous substrate grades, each validated through primary interviews with crystal growth furnace operators, LED fab procurement managers, defense aerospace qualification engineers, and polishing process chemists, combined with secondary triangulation across MIIT directive filings, EU F-Gas Regulation implementation schedules, BIS specification documents, and customs trade data for high-purity aluminum oxide, employing bottom-up wafer volume builds and top-down market sizing consistency checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across crystal structure, device application, dimensional form, and end-user qualification intensity. CAGRs derived from installed furnace capacity trajectories, micro-LED fab capex disclosures, and GaN epitaxy expansion curves in RF power devices, cross-referenced with energy-efficiency mandate enforcement timelines in China and defense procurement visibility windows in India.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules, China's dual carbon enforcement, and India's BIS defense localization mandates; material policy shifts or geopolitical disruption at Ukrainian captive energy facilities would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Silicon Metal Market