
 Photonic Crystals Market | 2026-2036
Photonic Crystals Market Size, Share, and Industry Trends Forecast 2026-2036
Photonic Crystals Market Intelligence
A divergence in fabrication scale and capital investment is bifurcating the competitive landscape. Large-scale producers like Corning Incorporated leverage automated manufacturing processes for high-volume products such as optical fibers. In contrast, NKT Photonics A/S specializes in high-performance photonic crystal fibers for niche scientific and industrial applications. IPG Photonics Corporation controls a significant share of the high-power fiber laser market by integrating its own proprietary crystal technologies.
Photonic crystals are periodic optical nanostructures engineered to affect the motion of photons in a manner similar to how semiconductor crystals affect electrons. Their defining characteristic is the photonic bandgap, a specific frequency range where photons are forbidden from propagating. This property enables precise control of light in devices for optical filtering, waveguiding, and signal processing. Photonic crystal fibers represent a mature product segment, while 3D photonic crystals are an area of active research for next-generation optical computing.
Material composition is constrained by global regulations like the EU's RoHS directive, which limits the use of hazardous substances in electronics. In the United States, performance and reliability standards for defense and aerospace applications are defined by military specifications. Concurrently, China's MIIT influences telecommunication equipment standards, indirectly shaping component requirements for 5G and future networks. Future market access depends on navigating these varied material and performance mandates while scaling production.
Market Dynamics
The market's structure is defined by a divergence in fabrication scale and capital investment. This split separates high-volume, automated production of mature products from specialized, high-performance manufacturing for niche scientific and industrial applications, shaping all competitive and pricing dynamics.
Growth Catalysts
- Nanofabrication Advances:Progress in techniques like electron-beam lithography and two-photon polymerization enables the creation of more complex and efficient crystal structures, opening new applications in optical computing and advanced sensors.
- Telecommunications Expansion:The build-out of 5G and future high-speed optical networks, particularly influenced by standards from bodies like China's MIIT, creates sustained demand for photonic crystal fibers and passive optical components.
- Electronics Manufacturing Hubs:Demand for photonic components is intensifying within the consumer electronics and display sectors, concentrated in manufacturing centers across Japan, South Korea, and Taiwan.
Market Restraints
- High Fabrication Costs:The capital expenditure required for advanced nanofabrication equipment, such as deep UV and electron-beam lithography systems, presents a significant barrier to entry and constrains capacity expansion.
- Material Composition Rules:Global regulations, notably the EU's RoHS directive, restrict the use of certain hazardous materials common in optical and electronic components, forcing costly reformulation and requalification cycles.
- 3D Crystal Scalability:The difficulty in fabricating large-volume, defect-free 3D photonic crystals remains a major technical hurdle, limiting their application to research and small-scale, high-value devices.
Strategic Opportunities
- Medical Biosensing:The unique light-manipulating properties of photonic crystals create opportunities in developing highly sensitive lab-on-a-chip devices and point-of-care diagnostics for the medical sector.
- On-Chip Optical Interconnects:Integrating photonic crystal waveguides with silicon photonics platforms offers a pathway to overcome data bottlenecks in high-performance computing and data centers.
- Defense and Aerospace Modernization:Demand for lightweight, EMI-resistant communication and sensing systems in aerospace and defense applications provides a market for ruggedized, high-performance photonic crystal components.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers and physicists with cross-disciplinary expertise in quantum optics, material science, and semiconductor fabrication processes impedes research and product development cycles.
- Lack of Design Standardization:The absence of universally accepted design rules and performance testing protocols for novel photonic crystal structures hinders interoperability and slows adoption by system integrators.
- Complex IP Landscape:Overlapping patents related to crystal structures, fabrication methods, and material compositions create a complex intellectual property environment that can lead to licensing disputes and deter new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photonic Crystals Market |
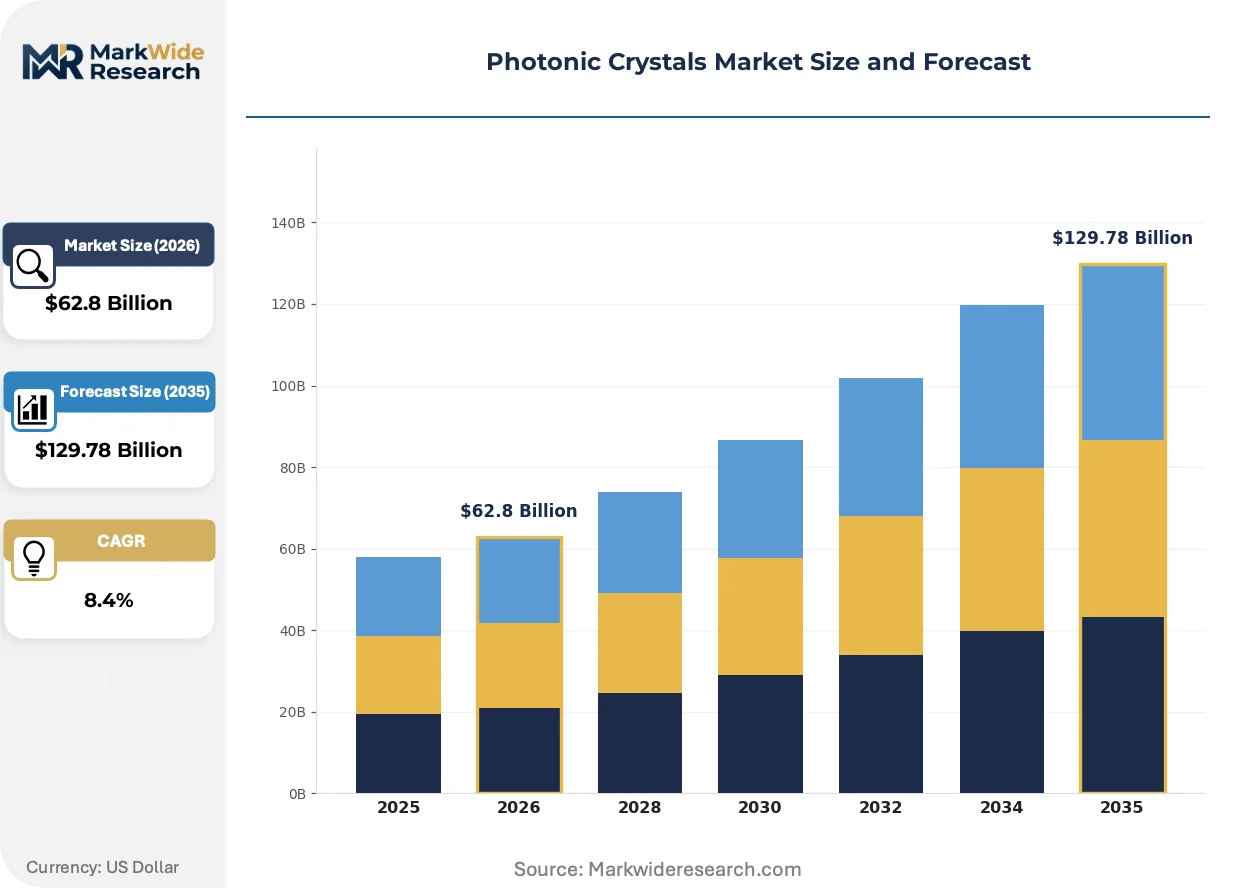
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $129.78 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Photonic Crystals, 3D Photonic Crystals, Photonic Crystal Fibers, Photonic Crystal Sensors Application: Optical Communication, Sensing, Imaging, Energy Harvesting End User: Telecommunications, Consumer Electronics, Defense, Healthcare Technology: Fabrication Techniques, Optical Devices, Nonlinear Optics, Quantum Technologies |
| Companies Covered | Corning Incorporated, NKT Photonics A/S, Opalux Inc., Photonic Lattice Inc., GLOphotonics SAS, IPG Photonics Corporation, Furukawa Electric Co., Ltd., Gooch & Housego PLC, Advance Photonic Crystals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photonic Crystals Market Strategic Shifts & Innovations
Advancements in material science and fabrication precision are enabling the integration of photonic functionalities into smaller, more complex systems. This drives a shift from discrete components to highly integrated photonic circuits, altering both product design and end-market applications.
Advanced Fabrication Methods
Two-photon polymerization is a direct laser writing technique used to create intricate three-dimensional nanostructures with high precision. Research institutions and specialty device manufacturers are adopting this method for rapid prototyping and the production of niche components. This technology is miniaturizing optical elements like micro-lenses, filters, and waveguides for direct integration into compact sensors and lab-on-a-chip systems.
Regulatory Performance Mandates
Military specifications (MIL-SPEC) in the United States establish rigorous performance and reliability requirements for components intended for defense and aerospace systems. These standards necessitate extensive environmental stress screening and operational testing, which increases development costs and lengthens qualification timelines. The aerospace electronics segment is most affected, compelling manufacturers to invest heavily in ruggedization and materials validation.
Customization in Procurement
A move toward application-specific photonic devices is altering purchasing patterns in scientific and industrial markets. End-users are transitioning from buying standard, off-the-shelf components to engaging in co-development partnerships with manufacturers for custom-designed photonic crystals. This trend is most visible in the high-power fiber laser and quantum computing sectors, where performance is optimized for a single, specific function.
Photonic Crystals Market Segmentation
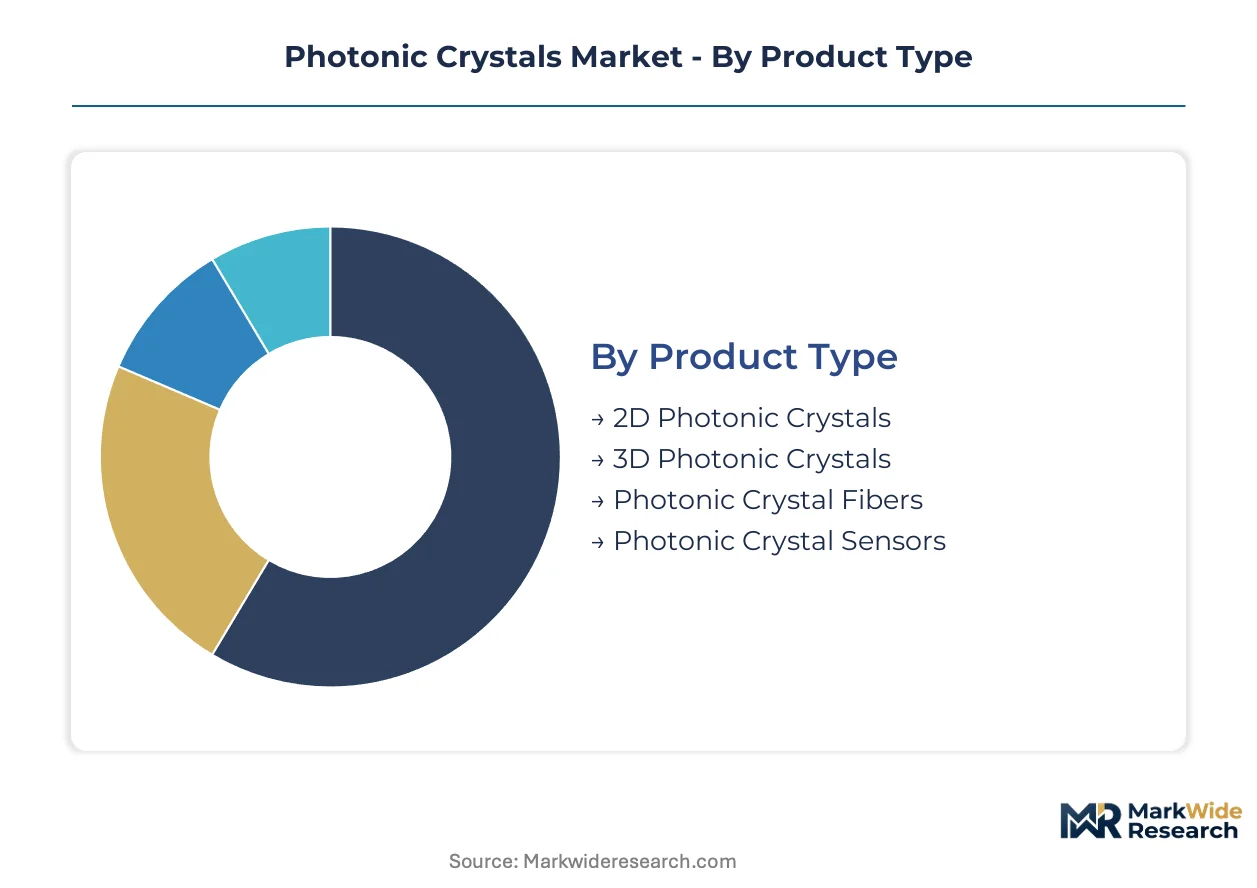
The Photonic Crystals market segmentation provides a granular view of product evolution, application diversity, and end-user adoption patterns. Understanding these segments is critical for identifying specific growth pockets and assessing the varying technological maturity across the industry. This detailed breakdown highlights areas of established demand versus emerging opportunities.
Product Type:
Margin pools within the product type segment often correlate with fabrication complexity and performance specialization, favoring advanced structures and high-precision components.
- Photonic Crystal Fibers:These optical fibers incorporate a microstructured cladding with a periodic arrangement of air holes, guiding light through either modified total internal reflection or photonic bandgap effects. Demand is strong in telecommunications for high-speed data transmission and in industrial lasers for power delivery, particularly from manufacturers in Japan and South Korea.
- 3D Photonic Crystals:Engineered with a periodic refractive index in all three spatial dimensions, these structures offer precise light manipulation capabilities, including full photonic bandgaps. Research and development efforts, especially in academic institutions and defense sectors, drive their application in next-generation optical computing and advanced sensing platforms.
- 2D Photonic Crystals:These structures feature a periodic refractive index in two dimensions, typically fabricated on a planar waveguide, enabling light confinement and guiding within the plane. Their primary use is in integrated optical circuits for compact filtering and routing functions.
- Photonic Crystal Sensors:Utilizing the sensitivity of photonic bandgap properties to changes in the surrounding environment, these devices detect variations in refractive index, temperature, or chemical composition. Medical biosensing and environmental monitoring are key areas for these specialized components.
The dominant share belongs to Photonic Crystal Fibers, while 3D Photonic Crystals are closing the gap fastest.
Application:
The volume of photonic crystal deployment varies significantly across applications, with established uses driving substantial unit demand and newer applications showing rapid uptake.
- Optical Communication:Photonic crystals enable high-bandwidth data transmission and signal processing by providing precise control over light propagation in waveguides, filters, and switches. The build-out of 5G infrastructure and data centers, especially influenced by China's MIIT standards, drives extensive component demand.
- Sensing:Photonic crystal structures enhance sensitivity and selectivity in various sensor types by exploiting their unique light-matter interaction properties. Medical diagnostics and environmental monitoring systems leverage these components for improved detection limits and miniaturization, particularly in point-of-care devices.
- Imaging:These components are integrated into advanced imaging systems to improve resolution, contrast, and spectral filtering capabilities, particularly in microscopy and spectroscopy. Specialized scientific instruments and industrial inspection systems incorporate photonic crystals for enhanced performance.
- Energy Harvesting:Photonic crystals are explored for their ability to control light absorption and emission, optimizing efficiency in solar cells and thermal emitters. Research efforts focus on enhancing light trapping and spectral selectivity in renewable energy technologies.
Optical Communication holds the largest market segment, with Sensing expanding most quickly.
End User:
The maturity of end-user industries significantly influences the adoption rate and customization requirements for photonic crystal components, from high-volume standardized products to niche, high-performance solutions.
- Telecommunications:This sector utilizes photonic crystals extensively for optical fibers, switches, and modulators to support high-speed data networks and internet infrastructure. Major telecom equipment manufacturers in Japan and South Korea integrate these components into their advanced systems.
- Healthcare:The medical industry employs photonic crystals in biosensors, diagnostic devices, and advanced imaging equipment for improved sensitivity and miniaturization. Lab-on-a-chip platforms and point-of-care diagnostics represent significant areas of innovation.
- Consumer Electronics:Photonic crystals find applications in displays, optical sensors, and compact cameras within consumer devices, enhancing performance and enabling smaller form factors. Electronics manufacturing hubs in Taiwan and South Korea are crucial demand centers.
- Defense:The defense sector integrates photonic crystals into lightweight, EMI-resistant communication systems, advanced sensors, and laser technologies for military applications. US military specifications (MIL-SPEC) dictate stringent performance and reliability standards for these components.
Telecommunications represents the largest end-user segment, with Healthcare climbing the fastest.
Technology:
Supply concentration in photonic crystal technology is often tied to specialized intellectual property and advanced manufacturing capabilities, particularly for novel fabrication methods and quantum applications.
- Fabrication Techniques:This segment includes methods like electron-beam lithography, two-photon polymerization, and nanoimprint lithography, which are essential for creating the intricate structures of photonic crystals. Advances in these techniques enable the production of more complex and efficient optical components.
- Quantum Technologies:Photonic crystals are critical enablers for quantum computing and quantum communication by precisely controlling photon interactions and entanglement. Research institutions and specialized startups are driving innovation in this high-value, emerging field.
- Optical Devices:This category encompasses various components such as waveguides, filters, resonators, and couplers that utilize photonic crystal principles for enhanced light manipulation. These devices are fundamental to integrated photonics platforms.
- Nonlinear Optics:Photonic crystals can enhance nonlinear optical effects, leading to applications in frequency conversion, optical switching, and ultra-fast light modulation. Specialized research focuses on creating materials with tailored nonlinear responses.
Fabrication Techniques holds the largest segment, while Quantum Technologies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand elasticity for photonic crystals varies significantly by application and regional maturity. High-volume consumer electronics and telecommunications components in Asia often exhibit greater price sensitivity. Conversely, specialized defense and medical devices in Western markets prioritize performance and reliability over cost.
United States
Demand for photonic crystals in the United States stems from defense and aerospace modernization efforts, alongside emerging opportunities in medical biosensing. US military specifications (MIL-SPEC) define stringent performance and reliability standards for components in these critical applications. Silicon Valley drives research in integrated photonics platforms for on-chip optical interconnects and advanced sensor development.
China
China's market for photonic crystals is propelled by the extensive build-out of 5G infrastructure and future high-speed optical networks. The Ministry of Industry and Information Technology (MIIT) influences telecommunication equipment standards, directly shaping component requirements for domestic and international suppliers. Shenzhen focuses on mass production of photonic components for consumer electronics and telecom equipment, catering to vast domestic demand.
Japan
Japan exhibits strong demand for photonic crystals in high-speed data transmission for telecommunications and advanced display technologies. The Ministry of Economy, Trade and Industry (METI) promotes research and development in advanced materials and nanofabrication techniques to maintain technological leadership. Tokyo's research institutions and manufacturers collaborate on next-generation optical computing and quantum technologies, fostering innovation.
South Korea
Consumer electronics displays and high-performance optical fibers for telecommunications drive the South Korean photonic crystals market. Standards from the Ministry of Food and Drug Safety (MFDS) impact medical device integration of photonic crystal sensors, particularly for diagnostic applications. Gyeonggi Province houses major electronics manufacturers integrating photonic components into compact devices and advanced optical systems.
Germany
Germany's market for photonic crystals is characterized by demand from industrial lasers, scientific instruments, and advanced sensing applications. The EU's RoHS directive constrains material composition in electronic and optical components, necessitating compliant formulations. Jena's optics cluster specializes in high-precision photonic crystal fibers for niche scientific and industrial uses, emphasizing performance and reliability.
Photonic Crystals Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the photonic crystals market. The competitive landscape bifurcates between large-scale producers focusing on automated, high-volume manufacturing and specialized firms catering to niche, high-performance applications. This structure fosters strategic partnerships for technology co-development and targeted capacity expansion in advanced fabrication. Portfolio diversification into new application areas also marks a significant competitive move.
At the scale-driven end, Corning Incorporated exemplifies large-scale producers leveraging automated manufacturing processes for high-volume products such as optical fibers, primarily serving the telecommunications sector. This archetype prioritizes cost-efficiency and extensive distribution networks. NKT Photonics A/S, a European specialist, represents firms concentrating on high-performance photonic crystal fibers designed for niche scientific and industrial applications, where bespoke solutions and precision are paramount. IPG Photonics Corporation anchors a significant share of the high-power fiber laser market, integrating proprietary crystal technologies into its offerings and reflecting a strategy of deep technological specialization.
| Leading Market Players |
|---|
| Corning Incorporated |
| NKT Photonics A/S |
| Opalux Inc. |
| Photonic Lattice Inc. |
| GLOphotonics SAS |
| IPG Photonics Corporation |
| Furukawa Electric Co., Ltd. |
| Gooch & Housego PLC |
| Advance Photonic Crystals LLC |
| Others |
Cost & Logistics Intelligence
High capital expenditure for advanced nanofabrication equipment, such as deep UV and electron-beam lithography systems, shapes the supply concentration and sets a high price floor for complex photonic components. This investment barrier limits the number of players capable of producing intricate crystal structures, influencing market access. The bifurcation between high-volume and niche production further defines pricing and supply dynamics.
Pricing Analysis
After-sales technical support for custom-designed photonic crystals drives significant lifetime value in specialized applications. The dominant pricing model is hybrid, combining contract-based long-term agreements for high-volume optical fibers with project-based or value-based structures for niche, high-performance components. Price differentiation stems from fabrication complexity and specific regulatory compliance, such as US military specifications. Pricing pressure intensifies due to high material reformulation costs mandated by directives like the EU's RoHS. Telecommunications and consumer electronics buyers exhibit higher price sensitivity compared to defense and medical sectors, which prioritize performance.
Supply Chain Analysis
Access to specialized nanofabrication equipment represents a critical chokepoint for the supply chain, limiting overall production capacity. Geographic supply concentration centers in electronics manufacturing hubs like Japan, South Korea, and Taiwan, alongside specialized optics clusters in Germany. The market relies heavily on high-purity silica and various semiconductor materials as core inputs. Single-source vulnerability for specific advanced materials or proprietary fabrication techniques presents a structural supply chain risk. Distribution runs through direct sales channels for custom, high-value components and through established distributor networks for high-volume standard products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a significant service-attach opportunity, with co-development partnerships and post-sales integration support expanding faster than hardware component sales. This trend reflects the increasing complexity and customization required for advanced photonic crystal applications.
For Market Incumbents:
Secure proprietary intellectual property related to advanced fabrication methods, particularly for 3D photonic crystals, to counter emerging specialized entrants. Invest in standardizing design rules for photonic crystal components to accelerate broader adoption across system integrators. Expand automated manufacturing capacity in strategic regions like Japan and South Korea to leverage existing electronics manufacturing infrastructure. Address the talent scarcity by funding university research programs in quantum optics and material science, building a future workforce.
For New Entrants and Emerging Players:
The lack of universally accepted design rules and performance testing protocols presents a service-layer gap where incumbents under-serve. Target specialized, high-value applications such as medical biosensing and on-chip optical interconnects, where performance outweighs cost considerations. The 3D photonic crystal segment, despite its scalability challenges, offers a penetrable research-driven market. A go-to-market angle focused on co-development partnerships with academic institutions and defense contractors can establish early market presence and build credibility.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors specialized firms with strong IP in next-generation applications like quantum technologies and 3D photonic crystals. The long-term viability of this market over a 5-10 year window depends on breakthroughs in scalable manufacturing for complex structures and broader integration into silicon photonics. Acquisition targets should include companies possessing proprietary nanofabrication expertise or unique material compositions. A signal to watch is the successful commercialization of defect-free 3D photonic crystals for high-volume applications beyond research.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire specialized nanofabrication IP | This strengthens proprietary technology portfolios against new market entrants. |
| Invest in design standardization efforts | Such efforts accelerate broader adoption by simplifying system integration for end-users. |
| Expand automated manufacturing capacity in Asia | This leverages existing electronics hubs for cost-efficient, high-volume production. |
| Form co-development partnerships for 3D crystals | These partnerships drive innovation and overcome scalability hurdles for next-generation components. |
| Develop advanced material compositions for RoHS compliance | This ensures market access in regulated regions like the European Union. |
Research Approach
Operator-level perspectives from R&D directors, optical engineers, material scientists, and procurement managers anchored the qualitative base for this analysis. This primary research was rigorously validated against extensive secondary data sources, including academic journals, patent databases, government reports from METI and MIIT, and company financial filings. The study utilized both bottom-up and top-down triangulation to ensure data consistency.
Sensitivity analysis framed the quantitative modeling, assessing market dynamics across the analysis window. The forecast framework segmented the market by product type, application, end-user, technology, and fabrication complexity. Compound Annual Growth Rates (CAGRs) were derived through a comprehensive analysis of historical trends and projected future demand. Key forecast inputs included 5G infrastructure build-out rates and R&D spending in quantum technologies.
Underlying assumptions cover current technological trajectories and regulatory stability, with deviation risk concentrated in the pace of nanofabrication advancements and global trade policy shifts. Revision becomes warranted when critical technological or regulatory conditions cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Residential 1080P Laser Television Projector Market
Optics
Photonics Sensor Market
Optics
Smartphone Camera Lenses Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Latin America Optical Imaging Market
Optics
US Photonics Market
Optics
Optical Fiber Market
Optics
Laser Transmitter Market
Optics
Germanium Lens Market
Optics
Global Fiber Optic Components Market
Optics
Liquid Crystal on Silicon Market
Optics
Electro Optics Market
Optics
Plastic Lens Market
Optics
Tunable Laser Market
Optics
Picosecond Lasers Market
Optics
Quartz Glass Market