
 Salt Lake Battery Grade Lithium Carbonate Market | 2026-2036
Salt Lake Battery Grade Lithium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Lake Battery Grade Lithium Carbonate Market Analysis
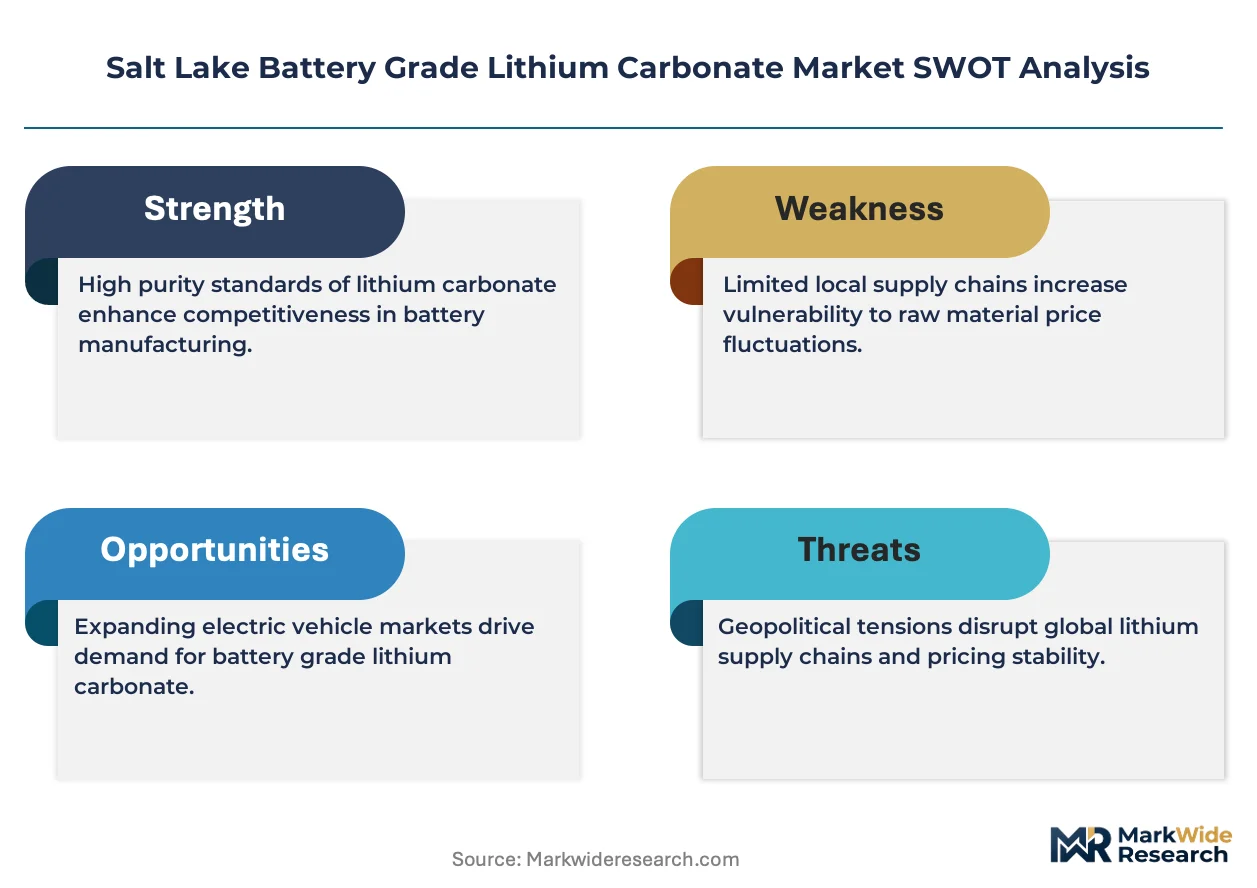
The price spread between battery-grade and industrial-grade salt lake lithium carbonate is hardening as cathode makers enforce tighter impurity thresholds. Albemarle Corporation leverages its Atacama brine operations to sustain long-term offtake contracts with Korean cathode producers. Ganfeng Lithium Co., Ltd. anchors its cost position through captive brine rights at Argentina's Cauchari-Olaroz project. Tianqi differentiates by controlling spodumene-to-carbonate conversion technology alongside its Australian hard-rock stakes.
Salt lake battery grade lithium carbonate denotes lithium carbonate derived from continental brine evaporation with sodium, magnesium, and calcium impurities reduced below thresholds specified by cathode manufacturers, typically achieving minimum 99.5% Li2CO3 purity through solvent extraction and ion exchange polishing. Its primary purpose is to serve as the lithium feedstock for nickel-cobalt-manganese and lithium iron phosphate cathode precursors in rechargeable cells. The batteries application segment leads volume absorption as energy storage deployments and electric vehicle production scale in parallel, while the high purity grade commands widening margin premiums over technical grade material. Specialty grade carbonate occupies a narrower but strategically defended niche serving solid-state battery developers with ultra-low sodium specifications.
China's SAMR enforces GB/T 11075 purity standards that filter substandard material from domestic battery supply chains, while the EPA in the United States monitors brine extraction impacts under Clean Water Act provisions that constrain permitting timelines for new Nevada projects. India's BIS is drafting lithium chemical standards under its PLI scheme for advanced chemistry cell manufacturing, creating prospective import qualification barriers. Stakeholders must track how regulatory divergence in purity certification across Beijing, Washington, and New Delhi reshapes arbitrage flows and regional capacity investment decisions.
Market Dynamics
China's SAMR enforcement of GB/T 11075 purity standards is compressing substandard supply and forcing cathode makers to source exclusively from brine operations capable of 99.5% Li2CO3 minimum purity through ion exchange polishing.
Growth Catalysts
- GB/T 11075 standard tightening:China's SAMR purity thresholds filter technical-grade material from battery supply chains, forcing cathode producers to upgrade feedstock specifications.
- Solid-state battery chemistry:Ultra-low sodium carbonate demand from next-generation cell developers creates premium-grade absorption above commodity pricing tiers.
- Qinghai Province concentration:Chaerhan Salt Lake cluster infrastructure expansion enables direct-ship battery-grade output to NCM and LFP precursor facilities.
Market Restraints
- Magnesium impurity removal:Salt lake brines require solvent extraction capex that hard-rock spodumene routes avoid, compressing margin structures for brine-only operators.
- Atacama-Cauchari supply dominance:Chilean and Argentine brine concessions concentrate 70% of non-Chinese battery-grade capacity, creating single-point geopolitical exposure.
- Direct lithium extraction substitution:DLE technologies promise 90% water recovery versus 50% for evaporation ponds, threatening legacy brine economics if scaled.
Strategic Opportunities
- India PLI scheme qualification:BIS draft standards for advanced chemistry cell manufacturing create first-mover import positioning for certified exporters.
- Nevada brine permitting:EPA Clean Water Act review timelines currently block new projects, but streamlined approval would unlock Clayton Valley and Railroad Valley resources.
- LFP cathode chemistry convergence:Iron phosphate formulations tolerate marginally higher impurity levels than NCM, expanding addressable brine supply pools.
Industry Challenges
- Ion exchange resin supply:Specialty polymer capacity for final-stage magnesium and calcium stripping concentrates with Japanese and German chemical suppliers, creating input bottlenecks.
- Brine-to-carbonate conversion certification:Korean cathode producers require six-month qualification timelines for new salt lake sources, freezing spot market participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Lake Battery Grade Lithium Carbonate Market |
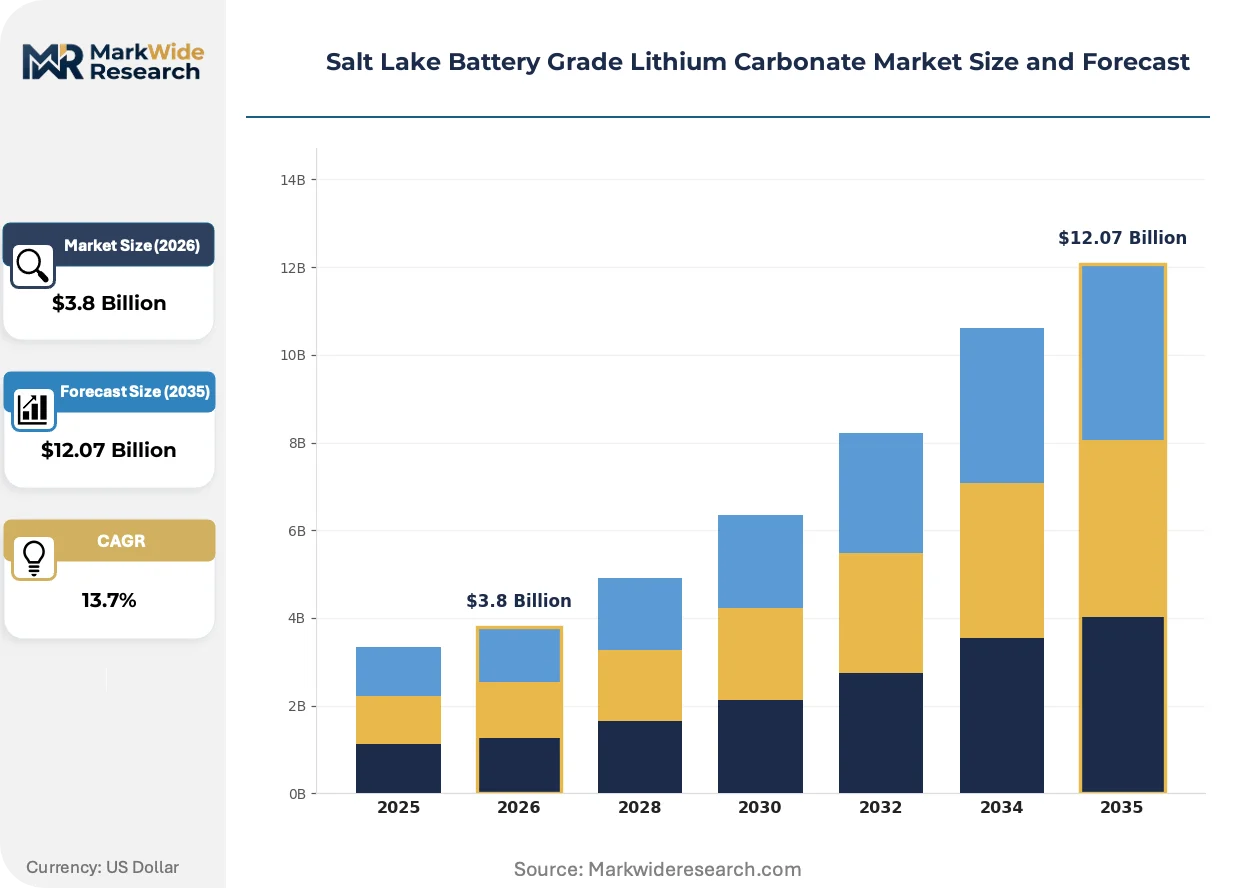
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Chemicals, Catalysts, Pharmaceuticals Grade: Standard, High Purity, Technical Grade, Specialty Grade Application: Energy Storage, Electric Vehicles, Aerospace, Electronics End User: Manufacturers, Distributors, Research Institutions, OEMs |
| Companies Covered | Qinghai Salt Lake Industry Co., Ltd, Livent Corporation, Albemarle Corporation, Piedmont Lithium Inc., Orocobre Limited, Sociedad Quimica y Minera de Chile, Tianqi Lithium, Lithium Americas Corp., Ganfeng Lithium Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Lake Battery Grade Lithium Carbonate Market Emerging Trajectories
Direct lithium extraction is compressing traditional evaporation timelines while regulatory divergence across purity certification is fragmenting regional supply qualification pathways.
Membrane-based selective lithium recovery is integrating into salt lake operations as a pre-concentration step before solar evaporation. Korean cathode producers are piloting DLE-coupled supply contracts to compress 18-month production cycles toward 90-day brine-to-carbonate turnaround. This acceleration is integrating marginal salt lake deposits into battery-grade supply pools previously excluded by evaporation economics.
China's dual carbon goals are tightening MEE oversight of brine extraction water intensity, forcing Qinghai operators to recirculate 85% of process streams versus historical 60% discharge rates. The regulatory pressure is redirecting expansion capital toward closed-loop evaporation infrastructure. Domestic cathode makers are responding by sourcing exclusively from operations with verified water-recovery certification.
Long-term offtake contracting is displacing spot market participation as Korean and Japanese cathode makers secure five-year supply agreements with fixed purity escalators. The contractual shift is compressing price discovery transparency and locking brine operators into dedicated volume commitments. This transformation is most visible in binding supply negotiations for 2027-2032 delivery windows.
Salt Lake Battery Grade Lithium Carbonate Market Segmentation
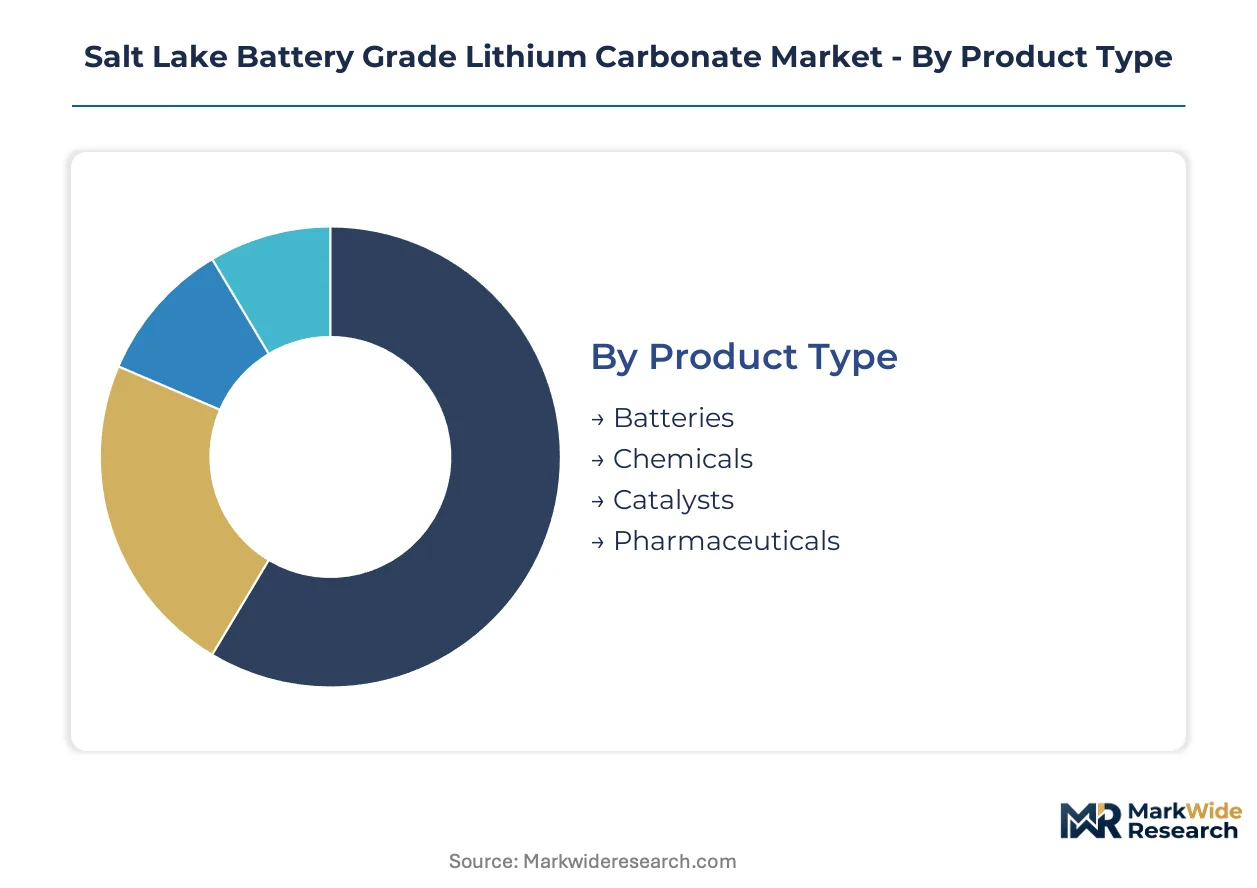
Salt lake battery grade lithium carbonate supply chains fragment across purity thresholds, end-use specifications, and customer qualification timelines. Segmentation reveals how cathode manufacturers, specialty chemical producers, and emerging solid-state developers compete for constrained brine-derived feedstock.
Product Type:
Supply concentration in Qinghai Province's Chaerhan Salt Lake cluster directs output volumes toward specific industrial applications with divergent purity tolerances.
- Batteries:Lithium carbonate meeting 99.5% Li2CO3 minimum purity through ion exchange polishing serves as the primary feedstock for NCM and LFP cathode precursors in rechargeable cells. Korean cathode producers absorb the majority of export-qualified material from Argentine Cauchari-Olaroz operations under long-term offtake structures.
- Chemicals:Industrial-grade material with marginally higher sodium and magnesium content supplies glass and ceramics manufacturing, where impurity thresholds remain less stringent than battery applications. China's domestic chemical sector sources predominantly from Qinghai's lower-purity evaporation streams.
- Catalysts:Battery-grade carbonate repurposed for petrochemical and polymerization catalyst production commands intermediate pricing between technical and specialty grades.
- Pharmaceuticals:Ultra-low heavy metal specifications for pharmaceutical-grade lithium compounds require additional solvent extraction stages beyond standard battery-grade processing.
Batteries absorbs the bulk of installed capacity; Pharmaceuticals is expanding most quickly.
Grade:
Cost tier differentiation separates commodity evaporation output from premium ion-exchange-polished material serving certified cathode supply chains.
- Standard:Material achieving 99.0-99.5% Li2CO3 purity through solar evaporation and basic filtration serves cost-sensitive industrial applications. China's SAMR GB/T 11075 enforcement is compressing this segment's addressable market as battery supply chains upgrade specifications.
- High Purity:99.5-99.9% Li2CO3 carbonate produced through multi-stage solvent extraction and ion exchange resin polishing qualifies for NCM cathode precursor manufacturing. Korean and Japanese cathode makers require six-month qualification timelines for new high-purity sources, freezing spot market participation.
- Technical Grade:Lower-purity material with elevated magnesium and calcium content supplies glass, ceramics, and lubricant grease manufacturing outside battery certification pathways.
- Specialty Grade:Ultra-low sodium carbonate with sub-50ppm Na specifications serves solid-state battery developers pursuing lithium metal anode architectures.
High Purity commands the dominant revenue share; Specialty Grade shows the steepest expansion trajectory.
Application:
Volume concentration in electric vehicle manufacturing reshapes how brine operators prioritize purity upgrades and capacity allocation across end-use segments.
- Electric Vehicles:NCM and LFP cathode production for automotive battery packs drives the majority of battery-grade lithium carbonate absorption. OEM procurement teams enforce supplier qualification protocols that lock brine operators into multi-year volume commitments.
- Energy Storage:Grid-scale battery deployments utilizing LFP chemistry tolerate marginally higher impurity levels than automotive NCM formulations, expanding addressable brine supply pools for this application.
- Aerospace:Specialized high-discharge-rate batteries for satellite and aircraft systems require traceable supply chains with documented impurity certification.
- Electronics:Consumer device batteries represent a fragmented demand base with dispersed procurement across multiple cathode suppliers.
Electric Vehicles captures the largest volume allocation; Energy Storage is climbing the fastest.
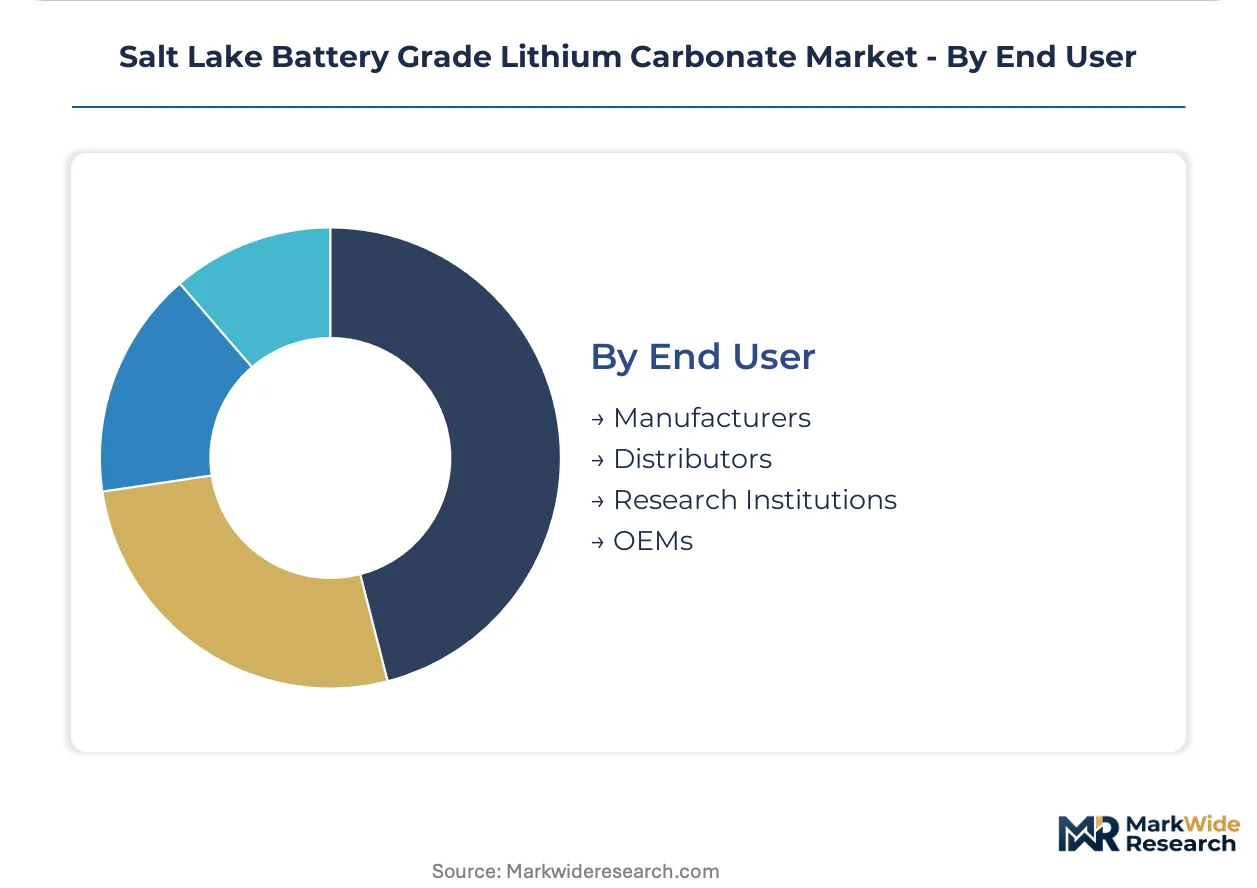
End User:
Customer type segmentation determines contracting structures, with direct manufacturer relationships displacing distributor intermediation in certified battery supply chains.
- Manufacturers:Cathode precursor producers and cell makers source directly from brine operators with verified GB/T 11075 or equivalent purity certification. Long-term offtake agreements with fixed purity escalators dominate procurement patterns.
- OEMs:Automotive and energy storage system integrators are consolidating supplier tiers, bypassing distributors to secure direct relationships with Argentine and Chilean brine operators.
- Distributors:Regional chemical distributors handle technical-grade material for industrial applications outside battery certification pathways.
- Research Institutions:Solid-state battery developers and materials science laboratories purchase specialty-grade carbonate in small volumes for pilot-scale production.
Manufacturers anchor procurement volume; OEMs are gaining share fastest through direct sourcing initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chaerhan Salt Lake cluster anchors the world's largest battery-grade lithium carbonate extraction infrastructure, with Qinghai Province's brine concentration ponds feeding cathode precursor facilities across East Asia.
China
Qinghai Province's Chaerhan Salt Lake operations supply the majority of domestic battery-grade material for NCM and LFP cathode manufacturing. SAMR enforcement of GB/T 11075 purity standards filters substandard output from certified supply chains. MEE oversight of water recirculation mandates is redirecting expansion capital toward closed-loop evaporation infrastructure in the Qaidam Basin.
Argentina
Cauchari-Olaroz brine concessions anchor South American battery-grade capacity expansion for Korean and Japanese cathode offtake contracts. Provincial mining codes in Jujuy and Salta provinces govern lithium extraction royalties and water rights allocation. Ganfeng Lithium's captive brine rights position the operation as a cost-competitive feedstock source for East Asian battery manufacturers.
Chile
Atacama Desert brine operations sustain long-term supply agreements with cathode producers requiring 99.5% Li2CO3 minimum purity. Corfo production quotas and environmental licensing under the Clean Water Act framework constrain new project permitting timelines. Albemarle's Salar de Atacama leases represent the most mature non-Chinese battery-grade carbonate extraction infrastructure.
United States
Clayton Valley and Railroad Valley brine deposits in Nevada remain undeveloped due to EPA Clean Water Act review bottlenecks. State-level water rights adjudication and federal environmental impact assessments create multi-year permitting delays. Lithium Americas' Thacker Pass spodumene project represents the most advanced domestic lithium chemical production pathway.
Australia
Hard-rock spodumene concentrate from Western Australia's Greenbushes and Pilgangoora mines feeds Tianqi's carbonate conversion technology. The country's national mining regulator oversees tailings management and water licensing for lithium chemical processing facilities. Kwinana and Kemerton industrial zones host spodumene-to-carbonate conversion plants serving Asian cathode supply chains.
Salt Lake Battery Grade Lithium Carbonate Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity certification and offtake contract duration, with ion exchange polishing capabilities separating certified battery-grade suppliers from industrial-grade operators. The vendor base concentrates around brine concession holders with captive water rights and spodumene-to-carbonate conversion specialists. Three archetypes dominate: integrated brine operators with evaporation pond infrastructure, hard-rock converters with chemical processing expertise, and project developers securing offtake ahead of production. Competitive dynamics center on long-term contracting with fixed purity escalators and backward integration into cathode precursor manufacturing.
Among integrated brine operators, Albemarle Corporation and Ganfeng Lithium Co., Ltd. occupy positions defined by captive concession rights and multi-year supply agreements. Tianqi Lithium exemplifies the hard-rock conversion archetype through its Australian spodumene stakes and carbonate processing technology. These three companies represent the dominant competitive anchors across the salt lake battery-grade lithium carbonate supply base, with each archetype pursuing distinct margin defense strategies.
| Leading Market Players |
|---|
| Qinghai Salt Lake Industry Co., Ltd |
| Livent Corporation |
| Albemarle Corporation |
| Piedmont Lithium Inc. |
| Orocobre Limited |
| Sociedad Quimica y Minera de Chile |
| Tianqi Lithium |
| Lithium Americas Corp. |
| Ganfeng Lithium Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between ion-exchange-polished battery material and basic evaporation output splits pricing power across Qinghai's Chaerhan cluster and Argentine Cauchari concessions. Korean cathode producers enforce six-month qualification timelines that lock premium-tier suppliers into multi-year offtake structures with fixed purity escalators, while unqualified operators compete on spot markets with compressed margins.
Pricing Analysis
Yield-adjusted purity premiums anchor value-based pricing as cathode manufacturers tie contract rates to cell performance outcomes rather than commodity benchmarks. Price differentiation rests on GB/T 11075 certification status and water-recovery verification under MEE oversight, with OEM procurement teams showing lowest sensitivity to unit cost and industrial chemical buyers absorbing margin pressure from magnesium removal capex requirements. Cost compression in standard-grade material is intensifying because hard-rock spodumene routes bypass solvent extraction investments.
Supply Chain Analysis
Freight costs from Argentine Jujuy and Chilean Atacama to Korean port facilities compound landed price spreads against Qinghai rail-shipped material. Supply concentrates in China, Argentina, and Chile, with brine operations drawing from captive water rights and solar evaporation infrastructure. Ion exchange resin supply concentrates with Japanese and German chemical suppliers, creating single-source vulnerability for final-stage polishing. Distribution runs through direct manufacturer relationships that displace spot market participation for certified battery-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as direct lithium extraction compresses traditional 18-month evaporation cycles toward 90-day brine-to-carbonate turnaround, displacing legacy pond infrastructure economics.
For Market Incumbents: Hedge against DLE technology obsolescence by securing captive brine rights with water-recovery certification ahead of MEE enforcement tightening. Reinforce cost position through backward integration into cathode precursor manufacturing in Qinghai industrial zones. Defend margin structures against hard-rock spodumene substitution by accelerating ion exchange capacity expansion. For New Entrants and Emerging Players: Begin with Nevada brine deposits where EPA permitting bottlenecks create acquisition opportunities ahead of streamlined approval pathways. Target energy storage LFP cathode segments that tolerate marginally higher impurity levels than automotive NCM formulations. Secure qualification partnerships with Korean cathode producers willing to pilot DLE-coupled supply contracts. For Investors and Strategic Acquirers: Re-rating potential sits with integrated brine operators possessing verified water-recovery certification given China's dual carbon goal enforcement tightening supply eligibility. Long-term viability favors concessions with closed-loop evaporation infrastructure and binding offtake coverage through the projection horizon. Monitor BIS standard finalization under India's PLI scheme as inflection indicator for qualified import demand.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Lithium Extraction Scale-Up | DLE deployment cuts production cycles from 18 months to 90 days, unlocking marginal salt lake deposits. |
| Closed-Loop Evaporation Infrastructure | MEE water-recovery mandates redirect capital toward 85% recirculation systems in Qinghai's Qaidam Basin. |
| Long-Term Offtake Contracting | Korean cathode producers lock five-year supply agreements with fixed purity escalators, freezing spot participation. |
| Backward Integration into Precursors | Brine operators capture margin expansion by controlling NCM and LFP precursor manufacturing stages. |
| India PLI Qualification Positioning | BIS draft standards create first-mover import barriers for certified exporters to advanced chemistry cell manufacturing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with brine operation plant managers, cathode precursor procurement leads, and ion exchange resin technical directors combined with SAMR enforcement documentation, EPA permit records, and Korean customs import data. Bottom-up capacity modeling and top-down demand triangulation validated segmentation outputs across the analysis window.
Granularity-level modeling captured product type, grade tier, and end-use application dimensions at the country-production-hub level. CAGRs derived from volume absorption trajectories in electric vehicle and energy storage segments, with purity certification thresholds and water-recovery compliance rates as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; high-purity and specialty-grade categories carry tighter precision than technical-grade material given concentrated cathode producer qualification data. Forecasts reflect assumptions around DLE technology adoption rates, MEE enforcement intensity, and Korean offtake contracting duration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Battery in Myanmar Market