
 United Kingdom Rechargeable Battery Market | 2026-2036
United Kingdom Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Rechargeable Battery Market Insights
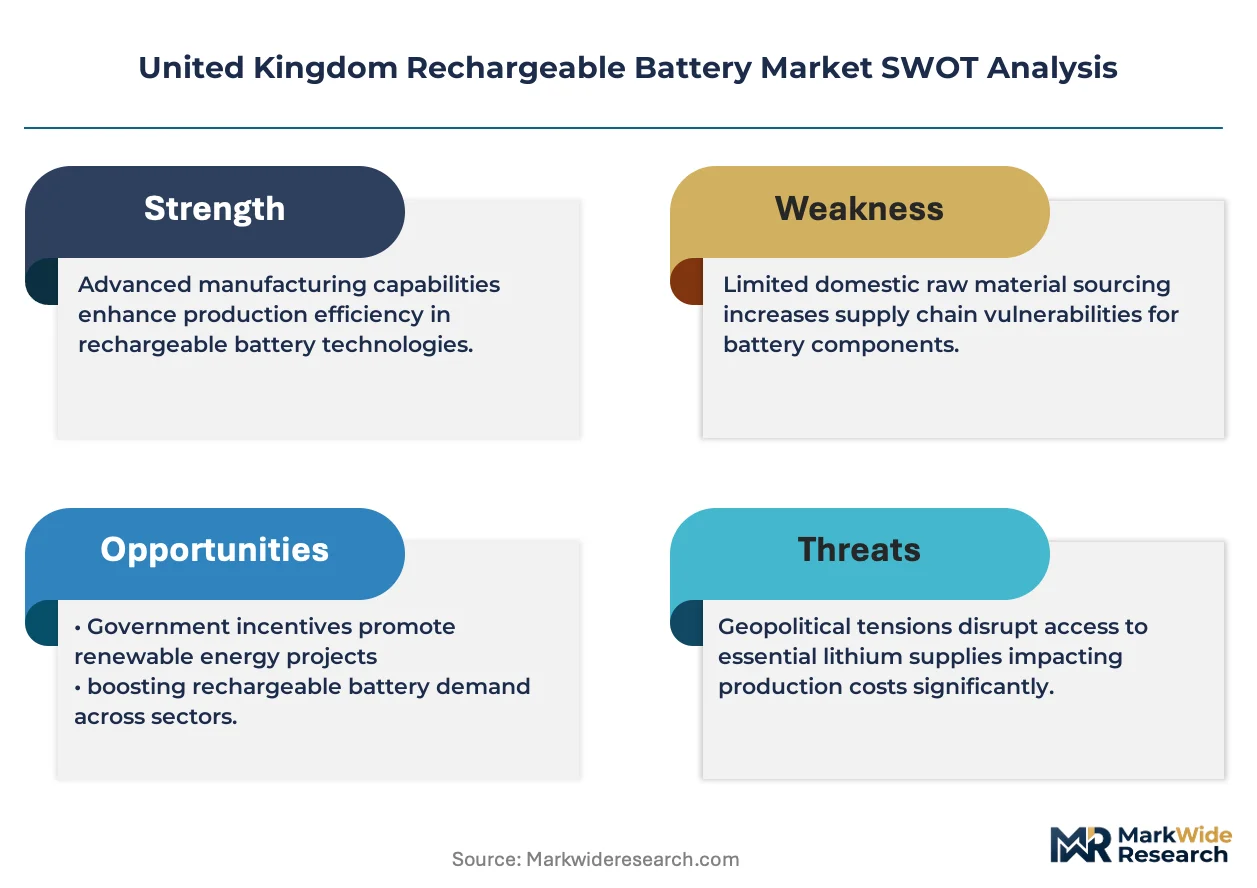
The price-performance gap between automotive-grade lithium-ion cells and commodity lead-acid replacements is hardening across UK supply chains. LG Energy Solution leverages its cylindrical cell expertise to sustain long-term contracts with premium EV assemblers. Samsung SDI anchors its UK position through differentiated nickel-cobalt-manganese cathode formulations designed for European cold-start requirements. Exide Technologies competes in the industrial motive-power segment where lead-acid still dominates fork-lift and warehouse automation fleets.
A rechargeable battery is an electrochemical energy storage device designed for repeated charge-discharge cycling, typically employing lithium-ion chemistries with graphite anodes and transition-metal oxide cathodes achieving energy densities of 250-300 Wh/kg for automotive applications. Its primary commercial purpose is to decarbonize transport and stabilize renewable electricity grids through stationary storage. Lithium-ion products command the dominant value pool in the UK market, while nickel-metal hydride retains residual share in hybrid vehicle architectures where thermal stability outweighs energy density requirements. Energy Storage applications are attracting the fastest capacity additions as grid-scale projects co-locate with offshore wind connections in Scotland and the North Sea.
The UK Battery Strategy and Office for Product Safety and Standards enforce strict cell testing protocols, while BSI Group administers PAS 63119 standards for second-life battery repurposing. These frameworks compel manufacturers to design for recyclability and traceability, effectively raising compliance costs for non-domestic suppliers. Stakeholders must monitor how the Advanced Manufacturing Plan and potential carbon border adjustments reshape sourcing economics for imported cathode materials.
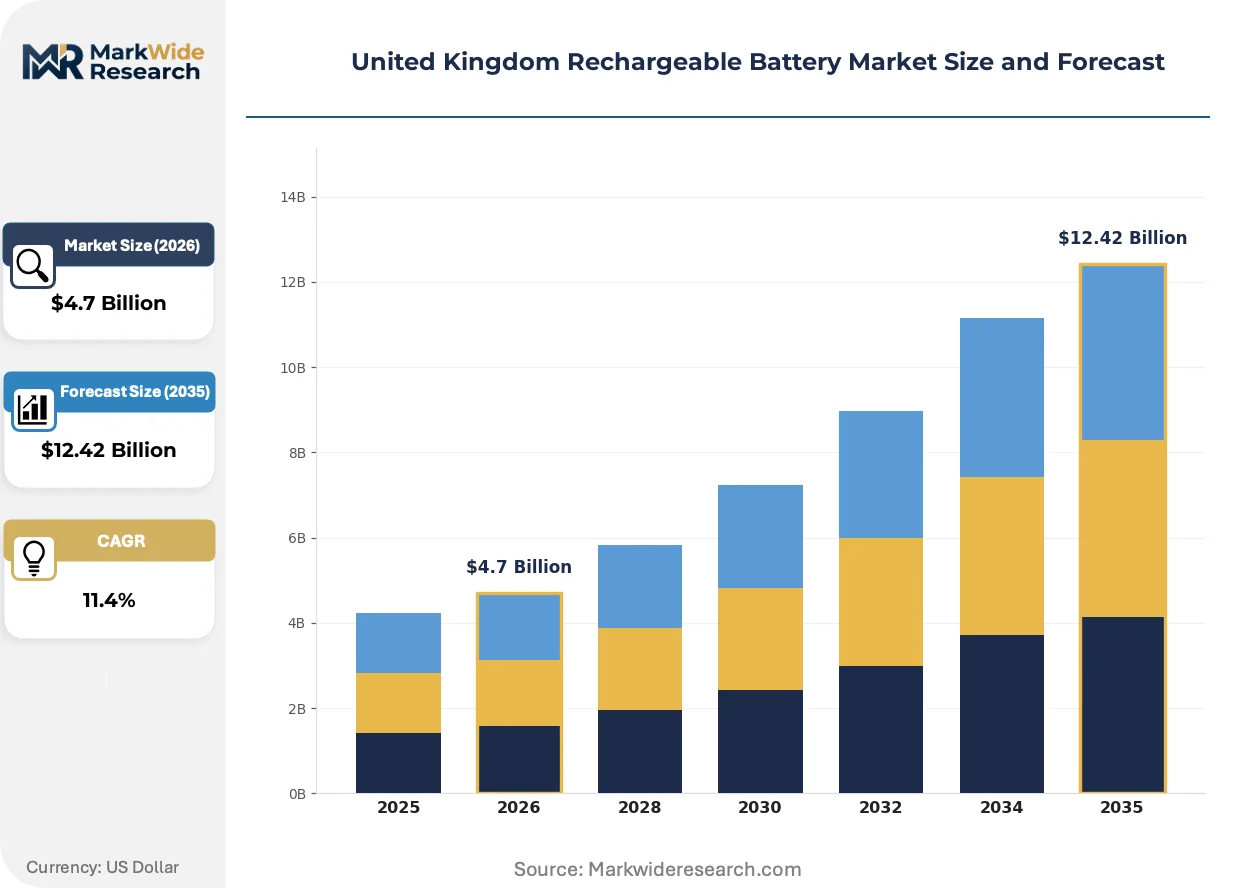
Market Dynamics
The UK's Zero Emission Vehicle mandate is compressing procurement timelines for lithium-ion cell capacity as fleet operators accelerate electrification commitments ahead of the 2035 internal combustion phase-out. This regulatory pressure is reshaping investment flows toward the Midlands battery belt and forcing cathode chemistry roadmaps to prioritize energy density over cost minimization.
Growth Catalysts
- Zero Emission Vehicle mandate:Fleet operators must electrify commercial vehicles by 2035, creating guaranteed offtake for high-nickel cathode cells.
- Offshore wind co-location:Grid-scale battery projects in Scotland and the North Sea are absorbing surplus generation, driving demand for containerized lithium-ion storage.
- Solid-state electrolyte research:Imperial College London and legacy Oxis Energy IP are redirecting R&D toward sulfur-lithium architectures with higher theoretical energy density.
Market Restraints
- Cathode material import dependency:UK cell manufacturing relies on processed nickel and cobalt from concentrated East Asian refining corridors, exposing margins to freight and duty volatility.
- Second-life certification friction:PAS 63119 standards administered by BSI Group impose traceability costs that slow repurposing of automotive packs into stationary storage.
- Lead-acid residual lock-in:Industrial motive-power segments retain lead-acid chemistry for fork-lift fleets due to established recycling infrastructure and lower upfront capital requirements.
Strategic Opportunities
- Second-life battery repurposing:Retired EV packs from the Midlands manufacturing corridor can feed stationary storage projects in Scotland if BSI certification timelines compress.
- Sulfur-lithium commercialization:Oxis Energy legacy patents and Imperial College research convergence could unlock cathode chemistries with 400+ Wh/kg potential for aviation applications.
- Carbon border adjustment preparation:The Advanced Manufacturing Plan incentives are pushing cathode precursor producers to document embedded emissions ahead of potential UK-EU carbon border mechanisms.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell manufacturing scale-up in Coventry and Warwickshire outpaces domestic university pipeline output for solid-state electrolyte specialists.
- Dual certification burden:Products must satisfy UK Battery Strategy testing protocols and Office for Product Safety and Standards requirements simultaneously, extending time-to-revenue for new cell formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Rechargeable Battery Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead Acid, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Energy Storage Application: Smartphones, Electric Vehicles, Power Tools, Uninterruptible Power Supply Distribution Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Wholesalers |
| Companies Covered | LG Energy Solution, Samsung SDI, Panasonic, GS Yuasa Corporation, Toshiba Corporation, BYD, CATL, Exide Technologies, SK Innovation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Rechargeable Battery Market Trends and Innovations
Solid-state electrolyte development is compressing conventional lithium-ion roadmaps as research institutions and industrial partners prioritize sulfur-lithium architectures. This technological pivot is redirecting capital toward materials science capabilities and away from incremental graphite anode improvements.
Solid-state battery technology employs ceramic or glass-ceramic electrolytes to replace flammable liquid electrolytes, enabling lithium-metal anodes with substantially higher energy density. Automotive OEMs are accelerating pilot procurement for premium EV platforms where thermal stability outweighs cost sensitivity. This chemistry is expanding into aviation propulsion applications as weight constraints dominate battery selection criteria.
The UK Battery Strategy mandates cell-level traceability and recyclability design standards enforced by the Office for Product Safety and Standards. Manufacturers must embed digital passports and disassembly protocols from initial design phases, raising compliance costs for imported cells. Domestic assemblers in the Midlands battery belt are responding by integrating recycling partnerships into offtake agreements.
Fleet operators are consolidating procurement decisions at the holding-company level rather than delegating to individual depot managers. This centralization is displacing fragmented spot purchasing with multi-year framework contracts tied to total-cost-of-ownership metrics. The shift is most visible in commercial vehicle electrification programs where charging infrastructure and battery leasing bundle into single supplier relationships.
United Kingdom Rechargeable Battery Market Segmentation
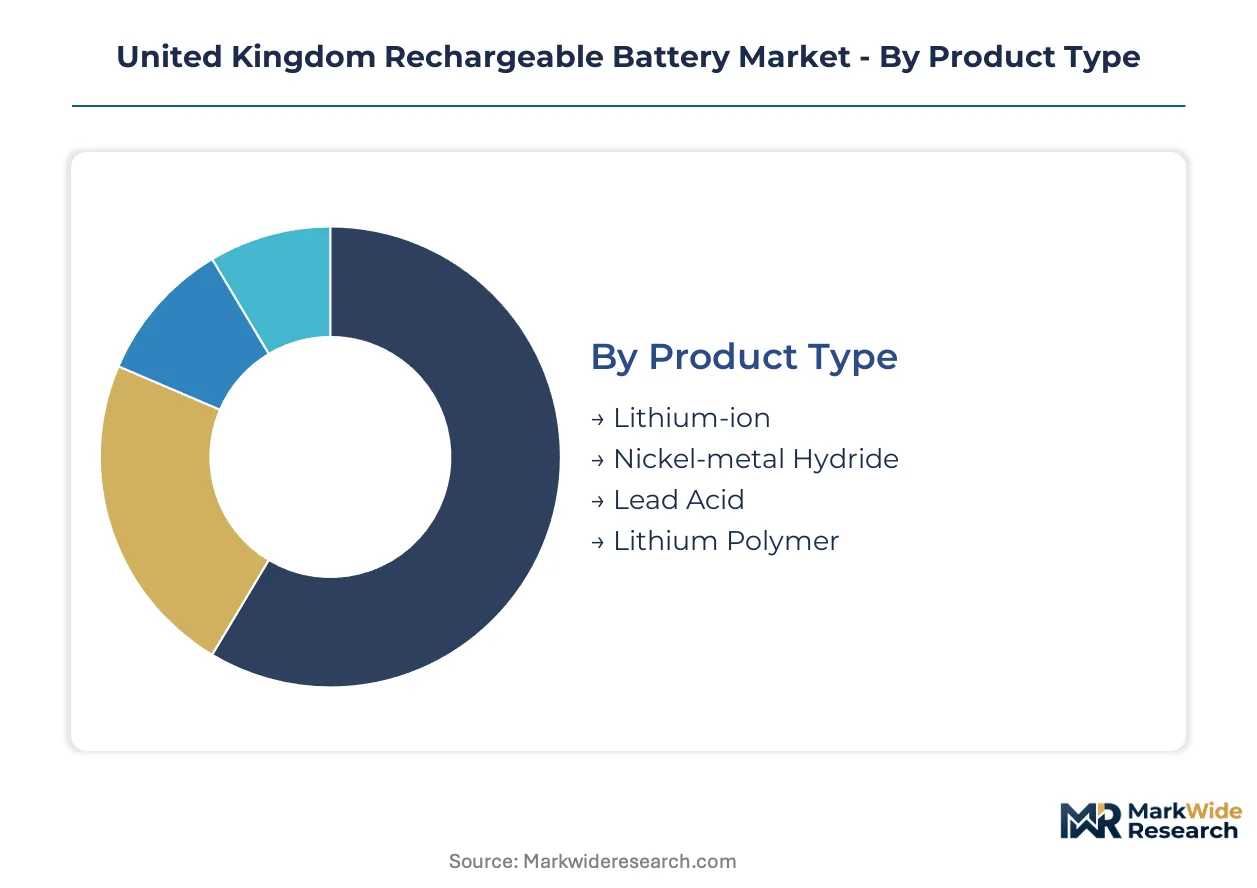
Segmentation in the United Kingdom rechargeable battery market reveals how capital allocation and technical requirements diverge across chemistries and customer types. Procurement patterns in the Midlands battery belt differ markedly from distributed industrial demand, shaping where manufacturers concentrate cell production capacity.
Product Type:
Capital intensity varies dramatically across electrochemical systems, with gigafactory-scale lithium-ion fabrication requiring orders of magnitude more upfront investment than lead-acid recycling infrastructure.
- Lithium-ion:Graphite anodes paired with nickel-cobalt-manganese or lithium-iron-phosphate cathodes deliver 250-300 Wh/kg for automotive applications. Fleet operators in Coventry and Warwickshire are absorbing the majority of UK cell output under long-term offtake agreements tied to the Zero Emission Vehicle mandate.
- Nickel-metal Hydride:Rare-earth alloy anodes and nickel oxyhydroxide cathodes provide thermal stability superior to lithium-ion in high-temperature cycling. Toyota and Honda hybrid platforms retain this chemistry for power-split transmissions where battery weight matters less than abuse tolerance.
- Lead Acid:Mature recycling infrastructure in the West Midlands supports closed-loop production for industrial motive-power applications.
- Lithium Polymer:Pouch-cell formats with gel electrolytes dominate consumer electronics where form-factor flexibility outweighs energy density optimization.
Most installed capacity flows through Lithium-ion. Expansion is steepest in Lithium Polymer as wearable devices and foldable smartphones proliferate.
End User:
Customer procurement sophistication determines contract structure complexity, with automotive OEMs demanding multi-year framework agreements that industrial buyers rarely match.
- Consumer Electronics:Smartphone and laptop manufacturers specify pouch-cell or cylindrical formats with strict cycle-life guarantees. Samsung SDI and LG Energy Solution supply tier-one device assemblers through just-in-time logistics hubs serving Cambridge and London tech corridors.
- Automotive:Cell-to-pack architectures dominate as Britishvolt successor projects and UK Battery Industrialisation Centre partners qualify high-nickel cathodes for premium EV platforms. Cold-start requirements in Scottish Highlands are driving nickel-cobalt-manganese formulations with enhanced low-temperature conductivity.
- Industrial:Fork-lift fleets and warehouse automation systems in the Midlands retain lead-acid dominance due to established maintenance protocols.
- Energy Storage:Containerized lithium-ion systems co-locate with offshore wind connections in Scotland and the North Sea, absorbing surplus generation that grid infrastructure cannot transmit.
Procurement volume concentrates in Automotive. Customer sophistication is climbing fastest in Energy Storage as grid operators model degradation curves into long-term capacity planning.
Application:
Performance specifications diverge sharply between portable power and stationary installations, with thermal management requirements dictating cell selection.
- Smartphones:Silicon-anode prototyping at Imperial College London targets 20% energy density improvements for next-generation flagships.
- Electric Vehicles:Solid-state electrolyte research redirects roadmaps toward sulfur-lithium architectures with theoretical densities exceeding 400 Wh/kg. Premium SUV and luxury sedan platforms in the Midlands battery belt are piloting these chemistries for aviation-derived range requirements.
- Power Tools:High-discharge cylindrical cells from Samsung SDI dominate professional construction equipment where burst current tolerance determines tool performance.
- Uninterruptible Power Supply:Data centre operators in Slough and London Docklands specify lithium-ion replacements for legacy lead-acid systems, prioritizing footprint reduction over capital cost minimization.
Deployment scale is largest in Electric Vehicles. Technical complexity is advancing most rapidly in Uninterruptible Power Supply as hyperscale facilities demand 15-year service life guarantees.
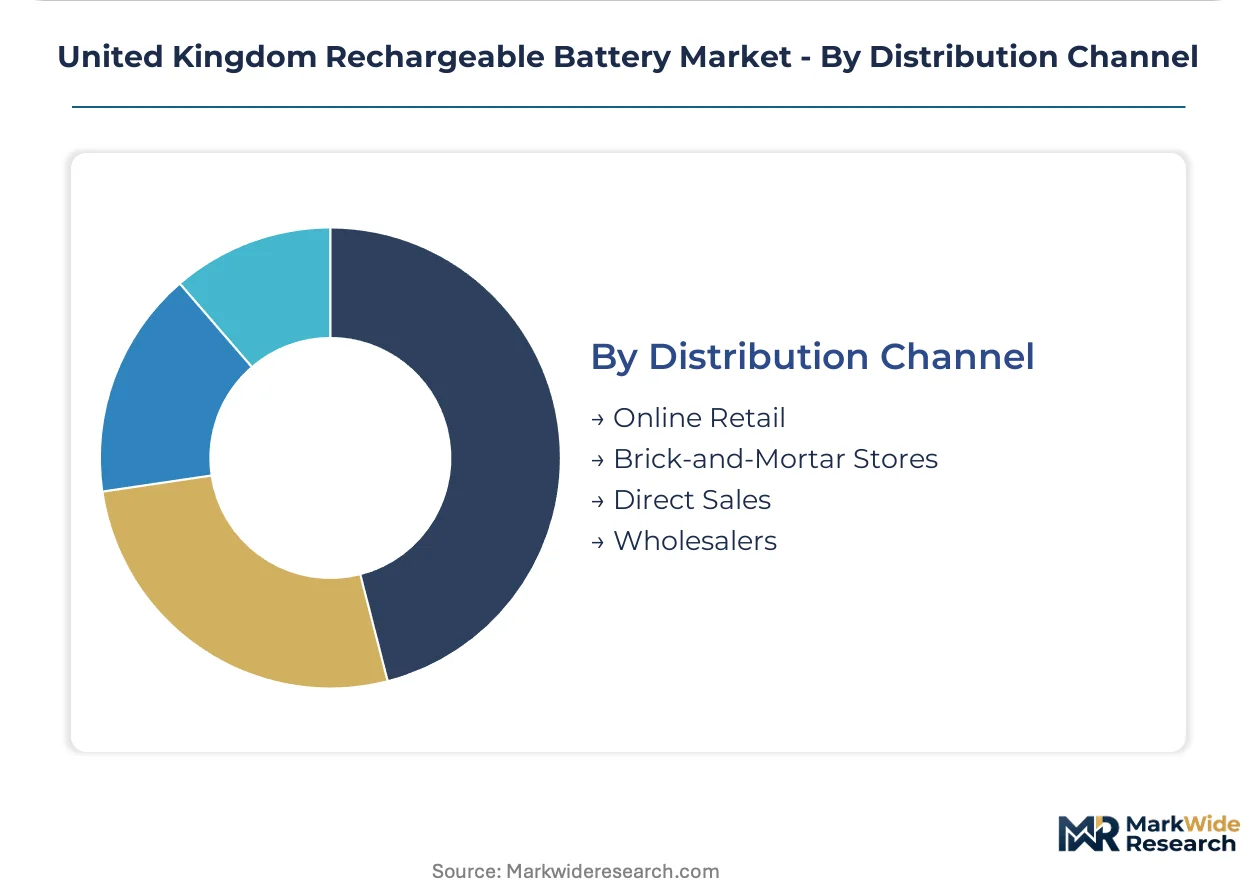
Distribution Channel:
Channel economics reflect customer technical competence, with direct sales commanding premium margins where application engineering support is bundled.
- Online Retail:Amazon and specialist battery distributors serve hobbyist and replacement markets with standardized lithium-polymer and cylindrical cell formats.
- Brick-and-Mortar Stores:Halfords and independent automotive retailers stock lead-acid and entry-level lithium-ion products for immediate installation.
- Direct Sales:Cell manufacturers maintain dedicated account teams for automotive OEMs and energy storage developers requiring bespoke thermal management integration.
- Wholesalers:RS Components and Farnell distribute industrial-grade cells to equipment manufacturers with volume pricing tied to annual offtake commitments.
Revenue concentration sits with Direct Sales. Channel investment is shifting most aggressively toward Online Retail as aftermarket replacement cycles shorten for consumer electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical engineering talent concentrates in the Midlands battery belt around Coventry and Warwickshire, where Britishvolt successor projects and the UK Battery Industrialisation Centre anchor cell manufacturing scale-up. This workforce cluster feeds procurement decisions across England, Scotland, and Wales.
England
Fleet operators in the Midlands accelerate electrification commitments under the Zero Emission Vehicle mandate. The Office for Product Safety and Standards enforces strict cell testing protocols for automotive-grade lithium-ion packs. The Midlands battery belt around Coventry hosts UK Battery Industrialisation Centre partnerships qualifying high-nickel cathodes for premium EV platforms.
Scotland
Grid-scale battery projects co-locate with offshore wind connections in the North Sea, absorbing surplus generation. The UK Battery Strategy mandates traceability standards that shape procurement for containerized lithium-ion storage. Aberdeen and Edinburgh anchor energy storage development clusters where hyperscale facilities demand long service life guarantees.
Wales
Industrial motive-power segments retain lead-acid dominance for fork-lift fleets due to established recycling infrastructure. PAS 63119 standards administered by BSI Group impose traceability costs on second-life battery repurposing. Newport and Cardiff host warehouse automation systems where maintenance protocols favor mature battery chemistries.
Northern Ireland
Data centre operators specify lithium-ion replacements for legacy lead-acid uninterruptible power supply systems. The Advanced Manufacturing Plan incentives push cathode precursor producers to document embedded emissions. Belfast anchors footprint reduction priorities for hyperscale facilities seeking 15-year service life guarantees.
United Kingdom Rechargeable Battery Market Competitive Landscape
Top-tier vendors anchor long-term automotive offtake agreements, while mid-tier specialists compete in industrial motive-power and stationary storage segments. The market structure reflects tiered procurement sophistication, with automotive OEMs demanding multi-year frameworks and industrial buyers favoring spot purchasing. Three archetypes dominate: cylindrical cell specialists, pouch-cell format providers, and integrated energy storage developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure cathode material supply corridors.
Within the cylindrical cell specialist tier, LG Energy Solution and Samsung SDI exemplify premium-tier positioning through differentiated cathode formulations. Panasonic occupies a position bridging consumer electronics and automotive supply chains. These three anchors represent divergent geographic origins—South Korean, Japanese, and Chinese manufacturing heritage—while converging on UK fleet operator procurement timelines.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| Panasonic |
| GS Yuasa Corporation |
| Toshiba Corporation |
| BYD |
| CATL |
| Exide Technologies |
| SK Innovation |
| Others |
Pricing and Supply Chain Analysis
Fleet operators consolidating procurement at the holding-company level have shifted UK battery pricing toward multi-year framework contracts with total-cost-of-ownership metrics rather than spot purchasing. This centralization favors suppliers bundling charging infrastructure, battery leasing, and maintenance services into single supplier relationships.
Pricing Analysis
Bundled service contracts dominate automotive and energy storage segments while unbundled transactional pricing persists in industrial motive-power and consumer replacement markets. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM qualification-grade cells from industrial certified products and aftermarket commodity replacements. Cost compression in the premium tier is intensifying because cathode material import dependency exposes margins to freight volatility. Industrial buyers exhibit highest price sensitivity due to established lead-acid recycling infrastructure and lower upfront capital thresholds.
Supply Chain Analysis
Processed nickel and cobalt supply rests on concentrated East Asian refining corridors in China, South Korea, and Japan. UK cell manufacturing draws from cathode precursor materials, electrolyte salts, and separator membranes produced in these geographies. Single-source vulnerability in high-purity nickel sulfate refining creates exposure to trade policy shifts. Distribution runs through direct sales teams for automotive OEMs, wholesalers for industrial equipment manufacturers, and online retail for consumer replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK rechargeable battery market represents a late-cycle quality story as fleet procurement shifts toward premium specifications demanding 15-year service life guarantees and embedded carbon traceability. This specification escalation favors suppliers with proven qualification records and integrated recycling partnerships.
For Market Incumbents: Anticipate margin compression from emerging sulfur-lithium chemistry developers by accelerating solid-state electrolyte pilot programs with Imperial College London research partners. Secure backward integration into cathode precursor supply through long-term offtake agreements with East Asian refiners ahead of potential UK-EU carbon border mechanisms. Prioritize BSI Group PAS 63119 certification investments to compress second-life repurposing timelines.
For New Entrants and Emerging Players: Enter via the industrial motive-power segment where lead-acid residual lock-in creates white-space opportunity for lithium-ion replacements in warehouse automation fleets. Target Wales and West Midlands fork-lift fleet operators with maintenance-protocol-compatible battery systems. Pursue channel partnerships with established industrial distributors rather than direct automotive OEM qualification.
For Investors and Strategic Acquirers: Automotive OEM captive supply divisions are the most active acquirer in this space, seeking cell manufacturing capacity to secure Zero Emission mandate compliance. Long-term viability favors assets with Midlands battery belt geographic positioning and UK Battery Industrialisation Centre partnership status. Watch Imperial College London solid-state research commercialization timelines as inflection signal for chemistry roadmap disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Secures supply corridor from East Asian refiners ahead of carbon border adjustments. |
| Solid-State Electrolyte Pilot Scale-Up | Positions suppliers for sulfur-lithium aviation applications with Imperial College research. |
| Second-Life Certification Acceleration | Compresses PAS 63119 timelines to feed retired EV packs into Scottish grid storage. |
| Multi-Year Framework Contracting | Locks in fleet operator procurement under total-cost-of-ownership metrics. |
| Midlands Manufacturing Footprint Expansion | Captures UK Battery Industrialisation Centre qualification pathways for premium cells. |
Research Methodology
Bottom-up automotive and energy storage demand modeling reconciled against top-down cell manufacturing capacity tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, cell manufacturing engineers, BSI Group certification specialists, and grid storage project developers combined with secondary validation from UK Office for Product Safety and Standards filings, SEC disclosures by listed battery manufacturers, and trade data from HM Revenue and Customs. Triangulation between these sources calibrated installed capacity estimates against actual offtake agreements.
Input-output matrices mapped cathode chemistry requirements across vehicle class, propulsion architecture, and stationary storage scale segments throughout the forecast period. CAGRs derived from segment-level demand build-ups incorporating Zero Emission Vehicle mandate compliance timelines and offshore wind connection schedules. Forecast inputs included electrochemical engineering talent pipeline data from Midlands universities and solid-state research commercialization indicators from Imperial College London.
Inputs from primary stakeholder interviews and regulatory filings were available through the study window; gaps in proprietary cathode material cost structures introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding mandate compliance rates and research commercialization timelines. Supply disruption in East Asian refining corridors and accelerated sulfur-lithium breakthroughs constitute the small set of triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Bangladesh Lead Acid Battery Market
Batteries
VRLA Batteries Market
Batteries
Breathing Battery Market
Batteries
West Europe Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Indonesia Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Sweden Rechargeable Battery Market
Batteries
India Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Marine Powerboat Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
48 Volt Battery System Market
Batteries
Cylindrical Lithium Battery Winding Machine Market