
 Ocean Thermal Energy Conversion Plant Market | 2026-2036
Ocean Thermal Energy Conversion Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Ocean Thermal Energy Conversion Plant Market Intelligence
A transition from government-funded research consortia to private-public utility partnerships is restructuring project development. Makai Ocean Engineering specializes in the design and testing of critical components like heat exchangers. DCNS leverages its extensive marine engineering expertise for large-scale platform design. OTEC International LLC focuses on developing smaller, modular systems for island nations and remote coastal communities.
Ocean thermal energy conversion plants generate electricity from the temperature difference between warm surface and cold deep seawater. These facilities typically use a closed-cycle system with ammonia as a working fluid to power a turbine, providing baseload renewable energy. Closed-cycle designs are the dominant plant type due to their technical maturity. While most existing plants have an energy output capacity below 5 MW for research purposes, commercial interest is shifting towards larger-scale projects.
Government frameworks are critical for project viability. In the United States, Department of Energy grants are instrumental, while Japan's METI integrates OTEC into its renewable energy strategy. The central challenge for stakeholders is balancing the high capital expenditure of commercial-scale plants against the incremental gains from smaller research installations.
Market Dynamics
The central tension shaping the ocean thermal energy conversion plant market is the financial and technical gap between small-scale, government-funded research installations and the high capital expenditure required for commercially viable, utility-scale baseload power plants.
Growth Catalysts
- National Energy Strategies:Japan's integration of OTEC into its national renewable energy strategy under METI provides a clear policy framework and funding mechanisms, accelerating pilot project development in locations like Okinawa.
- Heat Exchanger Advances:Innovations in heat exchanger design, particularly using new materials and micro-channel geometries, are improving thermal efficiency and reducing the physical footprint and cost of the core power block.
- Baseload Power Demand:Island nations and remote coastal communities are seeking reliable, non-intermittent renewable energy sources to displace expensive and volatile diesel fuel imports, creating a specific demand for OTEC's baseload generation profile.
Market Restraints
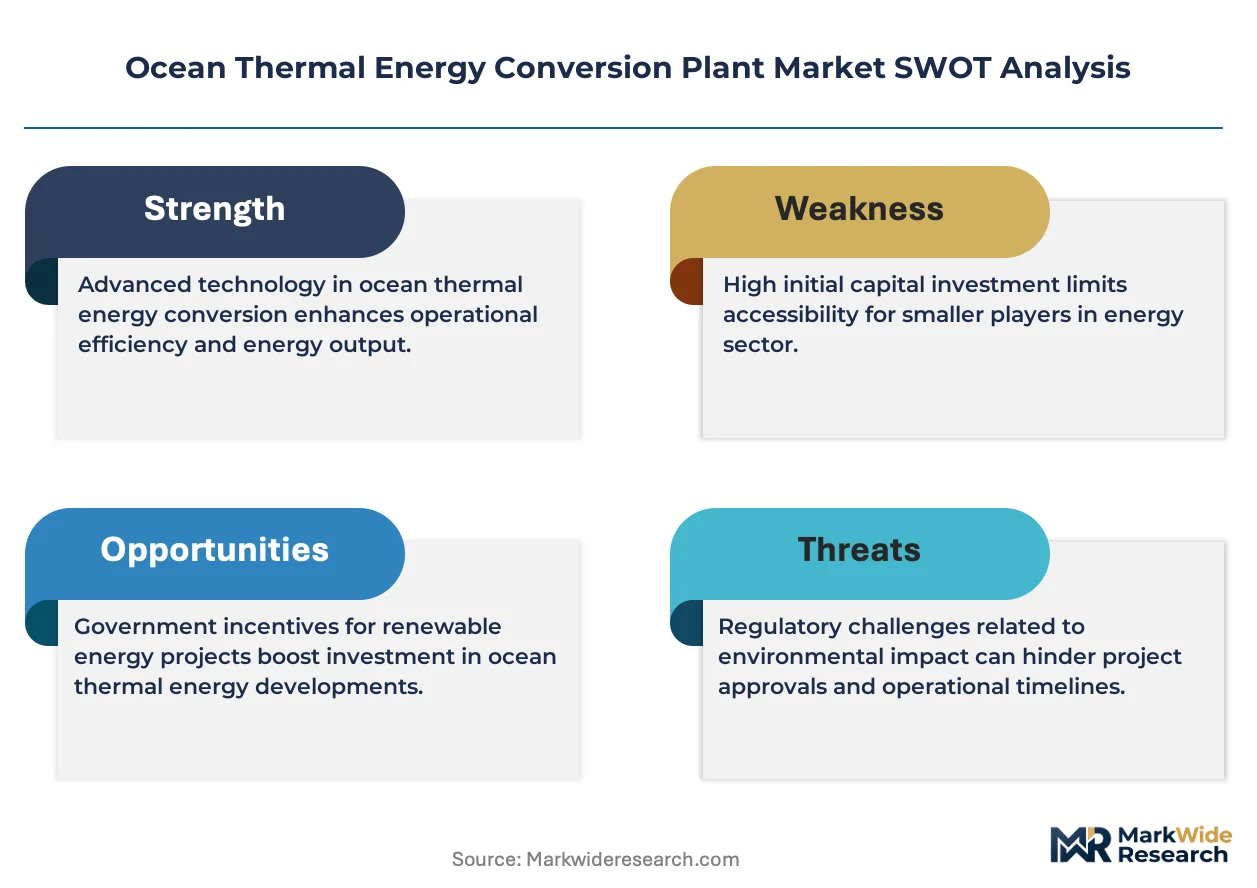
- High Upfront Capital:The extreme capital intensity for constructing large-scale platforms, deep-sea pipelines, and mooring systems presents a significant barrier to entry and project financing without substantial government backing.
- Technical Scalability Hurdles:Scaling up from sub-5 MW research facilities to commercial plants above 100 MW involves unproven engineering challenges, particularly concerning the cold water pipe's diameter and length.
- Geographic Limitation:Viable OTEC operation is restricted to tropical and subtropical regions with a consistent and significant temperature differential between surface and deep water, limiting the total addressable market geographically.
Strategic Opportunities
- Hybrid Applications:Co-locating OTEC plants with desalination facilities or deep ocean water air conditioning systems creates additional revenue streams, improving the overall economic case for project development.
- Green Hydrogen Production:OTEC's continuous power output can be used to power electrolyzers for green hydrogen production, providing a stable energy source for an emerging and high-value clean fuel market.
- Modular System Deployment:Developing smaller, containerized, and modular OTEC systems offers a pathway to serve smaller island grids and remote industrial sites without the financial risk of a single, large-scale plant.
Industry Challenges
- Long Permitting Cycles:Projects face lengthy and complex environmental impact assessments and permitting processes related to seawater intake and discharge, which can add years and significant cost before construction can begin.
- Specialized Workforce Scarcity:A limited talent pool exists with the combined expertise in marine engineering, thermodynamics, and power systems required for the design, construction, and operation of OTEC facilities.
- Grid Integration Complexity:Integrating a new, constant baseload power source into small or isolated island grids requires significant grid modernization and stability studies to prevent system imbalances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocean Thermal Energy Conversion Plant Market |
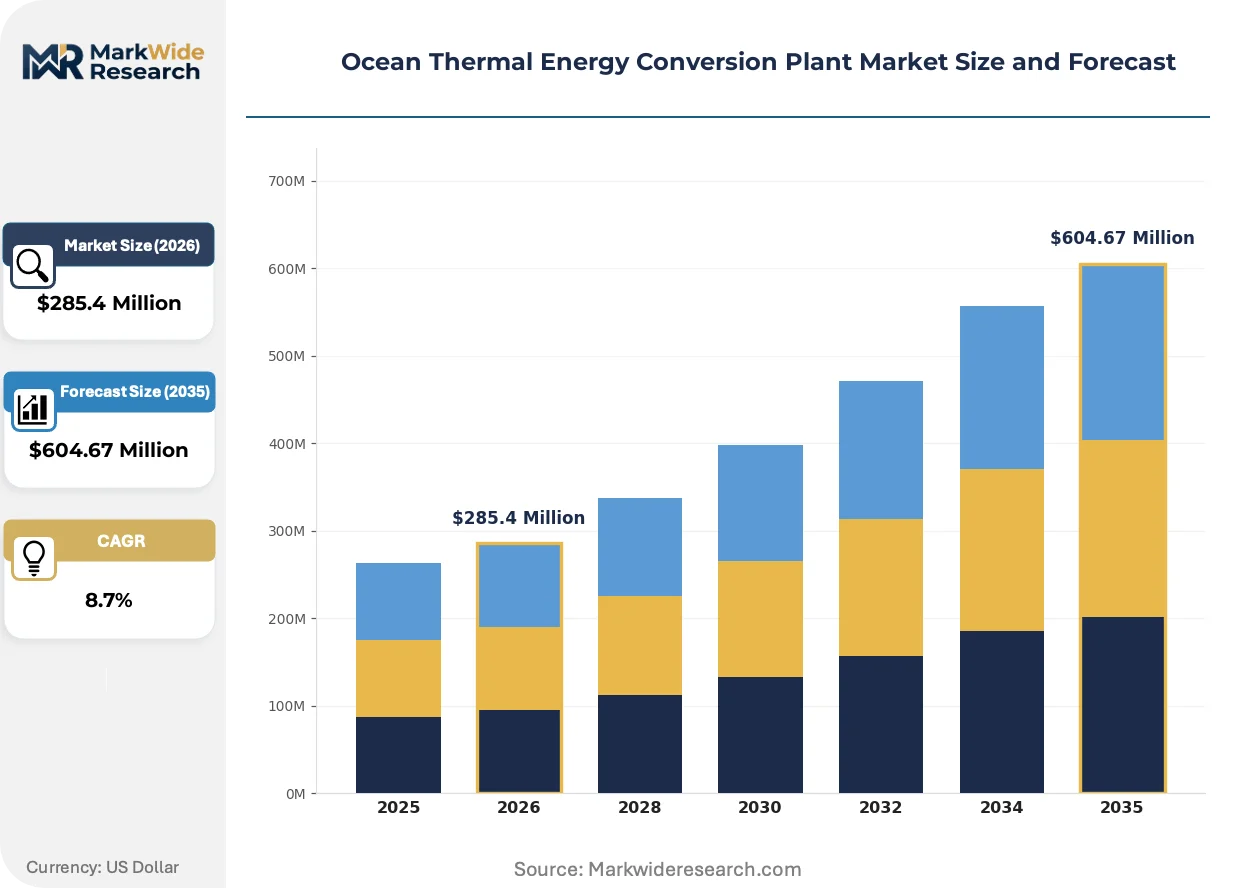
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Plant Type: Closed-Cycle, Open-Cycle, Hybrid-Cycle, Direct-Contact Energy Output Capacity: Below 5 MW, 5-10 MW, 10-15 MW, Above 15 MW End User: Renewable Energy Utilities, Research Institutions, Marine Power Developers, Government Agencies Technology: Ammonia-Based Systems, Refrigerant-Based Systems, Thermal Storage Integration, Heat Exchanger Innovations |
| Companies Covered | NELHA, DCNS, Makai Ocean Engineering, Akuo Energy, UTM OTEC, OTEC International LLC, Bardot Group, Global OTEC Resources, Bluerise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocean Thermal Energy Conversion Plant Market Strategic Shifts & Innovations
The market's evolution is defined by a concerted push to bridge the gap between experimental science and commercial deployment. This transition prioritizes modular designs, improved financial modeling through new policy incentives, and partnership structures that de-risk the high upfront investment.
Modular OTEC systems represent a significant product evolution. These systems utilize standardized, factory-built components for the power block and heat exchangers, enabling faster and more predictable deployment. Island utilities and private developers in the Pacific and Caribbean are adopting this approach for initial projects. This standardized design philosophy is expanding into applications for off-grid industrial power and community-scale energy, moving beyond purely bespoke research installations.
In the United States, the Inflation Reduction Act (IRA) provides a powerful regulatory tailwind. Its investment and production tax credits for clean energy projects fundamentally improve the financial viability of high-capital technologies like OTEC. Project developers, particularly those planning installations in US territories like Hawaii or Guam, can now leverage these federal incentives to attract private capital and secure long-term power purchase agreements with utilities.
A shift in project financing models is altering the demand landscape. The market is moving from a reliance on direct government grants for research toward public-private partnerships (P3s) where utilities and infrastructure funds co-invest. This model displaces the traditional approach of government-led development. This evolution is most apparent in the next wave of proposed commercial-scale pilot plants, where securing a long-term power purchase agreement is the critical first step.
Ocean Thermal Energy Conversion Plant Market Segmentation
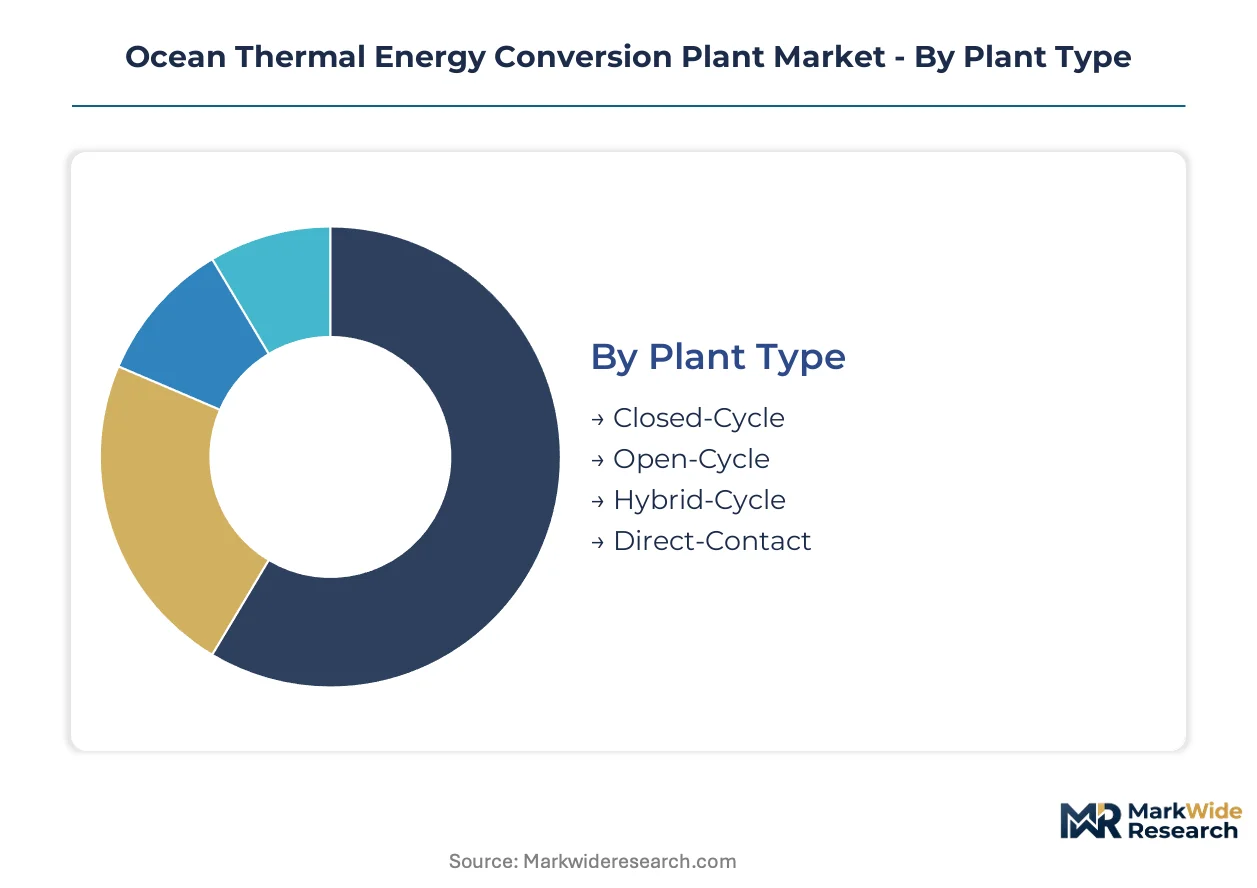
The Ocean Thermal Energy Conversion Plant Market segmentation provides a granular view of the technological approaches, operational scales, and target applications driving industry growth. Understanding these segments is crucial for stakeholders to identify investment opportunities and tailor solutions for specific energy demands and geographical contexts.
Plant Type:
The plant type segmentation highlights the trade-off between established closed-cycle systems and more experimental, higher-potential open-cycle or hybrid designs.
- Closed-Cycle:This dominant plant type utilizes a working fluid, typically ammonia, in a closed loop; warm surface water vaporizes the fluid to drive a turbine, and cold deep water condenses it. Deployment for closed-cycle systems concentrates in island nations and remote coastal areas seeking reliable baseload renewable power.
- Open-Cycle:This system directly flashes warm seawater into low-pressure steam to drive a turbine, with the added benefit of producing desalinated freshwater as a valuable by-product. Demand for open-cycle systems is emerging in arid coastal regions where both electricity and fresh water are critical needs.
- Hybrid-Cycle:This plant type integrates elements from both closed and open cycles, aiming to optimize overall energy conversion efficiency or enhance freshwater production capabilities.
- Direct-Contact:Direct-contact systems involve the direct mixing of warm and cold water streams for heat exchange, often offering a simpler design but presenting specific operational and efficiency challenges.
Mature deployment sits with Closed-Cycle plants. Newer deployment is concentrated in Hybrid-Cycle systems.
Energy Output Capacity:
The energy output capacity segmentation delineates projects by their scale and associated capital expenditure requirements.
- Below 5 MW:These installations primarily serve as research and demonstration platforms, validating component performance and system integration in controlled environments. Research institutions and government agencies in locations like Hawaii and Okinawa utilize these smaller plants for experimental validation.
- Above 15 MW:Projects in this category target commercial-scale electricity generation, designed to provide significant baseload power to regional grids. Utility companies in tropical regions are exploring these larger capacities to displace fossil fuel imports.
- 5-10 MW:This capacity range represents pilot projects bridging research and full commercial deployment, testing scalability and operational endurance.
- 10-15 MW:These plants are often pre-commercial prototypes, addressing the engineering challenges of larger cold water pipe diameters and complex mooring systems.
The market is observing a shift from small-scale research installations to larger commercial projects for grid integration.
End User:
End user segmentation reflects the diverse stakeholders driving OTEC development, from research to commercial deployment.
- Renewable Energy Utilities:These entities procure OTEC-generated electricity for grid integration, seeking stable, non-intermittent renewable power sources. Utilities in island territories are signing long-term power purchase agreements to secure consistent energy supply.
- Research Institutions:Academic and government-funded bodies conduct foundational and applied research into OTEC technology, component innovation, and environmental impacts. Institutions in Japan and the United States receive grants for pilot project development and material science studies.
- Marine Power Developers:These organizations focus on the commercialization and financing of OTEC projects, often forming public-private partnerships for project execution.
- Government Agencies:These bodies provide critical funding, regulatory frameworks, and strategic direction for OTEC development within national energy plans and renewable energy strategies.
While research institutions initially propelled OTEC development, renewable energy utilities are increasingly shaping commercial demand.
Technology:
Technology segmentation highlights the core engineering approaches and innovations underpinning OTEC plant design and performance.
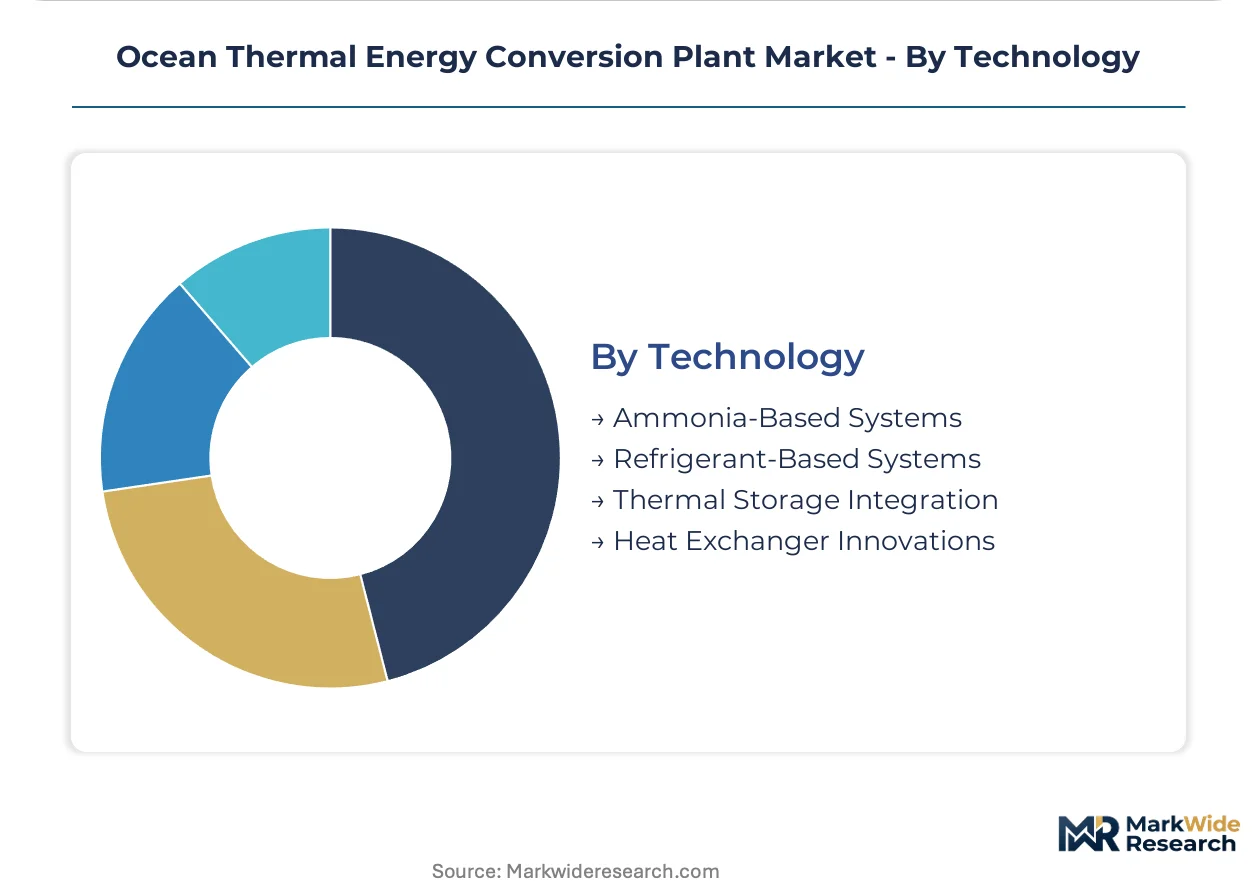
- Ammonia-Based Systems:These systems are characteristic of closed-cycle OTEC plants, leveraging ammonia's excellent thermodynamic properties as the working fluid for efficient power generation. This technology forms the backbone of most commercially viable OTEC designs for baseload applications.
- Heat Exchanger Innovations:Advances in heat exchanger design, including micro-channel geometries and novel corrosion-resistant materials, significantly improve thermal transfer efficiency and reduce overall plant footprint. These innovations are crucial for lowering the capital expenditure and enhancing the economic viability of OTEC projects.
- Refrigerant-Based Systems:This category explores the use of alternative refrigerants as working fluids in closed-cycle OTEC, potentially offering different operational characteristics or environmental profiles.
- Thermal Storage Integration:Incorporating thermal storage solutions aims to enhance the dispatchability of OTEC power, allowing for better grid management and stability for intermittent renewable sources.
Ammonia-based systems continue to provide the foundational technology, while heat exchanger innovations are improving economic feasibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warm ocean currents that create the necessary temperature differential for OTEC operations define the primary geographic scope for this market. Tropical and subtropical regions with stable thermal gradients are key to project viability. These areas are actively pursuing OTEC as a baseload renewable energy solution.
United States
The United States market is driven by energy security needs in its island territories like Hawaii and Guam. The Inflation Reduction Act (IRA) provides significant tax credits, improving project economics. Research and development efforts concentrate around the Natural Energy Laboratory of Hawaii Authority (NELHA) in Kona.
Japan
Japan's OTEC development is spurred by its national energy strategy and a desire for energy independence. METI actively supports pilot projects and integrates OTEC into its renewable energy goals. Commercial feasibility tests are underway in Okinawa, leveraging local deep-sea water resources.
Philippines
Philippine island grids seek stable baseload power to reduce reliance on costly diesel imports. The country's Department of Energy encourages renewable energy diversification and grid modernization. Potential project sites are identified across the Visayas and Mindanao regions, addressing localized energy deficits.
France
French overseas territories offer ideal conditions and a strong policy push for marine renewable energy. National energy strategies, aligned with EU Green Deal objectives, support OTEC pilot projects. Development efforts are notable in French Polynesia and Reunion Island, leveraging marine engineering expertise.
Indonesia
Indonesia, an archipelagic nation, faces unique challenges in providing consistent power to its remote islands. The national government's energy diversification plans prioritize indigenous renewable sources. Eastern Indonesian islands and Sulawesi are considered prime locations for OTEC development.
Ocean Thermal Energy Conversion Plant Market Key Industry Players
Strategic partnerships dominate the current landscape, especially for de-risking high capital expenditure projects and sharing technical expertise. The market structure involves a mix of large marine engineering firms, specialized technology developers, and research institutions. Strategic archetypes include integrators of large-scale platforms, niche component manufacturers focusing on efficiency, and modular system providers targeting specific regional needs. Competitive moves center on forming public-private partnerships, advancing heat exchanger technology, and expanding into new tropical geographies with strong baseload power demand.
Specialists in marine engineering and component development occupy distinct positions within the market. French-based DCNS exemplifies large-scale marine platform design, leveraging extensive naval expertise for complex OTEC structures and deep-sea infrastructure. Makai Ocean Engineering, a US-based firm, represents the archetype of critical component innovation, particularly in advanced heat exchangers and robust cold water pipe technology. OTEC International LLC, also US-based, anchors the segment focused on developing smaller, modular systems tailored for remote island grids and coastal communities, addressing their unique energy independence needs.
| Leading Market Players |
|---|
| NELHA |
| DCNS |
| Makai Ocean Engineering |
| Akuo Energy |
| UTM OTEC |
| OTEC International LLC |
| Bardot Group |
| Global OTEC Resources |
| Bluerise |
| Others |
Cost & Logistics Intelligence
Modular OTEC system deployment is reshaping cost economics and concentrating supply among specialized component manufacturers. This shift enables more predictable project budgeting and streamlined procurement for island nations.
Pricing Analysis
Project warranty and long-term service agreements form a critical component of OTEC plant pricing, often bundled into comprehensive power purchase agreements. Contract-based long-term offtake agreements dominate the market, driven by high upfront capital requirements. Price differentiation stems from plant capacity and the level of customization for specific site conditions. Pricing softness reflects the need to secure initial utility contracts for commercial validation.
Supply Chain Analysis
Heat exchanger component supply rests on specialized manufacturers primarily located in Japan, France, and the United States, leveraging advanced materials expertise. Key material dependencies include corrosion-resistant alloys, high-performance ammonia as a working fluid, and robust piping for deep-sea applications. Single-source vulnerability for certain critical components represents a significant structural risk. Distribution runs through marine engineering firms and EPC contractors who manage complex offshore logistics and installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OTEC market is currently supply-constrained, with limited commercial-scale project deployments driving higher initial costs. The scarcity of established large-scale cold water pipe manufacturing facilities props up early-stage project pricing.
For Market Incumbents:Anchor engineering talent by investing in specialized marine engineering and thermodynamics programs to address workforce scarcity. Consolidate market position through strategic acquisitions of niche component innovators, mitigating the threat from emerging specialized technology entrants. Expand into new tropical geographies like Indonesia and the Philippines, leveraging existing project financing expertise and regional demand.
For New Entrants and Emerging Players:Enter via modular system deployment, targeting smaller island grids and remote coastal communities with containerized, scalable solutions. Focus on hybrid applications, co-locating OTEC with desalination facilities to provide dual value streams of electricity and fresh water. The Pacific island nations represent the most penetrable segment for initial, smaller-scale projects. Partner effectively with local utilities for initial pilot project execution.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized OTEC technology developers given the increasing policy support, such as the US Inflation Reduction Act's tax credits. Long-term viability over the next decade hinges on successful scale-up to commercial capacities and sustained baseload power generation. Acquisition targets should include firms with proven heat exchanger innovations and deep-sea infrastructure expertise. The signal to watch is the successful commissioning of a 10 MW+ commercial plant demonstrating grid stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Long-Term Power Purchase Agreements | Long-term PPAs provide revenue stability for OTEC developers, attracting necessary project financing from utilities. |
| Invest in Advanced Heat Exchanger R&D | Innovations in heat exchanger design reduce capital expenditure and improve overall plant efficiency for commercial viability. |
| Form Public-Private Utility Partnerships | These partnerships de-risk high upfront investment and leverage government support for OTEC project execution. |
| Expand Modular System Manufacturing | Standardized modular OTEC units enable faster deployment and lower per-unit costs for remote island grids. |
| Integrate with Desalination or Green Hydrogen | Hybrid applications create additional revenue streams, enhancing the economic case for OTEC plant development. |
Research Approach
Trade association data, regulatory filings from the US Department of Energy and Japan's METI, and academic research papers anchored secondary inputs. This analysis combined extensive secondary research with primary interviews conducted with utility planning officers, EPC contractors, marine engineers, and government agency representatives. Bottom-up data collection was triangulated with top-down market sizing approaches.
Value and volume outputs were modeled at a granular level across plant type, energy output capacity, end user, and technology segments. Regional regulatory frameworks and deep-sea water availability provided additional modeling dimensions. Compound annual growth rates were derived from historical trends and projected technological advancements over the projection horizon. Heat exchanger efficiency gains served as a key forecast input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unexpected capital expenditure escalation or prolonged permitting delays. Forecasts reflect assumptions regarding technological maturity and policy continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Europe Thermal Power Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Southeast Asia Power Generation EPC Market
Power Generation
Cogeneration System Market
Power Generation
Marine Power Plant Market
Power Generation
Global Power Generation Market
Power Generation
Wind Power EPC Market
Power Generation
Thermal Power Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Subsea Power Grid System Market
Power Generation
Aeroderivative Gas Turbine Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Power Plant EPC Market
Power Generation
Global Power to Gas Market
Power Generation
Global Gas Turbines Market
Power Generation
Mobile Power Plant Market