
 Canada Electric Vehicle Battery Anode Market | 2026-2036
Canada Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Vehicle Battery Anode Market Insights
UL 2580 certification for EV battery cell safety is unwinding competitive access across the Canada electric vehicle battery anode landscape. Northern Graphite Corporation leverages its Lac-des-Iles mine and spherical graphite facility to anchor domestic feedstock security. NEO Battery Materials LTD differentiates through silicon oxide anode R&D targeting energy density gains for cold-climate performance. POSCO Future M competes via its Quebec-based cathode-anode integrated supply partnerships with Detroit Three automakers.
Canada electric vehicle battery anode denotes the negative electrode material—typically graphite, silicon, or lithium compounds with 300-350 mAh/g theoretical capacity—engineered through spheroidization and carbon coating to enable lithium-ion intercalation during charge cycles. Spheroidization and coating processes dominate manufacturing value capture due to equipment intensity and yield sensitivity. Graphite material type leads current procurement volumes while silicon blends represent the fastest-growing segment as OEMs target 20-minute fast-charge compatibility. Tier-1 suppliers occupy the deepest margin pools by qualifying anode formulations directly with Windsor and Oakville assembly plants.
Health Canada, Transport Canada, and Environment and Climate Change Canada jointly shape anode chemistry approvals through battery safety standards and end-of-life recycling mandates under the Canadian Environmental Protection Act. The Canadian Standards Association's evolving EV battery testing protocols are forcing anode suppliers to validate thermal runaway propagation resistance before OEM qualification. Stakeholders must monitor Ontario's critical minerals strategy disbursement timelines and federal clean technology investment tax credit eligibility rules to secure offtake positioning.
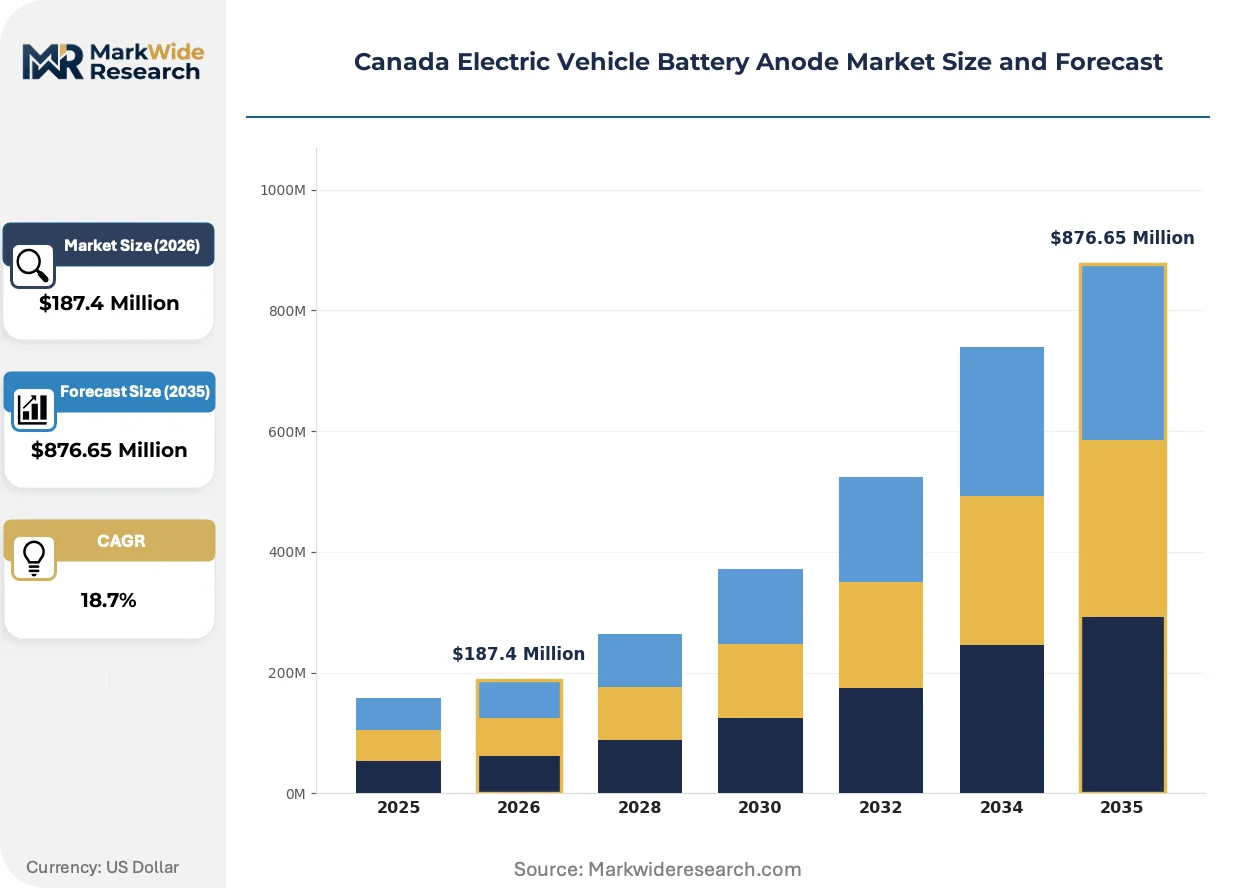
Market Dynamics
Federal zero-emission vehicle mandates are compressing anode qualification timelines as Windsor and Oakville assembly plants demand localized supply chains. Health Canada's evolving battery safety protocols and Ontario's critical minerals processing investments are concentrating feedstock demand around the Windsor-Toronto corridor.
Growth Catalysts
- Clean Technology Investment Tax Credit:Federal eligibility rules for anode production equipment are accelerating capital deployment into Ontario-based spheroidization facilities.
- Silicon oxide anode R&D:Cold-climate energy density requirements from Canadian fleet operators are pulling advanced anode formulations through qualification pipelines faster than graphite-only alternatives.
- Quebec cathode-anode integration:Integrated supply partnerships with Detroit Three automakers are creating captive demand anchors for anode producers with co-located cathode capabilities.
Market Restraints
- Spherical graphite supply concentration:Domestic spheroidization capacity bottlenecks at Ontario processing nodes create feedstock security vulnerabilities for non-integrated anode suppliers.
- UL 2580 certification timelines:Extended cell safety validation periods under Canadian Standards Association protocols delay OEM qualification by 18-24 months.
- Synthetic graphite cost volatility:Petroleum needle coke and metallurgical coke input price swings compress margin predictability for carbon-coated anode producers.
Strategic Opportunities
- Manitoba-Saskatchewan critical minerals corridor:Underdeveloped graphite exploration tenements offer first-mover positioning for vertically integrated anode feedstock security.
- End-of-life recycling mandates:Canadian Environmental Protection Act battery recycling rules create closed-loop anode material recovery revenue streams.
- Silicon-graphite composite convergence:Blending silicon oxide with spherical graphite enables 20-minute fast-charge compatibility for cold-climate fleet applications.
Industry Challenges
- Spheroidization equipment operator scarcity:Specialized millwright and process engineering talent gaps constrain yield optimization at Ontario carbon coating facilities.
- Thermal runaway propagation testing backlog:Health Canada validation queue compression delays anode formulation approvals for tier-2 suppliers seeking Windsor assembly plant qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Vehicle Battery Anode Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium, Conductive Additives Manufacturing Process: Spheroidization, Coating, Synthesis, Casting End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Umicore N.V., Northern Graphite Corporation, NEO Battery Materials LTD, NextSource Materials Inc., Targray Technology International Inc., Nanode Battery Technologies, HPQ Silicon, POSCO Future M, NextStar Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Vehicle Battery Anode Market Trends and Innovations
Active materials engineering and regulatory compliance automation are compressing product development cycles. Three interconnected developments are redefining competitive positioning across the value chain.
Silicon oxide anode formulations are supplanting pure graphite in premium electric vehicle platforms. Tier-1 suppliers serving Oakville and Windsor assembly plants are accelerating silicon blend adoption to meet 20-minute fast-charge specifications. Energy density gains from silicon intercalation are compressing pack size requirements while extending cold-climate range performance.
Health Canada and Transport Canada joint battery safety standards are forcing anode suppliers to pre-validate thermal runaway propagation resistance. The Canadian Standards Association's evolving EV battery testing protocols require documented cell-level failure mode analysis before OEM qualification. Tier-2 suppliers without in-house abuse testing capabilities face exclusion from Windsor-Toronto corridor procurement.
Direct qualification relationships between anode formulators and Windsor assembly plants are displacing distributor-mediated supply chains. Tier-1 suppliers are establishing technical service laboratories adjacent to OEM battery pack engineering centers. This channel compression is most visible in Ontario, where proximity to assembly plants determines qualification access.
Canada Electric Vehicle Battery Anode Market Segmentation
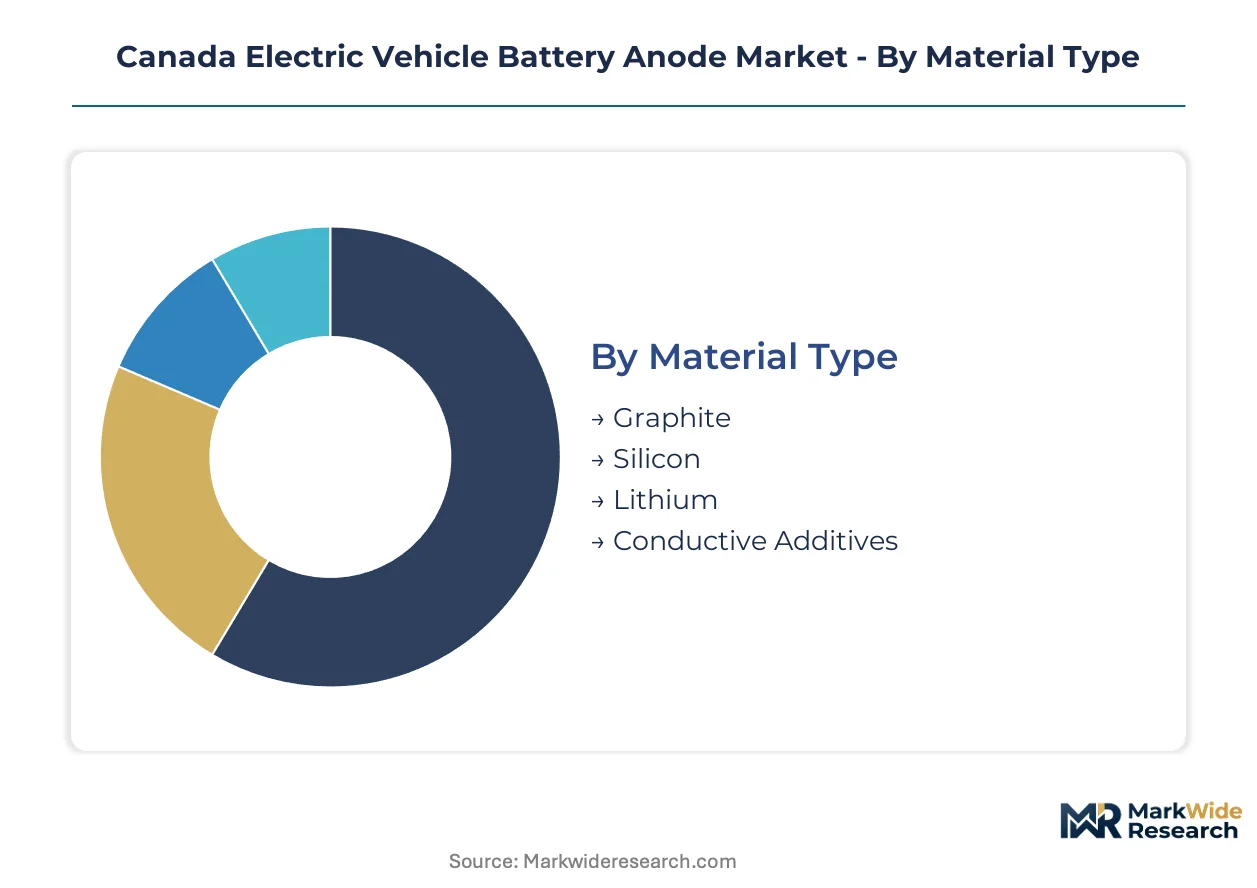
Segmentation of the Canada electric vehicle battery anode market reveals distinct procurement patterns across material chemistry, manufacturing intensity, and channel configuration. Windsor-Toronto corridor assembly plants drive qualification requirements that reshape competitive access for each segment category.
Material Type:
Graphite anode procurement concentrates around Ontario processing facilities serving domestic OEM qualification pipelines, while silicon formulations attract export-oriented R&D investment targeting cold-climate performance specifications.
- Graphite:Spherical natural and synthetic graphite compositions with 300-350 mAh/g theoretical capacity dominate current procurement volumes. Ontario-based spheroidization facilities at Lac-des-Iles and emerging Quebec processing nodes anchor domestic feedstock security for Windsor assembly plant contracts.
- Silicon:Silicon oxide and silicon-graphite composite formulations enable 20-minute fast-charge compatibility demanded by Canadian fleet operators. Health Canada battery safety validation timelines compress qualification windows for silicon blend suppliers seeking tier-1 OEM status.
- Lithium:Lithium titanate oxide variants serve niche cold-start applications in northern climate zones.
- Conductive Additives:Carbon black and CNT dispersions optimize electron transport in high-loading silicon composite electrodes.
Graphite holds the largest share; momentum sits with silicon.
Manufacturing Process:
Process selection determines capital intensity and yield sensitivity, with equipment-heavy stages capturing disproportionate margin pools.
- Spheroidization:Mechanical rounding of flake graphite to 10-20 micron spherical morphology concentrates value capture. Ontario millwright talent scarcity constrains yield optimization at carbon coating facilities serving Windsor-Toronto corridor demand.
- Coating:Pitch and resin carbon coating of spherical graphite enhances first-cycle efficiency and structural integrity during lithium intercalation. Direct qualification relationships with Oakville battery pack engineering centers favor coating specialists with adjacent technical service laboratories.
- Synthesis:Chemical vapor deposition and thermal treatment routes produce synthetic graphite precursors from petroleum needle coke.
- Casting:Slurry-based electrode casting integrates anode materials into copper foil current collectors for cell assembly.
Spheroidization commands the deepest margin pools; coating is expanding most quickly.
End User:
Customer type determines qualification depth, with direct OEM relationships displacing distributor-mediated supply chains across the value chain.
- OEMs:Ford, Stellantis, and General Motors battery pack engineering centers at Windsor and Oakville assembly plants demand documented thermal runaway propagation resistance under Canadian Standards Association protocols. Health Canada validation queues compress anode formulation approval timelines for direct suppliers.
- Tier-1 Suppliers:Cell manufacturers and battery pack integrators qualify anode formulations for platform-specific energy density and fast-charge specifications. Quebec cathode-anode integrated supply partnerships create captive demand anchors for qualified material providers.
- Aftermarket Providers:Replacement battery suppliers serve secondary vehicle markets and energy storage retrofits.
- Research Institutions:National Research Council and university laboratories pilot silicon-graphite composite convergence for next-generation cold-climate performance.
OEMs dominate procurement volume; tier-1 suppliers are climbing the fastest.
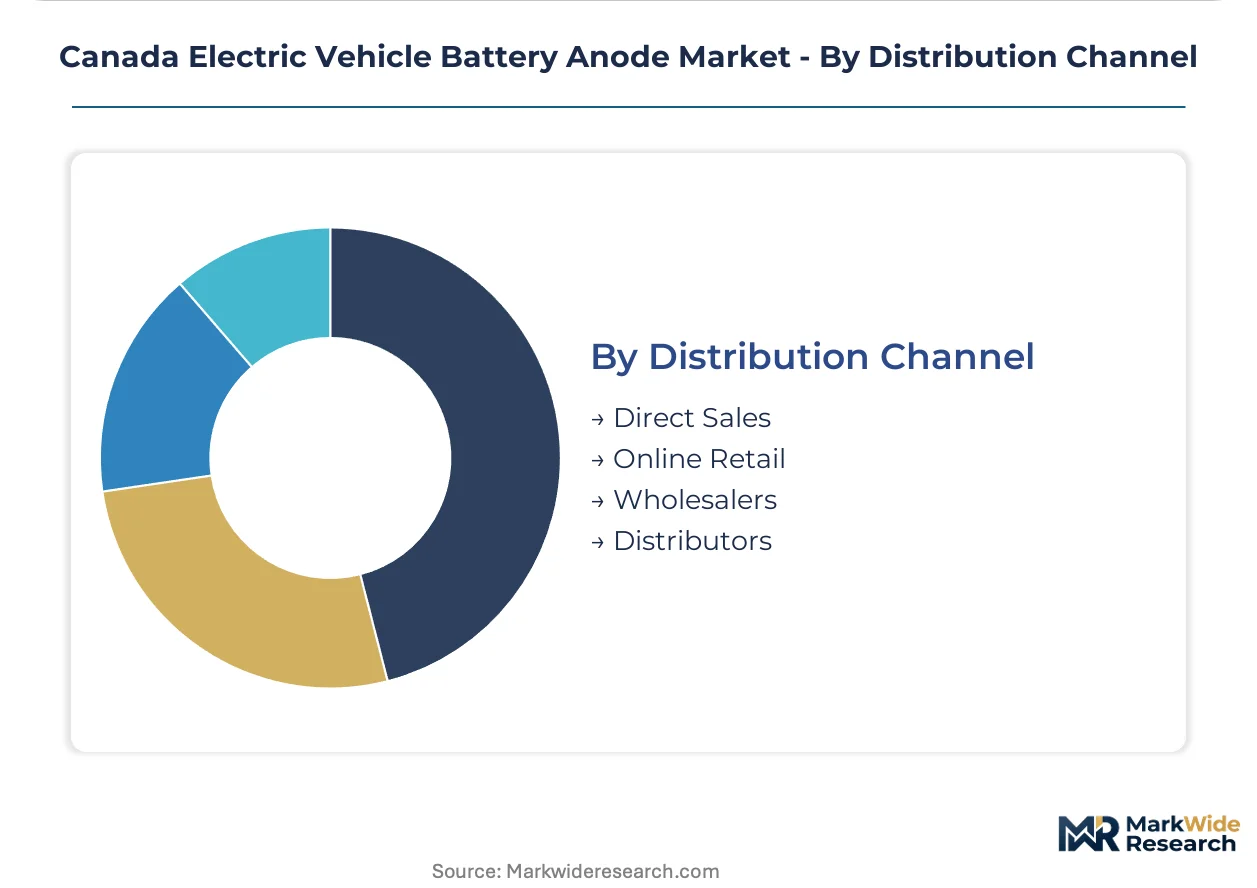
Distribution Channel:
Channel structure reflects qualification complexity, with technical service requirements favoring direct relationships over arm's-length transactions.
- Direct Sales:Technical service laboratories adjacent to Windsor and Oakville battery pack engineering centers enable formulation co-development and rapid qualification iteration. POSCO Future M and integrated cathode-anode producers leverage direct channels to secure Detroit Three automaker contracts.
- Distributors:Regional material handlers serve tier-2 suppliers and research institutions with standardized graphite formulations. Spherical graphite supply concentration at Ontario processing nodes limits distributor margin capture for non-integrated anode suppliers.
- Wholesalers:Bulk material aggregators supply conductive additives and processing chemicals.
- Online Retail:Digital platforms serve prototype quantities and research-grade materials.
Direct sales anchor revenue concentration; distributors show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal zero-emission vehicle mandates and Ontario's critical minerals strategy are concentrating anode demand within Canada, with provincial processing investments and Health Canada safety protocols shaping sub-regional competitive access.
Ontario
Windsor and Oakville assembly plants anchor procurement volume for spherical graphite and silicon anode formulations. Health Canada battery safety validation queues compress qualification timelines for suppliers seeking direct OEM relationships. The Windsor-Toronto corridor hosts spheroidization facilities and technical service laboratories serving Detroit Three automaker battery pack engineering centers.
Quebec
Integrated cathode-anode supply partnerships create captive demand anchors for material producers with co-located processing capabilities. The province's critical minerals processing investments attract foreign direct investment from Korean and Japanese battery material specialists. Montreal and Bécancour industrial zones concentrate precursor chemical synthesis and carbon coating operations.
British Columbia
Graphite exploration tenements in the province's interior offer feedstock security potential for vertically integrated anode producers. Transport Canada battery transport regulations influence material handling infrastructure investments at Vancouver port facilities. The province's clean technology tax credit eligibility rules accelerate capital deployment into pilot-scale spheroidization operations.
Alberta
Petroleum needle coke availability from oil sands upgrading operations supports synthetic graphite precursor supply for carbon-coated anode production. The province's emerging critical minerals strategy targets downstream processing investment attraction. Edmonton and Calgary serve as logistics hubs for metallurgical coke distribution to Ontario coating facilities.
Manitoba-Saskatchewan Corridor
Underdeveloped graphite exploration tenements offer first-mover positioning for anode feedstock security beyond Ontario-Quebec concentration. Prairie province mining regulations and provincial environmental assessment timelines shape project development cadence. Winnipeg and Saskatoon anchor regional logistics for material transport to Ontario processing nodes.
Canada Electric Vehicle Battery Anode Market Competitive Landscape
Listed leaders compete with private specialists across capital access and qualification speed dimensions. The vendor base spans integrated mining-to-coating operators, R&D-focused material innovators, and Asian battery material multinationals with Canadian partnership structures. Three archetypes dominate: domestic feedstock-integrated producers, silicon anode technology specialists, and cathode-anode integrated Korean-Japanese players. Capacity expansion into Ontario spheroidization facilities and direct qualification relationships with Windsor assembly plants represent the dominant competitive moves.
Within the domestic feedstock-integrated tier, Northern Graphite Corporation exemplifies vertical control from mine to spherical graphite production. NEO Battery Materials LTD occupies a position among silicon oxide anode R&D specialists targeting cold-climate energy density specifications. POSCO Future M anchors the multinational partnership archetype through Quebec-based cathode-anode integrated supply structures with Detroit Three automakers.
| Leading Market Players |
|---|
| Umicore N.V. |
| Northern Graphite Corporation |
| NEO Battery Materials LTD |
| NextSource Materials Inc. |
| Targray Technology International Inc. |
| Nanode Battery Technologies |
| HPQ Silicon |
| POSCO Future M |
| NextStar Energy |
| Others |
Pricing and Supply Chain Analysis
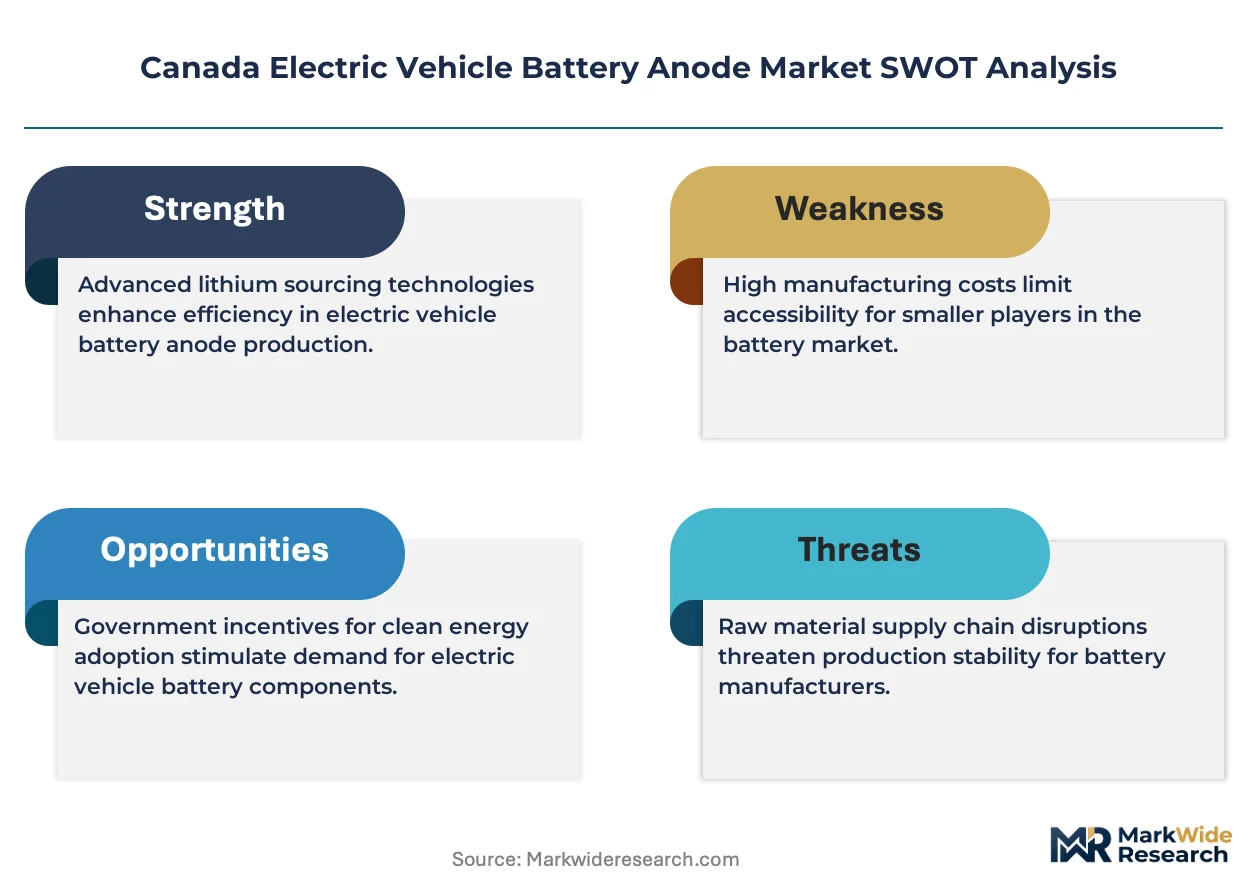
Silicon oxide substitution for spherical graphite in premium anode formulations simultaneously concentrates procurement power around Ontario coating facilities and compresses margin structures for synthetic graphite producers tethered to petroleum needle coke volatility. This chemistry shift rewards integrated suppliers with captive spheroidization capacity while exposing non-integrated formulators to feedstock security premiums.
Pricing Analysis
Certification level under UL 2580 and Canadian Standards Association protocols creates the primary spread between tier-1 qualified suppliers and tier-2 aspirants. Pricing stratifies across premium, standard, and economy tiers based on qualification depth and volume commitment scale. Cost compression in synthetic graphite feedstocks is intensifying because Alberta petroleum needle coke availability fluctuates with oil sands upgrading schedules. Fleet procurement teams at Windsor assembly plants exhibit highest price sensitivity, while OEM battery pack engineering centers prioritize thermal runaway propagation guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of spherical graphite feedstock dominates inventory strategy among Ontario coating facilities seeking to buffer against Lac-des-Iles mine output variability. Supply concentrates in Canada, China, and South Korea for spheroidized graphite anode materials. The value chain draws from Lac-des-Iles spherical graphite, Quebec cathode-anode integration partnerships, and Korean-Japanese carbon coating equipment imports. Single-source vulnerability at Ontario spheroidization nodes threatens feedstock security for non-integrated suppliers. Distribution runs through direct technical service relationships with Windsor and Oakville battery pack engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal zero-emission vehicle mandates and Health Canada battery safety protocol evolution constitute a dual regulatory inflection accelerating market disruption. Technology winners will capture qualification priority at Windsor-Toronto corridor assembly plants.
For Market Incumbents: Secure spheroidization capacity expansion in Ontario before millwright talent scarcity worsens yield optimization constraints. Lock long-term offtake agreements with Detroit Three automakers to anchor volume against Korean-Japanese cathode-anode integrated competitors. UL 2580 certification investment represents the critical defensive lever. For New Entrants and Emerging Players: Differentiate on silicon-graphite composite formulations targeting 20-minute fast-charge specifications for cold-climate fleet applications. Manitoba-Saskatchewan graphite exploration tenements offer first-mover feedstock security positioning beyond Ontario-Quebec concentration. Direct technical service laboratory placement adjacent to Oakville battery pack engineering centers accelerates qualification iteration. For Investors and Strategic Acquirers: Health Canada validation queue compression reshapes the acquisition landscape toward tier-2 suppliers with pre-submitted thermal runaway propagation documentation. Five-to-ten year viability hinges on cathode-anode integration capabilities or captive spherical graphite feedstock. Watch Ontario critical minerals strategy disbursement timelines as inflection signal for capital deployment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Spheroidization Capacity Expansion | Ontario-based mechanical rounding facilities capture margin from Windsor-Toronto corridor demand concentration. |
| Silicon Oxide Anode R&D Investment | Cold-climate energy density gains accelerate qualification pipelines for premium OEM platforms. |
| Cathode-Anode Integration Partnership | Quebec-based co-located processing secures captive demand anchors with Detroit Three automakers. |
| Direct OEM Technical Service Placement | Adjacent laboratories to Oakville battery pack engineering centers enable formulation co-development. |
| Critical Minerals Feedstock Security | Manitoba-Saskatchewan graphite tenements offer vertical control beyond Ontario processing node concentration. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in documented supply chain realities. The research team conducted structured discussions with spherical graphite procurement leads at Windsor assembly plants, carbon coating facility millwright supervisors, Health Canada battery safety protocol officers, and Quebec cathode-anode integration project managers. Secondary validation drew from Transport Canada zero-emission vehicle mandate filings, Canadian Standards Association EV battery testing protocol drafts, Ontario critical minerals strategy disbursement records, and Environment and Climate Change Canada recycling mandate guidance. Bottom-up capacity assessments at Lac-des-Iles and emerging processing nodes were triangulated against top-down OEM procurement forecasts.
Sensitivity analysis around silicon blend adoption rates and spheroidization yield assumptions frames the projection uncertainty. The analytical model spans material chemistry, manufacturing process intensity, and channel configuration dimensions across the projection horizon. CAGRs were derived from segment-level volume build-ups calibrated to federal ZEV mandate penetration curves and OEM platform rollout schedules. Key inputs include Health Canada validation queue throughput estimates and Ontario-based equipment capital deployment timelines under clean technology investment tax credit eligibility.
The analysis sits within stated boundaries; outcomes outside sustained federal ZEV mandate enforcement or Health Canada protocol stability would require recalibration. Forecasts reflect documented assumptions about silicon-graphite composite convergence speed and cathode-anode integration partnership durability. Revision becomes warranted when UL 2580 certification timeline compression crosses thresholds that exclude tier-2 supplier participation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market