
 Proton Exchange Membrane Fuel Cell (PEMFC) Market | 2026-2036
Proton Exchange Membrane Fuel Cell (PEMFC) Market Size, Share, and Industry Trends Forecast 2026-2036
Proton Exchange Membrane Fuel Cell (PEMFC) Market Intelligence
Increased investment in Chinese bipolar plate manufacturing capacity is restructuring the competitive landscape for global membrane electrode assembly suppliers. Ballard Power Systems leverages its deep expertise in heavy-duty motive applications for buses and trucks. Plug Power Inc. specializes in integrated hydrogen solutions for material handling and stationary power. Doosan Fuel Cell Co., Ltd. focuses its strategy on developing large-scale stationary fuel cell systems for utility and commercial building power generation.
A proton exchange membrane fuel cell is an electrochemical device that converts the chemical energy of hydrogen directly into electricity. Its core component is a polymer electrolyte membrane that facilitates proton transport between the anode and cathode, requiring operating temperatures typically below 100°C. The primary purpose is to provide a clean, efficient power source with only heat and water as byproducts. Automotive fuel cells for commercial vehicles represent a high-growth product type, while technology advancements focus on reducing platinum loading in catalysts and improving gas diffusion layer performance.
Regulatory frameworks such as the EU Green Deal and the US Inflation Reduction Act create powerful financial incentives for PEMFC adoption in transport and industry. Concurrently, standards from the International Organization for Standardization (ISO) and the International Electrotechnical Commission (IEC) ensure component interoperability and safety. Securing a stable supply chain for critical raw materials, including platinum-group metals and specialized polymers, remains the central strategic challenge for manufacturers aiming to scale production.
Market Dynamics
Intense policy support for decarbonization is the central force shaping the market, accelerating investment in manufacturing and infrastructure. This push from frameworks like the US Inflation Reduction Act and the EU Green Deal directly counteracts the high capital costs restraining widespread adoption.
Growth Catalysts
- Government Mandates:The EU Green Deal's transport decarbonization targets create powerful, non-negotiable demand for zero-emission solutions, directly benefiting PEMFCs in heavy-duty vehicles and buses across member states.
- Catalyst Technology Advancement:Innovations in catalyst formulation are successfully reducing the required loading of expensive platinum-group metals, lowering the bill of materials and making fuel cell stacks more commercially viable.
- Heavy-Duty Vehicle Demand:The operational requirements of long-haul trucking and municipal bus fleets, which demand long range and fast refueling, align perfectly with the technical capabilities of PEMFC systems over battery-electric alternatives.
Market Restraints
- Platinum Price Volatility:The high and fluctuating cost of platinum-group metals, which are essential for catalysts, creates significant cost uncertainty and presents a structural barrier to achieving price parity with incumbent technologies.
- Hydrogen Infrastructure Gap:A lack of widespread, reliable, and publicly accessible hydrogen production and refueling infrastructure remains the single largest obstacle to the mass adoption of PEMFC-powered vehicles.
- Membrane Durability:Ensuring long-term durability and performance stability of the polymer electrolyte membrane under real-world operating conditions, including frequent start-stop cycles and temperature variations, is a persistent technical restraint.
Strategic Opportunities
- Maritime and Aviation Sectors:Developing high-power-density PEMFC systems for auxiliary power units and eventually primary propulsion in the maritime and regional aviation sectors represents a significant long-term growth frontier.
- Stationary Power in Emerging Economies:Deploying PEMFCs for grid stabilization and reliable backup power in regions with developing electricity infrastructure, such as parts of Southeast Asia, offers a substantial new market.
- Green Hydrogen Integration:Coupling PEMFC power generation with on-site green hydrogen production from renewable sources like solar and wind allows for the creation of fully integrated, self-sufficient clean energy ecosystems for industrial parks and data centers.
Industry Challenges
- Component Supply Chain Scalability:Manufacturers face the operational challenge of rapidly scaling up production of precision components like gas diffusion layers and bipolar plates without compromising quality or consistency.
- Standardization of Components:The absence of globally harmonized ISO and IEC standards for key components and refueling connectors creates friction, increases design costs, and slows market development.
- High Manufacturing Capex:The substantial capital investment required to build and automate gigawatt-scale factories for fuel cell stack and system production presents a high barrier to entry and expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proton Exchange Membrane Fuel Cell (PEMFC) Market |
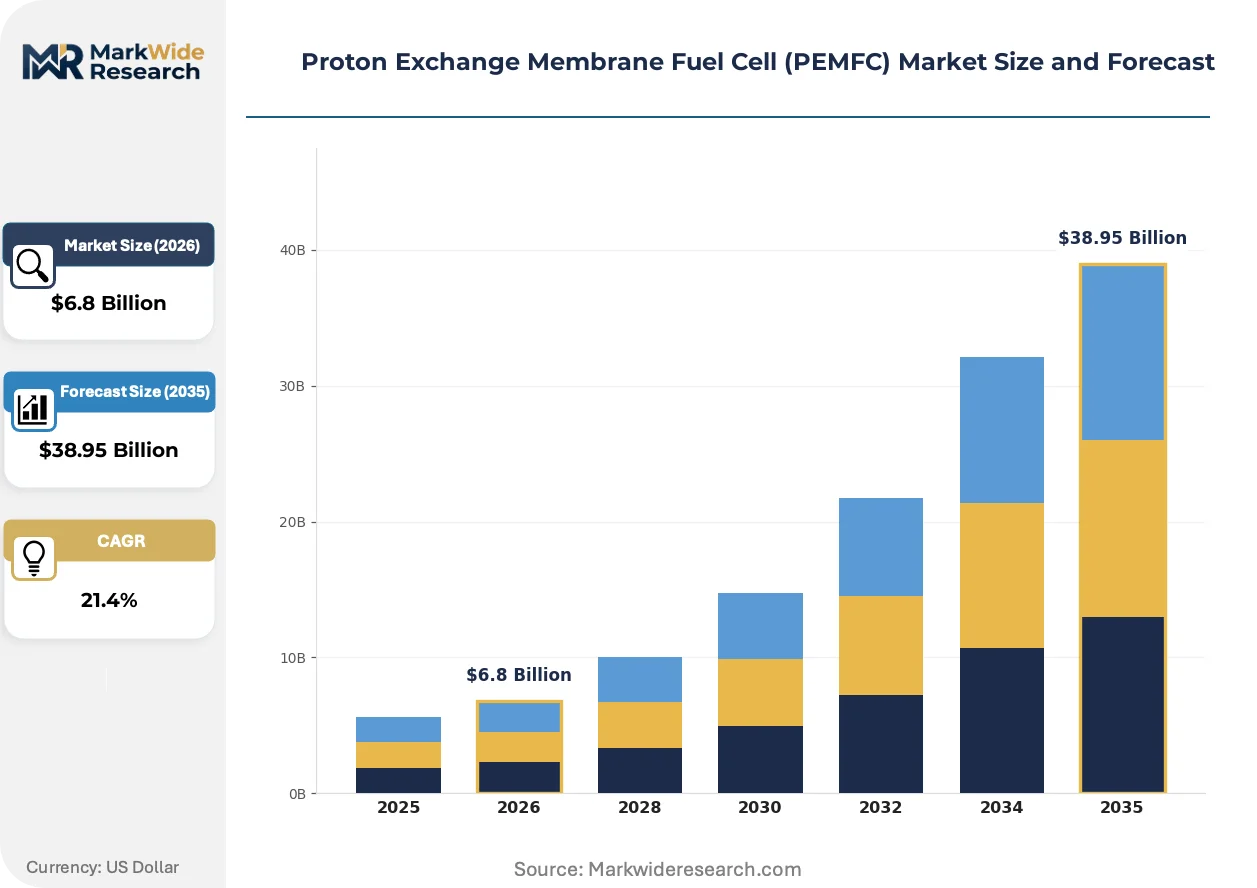
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $38.95 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Fuel Cells, Portable Fuel Cells, Stationary Fuel Cells, Backup Power Systems, Material Handling Equipment Technology: Membrane Electrode Assembly, Bipolar Plates, Gas Diffusion Layer, Catalysts, Humidifiers Application: Light-Duty Vehicles, Commercial Vehicles, UAVs, Residential Power, Telecommunications End User: Vehicle Manufacturers, Logistics Companies, Renewable Energy Providers, Emergency Services |
| Companies Covered | Nuvera Fuel Cells, LLC, Doosan Fuel Cell Co., Ltd., Ballard Power Systems, Nedstack Fuel Cell Technology BV, Intelligent Energy Limited, Plug Power Inc., ITM Power PLC, W. L. Gore & Associates, Inc., Proton Motor Fuel Cell GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proton Exchange Membrane Fuel Cell (PEMFC) Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from laboratory-scale development toward industrial-scale manufacturing. This transition emphasizes cost-down engineering, supply chain localization, and performance optimization for specific high-growth commercial applications.
Advanced catalyst-coated membranes (CCMs) are being engineered to minimize platinum content while maintaining high electrochemical activity. Heavy-duty vehicle OEMs are the primary adopters, integrating these next-generation components into their powertrain development cycles. This critical innovation is electrifying the commercial transport sector by improving the economic case for replacing diesel engines in long-haul trucks.
China's 'dual carbon' national strategy provides direct subsidies and policy preference for hydrogen-powered vehicles in municipal and logistics fleets. This creates a vast and protected domestic market, spurring massive investment in local PEMFC manufacturing capacity. Consequently, global component suppliers are compelled to establish or expand production within China to compete effectively.
Fleet operators are progressively demanding fully integrated hydrogen powertrain systems rather than purchasing standalone fuel cell stacks. This behavioral shift disrupts the component-centric sales model, forcing stack manufacturers to either partner with system integrators or develop their own complete vehicle propulsion solutions. This trend is most visible in the European commercial vehicle segment, where total cost of ownership is the primary procurement driver.
Proton Exchange Membrane Fuel Cell (PEMFC) Market Segmentation
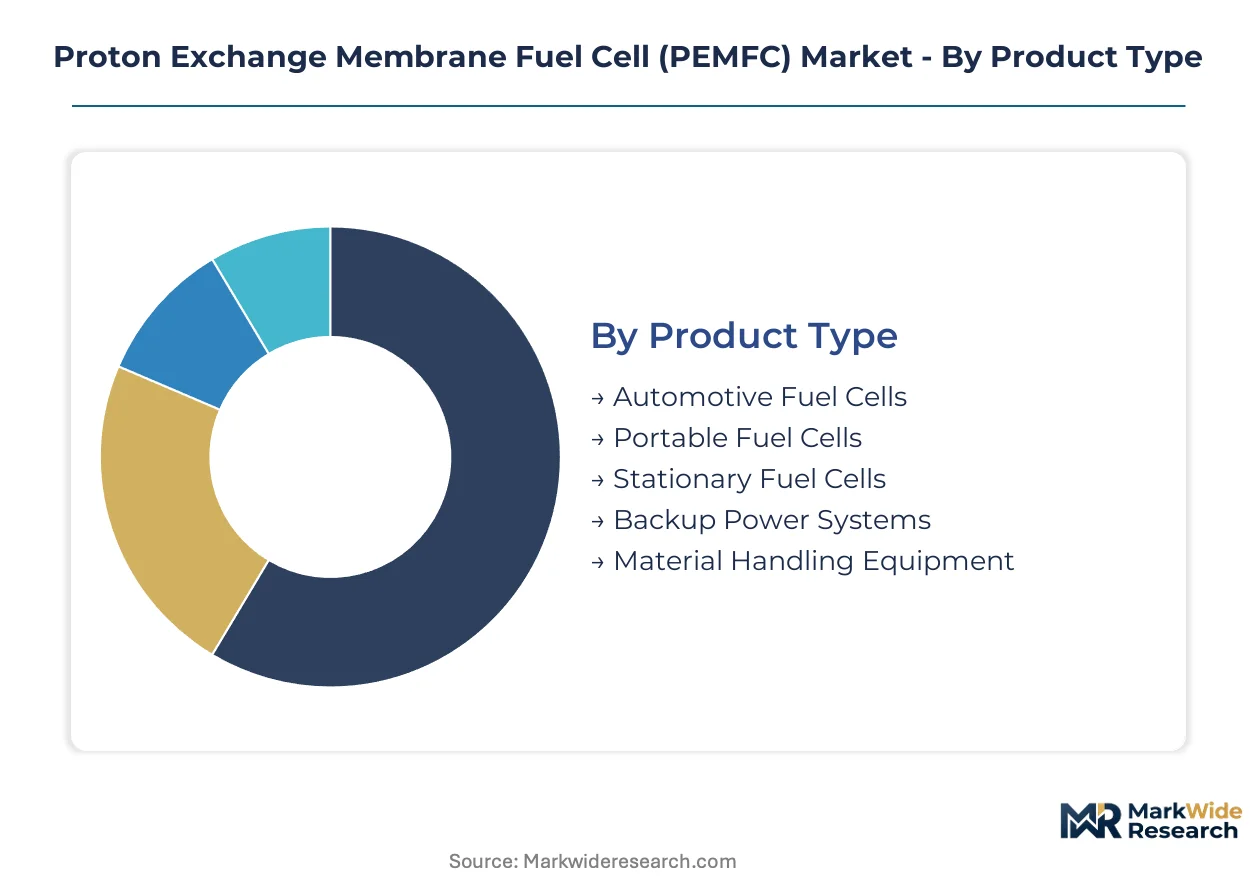
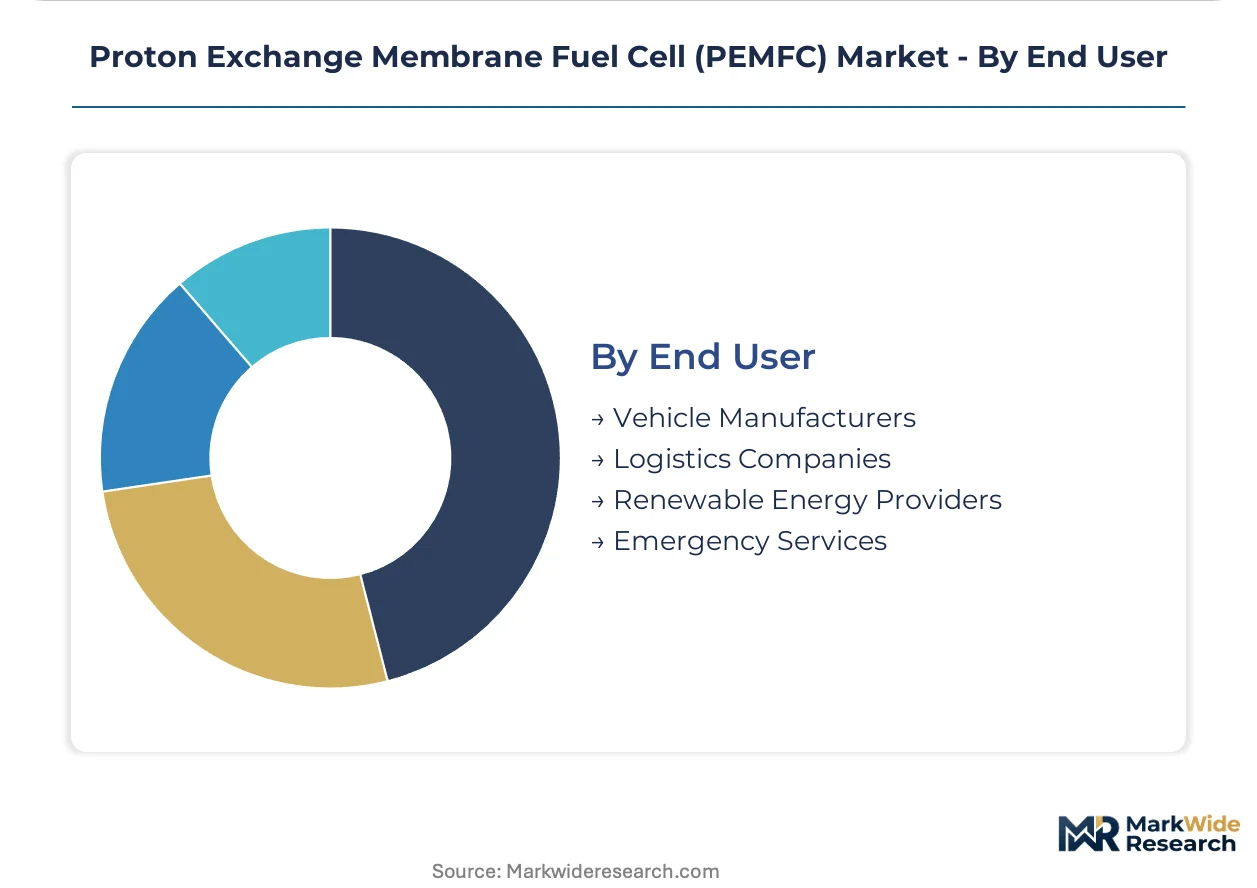
The Proton Exchange Membrane Fuel Cell (PEMFC) market exhibits distinct dynamics when segmented by product type, core technology, end-use application, and primary end-user. This segmentation highlights the diverse technical requirements and commercial imperatives driving PEMFC adoption across various sectors. Understanding these distinctions is crucial for strategic investment and targeted product development.
Product Type:
What differentiates buyers in this category is the power output requirement and operational environment for the fuel cell system.
- Automotive Fuel Cells:These high-power PEMFC systems are engineered for vehicle propulsion, converting hydrogen directly into electricity to drive electric motors. Demand concentrates heavily in Germany and China, driven by stringent emissions regulations and government mandates for zero-emission commercial transport.
- Stationary Fuel Cells:Stationary PEMFCs provide continuous or backup power for buildings, grid support, and distributed generation, designed for long operational lifespans. Their demand is concentrating in South Korea and Japan, where energy security concerns and grid stability initiatives are strong drivers.
- Portable Fuel Cells:Portable PEMFCs deliver compact, lightweight power for consumer electronics and small-scale off-grid applications.
- Backup Power Systems:These systems offer reliable, emissions-free emergency power for critical infrastructure like data centers and telecommunication networks.
- Material Handling Equipment:PEMFCs power forklifts and other industrial vehicles, providing extended runtimes and rapid refueling in logistics facilities.
Volume sits with Automotive Fuel Cells; growth tilts toward Stationary Fuel Cells.
Technology:
Component complexity and manufacturing precision define the competitive landscape within the technology segments.
- Membrane Electrode Assembly:The MEA is the central electrochemical component, comprising a proton exchange membrane sandwiched between catalyst layers and gas diffusion layers. Investment in MEA manufacturing is concentrating in Germany and China, driven by the need to localize critical supply chains for domestic PEMFC production.
- Catalysts:Catalysts, typically platinum-group metals, facilitate the electrochemical reactions at the anode and cathode, enabling efficient energy conversion. Research and development in catalyst technology is concentrating in Japan and the US, aiming to reduce platinum loading and lower material costs.
- Bipolar Plates:Bipolar plates manage reactant distribution, heat removal, and electrical current collection within the fuel cell stack.
- Gas Diffusion Layer:GDLs facilitate uniform gas distribution and water management, crucial for optimal fuel cell performance and durability.
- Humidifiers:Humidifiers ensure the proton exchange membrane remains hydrated, maintaining high proton conductivity and operational efficiency.
The technology segment with the highest capital expenditure is Membrane Electrode Assembly; Catalysts exhibit the steepest expansion trajectory.
Application:
The operational requirements and regulatory drivers dictate specific PEMFC system designs across various applications.
- Commercial Vehicles:This application segment includes heavy-duty trucks, buses, and other commercial transport vehicles requiring high power output and long range. Demand for PEMFCs in commercial vehicles is concentrating in the EU and China, propelled by stringent decarbonization mandates and subsidies.
- Light-Duty Vehicles:Light-duty vehicles comprise passenger cars and smaller utility vehicles, where PEMFCs compete with battery-electric powertrains. Japan and South Korea represent the primary markets for light-duty PEMFC vehicle deployment, supported by early infrastructure investments.
- Telecommunications:PEMFCs provide reliable backup power for cellular towers and remote communication infrastructure, ensuring network continuity.
- Residential Power:PEMFC systems offer clean, distributed power generation for homes, particularly in regions with high electricity costs or grid instability.
- UAVs:PEMFCs enable extended flight times and higher payloads for unmanned aerial vehicles compared to traditional battery systems.
Commercial Vehicles command the largest share of current demand; UAVs are gaining share fastest.
End User:
The procurement models and integration capabilities define the engagement strategies for different end-user groups.
- Vehicle Manufacturers:These end-users integrate PEMFC stacks and systems into their vehicle platforms, requiring robust supply chain partnerships and technical support. Collaboration between vehicle manufacturers and fuel cell suppliers is intensifying in Germany and the US, driven by new product development cycles for heavy-duty platforms.
- Logistics Companies:Logistics firms deploy PEMFC-powered material handling equipment and commercial fleets to reduce operational emissions and improve refueling efficiency. Adoption by logistics companies is particularly strong in North America and Europe, supported by incentives for green fleet transitions.
- Renewable Energy Providers:These providers use PEMFCs for grid stabilization and energy storage, coupling them with intermittent renewable sources like solar and wind.
- Emergency Services:Emergency services utilize PEMFCs for mobile power generation and backup, ensuring critical operations during outages or in remote areas.
Vehicle Manufacturers represent the largest purchasing segment; Renewable Energy Providers show significant future potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's significant reserves of platinum-group metals influence the global PEMFC market, impacting catalyst pricing and supply chain stability. These critical materials are essential for fuel cell catalyst production worldwide. Manufacturers across continents depend on a secure supply for scaling PEMFC technology.
Germany
Germany's robust automotive industry drives substantial demand for PEMFCs in heavy-duty vehicles and buses. The EU Green Deal mandates stringent transport decarbonization targets, accelerating PEMFC adoption. Manufacturing investment concentrates in key automotive and industrial centers across Germany for fuel cell component production.
China
China's vast domestic market for hydrogen-powered vehicles creates immense PEMFC demand, especially in municipal and logistics fleets. The nation's 'dual carbon' national strategy provides direct subsidies and policy preference for these technologies. Massive investment in local PEMFC manufacturing capacity is spurring production across various Chinese industrial zones.
South Korea
South Korea's strong focus on energy security and grid stability fuels demand for stationary PEMFC systems. The country's grid stability initiatives strongly support the deployment of large-scale fuel cell solutions. Doosan Fuel Cell Co., Ltd. leads development in this area, concentrating efforts on utility and commercial building power generation.
United States
The United States sees growing PEMFC demand from transport and industry sectors, alongside material handling applications. The US Inflation Reduction Act provides significant incentives for hydrogen infrastructure development and PEMFC adoption. Investment clusters around key industrial hubs, accelerating the build-out of a national hydrogen ecosystem.
Japan
Japan represents a primary market for light-duty PEMFC vehicle deployment, driven by early infrastructure investments. Research and development in catalyst technology is concentrating in Japan, aiming to reduce platinum loading. This strategic focus enhances the commercial viability of fuel cell stacks for various applications.
Proton Exchange Membrane Fuel Cell (PEMFC) Market Key Industry Players
Global majors compete with regional champions across manufacturing capacity and technological leadership in the PEMFC market. The competitive landscape features a blend of established industrial players and specialized fuel cell developers. Strategic archetypes include heavy-duty motive application experts, integrated hydrogen solution providers, and large-scale stationary system developers. Companies are engaging in significant manufacturing investment and strategic partnerships to expand their market reach.
Specialists in heavy-duty motive applications, Ballard Power Systems exemplifies expertise in fuel cell systems for buses and trucks. Plug Power Inc. represents integrated hydrogen solutions, focusing on material handling and stationary power requirements. Doosan Fuel Cell Co., Ltd., a South Korea-based entity, anchors the segment for large-scale stationary fuel cell systems, particularly for utility and commercial building power generation. These companies collectively illustrate the diverse strategic approaches within the PEMFC industry.
| Leading Market Players |
|---|
| Nuvera Fuel Cells, LLC |
| Doosan Fuel Cell Co., Ltd. |
| Ballard Power Systems |
| Nedstack Fuel Cell Technology BV |
| Intelligent Energy Limited |
| Plug Power Inc. |
| ITM Power PLC |
| W. L. Gore & Associates, Inc. |
| Proton Motor Fuel Cell GmbH |
| Others |
Cost & Logistics Intelligence
Commercial vehicle fleet operators demanding fully integrated hydrogen powertrain systems reshape the competitive landscape, compelling stack manufacturers to adapt their supply chains and pricing structures to total cost of ownership models.
Pricing Analysis
Warranty and service bundling increasingly define PEMFC system pricing, reflecting the long operational lifespans required for commercial applications. Contract-based long-term offtake agreements dominate for large fleet deployments, ensuring predictable costs. Price differentiation stems from the system's power output, durability, and the level of after-sales support provided by the supplier. Pricing pressure intensifies due to ongoing innovations in catalyst technology, which successfully reduce material costs. Commercial vehicle manufacturers remain highly price-sensitive, prioritizing total cost of ownership over initial capital expenditure.
Supply Chain Analysis
Logistics and freight costs for critical components impact overall PEMFC system economics, particularly for specialized parts manufactured in specific regions. The supply chain for PEMFCs draws from Germany for Membrane Electrode Assembly production and China for bipolar plates. Raw material dependencies include platinum-group metals for catalysts and specialized polymers for membranes. Platinum price volatility represents a significant structural risk for manufacturers. Distribution runs through direct sales channels to vehicle manufacturers and system integrators, with specialized component distributors serving smaller players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Proton Exchange Membrane Fuel Cell market presents a cost-of-compliance story, where the EU Green Deal's stringent transport decarbonization targets create a barrier-to-entry moat for compliant zero-emission solution providers.
For Market Incumbents:Deploy strategic partnerships with green hydrogen producers to secure stable, low-cost fuel supply for end-users. Deepen vertical integration into critical component manufacturing, such as gas diffusion layers, to mitigate supply chain risks and control costs. This strategy counters the threat of raw material price volatility and ensures consistent quality. Focus R&D on further reducing platinum loading in catalysts to improve the long-term economic viability of PEMFC systems.
For New Entrants and Emerging Players:Maritime and aviation sectors represent an underserved buyer archetype, seeking high-power-density PEMFC systems for auxiliary and primary propulsion. Target remote industrial sites and data centers in emerging economies for distributed power generation, leveraging green hydrogen integration for self-sufficient energy ecosystems. A go-to-market strategy centered on modular, scalable solutions with integrated energy management software can penetrate these specialized segments effectively.
For Investors and Strategic Acquirers:The window for entry favors patient capital seeking long-term growth in foundational decarbonization technologies. Focus on acquiring specialized component manufacturers for gas diffusion layers or bipolar plates, or software firms developing advanced fuel cell control systems. These targets offer critical intellectual property and manufacturing expertise. The successful commercial rollout of green hydrogen production hubs across Europe and North America serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure long-term platinum-group metal supply contracts | Ensures cost stability and reduces exposure to volatile commodity markets for catalyst production. |
| Invest in advanced catalyst-coated membrane (CCM) manufacturing | Reduces platinum content and improves performance, enhancing economic competitiveness for automotive applications. |
| Form strategic alliances with heavy-duty vehicle OEMs | Accelerates PEMFC system integration into commercial trucks and buses, expanding market penetration. |
| Develop integrated hydrogen production and fueling solutions | Addresses the critical hydrogen infrastructure gap, facilitating wider PEMFC adoption for fleet operators. |
| Expand component production capacity in China and Germany | Localizes critical supply chains and capitalizes on regional policy support for domestic PEMFC manufacturing. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic research underwrites the qualitative findings and quantitative projections within this analysis. Primary interviews with fuel cell engineers, automotive OEM strategists, logistics fleet managers, and material scientists provided critical insights. Secondary data from ISO standards, IEC specifications, national energy agency reports, and company annual reports further validated market dynamics. The methodology employed a robust bottom-up market sizing approach, triangulated with top-down validation.
The analytical framework decomposes the rate of change across product type, technology, application, end-user, and geographic region over the projection horizon. Each segment's growth trajectory was modeled based on historical trends, policy impact, and technological advancements. Compound Annual Growth Rates (CAGRs) were derived from a comprehensive assessment of these factors. Key forecast inputs included hydrogen infrastructure buildout projections and platinum price forecasts, reflecting their direct impact on market expansion.
Revisions become necessary when significant policy shifts, raw material supply disruptions, or unexpected technological breakthroughs materialize. Forecasts reflect a set of carefully documented assumptions regarding market development and regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Hydrogen Fuel Cells Market