
 Lithium-Ion Battery Pack for Consumer Market | 2026-2036
Lithium-Ion Battery Pack for Consumer Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Pack for Consumer Market Insights
Battery management software as a subscription layer is consolidating what consumers and OEMs actually pay for, shifting value from cell chemistry to firmware-controlled cycle optimization. Samsung SDI leverages its semiconductor heritage to integrate intelligent charge controllers directly into pack architectures. Panasonic sustains dominance in cylindrical form factors through decades of process refinement at its Japanese production facilities. LG Energy Solution anchors its position by supplying tier-one laptop OEMs with prismatic cells that meet stringent energy density thresholds.
A lithium-ion battery pack for consumer applications comprises multiple electrochemical cells arranged in series-parallel configurations, typically using nickel-manganese-cobalt or lithium iron phosphate cathodes with graphite anodes, achieving nominal voltages between 3.6V and 14.4V depending on series count. The pack incorporates protection circuitry, thermal management substrates, and cell balancing electronics to prevent overcharge, deep discharge, and thermal runaway during repetitive cycling in portable equipment. Smartphone batteries within the product type dimension command mature margins but face pressure from device longevity trends that extend replacement intervals. Power tool batteries generate the fastest growth as brushless motor platforms multiply voltage tiers and amp-hour ratings across professional trades. The 3000-4000mAh capacity band captures disproportionate value in premium laptop and tablet configurations where thinness constraints intersect with all-day runtime requirements.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape pack design decisions for any manufacturer accessing European consumer channels. China's SAMR enforces GB standards for cell safety testing that effectively gate market entry for uncertified suppliers. The US Consumer Product Safety Commission maintains recall authority over thermal incident reports, creating liability exposure that favors established suppliers with traceable quality systems. Stakeholders must monitor how solid-state cell prototypes and silicon-anode chemistries alter the cost-performance calculus for incumbent form factors before committing to multi-year capacity investments.
Market Dynamics
Cell-level traceability mandates from China's SAMR and the EU Battery Regulation are forcing pack manufacturers to reconfigure supply chain architectures around serialized production records and carbon accounting systems.
Growth Catalysts
- Platform Ecosystem Lock-In:Portable power tool manufacturers are expanding proprietary battery platform ecosystems to capture professional users through interoperable voltage tiers and amp-hour ratings across brushless motor product lines.
- GB Standards Enforcement:China's SAMR enforcement of GB standards for cell safety testing creates quality gates that filter out uncertified suppliers and consolidate market share among compliant producers.
- Silicon-Anode Migration:Silicon-anode chemistries are entering pilot production for premium laptop configurations, promising energy density improvements that justify premium positioning in thin-form-factor devices.
Market Restraints
- Cobalt Supply Concentration:Nickel-manganese-cobalt cathode formulations depend on cobalt feedstock concentrated in Central African mining jurisdictions, exposing cost structures to geopolitical disruption and artisanal supply volatility.
- Prismatic Cell Capacity Bottleneck:Tier-one laptop OEM procurement is concentrating around Seoul-based production clusters, creating allocation constraints for secondary manufacturers seeking prismatic cell supply.
- Thermal Runaway Liability:The US Consumer Product Safety Commission maintains active recall authority over thermal incident reports, elevating insurance and legal exposure for pack assemblers without traceable quality systems.
Strategic Opportunities
- Recycled Content Mandates:The EU Battery Regulation's recycled content thresholds create first-mover advantages for pack manufacturers establishing closed-loop collection infrastructure in European consumer channels.
- Subscription Firmware Models:Battery management software delivered as a recurring service layer enables OEMs to monetize cycle optimization and predictive maintenance beyond initial hardware margins.
- Power Tool Voltage Expansion:Professional trades are adopting higher-voltage brushless platforms, multiplying addressable pack volumes across 18V, 36V, and 54V configurations for construction and landscaping equipment.
Industry Challenges
- Cell Balancing Engineering Talent:Pack manufacturers face acute shortages of firmware engineers capable of developing adaptive charge algorithms for multi-series configurations with heterogeneous cell aging profiles.
- Dual Certification Timelines:Simultaneous pursuit of GB standard compliance and EU Battery Regulation carbon footprint declarations extends product launch cycles by twelve to eighteen months for cross-border suppliers.
- Legacy Form Factor Inventory Stranding:Cylindrical cell investments risk obsolescence as prismatic and pouch formats capture share in premium consumer electronics with stringent thickness constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Pack for Consumer Market |
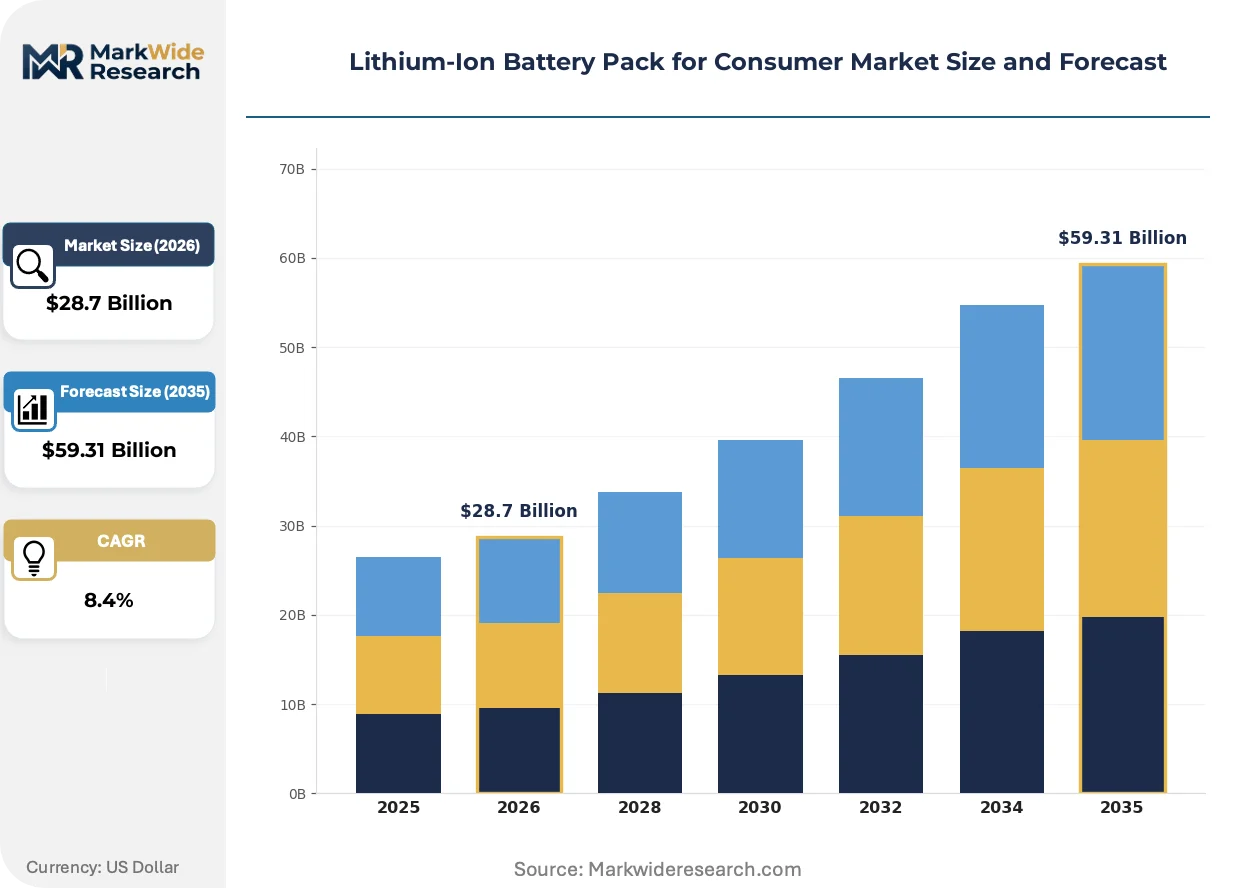
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphone Batteries, Laptop Batteries, Power Tool Batteries, Electric Vehicle Batteries Application: Consumer Electronics, Electric Mobility, Portable Devices, Renewable Energy Storage Capacity: 1000-2000mAh, 2000-3000mAh, 3000-4000mAh, 4000-5000mAh Form Factor: Cylindrical, Prismatic, Pouch, Stackable |
| Companies Covered | CATL, LG Energy Solution, Panasonic, Samsung SDI, BYD, A123 Systems, SK On, Toshiba, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Pack for Consumer Market Trends and Innovations
Intelligent charge controllers embedded at the pack level are displacing discrete protection circuits, compressing bill-of-materials complexity while enabling firmware-defined performance optimization across device categories.
Silicon-anode active materials are integrating into high-end laptop battery architectures, replacing graphite anodes in configurations where energy density thresholds exceed 700 watt-hours per liter. Tier-one OEM procurement teams in Taiwan and Japan are qualifying these cells for flagship ultrabook programs launching across the 2024-2026 design cycle. This chemistry migration is integrating cycle-life prediction algorithms directly into pack firmware, enabling runtime guarantees that justify premium positioning against incumbent graphite-based alternatives.
The EU Battery Regulation's carbon footprint declaration requirements are mandating supply chain documentation from mining through cell production for any pack entering European consumer channels. Manufacturers must now account for scope-three emissions and establish recycled content verification systems audited by notified bodies. Laptop and power tool segments with high European sales exposure are responding by dual-sourcing cells from producers with certified low-carbon production processes in Scandinavia and domestic EU gigafactories.
Professional power tool buyers are consolidating procurement around platform-compatible battery ecosystems rather than discrete pack purchases, compressing replacement battery aftermarket volumes while expanding initial platform attachment rates. Distribution is fragmentating between direct OEM subscription programs for large fleet operators and specialized trade distributors serving independent contractors. This behavioral shift is most visible in Germany and the United Kingdom, where construction sector consolidation has concentrated buying power among national equipment rental chains demanding interoperability guarantees across voltage tiers.
Lithium-Ion Battery Pack for Consumer Market Segmentation
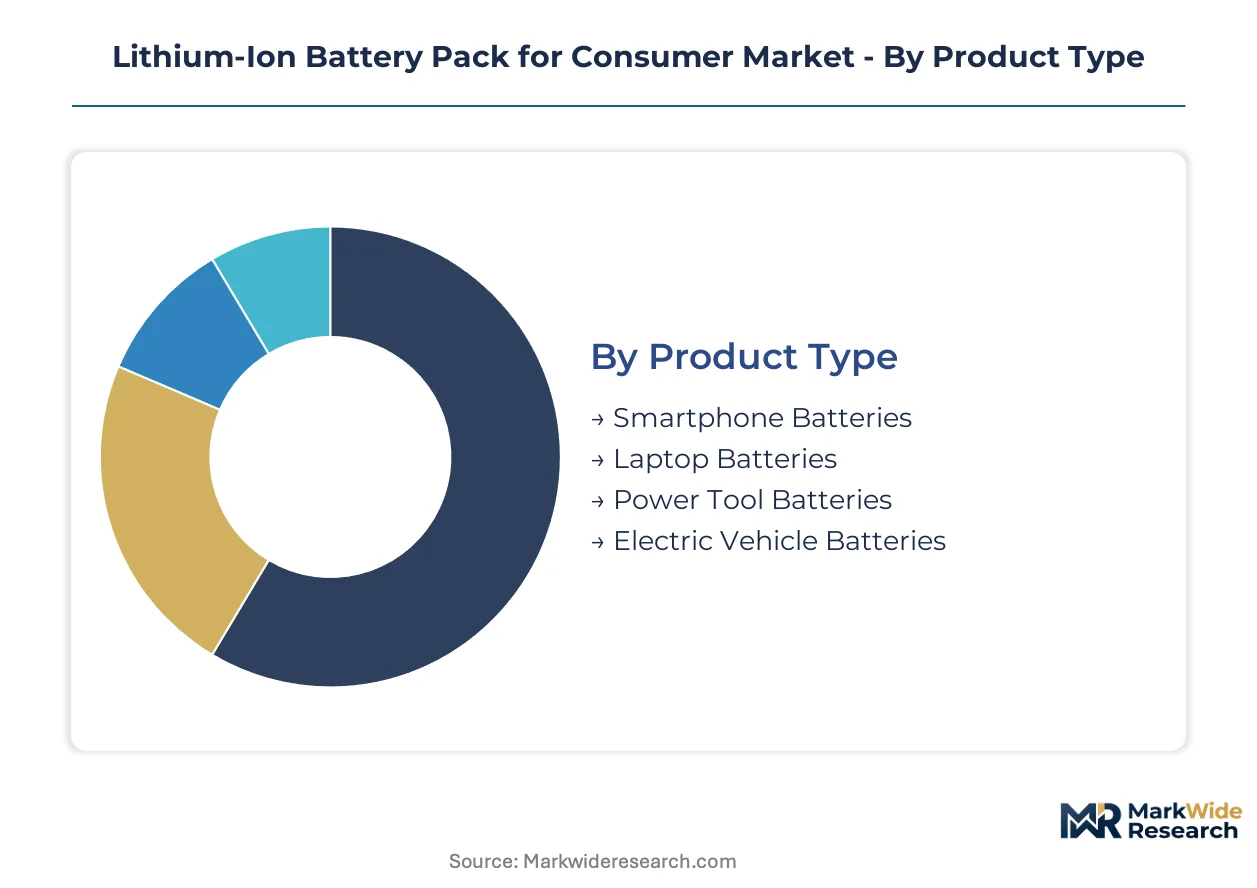
Consumer battery purchasing splits sharply between mass-market replacement cycles and premium OEM attachment. Pack architectures must align voltage, thermal, and firmware specifications to specific device categories rather than selling commoditized cells. Segmentation reveals where cell chemistry investments and platform ecosystem strategies concentrate returns.
Product Type:
Volume concentrates in smartphone and laptop replacements, while premium growth flows from professional tool platforms and emerging mobility applications.
- Smartphone Batteries:Nickel-manganese-cobalt cathodes dominate thin-form-factor designs where energy density exceeds 700 watt-hours per liter. Demand clusters around Shenzhen and Seoul manufacturing corridors serving Android OEMs and Apple supply chains, though device longevity trends extend replacement intervals and compress aftermarket volumes.
- Power Tool Batteries:Brushless motor platforms multiply voltage tiers across 18V, 36V, and 54V configurations with interoperable pack architectures. Professional trades in Germany and the United Kingdom consolidate procurement around platform ecosystems, expanding initial attachment rates while shrinking discrete replacement purchases.
- Laptop Batteries:Prismatic cells meeting stringent thickness constraints anchor tier-one OEM procurement from Seoul-based production clusters.
- Electric Vehicle Batteries:Modular pack designs scale from micromobility scooters to auxiliary power units, with cell balancing firmware adapting automotive-grade architectures for consumer price points.
Today's leader: Smartphone Batteries. Tomorrow's challenger: Power Tool Batteries.
Application:
End-use differentiation separates consumer electronics maturity from mobility and storage segments climbing the fastest.
- Consumer Electronics:Smartphone, laptop, and tablet packs achieve thin-form-factor targets through stacked pouch cells with graphite or silicon-anode chemistries. GB standards enforcement by China's SAMR and EU Battery Regulation carbon declarations filter supplier bases, consolidating share among certified producers with traceable quality systems.
- Electric Mobility:E-scooter and e-bike packs demand thermal runaway protection at price points below automotive standards. Shenzhen manufacturers supply European micromobility operators facing EU Battery Regulation recycled content thresholds and carbon footprint documentation requirements.
- Portable Devices:Wearables and handheld equipment drive miniaturization of protection circuitry and cell balancing electronics.
- Renewable Energy Storage:Residential solar-battery systems repurpose consumer-grade cells with simplified management systems for stationary duty cycles.
Consumer Electronics commands current margin pools. Electric Mobility offers the steepest expansion trajectory as micromobility fleets professionalize procurement.
Capacity:
Mid-range bands capture premium positioning where runtime requirements intersect with physical constraints.
- 3000-4000mAh:Premium laptop and tablet configurations demand this band for all-day runtime without thickness penalties. Taiwan and Japan OEM procurement teams qualify silicon-anode variants for flagship ultrabook programs, integrating cycle-life prediction algorithms into pack firmware to justify premium positioning.
- 4000-5000mAh:Gaming laptops and professional workstations accommodate larger packs where performance outweighs portability. Seoul-based cell producers allocate prismatic capacity to tier-one OEMs, creating supply constraints for secondary manufacturers.
- 2000-3000mAh:Mid-tier smartphones and ultraportable laptops balance cost and endurance.
- 1000-2000mAh:Wearables, wireless earbuds, and legacy device replacements populate this entry tier.
3000-4000mAh dominates premium positioning. 4000-5000mAh is gaining share fastest as professional computing segments expand.
Form Factor:
Manufacturing process maturity and design flexibility determine format selection across device categories.
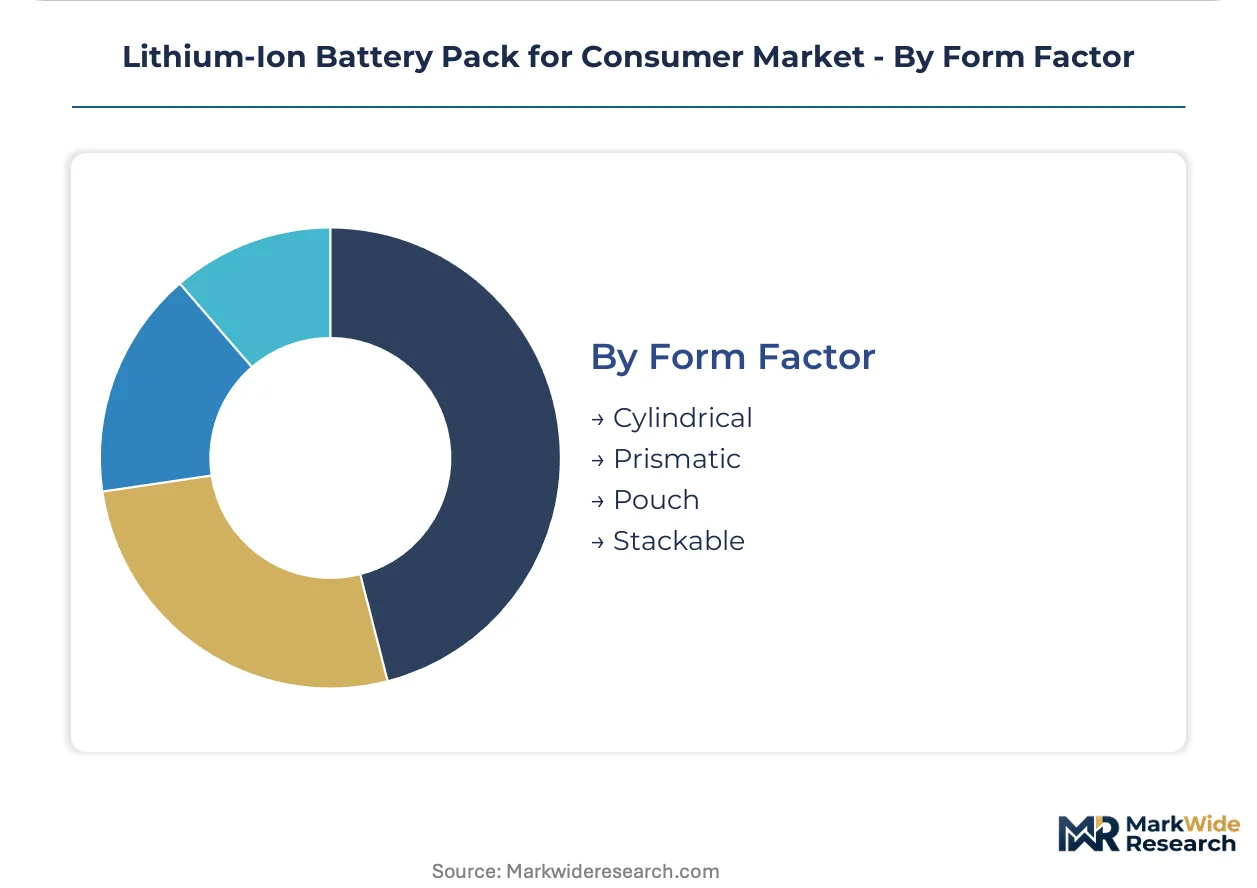
- Prismatic:Rigid aluminum-cased cells stack efficiently for laptop and power tool packs where space optimization matters. Japanese production facilities sustain decades of process refinement, though Seoul clusters face allocation pressure from concentrated tier-one OEM demand.
- Pouch:Flexible polymer-encased cells maximize volumetric efficiency in smartphones and wearables with irregular internal volumes. Shenzhen manufacturers dominate pouch cell assembly for Android OEM supply chains.
- Cylindrical:Standardized 18650 and 21700 formats leverage Panasonic's process leadership for high-volume applications.
- Stackable:Modular architectures enable voltage and capacity scaling across power tool platforms and residential storage systems.
Prismatic formats lead laptop and tool attachment. Pouch cells are expanding most quickly as smartphone thickness constraints tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shenzhen manufacturing corridor concentrates pouch cell assembly for global smartphone supply chains, while South Korean producers dominate prismatic capacity for premium laptop OEMs. This bifurcation shapes where pack manufacturers locate balancing electronics and firmware development centers.
China
Shenzhen and Dongguan clusters supply Android OEMs and micromobility operators with pouch and prismatic configurations. SAMR enforcement of GB standards for cell safety testing filters uncertified suppliers from export channels. The Yangtze River Delta anchors silicon-anode pilot lines for ultrabook programs targeting 2025-2026 launches.
South Korea
Seoul-based production clusters face allocation pressure as tier-one laptop OEMs concentrate prismatic cell procurement. The MFDS maintains medical-grade quality benchmarks that cell producers leverage for consumer electronics certification. Busan-Ulsan logistics hubs expedite carbon footprint documentation required under EU Battery Regulation.
Japan
Kansai and Chubu regions sustain decades of cylindrical cell process refinement at legacy facilities. METI coordinates domestic gigafactory investments to preserve cathode active material supply chains. Osaka-area pack assemblers specialize in protection circuitry miniaturization for wearable form factors.
Germany
Construction equipment rental chains in Bavaria and North Rhine-Westphalia consolidate procurement around interoperable power tool battery platforms. The KBA's automotive safety standards influence pack thermal management specifications for micromobility imports. ECHA administers REACH compliance that gates cell chemistry access to European consumer channels.
United States
The CPSC maintains active recall authority over thermal incident reports, elevating liability exposure for pack assemblers without traceable quality systems. Texas and California distribution centers stock replacement batteries for professional tool fleets and residential energy storage retrofits. OSHA workplace safety guidelines shape power tool battery handling protocols across construction trades.
Lithium-Ion Battery Pack for Consumer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cylindrical formats consolidating around legacy Japanese producers and pouch supply fragmenting across Shenzhen fabricators. The vendor base organizes into three tiers: integrated cell-to-pack conglomerates, independent pack assemblers with firmware capabilities, and commodity contract manufacturers. Capacity expansion and strategic partnerships dominate competitive moves, as silicon-anode qualification timelines favor early movers with OEM relationships.
Within the integrated conglomerate tier, CATL, LG Energy Solution, and Panasonic anchor regional supply architectures. CATL exemplifies the Chinese state-linked capacity builder with backward control over cathode materials. LG Energy Solution occupies a position bridging Seoul-based prismatic production and European carbon-compliant supply chains. Panasonic represents the Japanese process specialist sustaining cylindrical dominance through decades of manufacturing refinement at legacy facilities.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic |
| Samsung SDI |
| BYD |
| A123 Systems |
| SK On |
| Toshiba |
| EVE Energy |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's carbon footprint declaration mandate gates qualified supply and premium-tier pricing access, filtering uncertified suppliers from European consumer channels while enabling compliant producers to capture margin premiums through verified low-carbon production documentation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for silicon-anode configurations entering pilot production. A three-tier pricing structure across premium, standard, and economy levels separates firmware-enabled cycle optimization from commodity replacement cells. Price differentiation centers on GB standard certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because Shenzhen fabricators compete for Android OEM volume contracts. Professional power tool fleet operators show least price sensitivity due to platform ecosystem lock-in, while mass-market smartphone replacement buyers remain most sensitive.
Supply Chain Analysis
Firmware engineering talent shortages in Shenzhen and Seoul constrain pack balancing electronics production scaling. Supply concentrates in China, South Korea, and Japan, with cathode active materials feeding from domestic gigafactory investments. Raw material dependencies center on cobalt feedstock, graphite anodes, and electrolyte solvents. Single-source vulnerability runs through Central African mining jurisdictions for cobalt. Distribution runs through direct OEM subscription programs for large fleet operators and specialized trade distributors serving independent contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with the EU Battery Regulation's recycled content thresholds creating first-mover advantages that reshape procurement criteria across European consumer channels.
For Market Incumbents: Acquire firmware engineering capabilities to address acute talent shortages in adaptive charge algorithm development. Lock in prismatic cell allocation from Seoul-based production clusters before tier-one laptop OEM procurement concentrates supply further. Defend against silicon-anode substitution threats by qualifying next-generation chemistries through Taiwan and Japan OEM certification programs.
For New Entrants and Emerging Players: Direct-to-fleet subscription platforms offer the most penetrable route for bypassing established distributor relationships in German and UK construction equipment rental markets. Target power tool voltage expansion segments where brushless platform adoption multiplies addressable pack volumes. Enter through carbon-compliant supply chain partnerships with Scandinavian cell producers to satisfy EU Battery Regulation documentation requirements.
For Investors and Strategic Acquirers: Roll-up economics work for independent pack assemblers with firmware capabilities because cell balancing engineering talent scarcity prevents rapid organic replication. The five-to-ten year viability window favors targets with established GB standard and EU Battery Regulation dual certification pathways. Watch silicon-anode qualification timelines at Taiwan and Japan OEMs as the inflection signal for chemistry migration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Footprint Certification Program | EU Battery Regulation compliance unlocks premium European consumer channel access for verified low-carbon producers. |
| Firmware Engineering Acquisition | Adaptive charge algorithm talent scarcity makes pack-level intelligence capabilities defensible competitive moats. |
| Closed-Loop Collection Infrastructure | Recycled content verification systems create first-mover positioning ahead of EU Battery Regulation threshold enforcement. |
| Platform Ecosystem Partnership | Interoperable voltage tier agreements with power tool OEMs secure multi-year fleet operator attachment rates. |
| Silicon-Anode Qualification Investment | Taiwan and Japan OEM flagship ultrabook programs demand energy density thresholds exceeding graphite capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pack assembly plant managers, OEM procurement leads at laptop and power tool manufacturers, firmware engineering directors, and trade distributors with secondary validation against SAMR GB standard filings, EU Battery Regulation documentation databases, customs trade records, and SEC filings from listed cell producers. Bottom-up cell production estimates and top-down consumer electronics shipment data triangulated volume figures.
Historical reference periods anchored the projection horizon across the analysis window, with segmentation modeling across product type, application, capacity band, and form factor dimensions. CAGRs derived from fitted growth curves applied to qualified primary interview volume estimates. Forecast inputs incorporated silicon-anode pilot production timelines, GB standard enforcement trajectories, and EU Battery Regulation compliance cost assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state cell commercialization would alter the outlook. Forecasts reflect assumptions around carbon footprint declaration enforcement intensity and cobalt supply stability. Material deviation in SAMR certification timelines or EU recycled content threshold acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market