
 Lithium-Sulfur Battery Market | 2026-2036
Lithium-Sulfur Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Sulfur Battery Market Analysis
Electrochemical engineering talent is bifurcating between legacy lithium-ion optimization and next-generation sulfur cathode development, constraining pilot-scale manufacturing expansion. Sion Power Corporation leverages its Arizona-based R&D campus to anchor solid-electrolyte interface research for aerospace contracts. Lyten, Inc. competes through graphene-enhanced sulfur cathodes that differentiate its 3D-printed cell architecture from conventional slurry-coated designs.
Lithium-sulfur batteries store energy through reversible electrochemical conversion between sulfur cathodes and lithium metal anodes, achieving theoretical energy densities of 2,600 Wh/kg—roughly five times that of nickel-manganese-cobalt cells—while eliminating critical mineral dependencies. Their primary purpose centers on weight-sensitive applications where energy density outweighs cycle-life requirements, including unmanned aerial systems and satellite power subsystems. Pouch cells dominate prototype shipments due to flexible form factors that accommodate sulfur volume expansion during cycling, while cylindrical cells remain the fastest-growing format as automated winding equipment from lithium-ion lines adapts to sulfur cathode tapes. Aerospace applications command the highest margin pools because qualification timelines and safety premiums insulate suppliers from price competition.
EPA hazardous material transport rules and FAA Special Conditions for lithium battery installations shape cell packaging and thermal runaway containment requirements for U.S. manufacturers. EASA publishes parallel certification guidelines for aviation energy storage, while China's MIIT enforces GB standards for battery cell safety testing that sulfur chemistry must satisfy for export market access. Stakeholders must monitor which regulator first certifies lithium-sulfur for passenger aviation, as that jurisdiction will set the de facto global safety benchmark.
Market Dynamics
Solid-state electrolyte research is bifurcating the competitive landscape between aqueous polysulfide management and ceramic separator architectures, forcing manufacturers to place parallel bets on divergent technical paths before certification standards crystallize.
Growth Catalysts
- FAA Special Conditions maturation:Aviation battery safety protocols are creating a defined regulatory pathway for high-energy-density chemistries in electric propulsion systems, accelerating OEM qualification timelines.
- Electric unmanned aerial systems:Defense and logistics drone programs are specifying lithium-sulfur packs for endurance missions where payload constraints dominate operational design.
- South Korea cathode infrastructure:Legacy lithium-ion coating lines in Gumi and Ochang are being retrofitted for sulfur tape production, reducing pilot-scale capital requirements.
Market Restraints
- Lithium metal anode supply concentration:Roll-to-roll lithium foil production capacity clusters in China and Japan, creating input bottlenecks for non-Asian cell manufacturers.
- Polysulfide shuttle degradation:Dissolution of intermediate sulfur species into liquid electrolytes limits practical cycle life below commercial warranty thresholds.
- EPA hazardous material transport classification:Sulfur cathode active materials trigger stricter shipping documentation than conventional oxide cathodes, elevating logistics costs for prototype distribution.
Strategic Opportunities
- India PLI scheme extension:Advanced chemistry cell manufacturing incentives are expanding to include sulfur-based systems, attracting pilot line investment from Korean equipment vendors.
- Satellite power subsystem refresh cycles:Constellation operators are evaluating lithium-sulfur replacements for incumbent silver-zinc batteries in low-earth-orbit platforms.
- Solid-state ceramic separator convergence:Integration of LLZO garnet structures with sulfur cathodes is opening a performance tier unreachable by liquid electrolyte competitors.
Industry Challenges
- Electrochemical engineering talent scarcity:Universities are producing insufficient specialists versed in both lithium metal anode handling and sulfur cathode electrochemistry.
- EASA certification timeline uncertainty:Absence of published lithium-sulfur-specific airworthiness criteria is freezing aerospace procurement commitments.
- Automated winding equipment adaptation:Sulfur cathode brittleness requires recalibration of tension controls on cylindrical cell lines originally configured for NMC tapes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Sulfur Battery Market |
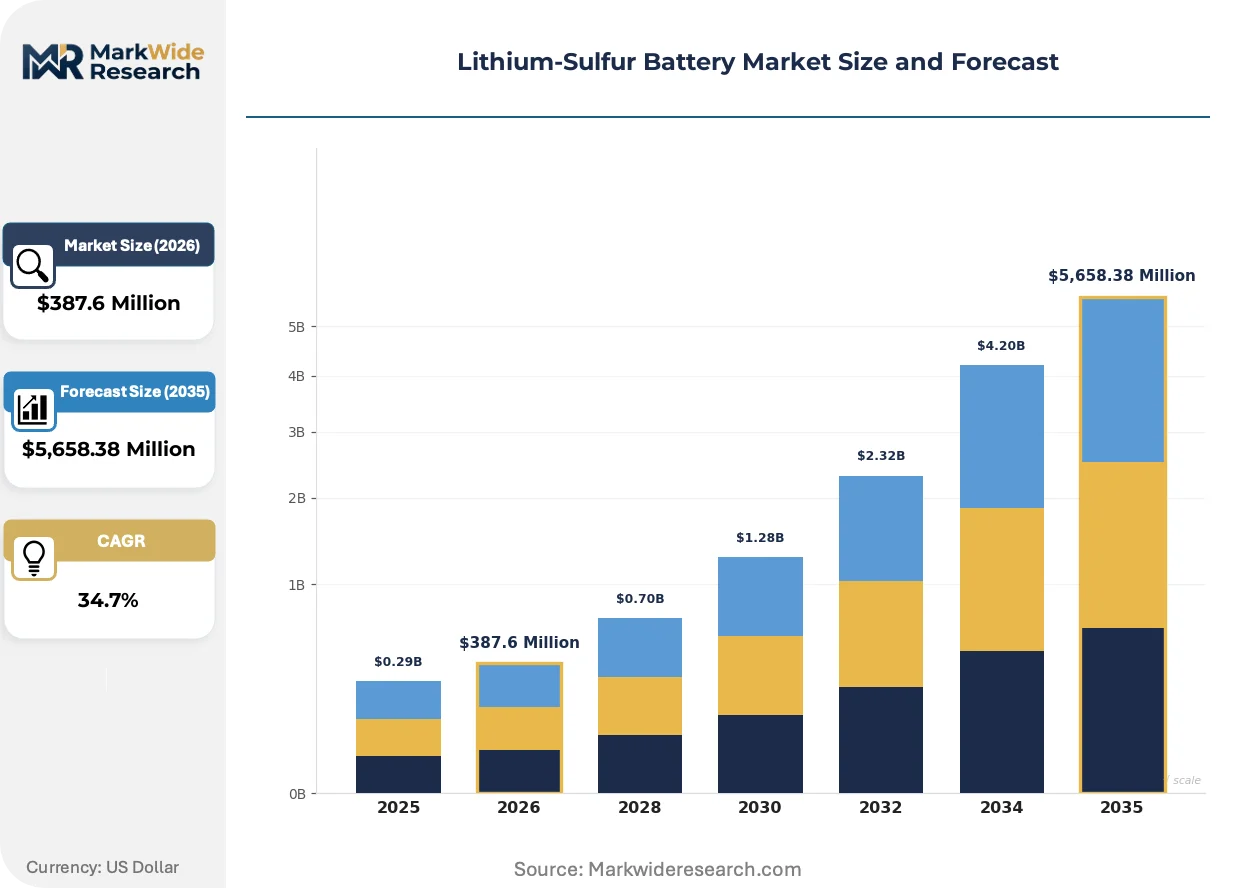
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $5,658.38 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Pouch Cells, Stackable Modules Application: Electric Vehicles, Portable Electronics, Renewable Energy Storage, Aerospace End User: Manufacturers, Research Institutions, Automotive OEMs, Industrial Users Technology: Electrochemical, Nanotechnology, Hybrid Systems, 3D Printing |
| Companies Covered | PolyPlus Battery Company, NexTech Batteries Inc., Li-S Energy Limited, Lyten, Inc., Zeta Energy LLC, Theion GmbH, Gelion plc, Sion Power Corporation, GS Yuasa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Sulfur Battery Market Emerging Trajectories
Research trajectories are diverging sharply between incremental liquid electrolyte improvements and disruptive solid-state architectures, with each path carrying distinct implications for manufacturing scale-up and end-use qualification.
Solid-state electrolyte development is bifurcating the technology roadmap between sulfide-based glass-ceramics and oxide garnet structures. Aerospace battery procurement teams are running dual-source qualification programs to preserve optionality. This technical divergence is compressing the window for single-architecture suppliers to achieve dominant design status before regulatory standards lock in.
REACH candidate list expansion for nickel and cobalt compounds is accelerating sulfur cathode interest among European automotive tier-ones seeking chemistry-agnostic supply security. The industrial consequence is redirected R&D funding from high-nickel NMC optimization toward sulfur conversion mechanisms. German OEMs are most affected, with cell qualification teams now benchmarking lithium-sulfur against sodium-ion for entry-segment applications.
Long-term offtake contracting is displacing spot purchasing for sulfur cathode active material as buyers seek volume commitments ahead of supply chain maturation. Tier-one cell manufacturers are locking multi-year agreements with petrochemical refiners for carbon-sulfur composite feedstocks. This pattern is most visible in South Korea, where POSCO and Samsung SDI have established dedicated sulfur processing joint ventures.
Lithium-Sulfur Battery Market Segmentation
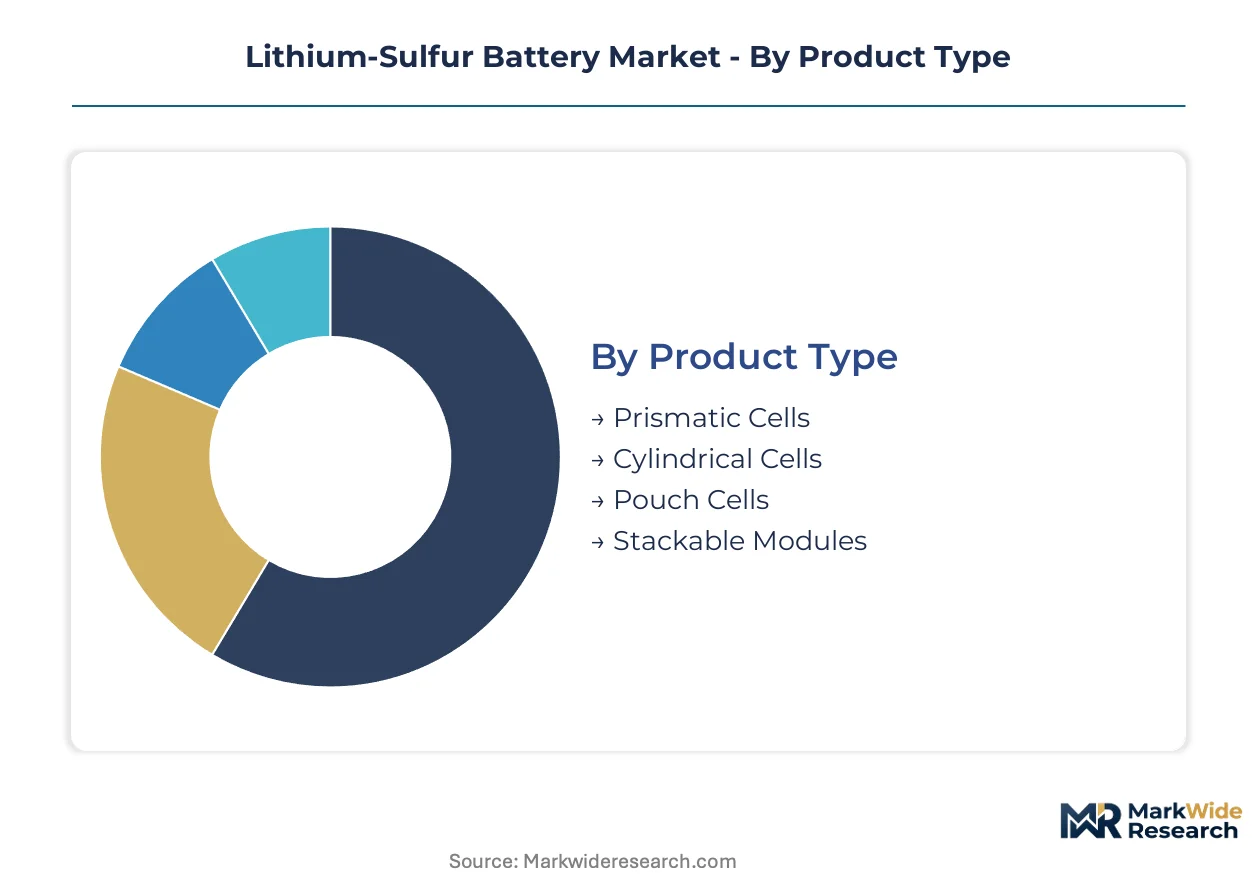
Segmentation in lithium-sulfur batteries reveals how regulatory pathways and application requirements fragment manufacturing priorities. FAA Special Conditions for aviation certification and EPA hazardous material classifications create divergent compliance burdens across product formats and end-use sectors.
Product Type:
FAA Special Conditions distinguish cell formats through thermal runaway propagation testing, with cylindrical and prismatic cells facing distinct containment protocols for electric propulsion systems.
- Pouch Cells:Flexible polymer-aluminum laminate enclosures accommodate sulfur cathode volume expansion during cycling. Demand concentrates in unmanned aerial systems and satellite power subsystems where form factor adaptability outweighs automated assembly efficiency. EASA certification timelines for pouch configurations in electric aviation remain unresolved.
- Cylindrical Cells:Automated winding equipment from legacy lithium-ion lines adapts to sulfur cathode tapes with recalibrated tension controls. South Korean manufacturers in Gumi and Ochang retrofit NMC production infrastructure for cylindrical sulfur pilot lines. Roll-to-roll lithium foil supply concentration in Japan creates input bottlenecks.
- Prismatic Cells:Rigid aluminum housings suit stationary renewable energy storage with reduced cycling frequency.
- Stackable Modules:Modular architectures enable satellite constellation operators to configure scalable power subsystems.
Established volume favors pouch cells; emerging adoption favors cylindrical cells.
Application:
Cost tier differentiation separates qualification-intensive aerospace contracts from price-sensitive portable electronics procurement.
- Aerospace:Electric propulsion system developers in Germany and the United States accelerate procurement as EASA and FAA certification pathways mature. Unmanned aerial systems for defense endurance missions specify lithium-sulfur packs where payload constraints dominate operational design. Safety premiums insulate suppliers from price competition.
- Electric Vehicles:German OEM qualification teams benchmark lithium-sulfur against sodium-ion for entry-segment applications as REACH candidate list expansion for nickel and cobalt compounds accelerates sulfur cathode interest.
- Renewable Energy Storage:Grid-scale deployments prioritize cycle life over energy density.
- Portable Electronics:Consumer device manufacturers await supply chain maturation before sulfur chemistry adoption.
Aerospace commands margin concentration; electric vehicles present volume scaling potential.
End User:
Customer type determines whether procurement emphasizes qualification documentation or research flexibility.
- Automotive OEMs:Cell qualification teams run dual-source programs to preserve optionality between liquid electrolyte and solid-state architectures before regulatory standards crystallize. Long-term offtake contracting for sulfur cathode active material displaces spot purchasing.
- Research Institutions:Fraunhofer Institute and Oak Ridge National Laboratory anchor solid-electrolyte interface research with distinct technical approaches to polysulfide shuttle degradation.
- Manufacturers:Tier-one cell producers lock multi-year agreements with petrochemical refiners for carbon-sulfur composite feedstocks.
- Industrial Users:Stationary power applications tolerate lower cycle life thresholds.
Procurement commitment depth separates automotive OEMs from research institutions.
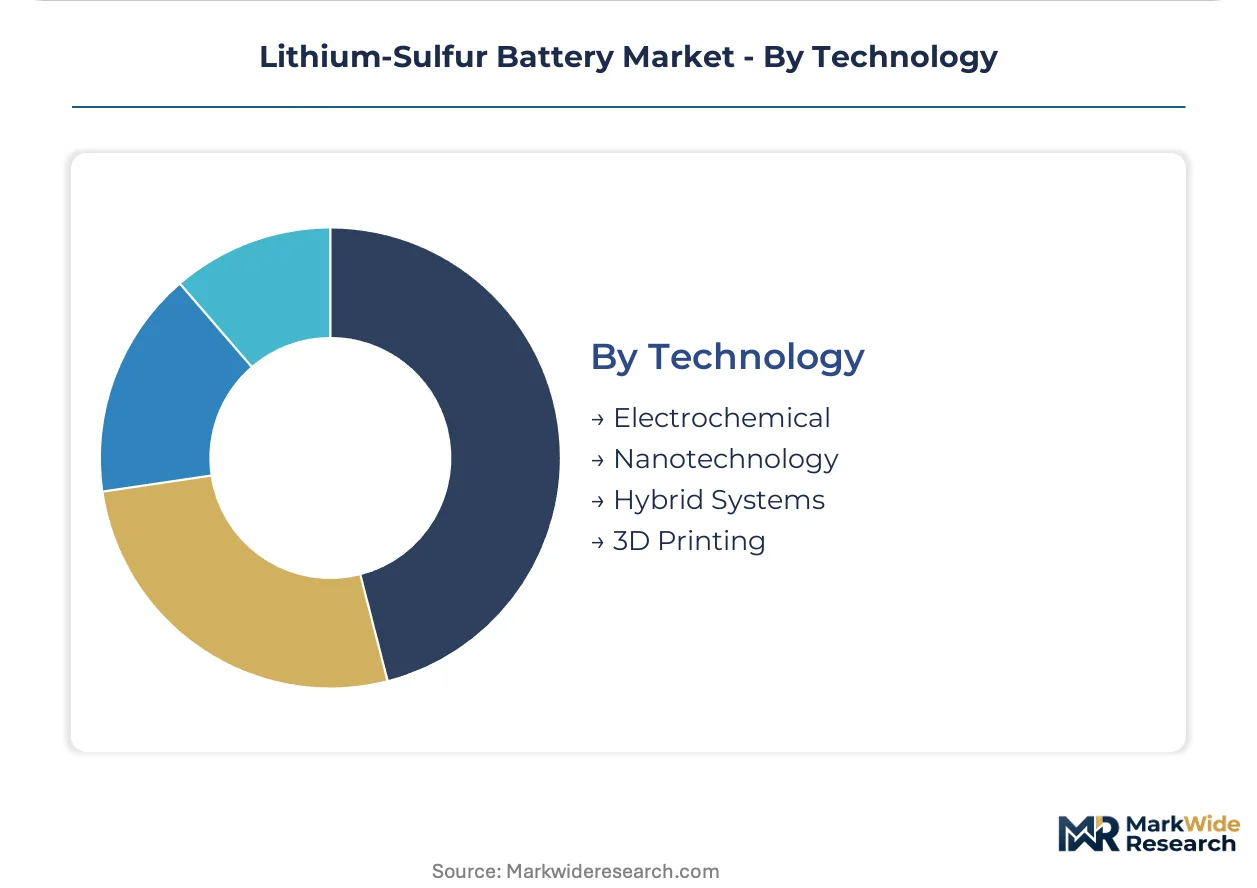
Technology:
Supply concentration in solid-state electrolyte research bifurcates between sulfide glass-ceramics and oxide garnet structures.
- Electrochemical:Reversible conversion between sulfur cathodes and lithium metal anodes achieves theoretical energy densities of 2,600 Wh/kg. Polysulfide shuttle degradation in liquid electrolytes limits practical cycle life below commercial warranty thresholds.
- Hybrid Systems:Integration of LLZO garnet structures with sulfur cathodes opens performance tiers unreachable by liquid electrolyte competitors.
- Nanotechnology:Graphene-enhanced sulfur cathodes differentiate 3D-printed cell architectures from conventional slurry-coated designs.
- 3D Printing:Additive manufacturing enables custom form factors for satellite power subsystems.
Hybrid systems gain share fastest; electrochemical approaches retain manufacturing maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification pathways for electric propulsion systems anchor United States demand, while EASA parallel guidelines and South Korean manufacturing infrastructure reshape procurement geography across three continents.
United States
Electric aviation developers in California and Washington accelerate high-energy-density cell procurement as FAA Special Conditions mature for commercial certification. EPA hazardous material transport rules constrain sulfur cathode distribution logistics. Sion Power Corporation anchors solid-electrolyte interface research from its Arizona R&D campus for aerospace contract fulfillment.
Germany
German OEM qualification teams benchmark lithium-sulfur against sodium-ion for entry-segment electric vehicles as REACH candidate list expansion for nickel and cobalt compounds redirects R&D funding. EASA publishes certification guidelines for aviation energy storage that freeze some procurement commitments pending specificity. Fraunhofer Institute drives solid-state electrolyte research resolving polysulfide shuttle degradation near Dresden.
South Korea
Samsung SDI and LG Chem legacy infrastructure in Gumi and Ochang repurposes for sulfur cathode pilot lines, reducing capital requirements for next-generation cell formats. The country's national industrial regulator enforces battery cell safety testing standards that sulfur chemistry must satisfy for export market access. POSCO established dedicated sulfur processing joint ventures with tier-one cell manufacturers to secure carbon-sulfur composite feedstock supply.
Japan
Roll-to-roll lithium foil production capacity clusters create input bottlenecks for non-Asian cell manufacturers seeking lithium metal anode supply. METI oversees industrial standards coordination for advanced battery chemistry commercialization. GS Yuasa Corporation occupies a position within the integrated manufacturer archetype serving domestic aerospace and defense applications.
India
PLI scheme extension to advanced chemistry cell manufacturing attracts pilot line investment from Korean equipment vendors seeking tariff-advantaged production bases. The Central Electricity Authority monitors grid-scale storage qualification protocols that may eventually accommodate lithium-sulfur systems. Maharashtra and Gujarat industrial corridors host emerging cathode material processing clusters.
Lithium-Sulfur Battery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure reflecting early-stage technology commercialization rather than mature consolidation. The vendor base spans solid-state electrolyte researchers, graphene-enhanced cathode developers, and legacy lithium-ion manufacturers repurposing infrastructure. Three archetypes dominate: aerospace-focused qualification specialists, materials-science-driven technology licensors, and industrial conglomerates leveraging captive manufacturing assets. Competitive moves concentrate on strategic partnerships for certification pathway navigation and pilot line capacity expansion ahead of regulatory standard crystallization.
Among United States-based developers, Sion Power Corporation and Lyten, Inc. exemplify divergent technical approaches to sulfur cathode commercialization. Theion GmbH represents the European specialist tier focused on aviation qualification timelines. Zeta Energy LLC and NexTech Batteries Inc. occupy positions within the materials-science archetype pursuing solid-state separator convergence. PolyPlus Battery Company anchors the aqueous electrolyte research vector, while Li-S Energy Limited and Gelion plc exemplify Commonwealth-market specialists targeting satellite and defense applications. GS Yuasa Corporation sits within the industrial conglomerate tier leveraging established manufacturing scale.
| Leading Market Players |
|---|
| PolyPlus Battery Company |
| NexTech Batteries Inc. |
| Li-S Energy Limited |
| Lyten, Inc. |
| Zeta Energy LLC |
| Theion GmbH |
| Gelion plc |
| Sion Power Corporation |
| GS Yuasa Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium metal anode substitution for conventional graphite electrodes is redrawing procurement geography toward Japan and China while compressing margin structures for non-Asian cell manufacturers facing input cost premiums.
Pricing Analysis
Geographic price spreads between South Korean pilot lines and U.S. aerospace qualification batches exceed threefold, reflecting FAA Special Conditions certification overhead and lithium foil import duties. Contract-based long-term offtake agreements dominate procurement, with pricing stratifying across aerospace-certified, automotive-benchmarked, and research-grade tiers. Cost compression in the automotive tier is intensifying as German OEMs benchmark sulfur cathodes against sodium-ion alternatives. Defense procurement teams show least price sensitivity due to mission-critical payload constraints.
Supply Chain Analysis
Tsugaru Strait transit vulnerability underscores roll-to-roll lithium foil concentration in Japan and China, creating single-source exposure for Western cell manufacturers. The chain draws from sulfur refinery outputs in South Korea, carbon composite substrates from German chemical specialists, and ceramic separator precursors from U.S. national laboratories. Tariff exposure on lithium metal imports threatens margin stability for European producers. Distribution runs through tier-one cell manufacturers directly to aerospace OEMs and satellite constellation operators, bypassing distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium-sulfur chemistry sits at an early-cycle expansion story where FAA and EASA certification pathway maturation is accelerating qualified supplier procurement ahead of manufacturing scale.
For Market Incumbents: Fortify aerospace certification moats by accelerating EASA-specific airworthiness documentation ahead of competitor submissions. Secure captive supply of carbon-sulfur composite feedstocks through joint ventures with Korean petrochemical refiners before spot market tightening. Sodium-ion benchmarking by German OEMs threatens volume tier pricing power. For New Entrants and Emerging Players: Differentiate on solid-state separator architectures where liquid electrolyte incumbents carry legacy polysulfide degradation constraints. Target satellite power subsystem refresh cycles as the most penetrable segment given silver-zinc replacement urgency and lower qualification barriers than passenger aviation. Pursue direct qualification partnerships with constellation operators rather than tier-one cell manufacturer channel dependence. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors materials-science specialists with published patent positions over integrated manufacturers with repurposed lithium-ion infrastructure. Long-term viability rests on which electrolyte architecture achieves dominant design status before regulatory standards crystallize. Monitor which jurisdiction first certifies lithium-sulfur for passenger aviation as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Convergence | LLZO garnet integration with sulfur cathodes opens performance tiers unreachable by liquid competitors. |
| Aviation Certification Pathway Navigation | FAA Special Conditions compliance separates premium aerospace suppliers from price-competitive tiers. |
| Pilot Line Capacity Expansion | South Korean retrofit of NMC infrastructure reduces capital barriers for sulfur cathode scale-up. |
| Long-Term Offtake Contracting | Multi-year carbon-sulfur feedstock agreements lock supply ahead of petrochemical refinery competition. |
| Dual-Source Qualification Programs | Aerospace procurement teams preserve optionality between sulfide glass-ceramic and oxide garnet architectures. |
Methodological Framework
Initial hypotheses were tested against primary input from cell engineering directors, aviation certification specialists, cathode materials procurement leads, and satellite power subsystem architects and refined through secondary validation against FAA Special Conditions documentation, EASA certification guidelines, EPA hazardous material transport classifications, and national laboratory solid-state research disclosures. Bottom-up cell shipment estimates triangulated against top-down aerospace and automotive demand projections.
Variance decomposition across product format, application sector, technology architecture, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by certification timeline probability and manufacturing scale readiness. Forecast inputs incorporated lithium metal anode supply concentration indices and sulfur cathode active material contract pricing trajectories.
The analysis sits within stated boundaries; outcomes outside concurrent FAA-EASA certification harmonization or solid-state electrolyte breakthrough timelines would require recalibration. Practitioners should keep alternative scenarios live as regulator priority shifts and materials-science patent filings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market