
 Automotive Sodium-Ion Battery Market | 2026-2036
Automotive Sodium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sodium-Ion Battery Market Outlook
Chinese cathode material producers are broadening precursor output for sodium-ion cells as CATL leverages its vertical integration into hard carbon anode supply while BYD anchors cell-to-pack architectures for passenger EV platforms. Faradion specializes in oxide cathode formulations for European automotive qualification. HiNa Battery Technology Co., Ltd. competes on prismatic cell scale-up for domestic bus OEMs.
An automotive sodium-ion battery stores electrochemical energy through sodium-ion intercalation into layered oxide or Prussian blue analog cathodes paired with hard carbon anodes, achieving energy densities of 100–160 Wh/kg while operating across wider temperature ranges than lithium-ion counterparts. Its primary purpose is to power electric drivetrains in cost-sensitive vehicle segments where raw material abundance outweighs premium energy density requirements. Prismatic formats dominate current manufacturing lines due to structural simplicity and thermal management compatibility with existing pack designs. Cylindrical cells represent the fastest-growing format as automated winding equipment from lithium-ion lines adapts readily to sodium-ion electrode stacks. Fleet operators constitute the deepest margin pool among end users because bulk procurement contracts reward standardized cell specifications across vehicle classes.
China's MIIT enforces GB/T standards for cell cycling life and thermal runaway propagation that shape sodium-ion product roadmaps, while the EU Battery Regulation through ECHA mandates carbon footprint disclosure and recycled content thresholds affecting market access timelines for imported cells. The US EPA tailpipe rules and NHTSA safety protocols indirectly steer OEM chemistry selection by tightening cost constraints on compliance pathways. Stakeholders must monitor how certification reciprocity between these regimes evolves to avoid stranded capacity in non-aligned testing protocols.
Market Dynamics
Hard carbon anode supply concentration in China's Shanxi province is reshaping cost structures for automotive sodium-ion cell producers, forcing pack integrators to negotiate long-term offtake agreements or develop captive precursor capabilities.
Growth Catalysts
- Urban logistics fleet electrification:Municipal zero-emission zones in Chinese megacities are mandating battery-electric commercial vehicle procurement, creating anchor demand for sodium-ion packs in cost-sensitive delivery van segments.
- GB/T 38031 thermal runaway standards:China's MIIT certification pathway for alternative chemistries provides regulatory clarity that accelerates OEM platform integration timelines versus unregulated battery categories.
- Prussian blue analog cathode maturation:Advances in lattice stability during high-rate cycling are extending cell cycle life for high-mileage taxi and ride-hail applications.
Market Restraints
- Hard carbon feedstock concentration:Biomass-derived anode precursor supply clusters in Shanxi and Henan provinces create geographic single-point vulnerability for non-Chinese cell producers.
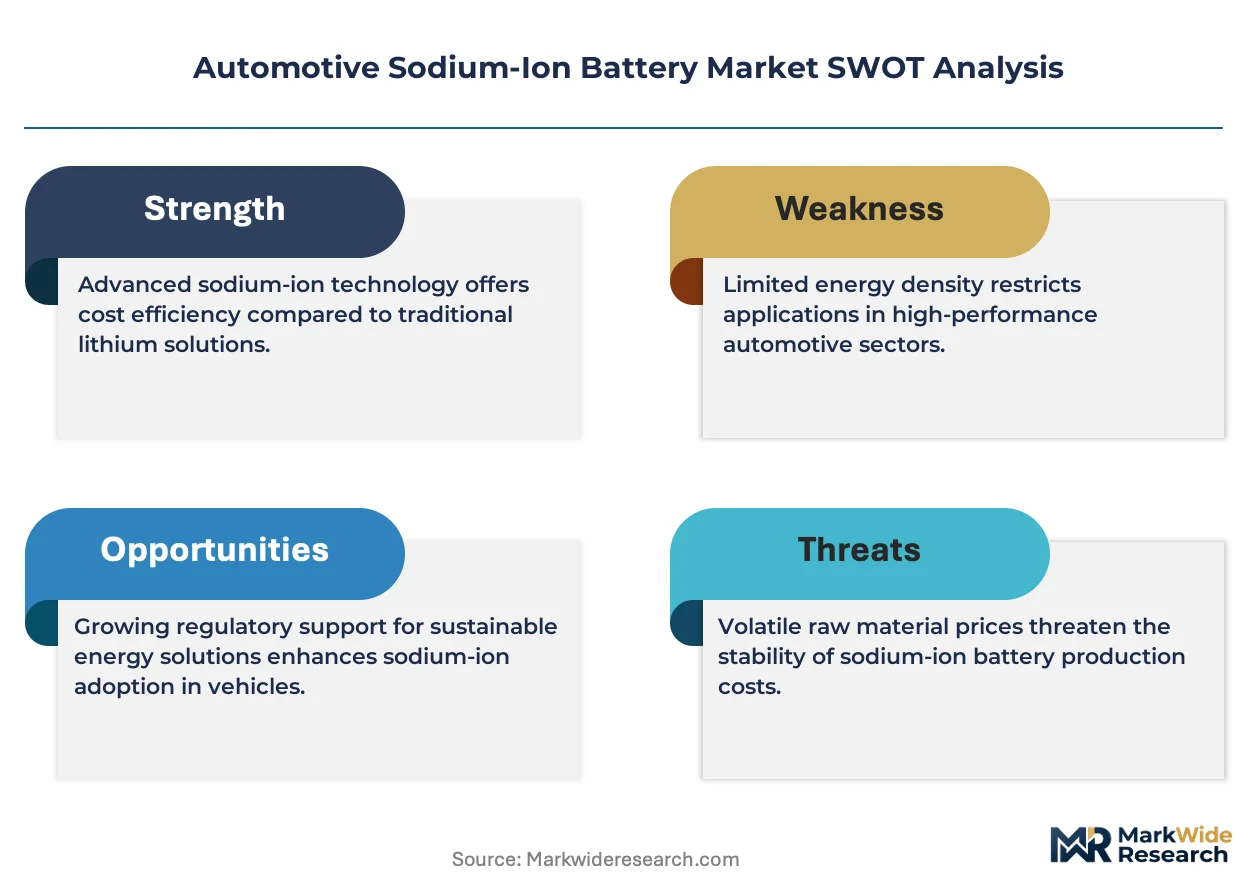
- Energy density ceiling:The 160 Wh/kg practical limit constrains sodium-ion competitiveness in premium passenger EV segments where lithium-ion NMC cells dominate.
- Recycling infrastructure immaturity:Absence of scaled pyrometallurgical recovery flows for sodium-ion electrolyte salts raises end-of-life cost uncertainty under EU Battery Regulation recycled content mandates.
Strategic Opportunities
- India's PLI scheme for ACC storage:The 18 GWh production-linked incentive window for advanced chemistry cells creates first-mover positioning for sodium-ion entrants targeting tropical climate durability requirements.
- Second-life stationary storage:Retired automotive sodium-ion packs with 70% residual capacity are converging with grid-scale buffer applications, extending value capture beyond vehicle lifecycle.
- Cell-to-pack architecture standardization:BYD's blade battery structural format is being adapted for sodium-ion chemistries, enabling pack-level cost reduction through module elimination.
Industry Challenges
- Electrolyte formulation talent scarcity:The small pool of electrochemists with sodium-ion-specific high-voltage additive experience constrains R&D velocity for European and North American cell startups.
- Dual chemistry pack integration:OEMs developing hybrid lithium-sodium architectures face thermal management complexity and battery management system software recalibration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sodium-Ion Battery Market |
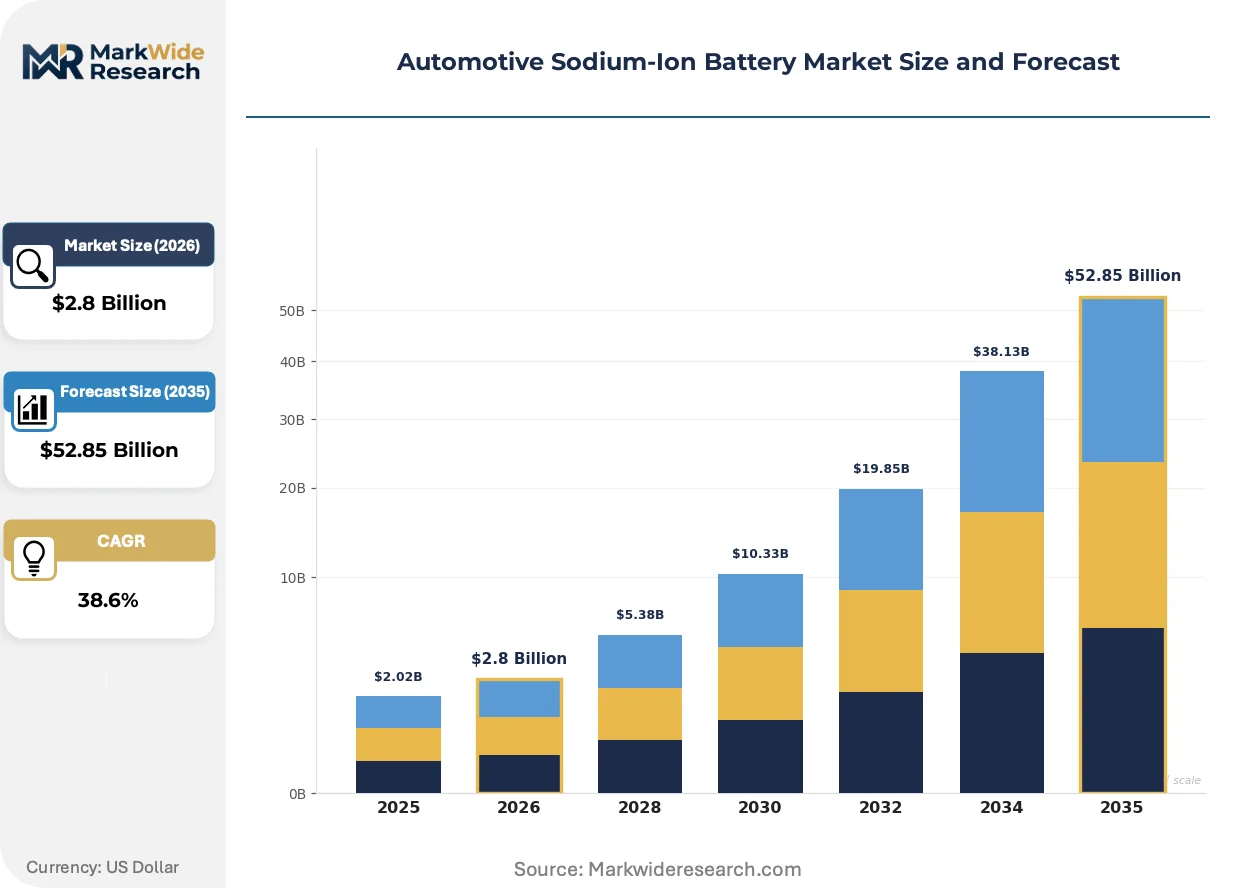
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $52.85 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Module End User: Vehicle OEMs, Fleet Operators, Aftermarket Providers, E-Bike Manufacturers Delivery Mode: Direct Sales, Online Distribution, Retail Outlets, Bulk Orders Technology: Low-Cost Manufacturing, High Charge Density, Fast Charging, Thermally Stable |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), BYD Company Limited, HiNa Battery Technology Co., Ltd., Faradion Limited, Altris AB, Natron Energy, Inc., Tiamat SAS, AMTE Power plc, NGK Insulators, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sodium-Ion Battery Market Strategic Shifts
Layered oxide cathode stabilization is converging with automated winding equipment adaptation, compressing sodium-ion cell qualification timelines and enabling cylindrical format scale-up that mirrors lithium-ion manufacturing learning curves.
Prussian white cathode formulations with rhombohedral lattice structures are converging with dry electrode coating processes, eliminating toxic solvent handling and reducing cell factory capital intensity. Korean equipment suppliers are retrofitting lithium-ion coating lines for sodium-ion electrode stacks at pilot scale. This convergence is compressing the cost gap between established lithium-ion and emerging sodium-ion production economics.
ECHA's carbon footprint disclosure requirements under EU Battery Regulation are forcing cell importers to document Scope 3 emissions from hard carbon precursor agriculture. German OEM qualification teams are prioritizing suppliers with certified sustainable biomass sourcing. The regulation is compressing market access timelines for producers lacking verified supply chain traceability systems.
Bulk procurement contracts by municipal bus operators are displacing spot-market cell purchasing, concentrating demand among standardized prismatic formats and squeezing margin for customized cylindrical variants. Chinese state-owned transit authorities are consolidating battery specifications across provincial fleets. This concentration is most visible in Jiangsu province, where Nanjing and Suzhou transit bureaus have harmonized pack dimensions and thermal interfaces.
Automotive Sodium-Ion Battery Market Segmentation
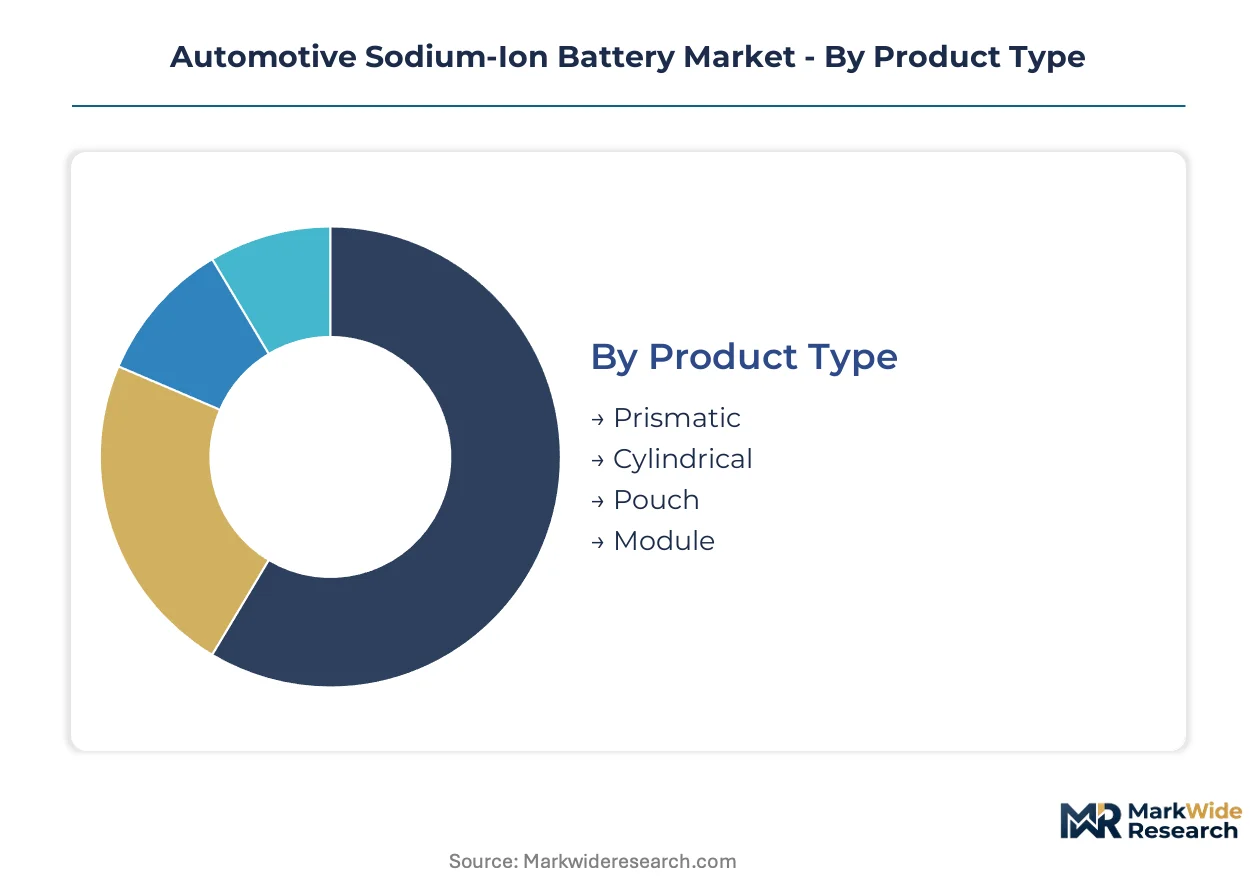
Sodium-ion battery commercialization demands precise segment targeting due to divergent capital requirements across cell formats and customer procurement patterns. Fleet operators and vehicle OEMs impose incompatible specification standards, forcing producers to commit to distinct manufacturing footprints early.
Product Type:
Prismatic formats demand the heaviest upfront tooling investment due to precision stamping dies and laser welding stations, while cylindrical lines repurpose existing winding equipment.
- Prismatic:Rectangular aluminum-cased cells with stacked electrode layers suit structural pack integration. Jiangsu province transit authorities in China specify this format for standardized bus procurement, rewarding suppliers with dedicated hard carbon anode supply agreements from Shanxi province.
- Cylindrical:Rolled electrode jellyrolls in steel cans leverage automated winding machinery migrated from lithium-ion production. Korean equipment suppliers near Gwangju are retrofitting coating lines for sodium-ion stacks, accelerating format adoption in European automotive qualification programs.
- Pouch:Laminated foil cells with polymer seals enable flexible pack geometries for compact vehicle architectures.
- Module:Pre-assembled cell groupings with integrated thermal management reduce pack integration labor for smaller OEMs.
Most installed capacity flows through Prismatic. Expansion is steepest in Cylindrical.
End User:
Margin capture varies sharply by customer type, with fleet operators extracting volume discounts that compress producer returns versus OEM technical partnerships.
- Vehicle OEMs:Passenger and commercial vehicle manufacturers specify cell-to-pack architectures with proprietary thermal interfaces. BYD's blade battery structural format adaptation for sodium-ion chemistries demonstrates how OEM partnerships lock in multi-year supply commitments.
- Fleet Operators:Municipal transit authorities and logistics companies procure standardized packs through bulk tender processes. Chinese state-owned bus operators in Nanjing and Suzhou have harmonized specifications, creating concentrated demand pools with limited supplier slots.
- Aftermarket Providers:Independent pack rebuilders and conversion shops source cells for legacy vehicle retrofits.
- E-Bike Manufacturers:Light electric vehicle producers prioritize cost minimization over cycle life for low-duty-cycle applications.
Vehicle OEMs absorb the majority of production volume. Fleet operators are gaining share fastest as municipal electrification mandates proliferate.
Delivery Mode:
Channel selection determines working capital intensity, with bulk orders requiring extended production cycles versus spot-market spot sales.
- Direct Sales:Long-term offtake contracts between cell producers and pack integrators or vehicle manufacturers. CATL's vertical integration into hard carbon supply supports direct negotiation with Chinese OEMs, bypassing distributor margins.
- Bulk Orders:Aggregated procurement by fleet consortia and state purchasing authorities. India's PLI scheme for advanced chemistry cells channels bulk orders through designated production facilities qualifying for incentive disbursement.
- Online Distribution:E-commerce platforms for replacement cells and small-format packs.
- Retail Outlets:Physical distributor networks serving aftermarket and e-bike segments.
Direct sales dominate value flows. Bulk orders are climbing the fastest as fleet procurement consolidates.
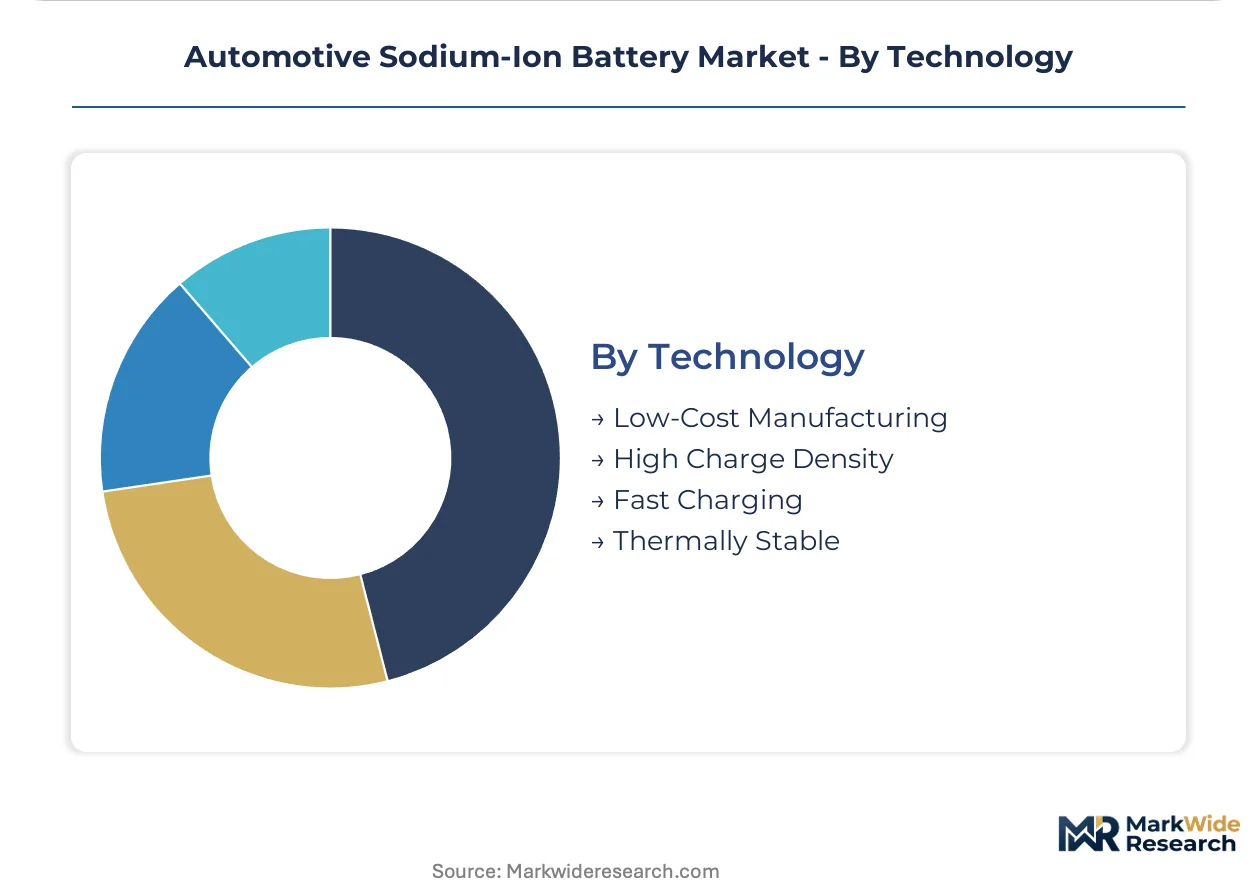
Technology:
R&D allocation splits between cost-focused process engineering and performance-oriented materials science with divergent patent strategies.
- Low-Cost Manufacturing:Dry electrode coating and simplified cell assembly reduce factory capital intensity. Prussian white cathode formulations paired with dry processes eliminate toxic solvent handling, compressing facility permitting timelines.
- Fast Charging:High-rate electrolyte additives and optimized porosity enable rapid energy replenishment. Taxi and ride-hail operators in Chinese megacities specify this capability for minimal vehicle downtime.
- High Charge Density:Advanced cathode loading and anode optimization maximize energy per unit mass.
- Thermally Stable:Inherent safety characteristics of sodium-ion chemistry reduce thermal runaway propagation risk, satisfying China's GB/T 38031 certification pathway for alternative chemistries.
Low-cost manufacturing commands the greatest installed base. Fast charging exhibits the steepest expansion trajectory as commercial vehicle electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting sodium-ion cell investment toward jurisdictions where GB/T certification reciprocity reduces duplicate testing costs. Producers migrate capacity to manufacturing clusters where MIIT pathway alignment accelerates OEM platform integration timelines versus fragmented compliance regimes elsewhere.
China
Municipal zero-emission zones in Nanjing and Suzhou are mandating battery-electric bus procurement through consolidated tenders. MIIT enforces GB/T 38031 thermal runaway standards that provide regulatory clarity for alternative chemistries. Jiangsu province hosts concentrated cathode precursor manufacturing while Shanxi province supplies hard carbon anode feedstock.
South Korea
Gwangju's battery belt is retrofitting lithium-ion coating lines for sodium-ion electrode stacks at pilot scale. The country's national industrial regulator coordinates with automotive OEMs on cell qualification protocols. Busan-Ulsan industrial corridor anchors equipment supplier clusters serving European automotive qualification programs.
India
The PLI scheme for advanced chemistry cells channels bulk procurement through designated production facilities qualifying for incentive disbursement. The central electricity authority mandates tropical climate durability testing for grid-connected storage derivatives. Tamil Nadu and Gujarat are emerging as production locations targeting second-life stationary storage applications.
Germany
ECHA carbon footprint disclosure requirements under EU Battery Regulation are compressing market access timelines for imported cells lacking verified supply chain traceability. KBA coordinates with OEM qualification teams on supplier certification. Bavaria hosts automotive engineering centers prioritizing sustainable biomass sourcing documentation.
United States
EPA tailpipe rules tighten cost constraints on compliance pathways for commercial vehicle electrification. NHTSA safety protocols indirectly steer OEM chemistry selection toward inherently stable cell architectures. Michigan and California anchor fleet operator procurement consortia negotiating standardized pack specifications.
Automotive Sodium-Ion Battery Market Competitive Environment
Chinese producers anchor one tier through integrated precursor supply; European specialists hold qualification-driven positioning through ECHA-aligned certification. The market exhibits tiered concentration with scale leaders, technology licensors, and regional fabricators occupying distinct competitive planes. Dominant competitive moves include captive hard carbon offtake agreements and cell-to-pack architecture licensing.
Within the scale-driven tier, Contemporary Amperex Technology Co., Limited represents integrated supply chain control from cathode precursor through pack assembly. BYD Company Limited exemplifies OEM-captive cell production adapted for structural battery formats. Faradion Limited occupies a position bridging European automotive qualification requirements with oxide cathode specialization.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Limited |
| HiNa Battery Technology Co., Ltd. |
| Faradion Limited |
| Altris AB |
| Natron Energy, Inc. |
| Tiamat SAS |
| AMTE Power plc |
| NGK Insulators, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Hard carbon precursor spot indices in Shanxi province cascade through three distinct pricing tiers for automotive sodium-ion cells, compressing margins for non-integrated pack assemblers while rewarding producers with captive anode supply or long-term offtake agreements with Jiangsu-based OEMs.
Pricing Analysis
Distributor margins on replacement cells for aftermarket channels absorb the steepest compression as fleet operators negotiate direct-to-OEM discounts through bulk tender processes. Contract-based long-term offtake agreements dominate volume flows, with price differentiation driven by GB/T 38031 certification tier and volume scale. Cost compression in the standard tier intensifies because Shanxi hard carbon supply concentration rewards backward-integrated producers. Municipal bus operators exhibit the highest price sensitivity; premium passenger EV platforms show the least.
Supply Chain Analysis
Second-life refurbishment flows for retired automotive packs are converging with grid-scale stationary storage channels, extending value capture beyond initial vehicle lifecycle. Hard carbon anode feedstock draws from biomass precursors concentrated in China's Shanxi and Henan provinces, while cathode oxide production clusters in Jiangsu and South Korea's Gwangju battery belt. Single-source vulnerability in Shanxi hard carbon supply creates geographic concentration risk. Distribution runs through direct sales contracts between cell producers and pack integrators, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive sodium-ion battery market functions as a geographic-arbitrage play where producers capture margin spreads between China's MIIT-aligned certification pathways and the EU's ECHA carbon disclosure requirements.
For Market Incumbents: Anticipate margin pressure from emerging Prussian blue analog specialists by locking multi-year hard carbon offtake agreements with Shanxi feedstock producers. Certification investment in ECHA-aligned supply chain traceability systems defends positioning against European entrants lacking verified biomass sourcing documentation.
For New Entrants and Emerging Players: Enter via India's PLI-designated production facilities for advanced chemistry cells, where tropical climate durability requirements and incentive disbursement windows create first-mover positioning. Target second-life stationary storage applications as the most penetrable segment, leveraging residual capacity convergence with grid-scale buffer demand.
For Investors and Strategic Acquirers: Asymmetric upside sits with equipment suppliers retrofitting lithium-ion coating lines for sodium-ion electrode stacks, given capital-light adaptation economics and Korean pilot-scale validation. Over the medium-term horizon, acquisition target archetypes include oxide cathode specialists with European automotive qualification progress. Monitor GB/T-ECHA certification reciprocity negotiations as the critical inflection signal for stranded capacity risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Hard Carbon Supply Agreement | Shanxi province feedstock control insulates margin from spot price volatility in biomass-derived anode precursors. |
| Cell-to-Pack Architecture Licensing | BYD's blade battery format adaptation for sodium-ion chemistries enables module elimination cost reduction. |
| ECHA Carbon Footprint Certification | Verified supply chain traceability accelerates EU market access timelines under Battery Regulation mandates. |
| PLI-Aligned Production Facility | India's incentive-designated capacity qualifies for bulk order channels through central electricity authority procurement. |
| Second-Life Stationary Storage Partnership | Grid-scale buffer applications extend value capture from retired automotive packs with residual capacity. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator tender managers, and hard carbon precursor producers with secondary validation from MIIT certification databases, ECHA regulatory filings, vehicle production registries, and customs trade flows. Bottom-up cell shipment tallies and top-down pack value estimates were triangulated against producer capacity disclosures.
Historical reference periods anchored the projection horizon through verified installation data and OEM platform launch timelines. The analytical framework modeled segmentation across cell format, end-user archetype, delivery mode, and technology tier, with CAGRs derived from penetration curve analysis and substitution elasticity against lithium-ion alternatives. Hard carbon precursor supply constraints and GB/T certification reciprocity evolution served as key forecast inputs.
The model holds under stable regulatory alignment between China's MIIT and EU ECHA frameworks; deviation in certification reciprocity negotiations or hard carbon feedstock export restrictions would shift capacity deployment timelines. Practitioners should monitor GB/T 38031 amendment cycles and Shanxi province environmental compliance actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market