
 Lithium Battery Components Market | 2026-2036
Lithium Battery Components Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Components Market Foresight
Direct cathode material supply agreements between Chinese producers and European automakers is tilting procurement away from spot-market lithium trading. Contemporary Amperex Technology Co. Limited anchors its position through integrated mining-to-cell operations across Jiangxi and Sichuan provinces. LG Energy Solution competes by sustaining high-nickel cathode R&D intensity in South Korean pilot facilities. Panasonic Holdings Corporation dominates cylindrical cell component supply through its long-running Tesla partnership.
Lithium battery components encompass the electrochemically active and passive materials assembled into cells, including cathodes formulated with nickel-manganese-cobalt oxide or lithium iron phosphate, anodes from synthetic or natural graphite, lithium salt electrolytes dissolved in carbonate solvents, and polyolefin microporous separators typically 12-25 micrometers thick. These components store and transfer ions between electrodes during charge and discharge cycles, enabling rechargeable energy storage for transportation and grid applications. Cathodes command the largest value share within component type segmentation due to raw material intensity and ongoing chemistry transitions toward higher nickel content. Pouch cells within form factor segmentation are capturing expanded share in electric vehicle platforms seeking packaging efficiency and weight reduction. Cell assembly within manufacturing stage segmentation concentrates margin pools where electrode coating precision and dry-room environmental control determine yield rates.
China's SAMR enforces GB standards for lithium-ion cell safety and cycling performance, while the EU Green Deal and F-Gas Regulation shape European import requirements for fluorinated electrolyte additives. The US IRA domestic content provisions are redirecting component sourcing toward North American qualified manufacturing zones. Stakeholders must monitor how regulatory divergence across these jurisdictions fragments certification requirements and capital allocation timelines.
Market Dynamics
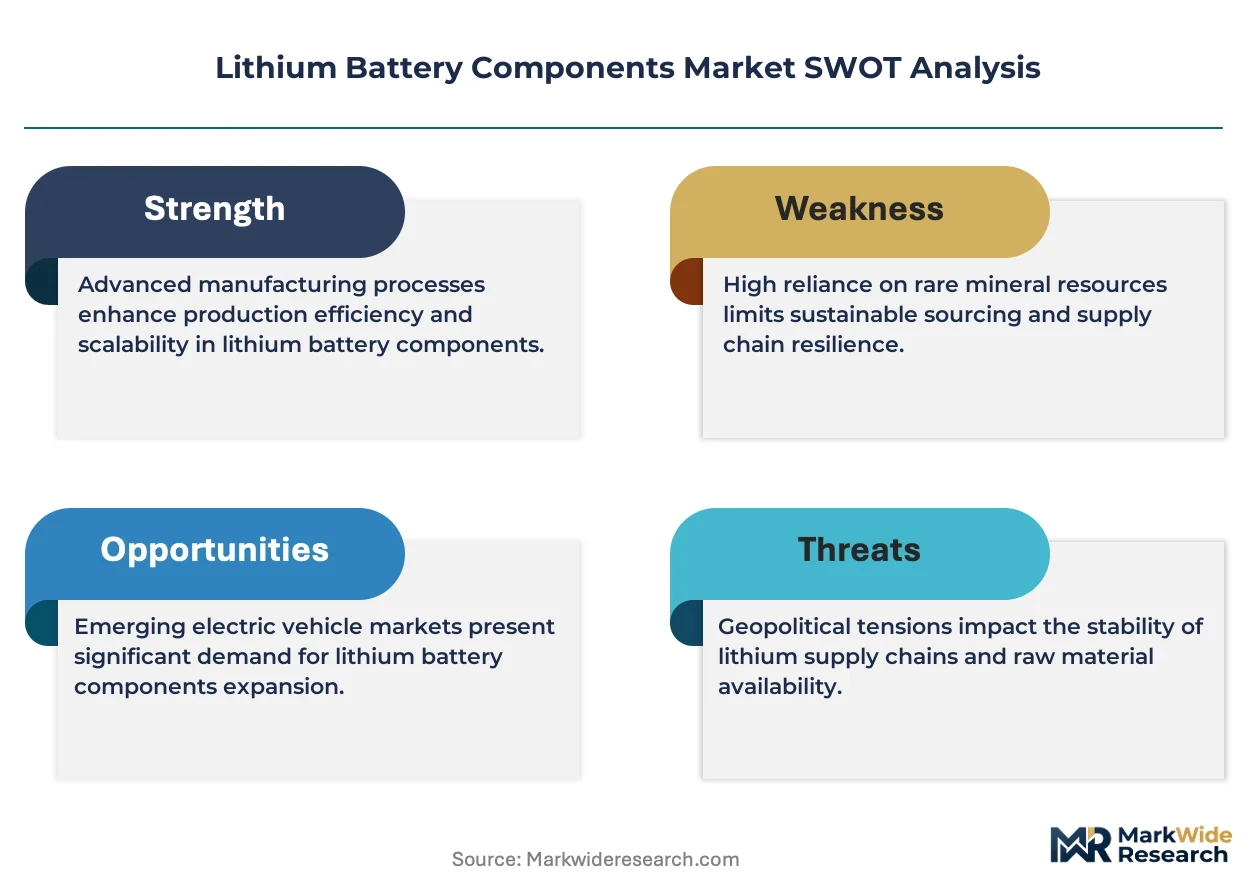
High-nickel cathode chemistry transitions are compressing supplier margins and reallocating capital toward integrated mining-to-materials operations across East Asian production clusters.
Growth Catalysts
- EU Green Deal battery passport mandates:Automakers are accelerating qualification of traceable cathode supply chains to satisfy carbon footprint disclosure requirements for European vehicle registrations.
- Electric aviation propulsion systems:Regional aircraft developers are contracting for silicon-anode pouch cells with 300+ Wh/kg targets, opening premium component demand outside automotive saturation.
- Jiangxi-Sichuan lithium belt concentration:Hard rock spodumene processing integration is shortening cathode precursor lead times for Chinese cell manufacturers serving export markets.
Market Restraints
- Fluorinated electrolyte additive cost volatility:LiPF6 and LiFSI salt prices swing with phosphorus pentachloride feedstock availability, squeezing electrolyte blender margins.
- Polyolefin separator supply concentration:Microporous membrane production clusters in South Korea and Japan create single-source vulnerability for European cell startups.
- High-nickel cathode thermal runaway thresholds:NCM 811 and 9½½ formulations require thicker ceramic coatings that reduce volumetric energy density gains.
Strategic Opportunities
- US IRA domestic content credits:North American electrode coating and dry-room assembly capacity qualifies for USD 35 per kWh production incentives through 2032.
- Grid-scale stationary storage:Lithium iron phosphate cathode demand from utility-scale battery projects is decoupling from automotive cycle timing.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separator technologies are creating qualification pathways for next-generation cell architectures.
Industry Challenges
- Electrode coating precision engineering talent:Dry-room environmental control and slot-die calibration expertise concentrates at incumbent Asian cell manufacturers.
- Multi-jurisdiction certification timelines:UN 38.3 transport testing, UL 9540A fire propagation, and GB 38031 compliance create 18-24 month product launch delays.
- Legacy cylindrical form factor retooling:21700 and 4680 winding equipment differs substantially from prismatic stacking lines, stranding capital at conversion facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Components Market |
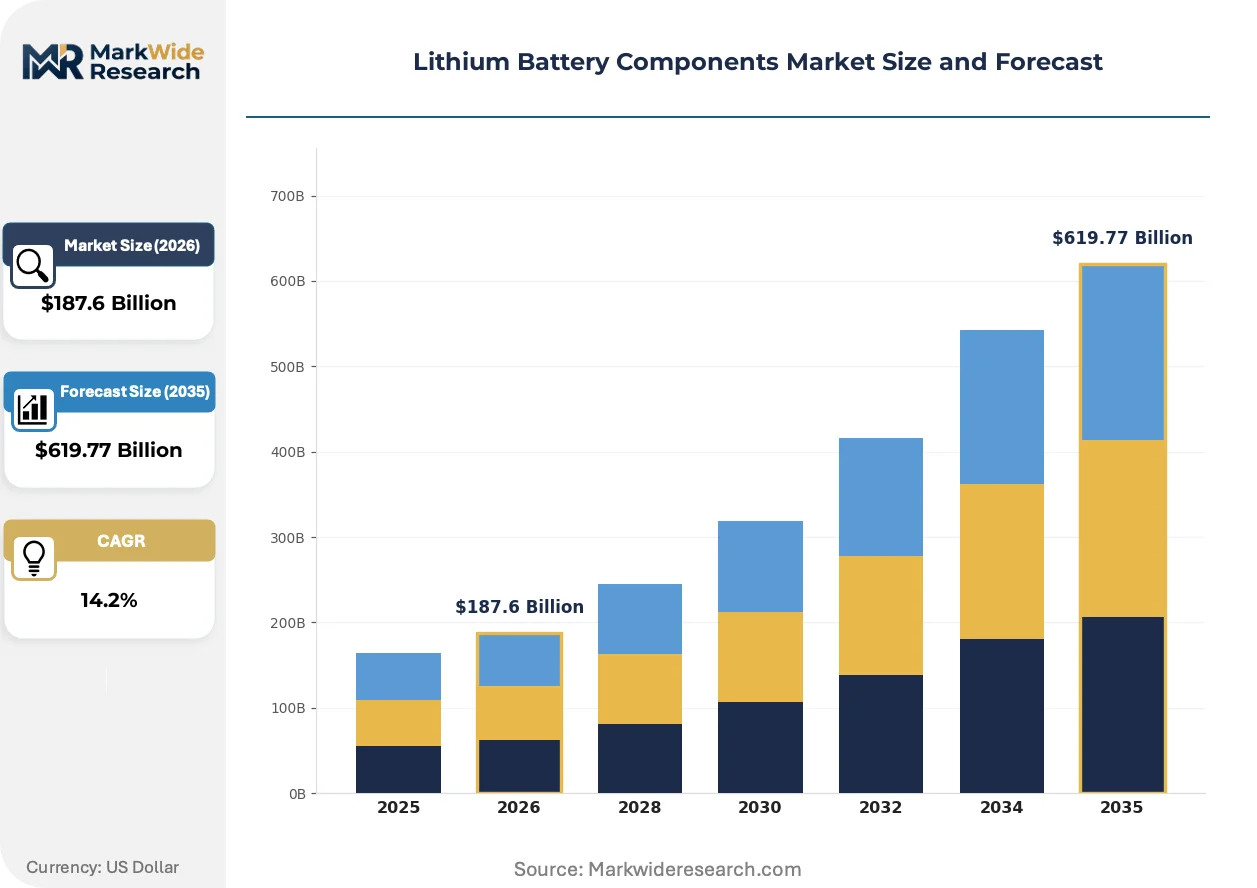
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Cathodes, Anodes, Electrolytes, Separators End User: Consumer Electronics, Electric Vehicles, Renewable Energy, Industrial Applications Form Factor: Cylindrical Cells, Prismatic Cells, Pouch Cells, Button Cells Manufacturing Stage: Raw Material Processing, Cell Assembly, Quality Control, Packaging |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, BYD Company Ltd., Samsung SDI, Albemarle Corporation, Ganfeng Lithium Co. Ltd., SQM, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Components Market Shifts & Advancements
Solid-state and silicon-anode architectures are forcing component suppliers to redesign interfaces between electrolytes, separators, and active materials.
Silicon-carbon composite anodes are migrating from cylindrical consumer cells into automotive prismatic designs. Battery engineers at European premium OEMs are qualifying 10-15% silicon loadings for 2026 platform launches. This migration from graphite-dominated anodes is compressing the energy density gap between nickel-rich and lithium iron phosphate cathode systems.
China's GB 38031 thermal propagation standards and SAMR cycling performance mandates are tightening separator puncture strength and electrolyte flash point specifications. Domestic cell manufacturers must submit third-party abuse testing documentation for vehicle platform approvals. High-voltage electrolyte additive portfolios face reformulation to pass nail penetration and overcharge protocols.
Long-term offtake contracting is displacing spot lithium carbonate purchases among cathode precursor producers. Korean and Japanese material suppliers are locking five-year supply agreements with Australian and Chilean spodumene brine operators. This shift concentrates price risk at the mining tier while stabilizing input costs for electrode coating operations in East Asian manufacturing clusters.
Lithium Battery Components Market Segmentation
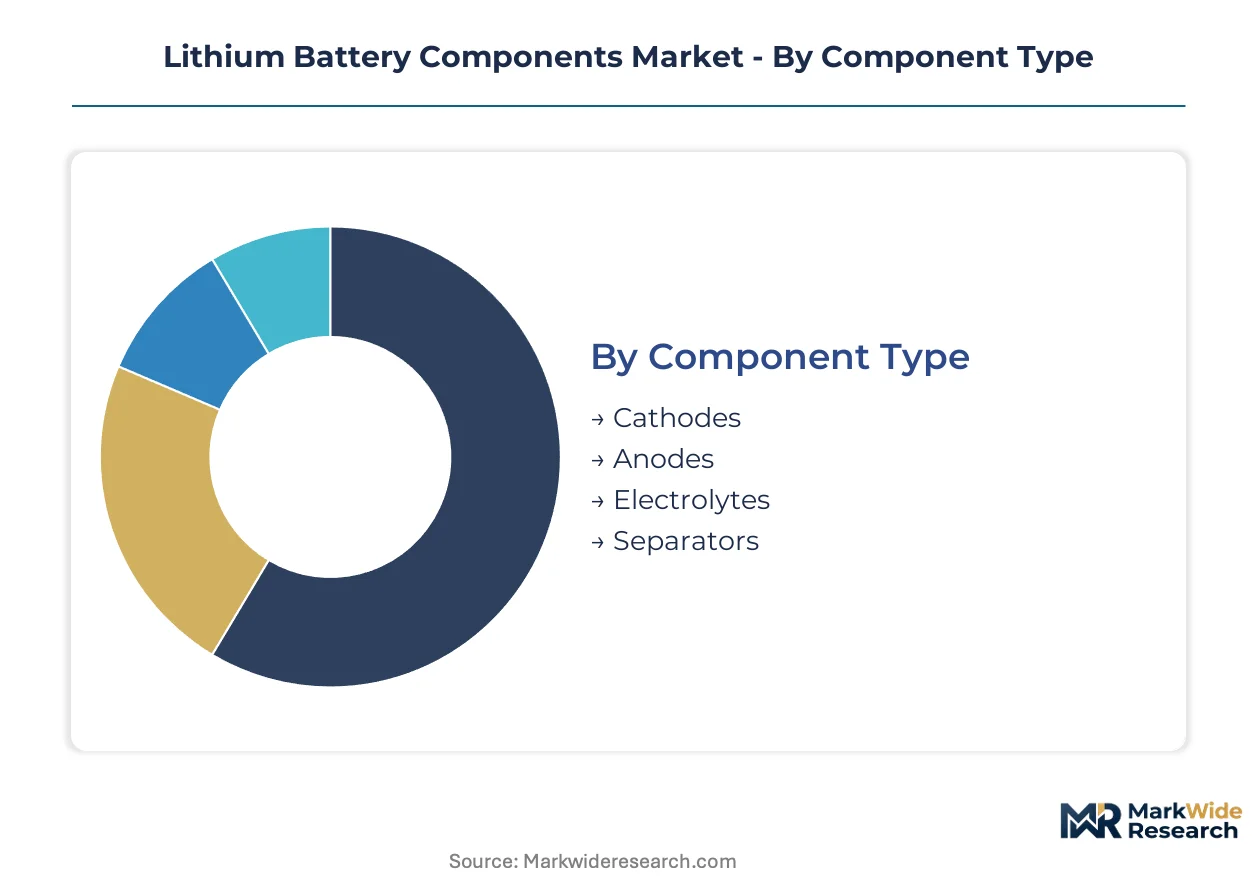
Component segmentation in lithium battery manufacturing reveals divergent investment cycles across the value chain. Raw material processing and cell assembly command multi-year capital commitments, while quality control and packaging turn over faster with technology refresh rates.
Component Type:
Cathode materials cycle through qualification timelines of 18-24 months for new chemistry introductions, while separators and electrolytes refresh formulations on 12-18 month cycles as safety standards evolve.
- Cathodes:Nickel-manganese-cobalt oxide and lithium iron phosphate formulations dominate automotive and grid storage applications. Demand concentrates in East Asian manufacturing clusters where integrated precursor production shortens lead times for cell manufacturers serving export markets.
- Anodes:Synthetic and natural graphite structures with silicon-carbon composites emerging for high-energy designs. European premium OEMs are qualifying 10-15% silicon loadings for platform launches, compressing the energy density gap between nickel-rich and lithium iron phosphate systems.
- Electrolytes:Lithium salt solutions in carbonate solvents with additive packages for high-voltage stability. LiPF6 and LiFSI salt prices swing with phosphorus pentachloride feedstock availability, squeezing blender margins.
- Separators:Polyolefin microporous membranes typically 12-25 micrometers thick with ceramic coatings for thermal stability. Microporous membrane production clusters in South Korea and Japan create single-source vulnerability for European cell startups.
Cathodes dominate installed base. Separators are where expansion concentrates.
End User:
Cost tier differentiation separates premium automotive contracts from commoditized consumer electronics supply, with renewable energy and industrial applications occupying mid-tier pricing bands.
- Consumer Electronics:Cylindrical and pouch cells for smartphones, laptops, and portable devices. This segment operates on compressed procurement cycles with annual supplier requalification and thin margins.
- Electric Vehicles:Prismatic and pouch cells with 300+ Wh/kg energy density targets. Regional aircraft developers are contracting for silicon-anode pouch cells, opening premium component demand outside automotive saturation.
- Renewable Energy:Lithium iron phosphate cathode demand from utility-scale battery projects is decoupling from automotive cycle timing. Grid-scale stationary storage creates countercyclical demand buffers.
- Industrial Applications:Forklifts, mining equipment, and material handling systems with durability requirements. This segment prioritizes cycle life over energy density, favoring conservative chemistry selections.
Electric vehicles dominate installed base. Renewable energy is climbing the fastest.
Form Factor:
Volume concentration in cylindrical cells for Tesla's 21700 and 4680 formats contrasts with prismatic stacking for Chinese automotive platforms and pouch flexibility for European OEM packaging optimization.
- Cylindrical Cells:Wound electrode structures with steel or aluminum casings. Panasonic Holdings Corporation dominates supply through its long-running Tesla partnership, though 21700 and 4680 winding equipment differs substantially from prismatic stacking lines.
- Prismatic Cells:Stacked electrode layers in rectangular aluminum housings. Chinese cell manufacturers favor this format for domestic electric vehicle platforms seeking thermal management integration.
- Pouch Cells:Flexible polymer-laminated enclosures with stacked electrodes. European automakers are capturing expanded share in electric vehicle platforms seeking packaging efficiency and weight reduction.
- Button Cells:Small-diameter disc formats for wearables and medical devices. This segment maintains stable demand with limited growth exposure to transportation electrification.
Cylindrical cells dominate installed base. Pouch cells are where expansion concentrates.
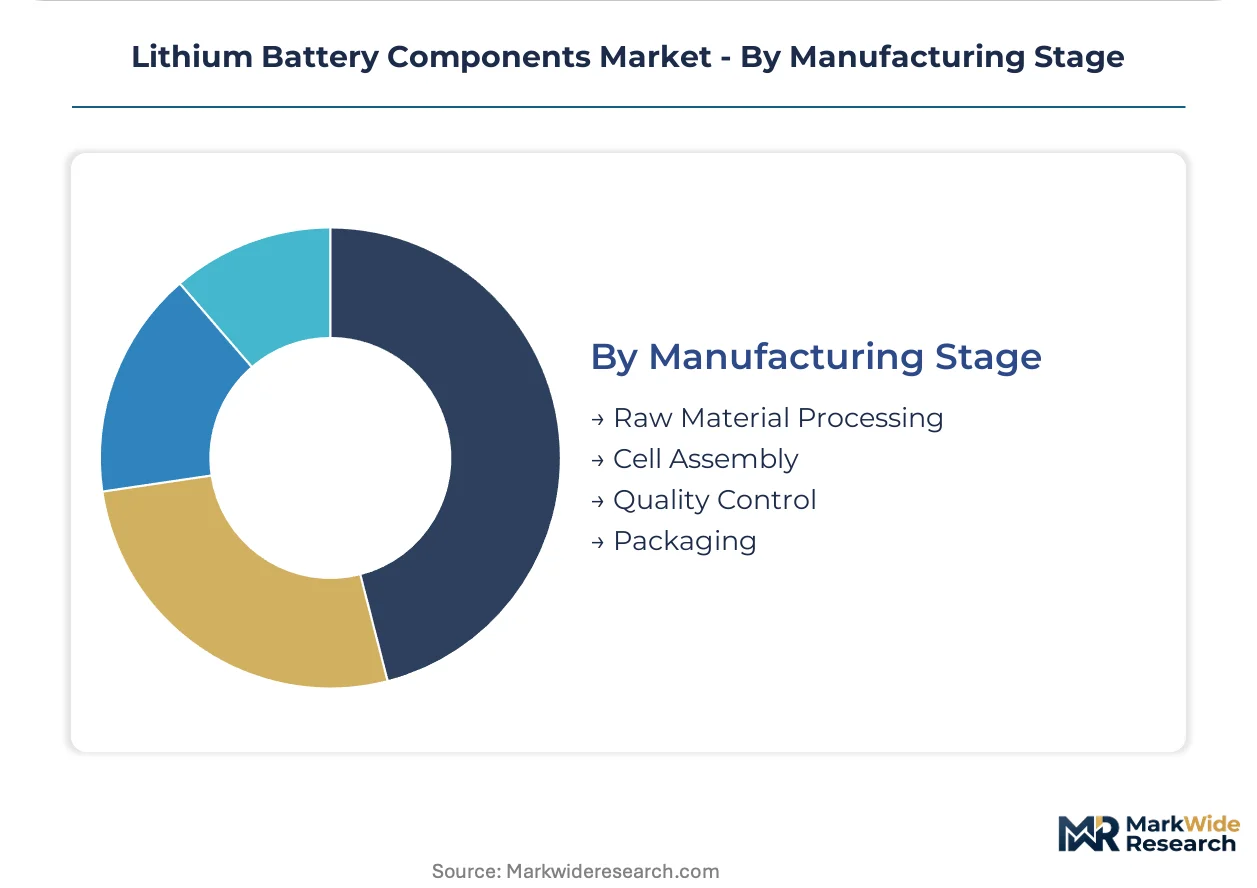
Manufacturing Stage:
Margin pools concentrate in cell assembly where electrode coating precision and dry-room environmental control determine yield rates, while raw material processing and packaging operate on thinner spreads.
- Raw Material Processing:Spodumene conversion, precursor synthesis, and active material refinement. Long-term offtake contracting is displacing spot lithium carbonate purchases among cathode precursor producers.
- Cell Assembly:Electrode coating, winding or stacking, electrolyte filling, and formation cycling. Dry-room environmental control and slot-die calibration expertise concentrates at incumbent Asian cell manufacturers.
- Quality Control:Electrochemical testing, dimensional inspection, and safety verification. UN 38.3 transport testing, UL 9540A fire propagation, and GB 38031 compliance create 18-24 month product launch delays.
- Packaging:Module assembly, battery management system integration, and thermal interface material application. This stage adapts fastest to platform-specific customer requirements.
Cell assembly dominates installed base. Quality control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cathode precursor producers extract pricing premiums from European automakers desperate for qualified supply, while North American cell startups absorb margin compression from IRA compliance costs. This asymmetry redistributes capital toward integrated mining-to-materials corridors in Jiangxi and Sichuan provinces.
China
Domestic electric vehicle platforms from BYD and CATL drive cathode material consumption at triple-digit GWh scale. SAMR enforces GB 38031 thermal propagation standards that tighten separator puncture strength specifications. The Jiangxi-Sichuan lithium belt concentrates hard rock spodumene processing capacity, shortening precursor lead times for export-oriented cell manufacturers.
South Korea
LG Energy Solution and Samsung SDI sustain high-nickel cathode R&D intensity for premium automotive contracts. MFDS coordinates with METI on cross-border battery passport data standards. Pilot facilities in Gyeonggi Province test NCM 9½½ formulations requiring thicker ceramic coatings that trade energy density for thermal stability.
Japan
Panasonic Holdings Corporation dominates cylindrical cell component supply through its Tesla partnership, anchoring demand for precision-wound electrode structures. METI's battery supply chain resilience initiatives fund domestic separator coating capacity expansion. Industrial clusters in Osaka and Nagoya prefectures concentrate dry-room environmental control expertise.
Germany
BMW and Volkswagen accelerate qualification of traceable cathode supply chains to satisfy EU Green Deal battery passport mandates for European vehicle registrations. KBA oversees UN 38.3 transport testing compliance that creates 18-24 month product launch timelines. The North Rhine-Westphalia corridor attracts electrode coating investments seeking proximity to premium OEM platform engineering centers.
United States
Tesla's 4680 cylindrical format adoption and Rivian's prismatic cell procurement drive component demand across Nevada and Illinois manufacturing zones. IRA domestic content provisions redirect electrode coating and dry-room assembly toward North American qualified manufacturing zones eligible for USD 35 per kWh production incentives through 2032. Michigan and Ohio sub-regions compete for cathode precursor plant siting decisions.
Lithium Battery Components Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where chemistry transitions and qualification timelines determine margin capture. The supplier base organizes into three tiers: integrated mining-to-cell conglomerates with captive precursor supply, independent material specialists competing on formulation agility, and regional fabricators serving protected domestic markets. Consolidation pressure concentrates at the cathode tier where raw material intensity rewards scale. Dominant competitive moves include backward integration into spodumene conversion assets and strategic partnerships locking five-year offtake agreements with Australian and Chilean mining operators.
Among East Asian integrated producers, Contemporary Amperex Technology Co. Limited and LG Energy Solution exemplify the mining-to-cell archetype through upstream control over Jiangxi hard rock and Korean precursor synthesis respectively. Panasonic Holdings Corporation occupies a distinct position within cylindrical cell component supply, representing the long-running platform partnership model with premium automotive OEMs. These three anchors demonstrate how geography and form factor specialization stratify competitive positioning.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Ltd. |
| Samsung SDI |
| Albemarle Corporation |
| Ganfeng Lithium Co. Ltd. |
| SQM |
| Umicore |
| Others |
Supply & Pricing Matrix
Single-source dependency on South Korean and Japanese separator production concentrates pricing power with incumbent membrane suppliers while forcing European cell startups into premium procurement tiers. This structural chokepoint widens spreads between qualified automotive-grade supply and commoditized industrial-grade alternatives, compressing margins for buyers locked out of long-term offtake agreements.
Pricing Analysis
Configured-to-order pricing for high-nickel cathode precursors commands substantial premiums over standard NCM 523 formulations, with contract structures stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation stems from SAMR cycling performance compliance costs and geographic delivery premiums to European automakers. Cost compression in electrolyte blending intensifies because phosphorus pentachloride feedstock volatility squeezes LiPF6 and LiFSI salt margins. Grid-scale stationary storage buyers exhibit highest price sensitivity due to project finance constraints, while premium automotive OEMs absorb certification premiums for traceable supply chains.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for electrode coating equipment and precursor materials. Geographic supply concentration centers on China, South Korea, and Japan, where Jiangxi-Sichuan hard rock processing, Gyeonggi Province high-nickel R&D, and Osaka-Nagoya dry-room expertise anchor production. Raw material dependencies rest on Australian spodumene, Chilean brine concentrates, and Japanese polyolefin resin. Single-source vulnerability permeates microporous membrane supply. Distribution runs through direct cathode precursor agreements with cell manufacturers, displacing spot lithium carbonate markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery passport interoperability between EU Green Deal mandates and Chinese SAMR disclosure standards is creating platform-economics inflection, rewarding suppliers with cross-jurisdiction qualification capabilities.
For Market Incumbents: Build captive precursor supply moats through backward integration into Jiangxi hard rock conversion assets and Korean NCM 9½½ pilot facilities. Secure five-year offtake agreements with Australian and Chilean mining operators to lock spodumene pricing before commodity volatility escalates. Invest in dual GB 38031 and UL 9540A certification capacity to defend against European cell startups qualifying domestic separator coating lines. For New Entrants and Emerging Players: North American electrode coating capacity in Michigan and Ohio sub-regions represents the most penetrable entry point, with IRA domestic content credits offsetting dry-room capital intensity. Silicon-anode pouch cell supply for regional aviation propulsion systems offers premium pricing outside automotive procurement saturation. Pursue joint qualification programs with European premium OEMs seeking packaging efficiency alternatives to cylindrical dominance. For Investors and Strategic Acquirers: The market sits at a chemistry-transition phase that favors integrated mining-to-materials conglomerates over independent formulation specialists. Long-term viability over the next decade hinges on upstream control over lithium belt assets and downstream cell assembly partnerships. Watch for solid-state electrolyte convergence milestones as inflection indicators separating sulfide-ceramic qualification leaders from stranded oxide-ceramic capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spodumene Conversion | Jiangxi hard rock processing shortens cathode precursor lead times for export markets. |
| Dual-Jurisdiction Certification Investment | GB 38031 and UL 9540A compliance opens European and North American automotive contracts simultaneously. |
| Long-Term Cathode Precursor Offtake Agreements | Five-year supply locks with Australian miners stabilize input costs against carbonate spot volatility. |
| Solid-State Electrolyte R&D Partnership | Sulfide ceramic separator qualification creates pathways for next-generation cell architectures. |
| North American Dry-Room Assembly Capacity | Nevada and Illinois zones qualify for IRA production incentives through 2032. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade data, SAMR regulatory filings, and IEA battery supply chain reports. Primary interviews engaged cathode precursor procurement managers at European automakers, dry-room environmental control engineers at Japanese cell manufacturers, electrolyte formulation specialists at Korean material suppliers, and lithium mining operations planners at Australian and Chilean spodumene producers. Bottom-up cell production capacity modeling triangulates against top-down cathode material consumption estimates across the analysis window.
Forecast inputs span component type segmentation by cathode chemistry, anode silicon loading percentage, separator ceramic coating thickness, and electrolyte additive portfolio composition. End-use segmentation incorporates electric vehicle platform energy density targets, grid-scale stationary storage project pipelines, and regional aviation propulsion system contracts. Form factor segmentation tracks cylindrical, prismatic, and pouch cell winding equipment capital allocation. Manufacturing stage segmentation models electrode coating precision yield rates and dry-room environmental control operating costs. CAGRs derive from installed base replacement cycles and chemistry transition adoption curves.
Practitioners should monitor solid-state electrolyte pilot production yields, IRA domestic content credit qualification thresholds, and EU Green Deal battery passport implementation timelines for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Global Lithium Mining Market