
 Process Plants Gas Turbine Market | 2026-2036
Process Plants Gas Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Process Plants Gas Turbine Market Insights
Aftermarket service channels for process plant gas turbines is tilting toward long-term service agreements bundled with digital monitoring. GE Vernova leverages its predictive analytics platform to lock in decade-long maintenance contracts with refinery operators. Siemens Energy anchors its position through regional service hubs that shorten turbine outage windows for petrochemical clients. Mitsubishi Heavy Industries competes on advanced blade coatings that extend hot gas path component life in sour gas environments.
Process plants gas turbines are rotating prime movers that convert thermal energy from compressed air-fuel combustion into mechanical shaft power, typically operating at inlet temperatures exceeding 1,300°C and driving compressors, pumps, or generators in continuous-duty industrial settings. Combined cycle configurations capture exhaust heat to raise steam for secondary power generation, delivering superior thermal efficiency for utilities and independent power producers. Heavy-duty gas turbines dominate margin pools in baseload chemical plant applications where durability outweighs startup agility, while aeroderivative turbines lead growth in peaking and mechanical drive roles across LNG liquefaction trains.
EPA New Source Performance Standards and MEE emission decrees in China mandate sub-25 ppm NOx output for new gas turbine installations, forcing OEMs to advance dry low emission combustor architectures. ISO 3977 and API 616 establish mechanical integrity benchmarks that gate market access for non-compliant equipment suppliers. Stakeholders must weigh hydrogen fuel blending roadmaps against current turbine material limits when specifying new units for net-zero-aligned process plants.
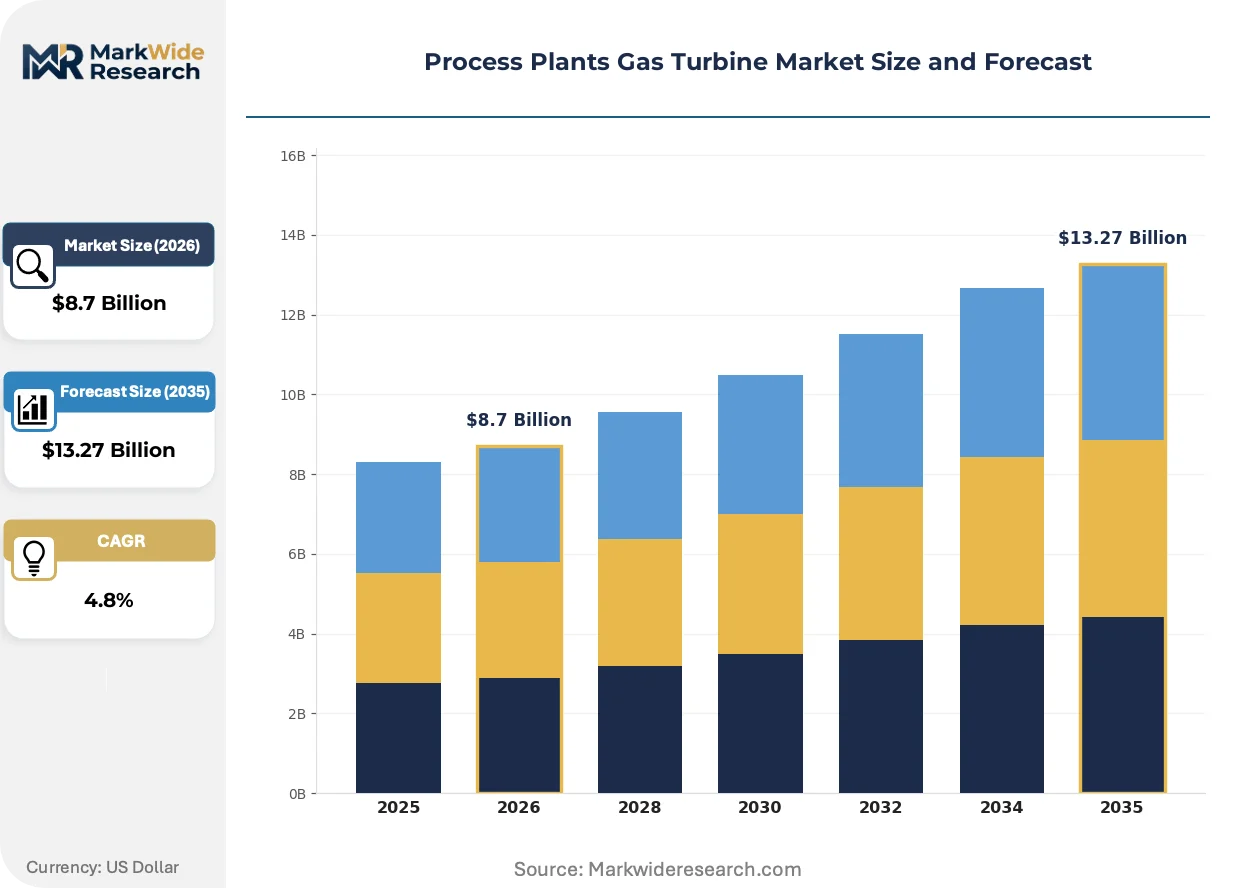
Market Dynamics
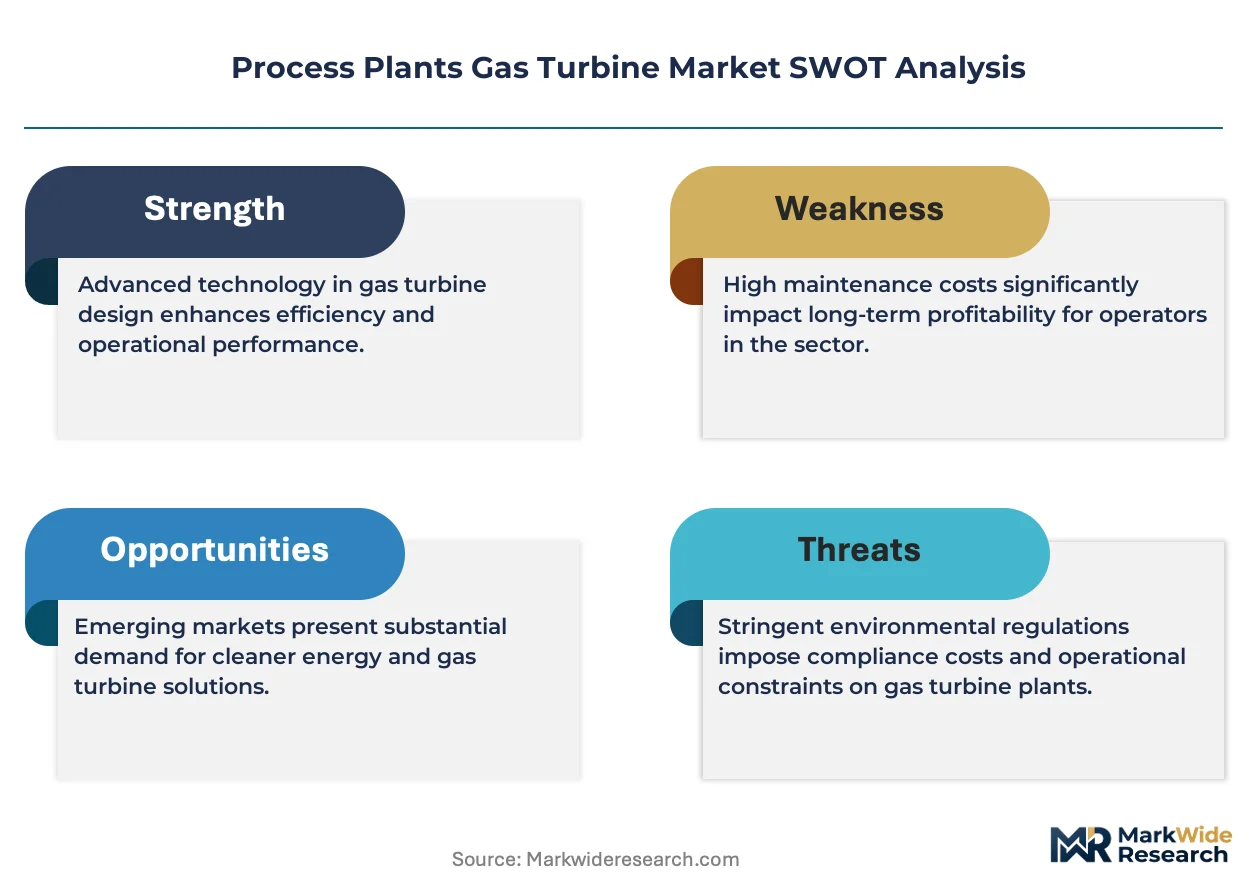
Refinery operators face mounting pressure to decarbonize thermal power systems while maintaining baseload reliability for continuous chemical processing. The tension between hydrogen fuel readiness and current turbine metallurgy limits is forcing premature capital planning cycles across petrochemical complexes.
Growth Catalysts
- EPA New Source Performance Standards:Sub-25 ppm NOx mandates accelerate dry low emission combustor retrofits across US Gulf Coast refineries. Upgrades trigger fleet-wide replacement cycles for aging Frame 5 and Frame 7 units.
- LNG liquefaction expansion:Mechanical drive applications for aeroderivative turbines multiply as Qatar and Mozambique greenfield projects advance. Baseload power demand from LNG trains exceeds utility-scale installations in project pipelines.
- Sour gas processing growth:Hot gas path components with advanced thermal barrier coatings extend maintenance intervals in hydrogen sulfide-rich environments. Petrochemical clusters in Jubail and Yanbu specify corrosion-resistant blade architectures.
Market Restraints
- Superalloy supply concentration:Single-source dependency for directionally solidified turbine blades from precision casting foundries in Germany and Japan creates vulnerability. Nickel-cobalt alloy price volatility directly impacts OEM margins.
- Hydrogen embrittlement limits:Current rotor disk and combustion liner materials constrain hydrogen fuel blending to sub-30% by volume without catastrophic creep acceleration. Material science roadmaps lag net-zero commitments by 10-15 years.
- Extended OEM lead times:Heavy-duty gas turbine manufacturing backlogs at primary assembly facilities stretch 24-36 months. Project developers defer chemical plant expansions rather than absorb schedule risk.
Strategic Opportunities
- Carbon capture integration:Post-combustion amine scrubbing retrofits on existing gas turbine exhaust streams unlock IRA tax credits for US refinery operators. Combined cycle configurations optimize heat recovery for solvent regeneration.
- Digital twin deployment:Physics-based performance modeling converges with operational data streams to predict compressor surge margins. Predictive maintenance contracts displace time-based overhaul schedules in Middle Eastern petrochemical hubs.
- Ammonia fuel pilot programs:Japanese METI funding accelerates turbine combustor testing for maritime-derived ammonia cracking. Power-to-X projects in Rotterdam and Singapore evaluate ammonia as hydrogen carrier for grid-scale storage.
Industry Challenges
- Specialized welding technician scarcity:Inconel and Haynes alloy repair procedures require ASME Section IX certified welders with superalloy experience. Training pipelines fail to match retirement rates in North American and European maintenance bases.
- API 616 compliance timelines:Third-party verification of mechanical integrity for custom compressor train configurations extends factory acceptance testing by 4-6 months. Documentation bottlenecks delay commercial operation dates.
- Legacy control system integration:Proprietary OEM turbine control architectures resist interoperability with modern distributed control systems. Refinery automation upgrades stall on protocol translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Plants Gas Turbine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Gas Turbines, Aeroderivative Turbines, Heavy-Duty Gas Turbines, Simple Cycle Turbines, Combined Cycle Turbines Technology: Dry Low Emission, Wet Low Emission, Reciprocating Engines, Steam Injection, Regenerative Cycle Application: Refining, Petrochemical Manufacturing, Power Generation, Natural Gas Compression, Mining Operations End User: Oil & Gas Producers, Chemical Manufacturers, Independent Power Producers, Mining Companies, Utilities |
| Companies Covered | GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, Ansaldo Energia, Baker Hughes, Rolls-Royce, IHI Corporation, Bharat Heavy Electricals, Solar Turbines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Plants Gas Turbine Market Trends and Innovations
Digital monitoring architectures are compressing maintenance intervals while regulatory pressure on nitrogen oxides forces combustor redesign. Equipment suppliers now bundle predictive analytics with hardware sales to capture aftermarket revenue streams.
Additive manufacturing is digitizing repair workflows for hot gas path components. Siemens Energy operates laser powder bed fusion cells for blade tip restoration at regional service hubs in Dammam and Singapore. Refinery operators receive restored airfoils with 40% faster turnaround than conventional casting replacement, compressing planned outage windows from 45 days to 28 days.
China's MEE emission decrees mandate continuous emissions monitoring systems for all new gas turbine installations above 50 MW thermal input. OEMs must certify dry low emission combustor architectures through third-party stack testing. Domestic suppliers in Shandong and Jiangsu provinces accelerate indigenous combustor development to avoid import dependency for NOx-compliant systems.
Long-term service agreements now displace transactional spare parts purchasing among Middle Eastern petrochemical operators. Saudi Aramco and SABIC affiliates negotiate decade-long maintenance contracts with guaranteed availability clauses. Channel intermediaries lose relevance as OEMs establish direct regional service organizations with localized parts inventories and dedicated field engineering teams.
Process Plants Gas Turbine Market Segmentation
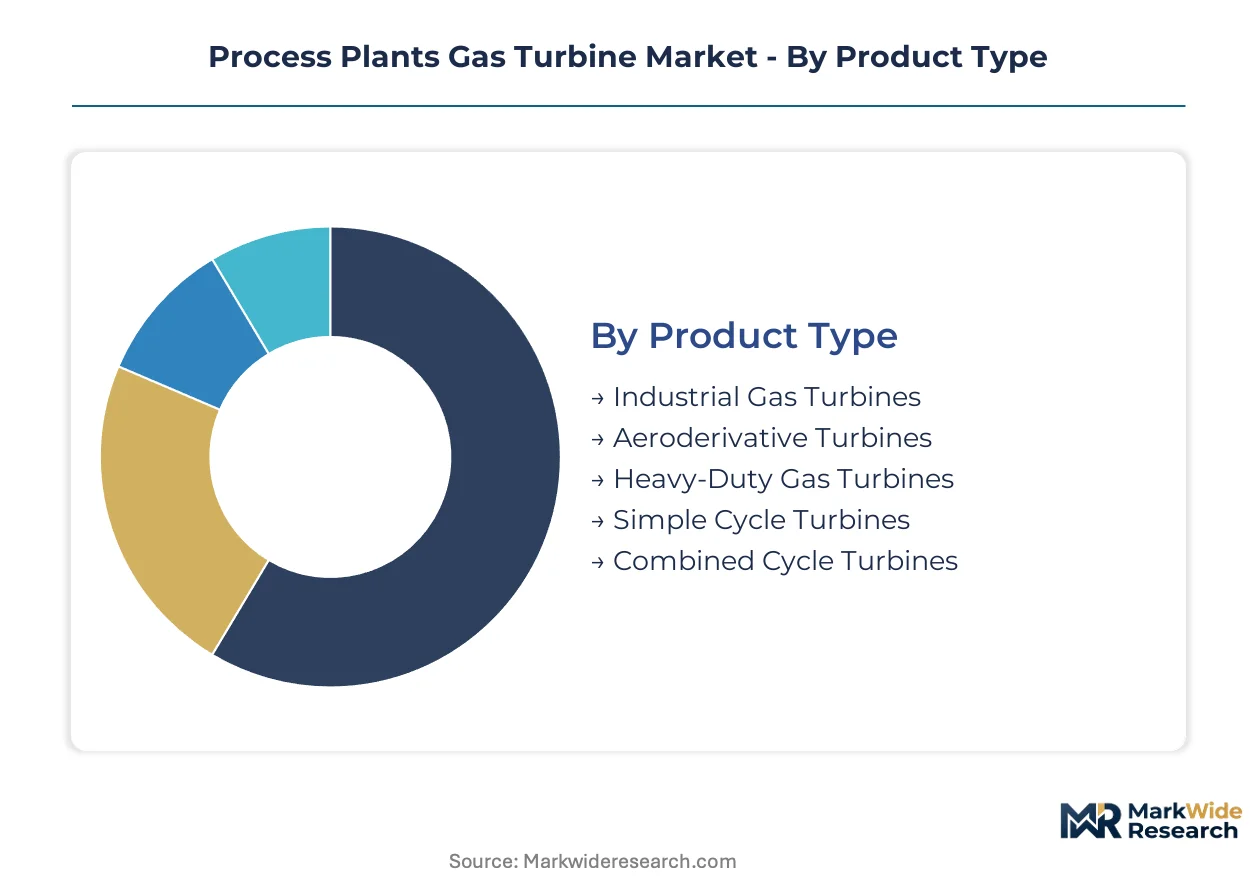
Segmentation in the process plants gas turbine market reveals distinct replacement cycles and margin profiles across equipment categories. Refinery operators and petrochemical producers prioritize different performance attributes when specifying turbines for continuous-duty applications versus peaking roles.
Product Type:
Replacement cycles vary dramatically across turbine architectures, with aeroderivative units turning over fastest due to flight-heritage maintenance protocols while heavy-duty frames persist for decades in baseload chemical service.
- Industrial Gas Turbines:Purpose-built rotating equipment optimized for mechanical drive and power generation in continuous industrial process environments. Demand concentrates in Saudi Arabia's Jubail Industrial City where petrochemical megaprojects require multi-unit installations for compressor train redundancy. EPA New Source Performance Standards mandate dry low emission combustor integration for new installations.
- Aeroderivative Turbines:Aviation-derivative engines adapted for industrial mechanical drive and peaking power applications with rapid startup capabilities. Qatar and Mozambique LNG liquefaction projects specify LM6000 and Trent 60 variants for refrigeration compressor duty. Shorter maintenance intervals reflect flight-heritage component lifing methodologies.
- Heavy-Duty Gas Turbines:Frame-scale industrial turbines designed for decades-long baseload operation in utility and chemical plant service.
- Simple Cycle Turbines:Single-shaft configurations optimized for mechanical drive without heat recovery steam generation.
- Combined Cycle Turbines:Integrated gas turbine-steam turbine systems capturing exhaust heat for secondary power generation.
Heavy-duty gas turbines anchor the volume base while aeroderivative turbines gain share at the steepest rate.
Technology:
Technology selection follows emissions compliance requirements and fuel flexibility specifications, with cost tiers separating proven combustor architectures from emerging low-carbon alternatives.
- Dry Low Emission:Lean-premixed combustor technology reducing NOx formation through controlled fuel-air mixing without water or steam injection. China's MEE emission decrees mandate sub-25 ppm NOx certification for all new installations above 50 MW thermal input. OEMs face third-party stack testing requirements for market access.
- Wet Low Emission:Water or steam injection into combustion zones suppressing flame temperatures to limit thermal NOx formation. US Gulf Coast refineries retrofit aging Frame 5 and Frame 7 units to meet EPA New Source Performance Standards. Water treatment infrastructure adds capital burden versus dry low alternatives.
- Reciprocating Engines:Piston-based prime movers offering fuel flexibility and rapid load response for distributed power applications.
- Steam Injection:Water vapor introduction into combustor or turbine flow path for power augmentation and emissions control.
- Regenerative Cycle:Heat exchanger-based systems recovering exhaust energy to preheat combustion air.
Dry low emission technology commands the premium tier while wet low emission systems dominate retrofit installations.
Application:
Application segmentation tracks capital deployment intensity across process industries, with refining and petrochemical manufacturing driving the largest unit sizes and longest service agreements.
- Refining:Fluid catalytic cracker air blower and hydrogen plant compressor drive applications requiring 99.9% availability. US Gulf Coast operators face EPA-mandated NOx compliance deadlines triggering fleet-wide upgrade cycles. Sour crude processing growth demands corrosion-resistant hot gas path coatings.
- Petrochemical Manufacturing:Ethylene cracker charge gas compressor and refrigeration train mechanical drive duty. Saudi Arabia's SABIC affiliates negotiate decade-long maintenance contracts with guaranteed availability clauses. Baseload power demand exceeds utility-scale installations in project pipelines.
- Power Generation:On-site electricity production for industrial complexes and independent power producers.
- Natural Gas Compression:Pipeline booster and storage injection compressor drive applications.
- Mining Operations:Remote power and mechanical drive for mineral processing and materials handling.
Refining anchors installed capacity while petrochemical manufacturing expands most quickly on megaproject development.
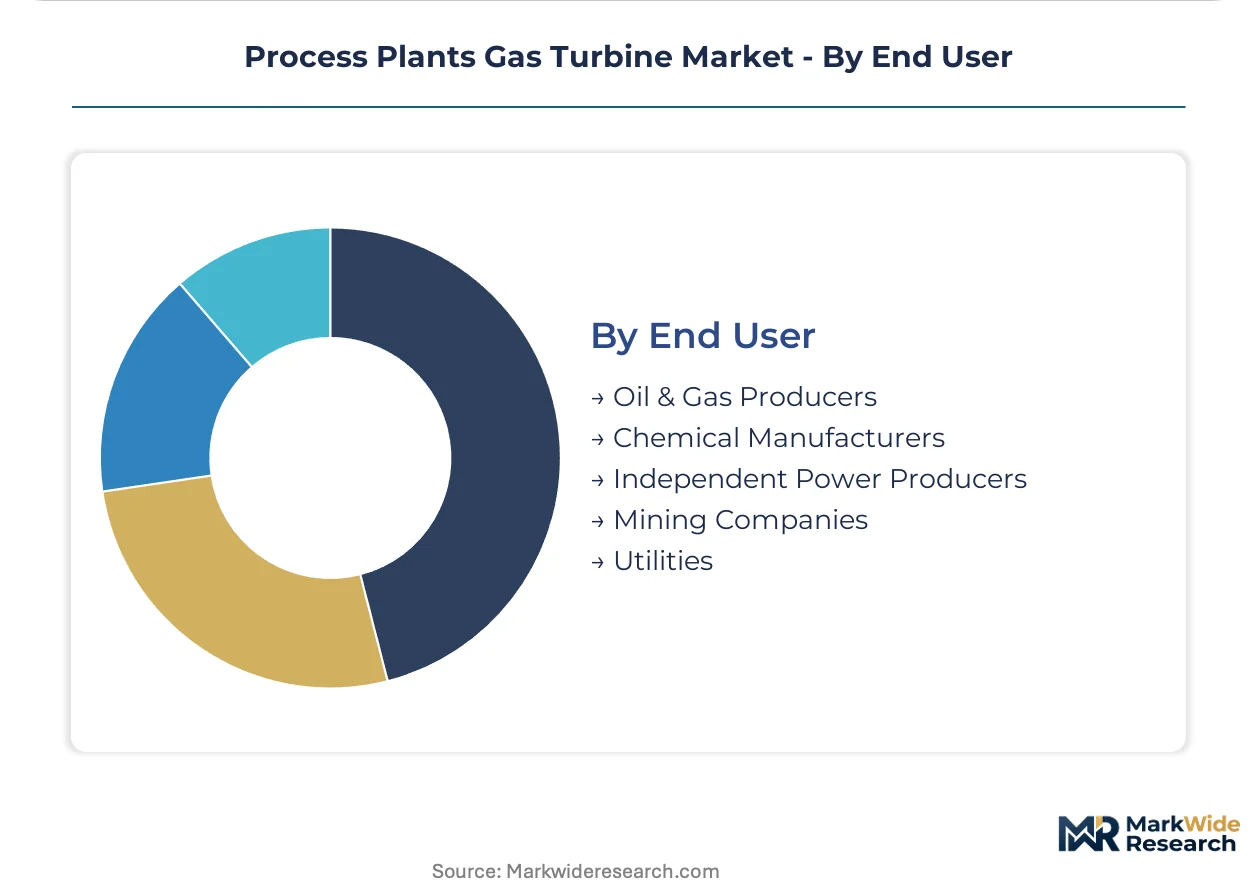
End User:
End user procurement patterns diverge between integrated majors with captive engineering capabilities and independent operators reliant on OEM service networks.
- Oil & Gas Producers:Upstream and midstream operators specifying turbines for production facility and pipeline compression duty. Integrated majors leverage long-term service agreements bundling predictive analytics with hardware procurement. Regional service hub proximity influences supplier selection.
- Chemical Manufacturers:Petrochemical and specialty chemical producers with continuous process reliability requirements. Saudi Aramco and SABIC affiliates drive Middle Eastern demand concentration through direct OEM relationships. Channel intermediaries lose relevance as localized parts inventories expand.
- Independent Power Producers:Merchant power developers without integrated fuel supply or offtake arrangements.
- Mining Companies:Extractive industry operators with remote site power and mechanical drive needs.
- Utilities:Regulated and deregulated electric power generators serving grid-connected markets.
Chemical manufacturers anchor procurement volume while independent power producers show the steepest contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Cooperation Council's pipeline network underwrites the Middle East's dominance in process plant gas turbine deployment. Jubail Industrial City's concentrated petrochemical infrastructure drives multi-unit procurement cycles for baseload mechanical drive applications.
United States
US Gulf Coast refineries expand aeroderivative fleets to process heavier domestic crude slates. EPA New Source Performance Standards mandate sub-25 ppm NOx compliance for new installations, triggering dry low emission combustor retrofits across Texas and Louisiana processing corridors. Corpus Christi and Houston ship channel complexes anchor replacement demand for aging Frame 5 and Frame 7 units.
Saudi Arabia
Saudi Aramco and SABIC affiliates negotiate decade-long maintenance contracts with guaranteed availability clauses. The country's national petroleum regulator enforces continuous emissions monitoring for all installations above 50 MW thermal input. Jubail and Yanbu industrial cities concentrate demand for corrosion-resistant hot gas path components in sour gas processing environments.
China
Shandong and Jiangsu province petrochemical clusters accelerate indigenous combustor development to avoid import dependency. MEE emission decrees mandate third-party stack testing certification for dry low emission architectures. Yangtze River Delta refineries retrofit wet low emission systems to meet tightening NOx limits ahead of 2025 compliance deadlines.
Germany
Ruhr Basin chemical manufacturers face EU Green Deal pressure to decarbonize thermal power systems while maintaining process reliability. ECHA REACH regulations constrain superalloy supply chains for precision-cast turbine blades. BASF Ludwigshafen and Bayer Leverkusen complexes pilot hydrogen fuel blending programs constrained by current rotor disk material limits.
Qatar
North Field LNG expansion projects specify LM6000 and Trent 60 variants for refrigeration compressor mechanical drive duty. The country's national petroleum regulator mandates emissions monitoring for all new liquefaction train installations. Ras Laffan Industrial City concentrates baseload power demand exceeding utility-scale installations in regional project pipelines.
Process Plants Gas Turbine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision casting and coating niches. The vendor base concentrates around three OEMs with full-scope capabilities spanning heavy-duty frames, aeroderivative adaptations, and long-term service agreements. Strategic archetypes separate full-line turbine OEMs from regional service hub operators and advanced materials specialists. Competitive moves center on captive service network expansion and predictive analytics platform deployment to lock in aftermarket revenue streams.
Within the full-line OEM tier, GE Vernova, Siemens Energy, and Mitsubishi Heavy Industries anchor global supply. GE Vernova represents the analytics-integrated service model, bundling predictive platforms with decade-long maintenance contracts. Siemens Energy exemplifies regional hub localization, compressing outage windows through distributed service infrastructure. Mitsubishi Heavy Industries occupies the advanced materials specialist position, extending component life in corrosive process environments through proprietary coating architectures.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Ansaldo Energia |
| Baker Hughes |
| Rolls-Royce |
| IHI Corporation |
| Bharat Heavy Electricals |
| Solar Turbines |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency for directionally solidified turbine blades from precision casting foundries in Germany and Japan compresses pricing power for OEMs while forcing buyers into long-term offtake commitments. This concentration simultaneously widens tier spreads between premium superalloy architectures and standard-grade alternatives, and locks supply chain configuration around regional hub-and-spoke service networks.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with petrochemical megaprojects securing 15-20% unit cost reductions on multi-turbine orders versus single-unit refinery purchases. Price differentiation hinges on hot gas path coating specifications and dry low emission combustor certification tiers. Cost compression in standard-grade heavy-duty frames is intensifying because Chinese domestic suppliers are undercutting European OEMs on wet low emission retrofits. Independent power producers exhibit highest price sensitivity due to merchant power margin volatility, while integrated chemical majors prioritize availability guarantees over upfront capital.
Supply Chain Analysis
Extended payment terms from 90 to 180 days are becoming standard for superalloy ingot procurement, with supply-chain finance facilities bridging working capital gaps for precision casting foundries. Manufacturing concentrates in Germany, Japan, and the United States for critical hot gas path components. The supply chain draws from nickel-cobalt alloy feedstock, ceramic thermal barrier coatings, and specialized welding consumables. Single-source vulnerability for directionally solidified blade castings creates structural risk. Distribution runs through OEM-captive regional service hubs with localized parts inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process plant gas turbines face high-growth disruption as EPA and MEE NOx mandates force fleet-wide combustor replacement cycles, compressing capital planning horizons and opening white-space for hydrogen-ready architectures.
For Market Incumbents: Insulate aftermarket revenue streams by deepening captive service network density in Middle Eastern petrochemical clusters, and accelerate certification investment for 30%+ hydrogen fuel blending before material science roadmaps mature. Dry low emission combustor retrofits and emerging ammonia fuel pilots threaten installed base lock-in for OEMs without advanced coating portfolios. For New Entrants and Emerging Players: Southeast Asian LNG liquefaction projects represent underpenetrated territory where aeroderivative mechanical drive specifications remain fluid. White-space exists in digital twin deployment for predictive maintenance, and in corrosion-resistant blade architectures for sour gas processing. A joint-venture go-to-market with established EPC contractors bypasses OEM service network disadvantages. For Investors and Strategic Acquirers: EPA New Source Performance Standards and MEE emission decrees reshape the acquisition landscape toward hydrogen-ready turbine portfolios and carbon capture integration capabilities. Long-term viability centers on OEMs with demonstrated dry low emission certification and regional service hub infrastructure. The signal to watch is ammonia fuel pilot program announcements from Japanese METI-funded consortia, which would accelerate material science investment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Hub Expansion | OEM-captive facilities in Dammam and Singapore compress outage windows for SABIC affiliates. |
| Dry Low Emission Combustor Certification | Third-party stack testing under MEE decrees gates market access for Chinese installations. |
| Advanced Thermal Barrier Coating Development | Proprietary architectures from Mitsubishi Heavy Industries extend life in Jubail sour gas environments. |
| Digital Twin Platform Deployment | Physics-based modeling from GE Vernova displaces time-based overhaul schedules. |
| Hydrogen Fuel Blending Roadmap | Rotor disk material limits constrain blending to sub-30% without creep acceleration. |
Research Methodology
Initial hypotheses were tested against primary input from refinery maintenance directors, petrochemical project developers, OEM aftermarket service heads, and precision casting procurement leads, and refined through secondary validation. Primary fieldwork drew from plant engineer interviews at Jubail and Yanbu industrial complexes, while secondary sources included EPA New Source Performance Standards filings, MEE emission decree documentation, and API 616 mechanical integrity specifications. Bottom-up unit deployment tracking triangulated against top-down petrochemical capacity expansion databases.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling capacity additions against replacement cycle timing. Segmentation dimensions included turbine architecture type, combustor technology tier, application intensity, and regional regulatory cluster. CAGRs derived from unit shipment trajectories weighted by thermal capacity ratings and service agreement attach rates. Forecast inputs incorporated LNG liquefaction train development pipelines and refinery NOx compliance deadlines.
Practitioners should monitor superalloy price volatility, hydrogen embrittlement material breakthroughs, and EPA enforcement discretion for early signals of forecast deviation. The analysis reflects assumptions regarding sustained petrochemical megaproject investment and gradual hydrogen fuel blending adoption. Macroeconomic contraction, regulatory acceleration, or step-change turbine efficiency gains would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Turbine Governor Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Levant Power Cable Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Japan Power EPC Market
Power Equipment
Turbine Control Systems Market
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Thailand Power EPC Market