
 Lithium Battery Grade Lithium Carbonate Market | 2026-2036
Lithium Battery Grade Lithium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Grade Lithium Carbonate Market Analysis
Downstream cathode active material production is tilting toward integrated lithium-to-battery supply chains, pulling margin pools away from standalone trading. Albemarle Corporation anchors North American lithium conversion through its Silver Peak and Kings Mountain operations. Ganfeng Lithium Co., Ltd. leverages captive brine and spodumene resources across Argentina and Australia to sustain cost-competitive battery-grade output. Sociedad Química y Minera de Chile S.A. dominates Atacama brine extraction, while Tianqi Lithium Corporation controls the Greenbushes hard-rock concentrate stream feeding Chinese refineries.
Lithium battery grade lithium carbonate is a high-purity lithium salt exceeding 99.5% Li₂CO₃, produced through brine evaporation or spodumene acid roasting followed by purification sequences including solvent extraction and crystallization, serving primarily as the lithium precursor for lithium iron phosphate and nickel-cobalt-manganese cathode chemistries. Battery grade product commands the dominant value share as electric vehicle cathode specifications tighten impurity thresholds for sodium, magnesium, and calcium below 50 ppm. Electric Vehicles application leads volume absorption, while Renewable Energy Storage represents the fastest-expanding demand pool as grid-scale lithium iron phosphate installations multiply. Direct Sales distribution channels capture the largest margin pools through long-term offtake agreements between refiners and cathode manufacturers.
China's SAMR enforces GB/T 26008 purity standards for battery-grade lithium carbonate, while the EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for batteries placed on the European market. The EPA oversees lithium extraction wastewater discharge under the Clean Water Act in the United States, constraining brine and hard-rock project permitting timelines. Stakeholders must monitor evolving regulatory thresholds for traceability, carbon intensity accounting, and circular material content that will determine qualified supplier status across major automotive procurement frameworks.
Market Dynamics
The lithium battery grade lithium carbonate market is undergoing a structural compression as cathode manufacturers consolidate procurement through direct long-term offtake agreements, bypassing traditional commodity traders and capturing margin pools previously held by intermediaries.
Growth Catalysts
- EU Battery Regulation:Mandates for carbon footprint declarations and recycled content thresholds are forcing cathode producers to qualify certified low-carbon lithium sources, creating premium demand pools for traceable battery-grade material.
- Lithium iron phosphate chemistry:Electric vehicle manufacturers in China are expanding LFP cathode lines for mass-market models, pulling disproportionate volumes of high-purity lithium carbonate relative to nickel-cobalt-manganese alternatives.
- Jiangsu-Sichuan cluster concentration:Integrated refining-to-cell manufacturing corridors in these provinces are reducing logistics costs and quality variance, accelerating offtake velocity for locally produced battery-grade carbonate.
Market Restraints
- Atacama supply concentration:Brine extraction from this Chilean salt flat supplies a dominant share of global lithium feedstock, creating geographic single-point vulnerability to water access disputes and local permitting delays.
- Spodumene concentrate cost volatility:Hard-rock mining and acid roasting operations in Western Australia face diesel and sulfuric acid price swings that transmit directly into battery-grade carbonate production economics.
- Sodium-ion substitution:CATL and BYD are commercializing sodium-ion cells for stationary storage and entry-level mobility, threatening to displace lithium carbonate demand in price-sensitive application tiers.
Strategic Opportunities
- US Inflation Reduction Act:Critical mineral sourcing requirements for electric vehicle tax credits are creating compliant supply chain premiums for lithium carbonate refined in free-trade-agreement countries.
- Direct recycling streams:Pyrometallurgical and hydrometallurgical recovery of lithium from end-of-life batteries offers an emerging feedstock alternative to virgin brine and spodumene.
- Grid-scale storage deployment:Utility-scale lithium iron phosphate installations in Texas and California are absorbing battery-grade carbonate volumes outside traditional automotive procurement channels.
Industry Challenges
- Qualified chemical engineer scarcity:Solvent extraction and crystallization expertise for battery-grade purification is concentrated among a narrow cohort of specialists with experience in lithium, rare earths, or nuclear materials processing.
- GB/T 26008 certification timelines:China's SAMR enforcement of updated purity standards requires extended analytical validation protocols that delay new refinery ramp-ups by six to twelve months.
- Brine evaporation yield variance:Climate-dependent concentration rates in high-altitude salars create production planning uncertainty that complicates offtake contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Grade Lithium Carbonate Market |
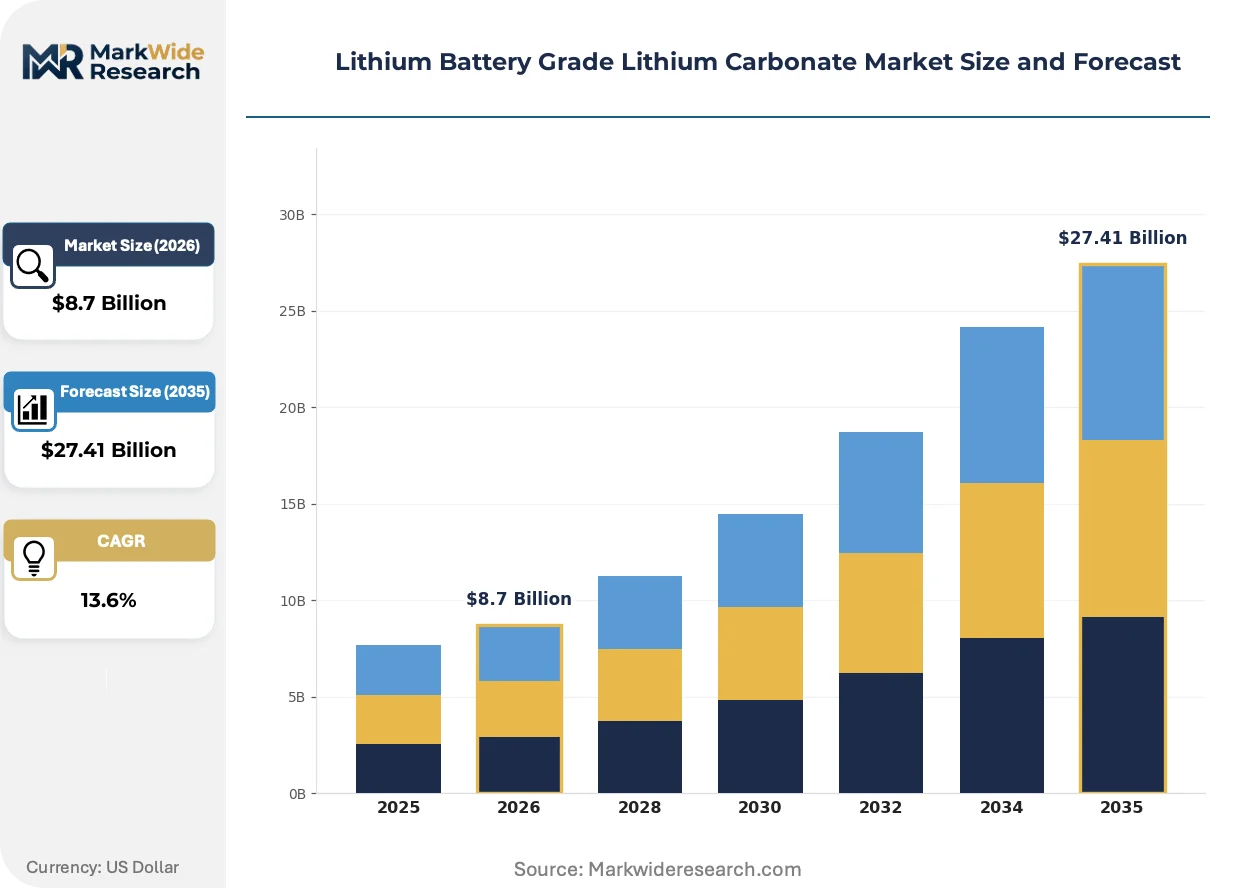
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Technical Grade, Industrial Grade, Pharmaceutical Grade Application: Electric Vehicles, Power Tools, Renewable Energy Storage, Consumer Electronics Distribution Channel: Direct Sales, Online Sales, Distributors, Retail End User: Automotive Manufacturers, Electronics Manufacturers, Energy Providers, Aerospace |
| Companies Covered | Allkem Limited, Livent Corporation, Albemarle Corporation, Shenzhen Chengxin Lithium Group Co., Ltd., Qinghai Salt Lake Industry Co., Ltd., Ganfeng Lithium Co., Ltd., Tianqi Lithium Corporation, Pilbara Minerals Limited, Sociedad Química y Minera de Chile S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Grade Lithium Carbonate Market Emerging Trajectories
Purification technology and procurement architecture are converging to redefine competitive advantage in battery-grade lithium carbonate, with traceability and carbon intensity emerging as distinct value dimensions beyond traditional purity metrics.
Direct solvent extraction (DLE) technology is migrating from pilot demonstrations to commercial deployment at select brine operations. SQM and Albemarle are retrofitting Atacama assets with selective adsorption and membrane systems that bypass traditional eighteen-month solar evaporation cycles. This compression of production timelines is enabling faster response to cathode manufacturer demand signals, though capital intensity remains prohibitive for junior developers.
China's MIIT battery material standards and the EU Battery Regulation are creating divergent compliance architectures that suppliers must navigate simultaneously. The MIIT framework emphasizes domestic traceability and purity thresholds, while Brussels mandates carbon accounting and recycled content verification. Cathode producers serving both markets are dual-certifying supply chains, adding audit costs that favor scaled refiners with dedicated compliance functions.
Long-term offtake contracting is displacing spot market liquidity as the dominant transaction mode. CATL, BYD, and LG Energy Solution are locking in five-to-ten-year supply agreements with fixed-volume, floating-price structures indexed to cathode demand rather than lithium commodity benchmarks. This behavioral shift is visible most acutely in China, where integrated cell-cathode-refiner relationships have nearly eliminated open-market trading for battery-grade material.
Lithium Battery Grade Lithium Carbonate Market Segmentation
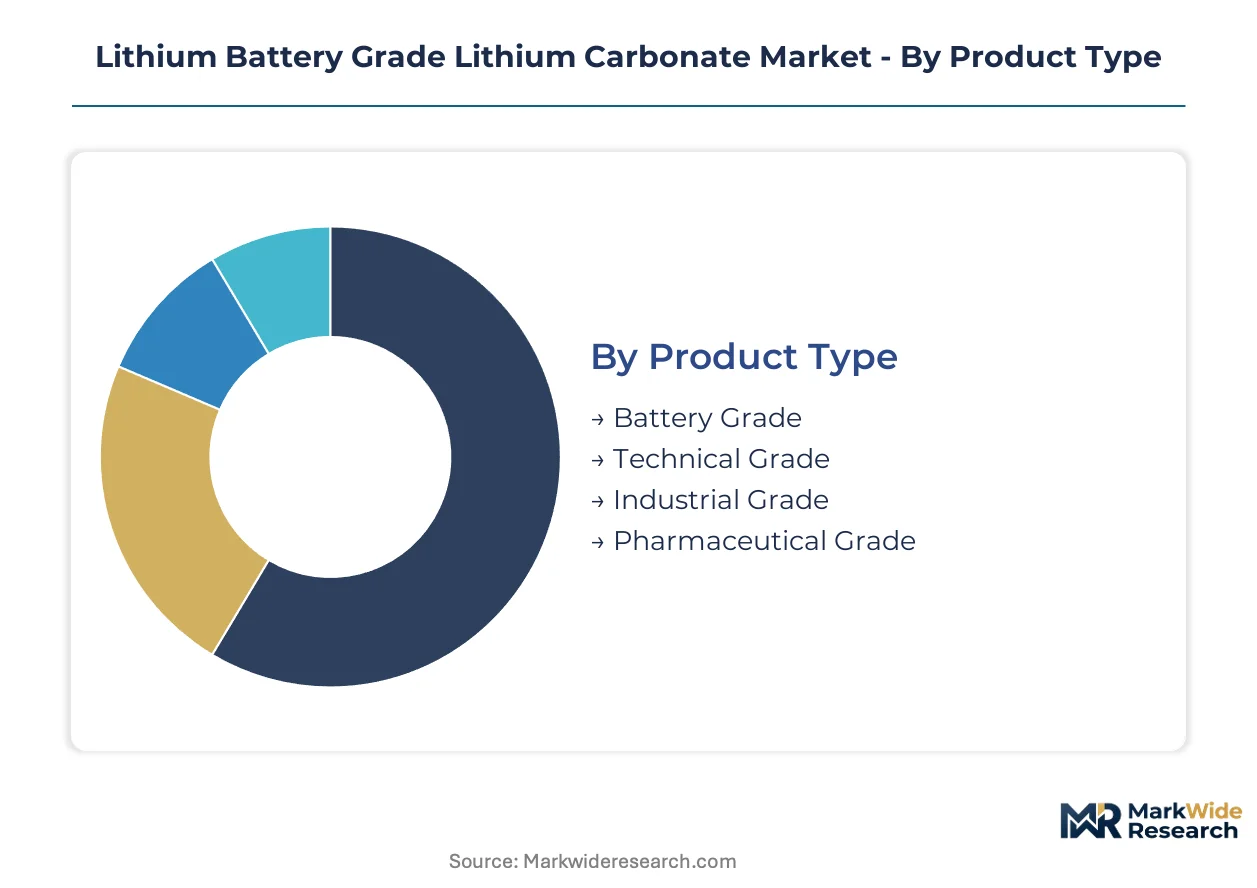
Battery-grade lithium carbonate specifications vary sharply across end-use applications, with cathode chemistry purity thresholds determining procurement premiums. Segmentation reveals how automotive qualification protocols are compressing the addressable supplier base while creating tiered value pools.
Product Type:
Battery grade commands the longest qualification cycles due to cathode manufacturer validation protocols, while technical and industrial grades turn over faster through commodity chemical channels.
- Battery Grade:Exceeds 99.5% Li₂CO₃ with sodium, magnesium, and calcium impurities below 50 ppm. Electric vehicle cathode producers in China's Jiangsu-Sichuan corridor are locking in dedicated refining capacity to secure this specification tier.
- Technical Grade:Purity ranges between 99.0% and 99.5% Li₂CO₃, suitable for glass and ceramics manufacturing. Demand concentrates in specialty ceramics producers serving semiconductor fabrication equipment supply chains.
- Industrial Grade:Lower purity material serves aluminum smelting flux and general chemical applications. Cement and glass manufacturers in India absorb volumes through spot procurement without long-term contracting.
- Pharmaceutical Grade:Ultra-high purity for mood disorder therapeutics and medical device lubricants. FDA and EMA validation requirements extend production timelines beyond standard battery-grade certification.
Battery grade dominates installed base value. Pharmaceutical grade is where expansion concentrates as medical lithium demand climbs the fastest.
Application:
Cost tier differentiation separates mass-market mobility from premium energy storage, with electric vehicles absorbing the highest-purity material at compressed margins.
- Electric Vehicles:Lithium iron phosphate and nickel-cobalt-manganese cathode chemistries consume the dominant volume share. BYD and CATL are expanding dedicated LFP lines for entry-level models, pulling disproportionate carbonate throughput.
- Renewable Energy Storage:Utility-scale lithium iron phosphate installations in Texas and California are absorbing battery-grade volumes outside automotive channels. Grid operators favor this chemistry for cycle stability and capital cost efficiency.
- Power Tools:Cordless equipment manufacturers specify mid-tier purity for nickel-manganese-cobalt cell packs. Milwaukee and DeWalt procurement teams prioritize cell energy density over extreme impurity thresholds.
- Consumer Electronics:Smartphone and laptop battery producers source through established Asian chemical distributors. Samsung SDI and LG Energy Solution lock in annual volumes through framework agreements with Chinese refiners.
Electric vehicles dominate installed base. Renewable energy storage is where expansion concentrates.
Distribution Channel:
Volume concentration favors direct procurement, with spot liquidity thinning as cathode manufacturers integrate backward into captive refining.
- Direct Sales:Long-term offtake agreements between refiners and cathode active material producers capture the largest margin pools. CATL, BYD, and LG Energy Solution have eliminated open-market exposure through five-to-ten-year supply contracts.
- Distributors:Regional chemical traders serve mid-tier battery producers and industrial applications without qualification bandwidth for direct refiner relationships. Indian and Southeast Asian manufacturers rely on Singapore-based distributors for smaller lot sizes.
- Online Sales:Digital platforms facilitate spot transactions for laboratory quantities and pilot-scale cathode development. Research institutions and startup cell developers source gram-to-kilogram lots through Alibaba and specialty chemical marketplaces.
- Retail:Minimal penetration limited to educational and hobbyist battery assembly kits. University engineering programs purchase small quantities through scientific supply retailers.
Direct sales dominates installed base. Distributors is where expansion concentrates as secondary battery markets proliferate.
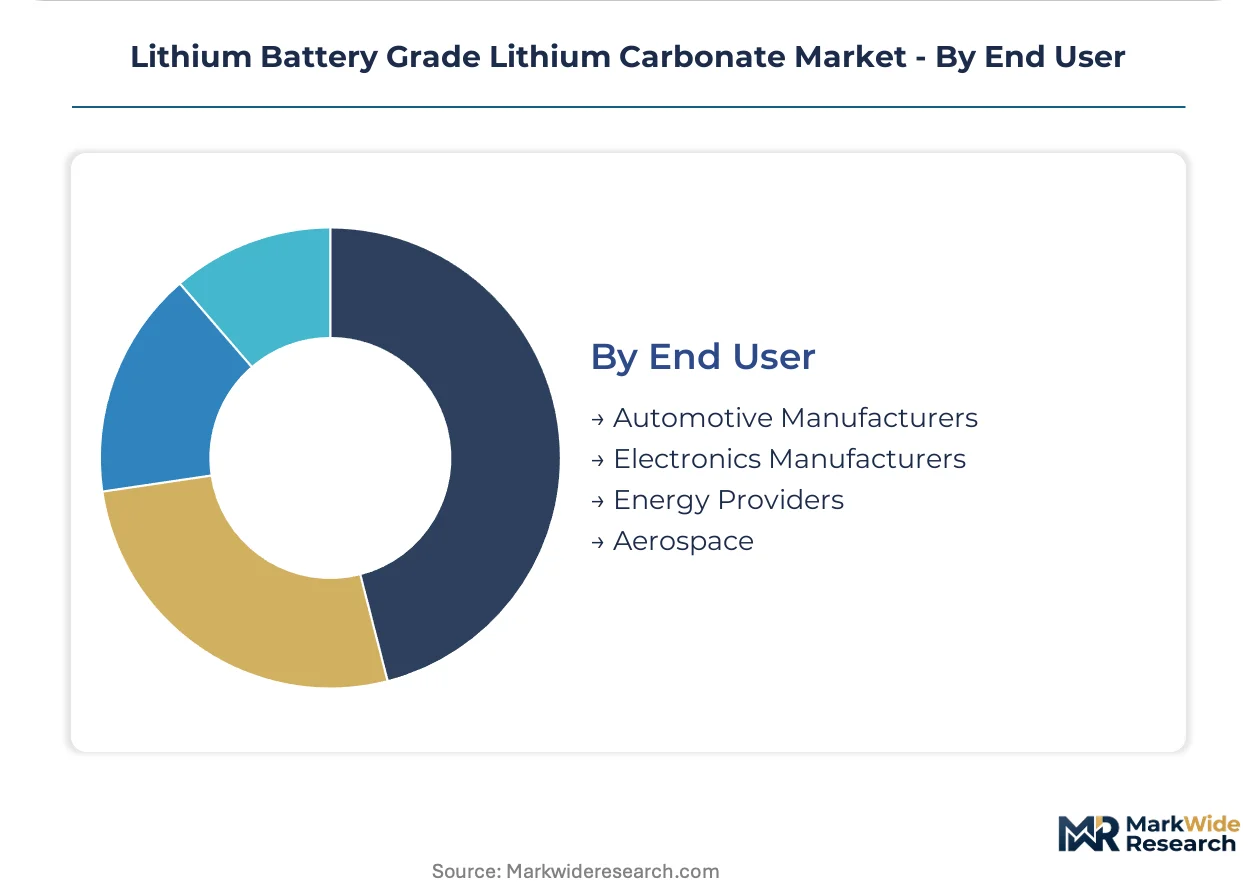
End User:
Customer type determines specification stringency, with automotive manufacturers imposing the most exhaustive traceability and carbon accounting requirements.
- Automotive Manufacturers:Tesla, Volkswagen Group, and Chinese OEMs mandate battery passport traceability and carbon footprint declarations under EU Battery Regulation compliance frameworks. Qualification protocols exclude non-certified refiners from approved supplier lists.
- Energy Providers:Utility-scale storage developers prioritize cost efficiency over extreme purity, accepting slight impurity variance for grid-scale lithium iron phosphate systems. NextEra Energy and Fluence source through aggregated procurement consortia.
- Electronics Manufacturers:Consumer device producers balance energy density requirements against supply security, maintaining dual-source strategies across Chinese and Korean chemical suppliers.
- Aerospace:Satellite and defense applications specify ultra-high purity with extensive documentation chains. NASA and ESA procurement specifications exceed standard battery-grade thresholds for mission-critical power systems.
Automotive manufacturers dominate installed base. Energy providers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cathode manufacturers absorb lithium carbonate volumes with minimal price elasticity, while European automotive buyers face steep cost sensitivity under EU Battery Regulation compliance burdens. Australian hard-rock producers operate at mid-tier elasticity, balancing spodumene concentrate volatility against long-term offtake security. Chilean brine extraction maintains the most inelastic supply response due to Atacama water access constraints.
China
Jiangsu and Sichuan provinces host integrated lithium refining corridors feeding CATL and BYD cathode lines. MIIT battery material standards enforce GB/T 26008 purity thresholds that exclude non-compliant refiners from automotive supplier lists. Ganfeng Lithium and Tianqi Lithium anchor production clusters in these provinces, locking in captive spodumene concentrate streams from Western Australia.
Chile
Atacama Desert brine extraction supplies dominant global lithium feedstock under SQM and Albemarle concession holdings. Local water access disputes and indigenous community permitting delays constrain production planning certainty. Antofagasta region refineries export battery-grade carbonate through Chilean port infrastructure to Asian cathode manufacturers.
Australia
Western Australia spodumene concentrate mining feeds Chinese refineries through Pilbara Minerals and Greenbushes operations. Diesel and sulfuric acid cost volatility transmits directly into hard-rock lithium economics, compressing margins during energy price spikes. Perth-based logistics corridors coordinate concentrate shipments to Jiangsu-Sichuan processing clusters.
United States
Nevada and North Carolina hard-rock deposits anchor Albemarle's Silver Peak and Kings Mountain conversion operations. EPA Clean Water Act oversight constrains brine and spodumene project permitting timelines, delaying new refinery ramp-ups. Inflation Reduction Act critical mineral sourcing requirements create compliant supply chain premiums for domestic lithium carbonate.
Germany
European cathode producers qualify low-carbon lithium sources under EU Battery Regulation carbon footprint declaration mandates. BASF and Umicore procurement teams enforce traceability protocols that exclude non-certified refiners from approved supplier lists. Saxony-Anhalt and North Rhine-Westphalia host emerging refining capacity serving Volkswagen Group and BMW cathode demand.
Lithium Battery Grade Lithium Carbonate Market Vendor Landscape
Integrated resource holders and standalone refiners split the market into divergent margin structures. Resource-integrated players capture upstream value through captive brine and spodumene access, while pure-play refiners compete on purification technology and qualification velocity. Three archetypes dominate: Atacama brine operators with solar evaporation assets, Australian hard-rock miners with spodumene concentrate streams, and Chinese integrated refiners with captive cathode customer relationships. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with producers locking in five-to-ten-year supply agreements ahead of rival qualification cycles.
Among Atacama-based operators, Sociedad Química y Minera de Chile S.A. exemplifies the brine-integrated archetype with established solar evaporation infrastructure. Albemarle Corporation occupies a parallel position in North American conversion capacity, anchoring supply security for automotive qualification protocols. Ganfeng Lithium Co., Ltd. represents the Chinese integrated model, combining captive resource positions across Argentina and Australia with domestic refining corridors serving CATL and BYD demand pools.
| Leading Market Players |
|---|
| Allkem Limited |
| Livent Corporation |
| Albemarle Corporation |
| Shenzhen Chengxin Lithium Group Co., Ltd. |
| Qinghai Salt Lake Industry Co., Ltd. |
| Ganfeng Lithium Co., Ltd. |
| Tianqi Lithium Corporation |
| Pilbara Minerals Limited |
| Sociedad Química y Minera de Chile S.A. |
| Others |
Supply Flow & Price Mechanics
Atacama brine concentration in Chile and Sichuan-Jiangsu refining clusters in China lock margin pools at opposite ends of the value chain, with cathode manufacturers capturing downstream premiums through direct offtake structures that bypass traditional commodity traders.
Pricing Analysis
Long-term offtake contracts with floating-price mechanisms indexed to cathode demand rather than spot lithium benchmarks drive lifetime value for integrated refiners. Price differentiation rests on GB/T 26008 certification status and carbon footprint verification under EU Battery Regulation mandates. Cost compression in technical-grade tiers is intensifying because sodium-ion substitution threatens price-sensitive storage applications. Energy providers exhibit highest price sensitivity, while automotive manufacturers accept premium pricing for qualified low-carbon material.
Supply Chain Analysis
Export-control regimes on direct lithium extraction technology limit flow of selective adsorption and membrane systems from US and European equipment suppliers to Chinese developers. Supply concentrates in Chile, Australia, and China, with hard-rock spodumene from Western Australia and Atacama brine feeding Jiangsu-Sichuan processing corridors. Raw material dependencies span diesel fuel for Pilbara mining operations, sulfuric acid for acid roasting, and fresh water for brine evaporation yield management. Single-source vulnerability around Atacama water access permits creates structural risk. Distribution runs through dedicated bulk shipping contracts to cathode active material producers, with spot liquidity nearly eliminated in battery-grade tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cathode manufacturer consolidation through CATL, BYD, and LG Energy Solution procurement centralization has shifted buyer power upstream, compressing standalone refiner margins while rewarding integrated resource-to-cathode supply chains.
For Market Incumbents: Pre-empt sodium-ion displacement by locking in automotive qualification cycles ahead of CATL and BYD commercialization timelines. Secure captive spodumene concentrate streams through equity positions in Western Australian hard-rock operations, insulating against diesel and sulfuric acid cost volatility that threatens acid-roasting economics. For New Entrants and Emerging Players: Establish a beachhead in grid-scale lithium iron phosphate storage applications outside automotive qualification bandwidth, where purity thresholds tolerate slight impurity variance. Target Texas and California utility procurement consortia through aggregated supply agreements, leveraging faster certification timelines than passenger vehicle battery passport requirements. For Investors and Strategic Acquirers: Capital is best deployed toward direct lithium extraction technology developers with demonstrated selective adsorption or membrane separation pilots, positioned to compress eighteen-month solar evaporation cycles into weeks. Watch for inflection signals in EPA Clean Water Act permitting velocity for Nevada brine projects, which would unlock compliant supply chain premiums under Inflation Reduction Act critical mineral sourcing rules.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Lithium Extraction Deployment | Selective adsorption retrofit at Atacama assets enables SQM and Albemarle to bypass traditional solar evaporation timelines. |
| Long-term Offtake Contracting | Five-to-ten-year agreements between Ganfeng Lithium and CATL eliminate spot market exposure for battery-grade carbonate volumes. |
| Dual Certification Investment | Simultaneous GB/T 26008 and EU Battery Regulation compliance adds audit costs that favor scaled refiners with dedicated compliance functions. |
| Backward Integration into Spodumene | Tianqi Lithium's Greenbushes equity stake secures captive concentrate feedstock for Sichuan refining corridors. |
| Direct Recycling Stream Development | Pyrometallurgical lithium recovery from end-of-life batteries offers emerging feedstock alternative to virgin brine and hard-rock sources. |
Methodological Framework
A standing panel of cathode active material procurement directors, lithium refinery operations managers, and electric vehicle platform engineers provided ongoing calibration throughout the study. Primary interviews with solvent extraction specialists and crystallization process engineers combined with secondary validation from SEC 10-K filings, customs and trade data, and MIIT battery material standard disclosures. Bottom-up refinery capacity modeling and top-down cathode demand forecasting triangulated volume and value estimates.
Scenario-bracketing around sodium-ion substitution velocity, EPA permitting timeline variance, and EU Battery Regulation carbon threshold stringency bounded the projection horizon. Segmentation dimensions spanned purity grade tier, cathode chemistry type, distribution channel structure, and regional regulatory cluster. CAGRs derived from installed base growth rates and replacement demand cycles across electric vehicle and grid-scale storage applications, with lithium iron phosphate chemistry penetration serving as a key demand elasticity input.
Macroeconomic conditions sit as an overlay; deviation in Chinese electric vehicle subsidy policy, Chilean peso exchange rate volatility, or European natural gas pricing would shift the trajectory. Forecasts reflect documented assumptions on DLE technology commercialization timelines and brine evaporation yield coefficients. Material shifts in Atacama water access permitting or GB/T 26008 certification protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market