
 Asia Pacific Electric Vehicle Battery Materials Market | 2026-2036
Asia Pacific Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Vehicle Battery Materials Market Insights
Skilled electrochemist and battery engineer availability is bifurcating the competitive landscape between firms that can staff pilot lines and those stalled at lab-scale validation. Contemporary Amperex Technology Co Limited leverages its vertical integration into lithium refining and cathode precursor synthesis to lock in raw material security. Sumitomo Chemical Co Ltd anchors its position through proprietary high-purity electrolyte formulations that dominate Japanese OEM supply chains. LG Chem competes aggressively on cylindrical cell chemistry roadmaps tied to South Korean automaker platforms.
Asia Pacific electric vehicle battery materials encompass refined inputs and processed intermediates—cathode active materials, anode graphite, electrolyte salts, and separator membranes—engineered to specific purity thresholds, particle size distributions, and electrochemical stability windows that determine cycle life and thermal safety in lithium-ion systems. These materials constitute the functional core of cells that store and release energy through reversible ion intercalation, with cathode chemistry selection directly dictating energy density, cost structure, and safety profile for automotive applications. Lithium-Ion and Nickel-Cobalt Manganese formulations occupy the dominant revenue share as OEMs prioritize range performance, while Lithium Iron Phosphate retains structural importance in commercial vehicle and grid storage segments where cycle longevity outweighs energy density requirements. Solid-State material development represents the fastest-growing R&D allocation, though manufacturing scalability constraints defer commercial volume into the latter half of the forecast window.
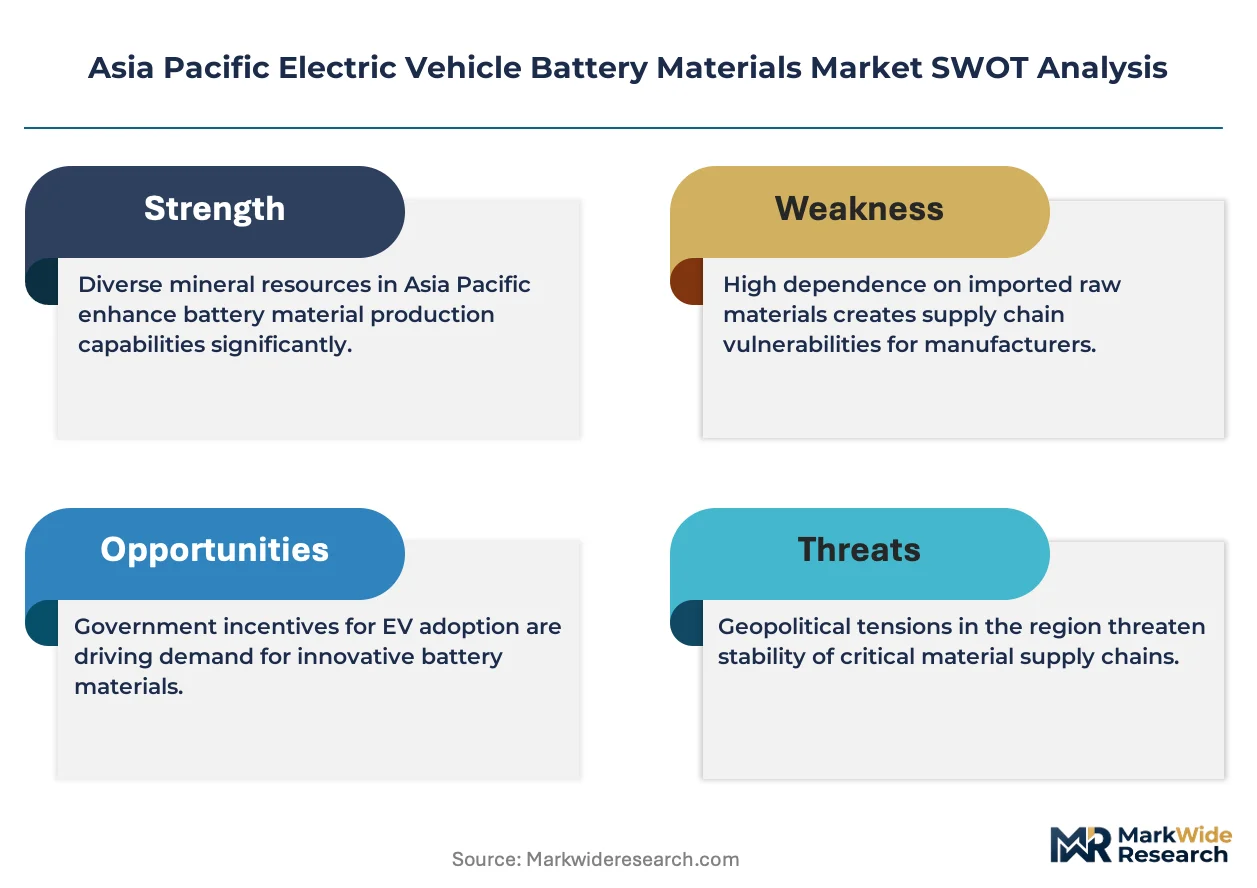
China's MIIT enforces GB standards on cell energy density and thermal runaway propagation, compelling material suppliers to reformulate cathode architectures and electrolyte additives. South Korea's MFDS and Japan's METI coordinate with industry on solid-state electrolyte safety protocols, creating regulatory convergence that shapes cross-border supply qualification timelines. REACH-aligned substance restrictions from European export markets increasingly filter into Asian supplier compliance frameworks, raising barriers for uncertified material entrants. Stakeholders must monitor how China's dual carbon goals and South Korea's battery passport requirements reshape upstream material provenance rules before committing to long-term offtake agreements.
Market Dynamics
China's MIIT energy density mandates under GB standards are forcing cathode architecture reformulation across the Asia Pacific supply base, compressing qualification timelines and concentrating procurement among vertically integrated suppliers with in-house precursor synthesis.
Growth Catalysts
- High-nickel NCM cathode chemistry:South Korean automaker platforms are accelerating adoption of nickel-rich formulations to meet range benchmarks, pulling demand toward POSCO and LG Chem supplier clusters in Gyeonggi-do.
- Japan's METI solid-state electrolyte protocols:Safety standard harmonization with South Korea's MFDS is reducing cross-border qualification friction, enabling faster pilot-to-volume transitions for sulfide-based electrolyte developers.
- Commercial vehicle electrification:Lithium Iron Phosphate retains structural importance in bus and truck segments across China and India where cycle longevity requirements outweigh energy density priorities.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings from Australian spodumene concentrate and South American brine concentrate are compressing cathode precursor margins and destabilizing long-term offtake contract structures.
- Supply concentration in China's Ningxia and Qinghai:Over-reliance on domestic graphite anode processing creates geographic vulnerability to the country's dual carbon enforcement and provincial energy rationing.
- Technical limitation in solid-state interface stability:Ceramic electrolyte-to-electrode contact resistance remains unresolved at pilot scale, deferring commercial volume targets beyond the mid-forecast window.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Subsidy thresholds for gigafactory establishment are attracting cathode active material joint ventures targeting domestic two-wheeler and three-wheeler electrification.
- Battery passport requirements in South Korea:Upstream material provenance rules are creating first-mover advantage for suppliers with blockchain-traceable lithium and cobalt supply chains.
- Silicon-anode and solid-state convergence:Pre-lithiation techniques paired with sulfide electrolytes offer pathways to 400 Wh/kg cell architectures for premium passenger EV segments.
Industry Challenges
- Skilled electrochemist scarcity:Pilot line staffing gaps between lab-scale validation and volume manufacturing are stalling technology transfer at mid-tier material suppliers in China and South Korea.
- GB standard certification timelines:China's MIIT thermal runaway propagation testing protocols are extending cell qualification cycles by 8-12 months, freezing procurement decisions.
- IP fragmentation across electrolyte additive patents:Licensing complexity between Japanese fluorinated solvent holdings and Chinese lithium salt process patents is inflating royalty stacks for electrolyte formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Vehicle Battery Materials Market |
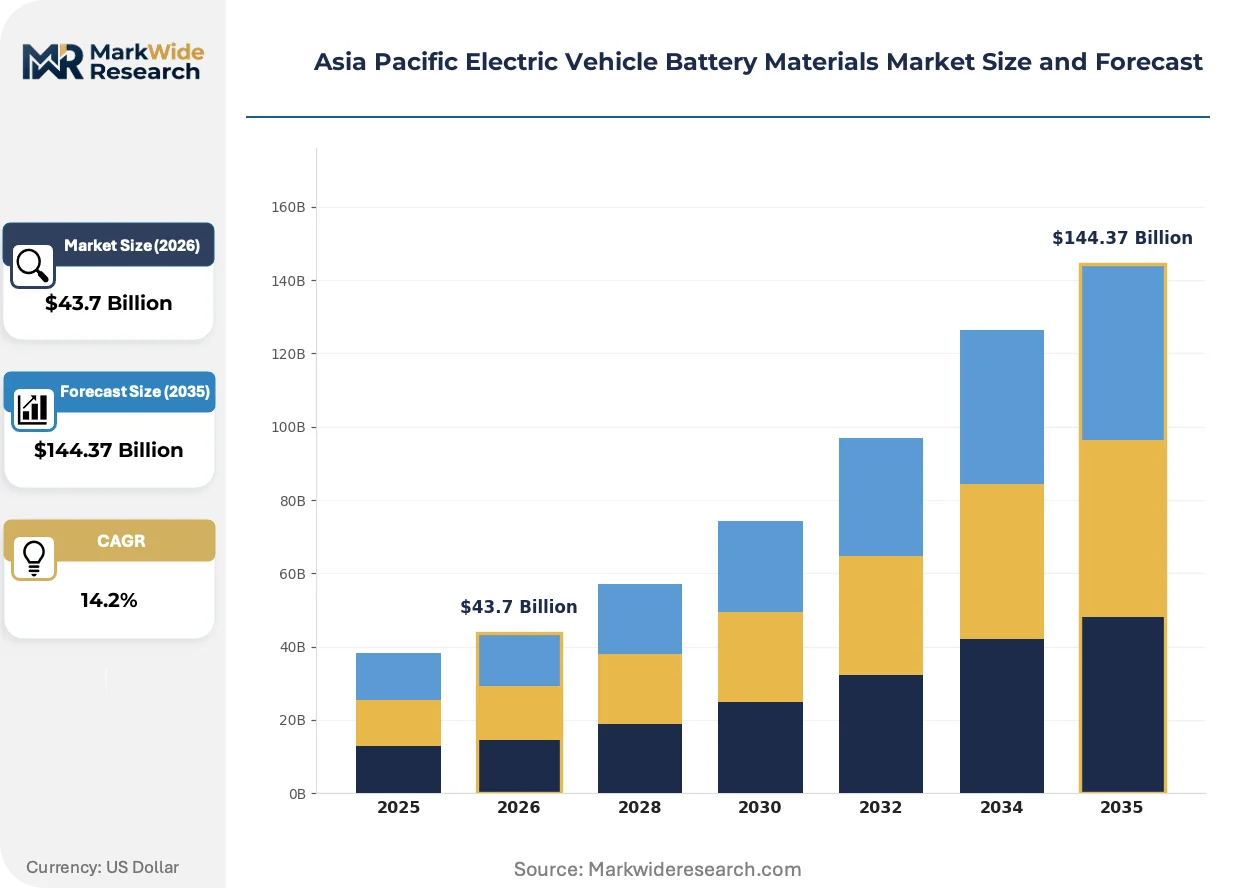
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $144.37 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium-Ion, Nickel-Cobalt Manganese, Lithium Iron Phosphate, Solid-State End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Fleet Operators Application: Consumer Electronics, Automotive, Grid Storage, Industrial Equipment Form Factor: Cylindrical, Prismatic, Pouch, Custom Shape |
| Companies Covered | UBE Corporation, Contemporary Amperex Technology Co Limited, Sumitomo Chemical Co Ltd, Nichia Corporation, LG Chem, BASF SE, Umicore SA, Kureha Corporation, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Vehicle Battery Materials Market Trends and Innovations
Materials engineering roadmaps across Asia Pacific are converging on energy density maximization and thermal stability, with cathode chemistry selection and electrolyte additive packages becoming the primary competitive differentiation vectors.
High-nickel NCM 9-series cathode materials are displacing mid-nickel 6-series formulations in premium passenger EV platforms. South Korean OEMs are specifying these chemistries for 2026-2028 model year vehicles, compressing cost-per-kilowatt-hour trajectories while demanding enhanced dry-room processing capabilities from material suppliers.
REACH-aligned substance restrictions from European export markets are filtering into Asian supplier compliance frameworks. ECHA candidate list screenings for nickel and cobalt compounds are forcing reformulation of cathode precursor waste streams, with Chinese exporters absorbing the highest certification burden to maintain EU market access.
Buyer concentration among tier-one cell manufacturers is consolidating procurement leverage. CATL and BYD are unbundling material specifications into performance-tier contracts, with cathode active material suppliers in Fujian and Hunan responding by segmenting output across premium certified, standard industrial, and economy-grade purity tiers.
Asia Pacific Electric Vehicle Battery Materials Market Segmentation
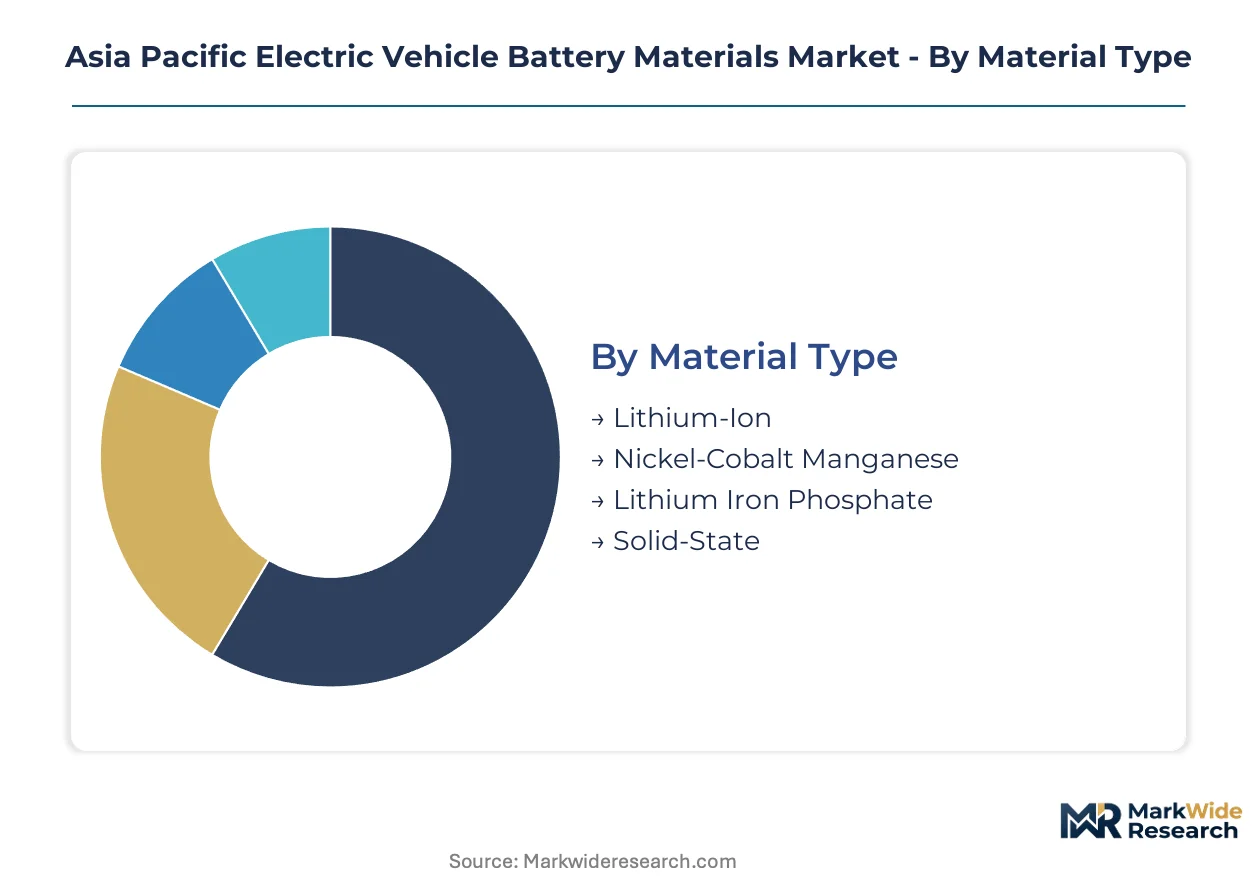
Segmentation in Asia Pacific electric vehicle battery materials reveals how procurement channels, technical specifications, and end-use requirements fragment demand across distinct supply routes. Channel configuration varies sharply by segment—automotive OEMs negotiate direct cathode active material contracts while aftermarket providers source through distributor networks with shorter lead times.
Material Type:
Channel distribution for material types splits between direct mill-to-cell-plant supply for high-volume cathode powders and specialty chemical distributor networks for electrolyte salts and separator coatings.
- Lithium-Ion:Graphite anode and lithium hexafluorophosphate electrolyte formulations constitute the foundational chemistry for cylindrical and prismatic cells. Procurement concentrates through South Korean cell manufacturers in Gyeonggi-do and Chinese gigafactories in Fujian, driven by GB standard energy density mandates from China's MIIT.
- Nickel-Cobalt Manganese:High-nickel NCM 811 and 9-series cathode precursors deliver premium energy density for passenger EV range benchmarks. Demand clusters around POSCO and LG Chem supplier networks serving Hyundai-Kia and Samsung SDI cell lines, pulled by South Korean automaker platform requirements.
- Lithium Iron Phosphate:Olivine-structured cathode materials prioritize cycle stability over energy density in commercial vehicle applications.
- Solid-State:Sulfide and oxide electrolyte materials remain pilot-scale with manufacturing scalability constraints deferring commercial volume.
Lithium-Ion dominates installed base. Nickel-Cobalt Manganese is where expansion concentrates.
End User:
Customer-type segmentation determines contract structure complexity, with direct OEM procurement requiring multi-year qualification cycles and aftermarket channels operating on spot-market flexibility.
- OEMs:Passenger and commercial vehicle manufacturers negotiate cathode active material offtake agreements spanning 5-7 years with embedded price volatility clauses. China's BYD and CATL lock in precursor supply through backward integration into lithium refining, while Japanese OEMs rely on Sumitomo Chemical electrolyte formulations under exclusive supply terms.
- Tier-1 Suppliers:Cell manufacturers like Samsung SDI and SK On procure separated materials for in-house electrode coating and cell assembly operations. These suppliers aggregate demand across multiple OEM platforms, creating volume leverage in cathode powder negotiations with POSCO and Huayou Cobalt.
- Aftermarket Providers:Battery replacement and refurbishment specialists source module-level materials through regional distributor networks.
- Fleet Operators:Bus and logistics vehicle fleet managers procure LFP-based battery systems with service-inclusive contracts.
OEMs dominate installed base. Tier-1 Suppliers is where expansion concentrates.
Application:
Application-driven demand splits between automotive-grade materials requiring full GB standard certification and industrial segments tolerating wider performance tolerances.
- Automotive:Passenger EV platforms specify high-nickel cathode materials and thin-film ceramic-coated separators to meet range and thermal safety requirements. China's MIIT enforces cell-level energy density thresholds that disqualify lower-tier material suppliers from OEM qualification lists.
- Grid Storage:Utility-scale battery installations prioritize LFP chemistry for cycle longevity over 6,000 cycles. Procurement flows through system integrators like Sungrow and BYD Energy Storage, with material specifications emphasizing calendar life and degradation rate guarantees.
- Consumer Electronics:Cylindrical cell materials for power tools and portable devices operate on shorter qualification cycles with lower purity thresholds.
- Industrial Equipment:Forklift and material handling battery systems utilize standardized LFP pouch cells with reduced energy density requirements.
Automotive dominates installed base. Grid Storage is where expansion concentrates.
Form Factor:
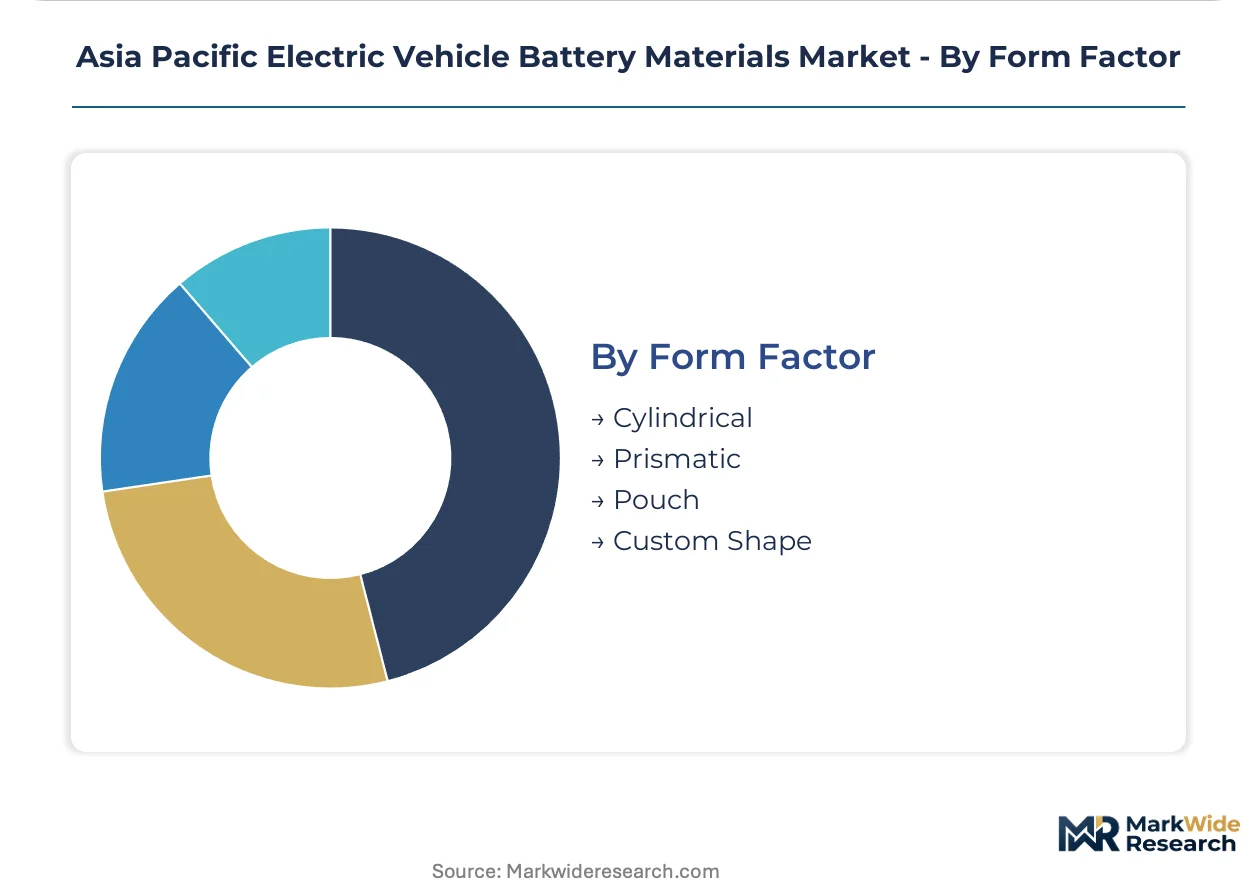
Cell geometry dictates electrode manufacturing equipment compatibility and separator membrane dimensional requirements, creating distinct material supply chains.
- Cylindrical:21700 and 4680 cell formats require precision-wound electrode strips with calibrated thickness tolerances. LG Chem and Samsung SDI cylindrical lines in South Korea specify nickel-rich cathode coatings optimized for high-rate discharge performance in premium passenger EV segments.
- Prismatic:Stacked electrode architectures with aluminum-laminated housings dominate Chinese OEM supply chains. CATL's prismatic cell lines in Ningde source cathode active materials with tailored particle size distributions for automated stacking equipment.
- Pouch:Flexible aluminum-polymer housings accommodate variable cell dimensions for hybrid vehicle applications.
- Custom Shape:Non-standard geometries for aerospace and specialty vehicle integration remain niche with limited material standardization.
Cylindrical dominates installed base. Prismatic is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the Asia Pacific region. China dominates cathode active material demand through passenger EV scale, while South Korea concentrates on high-nickel chemistry exports and Japan advances solid-state electrolyte development for next-generation platforms.
China
Passenger EV production at BYD and CATL gigafactories drives cathode precursor consumption at unmatched volumes. MIIT enforces GB standards on cell energy density and thermal runaway propagation, disqualifying lower-tier material suppliers from OEM qualification lists. Ningde in Fujian Province anchors cathode active material output, where CATL's backward integration into lithium refining secures captive raw material supply.
South Korea
Hyundai-Kia platform requirements pull demand toward nickel-rich NCM 811 and 9-series formulations for 2026-2028 model year vehicles. MFDS coordinates with Japan's METI on solid-state electrolyte safety protocols, reducing cross-border qualification friction for sulfide-based developers. Gyeonggi-do hosts the dominant cathode active material cluster, where POSCO and LG Chem supplier networks scale high-nickel output for Samsung SDI and SK On cell lines.
Japan
Automotive OEMs prioritize solid-state electrolyte development and high-purity electrolyte formulations for premium passenger segments. METI safety standard harmonization with South Korea's MFDS enables faster pilot-to-volume transitions for next-generation cell architectures. Osaka and Nagoya metropolitan areas concentrate materials R&D, where Sumitomo Chemical anchors proprietary electrolyte supply chains for domestic OEM platforms.
India
Two-wheeler and three-wheeler electrification creates emerging demand for LFP-based battery systems with cost-optimized material specifications. PLI scheme subsidy thresholds for advanced chemistry cell manufacturing attract cathode active material joint ventures targeting domestic vehicle electrification. Tamil Nadu and Gujarat states host emerging gigafactory clusters, where Reliance Industries and Ola Electric establish pilot electrode coating operations.
Australia
Spodumene concentrate exports from Western Australian mines supply lithium feedstock for Chinese and South Korean cathode precursor production. The country's national resources regulator enforces environmental compliance on hard-rock lithium extraction, shaping upstream material provenance requirements for battery passport schemes. Pilbara region concentrates hard-rock lithium mining, where Greenbushes and Pilgangoora operations expand concentrate output for Asia Pacific refining capacity.
Asia Pacific Electric Vehicle Battery Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated competitive structure. The upper tier commands cathode precursor synthesis and lithium refining capabilities that compress qualification timelines under MIIT mandates. Three archetypes define positioning: vertically integrated cell manufacturers with captive material production, standalone chemical suppliers with proprietary formulation IP, and mining-to-materials conglomerates controlling upstream concentrate supply. Dominant competitive moves include capacity expansion in high-nickel cathode powder and strategic partnerships locking in lithium offtake from Australian and South American sources.
Within the integrated cell manufacturer tier, Contemporary Amperex Technology Co Limited exemplifies backward integration from lithium refining through cathode precursor synthesis. Among Japan-based chemical specialists, Sumitomo Chemical Co Ltd occupies a position defined by electrolyte formulation expertise. LG Chem represents the diversified chemical conglomerate archetype, spanning cathode active materials through cell manufacturing.
| Leading Market Players |
|---|
| UBE Corporation |
| Contemporary Amperex Technology Co Limited |
| Sumitomo Chemical Co Ltd |
| Nichia Corporation |
| LG Chem |
| BASF SE |
| Umicore SA |
| Kureha Corporation |
| Mitsubishi Chemical Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day cathode precursor inventory buffers at South Korean cell plants concentrate pricing leverage among vertically integrated suppliers with in-house lithium refining, compressing margins for spot-market dependent formulators while amplifying cost pass-through power for backward-integrated producers under MIIT energy density mandates.
Pricing Analysis
Long-term offtake contracts spanning five to seven years dominate cathode active material procurement, with embedded price volatility clauses indexing lithium carbonate to Australian spodumene and South American brine benchmarks. Pricing stratifies across GB-certified premium tiers for OEM direct supply, standard industrial grades for Tier-1 cell manufacturers, and economy purity bands for aftermarket distributors. Cost compression in high-nickel NCM precursor runs through lithium hydroxide premium spreads and nickel sulfate processing fees. Aftermarket providers exhibit highest price sensitivity due to spot-market exposure, while CATL and BYD leverage volume scale to extract fixed-price tranches in backward-integrated supply structures.
Supply Chain Analysis
Strait of Malacca transit lanes carry Australian spodumene concentrate feedstock for Chinese and South Korean cathode precursor production, creating logistical chokepoint exposure for lithium hydroxide and carbonate refiners in Jiangsu and Gyeonggi-do. Upstream supply draws from Western Australian hard-rock mining, Chilean-Argentine brine evaporation, and Indonesian nickel laterite processing. Single-source vulnerability concentrates in China's Ningxia and Qinghai graphite anode processing zones under provincial energy rationing risk. Distribution runs through direct mill-to-cell-plant channels for high-volume cathode powders, with specialty electrolyte salts and separator coatings flowing via regional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte commercialization timelines and sodium-ion chemistry advances threaten incumbent lithium-ion material suppliers, demanding defensive positioning around interface engineering capabilities and precursor synthesis scale.
For Market Incumbents: Compound technical moats in high-nickel cathode architecture and solid-state interface engineering to outpace sodium-ion substitution threats in premium passenger EV segments. Lock in Australian and South American lithium offtake through equity stakes in concentrate operations, securing raw material security against spot-price volatility. Prioritize GB standard pre-certification investments to compress MIIT qualification cycles before 2026 model year procurement windows close. For New Entrants and Emerging Players: Differentiate on blockchain-traceable cobalt and lithium supply chains targeting South Korea's battery passport compliance requirements, where provenance transparency commands procurement preference. Penetrate India's PLI-subsidized gigafactory clusters in Tamil Nadu and Gujarat for LFP cathode joint ventures serving domestic two-wheeler electrification. Pursue toll-manufacturing arrangements with established electrode coating operations to bypass capital-intensive dry-room infrastructure requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded cathode active material assets lacking MIIT certification pathways or solid-state R&D allocation. Frame five-to-ten-year viability around sulfide electrolyte pilot-to-volume transition capability and high-purity lithium hydroxide refining positions. Monitor MFDS-METI safety protocol harmonization progress as inflection signal for cross-border supply qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | CATL's captive supply of battery-grade lithium hydroxide secures precursor cost stability against Australian concentrate volatility. |
| High-Nickel NCM Capacity Expansion | POSCO's Gyeonggi-do cluster scales 9-series cathode output to meet Hyundai-Kia 2026-2028 platform energy density specifications. |
| Solid-State Electrolyte Joint Development | Samsung SDI's sulfide pilot lines leverage MFDS-METI protocol alignment to accelerate Korean-Japanese OEM qualification timelines. |
| Battery Passport Supply Chain Traceability | Blockchain-verified cobalt and lithium chains position suppliers for South Korea's upstream material provenance enforcement. |
| PLI-Aligned Gigafactory Establishment | Reliance Industries' Tamil Nadu electrode coating operations target India's subsidy thresholds for domestic two-wheeler battery demand. |
Research Methodology
A spread of perspectives from cathode plant managers, lithium procurement leads at Tier-1 cell manufacturers, electrolyte R&D directors, and MIIT certification consultants converged on the working assumptions for material demand trajectories. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings from listed chemical suppliers, GB standard certification databases, and IEA electric vehicle deployment tracking. Bottom-up cathode powder volume estimates triangulated against top-down passenger EV production forecasts across the modeling period.
Segmentation dimensions modeled span material type chemistry, end-user procurement channel, application performance requirements, and cell form factor geometry. Value projections incorporated lithium carbonate price band sensitivity, high-nickel precursor premium spreads, and solid-state electrolyte pilot-scale cost trajectories. CAGRs derived from fitted growth curves applied to regional EV adoption rates, OEM platform electrification commitments, and cell energy density roadmaps without year-specific anchor points.
Material uncertainties — lithium price volatility, MIIT thermal runaway protocol revisions, solid-state interface stability breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions on cathode chemistry transition speeds and regulatory qualification timelines that may shift with technological or policy developments. Practitioners should keep alternative scenarios live as sodium-ion commercialization progress and battery passport enforcement stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market