
 Pouch Lithium-Ion Batteries Market | 2026-2036
Pouch Lithium-Ion Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Pouch Lithium-Ion Batteries Market Insights
China's gigafactory expansion is reconfiguring regional supply dynamics for pouch cell formats. CATL leverages its integrated cathode material operations to sustain cost discipline across high-volume contracts. LG Energy Solution anchors premium automotive programs through specialized large-scale pouch production lines. Samsung SDI competes in the European electric vehicle segment with nickel-rich chemistry platforms.
A pouch lithium-ion battery encloses electrode stacks and electrolyte within an aluminum-laminated flexible film rather than a rigid metal can, enabling customizable form factors and higher volumetric energy density exceeding 700 Wh per liter in advanced designs. Consumer electronics applications favor soft pouch formats where lightweight and thin profiles dominate design constraints, while electric vehicles drive structural demand toward large-scale capacity segments where fast-charging features command premium positioning. Energy storage systems represent an emerging margin pool as utilities specify extended cycle life requirements.
China's SAMR enforces GB standards for thermal runaway propagation and recycling traceability, directly shaping cell architecture decisions for domestic and export-bound production. South Korea's METI-aligned K-battery roadmap and the EU's Battery Regulation mandate carbon footprint disclosure and recycled content quotas, tightening market access for non-compliant suppliers. Stakeholders must monitor how regional certification divergence affects platform standardization strategies across multinational automotive programs.
Market Dynamics
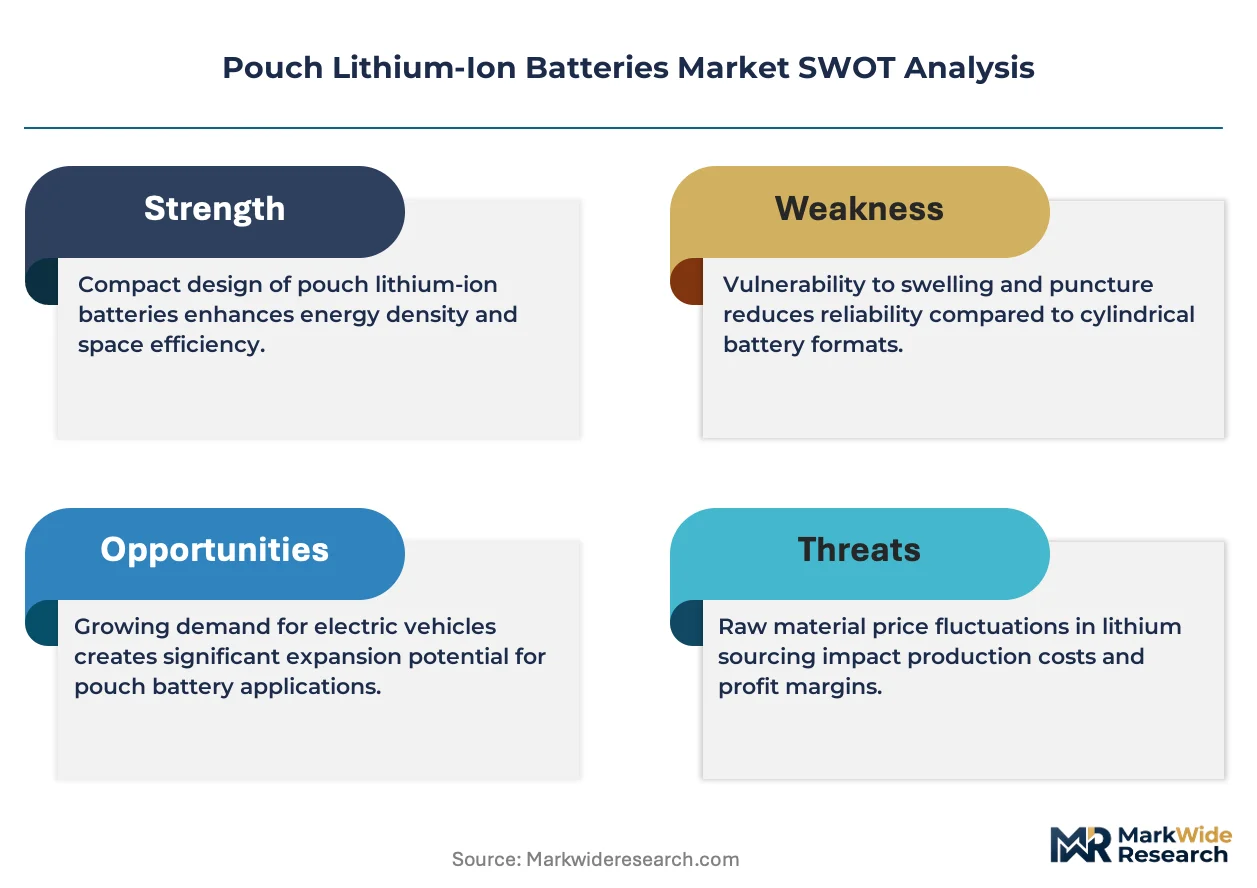
Large-format pouch cell procurement is concentrating among automotive OEMs redesigning platform architectures around modular battery packs, forcing suppliers to retool for standardized cell-to-pack geometries.
Growth Catalysts
- EU Battery Regulation:Mandated carbon footprint disclosure and recycled content quotas are accelerating facility upgrades among export-oriented suppliers.
- Fast-charging chemistry platforms:Silicon-anode integration is enabling 10-80% charge windows under 20 minutes for premium electric vehicle segments.
- South Korea's battery manufacturing corridor:Clustered cathode material and cell production is compressing logistics costs for high-volume contracts.
Market Restraints
- Lithium carbonate volatility:Raw material price swings exceeding 40% annually are compressing margin visibility for long-term supply agreements.
- Aluminum-laminated film supply concentration:Japanese and South Korean substrate suppliers control 80% of qualified automotive-grade supply.
- Thermal runaway propagation limits:Cell-level safety architecture adds 8-12% pack mass overhead versus prismatic alternatives.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Production-linked incentives are attracting cell manufacturing investments for two-wheeler and three-wheeler electrification.
- Grid-scale energy storage:Utility procurement of 4-hour duration systems is opening new margin pools for extended-cycle-life pouch designs.
- Solid-state electrolyte convergence:Hybrid solid-liquid architectures are enabling thinner separators and higher voltage operation in pilot lines.
Industry Challenges
- Cell formation protocol standardization:Divergent OEM specifications for aging and testing cycles are fragmenting equipment investment.
- Dry electrode coating scale-up:Solvent-free manufacturing requires 18-24 month qualification timelines for automotive certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouch Lithium-Ion Batteries Market |
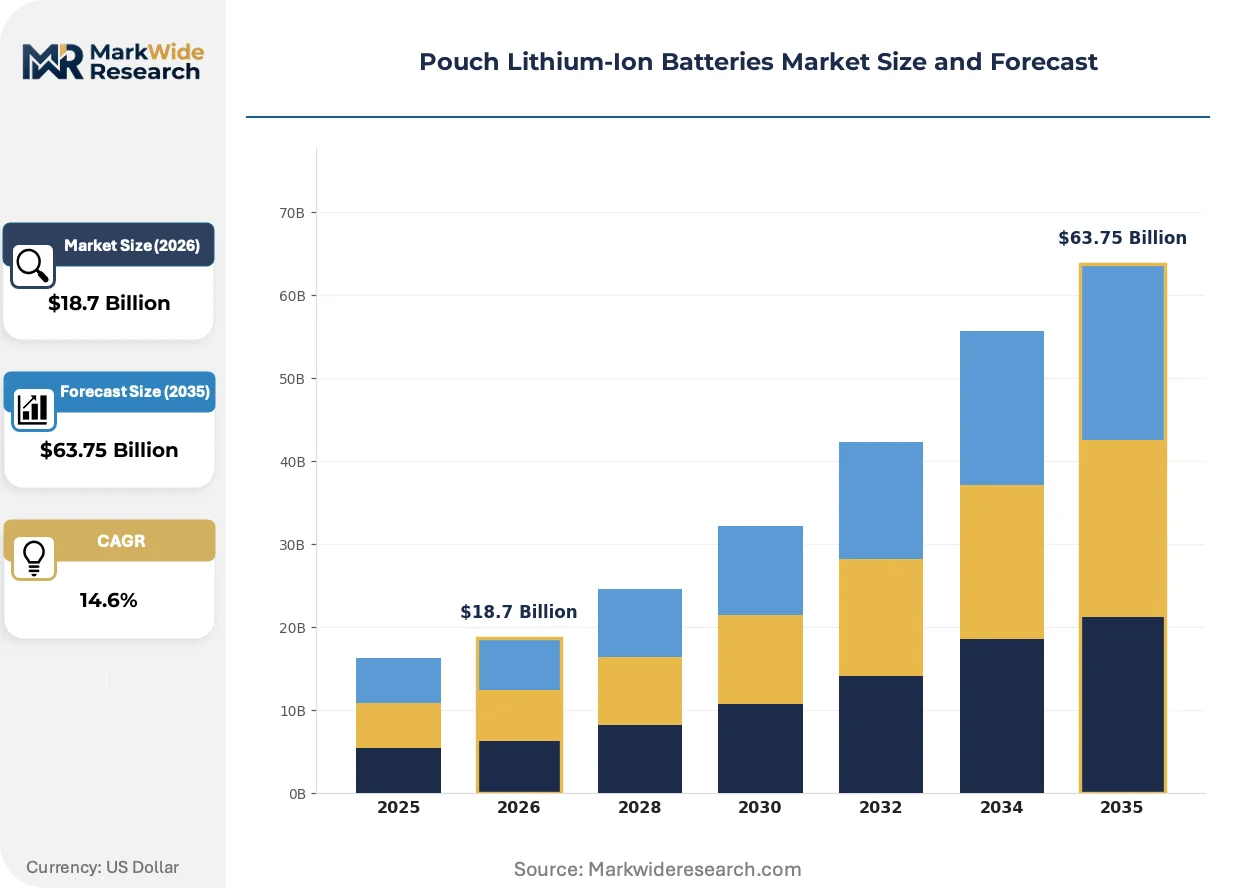
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Pouch, Rigid Pouch, Flexible Pouch, Ultra-Thin Pouch End User: Consumer Electronics, Electric Vehicles, Industrial Applications, Energy Storage Systems Capacity: Small Scale, Medium Scale, Large Scale, Extra Large Scale Feature: High Energy Density, Fast Charging, Lightweight, Flexible Design |
| Companies Covered | LG Energy Solution, Samsung SDI, Panasonic, CATL, BYD, A123 Systems, SK On, Amperex Technology Limited, Farasis Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouch Lithium-Ion Batteries Market Trends and Innovations
Cell architecture is converging around unified module interfaces while materials science pushes energy density boundaries through silicon-anode and high-nickel cathode combinations.
Silicon composite anodes are hybridizing with graphite substrates to mitigate volume expansion during lithiation. Automotive OEMs in Germany and South Korea are qualifying these chemistries for 2026 platform launches. The technology is hybridizing cost structures by reducing cobalt dependency while maintaining premium energy density positioning.
China's SAMR enforcement of GB 38031 thermal runaway standards is mandating 5-minute warning intervals before cell venting. Domestic suppliers are redesigning venting paths and adding ceramic-coated separators to achieve compliance. Export-bound production from CATL and BYD is now certified to both GB and UN 38.3 standards.
Fleet operators are consolidating procurement through battery-as-a-service contracts that unbundle cell ownership from vehicle financing. Commercial vehicle segments in California and the Netherlands are adopting this model to transfer residual value risk. The shift is compressing supplier sales cycles toward 10-year service agreements with performance guarantees.
Pouch Lithium-Ion Batteries Market Segmentation
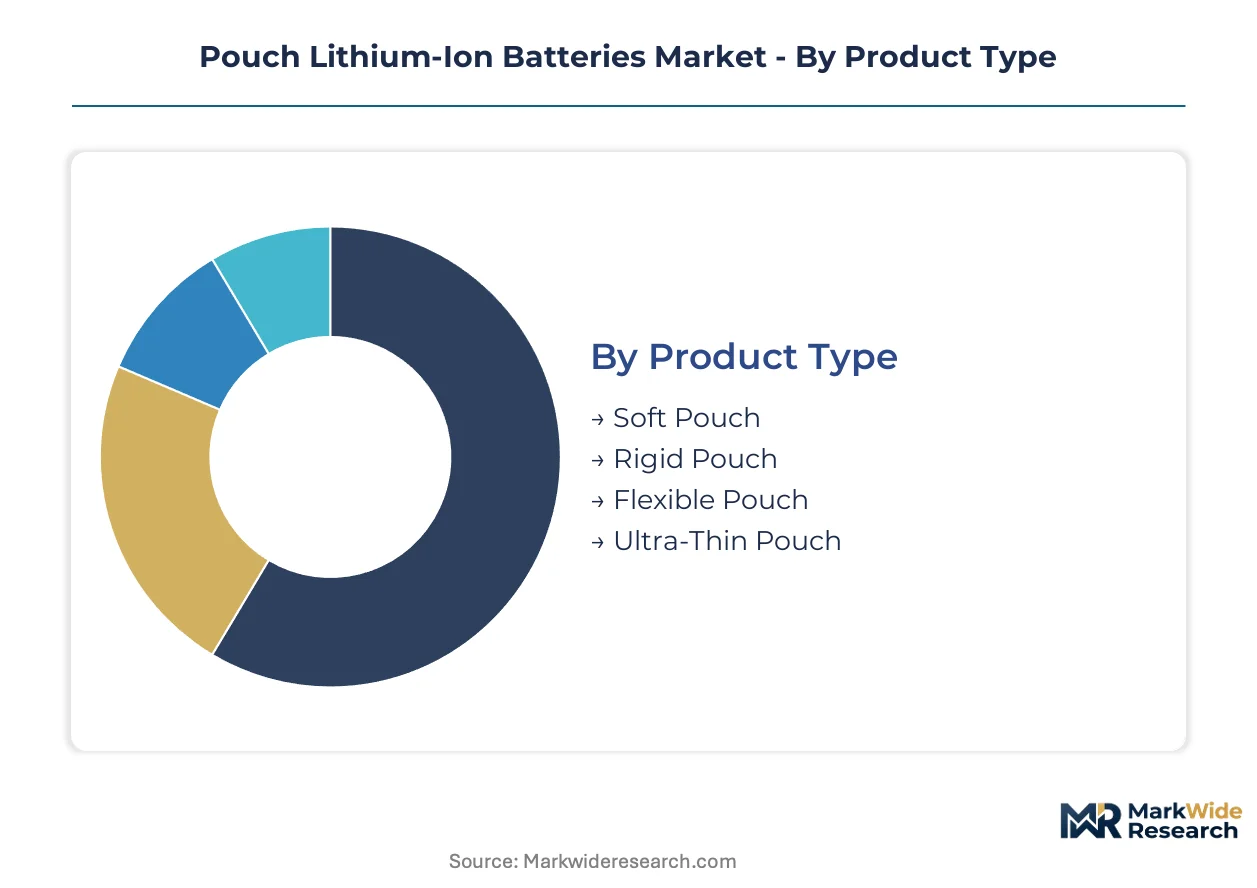
Pouch cell architectures diverge sharply across application requirements, with consumer electronics demanding rapid format iteration while automotive programs lock specifications for platform lifecycles. Segmentation reveals where margin pools concentrate versus where volume commoditization pressures dominate supplier economics.
Product Type:
Cycle times vary from six months for ultra-thin consumer formats to eight-year automotive qualification windows for rigid structural pouches.
- Soft Pouch:Aluminum-laminated polymer enclosures enable thickness profiles below 3mm for smartphones and wearables. CATL and ATL dominate procurement contracts for flagship device launches where annual model refreshes drive cell redesign cycles.
- Rigid Pouch:Reinforced aluminum-composite housings maintain dimensional stability under module compression loads. LG Energy Solution and SK On anchor European and South Korean automotive programs requiring cell-to-pack structural integration with decade-long service life guarantees.
- Flexible Pouch:Bending radii below 10mm accommodate foldable display devices and curved automotive interior surfaces. Samsung SDI and BYD supply experimental programs for next-generation form factors.
- Ultra-Thin Pouch:Sub-2mm profiles prioritize volumetric efficiency over cycle life in hearables and card-type devices. Chinese specialists serve high-volume, low-margin contracts with compressed development timelines.
Soft pouch dominates installed base. Rigid pouch is where expansion concentrates.
End User:
Margin structures stratify across customer procurement sophistication, from spot-market electronics purchasing to decade-spanning automotive service agreements.
- Consumer Electronics:Annual device refresh cycles compress supplier qualification periods. Apple and Samsung procurement teams negotiate multi-year volume commitments with price-down schedules tied to manufacturing scale milestones.
- Electric Vehicles:OEM platform architectures standardize around modular pack designs requiring 10-15 year cell performance warranties. Volkswagen, Hyundai, and Chinese EV specialists specify formation protocols and thermal management integration.
- Industrial Applications:Forklift, robotics, and medical equipment segments demand 3,000+ cycle life with minimal capacity fade. Regional integrators specify pouch formats for equipment retrofit programs.
- Energy Storage Systems:Utility procurement of 4-hour duration systems opens new demand for extended-cycle-life pouch designs. California and Australian grid operators specify degradation curves and warranty terms.
Consumer electronics commands volume leadership. Energy storage systems is climbing the fastest.
Capacity:
Production equipment and facility investments diverge across scale tiers, with gigafactory-scale lines requiring distinct tooling from pilot-scale specialty operations.
- Small Scale:Sub-10Ah cells serve hearables, medical sensors, and industrial IoT endpoints. Japanese and South Korean specialists maintain captive production for premium device integrators.
- Medium Scale:10-50Ah formats power power tools, two-wheelers, and residential storage systems. Chinese suppliers compete on throughput and material cost discipline.
- Large Scale:50-100Ah cells anchor passenger EV modules with fast-charging capability. LG Energy Solution and SK On operate dedicated lines for European and North American automotive programs.
- Extra Large Scale:Above-100Ah formats target commercial vehicle and stationary storage applications requiring minimized cell count for pack assembly efficiency. CATL and BYD pilot production for electric bus and grid-scale contracts.
Large scale dominates current manufacturing footprint. Extra large scale is gaining share fastest.
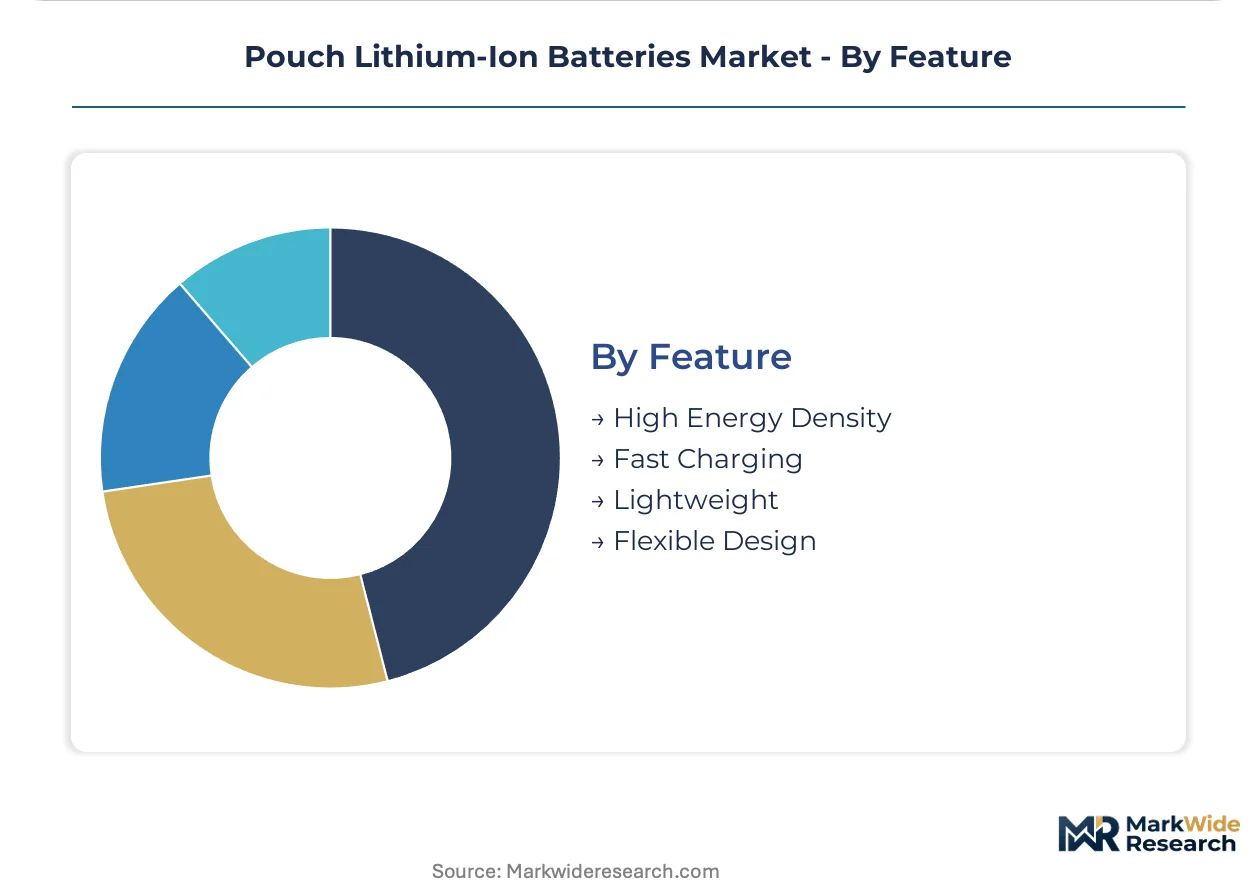
Feature:
Performance premiums attach unevenly across technical attributes, with fast-charging commanding automotive price premiums while lightweight positioning saturates consumer segments.
- High Energy Density:Silicon-anode and high-nickel cathode chemistries exceed 700 Wh per liter in advanced designs. Automotive OEMs in Germany and South Korea qualify these for premium platform launches.
- Fast Charging:Silicon-anode integration enables 10-80% charge windows under 20 minutes. Porsche, Hyundai, and Chinese EV brands specify these cells for 800V electrical architectures.
- Lightweight:Gram-level weight reduction drives material selection for drones, wearables, and aerospace applications. Specialists optimize aluminum-laminate thickness and electrolyte loading.
- Flexible Design:Mechanical compliance enables conformal integration with curved surfaces and dynamic stress environments. Experimental programs target foldable devices and automotive interior panels.
High energy density dominates premium positioning. Fast charging is where steepest expansion trajectory concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB 38031 thermal runaway standards that are reshaping cell architecture decisions across export-bound production. Regional regulatory divergence between Chinese GB standards, South Korean METI-aligned roadmaps, and EU Battery Regulation carbon mandates is fragmenting certification requirements for multinational automotive programs.
China
CATL and BYD anchor gigafactory expansion in the Yangtze River Delta and Pearl River Delta corridors. SAMR's updated GB standards for recycling traceability and thermal propagation are tightening compliance thresholds for domestic and export-bound cell suppliers. Ningbo and Shenzhen manufacturing clusters are retooling for standardized cell-to-pack geometries under modular platform architectures.
South Korea
LG Energy Solution and SK On drive large-format pouch procurement through the Gyeonggi-Seoul battery manufacturing corridor. METI-aligned K-battery roadmaps mandate carbon footprint disclosure and recycled content quotas for automotive-grade supply. Ulsan and Sejong production hubs are compressing logistics costs through clustered cathode material and cell operations.
Germany
Volkswagen and BMW procurement teams specify silicon-anode fast-charging chemistries for 2026 platform launches. EU Battery Regulation mandates are accelerating facility upgrades among export-oriented suppliers serving European automotive programs. Stuttgart and Munich engineering centers are qualifying formation protocols for 800V electrical architectures.
United States
California fleet operators are consolidating procurement through battery-as-a-service contracts for commercial vehicle electrification. NHTSA and state-level zero-emission mandates are tightening safety architecture requirements for cell-level thermal management. Detroit and Silicon Valley automotive programs are standardizing around modular pack designs with decade-long performance warranties.
Japan
Panasonic anchors premium consumer electronics and automotive supply through Kansai-region production. METI industrial policy supports solid-state electrolyte pilot lines enabling thinner separators and higher voltage operation. Osaka and Kyoto R&D clusters are hybridizing solid-liquid architectures for next-generation cell designs.
Pouch Lithium-Ion Batteries Market Competitive Landscape
Capability concentration sits with integrated material suppliers; scale advantage sits with high-volume cell fabricators. The market structures around three tiers: cathode-integrated conglomerates commanding cost discipline, specialized large-format producers anchoring automotive programs, and regional specialists serving consumer electronics refresh cycles. Dominant competitive moves include backward integration into cathode material operations and strategic partnerships for aluminum-laminated film supply security.
Among East Asian battery conglomerates, LG Energy Solution, Samsung SDI, and CATL occupy positions across distinct competitive vectors. LG Energy Solution exemplifies the large-format automotive specialist archetype through dedicated pouch production lines. Samsung SDI represents premium-tier positioning in European electric vehicle segments. CATL anchors the vertically integrated cost-leadership tier through captive cathode material operations.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| Panasonic |
| CATL |
| BYD |
| A123 Systems |
| SK On |
| Amperex Technology Limited |
| Farasis Energy |
| Others |
Pricing and Supply Chain Analysis
Aluminum-laminated film supply concentration determines both pricing tier spreads and supply chain shape, with Japanese and South Korean substrate suppliers commanding premium positioning for automotive-grade qualification while Chinese producers compete on cost for consumer electronics volumes. This single-source dependency cascades through cell formation costs and module integration pricing, compressing margin visibility for long-term supply agreements.
Pricing Analysis
Chinese suppliers undercut South Korean and Japanese competitors by 15-25% on equivalent capacity cells for consumer electronics contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—UN 38.3 and GB 38031 dual-certified cells command automotive premiums, while single-certified volumes compete on throughput. Cost compression in the economy tier intensifies because of lithium carbonate volatility and spot-market cathode material purchasing. Fleet operators and utility procurement teams exhibit lowest price sensitivity due to decade-long service agreement structures, whereas consumer electronics OEMs negotiate aggressive annual price-down schedules tied to manufacturing scale milestones.
Supply Chain Analysis
Extended payment terms from automotive OEMs are forcing cell manufacturers to deploy supply-chain finance facilities with raw material suppliers, compressing working capital cycles across the value chain. Manufacturing concentrates in China, South Korea, and Japan, with each geography anchoring distinct competitive vectors—China dominates cathode material integration, South Korea leads large-format pouch fabrication, Japan controls aluminum-laminated film substrate supply. The supply chain draws from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks, with pricing volatility in these inputs transmitting directly to cell cost structures. Single-source vulnerability in aluminum-laminated film substrates represents the dominant structural risk, as qualification timelines for alternative suppliers extend 18-24 months. Distribution runs through direct long-term offtake agreements for automotive volumes, with spot-market intermediaries handling consumer electronics and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation around modular platform architectures is shifting procurement leverage toward buyers, with Volkswagen, Hyundai, and Chinese EV specialists standardizing cell-to-pack geometries across supplier bases. This buyer-power concentration fragments incumbent margin structures while creating entry windows for specialists with differentiated formation protocols or fast-charging qualifications.
For Market Incumbents: Insulate automotive pricing power through captive aluminum-laminated film supply arrangements or strategic partnerships with Japanese substrate specialists. Secure GB 38031 and EU Battery Regulation dual-certification ahead of platform qualification windows to defend against emerging Chinese competitors with integrated cathode operations. Capacity addition in South Korea's Gyeonggi-Seoul corridor preserves logistics cost advantages for European and North American automotive programs.
For New Entrants and Emerging Players: Establish a beachhead in India's two-wheeler and three-wheeler electrification segment under the PLI scheme for ACC batteries, where incumbent presence remains thin and qualification timelines compress versus automotive. Target grid-scale energy storage procurement in California and Australia, where utility specifications for 4-hour duration systems favor extended-cycle-life pouch designs over prismatic alternatives. A battery-as-a-service go-to-market angle transfers residual value risk from fleet operators while locking in decade-long revenue visibility.
For Investors and Strategic Acquirers: EU Battery Regulation carbon footprint mandates reshape the acquisition landscape toward suppliers with verified low-carbon production and recycling traceability systems. Long-term viability over the projection horizon favors integrated material-cell operations or specialists with solid-state electrolyte pilot capabilities. Acquisition target archetype: mid-scale pouch fabricators with automotive qualification momentum but constrained working capital for gigafactory scale-up. The signal to watch is OEM platform standardization announcements specifying cell-to-pack geometries, which will determine which supplier qualification investments convert to volume share.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Material Operations | CATL's captive lithium iron phosphate production sustains cost discipline across high-volume automotive contracts. |
| Aluminum-Laminated Film Supply Partnership | LG Energy Solution's substrate sourcing agreements with Japanese suppliers secure automotive-grade qualification continuity. |
| Dual-Certification Investment (GB 38031 + UN 38.3) | BYD's export-bound production lines access both Chinese domestic and international automotive procurement pools. |
| Fast-Charging Chemistry Platform Development | Silicon-anode integration by South Korean specialists enables 10-80% charge windows for 800V electrical architectures. |
| Battery-as-a-Service Contract Structuring | California fleet operators transfer residual value risk through unbundled cell ownership and performance-guaranteed service agreements. |
Research Methodology
A spread of perspectives from cell manufacturing executives, automotive OEM procurement leads, cathode material suppliers, and utility energy storage planners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade data, SAMR GB standard documentation, and EU Battery Regulation implementation guidance. Bottom-up cell production capacity estimates triangulated against top-down electric vehicle production forecasts and energy storage deployment databases.
Demand-supply balance modeling anchored volume projections, with segmentation across product type, end user, capacity tier, and performance feature dimensions. The analytical framework incorporated cell-to-pack adoption curves, fast-charging penetration rates, and regional regulatory compliance timelines across the projection horizon. CAGRs derived from year-over-year growth rate convergence analysis rather than single-point extrapolation. Industry-specific forecast inputs included aluminum-laminated film substrate capacity expansion schedules and silicon-anode qualification milestones from automotive OEM engineering centers.
Sensitivities concentrate around lithium carbonate price volatility, thermal runaway standard enforcement timing, and solid-state electrolyte technology maturation. Forecasts reflect documented assumptions regarding OEM platform standardization adoption and recycling infrastructure buildout. Macroeconomic contraction, regulatory divergence between GB and EU standards, or breakthrough solid-state cell commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market