
 Lithium Iron Phosphate (LiFePO4) Battery Market | 2026-2036
Lithium Iron Phosphate (LiFePO4) Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Iron Phosphate (LiFePO4) Battery Market Analytics
UN 38.3 lithium battery transport certification is collapsing the supplier base for international OEM contracts, favoring manufacturers with in-house testing laboratories. CATL leverages its integrated cathode material production to sustain cost leadership across prismatic cell formats. BYD anchors its competitive position through proprietary blade-cell architecture and captive demand from its automotive division. LG Energy Solution competes in the premium cylindrical segment by navigating European automaker qualification timelines.
Lithium iron phosphate batteries employ an olivine-structured cathode material with nominal voltage of 3.2V and thermal runaway thresholds exceeding 270°C, making them suitable for high-cycle applications where safety margins outweigh energy density priorities. The prismatic product type dominates volume shipments due to pack-level space efficiency in electric vehicle platforms, while cylindrical formats retain margin advantages in power tools and industrial equipment where automated assembly reduces unit costs. Energy storage system applications are absorbing surplus production capacity as grid-scale deployments in deregulated electricity markets require decade-long cycle warranties.
China's MIIT imposes mandatory GB/T battery safety standards that gate domestic EV subsidy eligibility, while the EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for cells sold in member states. The US IRA domestic content bonus credit is redirecting cathode precursor investments toward North American processing facilities. Stakeholders must monitor how regional compliance divergence affects cell qualification costs and factory location decisions.
Market Dynamics
The LiFePO4 battery market is restructuring around cathode precursor supply concentration in China's Jiangsu-Fujian corridor, where integrated gigafactory complexes are capturing margin pools previously distributed across separate mining, refining, and cell assembly stages.
Growth Catalysts
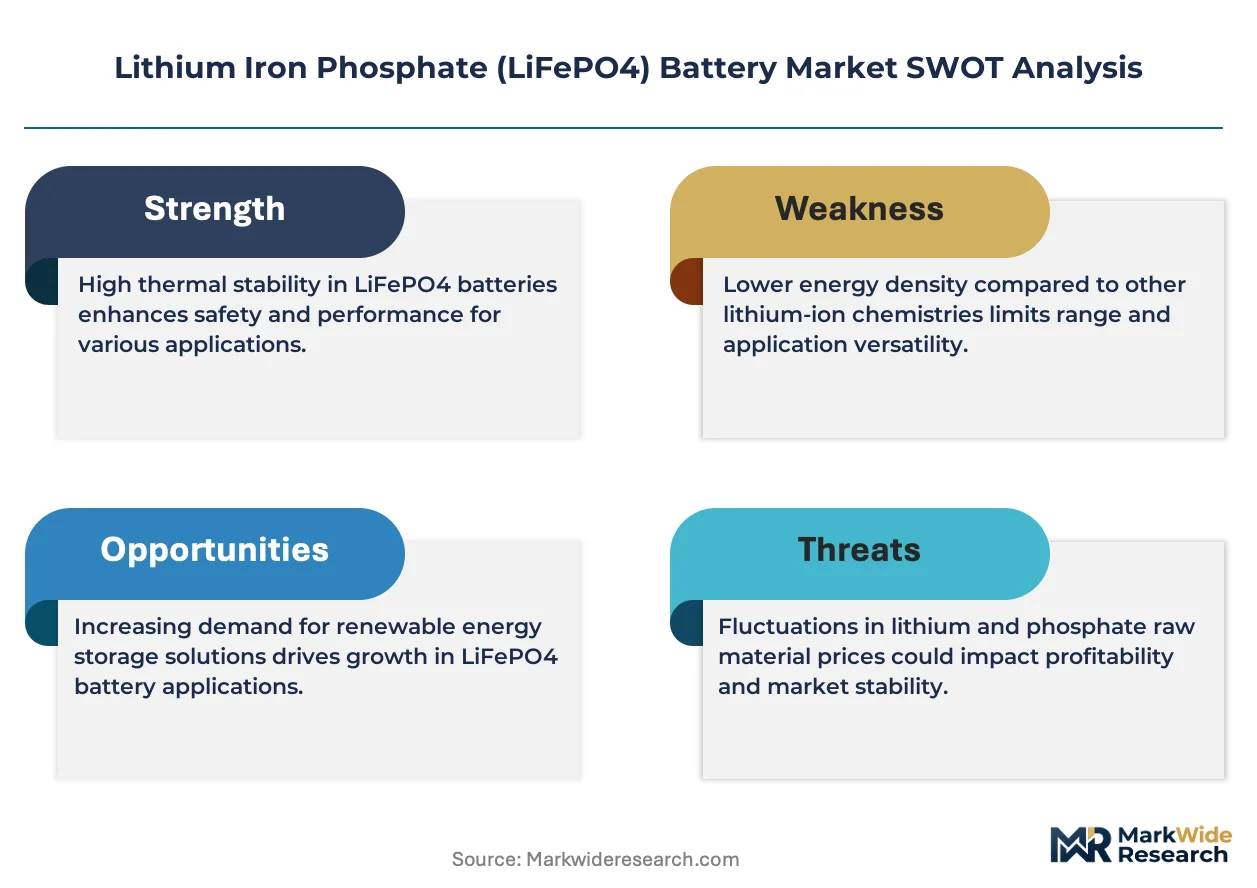
- EU Battery Regulation compliance deadlines:Carbon footprint declarations and recycled content mandates are redirecting European automaker procurement toward iron-phosphate chemistries with established supply chain documentation.
- Grid-scale energy storage absorption:Deregulated electricity markets in Texas, Germany, and Australia are absorbing surplus cell production through decade-long cycle warranty requirements that favor thermal stability over energy density.
- Prismatic cell format standardization:Pack-level space efficiency gains in electric vehicle platforms are consolidating procurement specifications around large-format prismatic designs.
Market Restraints
- Lithium carbonate price volatility:Concentrated spodumene processing in Western Australia and Chilean brine evaporation ponds creates input cost instability that compresses cathode material margins.
- Single-source dependency risk:China's MIIT-controlled GB/T certification gates and domestic subsidy eligibility create geographic concentration vulnerability for international OEM qualification pathways.
- Energy density ceiling:The olivine crystal structure's theoretical specific energy limit of 170 mAh/g constrains pack-level range performance in premium electric vehicle segments.
Strategic Opportunities
- US IRA domestic content bonus:The Inflation Reduction Act's processing and assembly incentives are redirecting cathode precursor investments toward North American facilities to capture tax credit stacking.
- Second-life stationary storage:Retired automotive battery packs are entering grid stabilization contracts through residual capacity arbitrage in California and Germany.
- UN 38.3 transport certification integration:In-house testing laboratory capabilities are collapsing supplier qualification timelines and opening international OEM contract access for mid-scale manufacturers.
Industry Challenges
- Electrolyte formulation talent scarcity:Specialized knowledge in high-voltage additive packages and solid-state interface engineering remains concentrated among Japanese and South Korean research institutes.
- Gigafactory capex intensity:Dry electrode coating equipment and automated formation cycling lines require capital deployment scales that strain non-captive balance sheets.
- Cross-border qualification timeline compression:Simultaneous NMPA, UL, and ECE R100 certification tracks create parallel compliance burdens for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Iron Phosphate (LiFePO4) Battery Market |
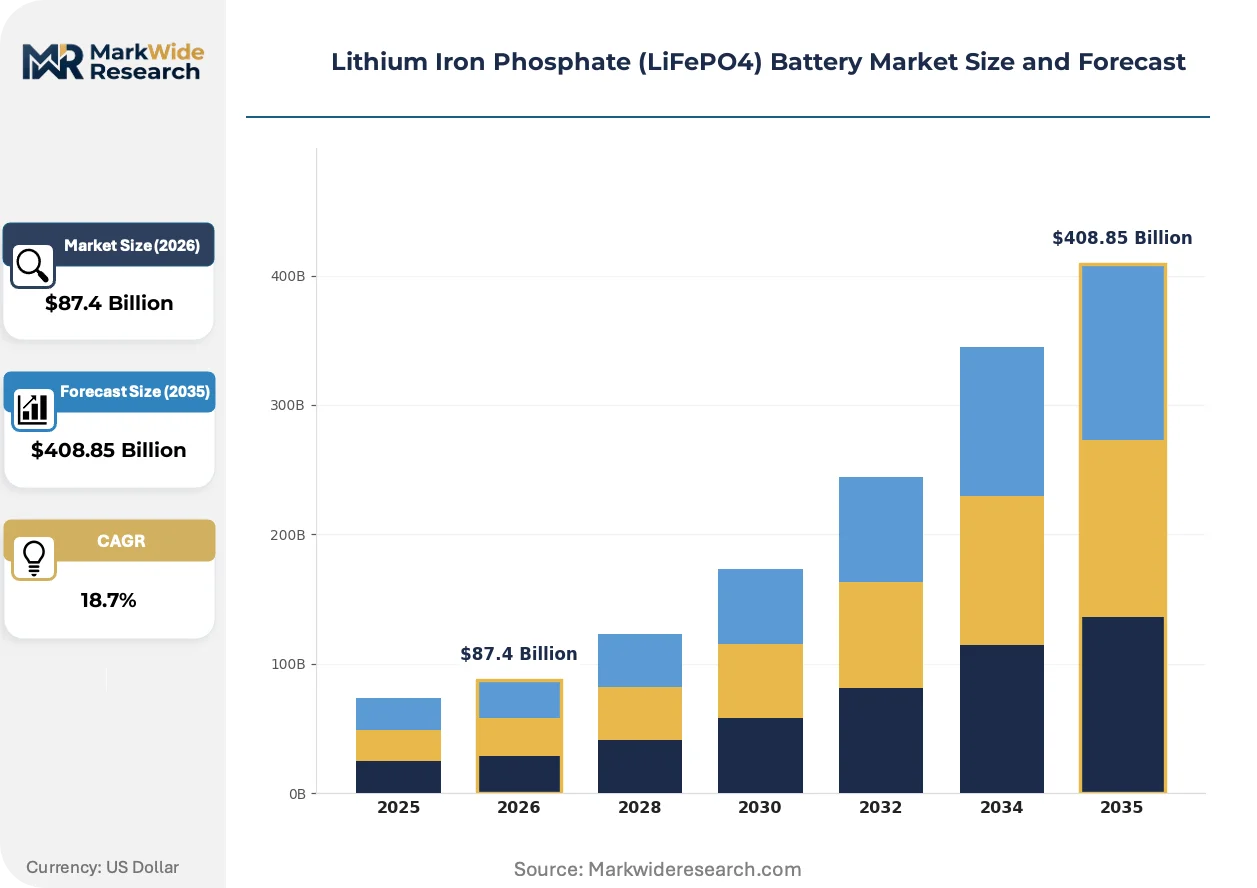
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $408.85 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Custom End User: Electric Vehicles, Solar Energy Storage, Industrial Equipment, UPS Systems Application: Energy Storage Systems, Power Tools, E-Bikes, Electric Boats Installation: On-grid, Off-grid, Mobile, Stationary |
| Companies Covered | A123 Systems Corp, LG Energy Solution, Contemporary Amperex Technology Co., Limited (CATL), EVE Energy, SK On, BYD Company Ltd., CALB (China Aviation Lithium Battery), Sunwoda, Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Iron Phosphate (LiFePO4) Battery Market Evolving Landscape
Cell architecture innovation is compressing the traditional trade-off between thermal safety margins and pack-level energy density, with structural battery designs eliminating module-level components entirely.
Dry electrode coating is supplanting solvent-based slurry processes in high-volume lines. The technology eliminates N-methyl-2-pyrrolidone recovery infrastructure. BYD and CATL are deploying pilot lines at 10 GWh scale. This process compression is enabling single-building integration from cathode powder to finished cell.
REACH substance restrictions and the EU Battery Regulation's carbon border adjustments are forcing supply chain reconfiguration. The industrial consequence is documented mine-to-cell traceability becoming a contract prerequisite. European energy storage integrators are now requiring ISO 14067 product carbon footprint declarations from Asian suppliers.
Automotive OEMs are consolidating cell procurement around long-term offtake agreements with fixed-volume, variable-pricing structures. The traditional spot-market spot-buy model for cylindrical cells is retreating to power tool and industrial equipment channels. This contractual shift is most visible in German automaker negotiations with Korean and Chinese producers.
Lithium Iron Phosphate (LiFePO4) Battery Market Segmentation
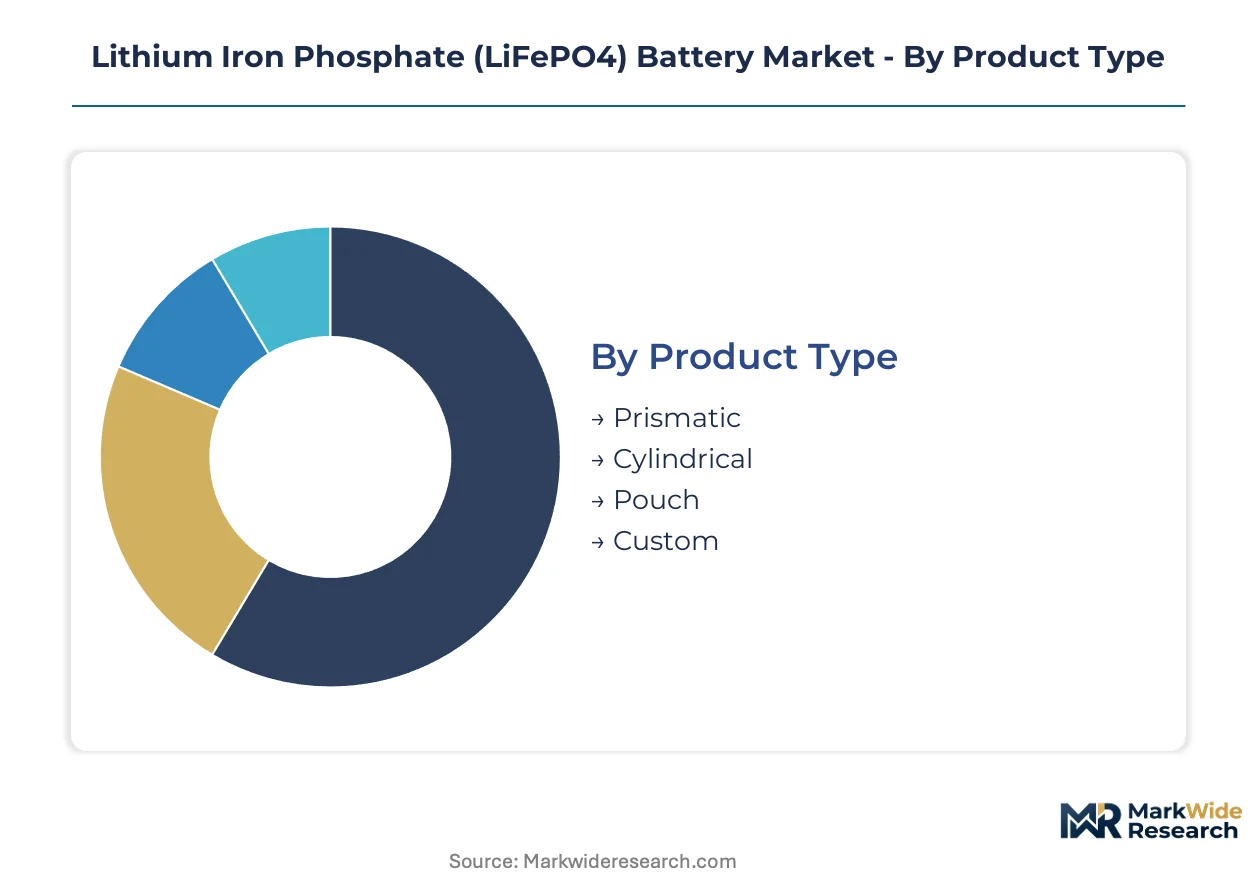
LiFePO4 cell formats and deployment configurations fragment procurement specifications across automotive, grid, and industrial channels. Margin pools concentrate where thermal safety requirements intersect with volume scale, creating divergent competitive dynamics across each category.
Product Type:
Margin pools sit with formats enabling pack-level space efficiency and automated assembly economies.
- Prismatic:Large-format aluminum-cased cells with stacked electrode architecture maximize volumetric efficiency in electric vehicle battery packs. CATL and BYD deploy prismatic designs across Jiangsu and Fujian gigafactories serving domestic EV makers and export markets requiring UN 38.3 transport certification.
- Cylindrical:Rolled jellyroll construction in standardized 18650, 2170, and 4680 formats leverages winding automation to reduce unit labor costs. Power tool and industrial equipment manufacturers in Germany and the United States specify cylindrical cells where high discharge rates and thermal management simplicity outweigh energy density constraints.
- Pouch:Laminated polymer-aluminum flexible housings enable custom aspect ratios for space-constrained applications.
- Custom:Application-specific geometries for marine and aerospace integrations requiring non-standard form factors.
Prismatic holds installed capacity. Cylindrical is rotating up the share rankings.
End User:
Customer type determines warranty duration, cycle life certification, and qualification timeline intensity.
- Electric Vehicles:Automotive OEMs mandate decade-long cycle warranties and cell-level traceability under China's GB/T standards and the EU Battery Regulation's carbon footprint declarations. CATL, BYD, and CALB compete for long-term offtake agreements with fixed-volume, variable-pricing structures displacing spot-market procurement.
- Solar Energy Storage:Grid-scale deployments in Texas, Germany, and Australia absorb surplus production capacity through thermal stability requirements that favor iron-phosphate chemistries over nickel-cobalt alternatives in deregulated electricity markets.
- Industrial Equipment:Forklift and material handling systems require high-cycle durability in warehouse environments.
- UPS Systems:Data center backup power applications prioritize safety margins and minimal maintenance intervals.
Electric Vehicles commands qualification infrastructure. Solar Energy Storage is climbing the fastest.
Application:
Deployment context shapes electrode formulation, electrolyte additive packages, and thermal management system complexity.
- Energy Storage Systems:Containerized grid installations and behind-the-meter commercial deployments in California and Germany utilize retired automotive packs through second-life residual capacity arbitrage, extending asset utility beyond vehicle service life.
- Power Tools:Cordless construction equipment retains cylindrical format dominance where automated assembly reduces unit costs and high discharge rates support intermittent heavy-load operation.
- E-Bikes:Lightweight urban mobility applications in Chinese and European cities favor pouch and cylindrical formats with simplified battery management systems.
- Electric Boats:Marine propulsion systems require saltwater corrosion resistance and thermal runaway containment exceeding 270°C thresholds.
Energy Storage Systems anchors demand volume. E-Bikes is gaining share fastest.
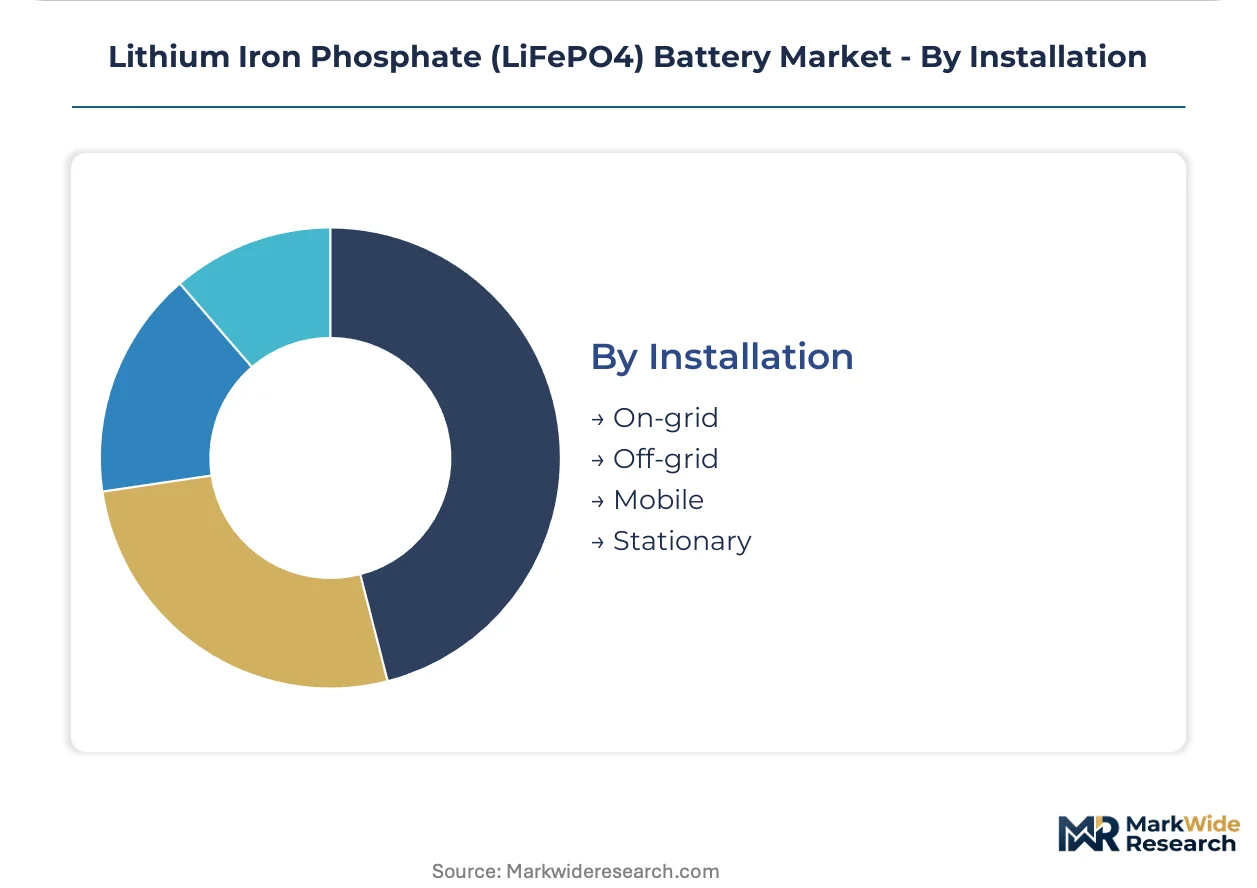
Installation:
Grid connection status and mobility requirements dictate enclosure standards, communication protocols, and service access design.
- On-grid:Utility-interactive systems in Germany and Texas participate in frequency regulation and peak shaving markets through FERC Order 841 compliance and EU electricity market coupling mechanisms.
- Off-grid:Remote industrial sites and rural electrification projects in Australia and the western United States require standalone power systems with solar-charging integration and extended temperature operation.
- Mobile:Vehicle-integrated and portable power systems for construction, recreation, and emergency response.
- Stationary:Fixed commercial and industrial backup installations with utility interconnection capability.
On-grid holds deployment scale. Off-grid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams and grid-scale energy storage developers constitute the primary buyer archetypes, with qualification timelines and certification requirements dictating supplier selection across manufacturing clusters.
China
CATL, BYD, and CALB operate vertically integrated gigafactories across Jiangsu and Fujian provinces, serving domestic EV manufacturers and export markets requiring UN 38.3 transport certification. MIIT-mandated GB/T battery safety standards gate domestic subsidy eligibility and redirect investment toward iron-phosphate chemistries. The Yangtze River Delta and Pearl River Delta corridors concentrate cathode precursor processing capacity with single-building integration from powder to finished cell.
United States
Grid-scale deployments in Texas absorb surplus production through decade-long cycle warranties that favor thermal stability over energy density in deregulated electricity markets. The IRA domestic content bonus credit redirects cathode precursor investments toward North American processing facilities to capture tax credit stacking. The Southwest and Mountain West regions host emerging cell assembly capacity targeting automotive OEM qualification timelines.
Germany
European automakers negotiate long-term offtake agreements with fixed-volume, variable-pricing structures that displace spot-market procurement for cylindrical and prismatic formats. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for cells sold in member states. Bavaria and Baden-Württemberg house automotive engineering centers driving cell qualification requirements for premium EV platforms.
South Korea
LG Energy Solution and SK On compete in premium cylindrical segments by navigating European automaker qualification timelines and electrolyte formulation requirements. MFDS-aligned safety protocols and KBA-type approval processes create parallel certification tracks for export-oriented producers. The Seoul Capital Area and Busan-Ulsan corridor concentrate R&D talent in high-voltage additive packages and solid-state interface engineering.
Australia
Remote industrial sites and rural electrification projects in Western Australia and Queensland require standalone power systems with solar-charging integration and extended temperature operation. Concentrated spodumene processing in Western Australia creates input cost linkages to cathode material margins. The National Electricity Market's frequency regulation services absorb containerized grid installations from second-life automotive pack arbitrage.
Lithium Iron Phosphate (LiFePO4) Battery Market Competitive Landscape
Player mix skews toward vertically integrated Asian conglomerates with captive cathode material production and automotive division demand. Tiered competition separates scale-driven gigafactory operators from mid-cap specialists with in-house UN 38.3 testing laboratories. Three archetypes dominate: integrated conglomerates controlling upstream precursor refining, technology licensors with proprietary cell architectures, and regional specialists serving industrial equipment channels. Competitive moves center on dry electrode coating equipment deployment and long-term offtake agreement negotiation with fixed-volume structures.
Among Chinese integrated producers, Contemporary Amperex Technology Co., Limited exemplifies the scale-driven archetype through its Jiangsu-Fujian corridor positioning, while BYD Company Ltd. occupies a distinctive tier through its blade-cell architecture representation and captive automotive demand. LG Energy Solution anchors the premium cylindrical segment among Korean competitors, navigating European qualification timelines that compress supplier selection windows. These three entities represent divergent strategic positions: upstream control with export certification integration, proprietary format specialization with vertical demand capture, and premium segment focus with multinational OEM relationship depth.
| Leading Market Players |
|---|
| A123 Systems Corp |
| LG Energy Solution |
| Contemporary Amperex Technology Co., Limited (CATL) |
| EVE Energy |
| SK On |
| BYD Company Ltd. |
| CALB (China Aviation Lithium Battery) |
| Sunwoda |
| Gotion High-Tech |
| Others |
Value Network & Pricing Analysis
Lithium carbonate substitution for nickel-cobalt precursors simultaneously redraws procurement geography toward Jiangsu-Fujian processing corridors and compresses cathode material margins through spodumene price indexation. Iron-phosphate chemistry adoption redirects buyer power toward integrated producers with captive precursor refining, collapsing spot-market premia for non-integrated assemblers.
Pricing Analysis
Long-term offtake contracts with quarterly lithium carbonate indexation dominate automotive procurement, displacing spot-market spot-buy models for cylindrical cells. Pricing stratifies across automotive-grade UN 38.3 certified supply, industrial equipment channels, and second-life residual capacity arbitrage. Cost compression in prismatic formats intensifies as dry electrode coating equipment deployment eliminates N-methyl-2-pyrrolidone recovery infrastructure. Grid-scale energy storage developers exhibit highest price sensitivity due to decade-long cycle warranty requirements, while premium cylindrical segments retain margin advantages through electrolyte formulation specialization.
Supply Chain Analysis
China and South Korea anchor cathode precursor processing and cell assembly capacity, with Australia feeding concentrated spodumene concentrate. The supply chain draws from Chilean brine evaporation ponds for lithium hydroxide and Japanese research institutes for high-voltage additive packages. Single-source vulnerability concentrates in China's MIIT-controlled GB/T certification gates, creating geographic concentration risk for international OEM qualification pathways. Distribution runs through vertically integrated gigafactory complexes with single-building integration from powder to finished cell, bypassing traditional merchant cathode material markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities emerge as EU Battery Regulation compliance deadlines and US IRA domestic content requirements create divergent qualification pathways, opening niches for mid-scale specialists with in-house testing laboratories.
For Market Incumbents: Fortify upstream control over cathode precursor refining in Jiangsu-Fujian corridors to defend margin pools against Korean cylindrical specialists entering European premium segments. Expand dry electrode coating pilot lines to 10 GWh scale before process patents consolidate. Capture carbon footprint documentation capabilities ahead of EU Battery Regulation recycled content mandates tightening contract prerequisites.
For New Entrants and Emerging Players: Differentiate on UN 38.3 transport certification integration with in-house testing laboratories to collapse supplier qualification timelines for international OEM contracts. Target Texas and Australian grid-scale energy storage deployments where thermal stability requirements favor iron-phosphate chemistries and decade-long cycle warranties absorb surplus production capacity. Pursue second-life stationary storage arbitrage through residual capacity contracts with California and German utilities.
For Investors and Strategic Acquirers: The EU Battery Regulation's carbon border adjustment mechanism reshapes the acquisition landscape toward suppliers with documented mine-to-cell traceability and ISO 14067 product carbon footprint capabilities. Long-term viability centers on producers with backward integration into cathode precursor processing rather than pure-play cell assemblers. Monitor GB/T certification gate expansions as signal for Chinese domestic subsidy eligibility shifts redirecting capacity investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Coating Scale-Up | Eliminates N-methyl-2-pyrrolidone recovery infrastructure and enables single-building integration from powder to cell. |
| Long-Term Offtake Agreement Negotiation | Locks in fixed-volume, variable-pricing structures with German and US automakers displacing spot procurement. |
| In-House UN 38.3 Testing Laboratory Investment | Collapsing supplier qualification timelines opens international OEM contract access for mid-scale manufacturers. |
| Backward Integration into Cathode Precursor Refining | Captures margin pools previously distributed across separate mining, refining, and cell assembly stages. |
| Second-Life Stationary Storage Platform Development | Extends asset utility beyond vehicle service life through California and German grid stabilization contracts. |
Research Methodology
Initial hypotheses were tested against primary input from cell manufacturing executives, automotive OEM procurement leads, energy storage system integrators, and cathode material R&D directors and refined through secondary validation. Primary fieldwork encompassed gigafactory operations in Jiangsu and Fujian provinces, European automaker engineering centers in Bavaria and Baden-Württemberg, and Texas grid-scale deployment sites. Secondary sources included MIIT GB/T certification databases, EU Battery Regulation implementation guidance, FERC Order 841 compliance filings, and customs trade data for lithium carbonate and spodumene concentrate flows. Bottom-up cell shipment data triangulated against top-down electric vehicle production forecasts and energy storage deployment pipelines.
Variance decomposition across the projection horizon isolates volume drivers by cell format, end-use segment, and regional regulatory cluster. Segmentation dimensions modeled include prismatic-cylindrical-pouch format splits, electric vehicle versus grid storage versus industrial equipment end-use channels, and China-US-Germany-Australia regional production clusters. CAGRs derive from installed capacity buildout schedules, OEM platform electrification roadmaps, and deregulated electricity market storage procurement mechanisms. Forecast inputs incorporate IRA domestic content bonus credit utilization rates and EU Battery Regulation carbon footprint declaration phase-in timelines.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate price stability, GB/T certification continuity, or European automaker iron-phosphate platform adoption would require recalibration. Forecasts reflect documented assumptions regarding dry electrode coating technology diffusion rates and second-life pack residual capacity degradation curves. Recalibration cycles align with material shifts in MIIT subsidy eligibility criteria, EU Battery Regulation delegated act publications, and Texas ERCOT market design reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market