
 Lithium Battery in Myanmar Market | 2026-2036
Lithium Battery in Myanmar Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery in Myanmar Market Insights
Aftermarket refurbishment revenue is narrowing as original equipment manufacturers tighten control over cell replacement protocols. Siam GS Battery Myanmar Limited dominates localized assembly operations for commercial vehicle fleets. Panasonic Corporation leverages its regional supply relationships to sustain premium positioning in consumer electronics channels. GSL Energy specializes in modular storage configurations for off-grid industrial sites.
Lithium batteries are electrochemical energy storage devices utilizing lithium-ion movement between anode and cathode materials, typically achieving energy densities of 150-300 Wh/kg depending on cathode chemistry. Their primary purpose in Myanmar centers on replacing lead-acid systems in telecom towers, solar mini-grids, and emerging electric mobility platforms. LFP chemistry leads current procurement volumes due to thermal stability advantages in tropical climates, while NMC formulations occupy the fastest-growing tier among electric two-wheeler OEMs seeking higher energy density. Stationary installations anchor the present revenue base, though portable configurations for construction and agriculture equipment represent an expanding margin pool.
Myanmar's Department of Trade and the national energy regulator shape import compliance for battery systems, with customs classifications determining duty exposure for finished packs versus cell components. The country's central bank influences foreign exchange availability for raw material procurement, directly constraining manufacturer working capital cycles. Stakeholders must monitor whether ASEAN harmonization of battery safety standards accelerates technical barriers or opens cross-border certification pathways.
Market Dynamics
The Ministry of Electricity and Energy's relaxation of import licensing for energy storage components is redrawing competitive boundaries, enabling fleet operators in Yangon and Mandalay to bypass legacy lead-acid supply channels and source lithium-ion packs directly from regional manufacturers.
Growth Catalysts
- ASEAN Harmonization Trajectory:Myanmar's customs classifications for finished battery packs versus cell components are aligning with emerging regional safety standards, reducing technical barriers for cross-border certification pathways.
- Electric Two-Wheeler Fleet Conversion:Commercial mobility operators in the Yangon industrial corridor are replacing internal combustion engines with lithium-ion powertrains to circumvent fuel import volatility and maintenance complexity.
- Solar Mini-Grid Deployment:Off-grid industrial sites in manufacturing zones are deploying modular LFP storage to replace diesel generator backup, driven by thermal stability requirements in tropical operating conditions.
Market Restraints
- Foreign Exchange Constrained Procurement:The Central Bank of Myanmar's rationing of hard currency extends working capital cycles for manufacturers importing cathode active materials and electrolyte salts.
- Cell Chemistry Concentration Risk:Regional supply of LFP and NMC cells clusters among a limited set of ASEAN assembly operations, creating vulnerability to upstream raw material allocation decisions.
- Lead-Acid Incumbency in Telecom:Tower operators retain installed base investments in valve-regulated lead-acid systems, delaying full lithium conversion despite superior cycle life metrics.
Strategic Opportunities
- Construction and Agriculture Equipment Electrification:Portable battery configurations for excavators and irrigation pumps represent an underpenetrated margin pool beyond stationary installations.
- Backward Integration into Cell Assembly:Localized pack assembly operations can extend upstream into electrode coating and cell formation, capturing value currently exported to Thailand and Vietnam.
- Department of Trade Duty Reclassification:Advocacy for component-level import classifications versus finished pack tariffs could reshape landed cost structures for industrial buyers.
Industry Challenges
- Battery Management System Firmware Expertise:Pack assemblers lack embedded software capabilities for state-of-charge algorithms and thermal runaway prevention, forcing reliance on foreign module suppliers.
- UN 38.3 Certification Timelines:Lithium-ion shipments require hazardous materials testing documentation that customs authorities scrutinize inconsistently, creating port clearance delays.
- Legacy Electrical Infrastructure Compatibility:Industrial sites with aging distribution networks face integration complexity when connecting high-voltage battery storage to existing switchgear and protection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery in Myanmar Market |
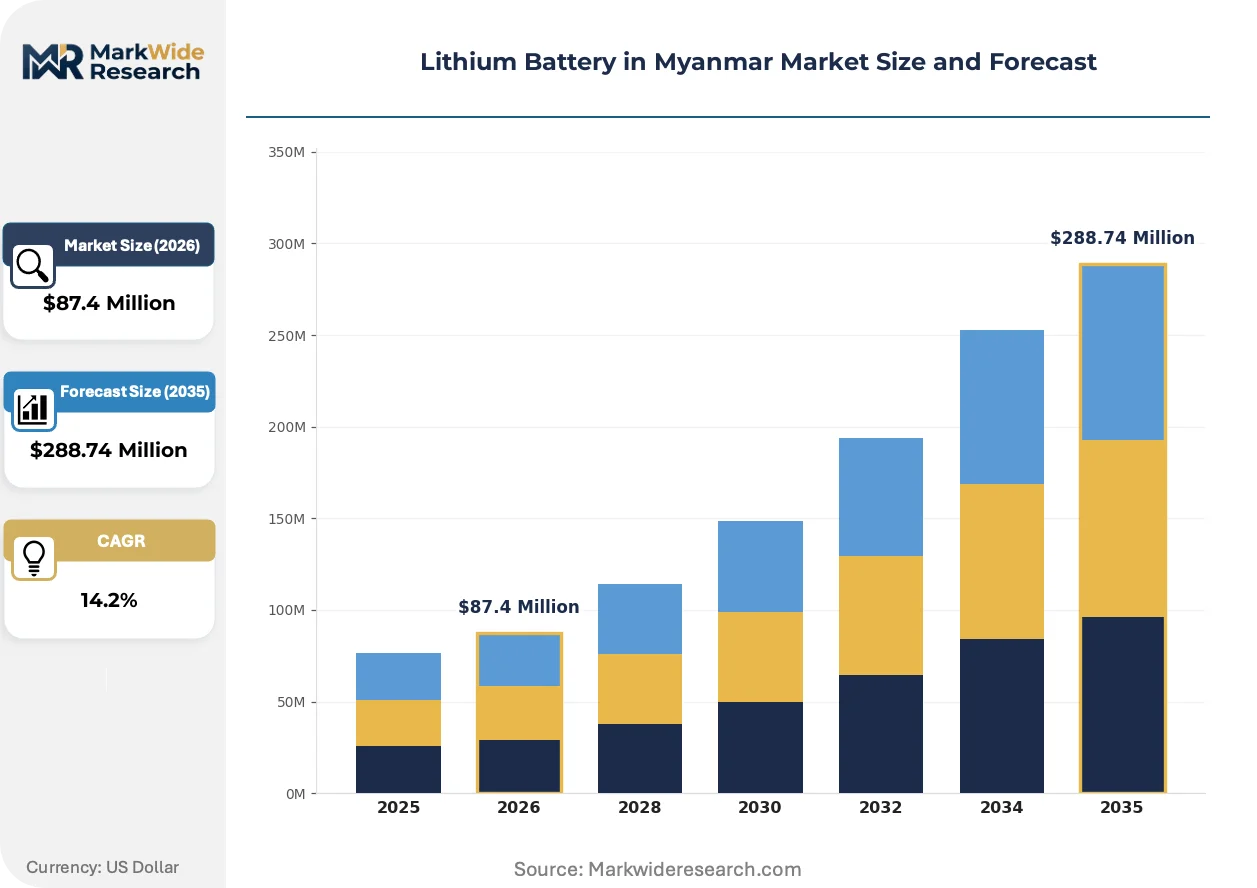
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, NCA, LTO Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Manufacturers, Retailers, Utilities, Service Providers Installation: Stationary, Portable, Built-in, Modular |
| Companies Covered | Panasonic Corporation, Schneider Electric SE, Siam GS Battery Myanmar Limited, Toyo Battery Myanmar Co Ltd, GSL Energy, Thailand Battery Manufacturers (Regional Suppliers), Singapore Battery Suppliers, Indonesian Battery Manufacturers, Chinese Battery Producers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery in Myanmar Market Trends and Innovations
Lithium battery technology in Myanmar is fragmenting across multiple chemistry and form-factor pathways simultaneously, with no single configuration achieving dominant design status across the three core demand verticals of mobility, stationary storage, and portable industrial power.
LFP cathode formulations are hybridizing with silicon-enhanced anode architectures to bridge the energy density gap with NMC alternatives while retaining thermal stability advantages. Electric two-wheeler OEMs serving the Mandalay commuter market are piloting these hybrid cells to extend range without sacrificing safety margins in ambient temperatures exceeding 40°C. The chemistry convergence is compressing the traditional premium-standard-economy tiering in procurement specifications.
Myanmar's Department of Trade and the national energy regulator are implementing customs valuation protocols that distinguish between energy storage components and finished battery systems, altering duty exposure calculations for importers. Industrial buyers in the Yangon corridor are restructuring purchase orders to maximize component-level classifications. Fleet operators with established regional supply relationships are responding by consolidating procurement through ASEAN-registered trading entities.
Aftermarket service models are unbundling from original equipment supply contracts as fleet operators develop in-house cell replacement capabilities. Commercial vehicle operators in Yangon are establishing direct relationships with regional cell suppliers, bypassing branded pack assemblers for refurbishment cycles. This disintermediation is most visible among telecom tower operators with technical staffing capacity to execute module-level swaps.
Lithium Battery in Myanmar Market Segmentation
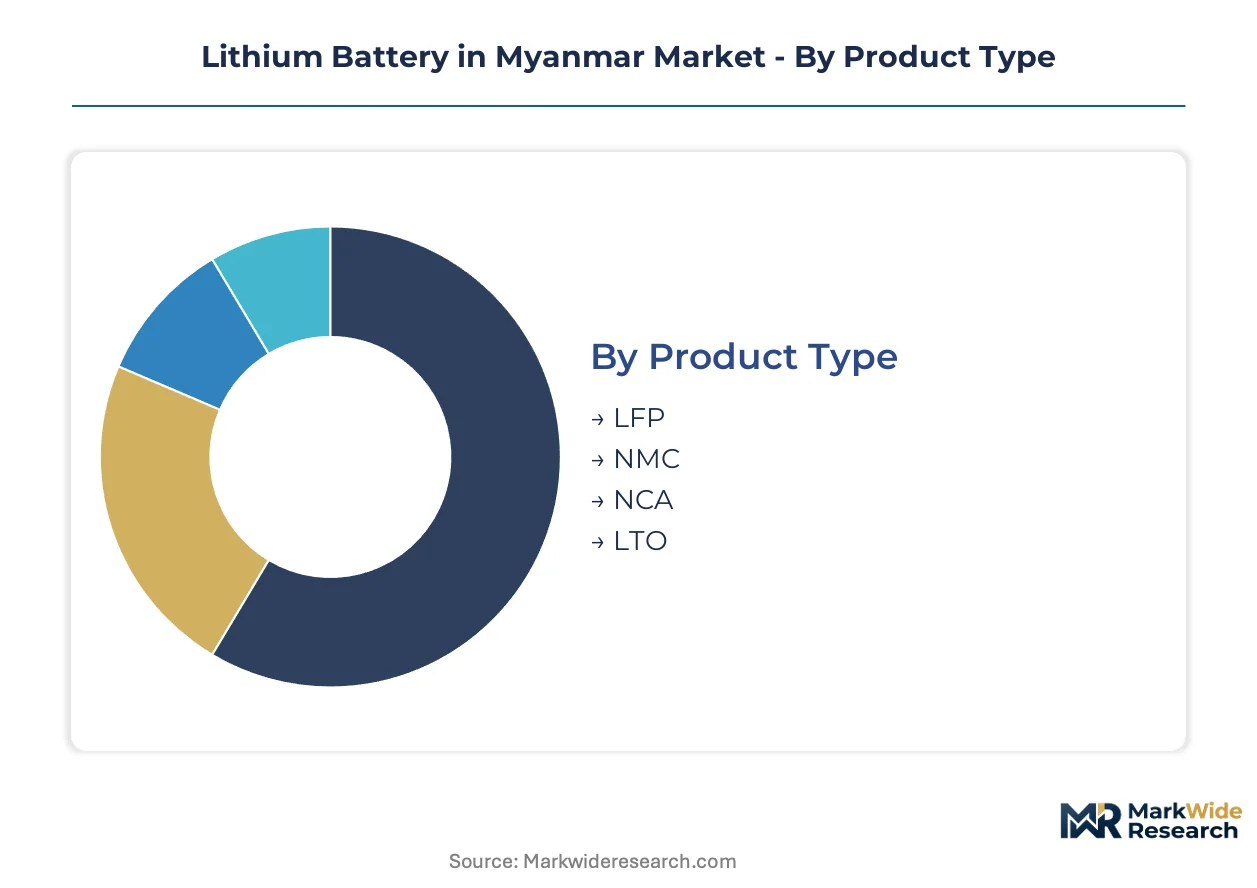
Segmentation in Myanmar's lithium battery market reveals how chemistry choices, application requirements, and installation constraints create distinct procurement corridors. Each dimension carries regulatory and logistical implications that reshape competitive boundaries.
Product Type:
Mature cathode formulations anchor industrial procurement, while emerging chemistries target mobility applications seeking higher energy density.
- LFP:Lithium iron phosphate cells achieve 150-160 Wh/kg with superior thermal stability in ambient temperatures exceeding 40°C. Telecom tower operators in the Yangon industrial corridor specify LFP for backup power to mitigate fire risk in unmanned installations.
- NMC:Nickel-manganese-cobalt formulations deliver 200-250 Wh/kg, enabling electric two-wheeler OEMs to extend range without increasing pack volume. Fleet operators in Mandalay are converting internal combustion engines to NMC powertrains to circumvent fuel import volatility.
- NCA:Nickel-cobalt-aluminum chemistry occupies premium consumer electronics channels requiring maximum energy density in constrained form factors.
- LTO:Lithium titanate anode systems enable ultra-fast charging for commercial vehicle fleets with route downtime measured in minutes.
LFP handles the majority of throughput; NMC is the fastest mover on share.
Application:
Cost tier stratification separates capital-intensive stationary installations from volume-driven consumer segments.
- Consumer Electronics:Smartphone and laptop OEMs source cylindrical and pouch cells through regional distributors, with Panasonic Corporation sustaining premium positioning via established supply relationships.
- Electric Vehicles:Two-wheeler conversions dominate procurement volumes in Yangon and Mandalay, where fleet operators bypass legacy fuel supply channels. The Ministry of Electricity and Energy's relaxed import licensing accelerates direct sourcing from ASEAN manufacturers.
- Renewable Energy Storage:Solar mini-grid developers deploy modular LFP configurations to replace diesel generator backup at off-grid industrial sites.
- Industrial Equipment:Construction and agriculture electrification represents an underpenetrated margin pool beyond stationary installations.
Renewable energy storage commands the highest average transaction value; electric vehicles are expanding most quickly in unit terms.
End User:
Customer type determines procurement sophistication, from technical specification control to price-taking distributor relationships.
- Manufacturers:Pack assemblers like Siam GS Battery Myanmar Limited source cells and management systems for localized commercial vehicle fleet supply.
- Retailers:Electronics distributors serve consumer replacement markets with finished packs, absorbing customs duty exposure on finished systems versus component classifications.
- Utilities:Grid operators evaluate battery storage for frequency regulation, constrained by aging distribution network compatibility.
- Service Providers:Telecom tower operators develop in-house cell replacement capabilities, disintermediating branded pack assemblers for refurbishment cycles.
Manufacturers absorb the largest import volume; service providers are restructuring procurement fastest toward direct cell relationships.
Installation:
Physical configuration dictates integration complexity and regulatory pathway, from plug-and-deploy portable units to engineered stationary systems.
- Stationary:Rack-mounted systems for telecom and solar applications require UN 38.3 certification documentation that customs authorities scrutinize inconsistently, creating port clearance delays.
- Portable:Configurations for construction and agriculture equipment utilize standardized form factors with simplified electrical integration.
- Built-in:OEM-integrated packs in electric two-wheelers tighten original equipment manufacturer control over cell replacement protocols, narrowing aftermarket refurbishment revenue.
- Modular:Scalable architectures enable off-grid industrial sites to increment capacity without full system replacement, with GSL Energy specializing in these configurations.
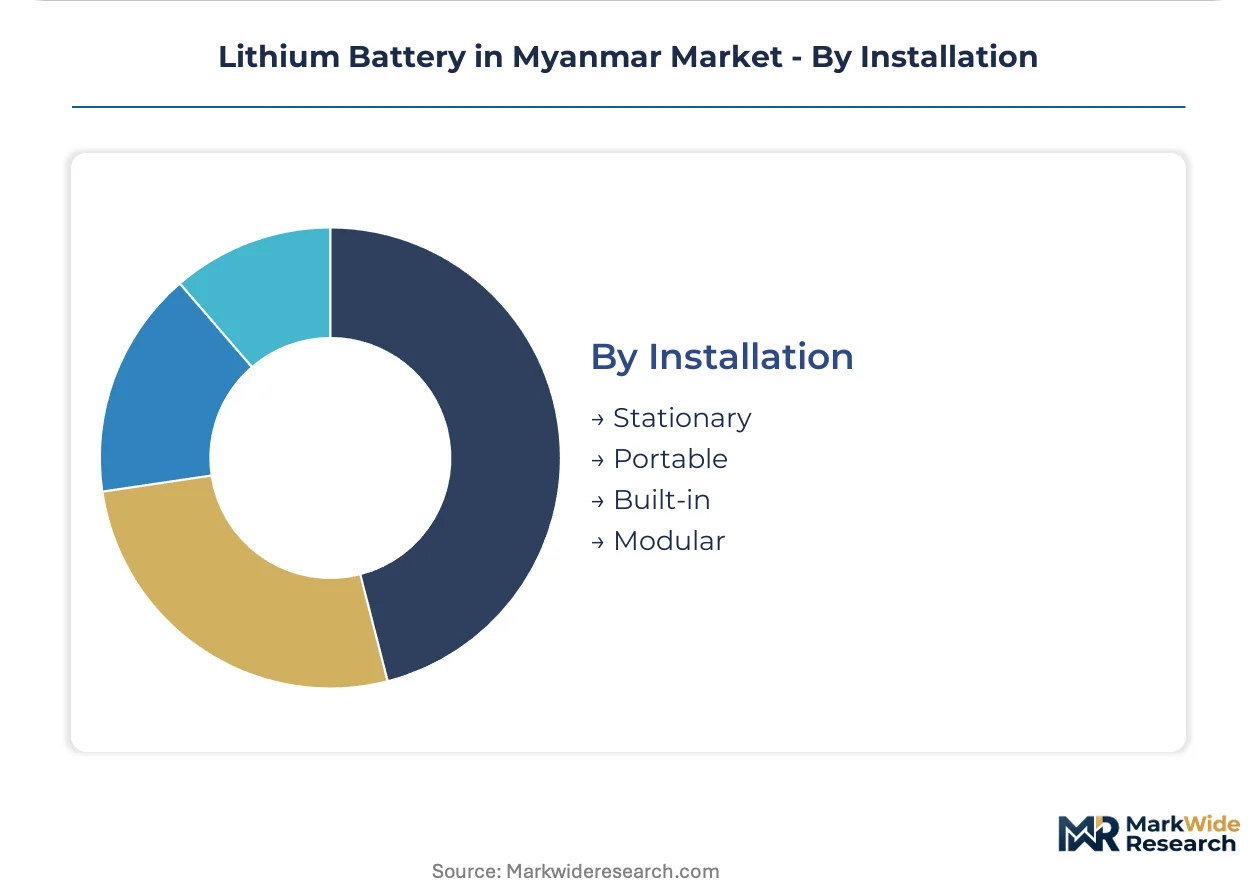
Stationary installations anchor present revenue; modular systems are climbing the fastest as manufacturing zones seek scalable backup solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive fleet operators in Mandalay drive volume procurement, while Yangon industrial buyers absorb premium pricing for thermal-stable configurations.
Yangon Industrial Corridor
Telecom tower operators and manufacturing zones anchor stationary storage demand for backup power systems. The Ministry of Electricity and Energy's relaxed import licensing enables direct sourcing from ASEAN manufacturers. Yangon's Thilawa Special Economic Zone concentrates modular LFP deployments for off-grid industrial sites replacing diesel generators.
Mandalay Commercial Hub
Electric two-wheeler fleet conversions dominate procurement volumes as commercial mobility operators circumvent fuel import volatility. The Department of Trade's customs classifications determine duty exposure for finished packs versus cell components. Mandalay's urban core clusters NMC procurement for higher energy density mobility applications.
Naypyidaw Administrative Zone
Government facility electrification programs create institutional demand for standardized battery configurations. The national energy regulator shapes grid-scale storage evaluation for frequency regulation applications. Central Myanmar's administrative capital hosts pilot deployments constrained by aging distribution network compatibility.
Southern Coastal Region
Solar mini-grid developers target off-grid fishing and agricultural communities with portable battery configurations. Foreign exchange rationing from the Central Bank of Myanmar extends working capital cycles for cathode material procurement. The Dawei and Myeik corridors represent underpenetrated margin pools for construction equipment electrification.
Lithium Battery in Myanmar Market Competitive Landscape
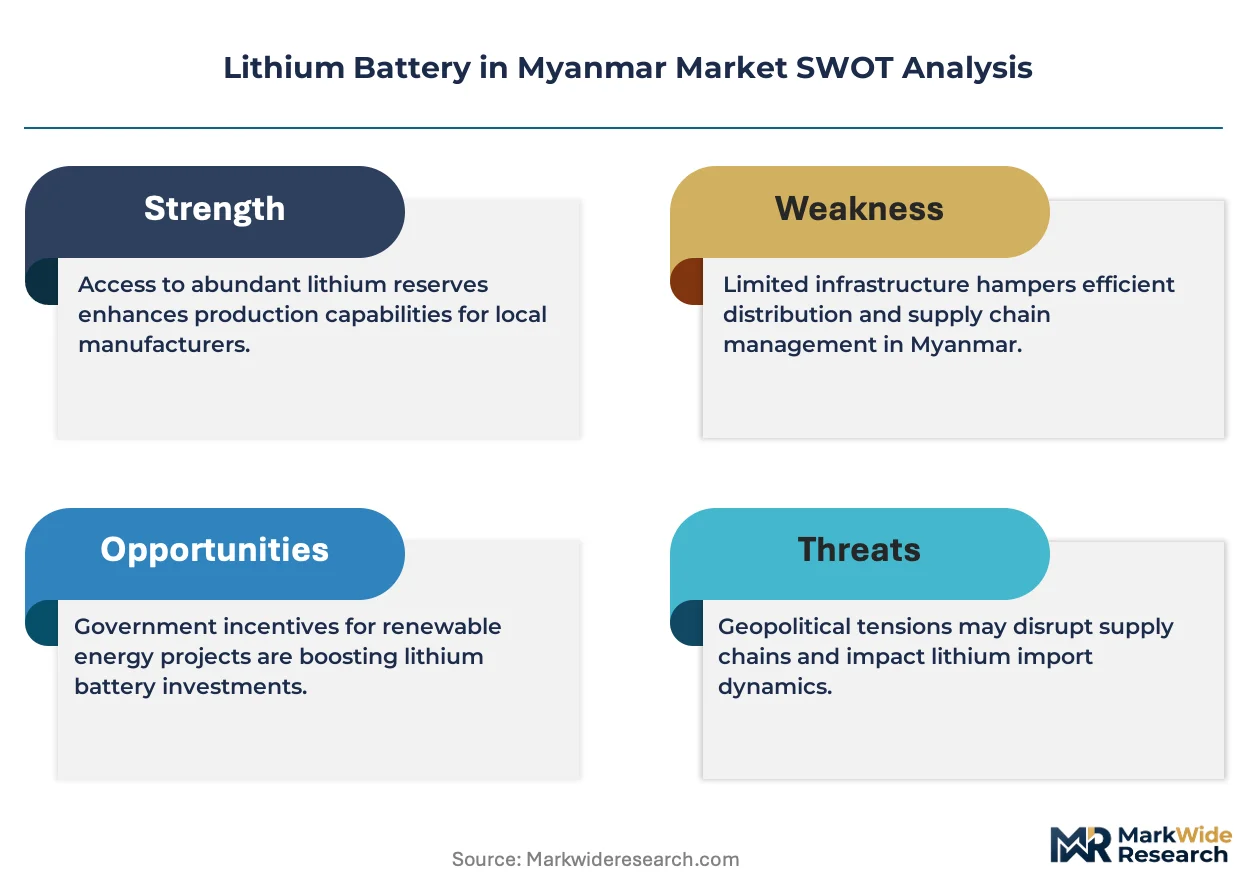
Capability concentration sits with regional cell suppliers; scale advantage sits with localized pack assemblers serving fleet operators. The vendor base separates into three tiers: branded electronics channels, commercial vehicle fleet suppliers, and modular storage specialists. Two strategic archetypes dominate—ASEAN-registered trading entities consolidating procurement, and backward-integrated assemblers capturing electrode coating value. Competitive moves center on customs classification restructuring and direct cell relationship cultivation.
Among Japan-based electronics conglomerates, Panasonic Corporation occupies premium positioning in consumer replacement channels. Siam GS Battery Myanmar Limited exemplifies the localized assembly archetype for commercial fleet supply. GSL Energy represents modular configuration specialization for off-grid industrial applications. These three anchors illustrate how geographic origin and organizational structure map to distinct procurement corridors within Myanmar's import-dependent supply framework.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Schneider Electric SE |
| Siam GS Battery Myanmar Limited |
| Toyo Battery Myanmar Co Ltd |
| GSL Energy |
| Thailand Battery Manufacturers (Regional Suppliers) |
| Singapore Battery Suppliers |
| Indonesian Battery Manufacturers |
| Chinese Battery Producers |
| Others |
Pricing and Supply Chain Analysis
Chinese cathode active material suppliers concentrate upstream pricing power, compressing margin pools for Myanmar-based pack assemblers who must absorb foreign exchange volatility while competing on landed cost against ASEAN-registered trading entities.
Pricing Analysis
Aftermarket refurbishment revenue drives lifetime value for fleet operators developing in-house cell replacement capabilities. Three-tier pricing structure across premium, standard, and economy levels separates Panasonic's consumer electronics channels from Siam GS Battery's commercial fleet supply and GSL Energy's modular industrial configurations. Cost compression in the standard tier intensifies because regional cell suppliers are consolidating procurement through ASEAN trading entities. Telecom tower operators exhibit highest price sensitivity due to installed base investments in lead-acid systems, while electric two-wheeler OEMs absorb premium pricing for NMC energy density advantages.
Supply Chain Analysis
Extended payment terms from Thai and Vietnamese electrode coating facilities are tightening working capital cycles for Myanmar pack assemblers sourcing cathode materials. Supply concentration clusters in China, South Korea, and Japan for cell production, with Thailand and Vietnam hosting regional electrode coating and formation operations. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability runs through Chinese cathode precursor supply. Distribution runs through ASEAN-registered trading entities consolidating procurement for Yangon and Mandalay fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's lithium battery market is cycling through a recovery phase as foreign exchange rationing eases and the Ministry of Electricity and Energy's import licensing relaxation unlocks pent-up fleet conversion demand.
For Market Incumbents: Pre-empt disintermediation by telecom tower operators through captive refurbishment service contracts and embedded battery management system firmware licensing. Siam GS Battery Myanmar Limited should extend upstream into electrode coating to capture value currently exported to Thailand, defending against direct cell relationships that fleet operators are cultivating with regional suppliers. For New Entrants and Emerging Players: Pursue construction and agriculture equipment electrification as the most penetrable white-space segment beyond stationary installations and mobility conversions. Modular portable configurations for excavators and irrigation pumps offer lower certification barriers than UN 38.3 stationary systems. A go-to-market angle through equipment leasing partnerships bypasses direct competition with established pack assemblers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ASEAN trading entities consolidating procurement for Myanmar fleet operators. The five-to-ten year viability window hinges on whether backward integration into cell assembly achieves scale before Chinese manufacturers establish direct Myanmar distribution. Watch for inflection in the Central Bank of Myanmar's foreign exchange allocation toward energy storage component imports as the priority signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Coating | Captures value currently exported to Thai and Vietnamese formation facilities. |
| ASEAN-Registered Trading Entity Consolidation | Restructures procurement to optimize customs classifications and duty exposure. |
| Battery Management System Firmware Licensing | Creates recurring revenue barrier against fleet operator disintermediation. |
| Modular Portable Configuration Development | Targets underpenetrated construction and agriculture equipment segments. |
| Direct Regional Cell Supplier Relationships | Bypasses branded pack assemblers for refurbishment cycle margin capture. |
Research Methodology
A standing panel of pack assembly operations managers, telecom tower maintenance directors, electric two-wheeler fleet procurement leads, and solar mini-grid project developers provided ongoing calibration across primary interview cycles. Secondary validation drew from Myanmar Department of Trade customs classification records, Central Bank of Myanmar foreign exchange allocation disclosures, ASEAN harmonization protocol documents, and UN 38.3 certification registries. Bottom-up cell shipment estimates triangulated against top-down energy storage deployment projections.
Scenario-bracketing framed low, base, and high cases across the projection horizon based on foreign exchange availability trajectories and import licensing enforcement variability. Segmentation dimensions modeled include cathode chemistry tier, application vertical, end-user procurement sophistication, and installation configuration type. CAGRs derived from logistic diffusion curves fitted to fleet conversion adoption patterns and diesel generator replacement cycles in off-grid industrial zones.
Macroeconomic conditions sit as an overlay; deviation in kyat-dollar exchange rates and regional lithium carbonate pricing would shift the trajectory. Forecasts reflect assumptions around ASEAN harmonization timelines and customs valuation protocol stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market