
 Large Capacity Lithium Battery Packs Sales Market | 2026-2036
Large Capacity Lithium Battery Packs Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Large Capacity Lithium Battery Packs Sales Market Insights
Modular battery pack architecture is hardening as the dominant procurement format, letting OEMs swap cell chemistries without redesigning thermal management or BMS hardware. CATL leverages its vertical cell-to-pack integration to capture platform-level contracts with premium EV brands. LG Energy Solution anchors its position through dedicated cylindrical supply lines for performance-oriented drivetrains. Samsung SDI competes on high-nickel NMC formulations that extend range benchmarks for luxury segments.
Large capacity lithium battery packs are electrochemical energy storage systems typically exceeding 10 kWh in rated capacity, constructed from serialized cell arrays with integrated battery management, thermal regulation, and high-current interconnects, manufactured through precision winding or stacking processes followed by electrolyte filling and formation cycling. Their primary purpose is to deliver sustained high-power discharge for mobility and grid-scale storage applications. Prismatic formats dominate automotive traction applications due to space-efficient stacking and structural pack integration, while cylindrical cells sustain premium positioning in performance EVs where consistent thermal behavior matters. LFP chemistry leads the utility-scale energy storage segment on cost and cycle life, with NMC retaining share in range-critical automotive platforms where energy density premiums justify cobalt and nickel exposure.
China's MIIT enforces GB standards for cell safety and traceability that determine market access for domestic pack assemblers. The EU's Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that reshape supplier qualification for European automotive OEMs. In the US, NHTSA and EPA rules on EV safety and zero-emission credits influence pack design priorities and volume commitments. Stakeholders must monitor how divergent certification timelines across these three jurisdictions affect platform standardization strategies and capital allocation for regional production capacity.
Market Dynamics
Cell-to-pack architecture is compressing module assembly tiers, forcing pack integrators to absorb thermal management and BMS development costs previously outsourced to tier-1 suppliers. This structural compression reshapes margin pools across the value chain.
Growth Catalysts
- EU Battery Regulation:Carbon footprint disclosure mandates and recycled content thresholds accelerate qualification of European-based cell suppliers for automotive OEM platform programs.
- Grid-scale storage procurement:Utility buyers in Texas and California are contracting multi-gigawatt-hour LFP installations, creating dedicated demand streams independent of automotive cycles.
- Silicon anode loading:Higher silicon percentages in graphite blends boost energy density without full solid-state transition costs, attracting premium EV drivetrain engineering teams.
Market Restraints
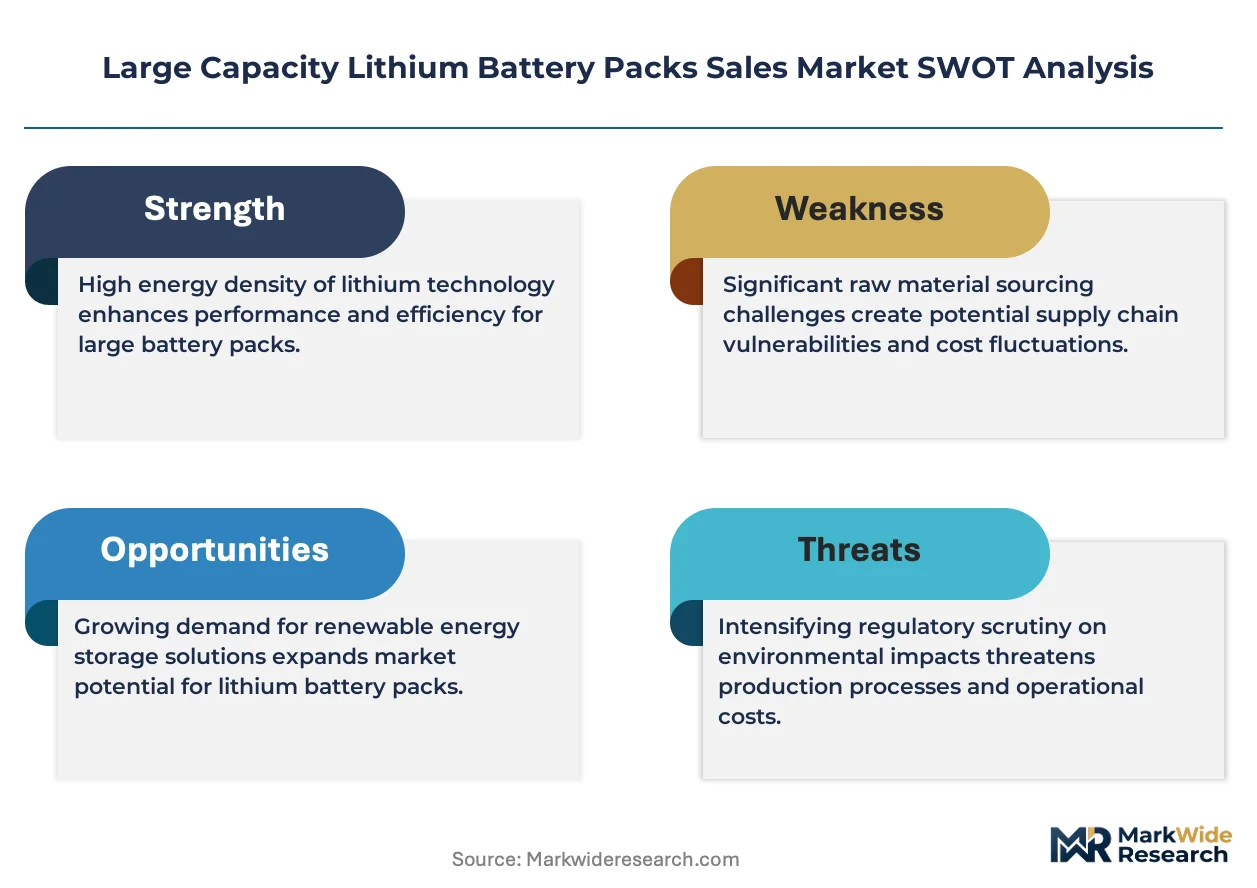
- Refined lithium carbonate volatility:Spot pricing swings in Chilean and Australian spodumene concentrate feedstocks compress pack assembler margins during contract renegotiation windows.
- Prismatic cell supply concentration:Six Chinese producers control over seventy percent of automotive-grade prismatic capacity, creating single-source vulnerability for European and North American pack integrators.
- Nickel supply geopolitics:Indonesian ore processing dominance and Russian refined metal sanctions exposure complicate NMC cathode supply security for high-range EV platforms.
Strategic Opportunities
- Second-life stationary storage:Retired automotive packs with seventy percent remaining capacity are redeploying behind-the-meter for commercial and industrial peak shaving in Germany and Japan.
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting pack assembly investments targeting domestic two-wheeler and three-wheeler electrification.
- Bidirectional charging integration:Vehicle-to-home and vehicle-to-grid hardware convergence creates new revenue streams for pack suppliers embedding DC-AC inverters and grid-interconnection firmware.
Industry Challenges
- Thermal runaway simulation expertise:Pack engineers with computational fluid dynamics and abuse testing credentials command premium compensation, constraining R&D team scaling for mid-tier suppliers.
- GB standard certification timelines:China's MIIT cell safety and traceability approvals extend platform launch schedules by eight to fourteen months for non-domestic pack integrators.
- Legacy BMS software integration:OEM proprietary communication protocols fragment pack supplier development roadmaps, forcing redundant firmware engineering across customer programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Capacity Lithium Battery Packs Sales Market |
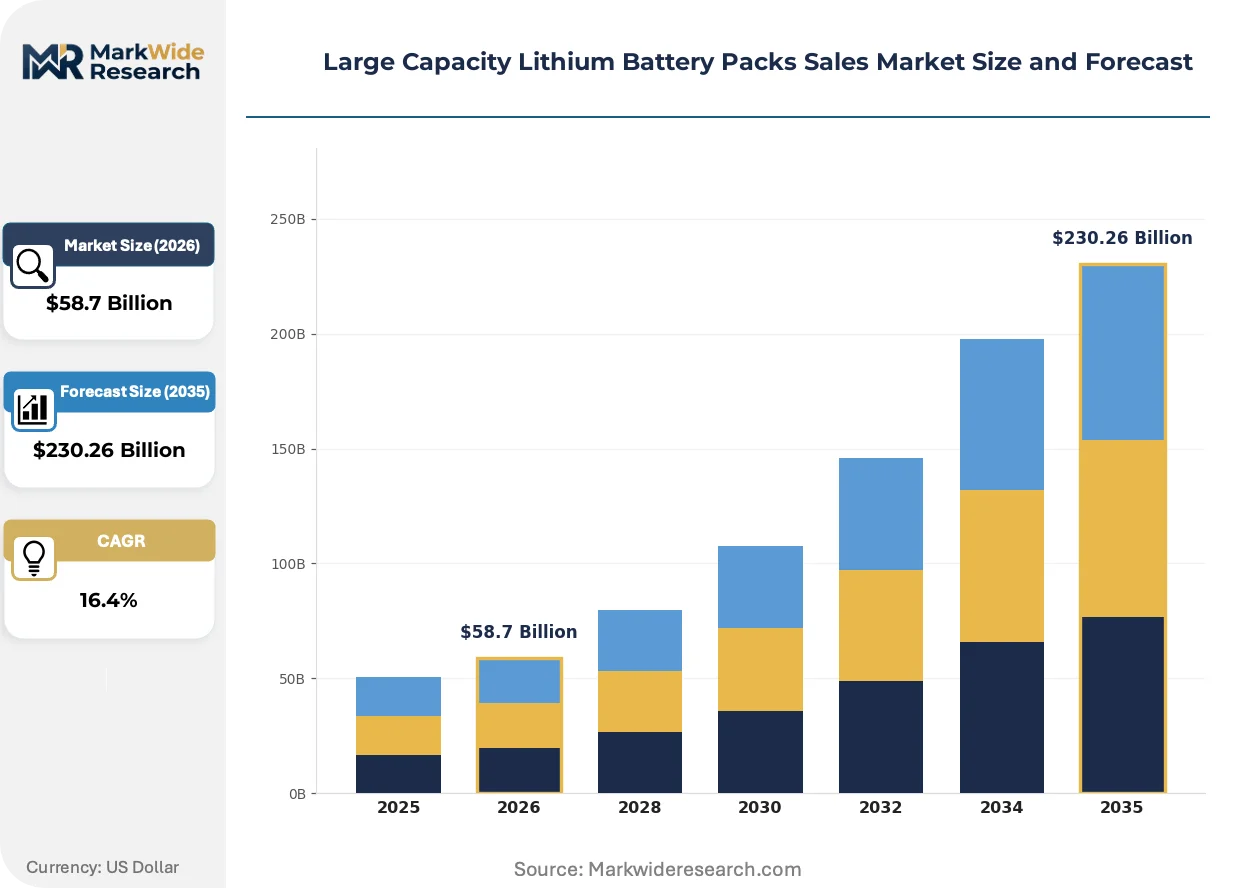
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $230.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Custom End User: Automotive, Renewable Energy, Consumer Electronics, Industrials Application: Energy Storage Systems, Electric Vehicles, UPS, Power Tools Technology: LFP, NMC, LTO, LiCoO2 |
| Companies Covered | CATL, LG Energy Solution, Panasonic, Samsung SDI, BYD, Eastman, Sony, Hefei Guoxuan, Tianjin Lishen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Capacity Lithium Battery Packs Sales Market Trends and Innovations
Dry electrode coating processes are eliminating solvent-based manufacturing steps, cutting energy consumption and capital intensity while enabling thicker cathode loadings. This process shift reconfigures equipment supplier relationships and factory footprint economics.
Cell-to-pack structural battery designs are overtaking modular architectures by eliminating module housings, busbars, and redundant thermal interface materials. Premium EV manufacturers in Germany and South Korea are adopting this format for platform-level weight reduction and pack volumetric efficiency gains. The technology is compressing tier-1 module supplier revenue pools while shifting margin capture toward cell producers with integrated thermal management capabilities.
The EU Battery Regulation's due diligence and carbon footprint disclosure requirements are forcing pack suppliers to deploy blockchain-enabled supply chain traceability systems. Cell producers must document upstream mining and refining emissions to qualify for European automotive OEM contracts. High-nickel NMC formulations face the steepest compliance burden due to cobalt and nickel supply chain complexity, accelerating LFP substitution for standard-range vehicle segments.
Fleet operators and energy storage developers are consolidating procurement through long-term offtake agreements with cell producers, bypassing traditional pack assembler intermediaries. Direct contracting locks in volume commitments and pricing visibility across five-to-seven-year horizons. This pattern concentrates most visibly in North American utility-scale storage deployments and European commercial vehicle electrification programs, where capital discipline and total cost of ownership transparency override brand preference.
Large Capacity Lithium Battery Packs Sales Market Segmentation
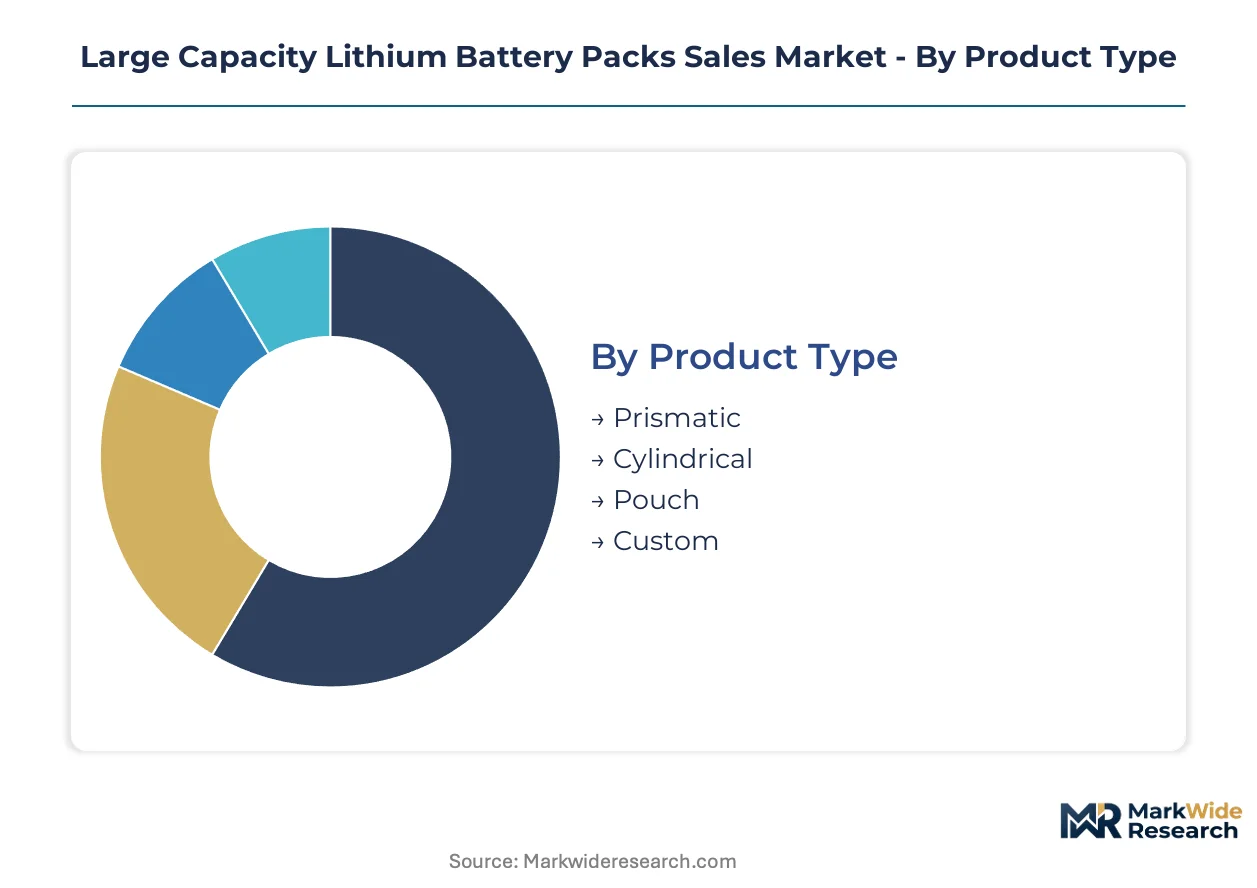
Large capacity lithium battery pack procurement decisions diverge sharply across customer archetypes, with automotive OEMs prioritizing energy density and cycle life while utility buyers optimize for capital cost per kWh and degradation curves. Segmentation clarity exposes where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Automotive OEMs and energy storage developers select cell formats based on thermal management requirements, structural integration needs, and supplier ecosystem maturity rather than unit cost alone.
- Prismatic:Rectangular aluminum-cased cells with stacked electrode layers enable direct pack-level structural integration without module housings. CATL and BYD dominate automotive-grade supply, with German premium EV platforms and Chinese OEM volume programs absorbing the majority of output.
- Cylindrical:Rolled jellyroll construction inside steel cans delivers consistent thermal behavior and automated manufacturing scalability. Tesla's 4680 format and LG Energy Solution's 21700 lines serve performance-oriented drivetrains where cylindrical format reliability offsets pack-level complexity.
- Pouch:Laminated polymer-aluminum foil enclosures minimize dead space in irregular pack geometries. SK On supplies Korean and European OEMs seeking flexible form factors for crossover and SUV platforms.
- Custom:Bespoke dimensions and terminal configurations address aerospace, marine, and specialized industrial applications with low volume tolerance for engineering overhead.
Volume sits with prismatic formats; growth tilts toward cylindrical as 4680-scale production achieves cost parity.
End User:
Customer type determines contract structure, with automotive programs demanding platform-level commitments and utility procurement favoring project-specific offtake agreements.
- Automotive:Passenger and commercial vehicle OEMs contract cell supply five to seven years forward, tying pricing to lithium carbonate indices and specifying thermal runaway propagation thresholds. NHTSA safety investigations and EU Battery Regulation carbon disclosure requirements extend qualification timelines.
- Renewable Energy:Utility and independent power developer procurement concentrates in Texas ERCOT and California CAISO markets, with LFP chemistry dominating multi-gigawatt-hour installations. FERC interconnection rules and state storage mandates shape deployment schedules.
- Consumer Electronics:Power tool and personal mobility device manufacturers source mid-capacity packs through trading houses, prioritizing delivery reliability over technical differentiation.
- Industrials:Forklift, mining equipment, and material handling OEMs specify ruggedized packs with IP67 enclosures and wide temperature operating ranges.
Automotive commands absolute revenue share; renewable energy expands most quickly as utility procurement scales beyond automotive cycle dependency.
Application:
Use case dictates cell chemistry selection, thermal architecture complexity, and battery management system firmware requirements.
- Energy Storage Systems:Grid-scale and behind-the-meter installations prioritize cycle life and degradation predictability over energy density. LFP chemistry from CATL and BYD dominates Texas and California utility deployments.
- Electric Vehicles:Traction applications balance range requirements against fast-charging capability and cold-weather performance. NMC formulations retain share in luxury segments; LFP penetrates standard-range platforms.
- UPS:Uninterruptible power supply applications demand high discharge rates and float charge stability for data center and telecommunications backup.
- Power Tools:Cordless equipment requires compact packs with high specific power and rapid cycle capability under partial state-of-charge conditions.
Electric vehicle applications anchor current volume; energy storage systems gain share fastest as grid-scale procurement accelerates.
Technology:
Cathode chemistry selection involves tradeoffs between energy density, cost structure, supply chain security, and regulatory compliance burden.
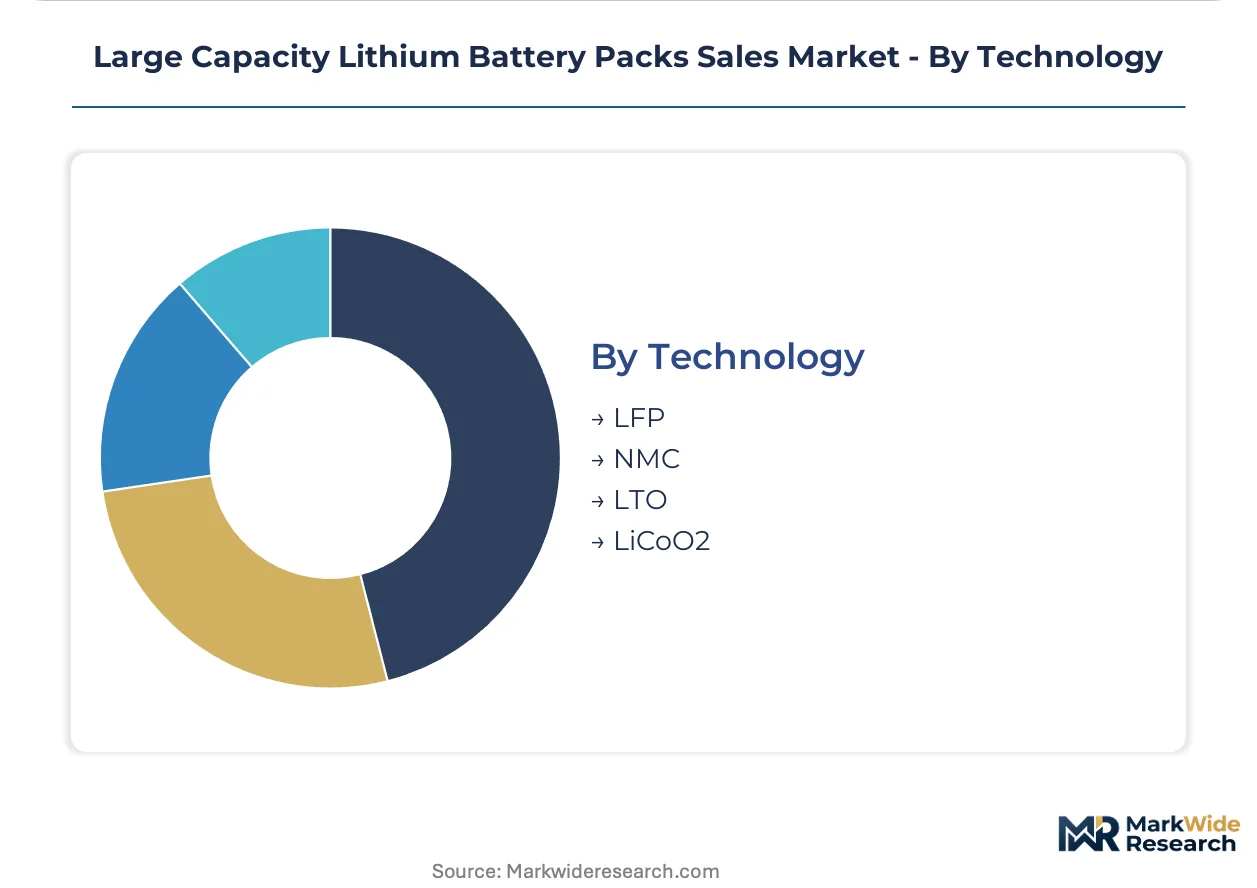
- LFP:Lithium iron phosphate eliminates cobalt and nickel exposure, delivering superior cycle life and thermal stability at lower material cost. CATL's cell-to-pack integration and BYD's blade cell format dominate utility storage and Chinese standard-range automotive.
- NMC:Nickel-manganese-cobalt layered oxides maximize volumetric energy density for range-critical applications. Samsung SDI and LG Energy Solution supply Korean and European premium OEMs, though Indonesian nickel processing concentration and EU Battery Regulation carbon disclosure requirements complicate qualification.
- LTO:Lithium titanate anodes enable extreme fast-charging and sub-zero operation with minimal degradation, serving niche bus and industrial applications where cycle life premiums justify cost.
- LiCoO2:Lithium cobalt oxide retains limited large-format relevance in aerospace and defense applications requiring maximum energy density regardless of cost or thermal risk.
LFP holds installed base dominance; NMC maintains technology leadership in energy density-critical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of prismatic cells yet domestic consumption strains capacity, while the United States and Germany compete for automotive-grade pack assembly investments. This production-consumption gap drives regional qualification timelines and tariff exposure for battery integrators.
China
CATL and BYD absorb domestic OEM demand for cell-to-pack architectures while MIIT GB standards extend approval timelines for foreign pack assemblers. The dual carbon goals accelerate NMPA certification requirements for grid-scale storage deployments. Shenzhen and Ningbo industrial clusters concentrate blade cell and prismatic output for both automotive and utility applications.
United States
ERCOT and CAISO utility procurement drives multi-gigawatt-hour LFP storage contracts independent of automotive demand cycles. NHTSA safety investigations and EPA zero-emission credit rules reshape pack design priorities for domestic EV platforms. Texas and California metropolitan markets anchor behind-the-meter and grid-scale installation growth.
Germany
Premium EV manufacturers adopt cell-to-pack structural designs for platform weight reduction and volumetric efficiency gains. EU Battery Regulation carbon footprint disclosure mandates accelerate qualification of European-based cell suppliers for automotive OEM programs. Bavaria and Baden-Württemberg host concentrated pack assembly operations serving German luxury drivetrain platforms.
South Korea
LG Energy Solution and Samsung SDI supply cylindrical and high-nickel NMC formulations for performance-oriented drivetrains and range-critical luxury segments. MFDS and national industrial policy support advanced chemistry cell R&D through targeted funding mechanisms. Seoul Capital Area and Busan-Ulsan clusters concentrate electrode coating and cell finishing capacity.
Japan
Panasonic sustains cylindrical cell supply relationships for premium performance EV programs while METI directs solid-state battery research investments. Domestic OEMs prioritize thermal runaway propagation thresholds and fast-charging capability in platform specifications. Kanto and Kansai industrial corridors maintain precision manufacturing expertise for automotive-grade cell assembly.
Large Capacity Lithium Battery Packs Sales Market Competitive Landscape
The competitive structure tilts toward vertically integrated cell producers with captive pack assembly capabilities. Six Chinese manufacturers control the majority of automotive-grade prismatic capacity, creating tiered supply access for European and North American integrators. Three archetypes dominate: integrated cell-to-pack specialists, dedicated cylindrical suppliers, and chemistry-agnostic trading houses. Capacity expansion and strategic qualification for regional regulatory compliance represent the dominant competitive moves.
Among integrated specialists, CATL, LG Energy Solution, and BYD exemplify the archetype of cell producers absorbing thermal management and BMS development costs previously outsourced to tier-1 suppliers. These entities occupy positions where platform-level contracts lock in five-to-seven-year volume commitments. Samsung SDI and Panasonic sit within the premium-tier vector, representing suppliers where high-nickel NMC formulations and cylindrical format reliability sustain positioning in luxury and performance segments.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic |
| Samsung SDI |
| BYD |
| Eastman |
| Sony |
| Hefei Guoxuan |
| Tianjin Lishen |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's carbon footprint disclosure mandate gates qualified supply access and premium-tier pricing for automotive OEM contracts. Pack assemblers without blockchain-enabled traceability systems face exclusion from European platform programs while certified suppliers command pricing premiums on validated low-carbon cell supply.
Pricing Analysis
Cost-down pressure on automotive-grade prismatic cells accelerates because six Chinese producers control over seventy percent of capacity and leverage integrated cell-to-pack architectures. Contract pricing stratifies across automotive platform tiers, with premium EV drivetrains absorbing high-nickel NMC premiums and standard-range platforms optimizing for LFP cost efficiency. Utility-scale storage buyers in Texas ERCOT and California CAISO markets exhibit highest price sensitivity, contracting on capital cost per kWh with minimal brand preference.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for cell import and pack assembly staging. Upstream supply draws from Chilean and Australian spodumene concentrate, Indonesian nickel ore processing, and Chinese cathode active material production. Single-source vulnerability concentrates in prismatic cell supply, with tariff exposure on Chinese-manufactured cells reshaping procurement strategies for North American and European integrators. Distribution runs through dedicated automotive logistics corridors and utility-scale project freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack structural battery designs are displacing modular architectures across premium EV platforms, compressing tier-1 module supplier revenue pools and shifting margin capture toward integrated cell producers.
For Market Incumbents: Hedge against silicon anode loading disruption by securing electrode coating equipment partnerships and qualifying dry electrode processes ahead of solvent-based line obsolescence. Absorb thermal management development costs previously outsourced to tier-1 suppliers through vertical integration into BMS firmware and pack-level thermal architecture. Defend platform-level contracts by accelerating GB standard certification timelines for Chinese market access. For New Entrants and Emerging Players: Capture second-life stationary storage deployment opportunities in Germany and Japan by establishing pack refurbishment operations and grid-interconnection firmware capabilities. Target India's PLI scheme production-linked incentives for advanced chemistry cell manufacturing, positioning for domestic two-wheeler and three-wheeler electrification demand. Lead with vehicle-to-home and vehicle-to-grid hardware convergence as differentiated revenue stream architecture. For Investors and Strategic Acquirers: European automotive OEM qualification of non-Chinese cell suppliers is the leading indicator that regional production capacity investments are reaching viable scale for platform-level contract capture. Frame long-term viability around five-to-ten year utility-scale storage offtake agreement visibility independent of automotive demand cyclicality. Monitor FERC interconnection rule acceleration and state storage mandate expansion as inflection signals for grid-scale deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Scale-Up | Eliminates module assembly tiers and captures thermal management margin previously held by tier-1 suppliers. |
| Silicon Anode Electrode Qualification | Boosts energy density without full solid-state transition costs for premium EV drivetrain platforms. |
| Blockchain Supply Chain Traceability Deployment | Satisfies EU Battery Regulation carbon disclosure mandates for European automotive OEM contract eligibility. |
| Second-Life Pack Refurbishment Operations | Redeploys retired automotive capacity into behind-the-meter commercial and industrial peak shaving applications. |
| Vehicle-to-Grid Hardware Integration | Creates new revenue streams through DC-AC inverter and grid-interconnection firmware embedding. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with OEM platform engineers, tier-1 pack assembler procurement leads, utility storage development officers, cathode material suppliers, and thermal management system designers. Bottom-up cell production capacity modeling triangulated against top-down automotive and energy storage demand projections derived from vehicle production databases, EIA storage installation records, and IEA technology deployment reports.
Granularity-level modeling operated at cell chemistry, format type, and end-use application dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by regional production cluster capacity expansion announcements and platform-level contract visibility. Forecast inputs incorporated lithium carbonate spot pricing volatility patterns, GB standard certification timeline distributions, and FERC interconnection queue processing rates.
The model holds under sustained electric vehicle platform electrification commitments and utility-scale storage procurement acceleration; deviation in nickel supply geopolitics, prismatic cell supply concentration shocks, or EU Battery Regulation enforcement intensity would shift trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Anode Material for Sodium-Ion Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market