
 Automotive Cylindrical Lithium Batteries Market | 2026-2036
Automotive Cylindrical Lithium Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cylindrical Lithium Batteries Market Insights
Electric vehicle platforms is expanding as the dominant demand channel for cylindrical lithium cells, displacing earlier power tool and consumer electronics offtake. Panasonic anchors Japan's cylindrical cell production through its Nevada and domestic facilities. LG Energy Solution competes through its Michigan and Polish manufacturing complexes. Samsung SDI differentiates via its specialized NCA chemistry leadership for premium automotive programs.
Automotive cylindrical lithium batteries are rechargeable electrochemical cells featuring a rolled electrode jellyroll architecture housed in a metal canister, typically with nickel-cobalt-manganese or lithium-iron-phosphate cathode formulations and graphite or silicon-blend anodes, engineered to deliver sustained discharge rates above 3C for traction applications. The 21700 and 4680 form factors are capturing structural attention as Tesla and other OEMs specify larger cells to reduce pack complexity and improve energy density at the module level. NMC technology leads current automotive nominations for its balanced energy density and cycle life, while LFP chemistry is gaining ground in standard-range vehicle segments where cost and thermal stability outweigh gravimetric performance targets.
The EU Battery Regulation, China's NMPA cell safety standards, and the US IRA domestic content provisions are collectively reshaping where cells qualify for vehicle integration and subsidy access. EVE Energy and BYD are navigating these requirements through dedicated European and North American supply base investments. Stakeholders must monitor how regional qualification rules interact with cathode material sourcing constraints.
Market Dynamics
Cell form factor migration from 21700 to 4680 architecture is compressing module counts and rewiring pack assembly economics across electric vehicle programs.
Growth Catalysts
- US IRA domestic content provisions:Battery cell qualification for federal tax credits now requires North American assembly and critical mineral sourcing, redirecting capital toward Michigan and Nevada manufacturing corridors.
- Silicon-blend anode chemistry:Higher theoretical capacity versus graphite is enabling 10-15% energy density gains in cylindrical formats without cathode changes.
- China's Jiangsu-Guangdong production belt:Concentrated cathode precursor and cell finishing capacity creates 48-hour supplier radius advantages for automotive OEM qualification programs.
Market Restraints
- Nickel sulfate price volatility:Class 1 nickel feedstock for NMC cathodes fluctuates with Indonesian ore export quotas and LME contract terms, squeezing cell margin structures.
- Single-source graphite dependence:Spherical purified anode material for high-rate cylindrical cells concentrates in China's Heilongjiang and Shandong provinces, creating geographic chokepoints.
- Thermal runaway propagation limits:Cell-to-cell failure containment in large-format cylindrical packs requires thicker interstitial barriers that reduce volumetric energy density.
Strategic Opportunities
- India's PLI scheme for ACC storage:50 GWh of allocated manufacturing capacity under production-linked incentives offers first-mover positioning for cylindrical cell entrants before local demand matures.
- Stationary energy storage repurposing:Automotive-grade cylindrical cells with 70-80% state-of-health retention are absorbing second-life demand from grid-scale battery projects seeking proven cycle data.
- EU Battery Regulation digital passport mandates:Cell-level traceability requirements create service revenue pools for compliance software and testing infrastructure providers.
Industry Challenges
- Electrolyte formulation talent scarcity:Formulators capable of optimizing lithium hexafluorophosphate salt concentrations for high-voltage NMC cylindrical cells command 40% wage premiums.
- UN 38.3 certification timeline compression:Updated lithium battery testing protocols for air transport are extending qualification cycles by 8-12 weeks for new cell variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cylindrical Lithium Batteries Market |
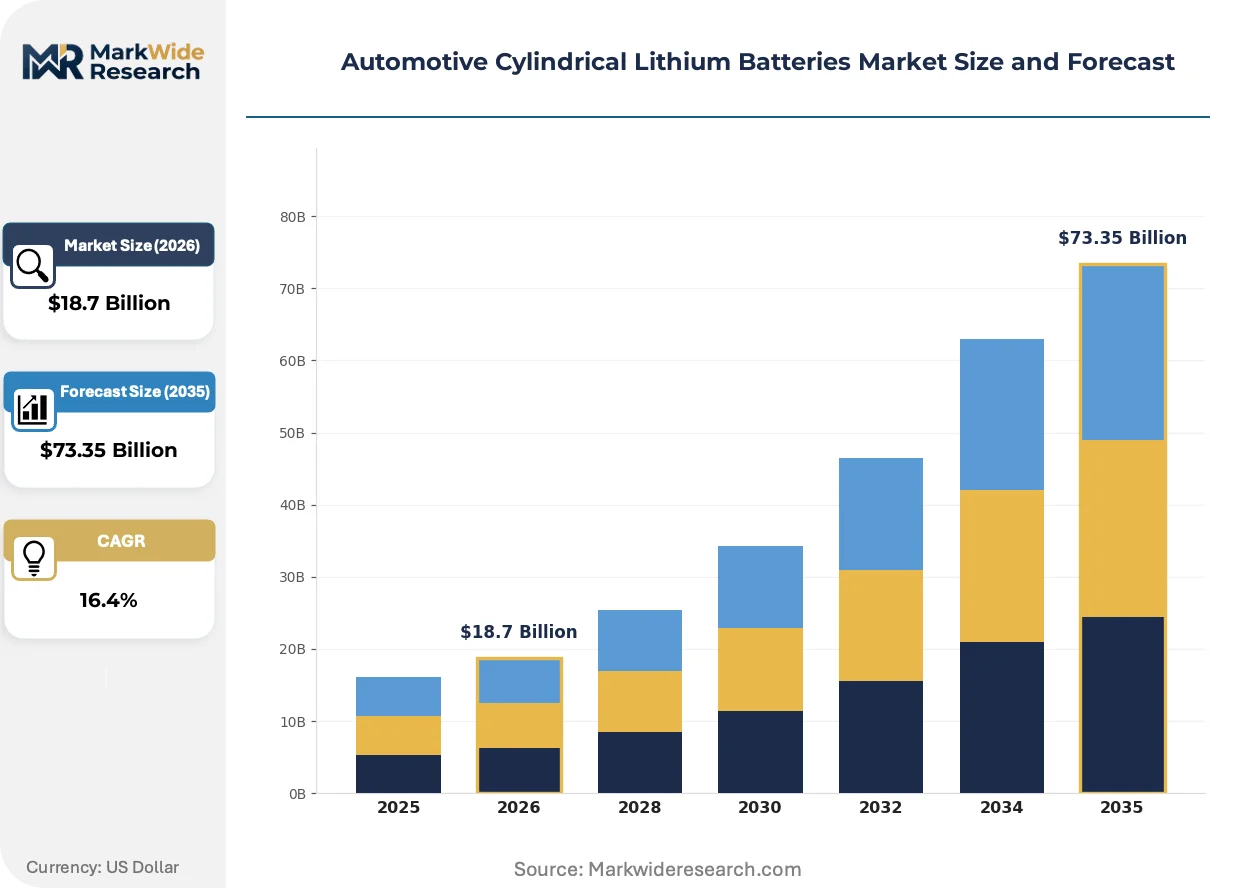
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 18650, 21700, 26650, 32400 End User: Electric Vehicles, Hybrid Vehicles, Power Tools, E-Bikes Technology: LFP, NMC, NCA, LTO Installation: In-Wheel, Underfloor, Trunk, Engine Compartment |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), Panasonic, LG Energy Solution, Samsung SDI, BYD, Sony, SK Innovation, Murata Manufacturing, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cylindrical Lithium Batteries Market Trends and Innovations
Manufacturing process intensification and chemistry convergence are collapsing the traditional trade-off between energy density and cycle life in automotive cylindrical cells.
Tabless electrode designs are eliminating conventional tab welding points that create current density hotspots and manufacturing yield losses. Tesla's dry electrode coating adoption is spreading to Korean and Chinese cell suppliers seeking comparable capex efficiency. The technology is absorbing winding equipment investment that previously served legacy jellyroll architectures.
EU Battery Regulation carbon footprint thresholds are mandating cell-level lifecycle declarations from 2027, with stricter limits applying to electric vehicle batteries placed on the European market. Manufacturers are responding by securing renewable power purchase agreements for electrode drying and formation cycling operations. Polish and Hungarian gigafactory locations are prioritizing grid decarbonization to maintain market access.
Fleet operators and energy service companies are consolidating procurement through long-term offtake agreements rather than spot market purchases, compressing supplier sales cycles and shifting margin capture toward volume guarantees. Direct OEM-cell maker contracts are displacing module integrator intermediaries in premium electric vehicle segments. This pattern is most visible in German and Scandinavian commercial vehicle electrification programs where total cost of ownership transparency drives sourcing centralization.
Automotive Cylindrical Lithium Batteries Market Segmentation
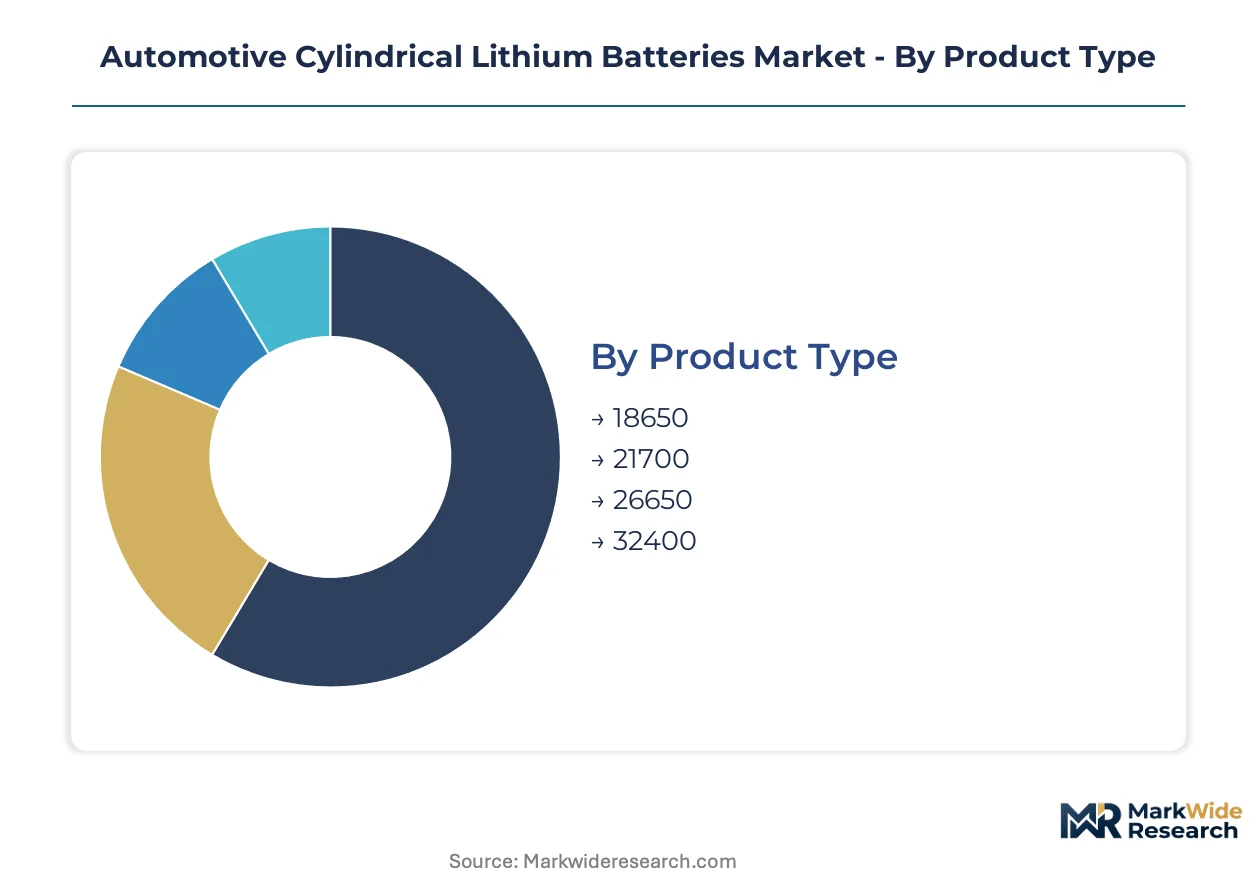
Automotive cylindrical lithium batteries fragment across four structural dimensions that determine procurement economics and qualification pathways. Form factor selection, end-use thermal profiles, cathode chemistry trade-offs, and vehicle integration constraints each create distinct supplier-customer matching requirements.
Product Type:
Cost tier separates buyers in this category, with premium electric vehicle programs specifying larger formats while cost-constrained applications retain legacy dimensions.
- 21700:These cells deliver 4.8Ah nominal capacity with nickel-cobalt-manganese cathodes optimized for sustained 3C discharge. Demand concentrates in Tesla's Nevada and Texas vehicle assembly facilities where pack-level energy density targets exceed 260 Wh/kg. Panasonic and LG Energy Solution dominate qualification programs for this format.
- 18650:The established 18mm diameter format carries 3.0-3.5Ah capacity with mature winding equipment depreciation already captured. Standard-range electric vehicle programs in China's Jiangsu manufacturing corridor specify this cell for cost-optimized module architectures where pack height constraints are secondary.
- 26650:Larger 26mm diameter cells serve heavy-duty hybrid commercial vehicles requiring 5Ah+ capacity per cell.
- 32400:Emerging large-format cylinders target electric bus underfloor packs seeking reduced cell count and simplified thermal management.
Volume sits with 21700; growth tilts toward 32400 as commercial vehicle electrification accelerates.
End User:
Application thermal intensity determines cell specification, with traction duty cycles imposing fundamentally different aging mechanisms than intermittent power tool discharge.
- Electric Vehicles:Full-electric platforms demand 1000+ cycle life at 80% depth-of-discharge with cell-to-cell voltage balancing across 4000+ unit packs. NMC chemistry leads nominations for premium sedans and SUVs where gravimetric energy density governs range certification. Tesla, BYD, and Volkswagen Group procurement teams specify cylindrical formats for structural battery pack integration.
- Hybrid Vehicles:Mild and full-hybrid architectures require 10C pulse discharge capability for regenerative braking absorption and torque assist. LTO chemistry penetration is highest here due to intrinsic rate capability and calendar life extending 15 years. Toyota and Honda qualification programs dominate offtake for this segment.
- E-Bikes:18650 and 21700 cells power European and North American electric bicycle fleets where 500Wh pack capacity satisfies 100km range requirements.
- Power Tools:Professional cordless equipment retains cylindrical preference for mechanical robustness and rapid swap compatibility.
Revenue concentrates in electric vehicles; margin expansion favors hybrid vehicle programs with specialized rate requirements.
Technology:
Customer type differentiates this category, with automotive OEMs prioritizing energy density while industrial buyers emphasize cycle life and safety margins.
- NMC:Nickel-manganese-cobalt layered oxide cathodes achieve 250-300 Wh/kg cell-level energy density with graphite-silicon blended anodes. Korean and Japanese cell suppliers anchor production for German and US premium electric vehicle programs where 800V architecture and fast-charging compatibility are mandatory. NMPA certification in China and UN 38.3 transport testing create qualification barriers for new entrants.
- LFP:Lithium iron phosphate chemistry trades 20% gravimetric density for thermal stability eliminating cobalt supply chain exposure. BYD Blade Battery architecture and Tesla's standard-range Model 3 specifications are expanding this chemistry's automotive share. Chinese cathode precursor capacity in Sichuan and Hubei provinces supports cost positioning.
- NCA:Nickel-cobalt-aluminum cathodes from Panasonic and Samsung SDI serve luxury electric vehicle segments where cell-level performance justifies material cost premiums.
- LTO:Lithium titanate anode chemistry delivers 10,000+ cycle life and -30°C cold-start capability for hybrid bus and grid storage second-life applications.
NMC commands current volume; LFP gains share fastest as cobalt price volatility and thermal safety standards tighten.
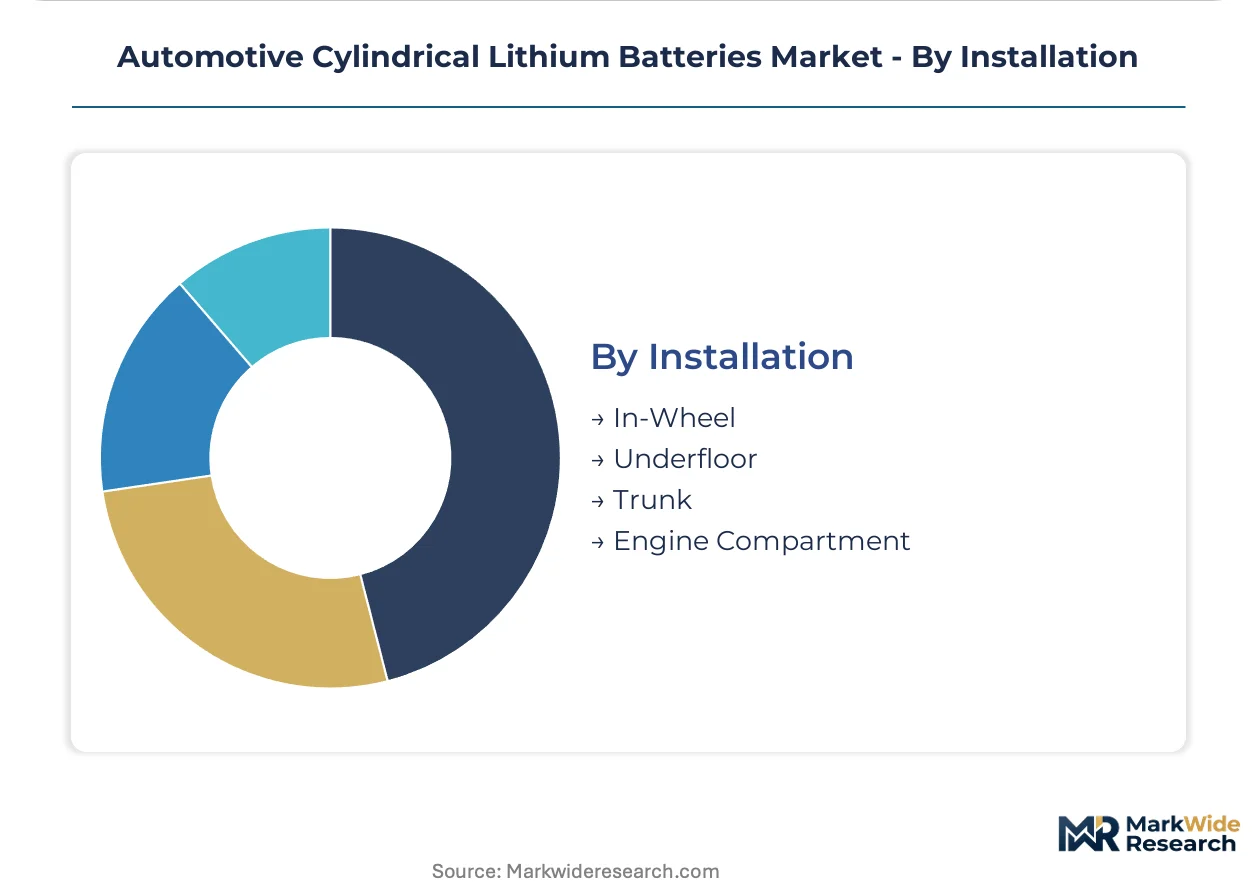
Installation:
Supply concentration shapes competitive dynamics, with underfloor pack architectures consolidating procurement through fewer module integrators than distributed in-wheel motor configurations.
- Underfloor:Flat skateboard architectures housing 60-100kWh packs between vehicle axles specify 21700 and 4680 cells in structural configurations where the pack enclosure replaces floor pan components. Tesla, Rivian, and Lucid Motors programs in California and Illinois assembly plants drive this segment's cylindrical cell absorption. Cell-to-pack designs eliminate module hardware, compressing cost per kWh.
- In-Wheel:Hub motor integrations demand 26650 and 32400 formats with reinforced casings resisting road debris impact and unsprung mass vibration. Chinese electric bus OEMs in Shenzhen and Chengdu specify this architecture for 12-meter transit vehicles.
- Trunk:Range-extender hybrid and conversion electric vehicle programs utilize cylindrical cells in removable or auxiliary pack configurations.
- Engine Compartment:Mild-hybrid 48V systems retain cylindrical formats for high-temperature tolerance adjacent to internal combustion powertrains.
Underfloor dominates absolute volume; in-wheel climbs the fastest as municipal transit electrification accelerates in China's tier-two cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in East Asian manufacturing corridors, while demand absorption tilts toward North American and European vehicle assembly centers. Regulatory qualification requirements are fragmenting supply chain geography as domestic content mandates reshape investment flows.
China
CATL and BYD procurement teams drive cylindrical cell absorption for domestic EV platforms, with NMPA battery safety certification tightening cell-level accountability standards. The Jiangsu-Guangdong production belt concentrates cathode precursor and cell finishing capacity within 48-hour supplier radii. Shenzhen and Ningbo anchor gigafactory construction for export-qualified production.
United States
Tesla's Nevada and Texas vehicle programs specify 21700 and 4680 formats for structural pack integration. IRA domestic content provisions redirect capital toward Michigan and Nevada manufacturing corridors to secure federal tax credit eligibility. Panasonic's Nevada facility anchors Japanese supplier presence in North American cylindrical cell production.
Germany
Volkswagen Group and BMW procurement centralization drives cylindrical format qualification for premium sedan and SUV platforms. EU Battery Regulation carbon footprint thresholds mandate renewable power purchase agreements for electrode drying operations. Polish and Hungarian gigafactory locations prioritize grid decarbonization to maintain European market access.
South Korea
LG Energy Solution and Samsung SDI compete through Michigan and Polish manufacturing complexes for automotive OEM nominations. MFDS chemical safety standards intersect with UN 38.3 transport testing to extend qualification timelines. Seoul-based R&D centers specialize in NCA chemistry leadership for premium vehicle programs.
Japan
Panasonic anchors domestic cylindrical cell production through joint venture structures with North American OEM partners. METI industrial policy supports silicon-blend anode development for next-generation energy density targets. Osaka and Kyoto manufacturing bases retain specialized winding equipment for high-rate cylindrical formats.
Automotive Cylindrical Lithium Batteries Market Competitive Landscape
Top-tier vendors anchor premium automotive qualification programs, while mid-scale specialists occupy regional supply niches. The vendor base stratifies across three tiers: integrated cathode-to-cell producers, pure-play cylindrical specialists, and module-integrators with captive cell sourcing. Korean and Japanese incumbents exemplify chemistry-differentiated positioning, while Chinese entrants leverage precursor supply chain proximity. Competitive moves concentrate on capacity expansion and strategic partnerships rather than M&A.
Within the integrated producer tier, Contemporary Amperex Technology Co., Limited and BYD occupy positions exemplifying vertical control from cathode precursor through cell finishing. Panasonic anchors Japanese cylindrical production through Nevada and domestic facilities. These three entities represent divergent geographic qualification strategies as regional content rules reshape market access.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| Panasonic |
| LG Energy Solution |
| Samsung SDI |
| BYD |
| Sony |
| SK Innovation |
| Murata Manufacturing |
| EVE Energy |
| Others |
Pricing and Supply Chain Analysis
Tesla's 4680 cell qualification requirements and Volkswagen Group's platform standardization mandates are compressing supplier margins and forcing tier-two cylindrical cell producers toward long-term offtake contracts or exit. This buyer-driven specification convergence concentrates procurement leverage with cell makers capable of NMC chemistry at scale and NMPA or EU Battery Regulation certification.
Pricing Analysis
Lead-time premiums of 15-20% apply to automotive OEMs requiring sub-90-day cell qualification for new vehicle programs, while spot inventory from overcapacity Chinese producers trades at discounts to contract benchmarks. Contract-based long-term offtake agreements dominate premium electric vehicle procurement, with price differentiation driven by cathode chemistry grade and UN 38.3 transport certification tier. Cost compression in standard-range LFP cells is intensifying because BYD and CATL are expanding Jiangsu corridor capacity ahead of demand absorption. Fleet operators and commercial vehicle OEMs exhibit highest price sensitivity, while luxury German OEMs prioritize energy density and thermal performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tesla, BYD, and Volkswagen Group, displacing module integrator intermediaries in premium segments. Geographic supply concentrates in China's Jiangsu and Guangdong provinces, South Korea's Seoul metropolitan area, and Japan's Osaka-Kyoto manufacturing belt. The supply chain draws from Indonesian nickel sulfate, Chinese spherical purified graphite from Heilongjiang, and Australian lithium hydroxide. Single-source graphite dependence from China's anode material producers creates geographic chokepoint vulnerability. Distribution runs through qualified supplier programs with 48-hour supplier radius requirements for automotive OEM qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cathode-to-cell integrated producers as IRA domestic content provisions and EU Battery Regulation carbon thresholds disqualify module-only assemblers and single-region suppliers from premium OEM nominations.
For Market Incumbents: Anticipate margin compression in 21700 commodity supply as Chinese LFP specialists expand European qualification programs. Defensive moves require securing North American electrode coating capacity for IRA tax credit eligibility and investing in dry electrode coating R&D to match Tesla's capex efficiency. Silicon-blend anode formulation talent acquisition represents a critical lever against Korean NCA chemistry leadership. For New Entrants and Emerging Players: Solid-state electrolyte prototyping for cylindrical formats offers a technology-first wedge into hybrid vehicle programs where Toyota and Honda seek 15-year calendar life. India's PLI scheme for ACC storage presents the most penetrable geography, with 50 GWh of allocated capacity and immature local demand. A go-to-market angle targeting municipal electric bus OEMs in China's tier-two cities with 32400 format specialization bypasses entrenched 21700 competition. For Investors and Strategic Acquirers: The window for entry favors cathode precursor producers with captive lithium supply and existing automotive qualification relationships. Long-term viability centers on vertical integration depth and regional manufacturing footprint diversification. The signal to watch is EU Battery Regulation digital passport compliance infrastructure buildout as a proxy for supplier qualification capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor | Secures nickel sulfate and lithium hydroxide supply for NMC cylindrical cell qualification under IRA domestic content rules. |
| Dry Electrode Coating Technology Adoption | Reduces electrode drying energy consumption and capex intensity to match Tesla's 4680 manufacturing economics. |
| EU Battery Regulation Digital Passport Infrastructure | Creates compliance service revenue and locks in automotive OEM relationships through traceability mandates. |
| Silicon-Blend Anode R&D Partnership | Enables 10-15% energy density gains without cathode chemistry changes for premium vehicle programs. |
| Polish or Hungarian Gigafactory Location | Positions production within EU Battery Regulation carbon footprint thresholds and Volkswagen Group supplier radius. |
Research Methodology
SEC 10-K filings, customs and trade data from China's General Administration of Customs, and IHS Markit vehicle production databases formed the secondary backbone. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, and cathode precursor plant managers combined with secondary validation through bottom-up cell shipment tracking and top-down electric vehicle production modeling. Triangulation across these sources established market sizing boundaries and growth trajectory confidence intervals.
Historical trendline analysis of cylindrical cell shipments by form factor and chemistry tracked capacity utilization and pricing dynamics across the projection horizon. The analytical framework modeled segmentation across vehicle class, propulsion architecture, cathode chemistry tier, and regional production cluster. CAGRs were derived from production ramp schedules of qualified gigafactory locations and OEM platform launch timelines. Forecast inputs included silicon-blend anode adoption curves and EU Battery Regulation compliance cost absorption assumptions.
Several conditions sit outside the modeled scope, including unannounced solid-state battery platform cancellations, Indonesian nickel export quota disruptions, and geopolitical trade barrier implementations. Forecasts reflect assumptions about cathode material cost trajectories and regulatory timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Automotive Lithium Based Battery Market