
 Electric Vehicle Traction Batteries Market | 2026-2036
Electric Vehicle Traction Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Traction Batteries Market Foresight
Chinese cell producers is realigning capacity toward prismatic and blade-format architectures. CATL leverages its integrated mining-to-cell pipeline to secure raw material access. LG Energy Solution anchors its position through joint ventures with established automakers across three continents. Samsung SDI competes on cylindrical cell precision for premium passenger vehicle programs.
Electric vehicle traction batteries store electrochemical energy at cell voltages typically spanning 3.2–4.3 V and deliver sustained discharge rates above 3C for acceleration events; their purpose is to power electric motors for propulsion while managing thermal stability across thousands of cycles. Lithium-ion chemistries currently dominate installed capacity, though solid-state architectures represent the fastest-growing technology segment as manufacturers resolve interfacial impedance barriers. Passenger vehicles absorb the majority of cell output, while commercial vehicles command higher per-unit margins due to larger pack sizes and durability requirements.
FDA oversight applies to battery systems in medical service vehicles, while EPA tailpipe rules and NHTSA safety standards shape passenger vehicle electrification timelines in the United States. The EU Green Deal and F-Gas Regulation constrain fluorinated coolant use in European thermal management systems, redirecting R&D toward dielectric fluid alternatives. Stakeholders must monitor how China's MIIT revises cell energy density thresholds and whether India's PLI scheme attracts cathode active material production to offset import dependence.
Market Dynamics
Cell chemistry convergence toward lithium iron phosphate and high-nickel ternary systems is compressing incumbent cobalt-dependent supply chains while reshaping raw material procurement priorities across the value chain.
Growth Catalysts
- EU Green Deal ICE phase-out mandates:Binding 2035 deadlines for combustion engine sales bans in member states are forcing automaker electrification roadmaps and locking in multi-year cell supply contracts.
- Commercial fleet electrification:Heavy-duty truck operators in North America and Europe are expanding depot-charging infrastructure and placing volume orders for megawatt-hour class battery systems.
- China's dual carbon policy framework:MIIT energy density thresholds and provincial new energy vehicle quotas are accelerating domestic OEM platform electrification and cell capacity localization.
Market Restraints
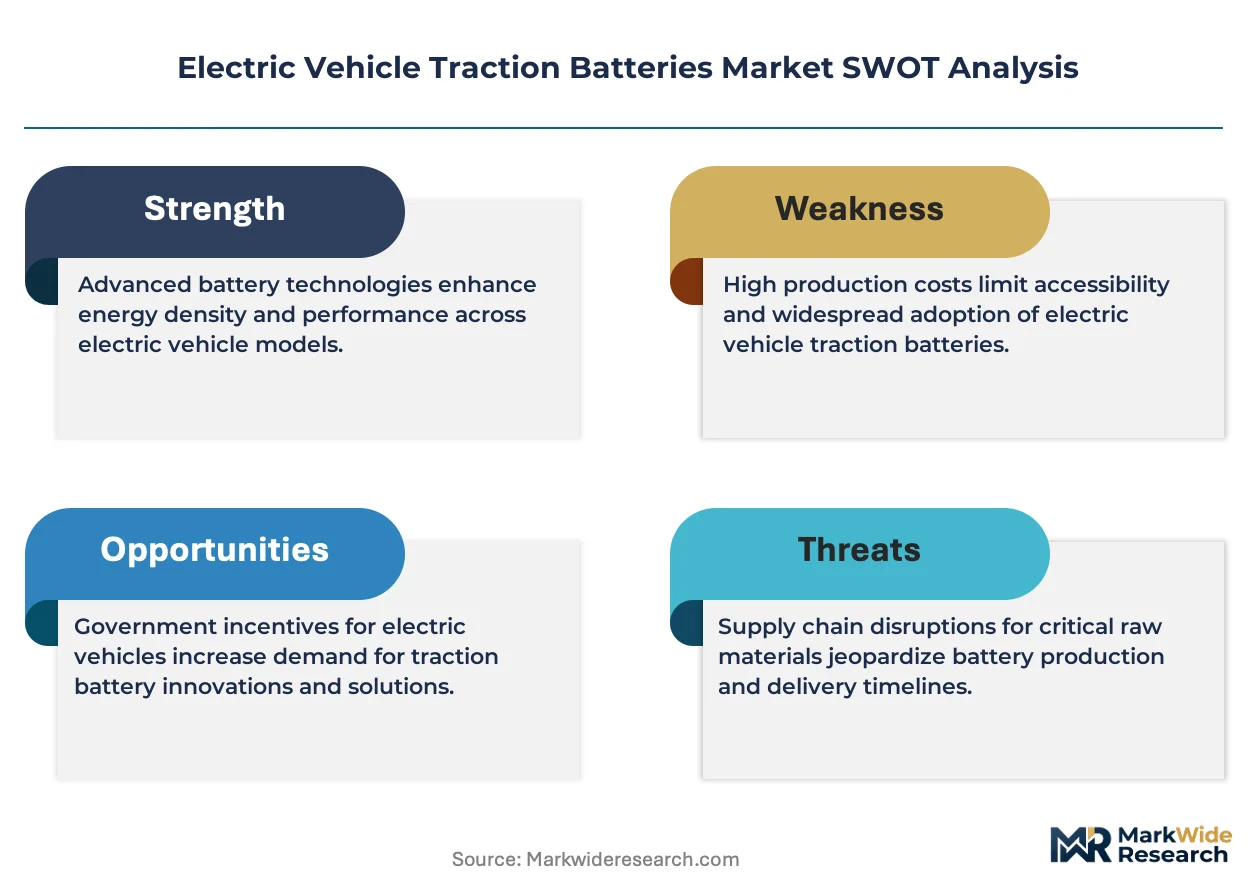
- Lithium carbonate price volatility:Concentrated South American and Australian spodumene supply exposes cell producers to input cost swings that compress gross margins during upstream tightness.
- Cathode active material geographic concentration:China's dominance in precursor chemical refining and powder processing creates single-source vulnerability for European and North American cell plants.
- Solid-state interfacial impedance barriers:Ceramic-electrolyte manufacturing defects and dendrite formation risks delay commercialization timelines for next-generation architectures.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for advanced chemistry cell manufacturing are attracting cathode material investments to offset import dependence on Chinese supply.
- Second-life stationary storage applications:Retired automotive packs are finding secondary deployment in grid-scale buffering systems, extending value extraction from initial cell production.
- Dielectric fluid thermal management:EU F-Gas Regulation constraints on fluorinated coolants are redirecting R&D toward immersion cooling technologies that eliminate synthetic refrigerant dependency.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design, formation protocol optimization, and solid-state interface engineering require specialized expertise that outpaces university program output.
- Gigafactory capital intensity:Dry electrode coating and continuous roll-to-roll assembly equipment demand multi-billion-dollar facility investments with extended depreciation horizons.
- UN 38.3 certification timelines:Transportation safety testing for new cell formats creates bottlenecks between pilot production and commercial shipment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Traction Batteries Market |
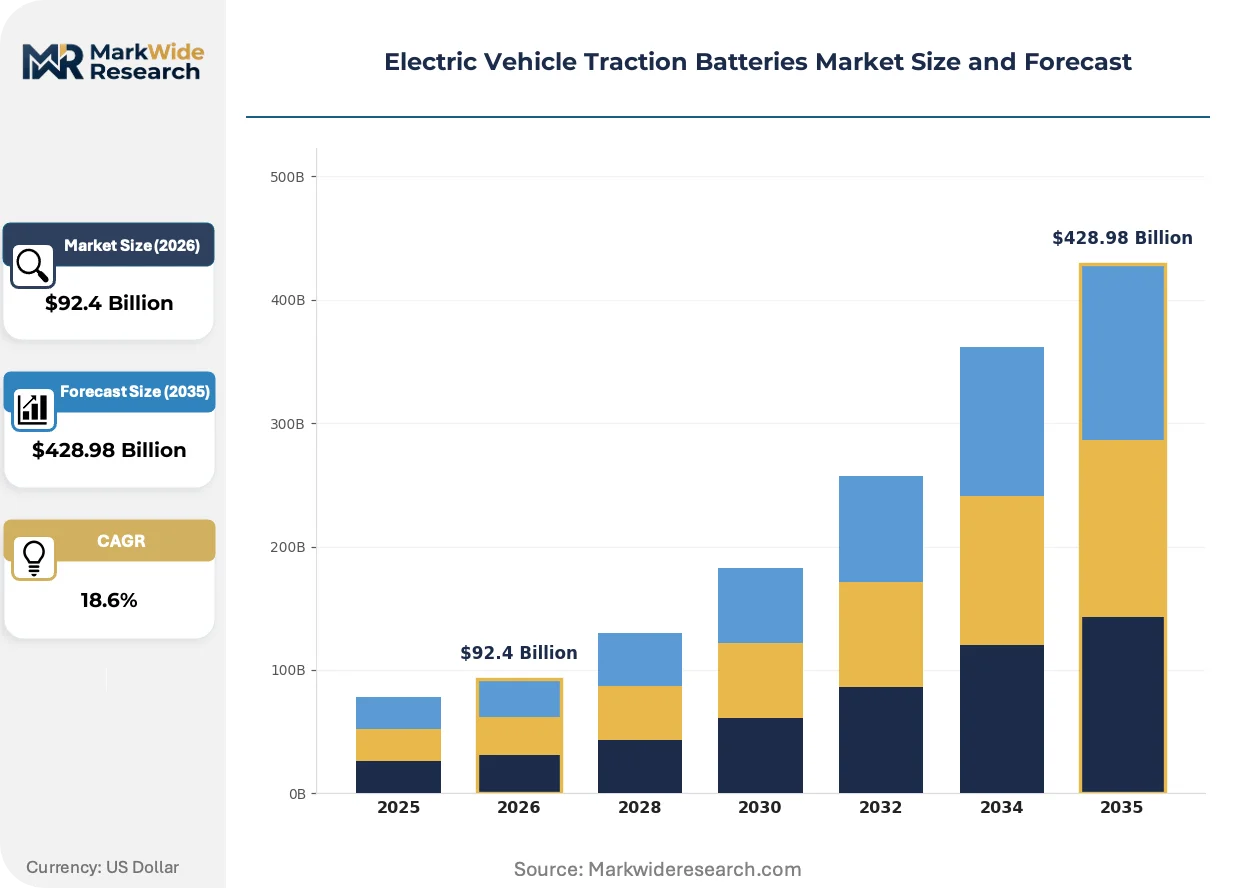
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $428.98 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Flow Battery End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: Fast Charging, Regenerative Braking, Battery Management System, Thermal Management Form Factor: Cylindrical, Prismatic, Pouch, Module |
| Companies Covered | CATL, LG Energy Solution, Panasonic Corporation, BYD, Samsung SDI, GS Yuasa, SK On, Gotion High-Tech, Envision AESC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Traction Batteries Market Shifts & Advancements
Silicon-anode formulations and cell-to-pack structural integration are compressing system-level cost curves while enabling energy density gains that extend vehicle range without proportional mass increases.
Silicon composite anodes with pre-lithiation treatments are electrifying next-generation cell architectures by replacing graphite-dominated negative electrodes. Premium passenger vehicle programs are adopting these materials despite initial cycle stability trade-offs. The technology is electrifying competitive positioning by enabling 300+ watt-hour per kilogram pack designs that close range gaps with combustion alternatives.
EPA tailpipe standards and NHTSA safety mandates are tightening concurrently, forcing OEMs to accelerate platform electrification timelines beyond initial commercial forecasts. The industrial consequence is compressed supplier qualification windows and locked-in chemistry commitments earlier in vehicle development cycles. Heavy-duty commercial segments face the steepest compliance cost escalations and are responding with dedicated cell form factors optimized for duty-cycle durability.
Fleet operators are consolidating procurement through direct long-term offtake agreements rather than tiered distributor networks. This channel disintermediation concentrates volume commitments with vertically integrated cell producers capable of decade-spanning supply security. North American commercial vehicle electrification programs exhibit the most pronounced shift, with logistics operators bypassing traditional automotive supplier hierarchies to secure dedicated production lines.
Electric Vehicle Traction Batteries Market Segmentation
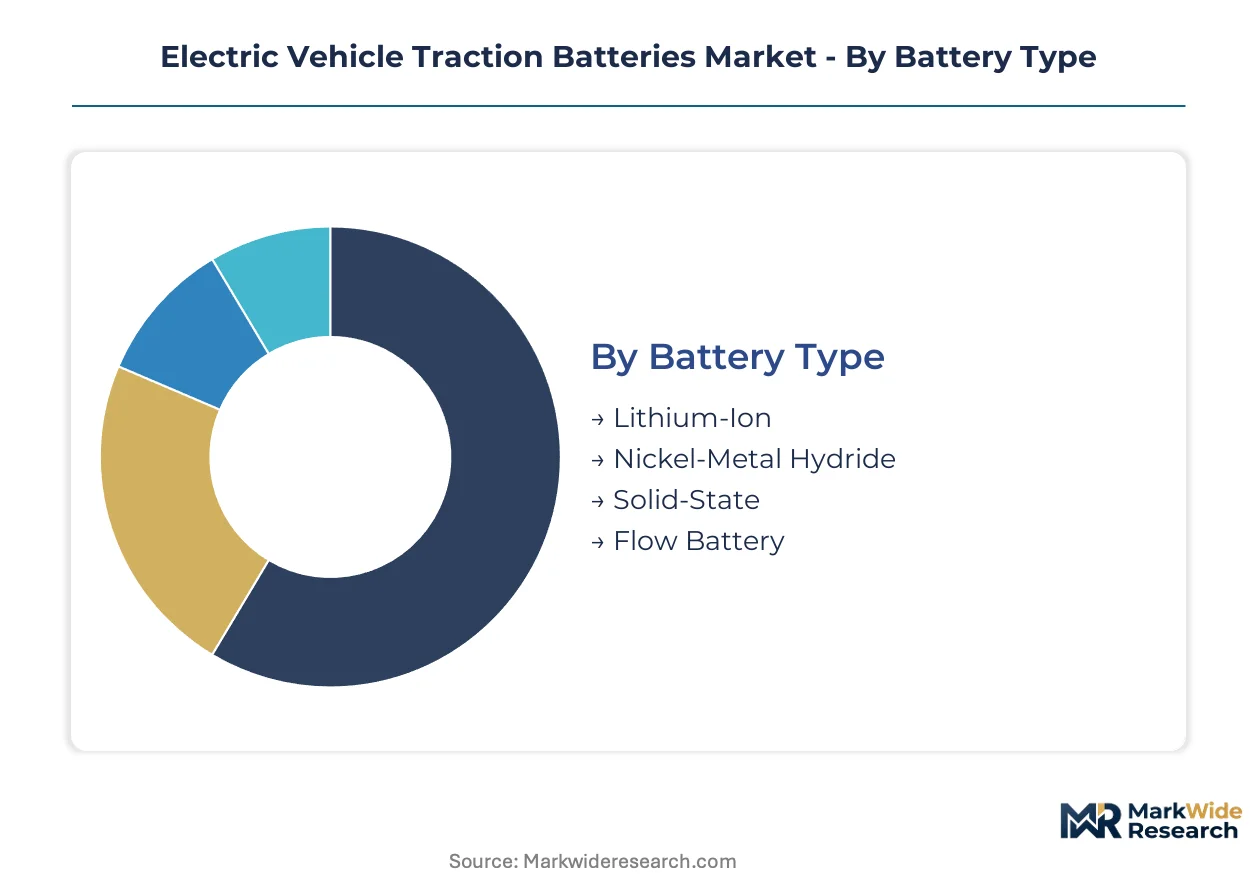
Segmentation in the electric vehicle traction batteries market reveals how buyer priorities diverge across vehicle platforms, thermal architectures, and cell geometries. Fleet operators prioritize cycle durability and depot-charging compatibility, while passenger OEMs optimize for energy density and pack integration efficiency.
Battery Type:
Purchase decisions in this category pivot on the trade-off between energy density, raw material cost exposure, and manufacturing maturity.
- Lithium-Ion:Dominates installed capacity through lithium iron phosphate and nickel-manganese-cobalt variants with proven formation protocols and established recycling pathways. Demand concentrates in China's Ningde and Shenzhen manufacturing corridors where CATL and BYD anchor gigafactory output; MIIT energy density thresholds are accelerating high-nickel ternary adoption despite cobalt supply chain vulnerabilities.
- Solid-State:Ceramic-electrolyte architectures promise 300+ Wh/kg pack designs with enhanced thermal stability and reduced dendrite formation risk. Toyota and Samsung SDI pilot lines in Japan and South Korea are resolving interfacial impedance barriers; the technology is expanding most quickly as OEMs lock in decade-spanning supply contracts for premium passenger platforms.
- Nickel-Metal Hydride:Mature chemistry with lower energy density but proven durability in hybrid electric vehicle applications; retains niche demand from Japanese OEMs with backward-integrated cell production.
- Flow Battery:Vanadium redox systems with decoupled power and energy scaling; finds limited traction in heavy-duty commercial depot charging buffers rather than onboard vehicle integration.
Volume sits with Lithium-Ion; growth tilts toward Solid-State.
End User:
Application-specific duty cycles dictate cell format, thermal management investment, and procurement channel structure.
- Passenger Vehicles:Absorbs majority of cell output through 60-100 kWh pack designs optimized for curb weight and cabin space constraints. Tesla's cylindrical 4680 format and CATL's blade-cell prismatic architecture compete for platform integration in Germany, China, and the United States; EPA tailpipe standards are compressing supplier qualification windows.
- Commercial Vehicles:Commands higher per-unit margins through megawatt-hour class systems with 3,000+ cycle durability requirements. Freight operators in California and the Netherlands are placing direct offtake agreements with cell producers, bypassing traditional automotive supplier hierarchies to secure dedicated production lines.
- Two-Wheelers:Compact 2-5 kWh packs with simplified thermal management; demand clusters in Indian and Southeast Asian urban mobility fleets where BIS certification and PLI scheme localization are reshaping procurement.
- Buses:Depot-charged heavy-duty platforms with roof-mounted or chassis-integrated pack configurations; municipal transit authorities in Shenzhen and Rotterdam specify cell-to-pack architectures for service-life cost optimization.
Procurement concentrates in Passenger Vehicles; margin expansion favors Commercial Vehicles.
Technology:
Performance differentiation increasingly depends on thermal stability and charge-rate engineering rather than raw cell chemistry alone.
- Fast Charging:350+ kW capable systems with advanced cooling loops and anode pre-lithiation to mitigate lithium plating; 800V architectures in Porsche and Hyundai platforms are driving dielectric fluid immersion development to replace fluorinated coolants constrained by EU F-Gas Regulation.
- Battery Management System:Cell-level voltage and temperature monitoring with predictive degradation algorithms; ASIL-D functional safety requirements are extending software validation timelines for European and North American OEM programs.
- Regenerative Braking:Bi-directional inverter integration capturing deceleration energy; standard across all electrified platforms with calibration varying by vehicle mass and duty cycle.
- Thermal Management:Active liquid cooling, phase-change materials, and emerging immersion designs; EU regulatory constraints on synthetic refrigerants are redirecting R&D toward engineered dielectric fluids.
Investment intensity peaks in Fast Charging; regulatory pressure is reshaping Thermal Management.
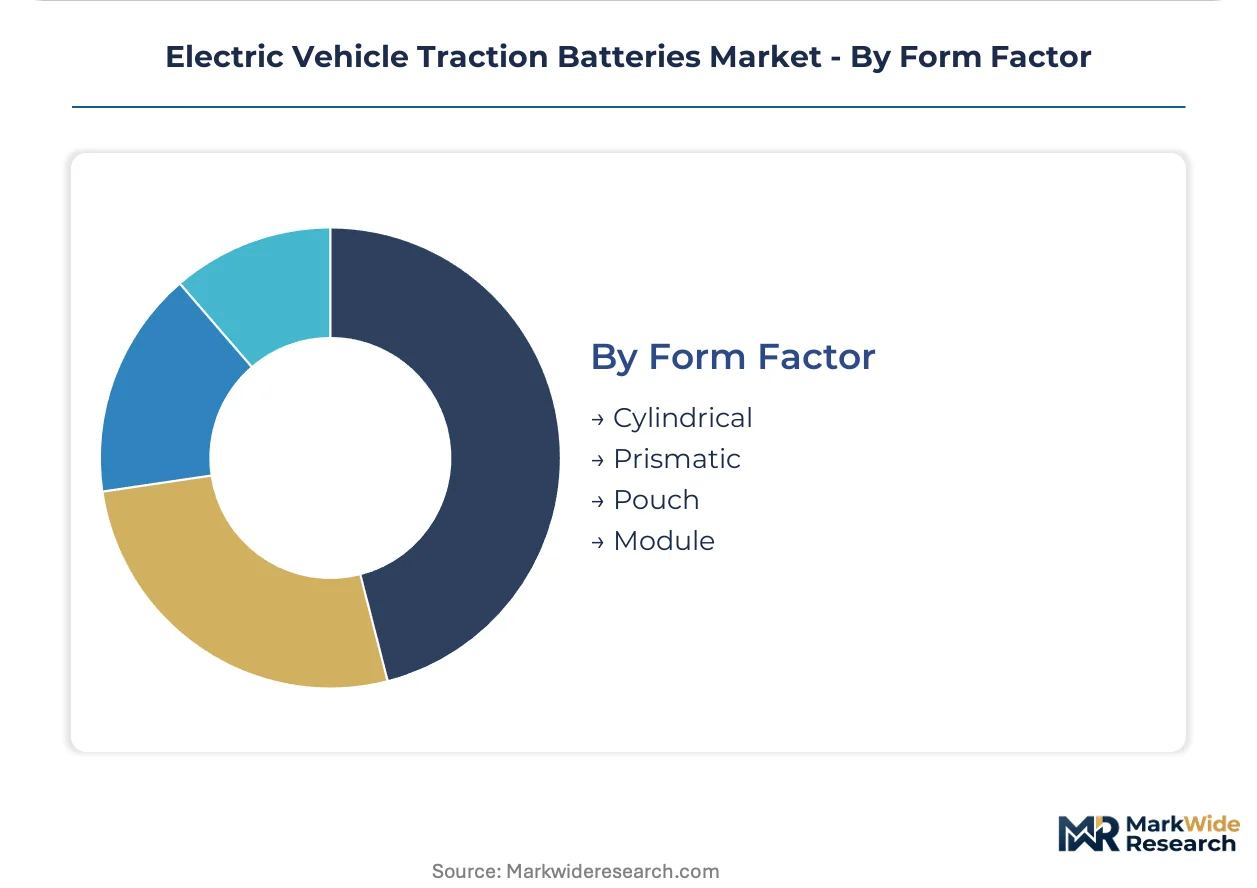
Form Factor:
Pack integration efficiency and manufacturing automation rates determine cost-positioning across cell geometries.
- Prismatic:Rectangular aluminum-cased cells with direct pack stacking and simplified module elimination; CATL's blade format and LG Energy Solution's joint venture output dominate Chinese and European OEM supply.
- Cylindrical:Steel-cased 2170 and 4680 formats with precision winding and high-speed assembly automation; Tesla's Nevada and Berlin facilities and Panasonic's Osaka lines anchor production for premium passenger programs.
- Pouch:Flexible polymer-laminated cells with high packaging efficiency but swelling management challenges; SK On and Samsung SDI supply Korean and European OEMs with cell-to-pack structural integration.
- Module:Intermediate assembly of cells into serviceable units; declining share as cell-to-pack and cell-to-chassis architectures eliminate intermediate tiers.
Production scale favors Prismatic; cylindrical precision retains premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean and Australian lithium deposits anchor raw-material supply chains feeding cell production clusters across three continents. Demand concentrates where automakers face binding electrification deadlines and where cathode refining capacity localizes.
China
Ningde and Shenzhen manufacturing corridors absorb the majority of global cell output through CATL and BYD gigafactory networks. MIIT energy density thresholds and provincial new energy vehicle quotas compress OEM platform development timelines. The Yangtze River Delta and Pearl River Delta clusters dominate prismatic and blade-format production, with cathode precursor refining concentrating in Hunan and Fujian provinces.
Germany
Stuttgart and Munich anchor European passenger vehicle electrification through premium OEM platform launches. The EU Green Deal's 2035 ICE phase-out mandate locks automakers into multi-year cell supply contracts with accelerated qualification windows. Thuringia and Lower Saxony host joint-venture cell plants supplying cylindrical and prismatic formats to domestic assembly lines.
United States
Michigan and Tennessee manufacturing corridors attract Korean and Japanese cell producers through IRA production incentives and domestic content requirements. EPA tailpipe standards and NHTSA safety mandates force platform electrification timelines beyond initial commercial forecasts. Nevada and Texas host cylindrical cell production for premium passenger programs with integrated cathode active material processing.
South Korea
Ulsan and Gwangju anchor cylindrical cell precision manufacturing for premium export markets. MFDS industrial standards and METI-aligned quality protocols shape formation protocol optimization for high-nickel ternary systems. The Seoul Capital Area concentrates battery management system software development with ASIL-D functional safety validation for European and North American OEM programs.
India
Tamil Nadu and Gujarat manufacturing corridors attract PLI scheme investments for advanced chemistry cell localization. BIS certification requirements and DGFT import tariff structures reshape procurement for two-wheeler and three-wheeler electrification programs. The Delhi-NCR cluster concentrates battery pack assembly for municipal bus electrification with depot-charging infrastructure deployment.
Electric Vehicle Traction Batteries Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state architectures and silicon-anode formulations. The vendor base concentrates around vertically integrated mining-to-cell pipelines and joint-venture structures with automakers across three continents. Three archetypes dominate: integrated raw-material controllers, joint-venture platform specialists, and precision cylindrical manufacturers. Competitive moves center on captive lithium supply agreements and multi-billion-dollar gigafactory capacity expansion with decade-spanning offtake commitments.
Within the integrated tier, CATL and BYD exemplify mining-to-cell pipeline control, while LG Energy Solution and Samsung SDI occupy joint-venture and precision-specialist positions respectively. These four anchors represent distinct geographic and technological positioning strategies—Chinese backward integration into raw materials, Korean partnership anchoring across Germany, the United States, and Poland, and Japanese-German precision manufacturing for premium cylindrical formats. The competitive dynamic pits capacity scale against chemistry specialization, with each archetype defending position through locked-in automaker supply relationships and regional regulatory alignment.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Corporation |
| BYD |
| Samsung SDI |
| GS Yuasa |
| SK On |
| Gotion High-Tech |
| Envision AESC |
| Others |
Supply & Pricing Matrix
The EU Green Deal's 2035 ICE phase-out mandate gates qualified supply access for European OEMs while compressing premium-tier pricing power among cell producers with certified low-carbon production pathways. Automakers lacking decade-spanning offtake contracts face exposure to spot-market lithium carbonate volatility that erodes pack-level margin stability.
Pricing Analysis
Warranty and service-bundling structures separate premium cell suppliers from commodity-tier competitors, with extended cycle-guarantee coverage and thermal-management system integration commanding 15-25% price premiums over bare cell transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with UN 38.3 transportation safety validation and ASIL-D functional safety compliance as primary price differentiation drivers. Pricing pressure stems from lithium carbonate spot-market volatility concentrated in South American and Australian spodumene supply corridors. Commercial vehicle fleet operators exhibit highest price sensitivity due to megawatt-hour class pack scales, while premium passenger OEMs prioritize energy density and thermal stability over unit cost.
Supply Chain Analysis
Warehouse-distribution layer configuration centers on regional distribution hubs in Rotterdam, Hamburg, and Singapore that buffer just-in-time cell delivery to European and Southeast Asian assembly plants. Raw material supply concentrates in Chile, Australia, and China for lithium extraction and cathode precursor refining, with cell production anchored in China's Yangtze River Delta, South Korea's Ulsan corridor, and Japan's Osaka industrial zone. The supply chain draws from concentrated spodumene and brine extraction that creates single-source vulnerability during upstream tightness. Distribution runs through direct long-term offtake agreements that disintermediate traditional automotive supplier hierarchies, particularly in North American commercial vehicle electrification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive lithium supply agreements and in-house cathode active material production determine cost-positioning survival. Players are pursuing upstream mining-to-cell pipeline control as the decisive competitive lever.
For Market Incumbents: To counter cobalt-dependent supply chain compression and high-nickel ternary chemistry convergence, CATL and LG Energy Solution should accelerate backward integration into Australian and Chilean lithium extraction assets while locking multi-year offtake agreements with European OEMs facing EU Green Deal deadlines. Capacity expansion in Thuringia and Lower Saxony strengthens joint-venture positioning against emerging solid-state entrants. For New Entrants and Emerging Players: Fleet operator direct procurement channels offer the most penetrable entry vector, bypassing entrenched Tier 1 automotive supplier relationships that incumbent cell producers dominate. Second-life stationary storage applications for retired automotive packs present white-space opportunity with lower certification barriers. A dielectric fluid thermal management specialization targets EU F-Gas Regulation compliance gaps that established players have not fully addressed. For Investors and Strategic Acquirers: Solid-state pilot line announcements from Toyota and Samsung SDI are the leading indicator that interfacial impedance barriers are approaching commercial resolution thresholds. Long-term viability across the projection horizon favors acquisition targets with silicon-anode formulation expertise and ceramic-electrolyte manufacturing capabilities. Watch for MIIT energy density threshold revisions that would disqualify incumbent lithium iron phosphate architectures from Chinese new energy vehicle subsidy eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Localization | India's PLI scheme attracts precursor refining investments to offset Chinese import dependence for domestic cell plants. |
| Solid-State Pilot Line Scale-Up | Toyota and Samsung SDI ceramic-electrolyte manufacturing advances resolve dendrite formation risks for premium passenger platforms. |
| Silicon-Anode Pre-Lithiation Deployment | 300+ Wh/kg pack designs from silicon composite anodes close range gaps with combustion alternatives in German luxury OEM programs. |
| Dielectric Fluid Immersion Cooling | EU F-Gas Regulation constraints redirect thermal management R&D toward engineered fluid alternatives for 800V fast-charging architectures. |
| Second-Life Stationary Storage Partnerships | Retired automotive packs extend value extraction through grid-scale buffering deployment with municipal transit authorities in Shenzhen and Rotterdam. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews across cell formation engineers, OEM platform electrification leads, cathode precursor procurement managers, and thermal management system designers. MIIT energy density threshold publications, EPA tailpipe standard dockets, and EU Green Deal implementation guidance provided policy-side validation. UN 38.3 transportation safety testing protocols and ASIL-D functional safety documentation supplied technical compliance benchmarks. Bottom-up cell production capacity tallies triangulated against top-down vehicle electrification forecasts across passenger, commercial, and two-wheeler segments.
Granularity-level modeling disaggregated volume and value outputs by battery type, end-user application, technology tier, and cell form factor across the analysis window. Vehicle class, propulsion architecture, and regional production cluster dimensions captured OEM platform-specific demand patterns. CAGRs derived from logistic curve penetration modeling calibrated to binding regulatory deadlines rather than extrapolated historical trends. Lithium carbonate price scenario inputs and solid-state commercialization timeline assumptions shaped sensitivity bounds.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, breakthrough solid-state manufacturing process discoveries, and abrupt subsidy scheme cancellations. Forecast outputs reflect documented assumptions around cathode chemistry adoption rates and charging infrastructure deployment velocities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Traction Battery Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Heating System Market