
 Li-Sulfur Battery Market | 2026-2036
Li-Sulfur Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Li-Sulfur Battery Market Insights
The gap between aerospace-grade performance tiers and commodity energy storage is recalibrating how manufacturers allocate cathode engineering resources. PolyPlus Battery Company leverages its aqueous lithium-sulfur chemistry to anchor premium defense and marine contracts where cycle life thresholds exceed commercial standards. Sion Power Corporation competes on solid-state architectures designed for electric aviation, while Zeta Energy LLC specializes in carbon nanotube cathode structures that differentiate its approach from conventional sulfur composite designs.
Li-sulfur batteries employ elemental sulfur cathodes paired with lithium metal anodes to achieve theoretical energy densities exceeding lithium-ion systems, with electrolyte formulations and polysulfide shuttle suppression representing critical manufacturing challenges. The technology serves applications demanding maximum gravimetric energy, including long-endurance drones, satellite power systems, and extended-range electric aircraft. Rechargeable configurations dominate current development pipelines, though non-rechargeable variants retain structural importance in mission-critical military deployments where single-use reliability outweighs cycling economics. Electric vehicles represent the fastest-growing application segment, yet military procurement channels command superior margin pools due to qualification barriers and performance guarantees.
FAA certification pathways for lithium-sulfur propulsion systems and EPA lifecycle assessment protocols for sulfur extraction are tightening entry requirements for non-domestic suppliers seeking US market access. The EU Green Deal's battery sustainability mandates, coupled with REACH chemical registration requirements for electrolyte components, are reshaping material sourcing obligations across European supply chains. Stakeholders must monitor which regulatory jurisdiction—aviation safety, chemical compliance, or end-of-life recycling—imposes the binding constraint on commercialization timelines.
Market Dynamics
The aerospace sector's gravimetric energy density requirements are compressing cathode engineering timelines, forcing sulfur composite manufacturers to choose between defense-grade cycle stability and aviation certification pathways.
Growth Catalysts
- Electric Aviation Mandates:Germany's aerospace clusters are piloting Li-sulfur propulsion for regional electric aircraft, with KBA certification frameworks accelerating airworthiness qualification timelines.
- Solid-State Electrolyte Maturation:Ceramic-polymer hybrid electrolytes are suppressing polysulfide shuttle effects below 0.1% capacity fade per cycle in laboratory conditions.
- REACH Compliance Arbitrage:EU Green Deal battery sustainability mandates are disqualifying cobalt-intensive chemistries from public procurement tenders, redirecting R&D toward sulfur-based alternatives.
Market Restraints
- Lithium Metal Anode Instability:Dendrite formation during high-rate cycling limits cell longevity to 200-300 cycles in commercial prototypes, far below aviation qualification thresholds.
- Elemental Sulfur Supply Concentration:Refining capacity clusters in the US Gulf Coast and Alberta tar sands operations, creating geographic vulnerability for European cathode manufacturers.
- Polysulfide Dissolution:Soluble intermediate species migrate to the anode, causing active material loss and electrolyte viscosity changes that degrade performance consistency.
Strategic Opportunities
- Marine Propulsion White Space:Norway's fjord electrification requirements and offshore vessel hybridization are creating demand for sulfur cathodes in salt-tolerant battery architectures.
- IRA Domestic Content Credits:US battery manufacturing tax incentives are attracting sulfur processing investments to bypass import dependency on Asian separator materials.
- Carbon Nanotube Cathode Convergence:Conductive scaffold integration with solid-state electrolytes is opening pathways for 500+ Wh/kg packaged cell configurations.
Industry Challenges
- FAA Certification Timeline Compression:Novel chemistry qualification for propulsion systems requires 3-5 year test campaigns with no grandfathering from lithium-ion precedent.
- Electrolyte Formulation Talent Scarcity:Polysulfide chemistry expertise concentrates in academic laboratories, with insufficient industrial-scale process engineers for gigafactory ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li-Sulfur Battery Market |
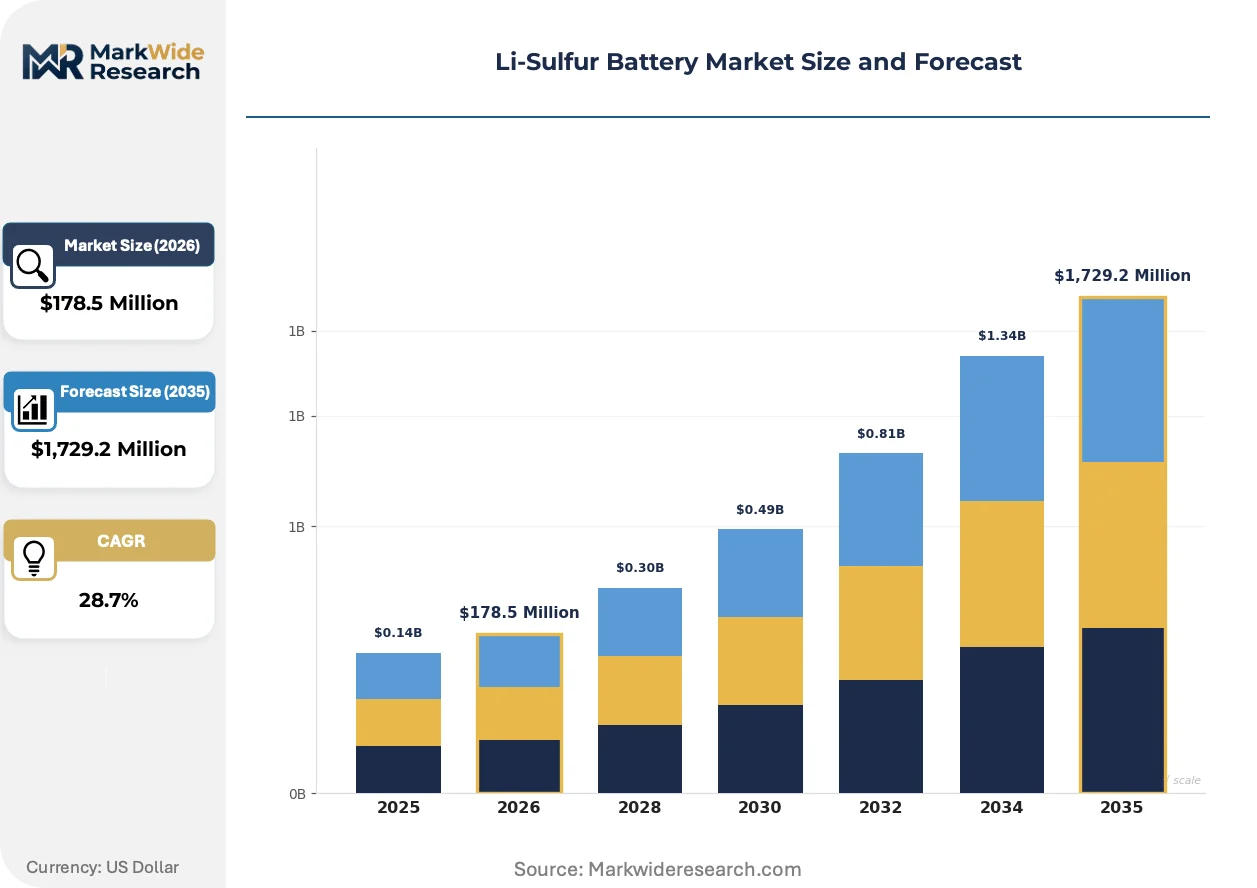
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $1,729.2 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Non-Rechargeable, Hybrid, Li-Sulfur Composite End User: Automotive, Aerospace, Consumer Electronics, Grid Storage Application: Electric Vehicles, Portable Devices, Renewable Energy Systems, Military Technology: Battery Management, Electrode Design, Membrane Technology, Energy Density Optimization |
| Companies Covered | PolyPlus Battery Company, NexTech Batteries, Lyten, Inc., Li-S Energy Limited, Zeta Energy LLC, Sion Power Corporation, Gelion PLC, GS Yuasa Corporation, Saft Groupe SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li-Sulfur Battery Market Trends and Innovations
Solid-state architectures are displacing liquid electrolyte designs across high-value applications, while regulatory jurisdictions compete to set the binding certification standard for aviation deployment.
Ceramic-polymer composite electrolytes are consolidating around lithium-phosphorus-sulfonamide chemistries that block polysulfide migration while maintaining ionic conductivity above 1 mS/cm. Electric aviation developers in Germany and the US are locking in multi-year supply agreements for pilot production lines. This electrolyte transition is consolidating competitive advantage around materials startups with in-house ceramic processing capabilities, marginalizing conventional separator suppliers.
REACH chemical registration requirements for electrolyte solvents and additives are forcing reformulation of polysulfide shuttle suppressants ahead of 2026 registration deadlines. European cathode manufacturers are pre-qualifying alternative ionic liquid additives to maintain market access. The regulatory pressure is compressing supplier qualification timelines, favoring integrated chemical producers with existing ECHA dossier expertise over specialty additive importers.
Defense procurement offices are unbundling battery acquisition from platform integration contracts, creating direct supplier relationships with cell manufacturers. This disintermediation bypasses traditional tier-one system integrators in satellite and unmanned aerial vehicle programs. The shift is most visible in US Department of Energy laboratory procurement and UK Ministry of Defence rapid capability insertion pathways.
Li-Sulfur Battery Market Segmentation
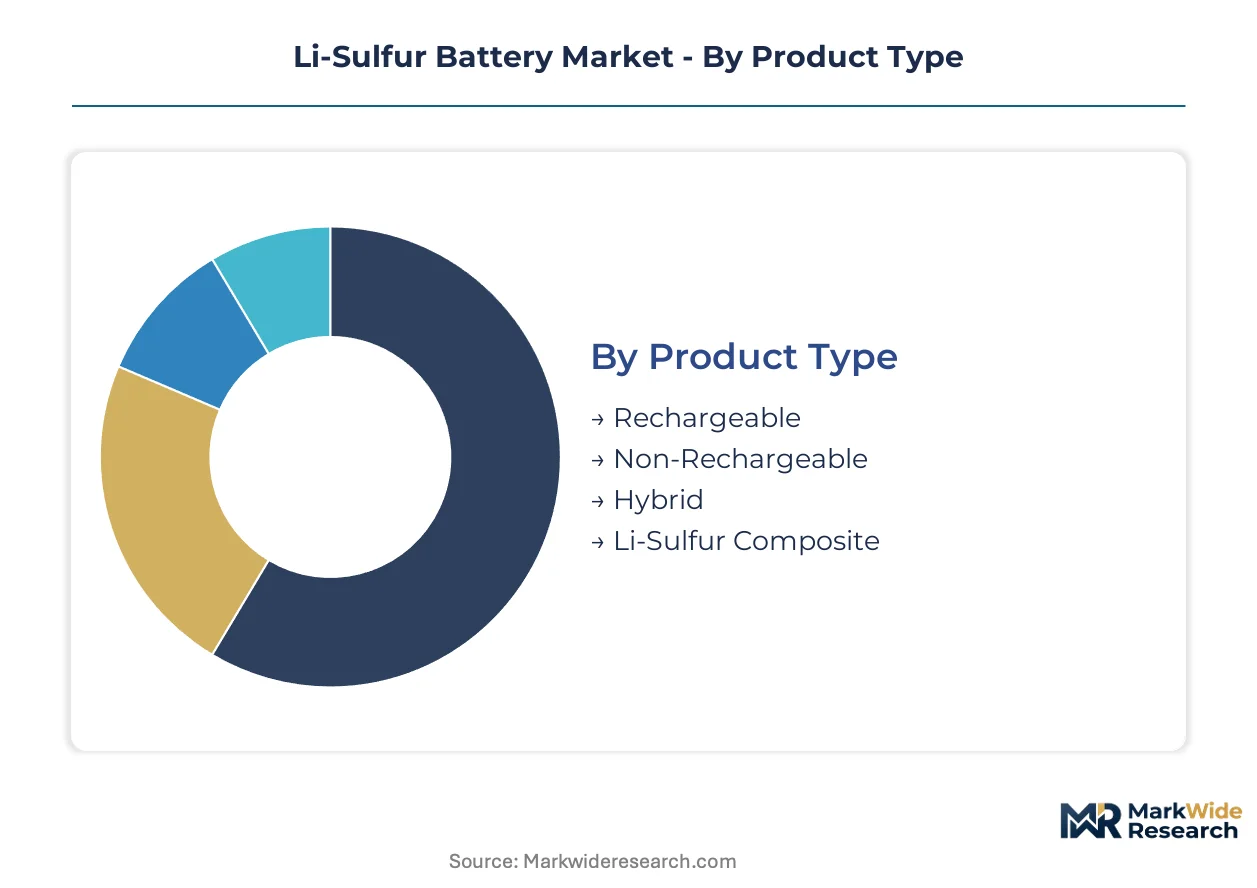
Li-sulfur battery segmentation reflects divergent technical maturity across product architectures and end-use qualification barriers. Each category reveals distinct competitive dynamics between defense-grade performance premiums and commercial volume economics.
Product Type:
Rechargeable configurations anchor current manufacturing investment, while non-rechargeable variants retain structural importance in single-use military applications where cycling economics are irrelevant.
- Rechargeable:Lithium metal anodes paired with sulfur cathodes enable cycling above 200 cycles in commercial prototypes. Demand concentrates in German aerospace clusters pursuing electric aviation certification under KBA frameworks, constrained by lithium dendrite formation thresholds.
- Non-Rechargeable:Primary cell architectures deliver single-use reliability exceeding rechargeable alternatives in mission-critical deployments. Procurement channels for US Department of Energy laboratory programs and UK Ministry of Defence rapid capability insertion pathways command superior margin pools due to qualification barriers.
- Hybrid:Dual-mode architectures combine primary and secondary electrochemistry for extended mission profiles.
- Li-Sulfur Composite:Advanced cathode formulations integrating conductive scaffolds with elemental sulfur active material.
Mature deployment sits with non-rechargeable military cells. Newer deployment is concentrated in rechargeable configurations for electric aviation.
End User:
Margin structures vary sharply between qualification-intensive aerospace procurement and volume-driven automotive contracts.
- Aerospace:Gravimetric energy density requirements exceeding 400 Wh/kg drive cathode engineering resource allocation. Germany's aerospace clusters pilot regional electric aircraft propulsion, with FAA certification pathways requiring 3-5 year test campaigns without lithium-ion grandfathering.
- Automotive:Electric vehicle integration demands cost parity with lithium-ion systems at scale. OEM pilot programs in Germany accelerate heavy-duty transport applications where weight sensitivity offsets cycle life limitations.
- Consumer Electronics:Portable power applications prioritize energy density over cycling endurance.
- Grid Storage:Stationary applications emphasize capital cost reduction over gravimetric performance.
Defense procurement offices are unbundling battery acquisition from platform integration, creating direct supplier relationships that bypass traditional tier-one system integrators.
Application:
Application segmentation tracks divergence between mobility platforms requiring packaged cell configurations and stationary systems tolerating larger form factors.
- Electric Vehicles:Heavy-duty transport electrification in Germany leverages Li-sulfur's weight advantages for extended-range commercial vehicles. IRA domestic content credits attract sulfur processing investments to bypass Asian separator material dependency.
- Military:Satellite power systems and long-endurance unmanned aerial vehicles demand maximum gravimetric energy. US and UK defense procurement channels prioritize single-use reliability in mission profiles where battery failure terminates operations.
- Portable Devices:Consumer electronics integration remains limited by cycle stability thresholds.
- Renewable Energy Systems:Stationary storage applications compete on capital cost against established lithium-ion infrastructure.
Electric vehicles are gaining share fastest among rechargeable applications, though military procurement retains structural margin premiums.
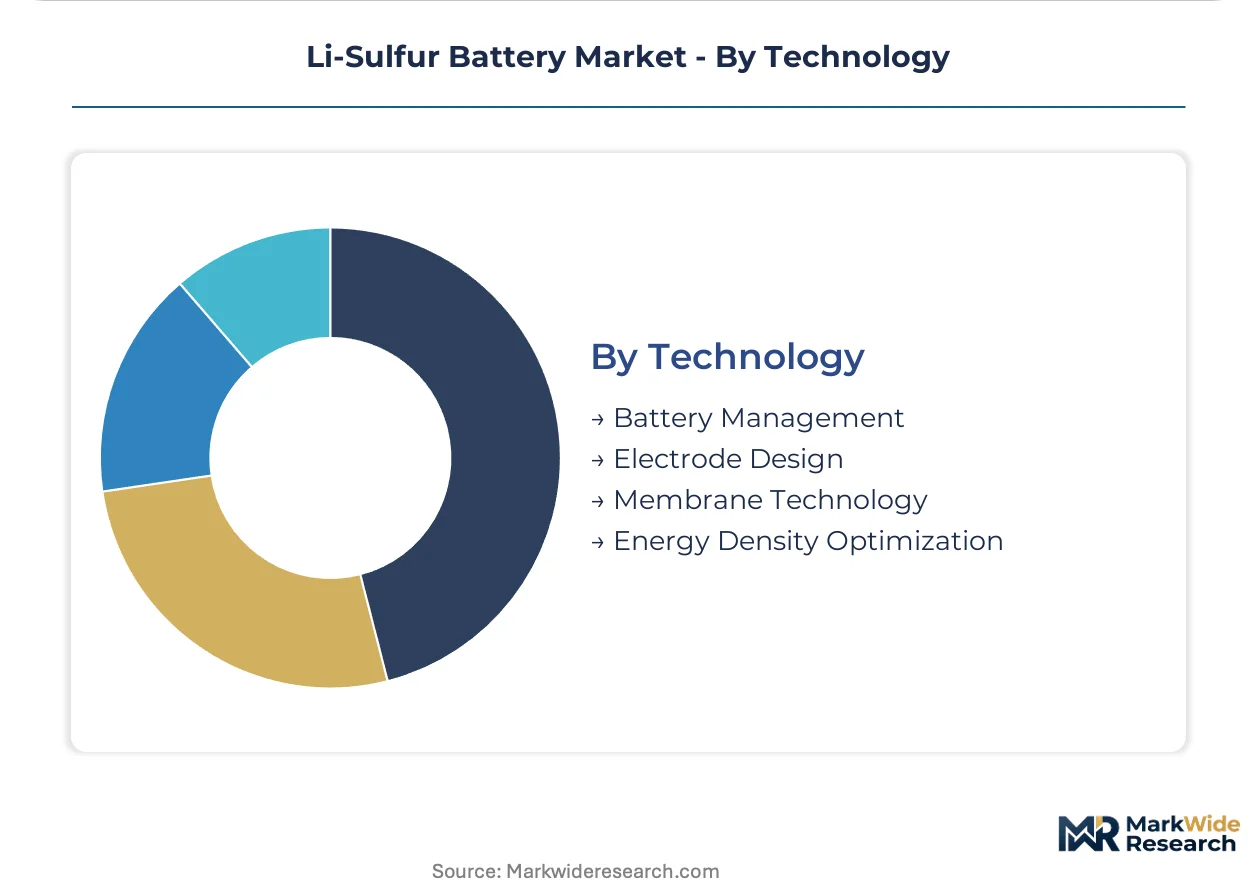
Technology:
Technology segmentation centers on electrolyte and electrode innovations that suppress polysulfide shuttle effects while maintaining ionic conductivity.
- Membrane Technology:Ceramic-polymer hybrid electrolytes block polysulfide migration below 0.1% capacity fade per cycle in laboratory conditions. European cathode manufacturers pre-qualify alternative ionic liquid additives to maintain REACH compliance ahead of 2026 registration deadlines.
- Electrode Design:Carbon nanotube cathode structures from specialized manufacturers differentiate conductive scaffold approaches from conventional sulfur composite designs. Solid-state electrolyte convergence with carbon nanotube scaffolds opens pathways for 500+ Wh/kg packaged cell configurations.
- Battery Management:Cell monitoring systems adapt lithium-ion algorithms for sulfur chemistry voltage profiles.
- Energy Density Optimization:Pack-level engineering balances gravimetric targets with thermal management requirements.
Membrane technology represents the most active patent filing category. Electrode design advances are concentrating in materials startups with in-house ceramic processing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich-Stuttgart aerospace corridors anchor Li-sulfur development activity, with German OEMs and Fraunhofer institutes accelerating electric aviation pilot programs. Regulatory momentum concentrates in jurisdictions with stringent aviation certification frameworks and cobalt-free procurement mandates.
Germany
KBA certification frameworks for electric aircraft propulsion compress qualification timelines for sulfur cathode manufacturers. EU Green Deal battery sustainability mandates disqualify cobalt-intensive chemistries from public tenders, redirecting automotive R&D toward sulfur alternatives. Stuttgart's aerospace clusters host pilot production lines for regional electric aircraft, with heavy-duty transport electrification scaling in North Rhine-Westphalia.
United States
IRA domestic content credits attract sulfur processing investments to bypass Asian separator material dependency. FAA certification pathways for novel propulsion systems require 3-5 year test campaigns without lithium-ion grandfathering, tightening entry requirements for non-domestic suppliers. Department of Energy laboratory procurement channels in California and New Mexico prioritize single-use reliability for satellite and unmanned aerial vehicle programs.
United Kingdom
Ministry of Defence rapid capability insertion pathways create direct supplier relationships with cell manufacturers, bypassing traditional tier-one system integrators. REACH chemical registration requirements for electrolyte components force reformulation of polysulfide shuttle suppressants ahead of 2026 deadlines. Oxford-Cambridge battery research corridors concentrate solid-state electrolyte development for defense-grade cycle stability thresholds.
Japan
METI funding for next-generation battery chemistries supports ceramic-polymer hybrid electrolyte maturation in Osaka-Nagoya industrial zones. JIS standards for aviation battery systems impose qualification barriers that favor domestic manufacturers with existing aerospace relationships. Tokyo-based materials startups consolidate competitive advantage around in-house ceramic processing capabilities.
South Korea
MFDS chemical safety assessments for electrolyte solvents compress supplier qualification timelines for European market access. Seoul Capital Area conglomerates leverage existing lithium-ion manufacturing infrastructure to pilot sulfur cathode integration. Busan-Ulsan ports facilitate sulfur refining feedstock imports from Alberta tar sands operations, mitigating geographic supply vulnerability.
Li-Sulfur Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Li-sulfur value chain. The vendor base separates between integrated chemical producers with ceramic processing capabilities and specialty additive developers dependent on external manufacturing. Three archetypes dominate: defense-focused contractors commanding qualification premiums, aviation-certification specialists locking in multi-year supply agreements, and materials startups bridging solid-state electrolyte convergence with carbon nanotube scaffolds. Competitive moves concentrate on strategic partnerships for electrolyte formulation expertise and backward integration into sulfur refining to bypass Gulf Coast supply concentration.
Within the defense-contractor archetype, PolyPlus Battery Company and Sion Power Corporation exemplify positioning around premium procurement channels where cycle life thresholds exceed commercial standards. Zeta Energy LLC occupies a specialist position among carbon nanotube cathode developers, differentiating from conventional sulfur composite approaches. These three represent the strategic segmentation between aqueous chemistry platforms, solid-state architectures, and conductive scaffold innovations that define current competitive boundaries.
| Leading Market Players |
|---|
| PolyPlus Battery Company |
| NexTech Batteries |
| Lyten, Inc. |
| Li-S Energy Limited |
| Zeta Energy LLC |
| Sion Power Corporation |
| Gelion PLC |
| GS Yuasa Corporation |
| Saft Groupe SA |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed research institutes and defense-funded battery developers anchor cathode engineering investments, compressing procurement timelines for sulfur composite manufacturers while insulating premium-tier pricing from commodity lithium-ion pressure. This ownership pattern concentrates supply negotiation leverage with German aerospace clusters and US Department of Energy laboratories, creating divergent pricing discipline across military qualification channels versus commercial pilot programs.
Pricing Analysis
Certification-grade pricing anchors cell valuation to airworthiness qualification outcomes rather than per-kWh commodity benchmarks. Three-tier pricing structure across defense-grade, aviation-certified, and commercial-prototype tiers separates procurement channels by cycle life thresholds and regulatory dossier completeness. Cost compression in commercial prototypes intensifies as automotive OEMs benchmark against lithium-ion parity, while military buyers exhibit minimal price sensitivity due to mission-critical reliability requirements. Volume scale offers limited discount leverage in defense procurement, where single-source qualification locks in multi-year offtake premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from electric aviation developers, while specialty chemical distributors serve research-scale cathode manufacturers. Elemental sulfur refining concentrates in US Gulf Coast operations and Alberta tar sands processing, with ceramic-polymer separator materials drawing from Japanese and South Korean manufacturing bases. Single-source vulnerability runs through lithium metal foil supply tethered to Chinese and Australian primary production. Distribution runs through qualified supplier programs that bypass traditional tier-one system integrators in defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyte formulation talent scarcity props pricing for qualified cell manufacturers, constraining gigafactory ramp timelines and sustaining margin premiums for incumbent producers with captive process engineering capabilities.
For Market Incumbents: Anchor defense procurement relationships through backward integration into sulfur refining and ceramic electrolyte processing, countering emerging solid-state specialists from Japan and Germany. Prioritize FAA certification investment ahead of lithium-ion grandfathering exclusions, while expanding capacity in North Rhine-Westphalia to capture EU Green Deal cobalt-free procurement mandates. For New Entrants and Emerging Players: Launch via direct supplier relationships with UK Ministry of Defence rapid capability insertion pathways, bypassing traditional system integrator channels. Target marine propulsion electrification in Norway as the most penetrable segment, exploiting salt-tolerant architecture requirements that lithium-ion struggles to satisfy. Lead with carbon nanotube cathode differentiation to secure pilot production agreements with German aerospace clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor materials startups with in-house ceramic processing capabilities in Japan and Germany, where METI and Fraunhofer funding gaps create acquisition windows. Long-term viability hinges on solid-state electrolyte convergence with aviation certification timelines. Watch FAA test campaign completion rates as the inflection signal for commercial volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Polymer Electrolyte Scale-Up | In-house processing capabilities consolidate competitive advantage around polysulfide suppression thresholds required for KBA certification. |
| Defense Procurement Direct Relationships | Unbundled battery acquisition from platform integration contracts bypasses tier-one system integrators in satellite programs. |
| EU REACH Pre-Registration | ECHA dossier expertise for ionic liquid additives secures market access ahead of 2026 solvent registration deadlines. |
| IRA Domestic Content Compliance | Sulfur processing investments in US Gulf Coast operations capture tax credits while reducing Asian separator dependency. |
| Aviation Certification Partnership | Multi-year supply agreements with German electric aircraft developers lock in cathode engineering resource allocation. |
Research Methodology
Multi-period observation of FAA certification pipeline progress, EU Green Deal procurement tender awards, and solid-state electrolyte patent filings anchored the trend analysis, supplemented by interviews with cell engineering directors, defense procurement officers, and ceramic materials specialists. Primary fieldwork triangulated against ECHA registration databases, KBA airworthiness bulletins, and METI funding disclosure records. Bottom-up cell manufacturer capacity assessments converged with top-down aerospace electrification spend projections.
Input-output matrices mapped sulfur cathode production volumes against electric aviation airframe development schedules across the analysis window. Segmentation dimensions modeled include product architecture, end-use qualification tier, electrolyte technology pathway, and regional regulatory cluster. CAGRs derived from unit economics trajectories for defense-grade versus commercial-prototype configurations, with cycle life improvement curves and certification timeline compression as battery-specific forecast inputs.
Regulatory deadline slippage, lithium metal anode failure rate volatility, and solid-state electrolyte conductivity breakthroughs are the dominant revision risks for commercialization timelines. Forecasts embed assumptions regarding REACH compliance cost pass-through and IRA domestic content threshold interpretations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market