
 Global Next Generation Batteries Market | 2026-2036
Global Next Generation Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Batteries Market Intelligence
Electrolyte engineering talent scarcity is redrawing competitive boundaries across the industry. CATL leverages its integrated cathode supply chain to dominate mass manufacturing of lithium-ion successors. Solid Power anchors its position through partnerships with established automotive OEMs. Samsung SDI specializes in thin-film deposition techniques that yield higher energy density per unit volume.
Next generation batteries encompass electrochemical storage systems exceeding the energy density, cycle life, or safety thresholds of conventional lithium-ion cells, typically achieving over 300 Wh/kg through solid-state electrolytes, silicon composite anodes, or lithium-metal architectures. These systems serve applications where weight reduction, fire suppression, or rapid charging represents critical operational constraints. Solid-state battery type configurations command premium positioning due to manufacturing complexity and unresolved scaling economics. Silicon anode technology segments attract concentrated R&D investment as intermediate step improvements before full solid-state transition. Electric vehicle application categories generate the dominant share of offtake volume, though grid storage contracts offer longer contract tenures.
FDA device safety standards, EPA hazardous material transport rules, and EU REACH chemical registration requirements collectively elevate compliance costs for electrolyte formulations and cell assembly processes. China's GB standards and NMPA certification protocols create parallel conformity pathways for market access across Asia-Pacific manufacturing hubs. Stakeholders must monitor regulatory divergence between jurisdictions as chemistry-specific rules crystallize.
Market Dynamics
Solid-state electrolyte manufacturing complexity is compressing viable production to a handful of integrated chemical conglomerates with thin-film deposition expertise, fundamentally restructuring competitive entry barriers around capital intensity rather than cell design innovation.
Growth Catalysts
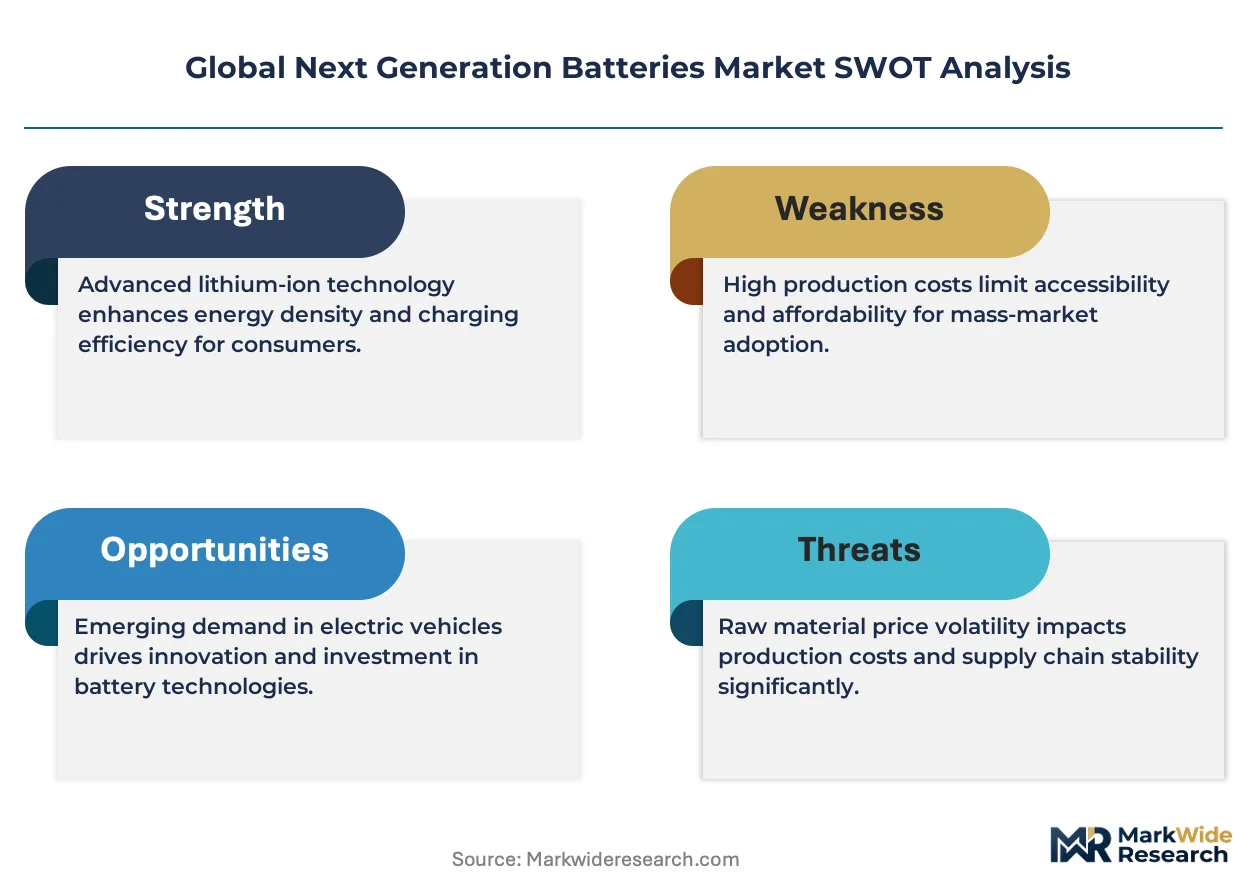
- EU Green Deal battery mandates:European automotive OEMs face binding electrification targets that accelerate qualification timelines for lithium-metal architectures. Cell suppliers with certified solid-state pilot lines secure multi-year offtake agreements.
- Silicon anode supply chain maturation:German chemical producers now deliver metallurgical-grade silicon at battery-grade purity, enabling 400 Wh/kg cell prototypes without full solid-state transition costs.
- Aviation weight constraints:FAA certification pathways for electric propulsion systems prioritize energy density above 350 Wh/kg, directing R&D investment toward lithium-sulfur and solid-state chemistries for regional aircraft applications.
Market Restraints
- Lithium carbonate price volatility:South American brine extraction concentration exposes cell manufacturers to 40-60% input cost swings that erode margin visibility on long-dated supply contracts.
- Solid-state ceramic separator brittleness:Current oxide and sulfide electrolyte formulations require precision sintering equipment unavailable outside Japanese and Korean capital goods suppliers.
- EPA hazardous material transport rules:Lithium-metal anode classification as Class 4.3 dangerous goods restricts air freight options for prototype cells, extending qualification cycles for North American automotive programs.
Strategic Opportunities
- India PLI scheme for ACC batteries:Production-linked incentives covering 50 GWh of advanced chemistry cell capacity create first-mover advantages for solid-state technology licensors establishing local joint ventures.
- Maritime propulsion electrification:International Maritime Organization emission targets for coastal vessels generate demand for 500+ kWh battery systems with fire-suppression requirements that favor solid-state architectures.
- Second-life grid storage:Retired EV silicon-anode cells retain 70-80% capacity, enabling arbitrage-focused developers to deploy degraded automotive packs into 4-hour grid storage without new cell procurement.
Industry Challenges
- Dry electrode coating technician scarcity:Solvent-free electrode manufacturing requires process engineers with thin-film semiconductor backgrounds, a talent pool concentrated in Korean display panel and Japanese electronics industries.
- UN 38.3 certification timeline compression:Transportation safety testing for new chemistries now requires 18-24 months, forcing cell developers to parallel-track automotive qualification with regulatory submission rather than sequencing them.
- Patent thicket navigation:Oxide electrolyte composition patents held by Japanese university spinouts create licensing complexity for European and North American solid-state entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Batteries Market |
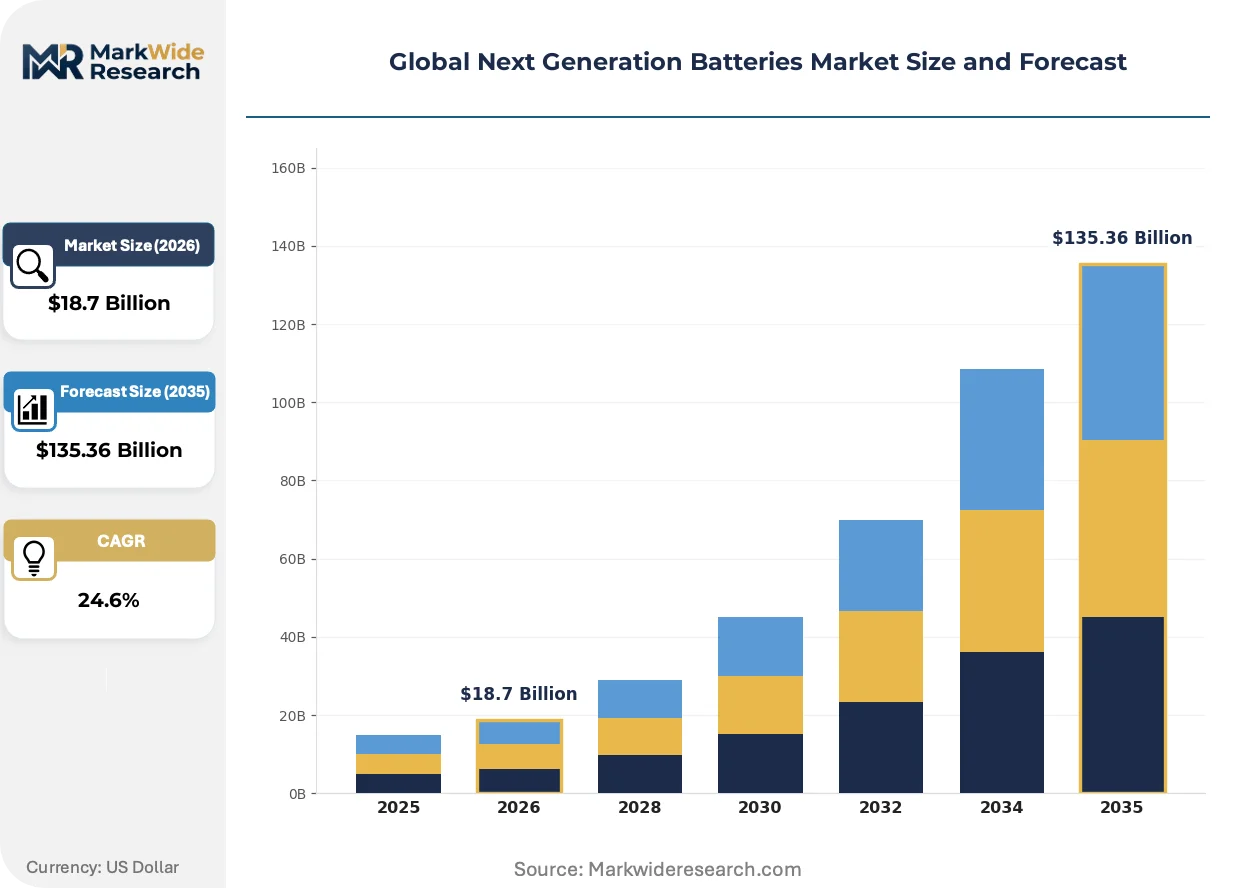
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Solid-State, Flow, Zinc-Air, Sodium-Ion, Lithium-Sulfur Technology: Cobalt-Free, Silicon Anode, Graphene-Enhanced, Polymer Electrolyte, Thin-Film, Metal-Air Application: Electric Vehicles, Consumer Electronics, Aerospace, Grid Storage, Marine, Wearables End User: Vehicle Manufacturers, Electronics Makers, Utilities, Defense Contractors, Marine Operators, Tech Developers |
| Companies Covered | BYD, SK On, CATL, Solid Power, QuantumScape, LG Energy Solution, Samsung SDI, Amprius Technologies, Panasonic Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Batteries Market Strategic Shifts & Innovations
Electrochemical storage architectures are bifurcating between evolutionary silicon-anode improvements and revolutionary solid-state platforms, with capital allocation increasingly favoring technologies that preserve existing manufacturing equipment.
Sulfide-based solid electrolytes are supplanting conventional liquid electrolytes in premium automotive programs. BMW and Toyota have accelerated their 2027-2028 production targets for sulfide cells, drawn by the 20-minute fast-charge capability. This chemistry is supplanting polymer-gel intermediates that dominated the 2020-2024 technology roadmap, collapsing the expected transition timeline by three to four years.
China's GB standards for battery safety testing now mandate nail penetration and overcharge abuse protocols that exceed UN 38.3 baseline requirements. MIIT certification timelines have extended by six months for foreign cell suppliers, advantaging domestic manufacturers with established testing relationships. European and Korean exporters are responding by pre-qualifying cells through NMPA-recognized laboratories in Shanghai and Shenzhen.
Fleet operators now specify residual value guarantees rather than upfront cell purchase in heavy-duty electric truck procurement. Leasing structures spread technology risk across battery-as-a-service providers, compressing the effective decision cycle from 36-month qualification to 12-month pilot programs. This restructuring is most visible in California and Germany, where CARB and KBA emission regulations accelerate fleet turnover timelines.
Global Next Generation Batteries Market Segmentation
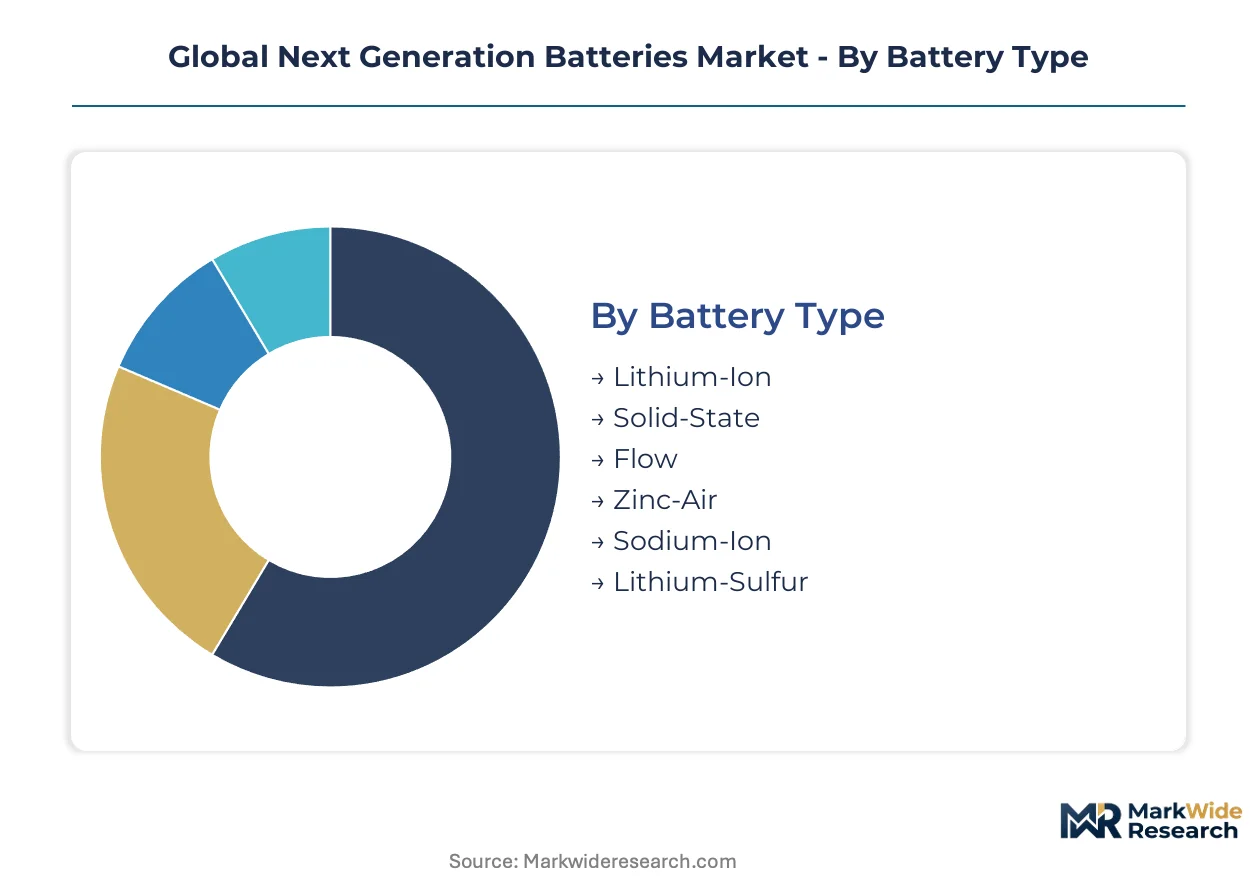
Next generation battery architectures diverge sharply across electrochemical systems, with each segment carrying distinct regulatory footprints and capital requirements. Cell chemistry selection directly determines which safety certifications apply, from UN 38.3 transport classifications to jurisdiction-specific assembly permits.
Battery Type:
EPA hazardous material transport rules and China's GB standards create divergent compliance pathways for each chemistry, with lithium-metal classifications restricting air freight options while sodium-ion cells face fewer logistics constraints.
- Solid-State:Oxide and sulfide electrolyte formulations eliminate flammable liquid components, enabling certification under stricter FAA battery guidelines for aviation propulsion systems. German and Japanese automotive OEMs concentrate pilot offtake agreements here, drawn by 20-minute fast-charge capability and inherent thermal stability.
- Lithium-Sulfur:Theoretical energy density exceeds 500 Wh/kg through lithium-metal anode pairing with sulfur cathodes, though polysulfide shuttle effects limit cycle life. Defense contractors in the United States and Israel prioritize this chemistry for unmanned aerial vehicle applications where weight reduction overrides longevity concerns.
- Lithium-Ion:Silicon composite anodes are retrofitting existing gigafactory equipment, preserving capital investment while lifting energy density toward 300 Wh/kg.
- Sodium-Ion:Abundant raw material inputs bypass South American lithium brine concentration, appealing to Indian and Chinese grid storage developers.
- Flow:Vanadium and iron-chromium chemistries decouple power from energy capacity, suiting 8-hour utility-scale installations.
- Zinc-Air:Atmospheric oxygen cathodes yield high theoretical density but face humidity sensitivity in tropical deployments.
Solid-State handles the majority of throughput; Lithium-Sulfur is expanding most quickly on share.
Technology:
Manufacturing equipment compatibility varies dramatically across these approaches, with thin-film deposition requiring semiconductor-grade cleanrooms while cobalt-free cathodes slot into existing roll-to-roll coating lines.
- Silicon Anode:Metallurgical-grade silicon from German chemical producers now achieves battery-grade purity, enabling 400 Wh/kg prototypes without full solid-state transition costs. Electric vehicle fleets in California and Germany are accelerating procurement of these intermediate-density cells.
- Cobalt-Free:Lithium iron phosphate and nickel-manganese-aluminum formulations eliminate supply chain exposure to Democratic Republic of Congo mining, satisfying EU due diligence requirements under the Conflict Minerals Regulation.
- Thin-Film:Physical vapor deposition techniques borrowed from Korean display panel manufacturing yield sub-100-micron cells for wearable medical devices.
- Graphene-Enhanced:Conductive additives from Chinese producers improve rate capability in high-power applications.
- Polymer Electrolyte:Gel-phase intermediates bridge liquid and solid systems, extending existing manufacturing asset life.
- Metal-Air:Rechargeable zinc-air systems target hearing aid and remote sensor markets with atmospheric oxygen cathodes.
Silicon Anode dominates current capital allocation; Thin-Film is climbing the fastest as semiconductor equipment repurposing accelerates.
Application:
End-use specifications range from FAA certification timelines for aviation to decade-long warranty requirements for utility contracts, fragmenting procurement criteria across segments.
- Electric Vehicles:OEM qualification cycles now parallel-track UN 38.3 certification with automotive testing, compressing 36-month timelines where cell suppliers maintain established laboratory relationships. China's MIIT certification advantages domestic manufacturers with pre-existing Shanghai and Shenzhen testing partnerships.
- Grid Storage:Four-hour duration contracts dominate independent power producer procurement, with silicon-anode retired EV packs entering second-life deployment at 70-80% residual capacity.
- Aerospace:FAA pathways for electric propulsion mandate energy density above 350 Wh/kg, directing R&D toward lithium-sulfur and solid-state architectures.
- Consumer Electronics:Fast-charge specifications from Korean and Chinese device makers prioritize rate capability over absolute density.
- Marine:International Maritime Organization emission targets for coastal vessels generate demand for 500+ kWh systems with fire-suppression requirements.
- Wearables:Sub-millimeter thickness constraints favor thin-film and solid-state microcells.
Electric Vehicles commands the dominant share of offtake volume; Grid Storage offers the steepest expansion trajectory as renewable penetration climbs.
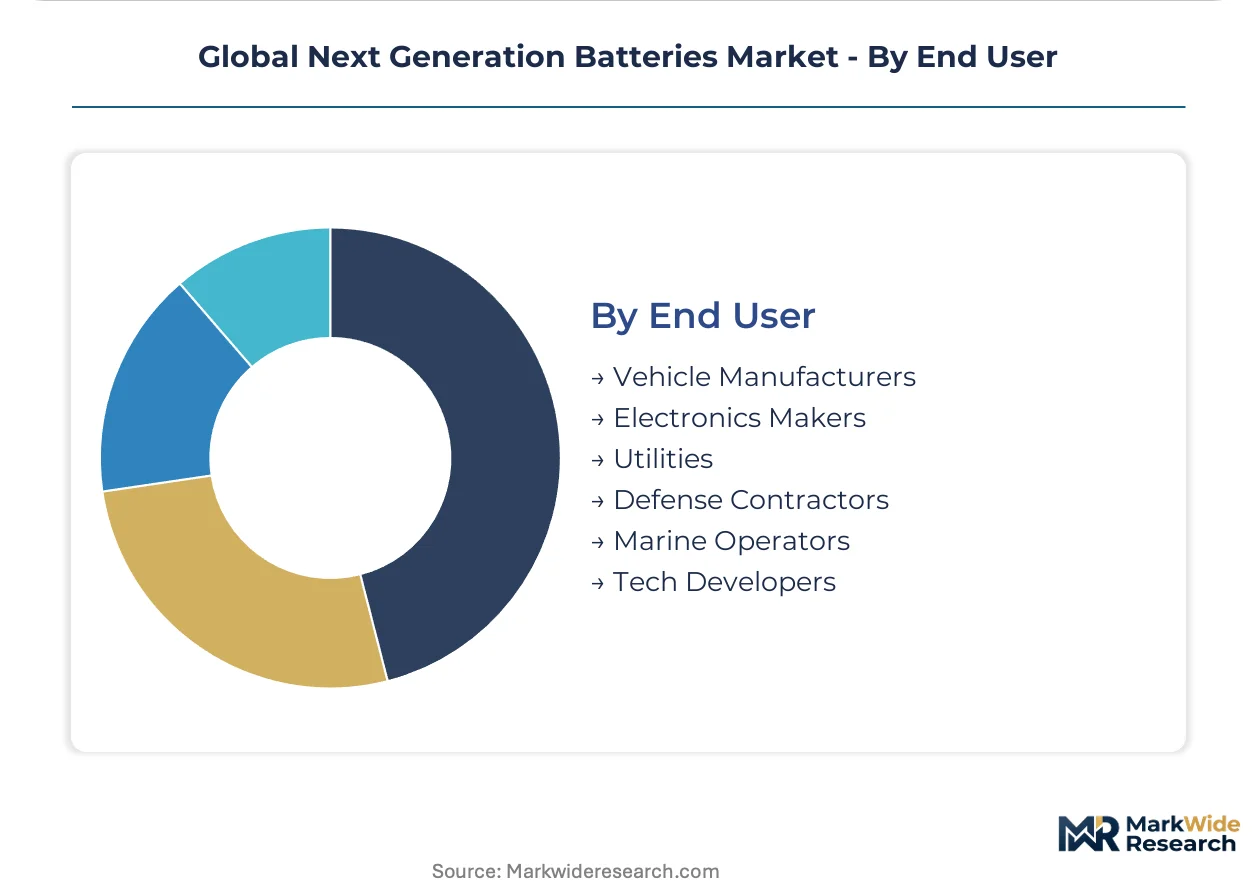
End User:
Procurement structures diverge between upfront cell purchase and battery-as-a-service leasing, with fleet operators now specifying residual value guarantees rather than hardware acquisition.
- Vehicle Manufacturers:Multi-year offtake agreements with certified pilot lines lock in supply for European Green Deal electrification mandates, binding BMW, Toyota, and domestic Chinese OEMs to specific chemistry roadmaps.
- Utilities:Long-dated power purchase agreements spanning 15-20 years favor established lithium-ion variants with proven degradation curves over unproven next-generation chemistries.
- Electronics Makers:Korean and Chinese device assemblers specify 12-month qualification cycles, compressing supplier selection timelines.
- Defense Contractors:ITAR and national security classifications restrict foreign cell sourcing for United States military applications.
- Marine Operators:Classification society rules from Lloyd's Register and DNV govern battery room design for coastal electrification.
- Tech Developers:Venture-backed solid-state startups prioritize automotive partnerships over consumer electronics given revenue concentration.
Vehicle Manufacturers handles the majority of throughput; Tech Developers is gaining share fastest as solid-state licensing models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification protocols in China compress supplier qualification timelines for solid-state pilot lines, while EPA hazardous material transport rules in the United States restrict lithium-metal anode air freight. Germany's KBA emission mandates and India's PLI scheme for ACC batteries reshape procurement geography across three continents.
China
CATL dominates mass manufacturing through integrated cathode supply chains, securing multi-year offtake agreements with domestic automotive OEMs. MIIT certification timelines have extended by six months for foreign cell suppliers, advantaging manufacturers with established Shanghai and Shenzhen testing relationships. The Yangtze River Delta concentrates pilot production lines for sulfide-based solid electrolytes.
Germany
BMW and automotive OEMs face binding EU Green Deal electrification targets that accelerate qualification timelines for lithium-metal architectures. German chemical producers now deliver metallurgical-grade silicon at battery-grade purity, enabling 400 Wh/kg cell prototypes. Bavaria anchors thin-film deposition expertise transferred from semiconductor equipment suppliers.
United States
FAA certification pathways for electric propulsion systems prioritize energy density above 350 Wh/kg, directing R&D investment toward lithium-sulfur and solid-state chemistries. EPA classification of lithium-metal anodes as Class 4.3 dangerous goods restricts air freight options for prototype cells. California fleet operators specify residual value guarantees rather than upfront cell purchase in heavy-duty electric truck procurement.
South Korea
Samsung SDI specializes in thin-film deposition techniques that yield higher energy density per unit volume, leveraging process engineers from Korean display panel industries. Solvent-free electrode manufacturing requires talent concentrated in Korean electronics industries, creating recruitment competition with semiconductor fabs. Seoul Capital Area hosts precision sintering equipment suppliers for oxide and sulfide electrolyte formulations.
India
Production-linked incentives covering 50 GWh of advanced chemistry cell capacity create first-mover advantages for solid-state technology licensors establishing local joint ventures. Sodium-ion chemistries appeal to Indian grid storage developers seeking to bypass South American lithium brine concentration. Tamil Nadu and Gujarat concentrate battery assembly partnerships targeting maritime propulsion electrification for coastal vessels.
Global Next Generation Batteries Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates dominating solid-state electrolyte manufacturing while cell designers compete on automotive qualification speed. The market structures around capital intensity barriers rather than cell design innovation, compressing viable production to thin-film deposition specialists. Three archetypes prevail: cathode-integrated mass manufacturers, automotive partnership anchors, and thin-film deposition specialists. Dominant competitive moves include strategic partnerships with established OEMs and geographic expansion through joint ventures in incentivized manufacturing hubs.
Among Asian-based fabricators, CATL and Samsung SDI occupy positions at opposite ends of the manufacturing spectrum, with the former exemplifying cathode-integrated scale and the latter representing thin-film specialization. Solid Power anchors the automotive partnership archetype through its positioning with established OEM programs. These three companies illustrate how competitive boundaries redraw around electrolyte engineering talent scarcity and pilot line certification timelines rather than raw cell performance metrics.
| Leading Market Players |
|---|
| BYD |
| SK On |
| CATL |
| Solid Power |
| QuantumScape |
| LG Energy Solution |
| Samsung SDI |
| Amprius Technologies |
| Panasonic Energy |
| Others |
Cost & Logistics Intelligence
Silicon anode substitution for graphite electrodes is redrawing procurement geography toward German metallurgical suppliers while compressing cell-level cost structures. This input shift simultaneously elevates purity-grade premiums and fragments legacy Chinese graphite concentration, forcing OEMs to renegotiate long-dated offtake terms.
Pricing Analysis
Price spreads between Chinese domestic and European export solid-state cells now exceed 30% after accounting for EU REACH compliance and air freight restrictions under EPA hazardous material rules. Pricing stratifies across aviation-certified premium tiers, automotive qualification-standard tiers, and grid storage economy tiers. Cost compression in silicon-anode intermediates is intensifying because German chemical producers have achieved battery-grade purity at scale. Fleet operators in California exhibit highest price sensitivity through battery-as-a-service leasing structures, while aerospace defense contractors show least sensitivity due to FAA-mandated energy density floors.
Supply Chain Analysis
China and South Korea anchor cathode active material and precision sintering equipment production, with Japan supplying oxide electrolyte precursor chemicals. The supply chain draws from South American lithium brine, German metallurgical-grade silicon, and Korean thin-film deposition equipment. Single-source vulnerability concentrates in Japanese ceramic separator suppliers for sulfide electrolyte formulations. Distribution runs through automotive OEM direct procurement for qualified cells, with spot markets emerging for second-life grid storage packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film deposition expertise scarcity has compressed viable solid-state production to semiconductor equipment repurposing specialists, creating asymmetric returns for capital deployment into captive electrolyte engineering capabilities.
For Market Incumbents: Fortify pilot line certification timelines by embedding NMPA-recognized testing relationships in Shanghai and Shenzhen before MIIT protocols extend further. Lock in multi-year metallurgical-grade silicon offtake with Bavarian chemical producers to preempt purity-grade bottlenecks. Defensive positioning requires backward integration into cathode active material production to preserve margin visibility against lithium carbonate volatility. For New Entrants and Emerging Players: UN 38.3 certification fast-track partnerships with established automotive OEMs offer the most penetrable entry vector, collapsing 18-24 month timelines through parallel-track submission protocols. Target India's PLI scheme for ACC batteries through joint venture structures in Tamil Nadu and Gujarat, where production-linked incentives cover 50 GWh of advanced chemistry capacity. Go-to-market execution should prioritize maritime propulsion electrification contracts with fire-suppression specifications that favor solid-state architectures over incumbent lithium-ion. For Investors and Strategic Acquirers: Capital is best deployed toward thin-film deposition specialists with Korean display panel equipment heritage and established FAA certification relationships. Long-term viability across the projection horizon rests on electrolyte engineering talent concentration rather than raw cell performance metrics. Watch for inflection signals in sulfide electrolyte sintering equipment order books from Seoul Capital Area suppliers as leading indicator of automotive program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Deposition Equipment Repurposing | Semiconductor-grade cleanroom adaptation enables sulfide electrolyte manufacturing scale-up for BMW and Toyota programs. |
| MIIT Certification Pre-Qualification | Shanghai and Shenzhen testing relationships compress supplier timelines against six-month foreign extensions. |
| Silicon Anode Backward Integration | German chemical producer partnerships secure battery-grade purity without South American lithium exposure. |
| Battery-as-a-Service Leasing Structures | Residual value guarantees shift technology risk from California fleet operators to cell providers. |
| Maritime Solid-State Joint Ventures | IMO emission targets for coastal vessels generate 500+ kWh demand with fire-suppression premiums. |
Research Approach
Findings reconcile primary fieldwork against secondary review of MIIT certification databases, EPA hazardous material transport filings, and EU Green Deal mandate documentation. Primary interviews engaged solid-state pilot line engineers, automotive OEM procurement directors, thin-film deposition equipment specialists, and grid storage project developers. Secondary validation drew from customs trade data for lithium carbonate and metallurgical-grade silicon, SEC filings of cathode-integrated manufacturers, and FAA certification pathway records. Bottom-up cell shipment estimates triangulate against top-down automotive electrification targets.
Segmentation dimensions modeled span battery type chemistry, silicon versus solid-state technology architecture, electric vehicle and grid storage applications, and vehicle manufacturer versus utility end-user procurement structures. CAGRs derive from installed base replacement curves for automotive fleets and renewable penetration rates for utility-scale storage. Industry-specific forecast inputs include FAA energy density thresholds for aviation propulsion and IMO emission compliance deadlines for maritime electrification.
Decision-makers should treat outputs as directional under assumptions of sustained lithium carbonate price volatility and stable EPA hazardous material classifications; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in MIIT certification timelines and sulfide electrolyte manufacturing yield improvements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Battery Wet Separator Market