
 Automotive Lithium-Ion Battery Cell Market | 2026-2036
Automotive Lithium-Ion Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lithium-Ion Battery Cell Market Analysis
Cell refurbishment and second-life material recovery is fragmenting from a concentrated OEM-controlled activity into a multi-stakeholder margin pool. Contemporary Amperex Technology Co. Limited leverages its vertical cathode production to capture upstream value. LG Energy Solution anchors its position through dedicated joint ventures with North American and European automakers. BYD Company Limited controls its entire battery-to-vehicle pipeline, insulating margin from external cell suppliers.
Automotive lithium-ion battery cells are electrochemical energy storage devices comprising cathode, anode, separator, and electrolyte layers, typically operating at 3.2–4.2 V nominal voltage and engineered for 1,000–3,000 deep discharge cycles depending on chemistry. Their primary purpose is to store and deliver high-density direct current to electric traction motors in zero-emission and hybrid drivetrains. Cylindrical cells dominate high-volume automated production lines due to mature winding equipment and consistent thermal behavior. Prismatic cells lead in pack-level volumetric efficiency, commanding premium positioning in European and Chinese premium electric platforms. LFP chemistry is displacing nickel-cobalt formulations in entry and mid-market passenger segments where cost-per-kilogram and thermal stability outweigh energy density requirements.
The EPA tailpipe emission standards and the EU Green Deal's battery passport mandate are forcing cell-level carbon footprint disclosure and recycled content quotas across supply chains. China's MIIT battery industry regulation establishes capacity utilization thresholds and technical entry barriers that filter subscale producers. NHTSA's evolving electric vehicle safety protocols in the United States are testing cell-to-pack architectures against thermal runaway propagation limits. Stakeholders must monitor how regional content rules and chemistry-specific subsidy eligibility reshape procurement geography and manufacturing investment decisions.
Market Dynamics
The automotive lithium-ion battery cell market is compressing around cathode chemistry transitions as LFP formulations displace nickel-cobalt alternatives across volume passenger segments, redrawing procurement priorities and supplier tier structures.
Growth Catalysts
- EPA tailpipe emission standards:The United States regulator mandates fleet-average CO2 reductions that force OEM electrification roadmaps, pulling cell demand into dedicated supply agreements.
- Jiangsu and Fujian manufacturing clusters:Concentrated cathode precursor refining and separator film production in these Chinese provinces collapse logistics costs for integrated cell producers.
- Cell-to-pack architectures:Structural battery designs eliminate module housings, cutting pack-level cost and weight while simplifying thermal management for platform engineering teams.
Market Restraints
- Lithium carbonate price volatility:Spot market swings in this cathode input material transmit directly to cell bill-of-materials, compressing margin predictability for non-integrated producers.
- EU F-Gas Regulation:This framework restricts fluorinated electrolyte solvents and cooling agents, forcing chemistry reformulation and compliance testing timelines that extend product qualification cycles.
- Solid-state battery substitution trajectory:Next-generation solid-electrolyte prototypes promise energy density step-changes that threaten to strand incumbent liquid-electrolyte manufacturing capacity before depreciation cycles complete.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:This production-linked incentive program offers capital expenditure support and import duty protection for local gigafactory investments, opening a demand geography outside established supply orbits.
- Battery passport mandates under EU Green Deal:Digital traceability requirements create service revenue pools for software-enabled lifecycle management platforms and second-life certification providers.
- Sodium-ion chemistry convergence:Emerging cathode-anode pairings using abundant raw materials address lithium supply concentration risks while meeting entry-segment energy density specifications.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design, formation protocol optimization, and solid-electrolyte interphase modeling require specialized expertise that outpaces university pipeline output across manufacturing geographies.
- NMPA certification timeline compression:China's cell approval protocols demand extensive cycle-life and abuse-testing documentation that extends product launch schedules for new entrants lacking regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lithium-Ion Battery Cell Market |
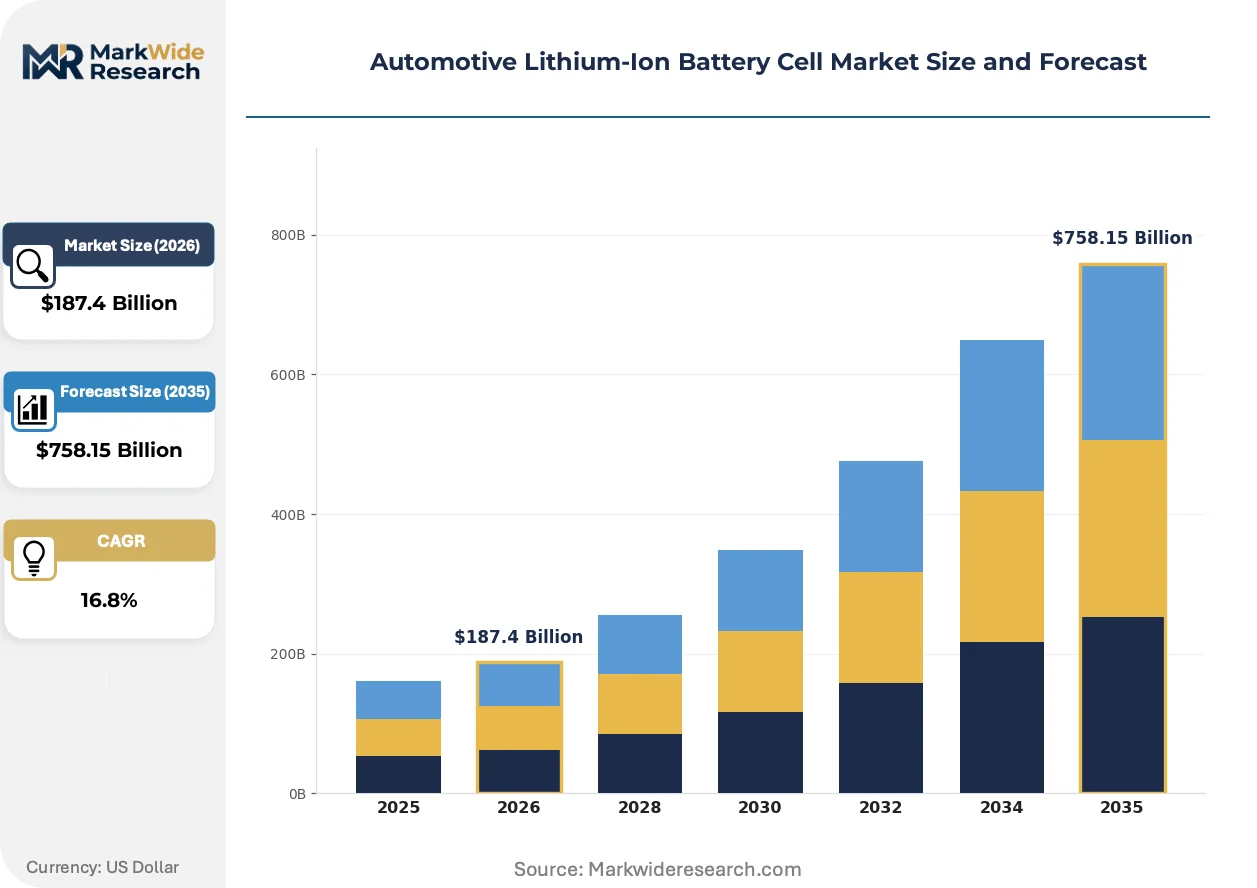
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouch Cell, Cylindrical Cell, Prismatic Cell, Custom Form Factor Technology: LFP, NMC, NCA, LCO End User: Passenger Vehicles, Commercial Vehicles, Electric Buses, Two-Wheelers Application: Hybrid Electric Vehicle, Battery Electric Vehicle, Plug-in Hybrid, Energy Storage Systems |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, BYD Company Limited, Samsung SDI, SK Innovation, A123 Systems, Northvolt, Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lithium-Ion Battery Cell Market Emerging Trajectories
Digital thread integration across cell design, manufacturing execution, and lifecycle traceability is compressing development cycles and enabling chemistry-specific performance optimization at scale.
Dry electrode coating technology eliminates solvent-based slurry processing and energy-intensive drying ovens. CATL and BYD are piloting this equipment across cylindrical and prismatic lines. The process is digitizing quality control through in-line impedance spectroscopy and machine-vision defect classification that feeds back to coating thickness algorithms in real time.
China's MIIT battery industry regulation establishes capacity utilization thresholds and technical entry barriers that filter subscale producers. The framework mandates minimum energy density and cycle-life benchmarks that reshape competitive tiers. European cell producers are responding by accelerating LFP qualification to meet the cost structures required for volume platform wins.
Fleet operators and energy storage integrators are consolidating procurement into multi-year offtake agreements with embedded price escalation clauses. Tier-1 automotive suppliers are losing intermediary margin as direct OEM-cell producer contracts proliferate. This pattern is most visible in Germany and the Netherlands, where utility-scale storage projects and commercial vehicle electrification create concentrated demand nodes.
Automotive Lithium-Ion Battery Cell Market Segmentation
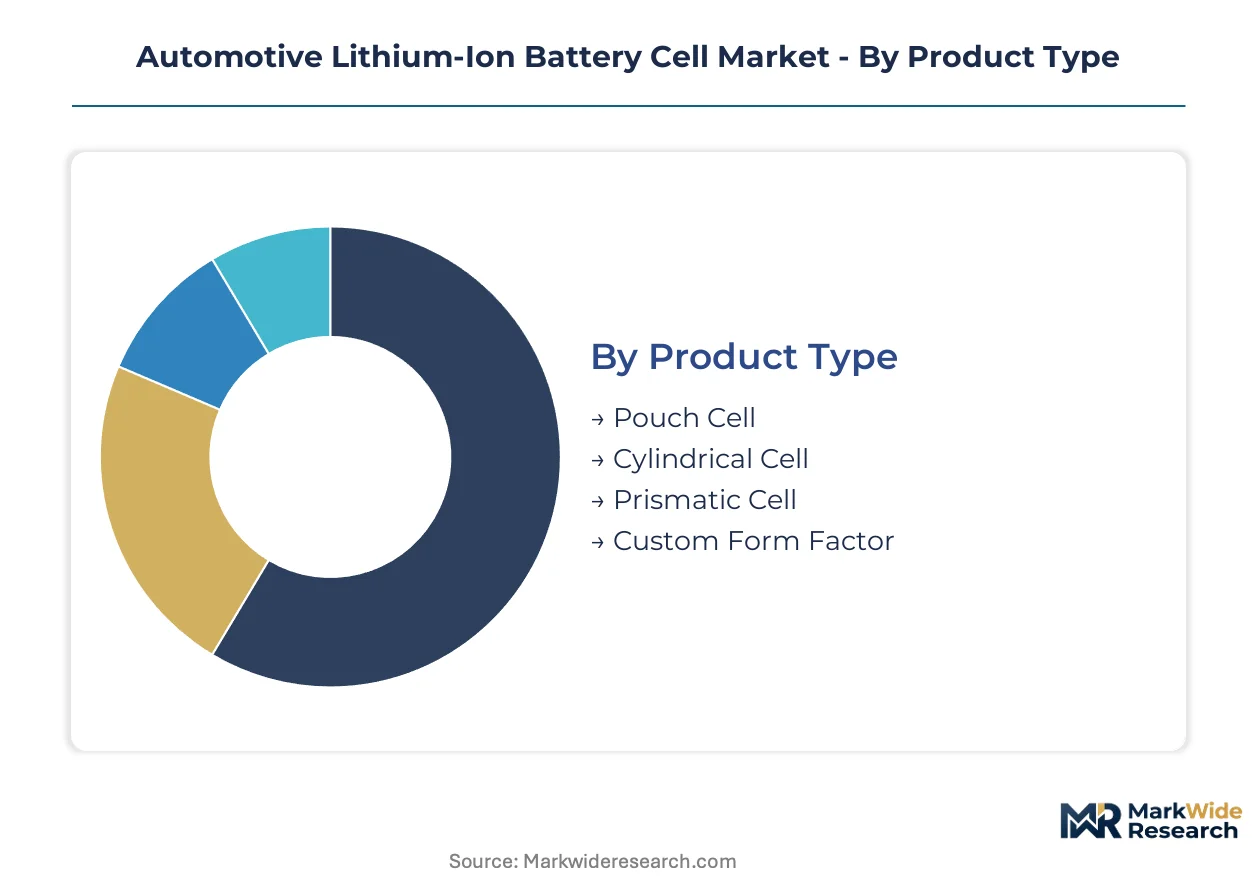
Automotive lithium-ion battery cell segmentation reveals how form factor, chemistry, and vehicle platform interact to determine procurement economics and manufacturing investment priorities. Each dimension carries distinct margin profiles and qualification barriers that reshape supplier competitive tiers.
Product Type:
Cell geometry dictates automation compatibility, thermal management architecture, and pack-level volumetric efficiency across passenger and commercial platforms.
- Cylindrical Cell:Rolled electrode jellyrolls in metal cans enable high-speed winding automation and consistent thermal behavior. Demand concentrates in North American and Chinese passenger platforms where Tesla and BYD anchor gigascale consumption, driven by mature equipment ecosystems and predictable abuse tolerance.
- Prismatic Cell:Stacked or wound electrodes in rectangular aluminum housings maximize pack-level space utilization. European premium electric platforms in Germany and the Netherlands favor this format for structural battery integration, constrained by slower lamination equipment throughput and higher capital intensity per line.
- Pouch Cell:Sealed flexible polymer laminates suit applications demanding maximum packaging freedom.
- Custom Form Factor:Bespoke dimensions serve niche commercial vehicle and aerospace prototypes requiring non-standard volumetric constraints.
Established volume favors cylindrical formats; emerging adoption favors prismatic architectures.
Technology:
Cathode chemistry selection trades energy density against material cost, thermal stability, and supply chain concentration risks.
- LFP (Lithium Iron Phosphate):Iron-phosphate cathodes operate at 3.2V nominal with exceptional thermal runaway resistance. Chinese passenger manufacturers dominate procurement, propelled by MIIT energy density thresholds and cobalt-free cost structures that undercut nickel-chemistry alternatives.
- NMC (Nickel Manganese Cobalt):Layered oxide cathodes deliver 200+ Wh/kg cell-level energy density. Korean and Japanese automakers specify high-nickel variants for long-range European and North American platforms, facing lithium carbonate volatility and F-Gas Regulation compliance timelines.
- NCA (Nickel Cobalt Aluminum):High-nickel formulations serve performance-oriented drivetrains demanding maximum gravimetric density.
- LCO (Lithium Cobalt Oxide):Cobalt-rich chemistry retains niche presence in premium two-wheeler and specialty vehicle segments.
Cost-driven procurement favors LFP; performance-critical applications favor NMC.
End User:
Vehicle category determines cycle depth requirements, duty cycle severity, and fleet-scale procurement consolidation patterns.
- Passenger Vehicles:Light-duty platforms account for dominant cell consumption, with OEMs consolidating supply agreements around platform-specific cell-to-pack architectures.
- Commercial Vehicles:Medium and heavy-duty trucks impose high-C-rate discharge demands and 3,000+ cycle life requirements. Fleet operators in Germany and the Netherlands are consolidating procurement into multi-year offtake agreements with direct cell producer contracts.
- Electric Buses:Municipal transit authorities specify LFP-dominant chemistry for fire safety and depot charging compatibility.
- Two-Wheelers:Low-cost LCO and LFP cells serve micromobility segments with shallow cycle depth and swappable battery requirements.
Fleet consolidation favors commercial vehicles; volume scale favors passenger platforms.
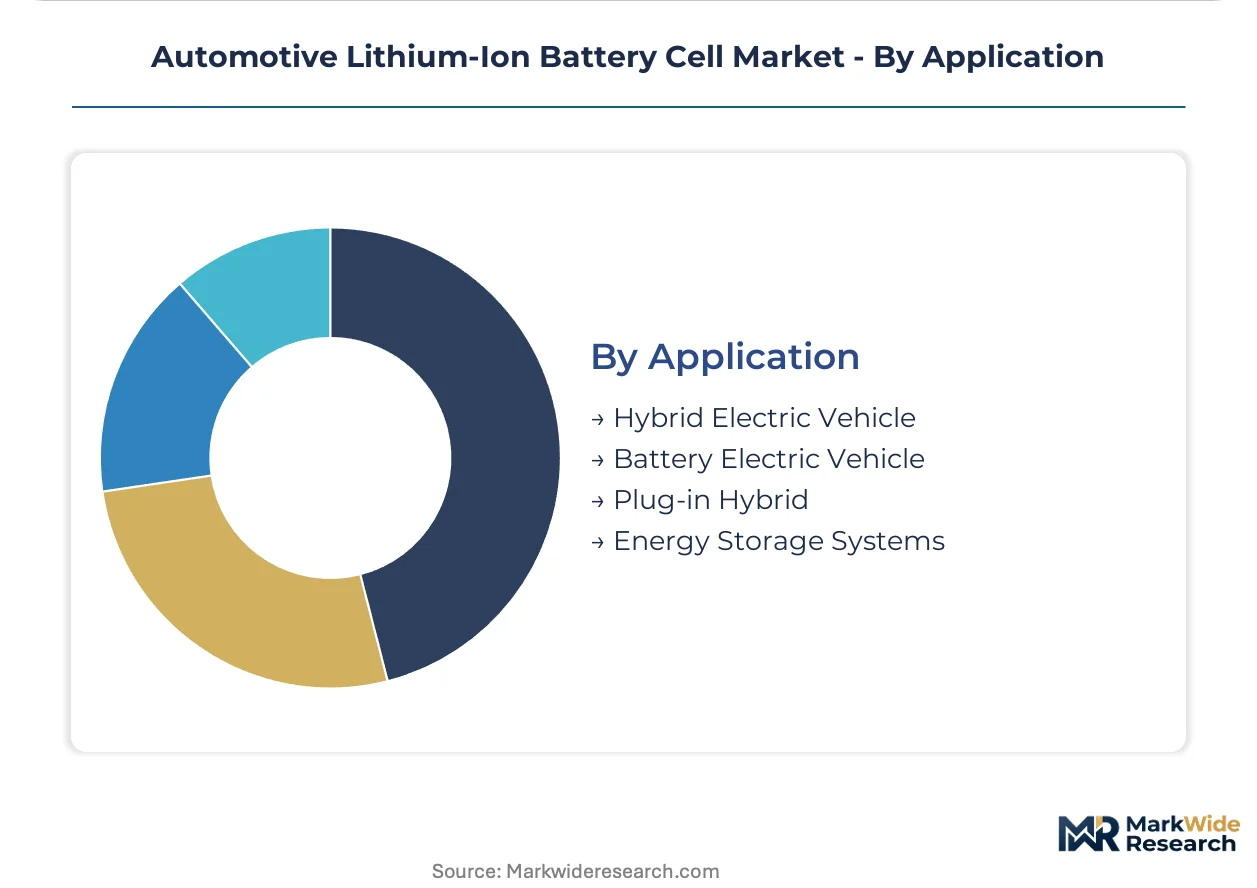
Application:
Drivetrain electrification degree determines pack size, thermal management complexity, and second-life recovery potential.
- Battery Electric Vehicle:Full-electric platforms demand 60-100+ kWh packs with cell-to-pack structural integration. Chinese and North American OEMs are qualifying dry electrode processes to compress manufacturing cost.
- Plug-in Hybrid:Smaller 15-25 kWh packs bridge electric-only commuting and combustion range extension. European manufacturers favor prismatic LFP for cost containment in mass-market segments.
- Hybrid Electric Vehicle:Sub-5 kWh systems prioritize power density over energy density for kinetic energy recovery.
- Energy Storage Systems:Second-life automotive cells and purpose-built LFP modules serve stationary grid applications with relaxed power density requirements.
Manufacturing investment favors battery electric platforms; second-life margin pools favor energy storage systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing capacity clusters in three national production hubs where cathode precursor refining, separator film production, and gigafactory assembly converge. Each geography shapes procurement patterns through distinct regulatory frameworks and industrial policy incentives.
China
CATL and BYD anchor gigafactory ecosystems in Jiangsu and Fujian provinces, consuming half of global cathode material output. MIIT battery industry regulation establishes minimum energy density thresholds and capacity utilization requirements that filter subscale producers. NMPA certification protocols demand extensive cycle-life documentation, extending product launch timelines for new entrants lacking regulatory infrastructure.
United States
EPA tailpipe emission standards mandate fleet-average CO2 reductions that force OEM electrification roadmaps, pulling cell demand into dedicated supply agreements. NHTSA electric vehicle safety protocols test cell-to-pack architectures against thermal runaway propagation limits. Michigan and Tennessee manufacturing corridors attract Korean and Japanese cell producers seeking proximity to Detroit Three and transplant assembly plants.
Germany
Premium electric platforms from Stuttgart and Munich automakers specify prismatic cell formats for structural battery integration. EU F-Gas Regulation restricts fluorinated electrolyte solvents, forcing chemistry reformulation and extended qualification cycles. North Rhine-Westphalia hosts separator film and electrolyte additive facilities serving Dutch and Belgian pack assembly operations.
South Korea
LG Energy Solution and Samsung SDI supply high-nickel NMC formulations to European and North American long-range platforms. METI-aligned technology partnerships with Japanese material suppliers secure cathode precursor offtake. Gyeonggi-do and Chungcheong provinces concentrate electrode coating and formation facility investments.
India
PLI scheme for advanced chemistry cells offers capital expenditure support and import duty protection for local gigafactory investments. Tamil Nadu and Gujarat states compete for anchor cell producers targeting two-wheeler and entry passenger vehicle electrification. BIS technical standards for cell safety and performance create compliance barriers for imported modules.
Automotive Lithium-Ion Battery Cell Market Vendor Landscape
Vertically integrated conglomerates and dedicated pure-play cell producers split the market into distinct competitive tiers with divergent margin capture mechanisms. Chinese producers leverage captive cathode supply chains to compress manufacturing cost, while Korean and Japanese competitors anchor positions through joint ventures with Western automakers. Two archetypes dominate: chemistry-agnostic scale operators optimizing equipment utilization across cylindrical and prismatic lines, and platform-captive specialists engineering cell-to-pack architectures for single OEM pipelines. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers racing to secure lithium carbonate offtake and formation facility permits ahead of rival qualification timelines.
Among Chinese producers, Contemporary Amperex Technology Co. Limited and BYD Company Limited exemplify the integrated conglomerate archetype, combining upstream cathode production with downstream vehicle assembly. LG Energy Solution represents the joint-venture anchored model, occupying a position between Korean material science capabilities and Western OEM platform requirements. These three entities sit within distinct strategic configurations: one optimizing backward integration depth, one controlling end-to-end electrification pipelines, and one bridging geographic supply-demand asymmetries through partnership structures.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Samsung SDI |
| SK Innovation |
| A123 Systems |
| Northvolt |
| Gotion High-Tech |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Jiangsu and Fujian cathode precursor corridors is compressing formation facility utilization rates below MIIT-mandated thresholds, forcing integrated producers to absorb margin erosion through captive lithium carbonate positions while non-integrated suppliers surrender pricing power to OEM direct procurement teams.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European supply chains, stratifying cell quotations by electrolyte chemistry compliance grade and carbon footprint certification tier. Three-tier pricing structure across premium, standard, and economy levels separates NMC high-nickel formulations from LFP cost-optimized cells and sodium-ion experimental batches. Cost compression in entry-segment cylindrical lines is intensifying because CATL and BYD are flooding spot markets with excess LFP capacity. Fleet operators in commercial vehicle segments demonstrate highest price sensitivity, while German premium OEMs accept cobalt-premium positioning for prismatic NMC architectures.
Supply Chain Analysis
Contemporary Amperex Technology Co. Limited, LG Energy Solution, and Samsung SDI hold dominant contract-manufacturing capacity across cylindrical and prismatic formation lines. Geographic supply concentration centers on China, South Korea, and Japan, where electrode coating equipment and separator film production cluster within 500-kilometer logistics radii. Raw material dependencies rest on lithium carbonate from Australian and Chilean brine operations, nickel laterite from Indonesian smelters, and cobalt hydroxide from DRC concentrates. Single-source vulnerability in cathode precursor refining creates supply chain risk, particularly for European cell producers lacking backward integration into lithium conversion. Distribution runs through direct OEM-cell producer offtake agreements that disintermediate traditional Tier-1 automotive supplier margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive lithium-ion battery cell demand is accelerating through a regulatory inflection as EPA tailpipe standards and EU battery passport mandates force OEM electrification roadmaps, compressing supplier qualification timelines and rewarding capacity-ready producers.
For Market Incumbents: Entrench platform-captive relationships by securing exclusive cell-to-pack architecture partnerships with Detroit Three and Stuttgart premium OEMs before solid-state prototypes reach commercial scale. Deepen backward integration into lithium carbonate conversion and cathode precursor refining to insulate margin from spot market volatility. Prioritize NMPA regulatory affairs infrastructure investment to compress certification timelines for cylindrical LFP variants targeting Chinese passenger volume. For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat PLI-protected manufacturing corridors represent the most penetrable entry point for two-wheeler and entry passenger vehicle cell supply, where BIS technical standards create compliance barriers for imported modules but reward local formation facility investment. Sodium-ion chemistry convergence for grid storage and micromobility applications offers a second white-space target with relaxed energy density specifications. Pursue joint venture structures with established cathode material suppliers to bypass lithium offtake queue positions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cell producers with multi-year offtake agreements embedding price escalation clauses and second-life certification service attachments. Long-term viability across the projection horizon favors producers with demonstrated cell-to-pack platform wins and captive lithium supply positions. Acquisition target archetype: mid-scale European prismatic specialists with EU F-Gas Regulation compliance infrastructure and pending German OEM qualification. Monitor solid-state battery prototype announcements from Japanese METI-aligned consortia as inflection indicator for incumbent liquid-electrolyte capacity stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Direct OEM-cell producer contracts disintermediate Tier-1 supplier margins across North American platforms. |
| Backward Integration into Cathode Production | Captive precursor refining compresses lithium carbonate cost exposure for Jiangsu and Fujian gigafactories. |
| EU F-Gas Regulation Compliance Certification | Fluorinated electrolyte reformulation qualification opens German and Dutch premium electric platform procurement. |
| Sodium-Ion Chemistry Scale-Up | Abundant raw material feedstocks address lithium supply concentration risks in entry-segment applications. |
| Cell-to-Pack Architecture Investment | Structural battery designs eliminate module housings, reducing pack-level weight and thermal management complexity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, cathode material R&D leads, and fleet operator energy managers. Secondary validation drew from MIIT battery industry filings, EPA tailpipe standard rulemaking documents, EU Green Deal battery passport technical specifications, and customs trade data on lithium carbonate import flows. Bottom-up cell shipment modeling triangulated against top-down OEM electrification roadmap projections.
Calibration against historical capacity utilization rates and formation facility permitting timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include cell geometry, cathode chemistry, vehicle platform architecture, and regional regulatory cluster. CAGRs derived from slope-intercept fitting of OEM announced battery electric vehicle production targets, adjusted for chemistry-specific energy density evolution. Industry-specific forecast inputs incorporated NMPA certification timeline distributions and F-Gas Regulation compliance cost assumptions.
Practitioners should monitor lithium carbonate spot price volatility, solid-state battery prototype announcements, and regional content rule revisions for early signals of forecast deviation. Forecasts embed assumptions regarding MIIT capacity utilization enforcement continuity and EPA standard implementation timelines. Quarterly review of cathode precursor refining capacity announcements and OEM direct procurement contract disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Lithium Sulfur Dioxide Battery Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Lithium Battery Components Market