
 Lithium-Ion Stationary Battery Market | 2026-2036
Lithium-Ion Stationary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Stationary Battery Market Insights
Containerized and modular system bundling is broadening buyer choice across utility and commercial procurement channels. Tesla leverages its integrated software-hardware stack to dominate utility-scale installations in North America. LG Energy Solution anchors its position through captive cathode supply and multi-gigawatt manufacturing scale. BYD competes aggressively on cost, extending its China-based LFP production into European and Australian storage tenders.
Lithium-ion stationary batteries are electrochemical energy storage systems using lithium-based intercalation compounds, typically housed in climate-controlled enclosures with operating voltages from 200 V to 1,500 V and cycle life ratings exceeding 6,000 cycles at 80% depth of discharge. Their primary purpose is to store grid electricity or renewable generation for dispatch during peak demand, frequency events, or supply interruptions. Utility-scale deployments represent the deepest margin pool due to long-term power purchase agreements and tolling structures, while residential segments exhibit faster volume growth as solar-plus-storage economics improve in deregulated retail markets. LFP chemistry leads in new installations because of superior thermal stability and extended cycle life, displacing NMC alternatives in stationary applications where energy density carries lower priority.
FERC Order 2222 in the United States enables distributed storage aggregation into wholesale markets, while the EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds for batteries placed on the European market. China's GB standards for electrochemical energy storage safety, enforced by SAMR, constrain product entry and shape design requirements for thermal runaway containment. Stakeholders must monitor how interconnection reform timelines and local content rules reshape procurement geography and supplier qualification criteria.
Market Dynamics
The Lithium-Ion Stationary Battery Market is being fundamentally restructured by the US Inflation Reduction Act's standalone storage tax credit, which redirects capital flows toward domestic battery assembly and away from imported integrated systems.
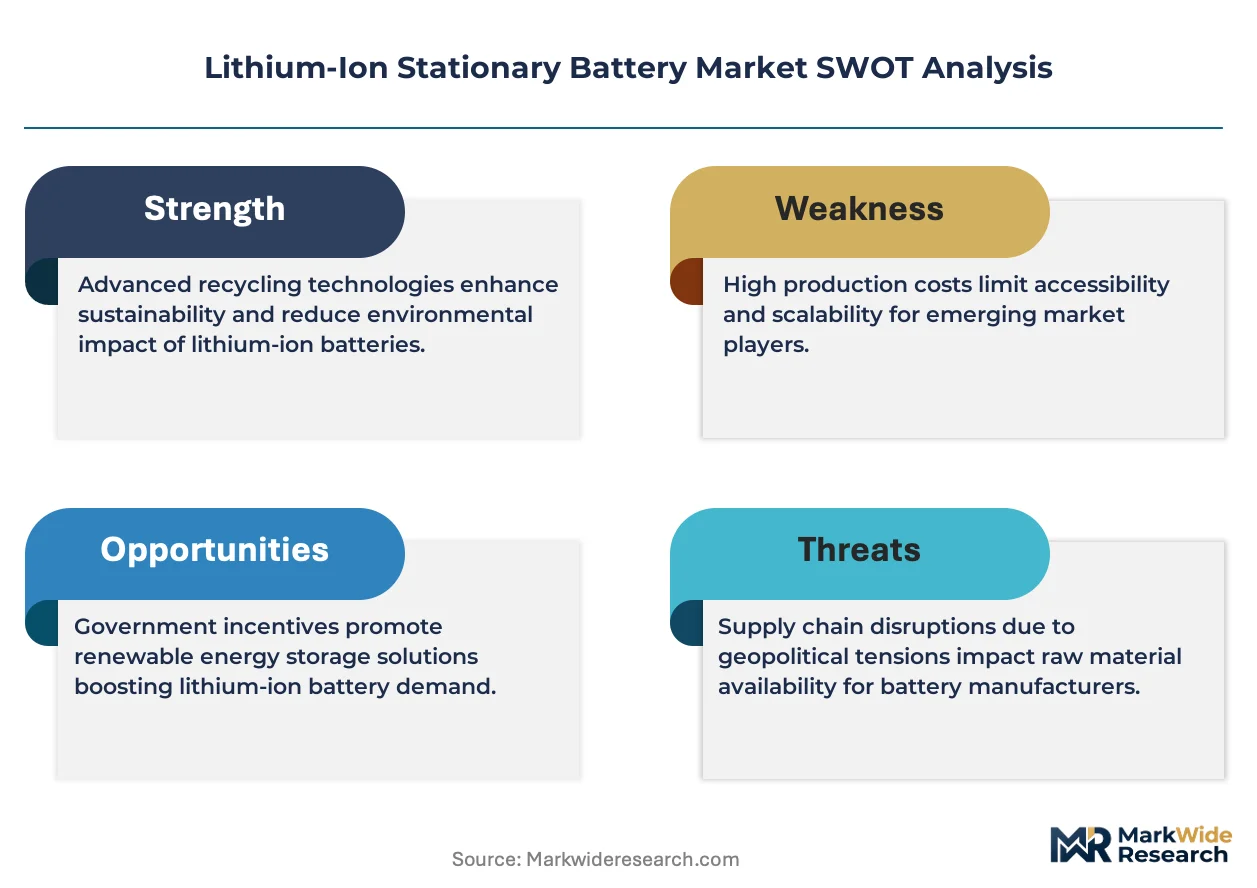
Growth Catalysts
- Interconnection queue reform:Grid operators in Texas and California are fast-tracking storage assets that provide frequency regulation and peak shaving services, rewarding fast-ramping lithium-ion systems with preferential queue positions.
- LFP chemistry maturation:Lithium iron phosphate cells now exceed 6,000 cycles at 80% depth of discharge, eliminating thermal runaway risks that constrained earlier NMC deployments in densely populated commercial zones.
- CAISO market redesign:California's wholesale market reforms now compensate storage for resource adequacy and flexible ramping, creating stacked revenue streams that improve project economics.
Market Restraints
- Cathode supply concentration:Processed lithium and refined cathode active material production clusters in China, exposing non-Chinese integrators to supply disruption and forced technology transfer requirements.
- Interconnection study delays:US regional transmission organizations now require 24-36 months for generator interconnection studies, freezing capital deployment and inflating project carrying costs.
- Fire suppression retrofit mandates:Evolving NFPA 855 standards for thermal runaway containment are forcing expensive enclosure redesigns and third-party certification delays.
Strategic Opportunities
- Virtual power plant aggregation:FERC Order 2222 enables distributed storage assets to participate in wholesale markets, creating software-layer value capture for residential and commercial fleet operators.
- Battery-as-a-service models:Third-party ownership structures separate hardware risk from offtake commitment, lowering barriers for commercial and industrial buyers in deregulated retail markets.
- EU Battery Regulation compliance services:Carbon footprint disclosure and recycled content mandates create advisory and certification revenue streams for testing laboratories and supply chain auditors.
Industry Challenges
- Thermal management engineering scarcity:Battery system integrators face acute shortages of electrochemical engineers capable of designing liquid cooling architectures for multi-megawatt containerized systems.
- Multi-standard certification timelines:Simultaneous UL 9540A, IEC 62619, and UN 38.3 testing requirements extend product launch cycles and fragment R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Stationary Battery Market |
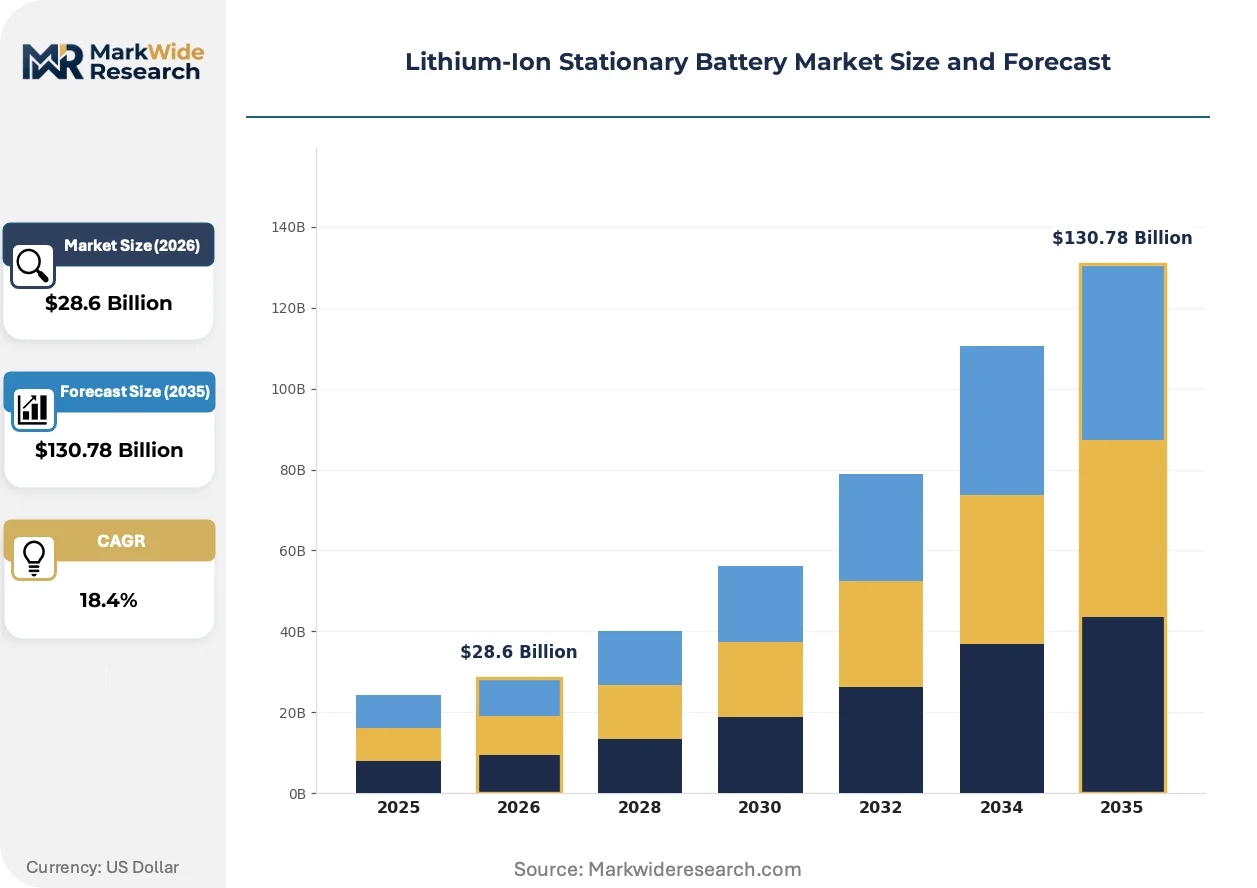
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Utility Application: Energy Storage, Load Shifting, Frequency Regulation, Backup Power Technology: LFP, NCA, NMC, LTO End User: Telecommunications, Healthcare, Renewable Energy, Data Centers |
| Companies Covered | Tesla, LG Energy Solution, BYD, CATL, Panasonic, Samsung SDI, Fluence Energy, GS Yuasa, SK Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Stationary Battery Market Trends and Innovations
Software-defined control architectures are compressing hardware differentiation and shifting value capture toward predictive analytics and automated dispatch optimization.
Intelligent battery management systems with cell-level sensing and machine learning-based state-of-health prediction are automating degradation forecasting and enabling dynamic warranty adjustments. Utility-scale operators in ERCOT and CAISO territories are deploying these systems to maximize arbitrage revenue and minimize unplanned downtime. The technology is automating manual oversight tasks that previously required dedicated operations teams, reducing labor intensity per megawatt installed.
The EU Battery Regulation's carbon footprint disclosure requirements and recycled content thresholds are forcing cathode suppliers to document supply chain emissions and establish European recycling partnerships. Battery manufacturers serving the European market must now redesign procurement contracts to include mass-balance accounting for recovered lithium, nickel, and cobalt. Stationary storage products lacking compliant lifecycle documentation face market exclusion, accelerating supplier consolidation around integrated miners and refiners with verified low-carbon processing.
Energy-as-a-service contracting is displacing traditional equipment sales in commercial and industrial segments, with offtakers preferring fixed monthly payments tied to guaranteed availability and performance metrics. Third-party owners assume technology risk and residual value exposure, while facility managers focus on operational integration rather than capital allocation. This model is most visible in deregulated US states where retail choice enables competitive supply and behind-the-meter optimization.
Lithium-Ion Stationary Battery Market Segmentation
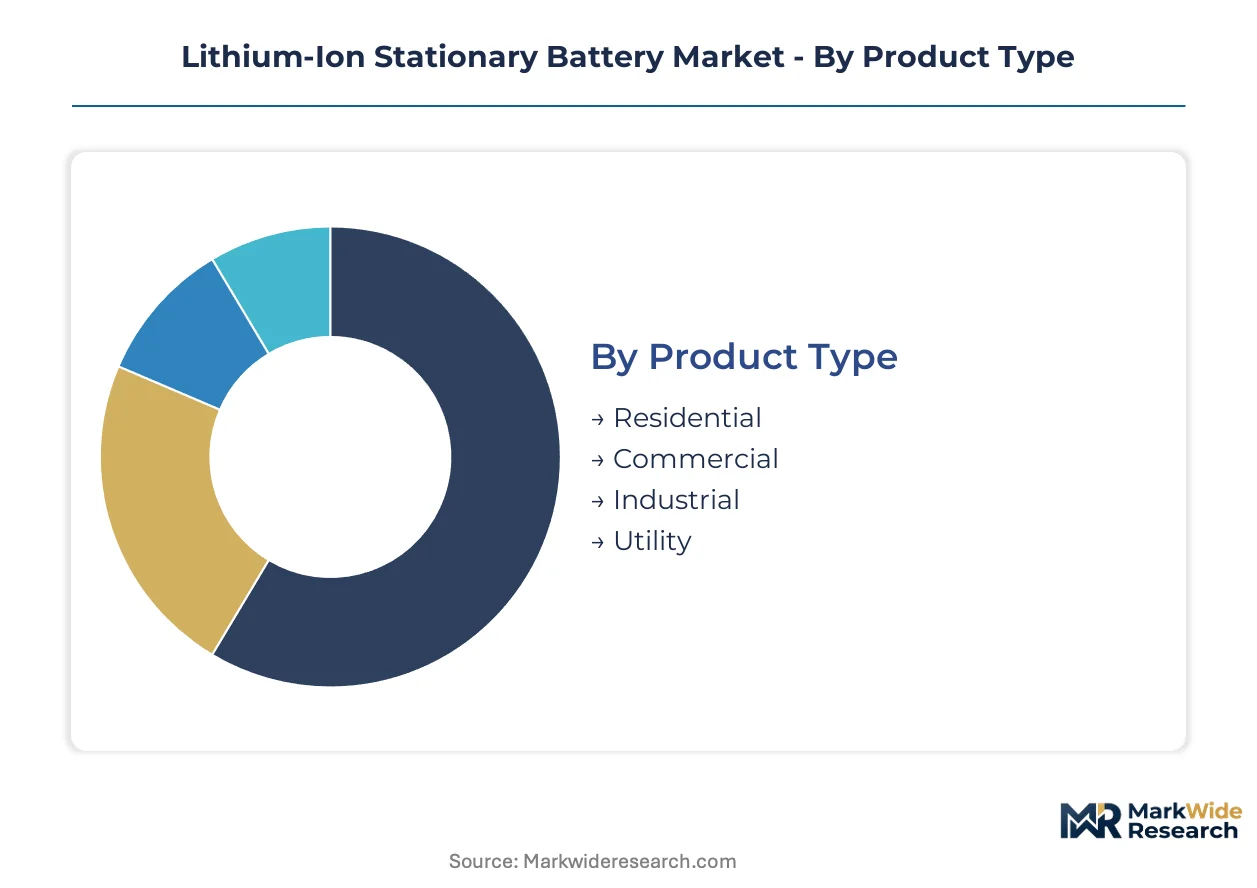
Segmentation in the Lithium-Ion Stationary Battery Market reveals how procurement patterns diverge across scale tiers and use cases. Upgrade cycles and replacement demand vary dramatically between grid-scale utilities and behind-the-meter installations, reshaping supplier priorities and channel economics.
Product Type:
Replacement cycles and capacity expansion timelines differ sharply across installation scales, with utility assets demanding 20-year service life while residential systems face 10-year upgrade horizons.
- Utility:Containerized systems exceeding 100 MWh dominate procurement volumes in Texas and California, where ERCOT and CAISO market reforms reward fast-ramping assets with preferential interconnection queue positions. Long-term power purchase agreements and tolling structures create the deepest margin pool, though 24-36 month interconnection study delays freeze capital deployment.
- Residential:Solar-plus-storage bundles drive fastest volume expansion in deregulated US retail markets, with third-party ownership structures separating hardware risk from offtake commitment. FERC Order 2222 enables aggregation into wholesale markets, creating software-layer value capture for fleet operators.
- Commercial:Behind-the-meter installations target demand charge reduction and backup power for critical facilities, with energy-as-a-service contracting displacing traditional equipment sales.
- Industrial:Megawatt-scale systems serve manufacturing facilities and process industries requiring uninterrupted power quality, with battery-as-a-service models lowering barriers for capital-constrained buyers.
Volume placements concentrate in Utility; the faster expansion belongs to Residential.
Application:
Revenue stacking potential varies by application, with multi-service assets commanding premium pricing against single-use installations.
- Energy Storage:Bulk shifting of renewable generation from off-peak to peak periods represents the foundational use case, with CAISO's resource adequacy compensation improving project economics for California deployments.
- Frequency Regulation:Fast-ramping response to grid frequency deviations commands the highest marginal revenue per MW deployed, though market saturation in Texas is compressing ancillary service prices.
- Load Shifting:Time-of-use arbitrage enables commercial and industrial users to reduce electricity costs, with economics improving as retail rate spreads widen in deregulated states.
- Backup Power:Uninterruptible supply for critical infrastructure drives healthcare and data center procurement, with NFPA 855 thermal runaway standards forcing expensive enclosure redesigns.
Energy Storage captures the largest installed base; Frequency Regulation delivers the highest revenue per megawatt-hour cycled.
Technology:
Chemistry selection trades cycle life against energy density, with thermal stability constraints driving divergence between stationary and mobility applications.
- LFP:Lithium iron phosphate cells exceed 6,000 cycles at 80% depth of discharge, eliminating thermal runaway risks that constrained earlier NMC deployments in densely populated commercial zones. LFP chemistry now leads new stationary installations as energy density carries lower priority than safety and longevity.
- NMC:Nickel-manganese-cobalt formulations retain niche presence where space constraints limit enclosure footprint, though cathode supply concentration in China exposes non-Chinese integrators to disruption.
- NCA:Nickel-cobalt-aluminum chemistry sees minimal stationary adoption due to thermal management complexity and higher material costs relative to LFP alternatives.
- LTO:Lithium-titanate oxide delivers extreme cycle life exceeding 15,000 cycles but at prohibitive cost for most grid-scale applications, finding limited use in frequency regulation services where rapid cycling is essential.
LFP dominates new capacity additions; LTO remains confined to premium cycling applications despite superior durability.
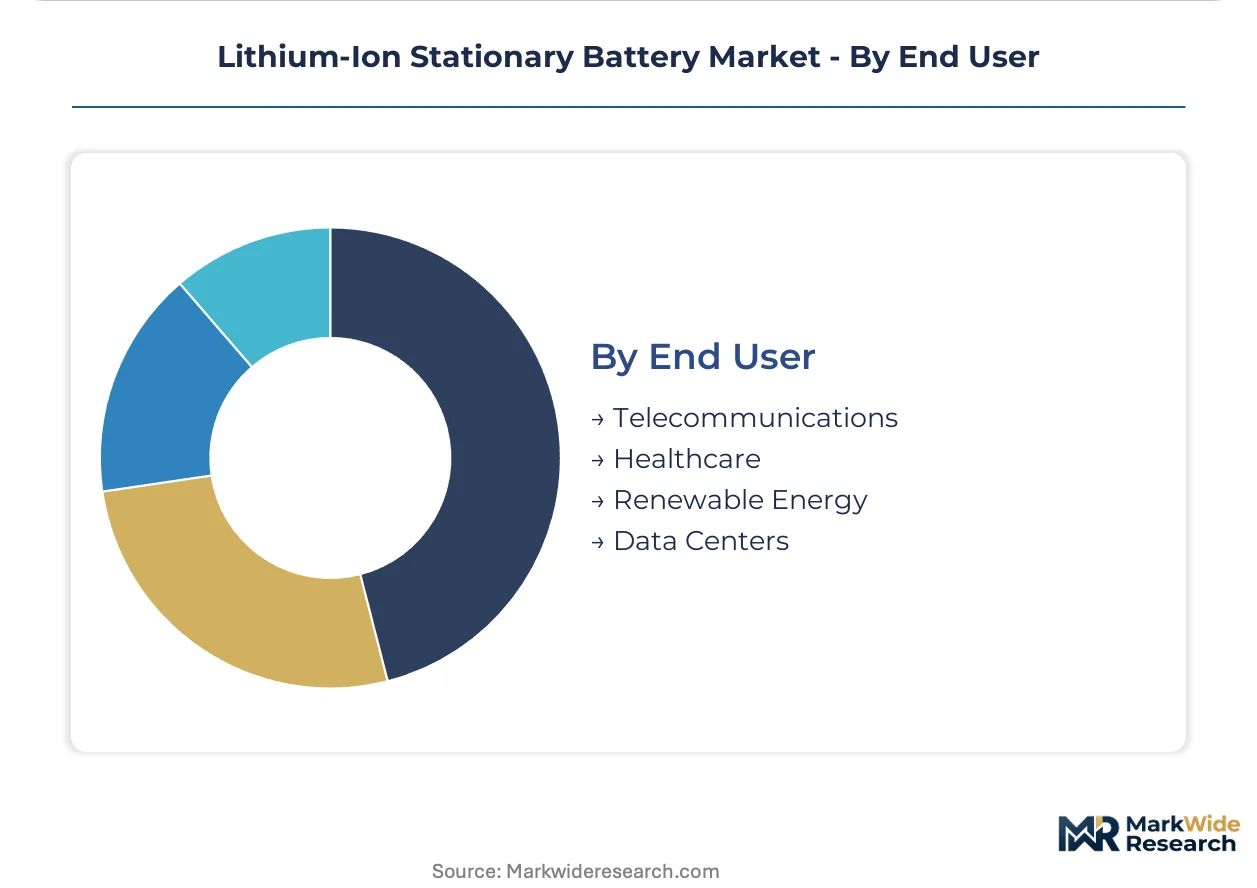
End User:
Criticality of power continuity and regulatory environment shape procurement urgency and budget authorization across verticals.
- Renewable Energy:Solar and wind developers deploy co-located storage to firm output and capture peak pricing, with the US Inflation Reduction Act's standalone storage tax credit redirecting capital toward domestic battery assembly.
- Data Centers:Hyperscale operators in Northern Virginia and Dallas-Fort Worth metroplexes procure battery systems as diesel generator replacements, driven by corporate carbon neutrality commitments and local air quality regulations.
- Telecommunications:Cell tower operators prioritize compact footprint and extreme temperature tolerance, with remote site deployments favoring modular containerized systems.
- Healthcare:Hospitals and medical facilities face stringent backup power mandates from state health departments, with life safety classification requiring redundant battery configurations and third-party certification.
Renewable Energy absorbs the greatest megawatt volume; Data Centers are climbing fastest as sustainability targets harden into procurement requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of processed lithium and cathode active materials, while the United States and Germany absorb the highest deployment volumes for grid-scale storage systems. This production-consumption divide shapes procurement strategies and supply chain risk exposure across major markets.
United States
Texas and California dominate utility-scale procurement, with ERCOT and CAISO market reforms rewarding fast-ramping storage assets with preferential interconnection queue positions. The Inflation Reduction Act's standalone storage tax credit redirects capital toward domestic battery assembly facilities. Northern Virginia and Dallas-Fort Worth hyperscale data centers are replacing diesel generators with lithium-ion systems to meet corporate carbon neutrality commitments.
China
Domestic demand surges from renewable energy developers pairing co-located storage with solar and wind projects to firm output and capture peak pricing. SAMR enforces GB standards for electrochemical energy storage safety, constraining product entry and shaping thermal runaway containment design requirements. The Yangtze River Delta and Pearl River Delta concentrate both cathode material refining and battery system manufacturing capacity.
Germany
Industrial facilities and commercial buildings drive behind-the-meter installations targeting demand charge reduction and backup power resilience. The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds for batteries placed on the European market. Bavaria and North Rhine-Westphalia host the densest clusters of manufacturing facilities integrating battery storage for power quality assurance.
Japan
Telecommunications infrastructure and precision manufacturing facilities prioritize compact footprint systems with extreme temperature tolerance. METI oversees grid interconnection standards and safety certifications for stationary storage deployment. The Kanto region around Tokyo concentrates corporate procurement for business continuity and peak shaving applications.
Australia
Remote mining operations and isolated grid communities deploy modular containerized systems to displace diesel generation and reduce fuel logistics costs. State-level renewable energy targets and grid stability programs accelerate utility-scale procurement in Queensland and South Australia. The National Electricity Market redesign creates revenue stacking opportunities for frequency regulation and arbitrage services.
Lithium-Ion Stationary Battery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the stationary battery value chain, creating a tiered market structure where scale advantages clash with agility and technical depth. The vendor base clusters around three strategic archetypes: integrated automotive-electronics conglomerates leveraging cell manufacturing scale, dedicated energy storage integrators optimizing software-hardware stacks, and industrial battery specialists with deep chemistry expertise. Competitive moves center on captive cathode supply agreements and multi-gigawatt manufacturing capacity expansion to secure offtake contracts.
Within the integrated conglomerate tier, Tesla and LG Energy Solution exemplify divergent approaches to market positioning. Tesla anchors its presence through software-defined control architectures and vertical integration from cell production through utility-scale installation. LG Energy Solution occupies a position emphasizing captive cathode supply chains and manufacturing scale across multiple geographies. BYD represents the cost-competitive archetype, extending China-based LFP production into European and Australian storage tenders through aggressive pricing and modular system bundling.
| Leading Market Players |
|---|
| Tesla |
| LG Energy Solution |
| BYD |
| CATL |
| Panasonic |
| Samsung SDI |
| Fluence Energy |
| GS Yuasa |
| SK Innovation |
| Others |
Pricing and Supply Chain Analysis
Utility-scale independent power producers in Texas and California anchor procurement volumes and enforce project-based contract pricing with multi-year offtake structures, compressing margins for integrators lacking captive cell supply.
Pricing Analysis
Cost-down pressure on containerized systems accelerates because BYD's aggressive LFP exports from China force incumbent integrators to absorb margin compression or cede market share. Pricing stratifies across premium-certified, standard-compliant, and economy-tier configurations, with UL 9540A certification and FERC interconnection qualification commanding substantial premiums. Price differentiation rests on thermal management sophistication and software stack maturity rather than raw cell cost. Commercial and industrial buyers exhibit highest price sensitivity due to shorter payback requirements, while utility offtakers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore coordinate hub-and-spoke logistics for containerized battery systems, with final assembly increasingly shifting to destination markets to satisfy local content rules. Cathode active material production concentrates in China, South Korea, and Japan, drawing from processed lithium and refined nickel feedstocks. Supply chain risk hinges on single-source vulnerability for high-purity lithium hydroxide and forced technology transfer requirements in Chinese joint venture structures. Distribution runs through EPC contractors and specialized energy storage integrators rather than traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stationary battery sector is becoming a vertical-integration race where cathode supply security and in-house cell manufacturing determine competitive survival.
For Market Incumbents: Anchor market position through captive cathode supply agreements with Australian and Chilean lithium producers, while expanding US-based assembly capacity to capture IRA tax credit benefits. Sodium-ion substitution threats from emerging Chinese producers demand accelerated LFP cost curves and software-layer differentiation to defend margin pools. For New Entrants and Emerging Players: FERC Order 2222 in the United States opens a window for distributed storage aggregation software plays, targeting residential and commercial fleet operators in deregulated ERCOT and PJM territories. Virtual power plant orchestration and dynamic tariff optimization represent the most penetrable white space, with battery-as-a-service contracting as the preferred go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors pure-play software-defined storage integrators with demonstrated CAISO or ERCOT market participation. Long-term viability requires exposure to multiple revenue stacking opportunities rather than single-service arbitrage. Watch for interconnection queue reform timelines as the critical inflection signal for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Supply Integration | Captive lithium hydroxide offtake from Australian spodumene producers secures margin control against Chinese refining concentration. |
| Domestic Assembly Expansion | US-based gigafactory investments unlock IRA standalone storage tax credits and accelerate interconnection queue positioning. |
| Software Stack Acquisition | Predictive analytics and automated dispatch platforms maximize arbitrage revenue in CAISO's resource adequacy markets. |
| Thermal Management Certification | UL 9540A third-party validation enables premium pricing in densely populated urban commercial zones. |
| Virtual Power Plant Platform | FERC Order 2222 aggregation software captures wholesale market participation value from distributed residential fleets. |
Research Methodology
Regulatory filings from FERC, SAMR, and METI, alongside project development databases and customs trade records, formed the secondary backbone for supply chain and deployment tracking. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators supplied operational validation, with bottom-up installation counts triangulated against top-down cathode material demand estimates.
Historical trendline analysis of utility-scale procurement cycles and residential solar-plus-storage attachment rates informed the projection framework across the analysis window. Segmentation modeling incorporated product scale tier, application revenue stack, chemistry type, and regional regulatory cluster dimensions. CAGRs derived from capacity-weighted average deployment velocities and manufacturing expansion announcements, with interconnection queue depth and IRA incentive phase-out schedules as key forecast inputs.
Caveats apply where interconnection study delays, cathode supply disruption, or NFPA 855 retrofit mandates could materially shift the outlook beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market