
 Rotary Blasthole Drilling Rig Market | 2026-2036
Rotary Blasthole Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Blasthole Drilling Rig Market Intelligence
The end-user base for rotary blasthole drilling rigs is consolidating among a smaller number of large, multinational mining companies. Caterpillar Inc. leverages its extensive global distribution and service network to support these major operators. Sandvik AB differentiates with a portfolio centered on automation and remote operation capabilities. Komatsu Ltd. sustains its market position through a focus on equipment reliability and integrated fleet management solutions.
A rotary blasthole drilling rig is a heavy-duty machine designed to create holes in rock for the placement of explosives in mining and quarrying. These rigs utilize a combination of high rotational force and downward pressure, or pulldown, to power a drill bit through hard geological formations. Within technology segments, automated control systems are becoming standard on new models, while remote monitoring capabilities command a premium. Mining excavation remains the dominant application, with quarrying operations representing a significant secondary market.
Equipment operation is governed by safety standards from bodies like the US Occupational Safety and Health Administration (OSHA) and requirements for CE marking in Europe. Engine selection is shaped by emissions rules from the EPA and equivalent agencies, impacting powertrain design. Stakeholder decisions must balance the capital expense of new rigs against the operational savings from advanced automation and remote control features.
Market Dynamics
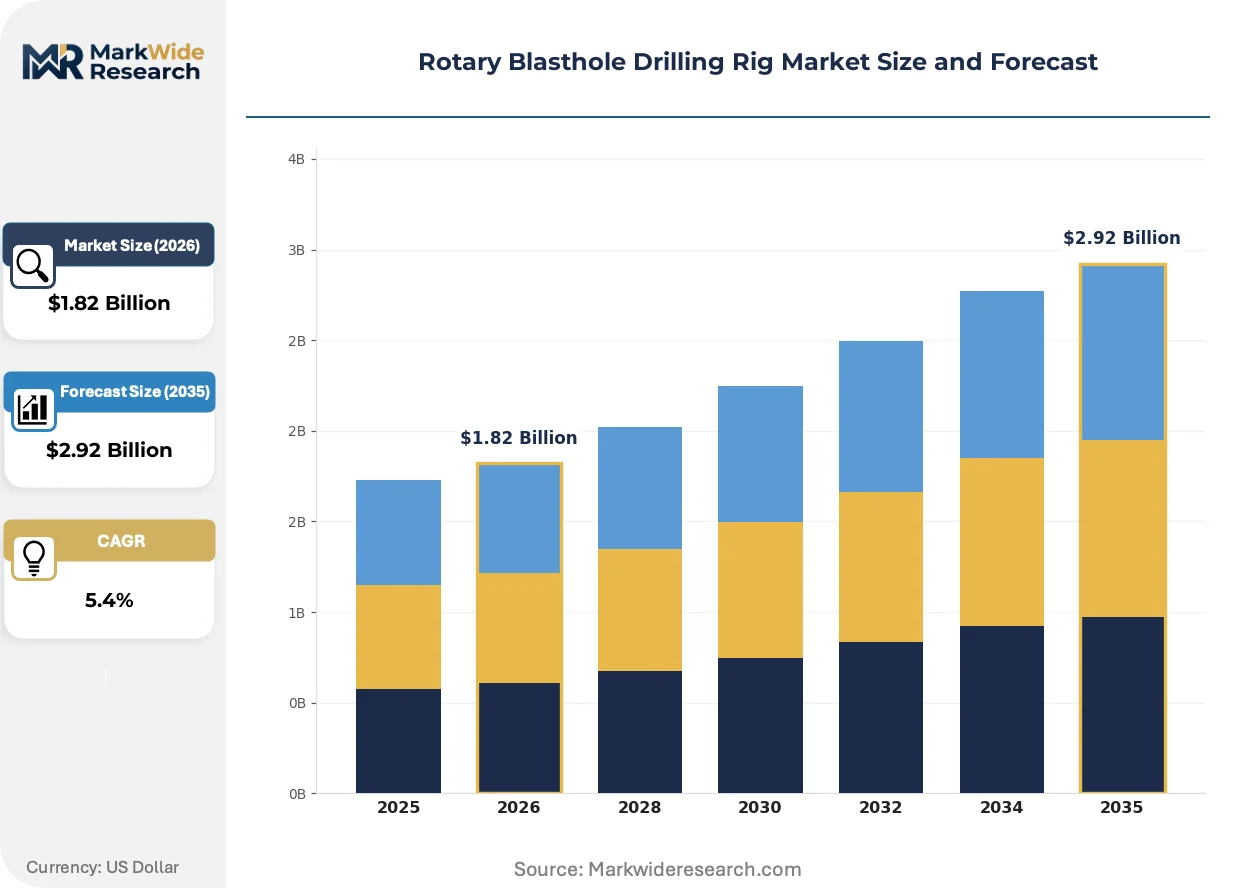
The market's central dynamic is the tension between high capital outlay for new rigs and the operational savings from automation. Demand for critical minerals forces operators to prioritize long-term productivity, reshaping procurement decisions around total cost of ownership.
Growth Catalysts
- Critical Mineral Demand:The energy transition accelerates excavation for minerals like lithium and copper, expanding the need for rigs in large-scale mining.
- Automation Integration:Automated control systems enhance operational safety and drilling precision, attracting investment from operators seeking productivity gains.
- Regulatory Fleet Turnover:Mandates from the EPA and OSHA in the US, plus CE marking in Europe, compel operators to upgrade aging fleets to safer, compliant rigs.
Market Restraints
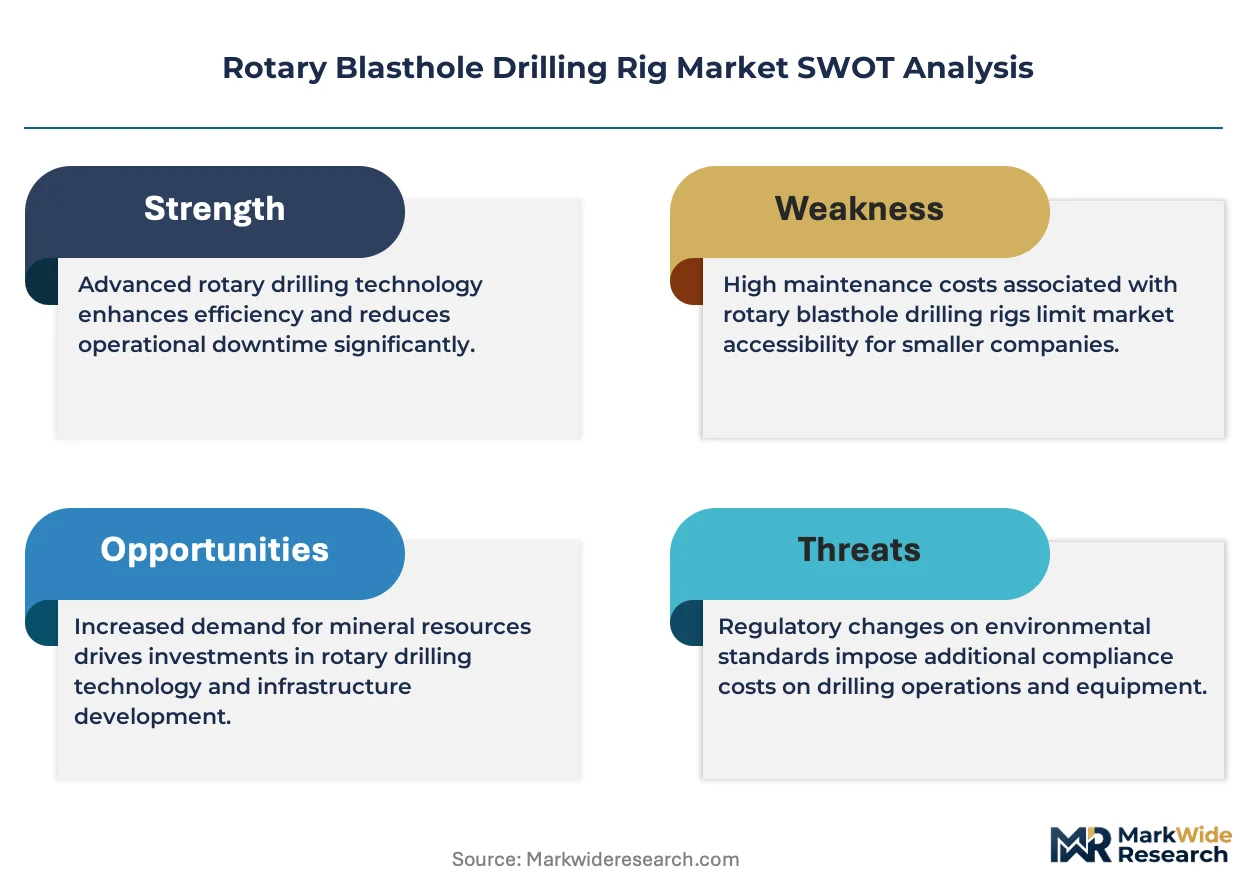
- Intense Capital Outlay:The high upfront investment for new rigs restricts acquisition for smaller operators, slowing fleet modernization.
- Component Supply Concentration:Supply of critical parts like high-torque rotary heads is concentrated, creating vulnerability to geopolitical disruption and price volatility.
- Legacy System Integration:Integrating new automated rigs with older mine fleet management software presents significant technical hurdles and slows adoption.
Strategic Opportunities
- New Mining Frontiers:Expansion into developing mining markets in Africa offers growth as new large-scale extraction projects receive funding.
- Automation Retrofit Services:Developing modular automation upgrade kits for the large installed base of older rigs creates a significant after-sales service opportunity.
- Alternative Powertrain Development:Investing in battery-electric rigs addresses operator demand for equipment meeting ESG targets and stringent emissions regulations.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians for complex automated drilling systems hampers the realization of promised efficiency gains.
- Cybersecurity Vulnerabilities:Rig connectivity for remote operation exposes mining companies to new cyber-attacks, requiring investment in digital security.
- Interoperability Barriers:A lack of data protocol standardization among OEMs hinders the integration of mixed fleets, preventing seamless mine-wide automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Blasthole Drilling Rig Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Drive, Rotary Table, Hydraulic, Electric, Pneumatic Technology: Automated Control, Remote Monitoring, Cable Deployed, Track Mounted, Self-Propelled Application: Mining Excavation, Quarrying Operations, Construction Site Preparation, Geothermal Drilling, Exploration Projects End User: Mining Companies, Infrastructure Developers, Energy Firms, Geological Survey Agencies |
| Companies Covered | Komatsu Ltd., Bauer AG, Caterpillar Inc., Furukawa Rock Drill Co. Ltd., Schramm Inc., Sandvik AB, Atlas Copco, Nanchang Kamach Mining Co. Ltd., Epiroc AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Blasthole Drilling Rig Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from pure mechanical force to data-driven operational intelligence. This transition prioritizes drilling precision, autonomous decision-making, and powertrain decarbonization, fundamentally altering equipment design and value propositions.
Digital twin technology creates a virtual replica of the drilling environment and rig performance. Major mining operators are adopting these platforms to simulate blast outcomes and predict component wear before committing physical assets. This software-driven planning is absorbing functions previously dependent on operator intuition and costly trial-and-error, increasing operational predictability.
European Union regulations like the Corporate Sustainability Reporting Directive (CSRD) mandate extensive environmental impact disclosure. This forces mining operators to track and report emissions from their entire equipment fleet, including drilling rigs. The powertrain segment is most affected, creating demand for rigs with telematics for emissions monitoring and a pull for future electric models.
A notable shift in procurement involves the move toward performance-based service contracts, away from simple asset sales. Under this model, mining companies pay for guaranteed uptime or per meter drilled, transferring maintenance and reliability risk to the equipment manufacturer. This trend is most prominent in Australia's high-volume iron ore sector, where predictable operational costs are critical.
Rotary Blasthole Drilling Rig Market Segmentation
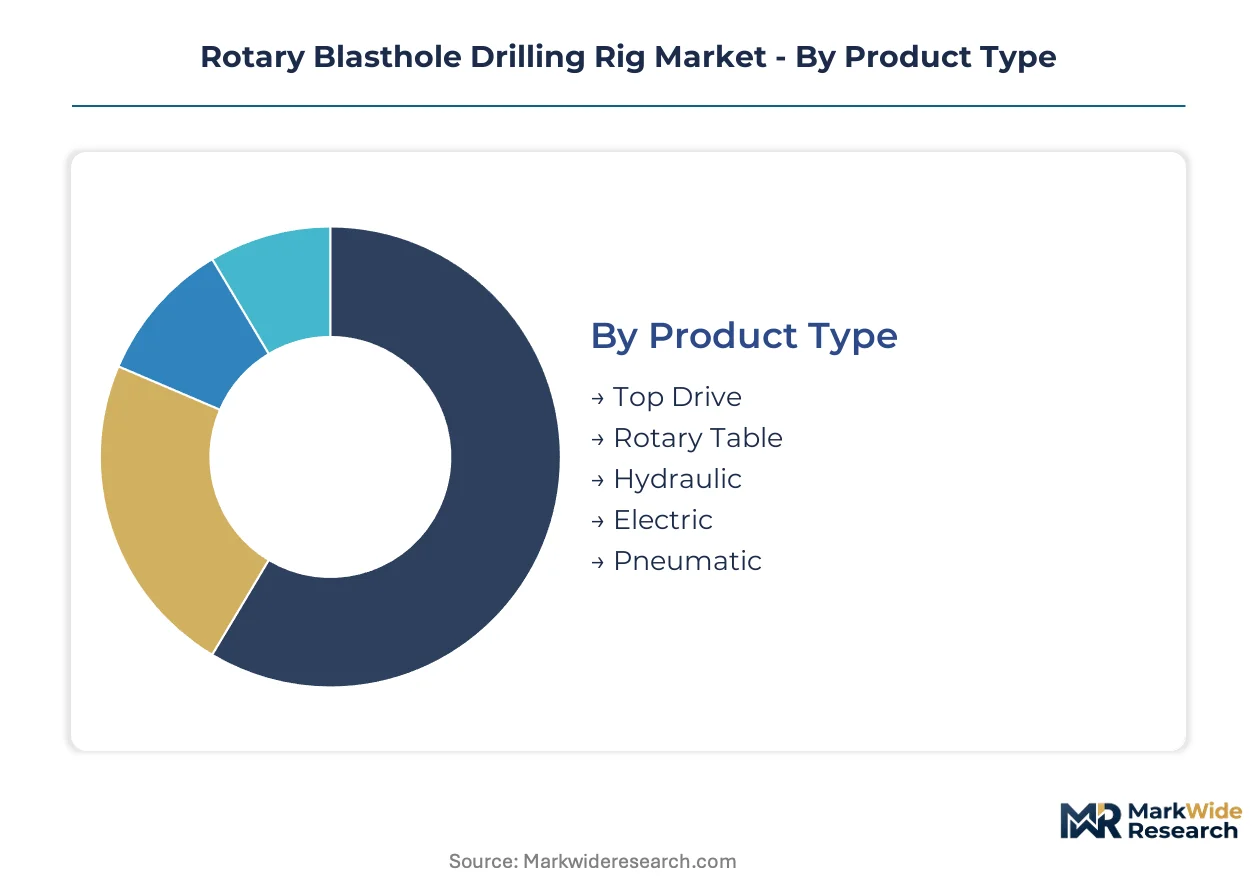
The Rotary Blasthole Drilling Rig market is segmented across critical dimensions including product type, underlying technology, primary application, and diverse end-user profiles. Understanding these segments clarifies the varying operational demands and technological preferences shaping procurement decisions across the industry.
Product Type:
The product type segmentation highlights the split between established mechanical designs and newer, more sophisticated power delivery systems for rotary blasthole drilling rigs.
- Top Drive:These rigs feature a motor mounted at the top of the drill string, providing direct rotational power and precise control over drilling parameters. Demand for top drive systems is concentrating in Australia's large-scale iron ore mines, driven by the need for high penetration rates in hard rock formations.
- Rotary Table:Rotary table rigs transmit power from a motor to the drill string via a rotating table on the rig floor, a foundational design known for its robust mechanical simplicity.
- Hydraulic:Hydraulic rigs utilize fluid power to generate both rotational torque and pulldown force, offering robust performance and fine-tuned control in varied geological conditions. These systems are critical for mining operations in South Africa, where their adaptability supports diverse mineral extraction projects.
- Electric:Electric rigs use electric motors for power, offering lower emissions and reduced noise, aligning with stricter environmental regulations and ESG targets.
- Pneumatic:Pneumatic rigs employ compressed air to power drilling mechanisms, often used in smaller-scale operations or specific geological conditions requiring percussive action.
Mature deployment sits with Rotary Table designs. Newer deployment is concentrated in Electric and Hydraulic rigs.
Technology:
Technology segmentation reveals the operational impact of advanced systems versus traditional mechanical configurations within the drilling rig market.
- Automated Control:These systems integrate sensors, software, and actuators to manage drilling parameters, optimizing penetration rates and ensuring consistent blast hole quality. Investment in automated control is accelerating in Canadian oil sands operations, driven by safety mandates and efficiency goals.
- Remote Monitoring:Telematics and IoT platforms enable real-time data collection on rig performance, health, and location, facilitating predictive maintenance and operational oversight. This technology is gaining traction among major mining companies globally, seeking to reduce downtime and improve asset utilization.
- Cable Deployed:Cable deployed systems refer to rigs where the drilling mechanism is lowered and operated via cables, typically for specific underground or difficult-to-access applications.
- Track Mounted:Track mounted rigs utilize continuous tracks for mobility, providing stability and excellent traction across rugged and uneven mining terrain.
- Self-Propelled:Self-propelled rigs integrate their own propulsion system, allowing them to move independently between drilling sites without requiring external towing.
The Cable Deployed segment exhibits stable deployment. Automated Control and Remote Monitoring technologies are expanding most quickly.
Application:
Application segmentation illustrates the primary end-use sectors driving demand for rotary blasthole drilling rigs, reflecting varying operational scales and geological challenges.
- Mining Excavation:This segment represents the largest application, involving the drilling of blastholes for the extraction of vast quantities of ore and overburden in open-pit mines. Demand is particularly strong in the copper mines of Chile, where large-scale operations require continuous, high-volume drilling.
- Quarrying Operations:Rigs in this segment create holes for rock fragmentation in quarries, supplying aggregates and construction materials. This application is significant across European markets, supporting infrastructure development and urban expansion projects.
- Construction Site Preparation:Rigs are utilized for drilling in large construction projects, preparing sites for foundations, roads, and other heavy infrastructure.
- Geothermal Drilling:This specialized application involves drilling deep holes to tap into geothermal energy sources for power generation or heating.
- Exploration Projects:Rigs for exploration are used to drill core samples and gather geological data, identifying potential new mineral deposits.
Construction Site Preparation maintains a consistent demand. Geothermal Drilling and Exploration Projects exhibit the steepest expansion trajectory.
End User:
End-user segmentation differentiates market demand based on the core business objectives and operational requirements of various industry stakeholders.
- Mining Companies:These entities represent the largest procurement group, investing in rigs for continuous, high-volume extraction of minerals and resources. Global mining majors like Rio Tinto and BHP drive significant purchasing decisions, prioritizing reliability and advanced automation features for their vast operations.
- Infrastructure Developers:This segment acquires rigs for large-scale earthmoving, road construction, and foundation work, requiring robust equipment for site preparation. Demand from infrastructure developers is notable in India, supporting extensive national highway and urban development projects.
- Energy Firms:Energy firms use rotary blasthole rigs for specific applications in the oil and gas sector or for preparing sites for energy infrastructure.
- Geological Survey Agencies:These governmental or research bodies utilize rigs for scientific exploration, mapping, and resource assessment.
Geological Survey Agencies maintain specialized procurement. Energy Firms and Infrastructure Developers are climbing the fastest in terms of new rig acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's extensive iron ore and coal sectors anchor significant demand for rotary blasthole drilling rigs. Large-scale mining excavation projects across the continent drive continuous procurement decisions. Operators prioritize equipment that enhances productivity and meets stringent environmental standards.
Australia
Demand for high penetration rates in hard rock formations drives top drive rig sales in Australia. The country's Mining Act 1992 governs operational safety and environmental compliance. Western Australia's Pilbara region concentrates iron ore extraction, propelling investment in advanced drilling technology.
Chile
Chile's vast copper mines require continuous, high-volume drilling for efficient ore extraction. The nation's Environmental Impact Assessment System (SEIA) mandates rigorous environmental controls for mining projects. The Antofagasta region, a major copper production hub, sees substantial investment in large-scale drilling fleets.
Canada
Oil sands operations and mineral extraction projects across Canada generate demand for automated control systems. Health Canada and provincial regulations emphasize safety protocols for heavy machinery in harsh environments. Alberta's oil sands region drives investment in efficiency-enhancing drilling solutions for resource recovery.
South Africa
Diverse mineral extraction projects in South Africa necessitate robust hydraulic rigs for varied geological conditions. The Mineral and Petroleum Resources Development Act (MPRDA) regulates mining operations and equipment standards. The Bushveld Igneous Complex, rich in platinum group metals, experiences consistent demand for adaptable drilling equipment.
United States
Mining excavation and quarrying operations across the United States sustain demand for reliable drilling rigs. OSHA standards dictate strict safety requirements for heavy equipment in construction and mining. Nevada's gold mining industry, a major sector, continuously upgrades fleets to meet production targets.
Rotary Blasthole Drilling Rig Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue automation and alternative powertrain development. The market structure exhibits consolidation among a few large multinational players, alongside specialized regional manufacturers. Strategic archetypes include integrated solution providers, technology innovators, and robust equipment suppliers. Companies often engage in strategic partnerships to expand their service networks and pursue portfolio diversification into advanced features.
Within the integrated solution provider archetype, Caterpillar Inc. leverages its extensive global distribution network to support major operators across diverse geographies. Sandvik AB exemplifies a technology innovator, differentiating its portfolio with advanced automation and remote operation capabilities designed for enhanced safety and drilling precision. Komatsu Ltd. sits within the robust equipment supplier category, sustaining its market position through a focus on equipment reliability and integrated fleet management solutions tailored for demanding mining environments. These companies collectively influence technological advancements and market standards.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Bauer AG |
| Caterpillar Inc. |
| Furukawa Rock Drill Co. Ltd. |
| Schramm Inc. |
| Sandvik AB |
| Atlas Copco |
| Nanchang Kamach Mining Co. Ltd. |
| Epiroc AB |
| Others |
Cost & Logistics Intelligence
Performance-based service contracts are reshaping cost economics for rotary blasthole drilling rigs, simultaneously influencing how manufacturers manage specialized component supply. This shift transfers maintenance and reliability risk to equipment producers.
Pricing Analysis
Service contracts bundled with guaranteed uptime or per meter drilled define the primary pricing model for rotary blasthole drilling rigs. Price differentiation stems from advanced automation features and the rig's capacity for high penetration rates in hard rock formations. Pricing softness reflects intense competition among major OEMs for large-scale mining projects. Global mining majors exhibit lower price sensitivity, prioritizing total cost of ownership and consistent operational output.
Supply Chain Analysis
Dual-sourcing requirements for critical components like high-torque rotary heads are becoming more common among large mining operators, diversifying supply. Geographic supply concentration for these specialized parts often centers in industrial manufacturing hubs like Germany and Japan. Dependencies include advanced electric motors and automated control system modules, creating vulnerability to geopolitical disruption. Distribution runs through established global OEM networks and specialized regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotary blasthole drilling rig market operates as a supply-constrained environment, where the concentrated supply of critical components like high-torque rotary heads props up equipment pricing. This dynamic influences procurement strategies and long-term investment decisions.
For Market Incumbents:Deploy advanced automation R&D to maintain technological leadership against emerging threats from specialized tech firms focusing on AI-driven drilling optimization. Integrate digital twin capabilities deeper into existing fleet management solutions to enhance predictive maintenance offerings, insulating against operational downtime. Expand after-sales service networks, particularly for modular automation retrofit kits, to capture revenue from the large installed base of older rigs.
For New Entrants and Emerging Players:Battery-electric powertrain development offers a technology-first wedge for new entrants into the rotary blasthole drilling rig market. Target underpenetrated segments like geothermal drilling and exploration projects, where lower emissions and noise profiles command a premium. A go-to-market angle involves offering flexible leasing models tied to ESG performance metrics, appealing to operators with strict environmental targets.
For Investors and Strategic Acquirers:Exit pathways concentrate in strategic acquisitions by major OEMs seeking to integrate specialized automation or alternative powertrain technologies. Long-term viability hinges on companies with proven intellectual property in advanced control systems and electrification, particularly those addressing interoperability barriers. The signal to watch is the increasing number of pilot projects for fully autonomous drilling operations in major mining regions like Australia.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Automation Retrofit Services | Captures aftermarket revenue from legacy fleets and extends asset life for mining companies. |
| Invest in Battery-Electric Rig R&D | Addresses ESG targets and stringent emissions regulations, attracting environmentally conscious operators. |
| Standardize Data Protocols for Rigs | Facilitates seamless integration of mixed fleets, enhancing mine-wide automation and efficiency. |
| Strengthen Component Supply Chains | Mitigates geopolitical risks and price volatility for critical high-torque rotary heads. |
| Develop Digital Twin Simulation Platforms | Increases operational predictability and optimizes blast outcomes for major mining operators. |
Research Approach
Industry association reports, regulatory filings from EPA and OSHA, and OEM technical specifications formed the secondary backbone of this analysis. This was complemented by primary interviews with mining company executives, rig operators, OEM engineers, and component suppliers. Insights from these discussions were triangulated with secondary data, employing both bottom-up and top-down approaches to validate market sizing.
Historical trendline analysis provided the foundation for projecting market expansion across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user profiles, alongside critical mineral demand. Compound annual growth rates were derived from projected shifts in procurement patterns and regulatory compliance timelines. Automation adoption rates served as a key industry-specific forecast input.
Several conditions sit outside the modeled scope, including major geopolitical conflicts and unforeseen material science breakthroughs. Forecasts reflect assumptions regarding stable regulatory environments and sustained capital expenditure by mining firms. Deviation in global commodity prices would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
Broaching Machine Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Concrete Testers Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Global Crane Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market