
 Trailer Winch Market | 2026-2036
Trailer Winch Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Winch Market Analytics
Boat trailer applications is broadening as coastal recreation participation climbs and marina infrastructure expands across Florida and the Carolinas. WARN Industries leverages its heritage in off-road recovery systems to sustain brand authority in heavy-duty marine loading scenarios. Superwinch anchors its position through dedicated R&D in sealed-motor architectures that resist saltwater corrosion.
A trailer winch is a mechanical device mounted to a trailer frame to pull, load, or secure cargo through drum-spooled cable or synthetic rope, typically rated by line pull capacity from 1,500 to 15,000 pounds and powered by electric motors, hydraulic systems, or manual cranks. Electric winches dominate OEM supply agreements due to cleaner integration with vehicle electrical systems and reduced maintenance versus hydraulic alternatives. Hand winches retain share in price-sensitive utility segments where power access remains unreliable. Construction trailers represent the fastest-growing application dimension as equipment rental fleets expand self-loading capabilities.
FCC oversight of wireless remote accessories and NHTSA trailer lighting and braking standards shape product compliance pathways for manufacturers selling into the US market. EPA small-engine emissions regulations are accelerating electric motor substitution for gasoline-powered hydraulic pump units. Stakeholders must weigh motor efficiency trajectories against sealed-housing cost premiums when configuring next-generation product lines.
Market Dynamics
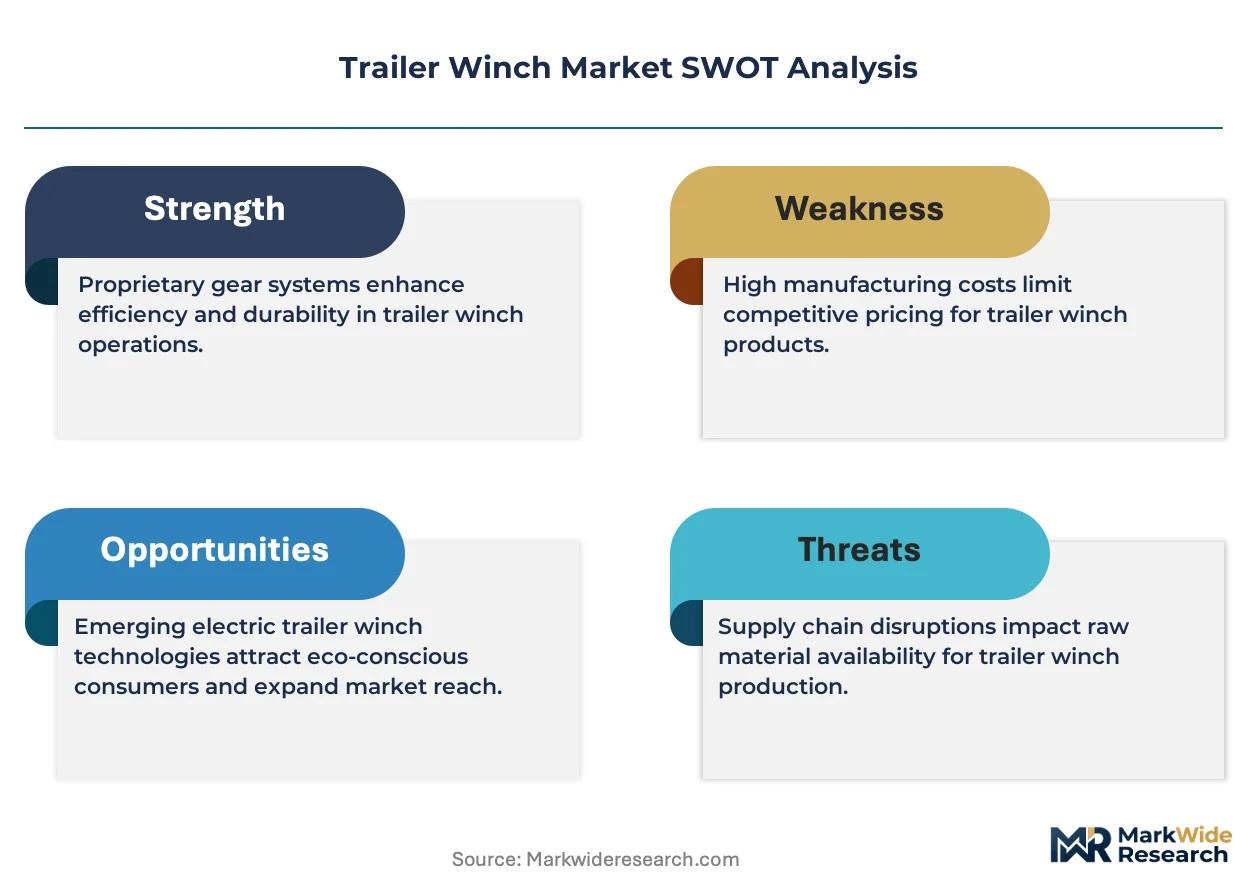
EPA small-engine emissions regulations are compressing gasoline-powered hydraulic pump demand while accelerating sealed electric motor architectures across marine and utility trailer segments.
Growth Catalysts
- Marina infrastructure expansion:Coastal municipalities in Florida and the Carolinas are allocating public funds to boat ramp modernization, directly lifting winch procurement from commercial trailer operators serving recreational boating.
- REACH substance restrictions:European chemical regulations on hexavalent chromium coatings are pushing manufacturers toward zinc-nickel plating systems that extend drum corrosion resistance in saltwater environments.
- Sealed motor IP ratings:Advances in IP68-rated housings are enabling electric winch deployment in submerged loading scenarios previously restricted to hydraulic systems.
Market Restraints
- Copper and rare-earth magnet costs:Electric motor supply chains face input price volatility from concentrated Chinese rare-earth processing and Chilean copper concentrate markets.
- NHTSA trailer lighting integration:Federal braking and lighting standards create compliance friction for wireless remote accessory manufacturers seeking streamlined type approval.
- Manual crank persistence:Hand winches retain cost advantage in developing utility segments where electrical infrastructure reliability remains inconsistent.
Strategic Opportunities
- Equipment rental fleet self-loading:Construction equipment rental operators are retrofitting trailers with integrated winch systems to reduce third-party loading dependencies.
- IRA clean energy incentives:US domestic manufacturing credits for electric motor production are attracting assembly investment away from offshore hydraulic pump sourcing.
- Synthetic rope substitution:Ultra-high-molecular-weight polyethylene cable is displacing steel wire in weight-sensitive recreational applications, opening aftermarket upgrade revenue.
Industry Challenges
- FCC Part 15 certification timelines:Wireless remote control manufacturers face extended approval cycles for radio frequency devices, delaying product launch schedules.
- Legacy hydraulic system integration:Fleet operators with existing gasoline pump infrastructure confront capital intensity in full electric conversion versus hybrid retrofit paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Winch Market |
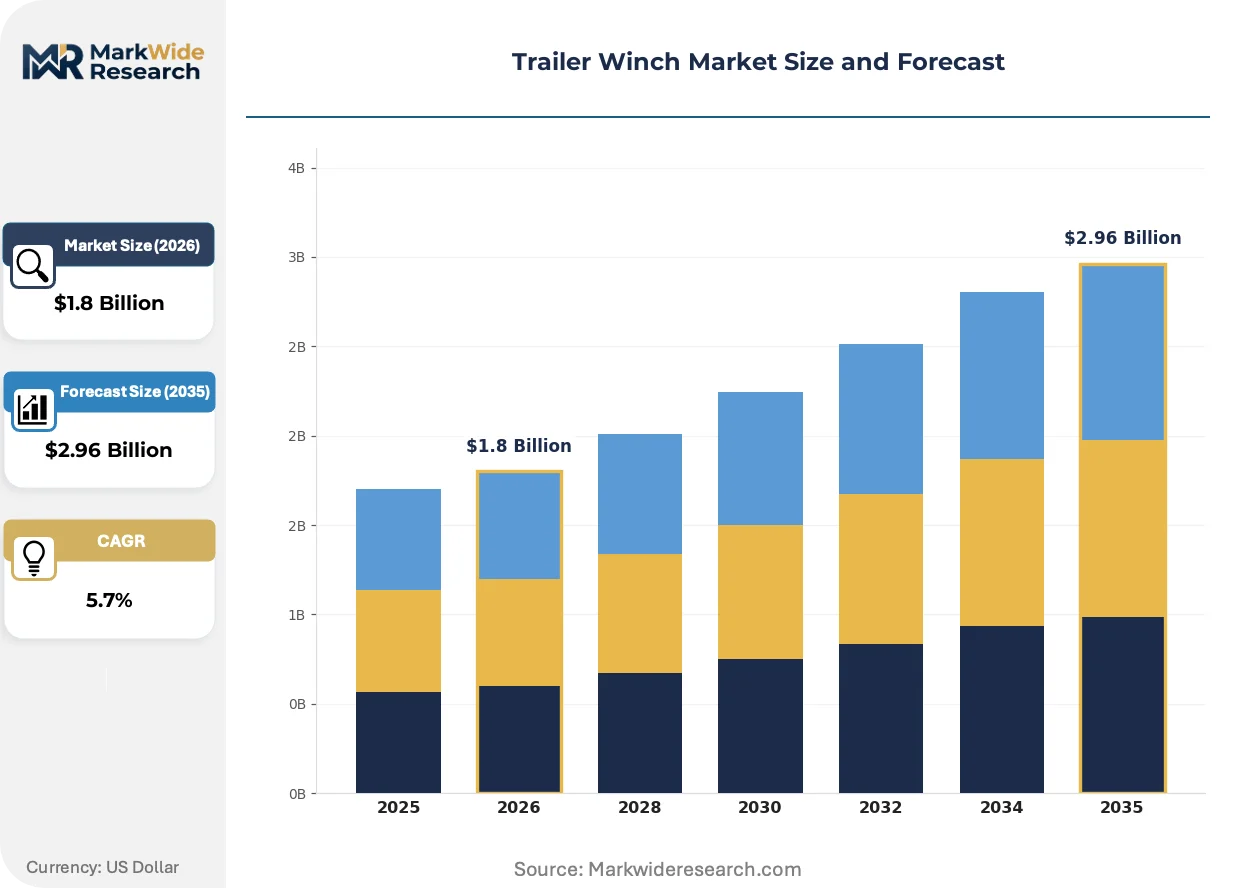
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Winches, Hydraulic Winches, Hand Winches, Pneumatic Winches Application: Boat Trailers, Car Trailers, RVs, Construction Trailers End User: Commercial Users, Individual Users, Rental Companies, Government Agencies Installation Type: Fixed Mount, Portable, Modular, Custom Installations |
| Companies Covered | WARN Industries, Superwinch, Ramsey Winch, Fulton, Dutton-Lainson Company, Powerwinch, COMEUP Industries, Westin Automotive, Smittybilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Winch Market Evolving Landscape
Product development trajectories center on corrosion-resistant architectures, regulatory-aligned powertrain transitions, and procurement model compression across fragmented end-use bases.
Synthetic rope technology is rewriting load-handling specifications in recreational marine trailers. Saltwater boat operators are adopting Dyneema-based lines at accelerating rates, drawn by weight reduction and handling safety. This material transition is compressing steel cable aftermarket revenue while expanding premium winch configuration attach rates.
EPA Phase 3 small-engine standards are forcing gasoline hydraulic pump redesigns or outright replacement. Manufacturers serving the US market are reallocating R&D toward brushless DC motor integration to maintain product line viability. Marine trailer OEMs are responding with exclusive electric winch supply agreements that lock out gasoline alternatives from new platform designs.
Fleet procurement consolidation is concentrating buying power among national equipment rental operators. Regional distributors are losing volume to direct manufacturer contracts, compressing wholesale margin structures. This channel shift is most visible in the southeastern United States, where construction rental fleet expansion is synchronizing with coastal marine demand clusters.
Trailer Winch Market Segmentation
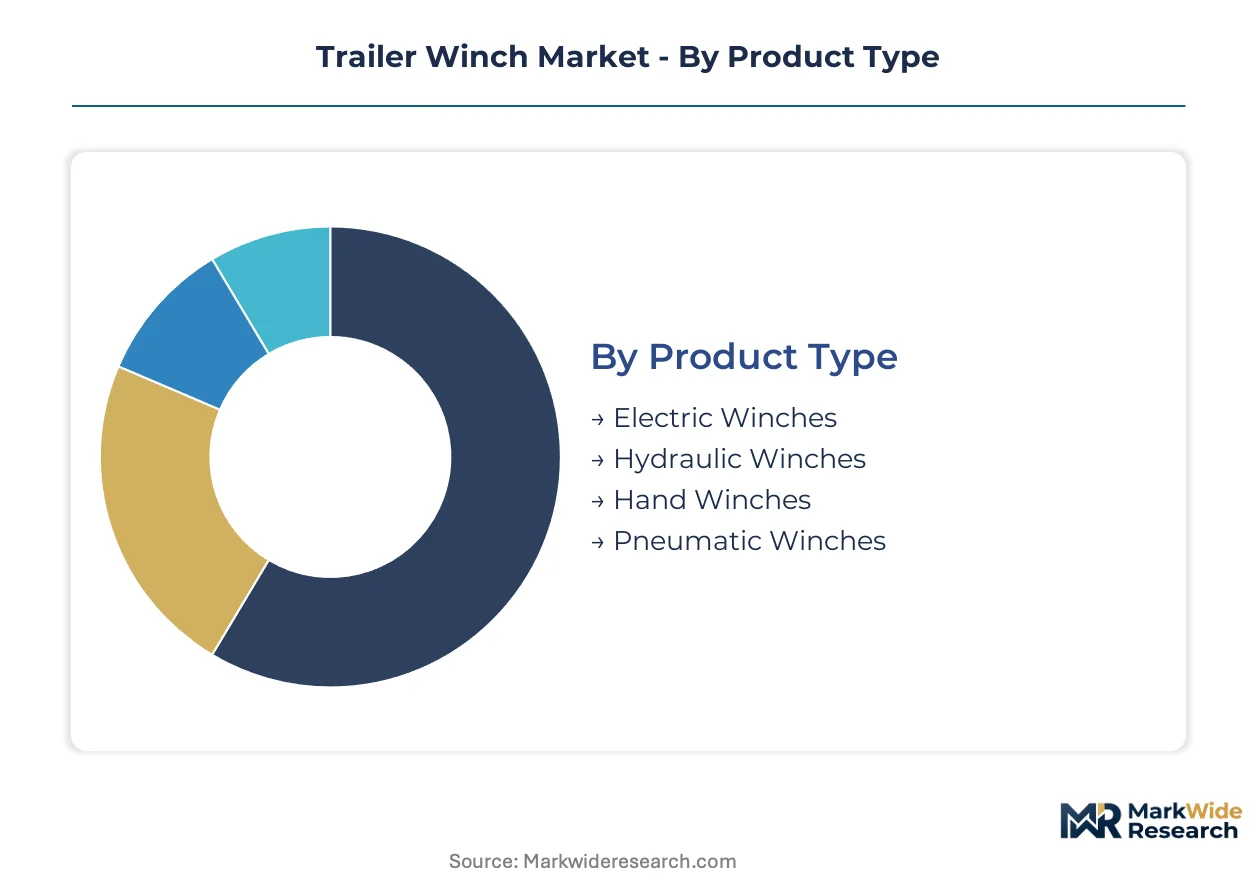
Trailer winch procurement patterns diverge sharply across powertrain technologies, trailer configurations, and operator scale. Each segmentation axis reveals distinct margin structures, regulatory exposure, and channel access requirements that shape supplier positioning.
Product Type:
Powertrain architecture determines compliance pathways, maintenance profiles, and integration complexity with host vehicle systems.
- Electric Winches:Brushless DC motors with sealed IP68-rated housings integrate directly with vehicle electrical architectures. EPA Phase 3 small-engine standards are accelerating OEM procurement from marine trailer manufacturers in Florida and the Carolinas.
- Hydraulic Winches:Gasoline-powered pump units retain share in heavy-duty construction applications where sustained high-load operation exceeds battery duty cycles. Fleet operators confront capital intensity in full electric conversion versus hybrid retrofit paths.
- Hand Winches:Manual crank mechanisms serve price-sensitive utility segments where electrical infrastructure reliability remains inconsistent.
- Pneumatic Winches:Compressed-air systems occupy niche industrial trailer applications with existing shop air availability.
Electric winches lead on scale; hydraulic winches lead on momentum in heavy-duty displacement.
Application:
Trailer payload characteristics dictate line pull ratings, corrosion protection specifications, and duty cycle requirements.
- Boat Trailers:Saltwater immersion demands zinc-nickel plated drums and synthetic rope compatibility. Marina infrastructure expansion across Florida and the Carolinas is lifting procurement volumes from commercial operators serving recreational boating.
- Construction Trailers:Equipment rental fleets are retrofitting self-loading capabilities to reduce third-party dependencies. This segment is gaining share fastest among application categories.
- Car Trailers:Enclosed and open auto transport configurations prioritize compact winch footprints and wireless remote integration.
- RVs:Weight-sensitive recreational applications favor aluminum housing constructions and low-amperage motor designs.
Boat trailers lead on scale; construction trailers lead on momentum.
End User:
Procurement authority and volume concentration vary dramatically across operator categories, reshaping channel economics.
- Commercial Users:Fleet operators with centralized maintenance facilities negotiate direct manufacturer contracts, compressing distributor margins.
- Rental Companies:National equipment rental chains are consolidating buying power and standardizing winch specifications across regional fleets.
- Individual Users:Recreational boaters and hobbyist haulers purchase through marine retail channels with high aftermarket attachment rates.
- Government Agencies:Municipal public works departments specify domestic assembly and Buy America compliance for infrastructure trailer deployments.
Commercial users lead on scale; rental companies lead on momentum.
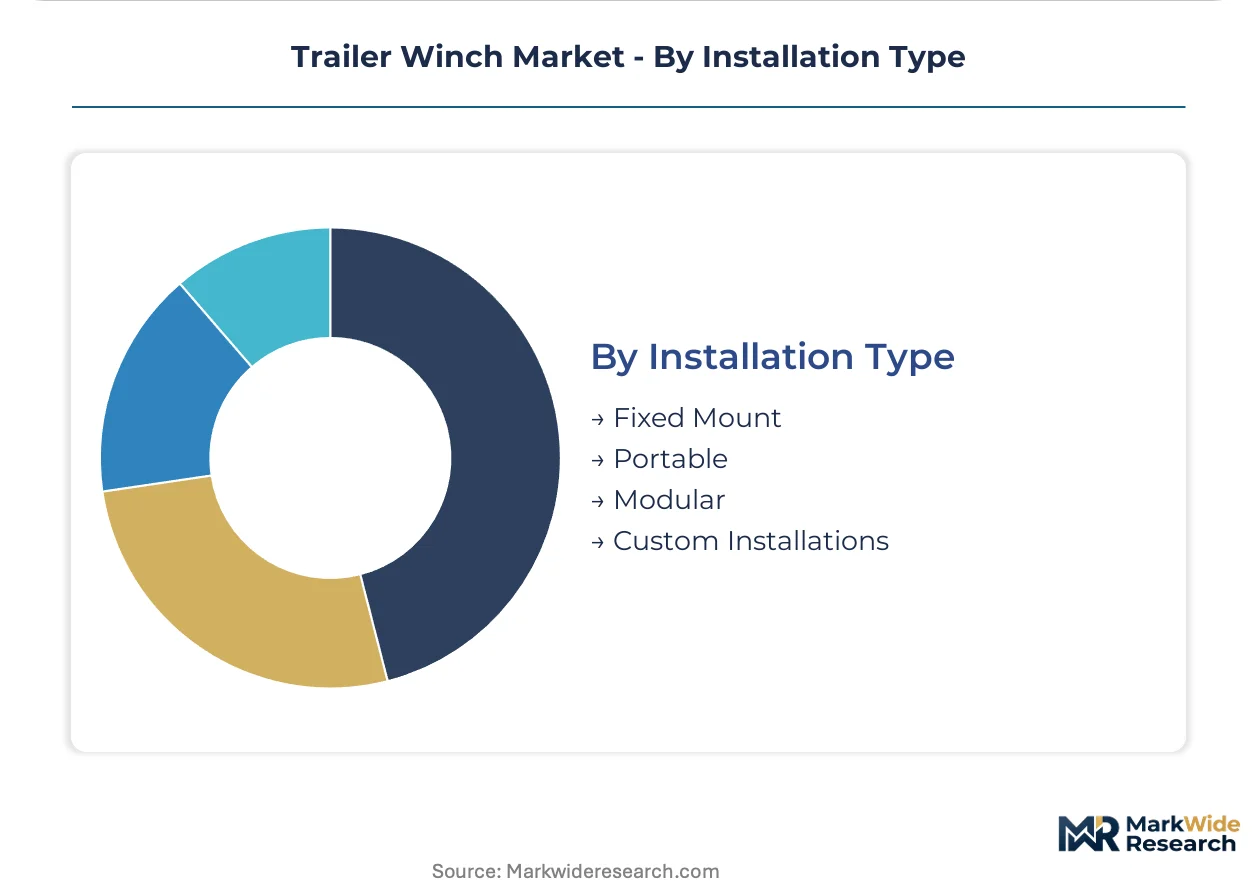
Installation Type:
Mounting flexibility determines aftermarket accessibility and OEM integration depth.
- Fixed Mount:Permanent frame-integrated installations dominate OEM supply agreements with marine and construction trailer manufacturers.
- Portable:Receiver-hitch and bumper-mounted units serve multi-trailer operators requiring equipment mobility across fleet assets.
- Modular:Bolt-on rail systems enable rapid reconfiguration between drum sizes and line pull ratings.
- Custom Installations:Specialized heavy-haul and lowboy trailers require engineered mounting solutions with structural reinforcement.
Fixed mount leads on scale; portable leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting electric winch assembly toward jurisdictions offering IRA domestic manufacturing credits, while REACH compliance costs in Europe push plating and coating operations to North American facilities with lighter chemical handling burdens.
United States
Boat trailer demand concentrates along Florida's Gulf Coast and the Carolinas, where marina infrastructure bonds fund ramp modernization. EPA Phase 3 small-engine standards are eliminating gasoline hydraulic pump eligibility from new marine platform designs. WARN Industries and Superwinch anchor supplier relationships with southeastern OEMs through exclusive electric winch supply agreements.
Canada
Recreational boating participation in British Columbia and Ontario drives aftermarket winch replacement cycles. Environment and Climate Change Canada aligns small-engine emissions rules with EPA thresholds, simplifying cross-border product certification. Vancouver Island marine retailers report accelerating synthetic rope conversions among saltwater trailer operators.
Germany
Construction equipment rental fleets in North Rhine-Westphalia and Bavaria specify self-loading trailer capabilities to reduce jobsite logistics costs. ECHA REACH restrictions on hexavalent chromium coatings force drum manufacturers toward zinc-nickel plating systems. KBA trailer braking standards create compliance overlap with NHTSA rules for exporters serving North American markets.
China
Rare-earth magnet processing concentration in Inner Mongolia and Jiangxi provinces shapes electric motor cost structures for export-oriented winch assemblers. MIIT energy efficiency standards for industrial motors are tightening brushless DC specifications. Ningbo and Qingdao port clusters handle bulk marine trailer exports to Southeast Asian markets.
Australia
Caravan and RV manufacturing in Victoria and Queensland sustains demand for weight-sensitive aluminum-housing winches. TGA-equivalent electrical safety certifications apply to wireless remote accessories entering the market. Perth-based mining equipment rental operators retrofit heavy-haul trailers with hydraulic winch systems for remote site self-loading.
Trailer Winch Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with marine and construction trailer OEMs favoring direct supplier relationships while aftermarket channels sustain distributor networks. The vendor base organizes around three archetypes: heritage off-road recovery brands with marine extensions, dedicated winch engineering houses with sealed-motor IP, and diversified automotive accessory suppliers with trailer adjacencies. Competitive moves center on exclusive OEM supply lock-ups and synthetic rope compatibility certification.
Among heritage recovery-system specialists, WARN Industries and Superwinch occupy positions defined by saltwater corrosion resistance capabilities and marine loading scenario expertise. Fulton and Dutton-Lainson Company exemplify the diversified automotive accessory tier, with corporate structures suggesting broader trailer component portfolios beyond winch specialization. Ramsey Winch represents the dedicated engineering-house archetype, with company naming indicating focused winch product lineage rather than diversified manufacturing.
| Leading Market Players |
|---|
| WARN Industries |
| Superwinch |
| Ramsey Winch |
| Fulton |
| Dutton-Lainson Company |
| Powerwinch |
| COMEUP Industries |
| Westin Automotive |
| Smittybilt |
| Others |
Value Network & Pricing Analysis
Copper futures volatility on the London Metal Exchange cascades through electric motor supply chains into three-tier pricing structure across premium, standard, and economy levels, with sealed IP68-rated winch assemblies commanding differential margins against commodity hand-crank alternatives.
Pricing Analysis
Distributor margin compression in the southeastern United States runs through direct-to-OEM procurement contracts that national equipment rental operators negotiate with WARN Industries and Superwinch, bypassing wholesale channels entirely. Price differentiation hinges on NHTSA lighting integration certification and zinc-nickel plating grade for saltwater exposure. Cost compression in standard-tier electric winches is intensifying because rare-earth magnet supply uncertainty from Chinese processors feeds into motor assembly premiums. Fleet operators exhibit lowest price sensitivity due to lifecycle cost accounting, while individual recreational boaters remain most responsive to upfront equipment outlays.
Supply Chain Analysis
Regional distribution centers in Ningbo and Qingdao anchor hub-and-spoke patterns for marine trailer exports, with downstream fulfillment drawing from Inner Mongolia rare-earth processing and Chilean copper concentrate feeds. Brushless DC motors, synthetic Dyneema rope, and zinc-nickel plated drums constitute critical component inputs. Single-source vulnerability concentrates in Chinese rare-earth magnet supply, exposing assemblers to export restriction risk. Distribution runs through direct manufacturer contracts with construction rental fleets and marine OEMs, compressing traditional distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where IRA domestic manufacturing credits in the United States offset REACH compliance costs that European drum plating operations face, redirecting assembly investment toward southeastern coastal states.
For Market Incumbents: Anticipate synthetic rope substitution accelerating aftermarket revenue compression by certifying compatibility across premium winch configurations before Dyneema-based lines displace steel cable attach rates entirely. Deepen backward integration into sealed-motor IP68 housing production to defend margin position against contract manufacturers entering through electric motor assembly partnerships. Lock exclusive supply agreements with Florida and Carolinas marine trailer OEMs before EPA Phase 3 standards eliminate gasoline hydraulic pump eligibility from new platform designs.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in wireless remote accessories offers entry terrain where FCC Part 15 certification delays have deterred specialist engineering houses from pursuing marine trailer integration. Target portable winch configurations for multi-trailer fleet operators requiring equipment mobility across construction and recreational assets, a segment where distributor relationships remain underdeveloped. Pursue synthetic rope aftermarket upgrade positioning rather than competing against established electric winch OEM supply lock-ups.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional distributors lose volume concentration to direct manufacturer contracts, creating acquisition opportunities for distressed wholesale networks with southeastern United States marine retail exposure. Focus on mid-cap winch engineering specialists with captive sealed-motor IP rather than diversified automotive accessory portfolios lacking corrosion-resistance differentiation. Watch for FCC Part 15 approval timeline acceleration as signal that wireless remote accessory barriers are lowering, potentially inviting contract manufacturer entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Motor IP68 Certification | Enables electric winch deployment in submerged loading scenarios previously restricted to hydraulic systems. |
| Synthetic Rope Compatibility Program | Captures aftermarket upgrade revenue as Dyneema-based lines displace steel wire in recreational marine trailers. |
| Direct OEM Supply Agreement | Bypasses distributor margin compression by locking exclusive relationships with Florida and Carolinas trailer manufacturers. |
| IRA Manufacturing Credit Utilization | Attracts brushless DC motor assembly investment away from offshore hydraulic pump sourcing. |
| REACH-Compliant Plating Transition | Positions drum manufacturers for European market access through zinc-nickel systems replacing hexavalent chromium coatings. |
Research Methodology
Coverage spans the United States, Canada, Germany, China, and Australia, with primary inputs from each market combining interviews with marine trailer OEM procurement teams, construction equipment rental fleet managers, aftermarket distributors, sealed-motor R&D directors, and regulatory compliance officers with secondary validation. SEC 10-K filings, EPA emissions rulemakings, ECHA REACH substance restriction updates, and MIIT industrial motor efficiency standards provide foundational data. Bottom-up shipment data from trailer manufacturers triangulates against top-down spending estimates from rental fleet operators.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window, with segmentation modeling across powertrain architecture, trailer application, end-user category, and installation type. CAGRs derive from installed base growth, replacement cycle compression, and technology substitution curves. Brushless DC motor efficiency trajectories and synthetic rope adoption rates constitute industry-specific forecast inputs.
Caveats apply where rare-earth export restrictions, copper concentrate supply disruptions, or FCC certification timeline extensions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Suction Excavator Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Rotomolding Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
France Metal Fabrication Equipment Market