
 Global Crane Market | 2026-2036
Global Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crane Market Analysis
Buyer concentration in global infrastructure is broadening as state-backed developers and renewable-energy consortia displace traditional construction contractors as the largest procurement accounts. SANY Group leverages integrated casting and fabrication capacity to anchor pricing power across Asia-Pacific project pipelines. Liebherr Group sustains engineering intensity in all-terrain and crawler designs that command specification-driven selection in European wind farm tenders. XCMG Group competes on manufacturing scale and domestic channel density, dominating standardized mobile crane segments in China and Belt-and-Road outbound markets.
A crane is a machine equipped with ropes, wire ropes, chains, and sheaves for lifting, lowering, and horizontally moving materials, with load capacities spanning under one ton to over 5,000 tons depending on configuration and counterweight engineering. Its primary commercial purpose is to enable vertical and horizontal material handling in construction, energy, logistics, and extractive operations where manual or ground-based transport is infeasible. Mobile crane deployments lead volume across construction site applications where rapid relocation between work zones determines equipment economics. Tower crane configurations concentrate margin pools in urban high-rise projects where lifting height and precision outweigh transport flexibility. Offshore deployment categories are expanding fastest as floating wind and oil platform decommissioning drive demand for heavy-lift vessels with integrated crawler or pedestal-mounted systems.
OSHA crane operator certification requirements in the United States, EU Machinery Directive conformity assessments under CE marking, and China's GB/T national standards for construction machinery collectively shape product design, operator training mandates, and market access conditions across major supply corridors. Japan's METI technical standards for earthquake-resistant design further constrain product eligibility in seismically active markets, favoring manufacturers with localized engineering adaptation. Stakeholders must monitor how carbon-border adjustment mechanisms and embodied-emissions disclosure rules reshape sourcing decisions for steel-intensive crane structures and reconfigure competitive advantage toward low-carbon supply chains.
Market Dynamics
EU carbon-border adjustment mechanisms and China's GB/T embodied-emissions disclosure standards are forcing manufacturers to reconfigure steel-intensive supply chains and document lifecycle emissions across crawler, mobile, and tower crane production lines.
Growth Catalysts
- Offshore wind expansion:Floating wind farm developers in the North Sea and Baltic corridors are expanding procurement of heavy-lift crawler units rated above 1,500 tons for turbine installation and maintenance operations.
- EU Machinery Directive updates:CE marking conformity assessments now mandate remote-monitoring capabilities and predictive maintenance interfaces, accelerating replacement cycles for legacy fleets across European construction consortia.
- Port modernization clusters:State-backed infrastructure programs in Shanghai, Rotterdam, and Singapore are sustaining double-digit order volumes for ship-to-shore gantry and mobile harbor crane categories.
Market Restraints
- High-grade steel volatility:Quenched and tempered plate prices for boom fabrication swing with scrap and alloy surcharges, compressing margin buffers for mid-tier manufacturers without captive rolling mill access.
- Specialized bearing concentration:Slewing ring and main hoist winch assemblies rely on a narrow supplier base concentrated in Germany and Japan, exposing procurement timelines to single-source risk.
- Operator certification bottlenecks:OSHA crane operator certification requirements in the United States create 6-12 month training backlogs, constraining fleet utilization rates and delaying project mobilization.
Strategic Opportunities
- Saudi giga-project pipeline:NEOM and Red Sea tourism developments are generating tender volumes for 800-ton all-terrain units that exceed regional dealer inventory, creating first-mover advantage for manufacturers with localized assembly partnerships.
- Battery-electric retrofit kits:Convergence of high-density lithium-ion packs and regenerative hoist drives is opening retrofit revenue streams for urban tower crane fleets facing municipal diesel bans.
- India PLI scheme alignment:Production-linked incentive frameworks for construction machinery are attracting component localization investments that reduce landed cost disadvantages versus ASEAN-sourced competitors.
Industry Challenges
- Welding technician scarcity:ASME Section IX-certified welders for high-strength boom fabrication command 40% wage premiums in Poland and Czech Republic, constraining capacity expansion for European manufacturers.
- Software integration complexity:Anti-collision systems, load-moment indicators, and telematics platforms require interoperability across OEM-proprietary protocols, complicating mixed-fleet operations for rental houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crane Market |
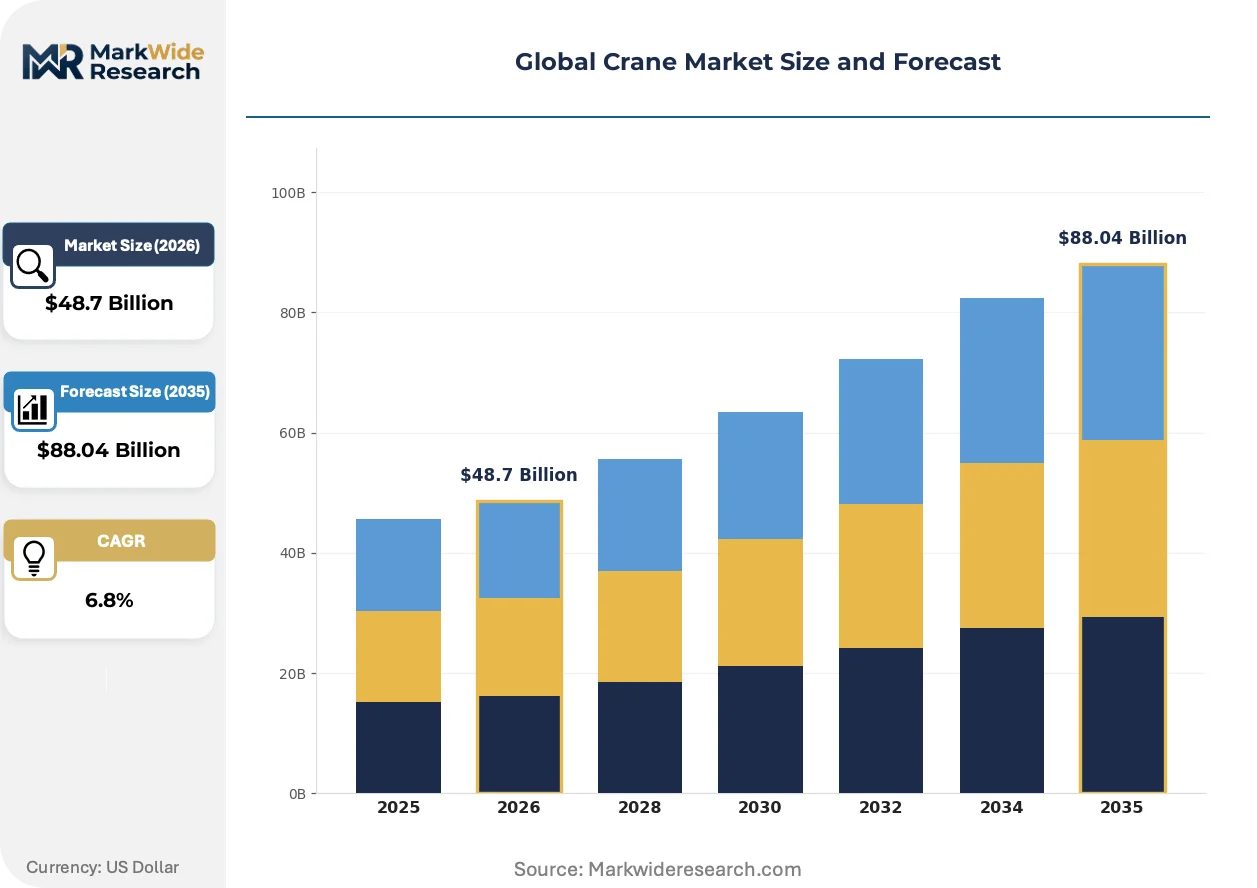
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tower Crane, Mobile Crane, Loader Crane, Crawler Crane End User: Construction, Mining, Shipping, Oil & Gas Deployment: Onshore, Offshore, Industrial Site, Construction Site Service Type: Rental, Sales, Maintenance, Repair |
| Companies Covered | Liebherr Group, Terex Corporation, Manitowoc Company Inc., Konecranes Plc, Cargotec Corporation, Tadano Ltd., SANY Group, XCMG Group, Zoomlion Heavy Industry Science and Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crane Market Emerging Trajectories
Digitization of crane operations is compressing the gap between equipment specification and real-time performance optimization, with telematics, automation, and alternative powertrains converging to redefine competitive differentiation across rental and owner-operator segments.
Regenerative electrification is decentralizing power architecture in heavy-lift crawler designs. Kinetic energy recovery systems now capture hoist-descent loads to supplement diesel-electric hybrids, reducing fuel consumption by 15-20% in continuous-lift scenarios. Offshore wind contractors in the North Sea are specifying these configurations to meet charterer emissions reporting requirements and reduce bunker cost exposure on multi-year installation campaigns.
EU Machinery Directive amendments under the 2023 CE marking recast mandate cybersecurity-by-design for safety-related control systems. Manufacturers must now document threat-risk assessments and secure software update procedures for crane management systems. European wind farm tenders are already incorporating these conformity prerequisites into technical evaluation matrices, disadvantaging suppliers without EU-notified body relationships.
Rental houses are unbundling operator training from equipment lease agreements, selling certified instruction as a standalone revenue line. XCMG and SANY dealers in Southeast Asia now bundle GB/T-compliant operator certification with monthly rental contracts, capturing margin that previously flowed to third-party training centers. This model is compressing switching costs for construction contractors and concentrating fleet loyalty toward vertically integrated rental providers.
Global Crane Market Segmentation
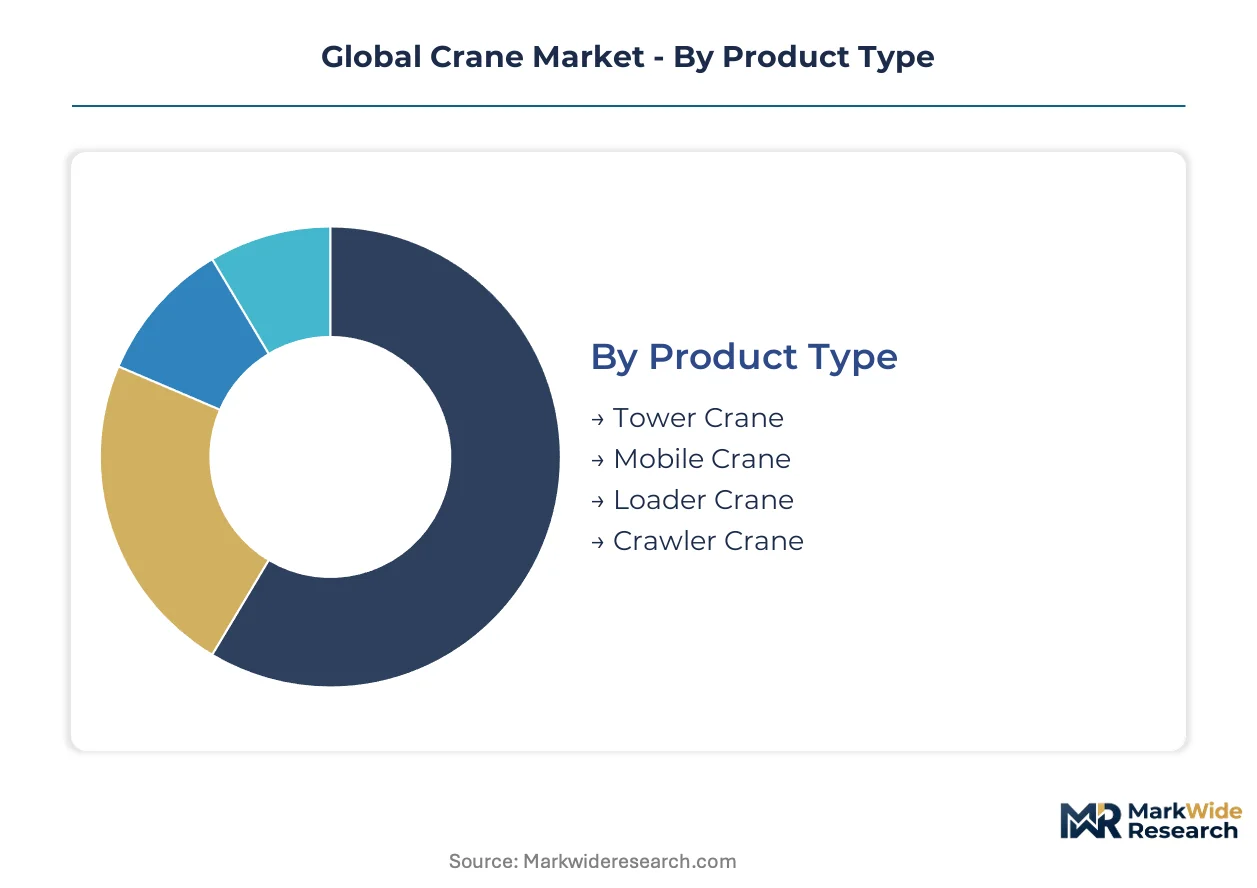
Crane procurement decisions diverge sharply across project types, with lifting height requirements, mobility constraints, and regulatory exposure creating distinct specification clusters. Understanding these segment boundaries clarifies where manufacturers must anchor engineering investment versus where rental economics dominate.
Product Type:
Buyers select configurations based on transport logistics versus vertical reach trade-offs, with urban density and site access dictating whether mobility or height precision takes priority.
- Mobile Crane:Truck-mounted and all-terrain designs deploy hydraulic telescoping booms for rapid relocation between construction zones. Demand concentrates in German and Saudi road-building consortia where mobilization speed determines project economics, though axle-load regulations in California and Bavaria constrain maximum configurations.
- Tower Crane:Fixed-base luffing and hammerhead designs achieve 80-meter lifting heights with precision load placement. Procurement clusters in Shanghai and Mumbai high-rise developments where municipal height bonuses reward vertical construction, yet foundation engineering costs and aviation clearance protocols extend sales cycles.
- Crawler Crane:Tracked undercarriage distributes loads across soft ground for heavy-lift operations above 1,000 tons.
- Loader Crane:Articulated knuckle-boom mounts service logistics fleets and municipal maintenance vehicles.
Mobile cranes lead on scale; crawler cranes lead on momentum.
End User:
Capital intensity and project duration separate owner-operator economics from rental-mediated procurement across extractive and built-environment applications.
- Construction:General contractors and specialty trade subcontractors deploy mixed fleets across residential, commercial, and civil infrastructure phases. Activity concentrates in Chinese state-backed urban renewal and Indonesian nickel-processing smelter builds, though interest rate sensitivity in Australian and Canadian markets has compressed equipment replacement budgets.
- Oil & Gas:Upstream platform installation and downstream refinery turnaround operations specify explosion-proof electrical packages and Arctic-grade steel specifications. North Sea decommissioning and Qatar expansion projects sustain crawler crane demand, yet energy transition capital reallocation has lengthened tender timelines.
- Mining:Open-pit and underground extraction operations require ruggedized superstructures for continuous-duty material handling.
- Shipping:Port terminal operators and shipyards order gantry and floating crane systems for vessel loading and drydock operations.
Construction dominates absolute volumes; oil and gas commands specification premiums.
Deployment:
Site classification determines regulatory jurisdiction, with maritime and industrial safety regimes imposing distinct certification burdens on equipment configuration.
- Offshore:Floating wind installation vessels and platform supply vessels integrate heavy-lift systems with dynamic positioning compensation. Procurement is climbing the fastest in North Sea and Baltic corridor tenders where charterer emissions reporting mandates favor hybrid-electric powertrains, though classification society approval timelines extend delivery schedules.
- Construction Site:Temporary installations on greenfield and brownfield developments face OSHA, EU Machinery Directive, or GB/T compliance depending on project location.
- Onshore:Fixed industrial installations and infrastructure projects operate under national construction safety codes.
- Industrial Site:Permanent material handling systems in manufacturing and process plants integrate with facility automation.
Construction site deployment sustains baseline volumes; offshore deployment captures margin expansion.
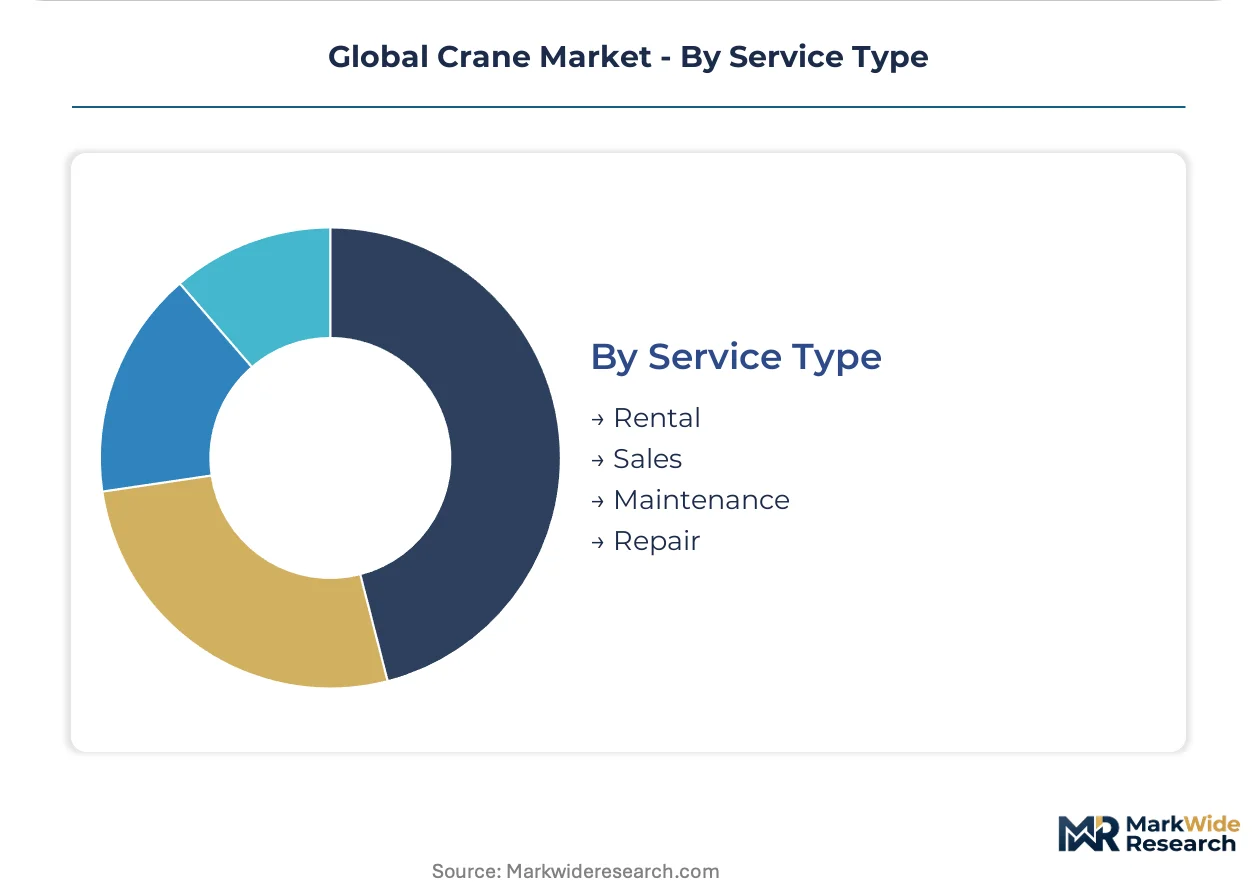
Service Type:
Asset utilization patterns and balance sheet preferences divide markets between ownership, rental mediation, and aftermarket service retention.
- Rental:Fleet operators bundle equipment, operator certification, and maintenance into monthly contracts. Penetration deepens in Southeast Asian markets where XCMG and SANY dealers now package GB/T-compliant training with lease agreements, capturing margin that previously flowed to third-party instruction centers.
- Sales:Direct procurement by large contractors and extractive companies with multi-year project visibility and captive maintenance capabilities.
- Maintenance:Scheduled inspection and component replacement programs extend asset life and preserve residual values.
- Repair:Unplanned breakdown remediation and accident reconstruction services.
Rental leads on customer count; sales leads on revenue per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welders and certified crane operators concentrate in Germany's industrial belt, China's coastal manufacturing zones, and the US Gulf Coast energy corridor, anchoring regional production capacity and aftermarket service networks.
China
State-backed infrastructure programs and port modernization sustain procurement volumes across mobile, tower, and crawler crane categories. MIIT enforces GB/T national standards for construction machinery safety and operator certification. Shanghai and Ningbo-Zhoushan port clusters generate double-digit order flows for ship-to-shore gantry systems.
Germany
Engineering-intensive all-terrain and crawler designs command specification-driven selection in European wind farm tenders. EU Machinery Directive conformity assessments under CE marking mandate remote-monitoring capabilities and predictive maintenance interfaces. Bavaria and Baden-Württemberg host concentrated fabrication capacity for high-strength boom assemblies.
United States
OSHA crane operator certification requirements create training backlogs that constrain fleet utilization rates and delay project mobilization. EPA emissions standards and state-level diesel equipment bans in California accelerate interest in battery-electric retrofit configurations. Texas and Louisiana Gulf Coast energy developments sustain demand for heavy-lift crawler units in petrochemical and offshore wind supply chain construction.
Saudi Arabia
NEOM and Red Sea tourism developments generate tender volumes for 800-ton all-terrain units that exceed regional dealer inventory. The Saudi Standards, Metrology and Quality Organization (SASO) implements technical regulations for construction machinery import conformity. Riyadh and the Eastern Province concentrate giga-project construction activity requiring specialized heavy-lift mobilization.
India
Production-linked incentive frameworks for construction machinery attract component localization investments that reduce landed cost disadvantages versus ASEAN-sourced competitors. BIS certification requirements govern crane safety standards and structural material specifications. Maharashtra and Gujarat industrial corridors concentrate infrastructure development and manufacturing plant construction driving mobile crane deployment.
Global Crane Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across engineering intensity, manufacturing scale, and geographic coverage dimensions. Market structure tilts toward consolidation at the premium specification tier while fragmenting across standardized mobile crane segments. Three archetypes dominate: integrated casting-to-assembly conglomerates with captive steel supply; specification-driven engineering houses with deep EU regulatory relationships; and scale-focused manufacturers competing on channel density and domestic procurement alignment. Competitive moves center on localized assembly partnerships for giga-project access and battery-electric powertrain development for municipal compliance positioning.
Among the named players, Liebherr Group and SANY Group occupy distinct archetype positions, with Terex Corporation representing North American manufacturing heritage. Liebherr exemplifies the engineering-intensive specialist model with deep European regulatory integration. SANY anchors the integrated conglomerate tier with casting and fabrication capacity supporting Asia-Pacific project pipelines. Terex sits within the diversified industrial portfolio segment with historical strength in aerial work platforms and material handling equipment. XCMG Group represents the scale-driven domestic champion archetype competing on manufacturing throughput and Belt-and-Road outbound market penetration.
| Leading Market Players |
|---|
| Liebherr Group |
| Terex Corporation |
| Manitowoc Company Inc. |
| Konecranes Plc |
| Cargotec Corporation |
| Tadano Ltd. |
| SANY Group |
| XCMG Group |
| Zoomlion Heavy Industry Science and Technology Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Regenerative electrification retrofits are simultaneously compressing lifecycle cost structures for tower crane operators and concentrating procurement leverage among manufacturers with captive battery-pack integration capabilities. This dual transformation reshapes how rental houses negotiate lease terms and how OEMs source powertrain components across European and Chinese assembly lines.
Pricing Analysis
Bundled operator-certification services versus unbundled equipment-only contracts now define the dominant pricing split across Asian rental markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked all-terrain units with predictive maintenance interfaces from basic mobile configurations without telematics. Cost compression in mid-tier crawler segments is intensifying because Chinese manufacturers are exporting surplus casting capacity into Southeast Asian project pipelines. Small contractors with intermittent project visibility exhibit highest price sensitivity, while state-backed wind farm consortia prioritize specification compliance over capital expenditure minimization.
Supply Chain Analysis
High-grade quenched and tempered steel plate supply rests on German, Japanese, and Chinese rolling mill capacity, with boom fabrication drawing from these concentrated metallurgical inputs. Slewing ring bearings and main hoist winch assemblies rely on specialty producers in Germany and Japan, creating single-source vulnerability for European and North American crane builders. Tariff exposure on alloy steel imports is forcing manufacturers to qualify secondary Asian suppliers. Distribution runs through OEM-owned dealer networks in China and independent rental houses in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through battery-electric retrofit penetration, where premium-tier positioning captures municipal diesel-ban compliance premiums while standardized manufacturing drives down powertrain unit costs.
For Market Incumbents: Acquire certified welding technician training programs to lock in ASME Section IX-qualified labor pools before European capacity constraints harden. Defend specification-driven selection in North Sea wind tenders by deepening EU-notified body relationships for Machinery Directive conformity assessments. Channel control through localized assembly partnerships in Saudi Arabia protects against giga-project inventory shortages.
For New Entrants and Emerging Players: The 800-ton all-terrain price-point gap between European engineering houses and Chinese scale manufacturers creates entry space for mid-tier specialists with modular design platforms. India's PLI-aligned component localization offers the most penetrable geography for reducing landed cost disadvantages. Go-to-market through state-backed infrastructure consortiums bypasses fragmented contractor procurement.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play rental operators without captive manufacturing, as fleet utilization rates recover from OSHA certification bottlenecks. Long-term viability favors vertically integrated conglomerates with casting-to-assembly control and Belt-and-Road channel density. Watch North Sea floating wind tender volumes as the inflection signal for heavy-lift crawler demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Powertrain Development | Captures municipal diesel-ban compliance premiums in European urban construction zones. |
| Localized Assembly Partnership | Secures giga-project access in Saudi Arabia where dealer inventory falls short of tender volumes. |
| EU-Notified Body Certification Investment | Enables CE marking for cybersecurity-by-design mandates in Machinery Directive conformity assessments. |
| Operator Training Vertical Integration | Bundles GB/T-compliant certification with rental contracts, capturing margin from third-party instruction centers. |
| Backward Integration into Casting Capacity | Anchors pricing power through captive steel supply for boom fabrication across Asia-Pacific pipelines. |
Methodological Framework
Coverage spans China, Germany, the United States, Saudi Arabia, and India, with primary inputs from each market's crane procurement decision-makers. The research combines interviews with maintenance directors at rental houses, OEM procurement teams, plant engineers at construction consortia, and aftermarket service heads with secondary validation from customs trade data, SEC filings, MIIT production statistics, and EU Machinery Directive conformity databases. Bottom-up project pipeline enumeration and top-down manufacturing capacity assessments triangulate volume estimates.
Granularity-level modeling disaggregates the market by product type, end-use industry, deployment environment, and service model across the projection horizon. CAGRs derive from segment-level demand elasticity analysis against infrastructure investment flows and regulatory compliance timelines. Forecast inputs incorporate steel price volatility indices, port modernization expenditure plans, and offshore wind charterer emissions reporting mandates.
Caveats apply where GB/T disclosure standard enforcement, EU carbon-border adjustment implementation pace, or high-grade steel alloy surcharge volatility could materially shift the outlook. Forecasts reflect assumptions about certification backlog resolution and giga-project mobilization schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Global Cone Crusher Market
Construction Equipment
Industrial Ovens Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Snow Clearing Vehicles Market