
 Global Hot Runner Market | 2026-2036
Global Hot Runner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hot Runner Market Analysis
Modular nozzle-manifold bundling is rebalancing how tier-one automotive suppliers evaluate total cost of ownership against single-component sourcing. Mold-Masters leverages its integrated hot half portfolio to anchor long-term contracts with North American automotive OEMs. EWIKON Heißkanalsysteme GmbH competes through specialized nozzle solutions for high-cavitation medical applications. Husky Injection Molding Systems Ltd. dominates large-tonnage hybrid system deployments across Asian packaging corridors.
A hot runner is a heated manifold assembly that maintains thermoplastic resin in a molten state between the injection machine barrel and mold cavities, typically operating at temperatures between 200°C and 400°C depending on polymer viscosity, eliminating solidified sprues and reducing material waste in precision molding operations. Manifold systems lead unit volume due to their ubiquity across multi-cavity automotive and consumer electronics molds, while electric technology segments capture expanding margin pools as energy efficiency standards tighten across manufacturing jurisdictions. Plastic material applications sustain the largest addressable base, though composite-compatible nozzle designs represent the fastest-growing configuration as lightweighting requirements penetrate industrial equipment and transportation sectors.
The EPA enforces emissions thresholds that affect polymer processing equipment selection in US manufacturing facilities, while REACH and RoHS frameworks in Europe restrict hazardous substance content in hot runner components destined for consumer contact applications. China's GB standards and MIIT energy efficiency directives shape local procurement criteria for injection molding systems. ISO certification requirements for medical and automotive supply chains further filter vendor qualification protocols across all three regulatory zones. Stakeholders must monitor evolving substance restrictions and efficiency mandates to anticipate redesign cycles and qualification timelines.
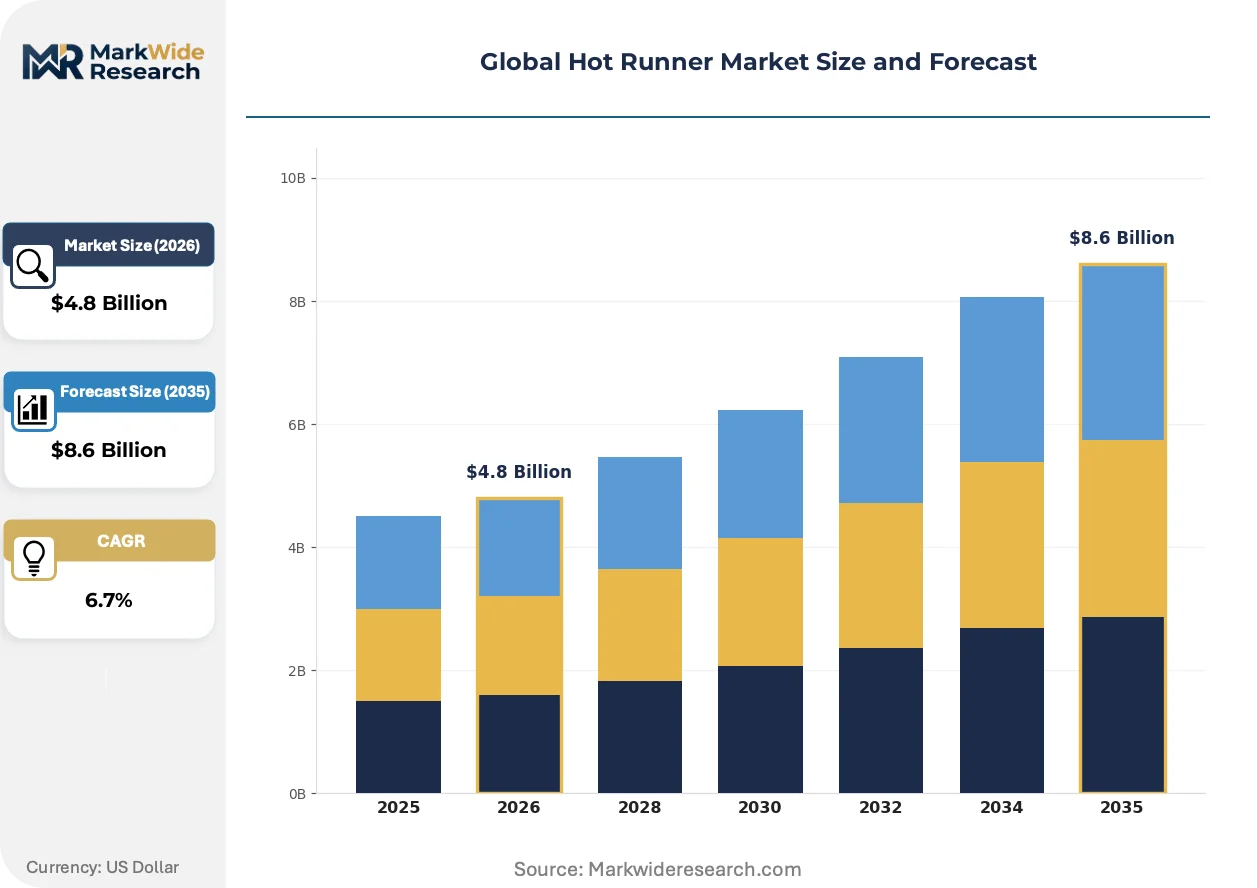
Market Dynamics
Electric manifold technology is displacing hydraulic systems as energy efficiency mandates tighten across manufacturing jurisdictions, forcing mold builders to requalify supplier portfolios around thermal uniformity specifications.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases accelerates conversion to low-global-warming-potential thermal management fluids in German and Italian automotive molding clusters.
- Lightweighting mandates:Automotive OEMs in China and the United States specify hot runner systems for thin-wall interior components to meet corporate average fuel economy targets.
- Multi-cavity medical molding:High-cavitation nozzle configurations capture expanding demand for single-use diagnostic consumables in regulated healthcare supply chains.
Market Restraints
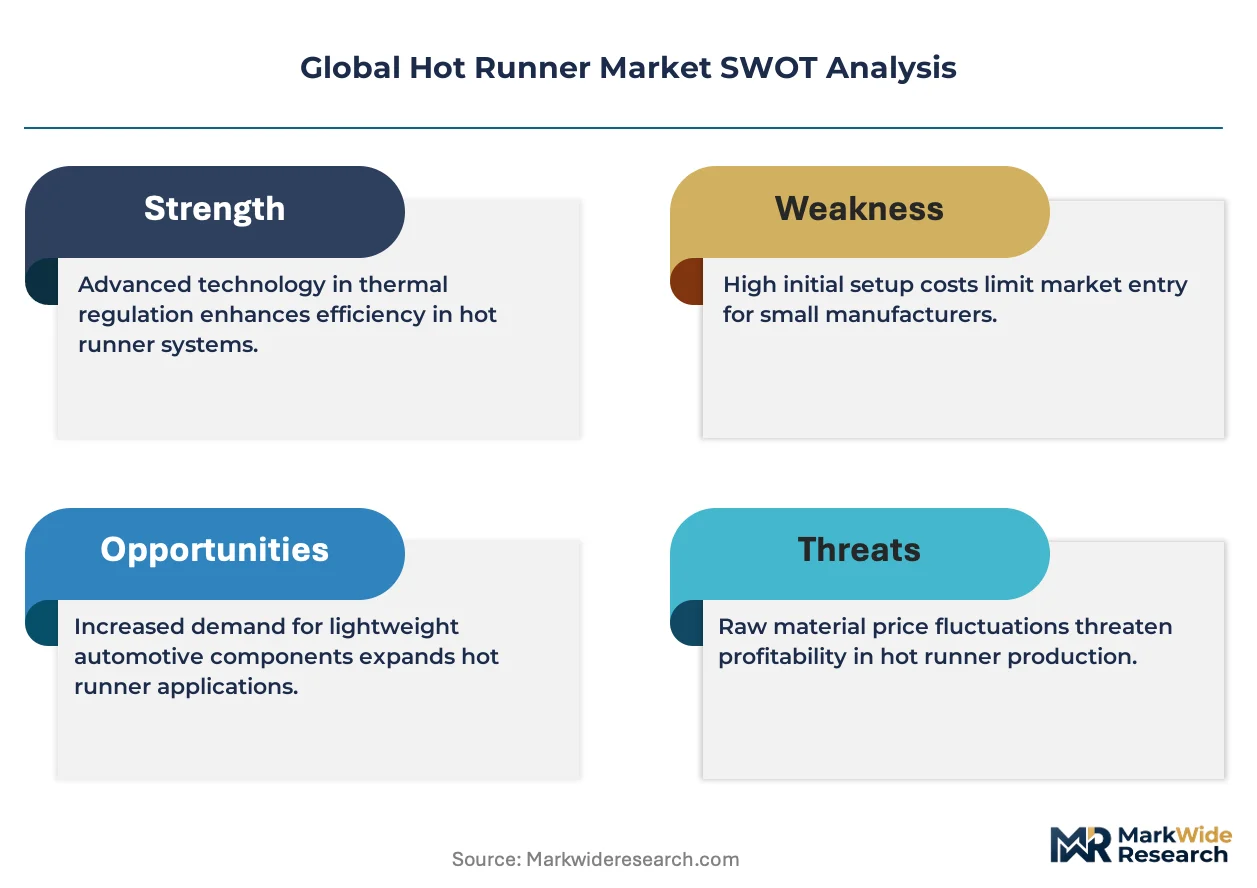
- Copper and specialty steel volatility:Manifold block raw material costs fluctuate with London Metal Exchange pricing, compressing margins for mid-tier system integrators.
- Heater cartridge supply concentration:Sourcing of high-watt-density heating elements concentrates among Japanese and German component specialists, creating single-source vulnerability.
- REACH substance restrictions:ECHA candidate list expansions force reformulation of nozzle tip coatings and manifold surface treatments, extending qualification timelines.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for electronics manufacturing attract precision molding investment to Tamil Nadu and Gujarat, creating greenfield hot runner demand.
- Bio-based polymer compatibility:PLA and PHA processing requirements drive nozzle design innovation for lower-temperature, shear-sensitive resin flow control.
- Remote thermal monitoring:IoT-enabled manifold diagnostics create recurring revenue streams through predictive maintenance subscriptions.
Industry Challenges
- Multi-physics simulation expertise:Mold flow analysis for complex manifold geometries requires scarce computational fluid dynamics specialists, extending design cycles.
- ISO 13485 medical certification:Validation protocols for cleanroom-compatible hot runner systems demand 18-24 month qualification periods, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hot Runner Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Half, Cold Half, Manifold Systems, Nozzle Solutions Technology: Electric, Hydraulic, Pneumatic, Hybrid End User: Automotive, Consumer Electronics, Industrial Equipment, Packaging Material: Plastic, Metal, Composite, Others |
| Companies Covered | Mold-Masters, EWIKON Heißkanalsysteme GmbH, Husky Injection Molding Systems Ltd., Barnes Group Inc., GÜNTHER Heisskanaltechnik GmbH, INCOE Corporation, Synventive Molding Solutions, CACO PACIFIC Corporation, Yudo Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hot Runner Market Emerging Trajectories
Digital thermal control architectures and sustainable material processing requirements are redefining competitive differentiation in precision molding equipment procurement.
Sequential valve-gate control technology is expanding into large-format automotive fascia and bumper molding applications. Tier-one suppliers in Germany and the United States adopt synchronized multi-point injection to eliminate weld lines on class-A surfaces. This capability is expanding into commodity interior components as cost curves flatten and software licensing models proliferate.
China's MIIT energy efficiency directives now mandate variable-frequency drive compatibility for auxiliary molding equipment. Local injection machine builders in Guangdong and Zhejiang provinces requalify hot runner controllers to meet GB standard power consumption thresholds. Export-oriented mold fabricators face dual compliance burdens as they simultaneously satisfy EU F-Gas and domestic efficiency frameworks.
Automotive procurement teams unbundle hot runner specification from mold build contracts, creating direct vendor relationships that bypass traditional moldmaker intermediaries. OEM thermal engineering groups in Michigan and Bavaria now issue standalone technical requirements for manifold systems. This pattern concentrates most visibly in electric vehicle platform launches where lightweighting targets override legacy supplier preferences.
Global Hot Runner Market Segmentation
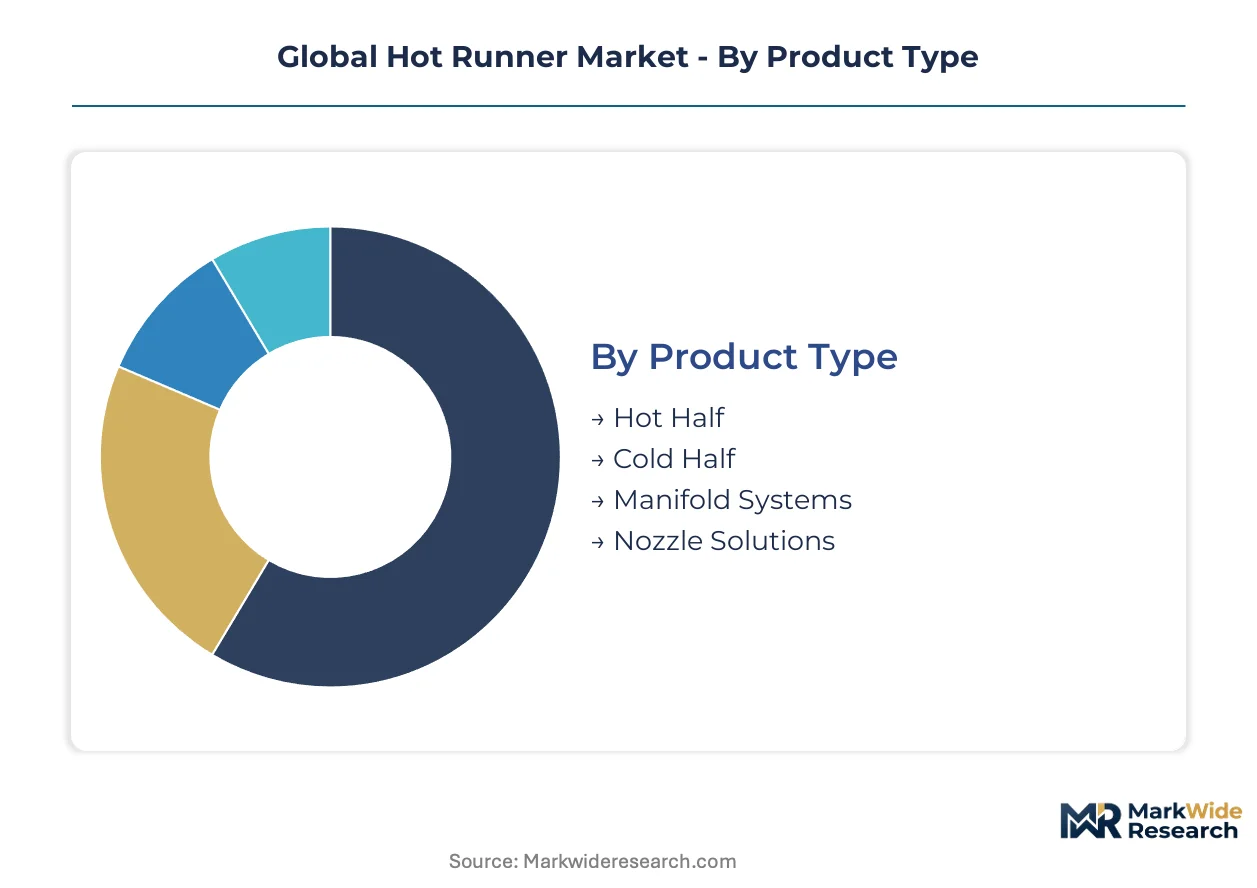
Hot runner procurement decisions split between standardized catalog configurations for high-volume automotive programs and engineered-to-order systems for medical and aerospace qualification pathways. Segment boundaries blur as modular architectures allow mold builders to mix electric nozzles with hydraulic manifolds within single tool assemblies.
Product Type:
Customization intensity varies sharply across this category, with integrated hot half assemblies demanding concurrent engineering alongside mold design versus drop-in nozzle replacements.
- Manifold Systems:Central distribution blocks machined from specialty tool steels route molten polymer through precision-drilled channels to multiple cavities. German automotive clusters in Stuttgart and Wolfsburg specify these for instrument panel and door module programs where thermal uniformity governs dimensional stability.
- Nozzle Solutions:Individual heated components direct flow into specific cavity locations, available in valve-gate, thermal-gate, and open-tip configurations. Demand concentrates in high-cavitation medical molding for diagnostic consumables where gate vestige control determines part acceptance.
- Hot Half:Pre-assembled manifold-nozzle-controller units reduce mold build cycle times through standardized interfaces. Michigan-based automotive OEMs increasingly source these directly, bypassing traditional moldmaker intermediaries.
- Cold Half:Unheated mold sections including cavity inserts and ejection systems, typically procured separately from hot runner components. Integration complexity rises as thin-wall packaging applications demand tighter hot-cold interface tolerances.
Most installed capacity flows through Manifold Systems. Expansion is steepest in Nozzle Solutions.
Technology:
Energy efficiency mandates and precision requirements divide this category across cost tiers, with electric systems commanding premium positioning against legacy hydraulic infrastructure.
- Electric:Servo-driven valve pin actuation delivers sub-millisecond synchronization for sequential injection control. China's MIIT efficiency directives accelerate displacement of hydraulic alternatives in Guangdong export molding corridors.
- Hybrid:Combines electric nozzle actuation with pneumatic or hydraulic manifold clamping for large-tonnage applications. Asian packaging clusters favor these for 500-ton-plus injection machines where pure electric torque limits constrain design.
- Hydraulic:Fluid-powered actuation persists in legacy automotive tooling where capital replacement cycles extend beyond technology refresh timelines. REACH fluid compatibility requirements now force reformulation of thermal transfer oils.
- Pneumatic:Compressed air systems occupy niche positions in cleanroom medical applications where oil contamination risks override efficiency penalties. Japanese precision molders specify these for optical lens production.
Electric technology captures the dominant share of new order intake. Hybrid configurations climb fastest in large-format automotive fascia molding.
End User:
Customer sophistication and qualification burden create distinct margin tiers, with medical and automotive segments demanding divergent certification protocols.
- Automotive:Tier-one suppliers specify hot runners for interior trim, under-hood components, and structural elements where lightweighting targets drive thin-wall designs. EPA corporate average fuel economy standards intensify resin reduction mandates across US manufacturing footprints.
- Consumer Electronics:High-cavitation requirements for smartphone housings and wearable device components emphasize cycle time minimization. Shenzhen and Dongguan molding clusters prioritize rapid color change capabilities.
- Packaging:Food-contact compliance and high-speed production dominate specification criteria. EU F-Gas Regulation shapes thermal management fluid selection for dairy and beverage closure molding in German and Italian facilities.
- Industrial Equipment:Lower volume, higher mix applications favor flexible nozzle configurations adaptable across mold changeovers. Indian electronics manufacturing incentives under PLI schemes attract precision molding investment to Tamil Nadu corridors.
Automotive channels absorb the greatest installed base volume. Medical-adjacent diagnostic molding within Consumer Electronics expands most quickly.
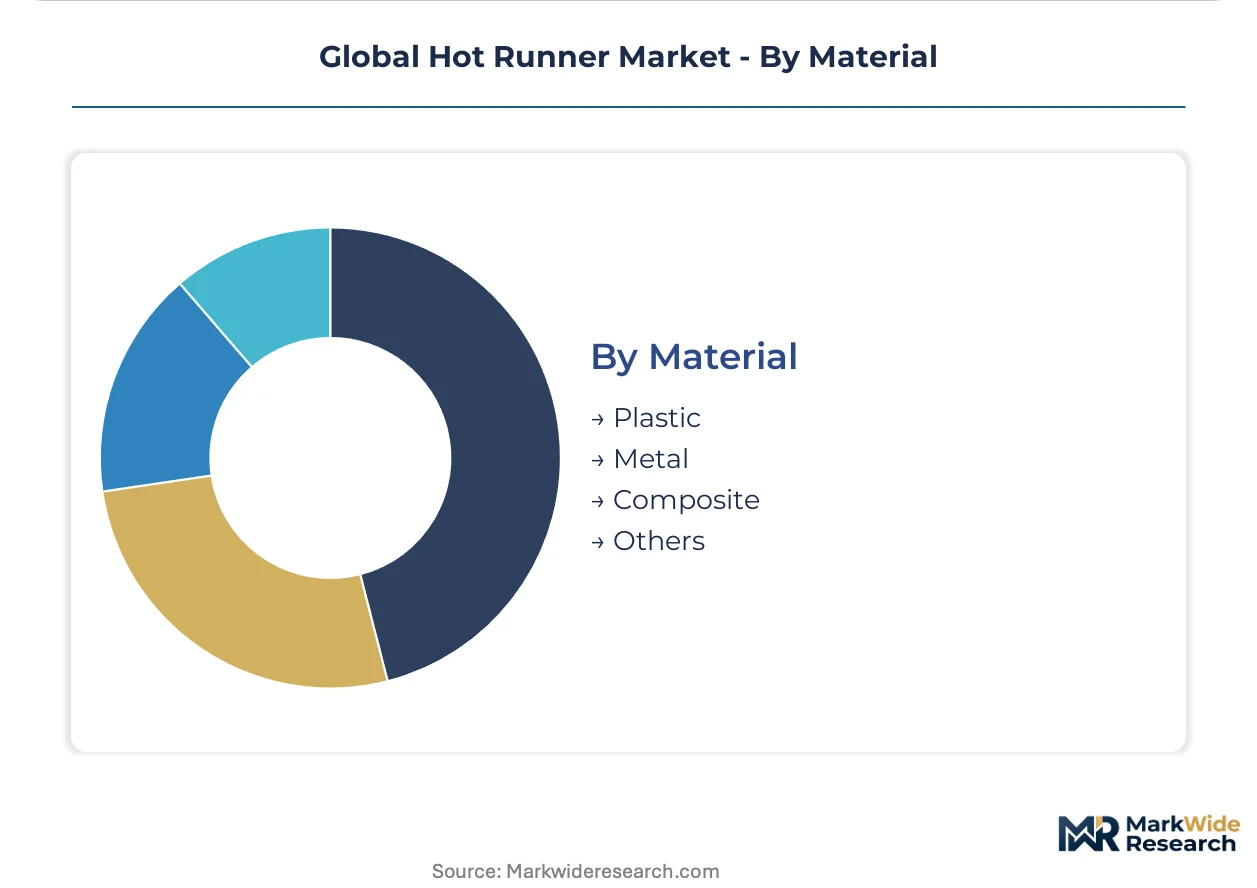
Material:
Processing temperature windows and abrasive characteristics segment this category by nozzle wear rates and heater specification requirements.
- Plastic:Polypropylene, ABS, polycarbonate, and nylon formulations constitute the primary processing base. Automotive interior programs in the United States and Germany drive specification for glass-filled variants requiring hardened nozzle tip materials.
- Composite:Long-fiber reinforced thermoplastics and carbon-filled compounds demand specialized flow channel geometries to preserve fiber length. Aerospace and electric vehicle battery housing applications concentrate demand in Bavaria and Michigan.
- Metal:Powder injection molding and thixomolding applications for small structural components utilize hot runner systems with extended temperature capabilities. Japanese automotive suppliers lead adoption for transmission and engine components.
- Others:Bio-based polymers including PLA and PHA require lower-temperature nozzle designs with reduced shear heating. European packaging sustainability mandates accelerate qualification timelines for these materials.
Plastic applications anchor current installed capacity. Composite-compatible configurations gain share fastest as lightweighting penetrates transportation sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hot runner industry traces its commercial origins to German precision tooling traditions of the 1960s, when heated manifold systems first displaced cold runner architectures in automotive injection molding. From this European foundation, manufacturing knowledge diffused through machinery export channels and joint venture formations across North American and Asian industrial corridors.
Germany
Stuttgart and Wolfsburg automotive clusters specify manifold systems for instrument panel and door module programs where thermal uniformity governs dimensional stability. The EU F-Gas Regulation accelerates conversion to low-global-warming-potential thermal management fluids in German molding facilities. Bavarian precision molders anchor European demand for high-cavitation medical nozzle configurations.
China
Guangdong and Zhejiang injection machine builders requalify hot runner controllers to meet MIIT energy efficiency directives and GB standard power consumption thresholds. Shenzhen and Dongguan molding clusters prioritize rapid color change capabilities for consumer electronics housings. Export-oriented fabricators face dual compliance burdens satisfying both domestic efficiency frameworks and EU F-Gas requirements.
United States
Michigan-based automotive OEMs increasingly source hot half assemblies directly, bypassing traditional moldmaker intermediaries. EPA corporate average fuel economy standards intensify resin reduction mandates across US manufacturing footprints. Thermal engineering groups in Detroit issue standalone technical requirements for manifold systems in electric vehicle platform launches.
India
PLI scheme incentives for electronics manufacturing attract precision molding investment to Tamil Nadu and Gujarat industrial corridors. The country's national industrial efficiency directives shape procurement criteria for injection molding systems in greenfield facilities. Local automotive suppliers in Pune and Chennai adopt hot runner technology for interior component lightweighting programs.
Japan
Japanese precision molders specify pneumatic hot runner systems for optical lens production in cleanroom environments where oil contamination risks override efficiency penalties. METI industrial technology roadmaps influence thermal control architecture development in domestic machinery sectors. Nagoya-area automotive suppliers lead adoption of metal powder injection molding applications for transmission components.
Global Hot Runner Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and certification burden dimensions. The vendor base stratifies into three tiers: integrated system houses commanding automotive OEM direct relationships, specialized nozzle manufacturers serving medical qualification pathways, and regional component fabricators competing on delivery speed. Consolidation pressure concentrates among mid-tier system integrators facing raw material volatility and extended qualification timelines. Dominant competitive moves include backward integration into heater cartridge supply and technology licensing partnerships for sequential valve-gate control architectures.
Within the integrated system tier, Mold-Masters anchors North American automotive supply relationships through its hot half portfolio. EWIKON Heißkanalsysteme GmbH occupies a specialist position exemplifying German precision engineering in medical nozzle configurations. Husky Injection Molding Systems Ltd. represents scale-driven deployment capabilities across Asian packaging corridors.
| Leading Market Players |
|---|
| Mold-Masters |
| EWIKON Heißkanalsysteme GmbH |
| Husky Injection Molding Systems Ltd. |
| Barnes Group Inc. |
| GÜNTHER Heisskanaltechnik GmbH |
| INCOE Corporation |
| Synventive Molding Solutions |
| CACO PACIFIC Corporation |
| Yudo Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Tier-one automotive OEMs in Michigan and Bavaria now issue standalone hot runner technical specifications, shifting procurement toward direct vendor relationships that compress traditional moldmaker margins and restructure pricing power across the value chain. This buyer concentration favors integrated system houses with captive heater cartridge supply and ISO 13485 certification pathways.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the hot runner market by certification burden and thermal control sophistication. Premium tiers capture medical-grade ISO 13485-qualified systems with sub-millisecond valve-gate synchronization, while economy tiers serve high-volume automotive programs with standardized manifold configurations. Price differentiation hinges on heater cartridge watt-density specifications and sequential injection software licensing. Cost compression in mid-tier automotive supply chains is intensifying because copper and specialty steel volatility compresses integrator margins. Tier-one automotive OEMs exhibit lowest price sensitivity due to lightweighting mandates, whereas Indian electronics manufacturing PLI beneficiaries demonstrate highest sensitivity as greenfield facilities optimize capital deployment.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Guangzhou anchor hub-and-spoke patterns for hot runner component logistics, with final assembly co-located near precision molding clusters. Manufacturing concentration centers on Germany, China, and Japan for manifold block machining, heater cartridge winding, and controller firmware development. Raw material dependencies draw from Swedish tool steel foundries, Japanese high-watt-density heating element specialists, and German thermal sensor fabricators. Single-source vulnerability in heater cartridge supply creates structural risk, as MIIT efficiency directives and EU F-Gas Regulation simultaneously reshape procurement criteria. Distribution runs through mold builder intermediaries for standard automotive programs, while direct OEM relationships dominate electric vehicle platform launches and medical qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Hot Runner Market represents a late-cycle quality story as automotive lightweighting mandates and medical diagnostic consumption shift procurement toward premium electric manifold systems with ISO-certified thermal uniformity.
For Market Incumbents: Extend backward integration into heater cartridge production to neutralize Japanese and German component specialist concentration risk. Anchor long-term contracts with North American automotive OEMs through hot half portfolio standardization, while investing in sequential valve-gate software licensing to defend against emerging nozzle specialists targeting medical high-cavitation applications. For New Entrants and Emerging Players: Enter via bio-based polymer-compatible nozzle designs for PLA and PHA processing, where European packaging sustainability mandates accelerate qualification timelines. Target Tamil Nadu and Gujarat electronics manufacturing corridors under India's PLI scheme, where greenfield precision molding investment outpaces established supplier presence. Lead with IoT-enabled remote thermal monitoring subscriptions to differentiate from capital-equipment incumbents. For Investors and Strategic Acquirers: Automotive OEM thermal engineering groups are the most active acquirer in this space, consolidating direct vendor relationships for electric vehicle platform standardization. Mid-tier system integrators with ISO 13485 pathways and captive heater supply represent prime acquisition targets over a long-term viability window. Monitor ECHA candidate list expansions for nozzle tip coating substance restrictions as the inflection indicator for redesign cycle acceleration and qualification timeline extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heater Cartridge Supply | Captive production of high-watt-density elements neutralizes single-source vulnerability from Japanese specialists. |
| Sequential Valve-Gate Software Licensing | Synchronized multi-point injection eliminates weld lines for Michigan and Bavarian automotive OEM class-A surface requirements. |
| ISO 13485 Medical Certification Investment | Eighteen-to-twenty-four month qualification periods create defensive moats against mid-tier automotive competitors. |
| IoT-Enabled Remote Thermal Monitoring | Predictive maintenance subscriptions generate recurring revenue streams beyond capital equipment sales cycles. |
| Bio-Based Polymer Nozzle Development | Lower-temperature shear-sensitive designs capture European packaging sustainability mandate acceleration. |
Methodological Framework
Multiple input streams — primary interviews with hot runner system design engineers, mold builder procurement leads, and automotive OEM thermal engineering groups; secondary validation through SEC filings of listed machinery manufacturers, MIIT energy efficiency directive documentation, and ECHA substance restriction databases; plus customs trade data for tool steel and heater cartridge flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification requirements across German automotive clusters, Guangdong export molding corridors, and Michigan electric vehicle platform launches. Secondary sources included ISO certification registry analysis, EU F-Gas Regulation implementation timelines, and PLI scheme beneficiary disclosures for Indian electronics manufacturing.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass product type, technology architecture, end-use vertical, and material processed, with additional granularity for regional regulatory framework clusters. CAGRs were derived from installed base replacement cycles, greenfield capacity addition patterns, and technology displacement curves for hydraulic-to-electric transitions. Industry-specific forecast inputs incorporated MIIT efficiency directive compliance deadlines and REACH substance restriction phase-in schedules.
Inputs from primary stakeholder interviews and regulatory documentation were available through the study window; gaps in real-time heater cartridge pricing and mold builder inventory levels introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions regarding electric vehicle platform launch timelines and medical diagnostic consumption trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Dock Door Market
Construction Equipment
Press Brakes Market