
 Saudi Arabia Completion Equipment and Services Market | 2026-2036
Saudi Arabia Completion Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Completion Equipment and Services Market Analytics
National oil companies are rotating their procurement toward integrated service providers capable of delivering full-field development packages. Schlumberger Ltd anchors its position through deep vertical integration across well testing and artificial lift technologies. Baker Hughes Company differentiates via smart completion systems that merge downhole sensors with surface data analytics. Halliburton Company dominates stimulation services through established infrastructure in the Eastern Province.
Completion equipment and services encompass the hardware, tools, and engineered interventions required to prepare a drilled well for hydrocarbon production, including wellhead systems rated for pressures exceeding 15,000 psi and intelligent packers capable of zonal isolation in high-temperature reservoirs. Completion packers and safety valves command the largest product share due to their non-discretionary role in well integrity assurance across Saudi Aramco's mature and greenfield developments. Smart completion and integrated solutions represent the fastest-expanding technology categories as operators pursue real-time reservoir management and remote actuation capabilities in offshore and tight gas environments.
SFDA oversees occupational safety standards for downhole operations, while the IKTVA program mandates local value creation thresholds that foreign vendors must satisfy to qualify for Aramco contracts. These frameworks compel service companies to deepen Saudi-based manufacturing and engineering capacity, directly influencing market access conditions and partnership structures. Stakeholders must monitor how the Kingdom's gas expansion targets and unconventional resource development timelines reshape the relative priority of sand control versus artificial lift technologies.
Market Dynamics
Saudi Aramco's IKTVA program is compressing procurement timelines while mandating 70% local value creation, forcing foreign service providers to transfer manufacturing know-how to Saudi-based joint ventures or lose contract eligibility.
Growth Catalysts
- Gas expansion targets:The Kingdom's push to develop Jafurah and other unconventional gas fields is accelerating sand control and hydraulic fracturing service demand in the Eastern Province.
- IKTVA localization mandates:Aramco's supplier qualification framework rewards in-Kingdom manufacturing with preferential contract access, incentivizing fabrication facilities in Jubail and Ras Al-Khair.
- Intelligent completion adoption:Real-time zonal monitoring and remote actuation technologies are penetrating offshore and tight gas reservoirs as operators pursue reservoir optimization.
Market Restraints
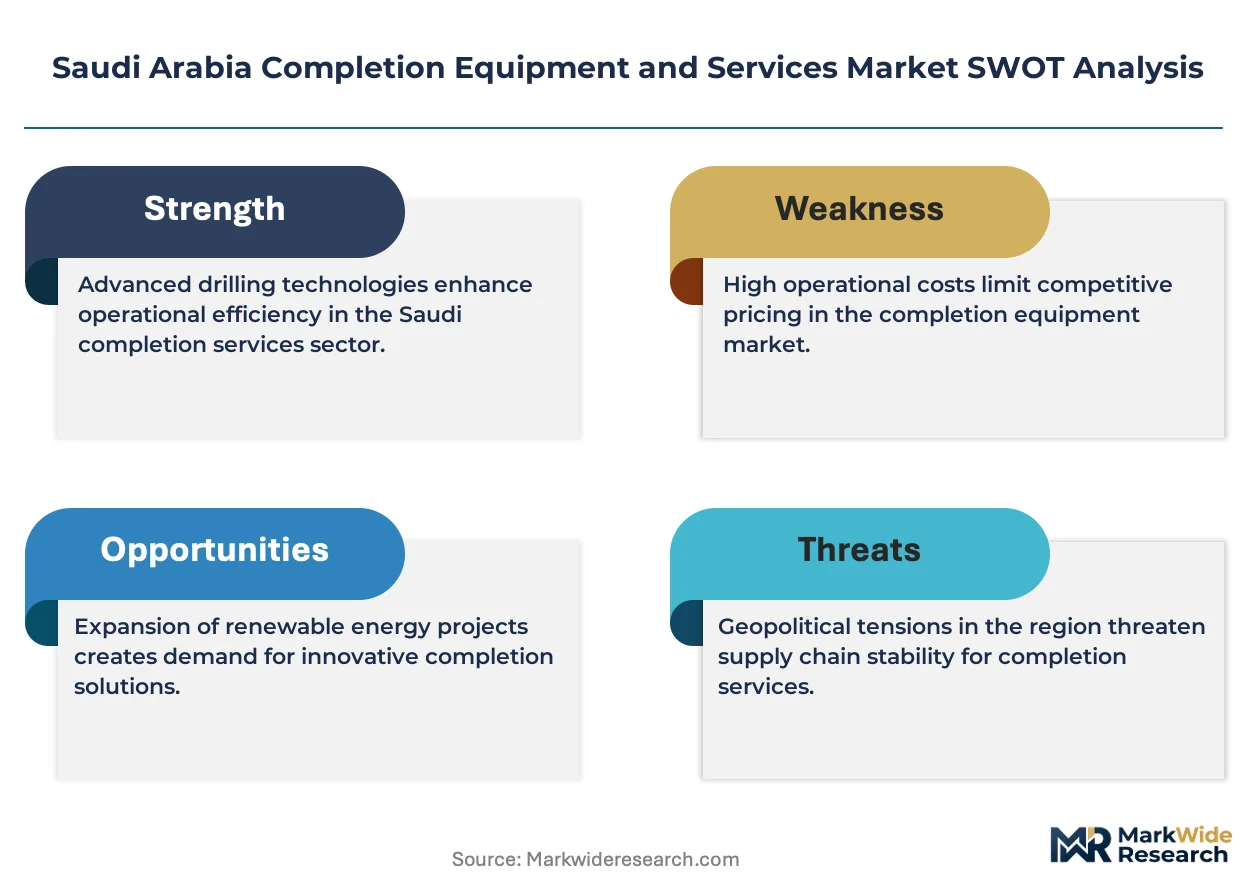
- Specialized alloy supply concentration:High-nickel alloys and premium OCTG grades for sour service wells rely on limited European and Japanese mill capacity, exposing procurement to lead time volatility.
- SFDA safety compliance costs:Downhole equipment certification for high-pressure high-temperature applications requires extensive third-party validation, extending qualification cycles for new market entrants.
- Technical talent scarcity:Completion engineering expertise in intelligent systems and digital wellbore architecture remains concentrated among a small pool of expatriate specialists and select Saudi university programs.
Strategic Opportunities
- Red Sea offshore frontier:Unexplored deepwater blocks offer greenfield demand for subsea completion systems and tieback technologies as exploration drilling accelerates.
- Artificial lift integration:Convergence of ESP monitoring with intelligent completion networks creates bundled service opportunities in mature Ghawar and Khurais developments.
- Jubail supply cluster expansion:The industrial city's emerging oilfield services corridor enables foreign vendors to satisfy IKTVA thresholds through localized machining and assembly operations.
Industry Challenges
- Digital-legacy system integration:Retrofitting smart completion sensors onto existing wellhead infrastructure in mature fields demands complex interface engineering and extended downtime windows.
- Certification timeline compression:SFDA and Aramco Materials System Specifications require simultaneous validation cycles, creating documentation bottlenecks for new technology introductions.
- Specialized workforce development:Training Saudi nationals in downhole tool assembly, pressure testing, and failure analysis remains slower than localization targets demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Completion Equipment and Services Market |
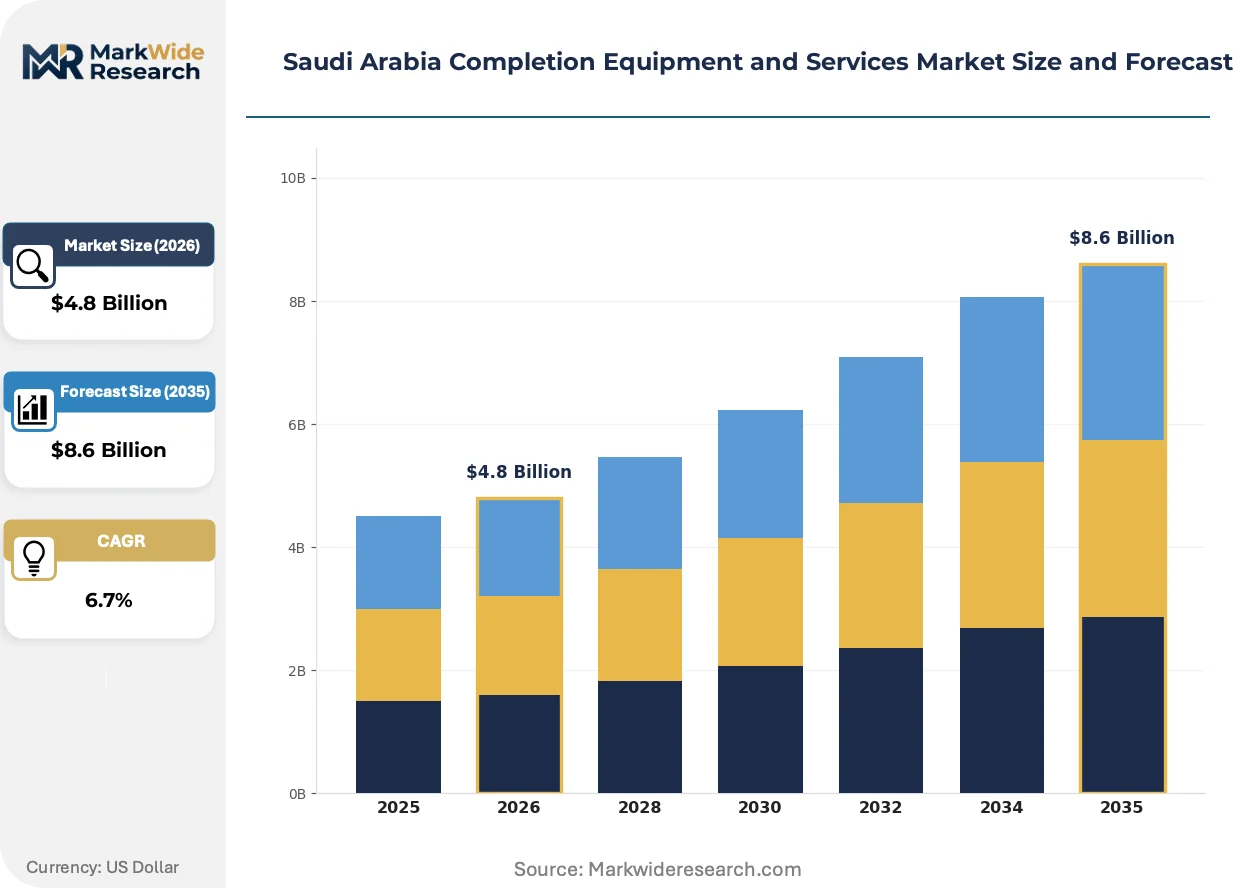
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wellhead Systems, Tubing Hangers, Completion Packers, Safety Valves Service Type: Well Testing, Cementing Services, Stimulation Services, Completion Installation End User: Oil & Gas Companies, Independent Producers, Service Contractors, National Oil Companies Technology: Smart Completion, Sand Control, Artificial Lift, Integrated Solutions |
| Companies Covered | Weatherford International plc, TAQA KSA, Schlumberger Ltd, Weir Group PLC, Superior Energy Services Inc, Halliburton Company, National-Oilwell Varco Inc, Welltec A/S, Baker Hughes Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Completion Equipment and Services Market Evolving Landscape
Downhole digitalization and local content enforcement are restructuring how completion technologies reach Saudi well sites. Vendors must now engineer for reservoir intelligence while manufacturing within Kingdom borders.
Intelligent packer systems with embedded fiber-optic sensing are bifurcating the completion hardware market. Aramco's unconventional gas divisions are specifying these for Jafurah shale wells at accelerating rates. The technology is bifurcating procurement patterns between premium integrated packages and conventional commodity completions.
SFDA's updated pressure equipment safety directives are tightening third-party inspection requirements for wellhead assemblies rated above 10,000 psi. Foreign fabricators now face mandatory in-Kingdom recertification even for ISO-compliant international products. Offshore project timelines are absorbing 4-6 month compliance extensions as documentation workflows adapt.
Service contract unbundling is fragmenting the traditional integrated provider model. Aramco's procurement teams are separating stimulation, artificial lift, and intelligent completion scopes to optimize IKTVA scoring across multiple Saudi-qualified vendors. The Eastern Province drilling corridor exhibits the most visible contract segmentation, with discrete awards for zonal isolation, sand control, and production optimization modules.
Saudi Arabia Completion Equipment and Services Market Segmentation
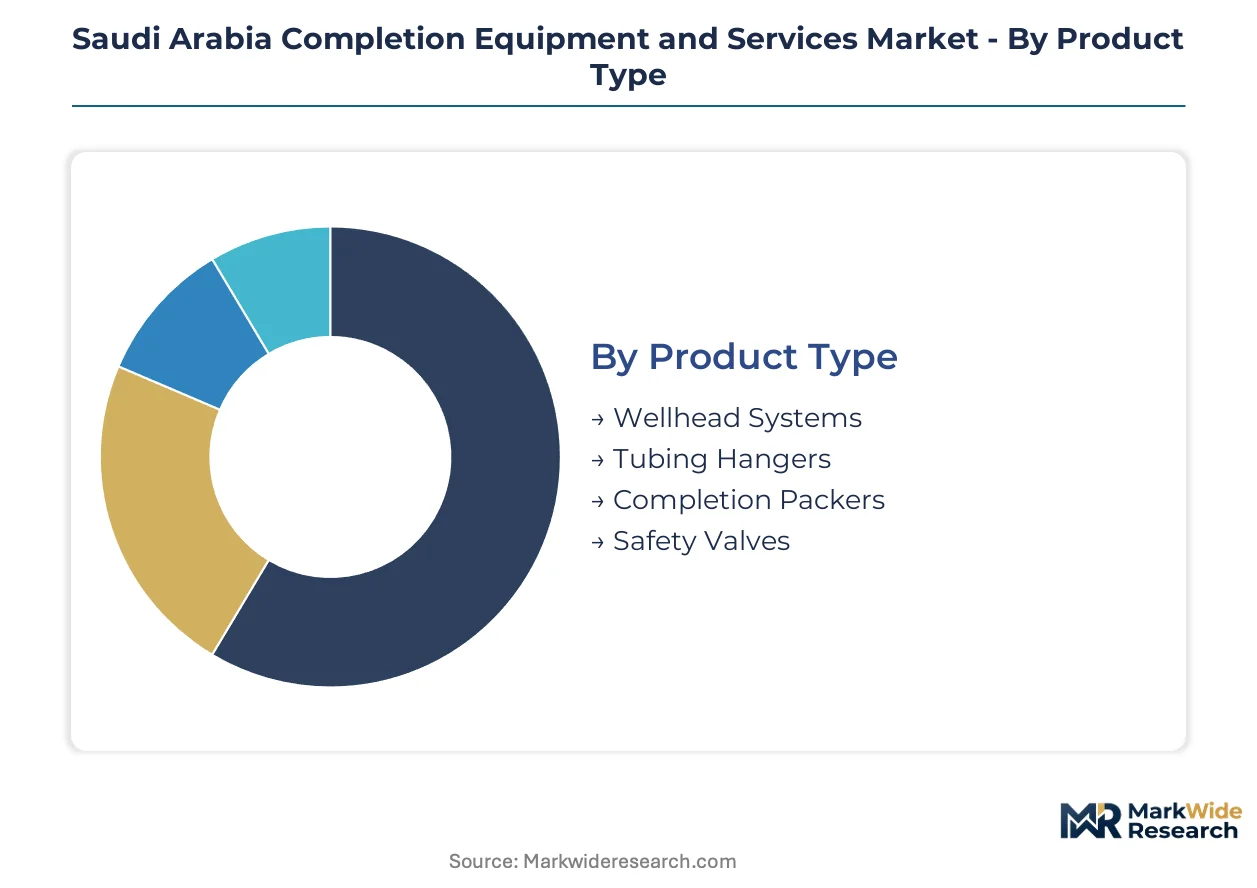
Saudi Aramco's IKTVA localization mandates are fragmenting procurement patterns across product and service categories. Vendors must now map segment-specific capabilities to Eastern Province manufacturing clusters and Rub' al-Khali basin deployment corridors to maintain contract eligibility.
Product Type:
Domestic fabrication concentrates in Jubail and Ras Al-Khair for pressure-containing equipment, while specialized alloy components remain import-dependent from European and Japanese mill sources.
- Wellhead Systems:Pressure-rated assemblies exceeding 15,000 psi integrate casing heads, tubing heads, and christmas trees for surface pressure control. Demand clusters around offshore Red Sea developments and high-pressure gas wells in Jafurah, with SFDA mandating in-Kingdom recertification even for ISO-compliant international products.
- Completion Packers:Elastomeric and mechanical sealing devices isolate production zones within the wellbore, with intelligent variants embedding fiber-optic sensing for real-time monitoring. Aramco's unconventional gas divisions are specifying these for tight gas reservoirs at accelerating rates.
- Tubing Hangers:Load-bearing components suspend production tubing within wellhead assemblies, typically manufactured from high-strength steel grades.
- Safety Valves:Downhole and surface barrier devices prevent uncontrolled hydrocarbon release, subject to rigorous SFDA pressure equipment directives.
Completion packers hold the largest share; momentum sits with intelligent packer systems.
Service Type:
Service contract unbundling is separating historically integrated scopes, with Aramco procurement teams disaggregating stimulation, artificial lift, and installation modules to optimize IKTVA scoring across multiple qualified vendors.
- Stimulation Services:Hydraulic fracturing and acidizing interventions enhance reservoir permeability in tight formations. The Kingdom's Jafurah shale development is accelerating sand control and fracturing demand in the Eastern Province.
- Well Testing:Diagnostic flow measurement and reservoir characterization services evaluate production potential prior to full completion. Offshore frontier blocks require subsea-capable testing packages with extended reach capabilities.
- Cementing Services:Zonal isolation and casing bond assurance through engineered slurry placement.
- Completion Installation:Downhole assembly deployment and pressure testing of packers, valves, and intelligent systems.
Stimulation services anchor current revenue; well testing is expanding most quickly in frontier exploration.
End User:
Customer concentration reflects Saudi Arabia's hydrocarbon sector structure, with national oil companies commanding dominant procurement volumes and independent producers gaining marginal access to marginal fields.
- National Oil Companies:Saudi Aramco and its subsidiaries drive procurement through IKTVA-weighted tenders favoring localized manufacturing. The company's Materials System Specifications and SFDA compliance requirements create dual validation bottlenecks for new technology introductions.
- Oil & Gas Companies:International operators participating in concession agreements and joint ventures. These entities must route procurement through Aramco-approved vendor lists, constraining direct supplier relationships.
- Independent Producers:Smaller operators targeting marginal fields and service contracts.
- Service Contractors:Tier-2 and tier-3 providers subcontracted for specialized installation and maintenance scopes.
National oil companies dominate volume; independent producers are gaining share fastest as marginal field licensing expands.
Technology:
Technology adoption bifurcates between premium integrated systems for unconventional and offshore applications versus conventional commodity completions for mature onshore developments.
- Smart Completion:Downhole sensor networks and remotely actuated valves enable real-time zonal monitoring and production optimization. Fiber-optic-enabled packers are penetrating Aramco's tight gas and offshore reservoirs as operators pursue reservoir intelligence.
- Integrated Solutions:Bundled hardware and service packages combining intelligent completion, artificial lift, and data analytics. Procurement teams are separating these scopes to optimize localization scoring, fragmenting the traditional integrated provider model.
- Sand Control:Screen and gravel pack systems prevent formation sand production in unconsolidated reservoirs.
- Artificial Lift:ESP and gas lift systems maintain production from pressure-depleted formations, with monitoring convergence creating bundled opportunities in Ghawar and Khurais.
Smart completion claims the steepest expansion trajectory; integrated solutions face procurement fragmentation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi completion equipment flows primarily from Eastern Province fabrication clusters toward Rub' al-Khali basin drilling sites and offshore Red Sea blocks, with procurement patterns increasingly governed by IKTVA localization thresholds.
Eastern Province
Dhahran anchors the Kingdom's hydrocarbon infrastructure with Saudi Aramco headquarters and the largest concentration of drilling activity. SFDA pressure equipment directives mandate in-Kingdom recertification for all wellhead assemblies above 10,000 psi. Jubail's industrial corridor hosts expanding machining and assembly operations as foreign vendors localize to satisfy IKTVA mandates.
Rub' al-Khali Basin
The Empty Quarter contains the Jafurah unconventional gas development driving sand control and hydraulic fracturing demand. Aramco's gas expansion targets accelerate intelligent completion adoption in tight reservoirs. Remote desert locations require specialized logistics corridors from Eastern Province supply bases.
Western Region
The Red Sea offshore frontier remains underexplored but attracts subsea completion system interest as exploration drilling accelerates. Deepwater blocks demand tieback technologies and extended-reach testing capabilities. Jeddah serves as the primary logistics hub for western offshore operations.
Riyadh
The capital coordinates national procurement policy and IKTVA compliance verification through Aramco's supplier qualification frameworks. Government ministries oversee SFDA safety standard updates and local content enforcement. Technical training programs at Saudi universities attempt to address completion engineering talent scarcity.
Saudi Arabia Completion Equipment and Services Market Competitive Landscape
Player mix skews toward integrated oilfield service conglomerates with deep vertical capabilities across well construction and production optimization. Market structure concentrates around three to five global providers capable of delivering full-field development packages under IKTVA-weighted tenders. Strategic archetypes include technology-integrated specialists, manufacturing-localized joint ventures, and stimulation-focused service providers. Dominant competitive moves encompass in-Kingdom fabrication partnerships and intelligent completion technology licensing arrangements.
Among U.S.-based integrated service providers, Schlumberger Ltd, Halliburton Company, and Baker Hughes Company exemplify the scale-driven tier capable of bundling hardware manufacturing with engineered interventions. These entities occupy positions where IKTVA compliance and technology transfer requirements converge, representing the archetype of foreign vendors restructuring Saudi operations around joint venture manufacturing and localized engineering capacity.
| Leading Market Players |
|---|
| Weatherford International plc |
| TAQA KSA |
| Schlumberger Ltd |
| Weir Group PLC |
| Superior Energy Services Inc |
| Halliburton Company |
| National-Oilwell Varco Inc |
| Welltec A/S |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Carbon steel wellhead assemblies displacing nickel-alloy specifications in lower-sour applications simultaneously compress procurement geography toward Jubail fabrication clusters and reset pricing economics across pressure-rated equipment tiers.
Pricing Analysis
Current-generation intelligent packer systems command substantial premiums over conventional mechanical packers, while next-generation fiber-optic-enabled variants enter limited deployment at elevated price points. Pricing stratifies across premium, standard, and economy tiers based on SFDA certification grade and Aramco Materials System Specification compliance level. Cost compression in standard-tier wellhead assemblies intensifies because IKTVA localization mandates force foreign vendors to absorb joint venture overhead. National oil companies exhibit lowest price sensitivity due to non-discretionary well integrity requirements, while independent producers negotiate aggressively on commodity completion hardware.
Supply Chain Analysis
Extended inventory cycles for high-nickel alloys and premium OCTG grades stretch lead times beyond standard procurement windows, forcing operators to buffer safety stock. Manufacturing draws from European and Japanese mill sources for sour-service alloys, while domestic machining concentrates in Jubail and Ras Al-Khair for pressure-containing assemblies. Single-source vulnerability in specialized metallurgy exposes procurement to mill capacity constraints and logistics chokepoints through Red Sea shipping corridors. Distribution runs through Aramco-approved vendor lists with tiered qualification tiers governing direct contract eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Aramco's procurement consolidation under IKTVA-weighted tenders concentrates buyer power among a single national oil company, reshaping supplier negotiation dynamics across the Eastern Province.
For Market Incumbents: Shield installed base relationships through accelerated Jubail manufacturing partnerships that satisfy localization thresholds before contract renewal cycles. Deepen captive supply of intelligent completion electronics through technology licensing with Saudi engineering joint ventures. Defensive positioning requires preemptive SFDA certification investments as the regulator tightens pressure equipment directives.
For New Entrants and Emerging Players: Lead with specialized sand control or well testing modules that slot into Aramco's unbundled procurement architecture. The Red Sea offshore frontier offers the most penetrable geography given limited incumbent subsea completion footprints. A go-to-market angle anchored in rapid SFDA qualification turnaround differentiates against established players burdened by legacy documentation workflows.
For Investors and Strategic Acquirers: The market sits at a localization-enforcement phase that favors manufacturing-localized joint ventures over pure technology licensors. Long-term viability across the five-to-ten year horizon hinges on IKTVA scorecard positioning rather than standalone technical differentiation. Acquisition targets should demonstrate established Jubail or Ras Al-Khair fabrication assets with Aramco supplier qualification already secured. The signal to watch is Aramco's unconventional gas drilling cadence, which dictates sand control and intelligent completion demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| In-Kingdom Manufacturing Joint Venture | Establishes IKTVA-compliant production capacity within Aramco's preferred supplier geography. |
| SFDA Pressure Equipment Certification | Enables contract eligibility for wellhead assemblies above 10,000 psi ratings. |
| Intelligent Packer Technology Licensing | Transfers fiber-optic sensing capabilities to Saudi-based engineering operations. |
| Jubail Supply Cluster Expansion | Positions fabrication facilities within the Eastern Province's emerging oilfield services corridor. |
| Artificial Lift Monitoring Integration | Creates bundled service opportunities converging ESP systems with completion networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade flow databases, and Aramco procurement disclosures to construct validated market estimates. Interviews with completion engineering directors, SFDA compliance officers, Aramco procurement managers, and Jubail facility operators informed demand segmentation and localization timeline assumptions. Secondary sources include Saudi Industrial Development Fund reports, Eastern Province customs records, and pressure equipment certification registries. Bottom-up equipment unit economics triangulate against top-down national oil company capital expenditure patterns.
Segmentation dimensions modeled span product type, service category, technology generation, and end-user procurement tier across the projection horizon. CAGRs derive from equipment deployment rates tied to drilling activity forecasts and technology substitution curves for intelligent versus conventional completions. Industry-specific inputs incorporate Jafurah shale development timelines, Red Sea offshore exploration licensing, and IKTVA scorecard weighting evolution.
Forecasts assume regulatory continuity in SFDA pressure equipment directives and IKTVA localization thresholds; material policy shifts would require re-modeling. Outputs reflect assumptions about Aramco drilling cadence, alloy mill capacity availability, and joint venture technology transfer pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electric Hot Chamber Die Casting Machines Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Sandblast Nozzle Market