
 Industrial and Commercial Floor Scrubbers Market | 2026-2036
Industrial and Commercial Floor Scrubbers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial and Commercial Floor Scrubbers Market Intelligence
Equipment leasing channels is tilting toward bundled service contracts that include preventive maintenance and consumables. Tennant Company leverages its direct service fleet to capture recurring revenue streams. Nilfisk Group anchors its position through specialized distribution partnerships in European industrial corridors. Kärcher competes on manufacturing scale, operating multiple production facilities that supply regional hubs with localized configurations.
Industrial and commercial floor scrubbers are motorized cleaning machines equipped with cylindrical or disc brushes, solution tanks, and vacuum recovery systems designed to remove debris and contaminants from hard floor surfaces in high-traffic environments. These machines typically operate at pressures ranging from 100 to 450 psi and incorporate squeegee assemblies that recover wastewater for compliant disposal. Walk-behind units still occupy the largest installed base across manufacturing floors, though rider models command higher per-unit margins and faster payback periods in facilities exceeding 50,000 square feet. Battery-powered operating mechanisms are displacing gas-powered alternatives as lithium-ion chemistry improves runtime and eliminates indoor emissions concerns in healthcare and retail end-user segments.
OSHA workplace safety standards mandate slip-resistant surfaces and documented cleaning protocols that elevate mechanized scrubbing above manual mopping in liability-sensitive industries. The EPA enforces wastewater discharge regulations that shape recovery tank capacities and filtration specifications for equipment sold into food processing and pharmaceutical manufacturing environments. Stakeholders must monitor battery recycling infrastructure development and regional energy grid carbon intensity, as these factors will determine total cost-of-ownership calculations and procurement criteria across commercial and industrial buyer segments.
Market Dynamics
Battery chemistry improvements and EPA indoor emissions enforcement are compressing payback periods for electrified fleets while devaluing propane-powered inventory across healthcare and retail estates.
Growth Catalysts
- OSHA Slip-Resistance Mandates:Documented mechanized cleaning protocols reduce liability exposure in food processing and pharmaceutical manufacturing. Facilities mechanize to satisfy incident documentation requirements.
- Lithium-Ion Runtime Extension:Shift work compatibility now matches gas-powered runtime without refueling infrastructure. Warehouses above 100,000 square feet accelerate fleet turnover.
- Sun Belt Commercial Expansion:Arizona, Florida, and Texas retail and logistics construction concentrates demand for rider-scrubber deployments in climate-controlled distribution environments.
Market Restraints
- Critical Mineral Supply Concentration:Cobalt and lithium processing concentrates in the Democratic Republic of Congo and Chilean salars. Battery pack costs fluctuate with extraction licensing delays.
- Skilled Technician Scarcity:Brush motor rebuilds and squeegee calibration require electro-mechanical competency absent from standard janitorial staffing models. Service network coverage gaps persist outside metropolitan cores.
- Propane Infrastructure Sunk Costs:Existing fleet depots and bulk tank installations lock institutional buyers into combustion equipment refresh cycles despite operating cost disadvantages.
Strategic Opportunities
- EPA Clean Air Act Tier 4 Compliance Deadlines:Indoor emissions thresholds tighten enforcement in 2026-2028 windows. Battery-powered equipment qualifies for accelerated depreciation under IRA commercial clean vehicle provisions.
- Autonomous Navigation Convergence:Lidar mapping and obstacle-avoidance algorithms from warehouse robotics transfer to scrubber platforms. Early deployments target overnight cleaning in healthcare corridors.
- Rental-Subscription Channel Expansion:Equipment-as-a-service bundles preventive maintenance and consumables. Mid-market facilities below 50,000 square feet access rider-scrubber capability without capital commitment.
Industry Challenges
- Cross-Contamination Protocol Integration:Healthcare facilities require color-coded brush systems and validated disinfection sequences. Scrubber specification conflicts with existing mop-bucket standard operating procedures.
- Wastewater Discharge Permitting:EPA NPDES variances for recovery tank contents vary by municipality. Multi-site operators face fragmented compliance documentation across state lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial and Commercial Floor Scrubbers Market |
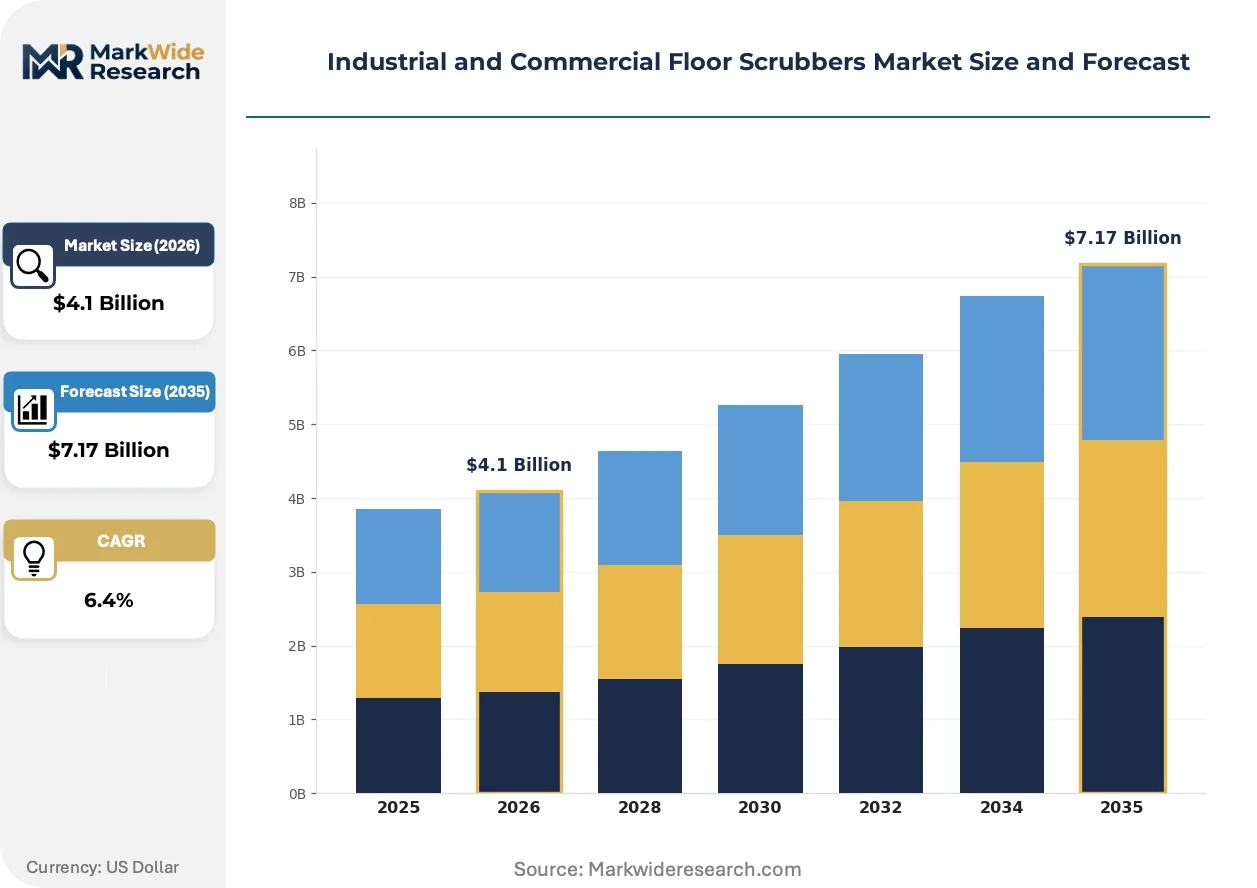
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-behind, Rider, Automated, Hybrid End User: Manufacturing, Retail, Hospitality, Healthcare Operating Mechanism: Battery-Powered, Electric, Gas-Powered, Manual Market Segment: Commercial, Industrial, Government, Others |
| Companies Covered | Tennant Company, Nilfisk Group, Kärcher, Hako GmbH, Diversey, Inc., Amano Corporation, Numatic International, Dulevo International S.p.A., Factory Cat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial and Commercial Floor Scrubbers Market Strategic Shifts & Innovations
Scrubber platforms are absorbing sensor and connectivity architectures from adjacent industrial equipment categories. This convergence compresses differentiation cycles and elevates software service attach rates above hardware margins.
IoT-enabled fleet management is digitizing utilization tracking and predictive maintenance scheduling. Large retail chains deploy connected scrubbers to optimize route efficiency across 500-plus store networks. Real-time brush-wear telemetry is digitizing inventory planning for consumables and reducing unplanned downtime in 24-hour logistics operations.
EPA enforcement of the Clean Air Act's indoor emissions standards is accelerating battery-electric procurement timelines. Facilities within non-attainment zones face inspection priority designation that elevates compliance risk for propane equipment. Healthcare systems in California and northeastern corridor states are retiring combustion fleets ahead of scheduled replacement cycles to preempt regulatory exposure.
Leasing structures with embedded service obligations are displacing outright purchase in mid-market accounts. Third-party facility management providers bundle scrubber access into square-footage-based contracts. This shift concentrates procurement authority at regional FM consolidators and reduces manufacturer direct sales penetration in the 25,000-75,000 square foot facility segment.
Industrial and Commercial Floor Scrubbers Market Segmentation
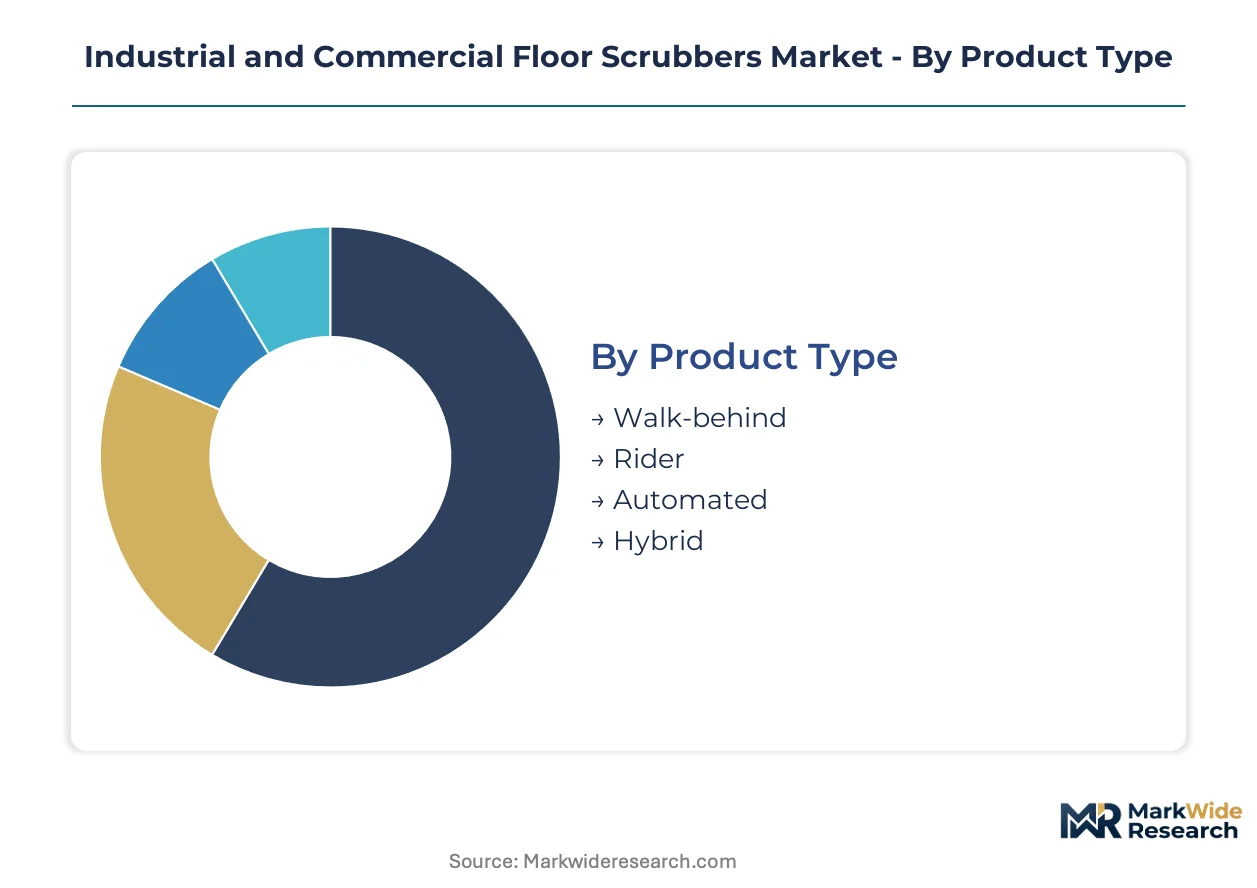
Floor scrubber procurement varies sharply by facility square footage, shift structure, and regulatory exposure. Segmentation reveals where electrification investments concentrate and which buyer profiles prioritize autonomous capability over capital cost.
Product Type:
Use-case spectrum spans compact walk-behind units for congested retail aisles to autonomous platforms for overnight healthcare corridors.
- Walk-behind:Cylindrical or disc brush configurations operating at 100-450 psi dominate manufacturing floors below 50,000 square feet. Demand concentrates in Sun Belt distribution centers where shift supervisors prioritize maneuverability over speed.
- Rider:Seated-operator designs with 36-48 inch cleaning paths deliver faster payback in facilities exceeding 50,000 square feet. Arizona and Texas logistics hubs accelerate fleet turnover here as lithium-ion runtime matches gas-powered alternatives.
- Automated:Lidar-equipped platforms with obstacle-avoidance algorithms target overnight cleaning in liability-sensitive healthcare environments.
- Hybrid:Dual-power architectures bridge battery-electric and combustion capabilities for facilities with intermittent grid reliability.
The dominant share belongs to Walk-behind, while Automated is closing the gap fastest.
End User:
Cost tier differentiation separates capital-intensive manufacturing deployments from service-contract-driven hospitality estates.
- Manufacturing:OSHA slip-resistance mandates and documented cleaning protocols drive mechanized scrubbing in food processing and pharmaceutical plants. EPA wastewater discharge regulations shape recovery tank specifications here.
- Healthcare:Color-coded brush systems and validated disinfection sequences address cross-contamination protocols. California and northeastern corridor systems retire combustion fleets preemptively to avoid Clean Air Act exposure.
- Retail:Large chains deploy connected scrubbers across 500-plus store networks for route optimization.
- Hospitality:Third-party facility management providers bundle scrubber access into square-footage-based contracts.
Manufacturing commands the largest installed base, though Healthcare is expanding most quickly as autonomous navigation converges with overnight cleaning requirements.
Operating Mechanism:
Application environment dictates power source selection, with indoor emissions thresholds eliminating gas-powered alternatives in regulated zones.
- Battery-Powered:Lithium-ion chemistry improvements extend runtime to match shift-work compatibility without refueling infrastructure. IRA commercial clean vehicle provisions enable accelerated depreciation.
- Electric:Corded configurations persist in fixed-route industrial corridors with reliable grid access.
- Gas-Powered:Propane infrastructure sunk costs lock institutional buyers into combustion refresh cycles despite operating cost disadvantages.
- Manual:Push-powered units retain niche presence in small-format retail below 10,000 square feet.
Battery-Powered leads procurement timelines, while Electric maintains steady replacement demand in mature industrial corridors.
Market Segment:
Customer type determines whether procurement flows through capital budgets or operational expenditure structures.
- Commercial:Leasing channels with embedded service obligations displace outright purchase in mid-market accounts. Regional FM consolidators concentrate authority in the 25,000-75,000 square foot facility segment.
- Industrial:Direct sales penetration remains highest here as specialized recovery tank capacities and filtration specifications require manufacturer consultation.
- Government:Municipal procurement cycles favor standardized specifications and multi-year maintenance contracts.
- Others:Educational institutions and transportation terminals represent fragmented demand with extended replacement cycles.
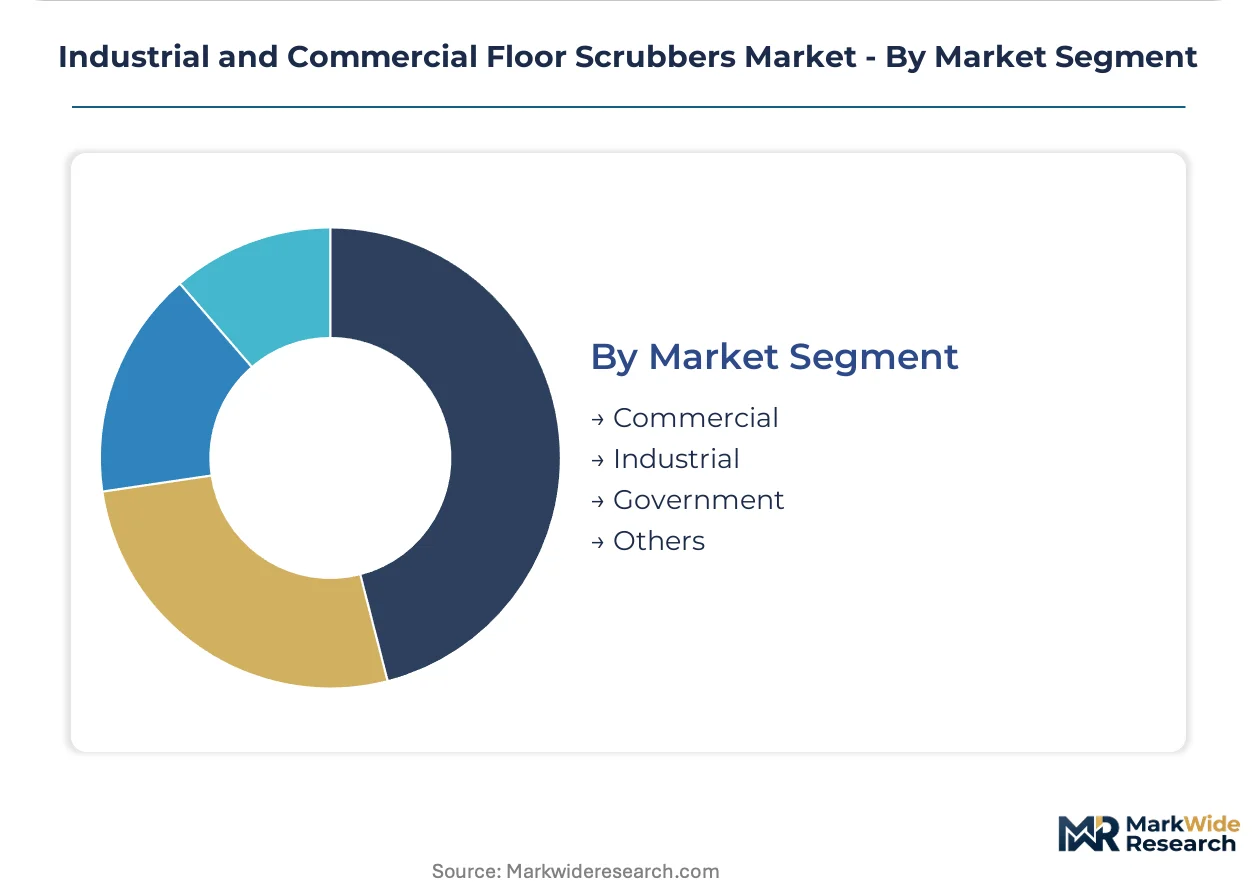
Commercial segment holds the dominant position, while Industrial is gaining share fastest through specialized specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European distribution hub demand for mechanized cleaning fleets. Texas's Permian Basin logistics corridors anchor North American rider-scrubber deployment velocity. Japan's Shinkansen maintenance depots drive precision-engineered compact unit specifications.
United States
Sun Belt commercial real estate expansion concentrates rider-scrubber procurement in Arizona, Florida, and Texas distribution centers. EPA Clean Air Act indoor emissions enforcement accelerates battery-electric fleet turnover in California and northeastern corridor healthcare systems. Dallas-Fort Worth logistics hubs deploy connected scrubber fleets across climate-controlled warehousing estates exceeding 100,000 square feet.
Germany
Industrial corridor manufacturing floors in North Rhine-Westphalia sustain walk-behind unit demand for OSHA-equivalent slip-resistance compliance. EU Green Deal carbon intensity benchmarks elevate battery-electric procurement criteria in Baden-Württemberg automotive supplier plants. Stuttgart's precision manufacturing clusters specify recovery tank capacities aligned with pharmaceutical wastewater discharge regulations.
China
Yangtze River Delta logistics parks absorb automated scrubber platforms for overnight cleaning in e-commerce fulfillment centers. MEE indoor air quality standards tighten emissions thresholds in Beijing-Tianjin-Hebei manufacturing zones. Shenzhen's electronics assembly corridors deploy lithium-ion fleets to eliminate propane infrastructure in cleanroom-adjacent environments.
Japan
Kanto region hospital networks pioneer autonomous navigation deployment in liability-sensitive healthcare corridors. METI energy efficiency standards shape battery chemistry selection in Osaka-Kansai industrial estates. Nagoya's automotive manufacturing clusters integrate scrubber fleet telemetry with existing production line monitoring systems.
Industrial and Commercial Floor Scrubbers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in brush motor and squeegee assemblies. The vendor base concentrates around three strategic archetypes: direct-service fleet operators capturing recurring revenue, scale manufacturers supplying regional hubs with localized configurations, and specialized distribution partnerships anchoring European industrial corridors. Dominant competitive moves include bundled service contract expansion and autonomous navigation capability licensing from adjacent warehouse robotics.
Among established platform integrators, Tennant Company, Nilfisk Group, and Kärcher occupy positions reflecting distinct geographic and channel strategies. Tennant exemplifies the direct-service fleet archetype with embedded preventive maintenance obligations. Nilfisk represents specialized distribution partnership models concentrated in European industrial corridors. Kärcher anchors scale-driven manufacturing with multiple production facilities supplying regional hubs.
| Leading Market Players |
|---|
| Tennant Company |
| Nilfisk Group |
| Kärcher |
| Hako GmbH |
| Diversey, Inc. |
| Amano Corporation |
| Numatic International |
| Dulevo International S.p.A. |
| Factory Cat |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese lithium-ion battery cell production is compressing pack costs for scrubber OEMs while simultaneously eroding supplier pricing power across the battery-electric equipment tier. This utilization dynamic forces component suppliers toward volume commitments and long-term offtake structures that downstream manufacturers leverage into competitive equipment pricing.
Pricing Analysis
Volume-discount tiering structures dominate procurement between fleet operators and OEMs, with three-tier pricing separating autonomous platforms from rider-scrubbers from walk-behind units. Price differentiation rests on battery chemistry grade and EPA Clean Air Act compliance certification, with Tier 4-ready battery systems commanding premiums over transitional configurations. Cost compression in the mid-market walk-behind segment is intensifying due to contract-manufacturing expansion in Asian production hubs. Third-party facility management providers exhibit the highest price sensitivity, while healthcare systems with liability exposure demonstrate relative inelasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with Taiwanese and South Korean electronics foundries producing motor controllers and IoT connectivity modules for autonomous scrubber platforms. Geographic supply concentration centers on China for lithium-ion cells, Germany for precision brush motors, and the United States for squeegee assemblies and vacuum recovery systems. Raw material dependencies include cobalt from the Democratic Republic of Congo, lithium carbonate from Chilean salars, and rare-earth magnets for brush motor efficiency. Single-source vulnerability in cobalt hydroxide refining creates exposure to extraction licensing delays. Distribution runs through specialized industrial equipment dealers and direct-service fleets in North American and European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as scrubber telemetry converges with warehouse management systems and building automation protocols. Interoperability with existing enterprise software stacks is becoming the primary ecosystem lock-in mechanism.
For Market Incumbents: Build data-asset moats through connected fleet telemetry that embeds scrubber platforms into broader facility management software ecosystems. Tennant Company's direct-service fleet model offers a template for capturing recurring revenue through preventive maintenance bundling. Defensive moves should prioritize backward integration into battery pack assembly to insulate margins from cobalt price volatility. Capacity addition in Sun Belt logistics corridors will preempt emerging regional competitors. For New Entrants and Emerging Players: Geographic underpenetration in secondary European industrial corridors outside Germany's North Rhine-Westphalia cluster offers white-space expansion potential. Mid-market healthcare facilities below 100,000 square feet remain underserved by autonomous navigation solutions calibrated for larger estates. Rental-subscription channel partnerships with regional facility management consolidators provide the most penetrable go-to-market angle without capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward software-enabled service platforms with embedded hardware access rather than pure equipment manufacturers. Long-term viability across the next decade hinges on autonomous navigation capability and recurring revenue attach rates. Acquisition targets should demonstrate existing IoT fleet management deployments with proven utilization telemetry. The signal to watch is EPA enforcement intensity in non-attainment zones, which would accelerate fleet turnover timelines and concentrate procurement authority at compliant platform providers.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Licensing | Lidar mapping algorithms from warehouse robotics transfer to overnight healthcare corridor cleaning deployments. |
| Battery Supply Agreement | Long-term cobalt and lithium offtake contracts insulate margins from critical mineral price volatility. |
| Platform Integration | Scrubber telemetry interoperability with building automation systems creates enterprise software stickiness. |
| Service Fleet Expansion | Direct preventive maintenance coverage in Sun Belt logistics corridors captures recurring revenue streams. |
| Geographic Manufacturing Footprint | Regional assembly hubs in Texas and Arizona reduce delivery costs for rider-scrubber deployments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across manufacturing and healthcare facilities, combined with secondary validation through SEC 10-K filings, EPA enforcement databases, customs trade data, and industrial equipment registration records. Bottom-up triangulation across facility square footage estimates and equipment replacement cycles was cross-referenced with top-down market sizing derived from lithium-ion battery pack shipment data and scrubber motor controller import volumes.
Forecast inputs considered product type segmentation across walk-behind, rider, and autonomous platforms; end-user differentiation between manufacturing, healthcare, retail, and hospitality estates; operating mechanism shifts from propane to battery-electric; and market segment variation between commercial leasing and industrial direct purchase. CAGRs were derived from regression analysis of historical fleet turnover rates against regulatory enforcement intensity and lithium-ion cost curves. Industry-specific inputs included OSHA slip-resistance mandate adoption timelines and EPA Clean Air Act non-attainment zone designations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autonomous navigation specialists from adjacent warehouse robotics would shift outcomes beyond modeled parameters. Forecasts reflect assumptions about battery chemistry improvement trajectories and regional energy grid carbon intensity evolution. Specific risk factors include critical mineral export restriction policies, skilled technician training pipeline constraints, and fragmented EPA NPDES wastewater discharge permitting across municipal jurisdictions. Quarterly review of EPA enforcement priority designations and cobalt hydroxide spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mini Excavators Market
Construction Equipment
Construction Pump Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Boom Cranes Market