
 Surface Drilling Rig Market | 2026-2036
Surface Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Drilling Rig Market Analysis
Chinese steel foundries and South Korean hydraulic component makers are decoupling from traditional European supply schedules for rig chassis and mast assemblies. Atlas Copco AB leverages its captive compressor technology to dominate integrated drill string systems. Komatsu Ltd. anchors its position through backward integration into smart machine control hardware.
Surface drilling rigs are self-propelled or skid-mounted machines engineered to create boreholes in rock or overburden using rotary, percussive, or auger mechanisms, typically delivering compressed air or fluid at pressures exceeding 20 bar to clear cuttings and stabilize the hole wall; their primary purpose is to enable mineral discovery, geotechnical characterization, and production blasthole drilling across hard-rock terrain. Rotary drills command the largest installed base in open-pit iron ore and coal operations, while DTH drills capture premium pricing in deep-hole hard-rock applications where penetration rates determine mine economics. Remote-controlled technology is expanding fastest in underground-to-surface teleremote applications, though semi-automatic rigs still constitute the majority of current replacement demand.
EPA Tier 4 Final and EU Stage V emission frameworks are tightening particulate and NOx thresholds for diesel-powered rigs, compelling OEMs to certify hybrid-electric powertrains or face restricted market access in regulated jurisdictions. MSHA and OSHA anchoring requirements for operator exposure to whole-body vibration and noise are accelerating cabin redesign cycles and sensor-based proximity system adoption. Stakeholders must weigh the capital cost of full automation against the operational savings from reduced labor exposure in remote or high-altitude deployments.
Market Dynamics
Autonomous drilling capability is compressing fleet replacement cycles as mining operators prioritize labor reduction in hazardous extraction zones. EPA Tier 4 Final and EU Stage V emission mandates are forcing diesel-electric hybrid retrofits that add capital cost but unlock regulated market access.
Growth Catalysts
- Copper-gold belt expansion:Andean mining corridors in Chile and Peru are driving fleet orders for deep-hole capable rigs as ore grades decline and stripping ratios increase.
- EPA Tier 4 Final compliance:North American contractors must certify hybrid-electric powertrains to maintain access to federal and state mining leases, accelerating technology refresh.
- Remote teleremote deployment:Underground-to-surface control architectures are penetrating hard-rock iron ore operations where operator safety limits conventional manned drilling.
Market Restraints
- High-grade steel input volatility:Rig mast and chassis fabrication depends on specialized alloy plate subject to Chinese export quota fluctuations.
- Hydraulic component concentration:Precision piston pumps and valves concentrate among South Korean and German suppliers, creating single-source vulnerability.
- NOx aftertreatment complexity:Selective catalytic reduction systems add maintenance burden and cold-start reliability issues in high-altitude Andean deployments.
Strategic Opportunities
- Autonomous retrofit kits:Semi-automatic rig installed base presents aftermarket sensor and control upgrade potential for mid-tier contractors.
- Battery-electric powerpacks:Lithium-titanate battery systems are converging with onboard compressor drives to eliminate diesel engines in underground applications.
- EU Green Deal alignment:Carbon border adjustment mechanisms will favor low-emission rig suppliers in European mining equipment procurement.
Industry Challenges
- Mechatronics technician scarcity:Integration of hydraulic, electric, and control systems requires cross-trained maintenance personnel rarely available in remote mining districts.
- MSHA whole-body vibration certification:Cabin redesign cycles for operator exposure compliance extend product development timelines and test facility bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Drilling Rig Market |
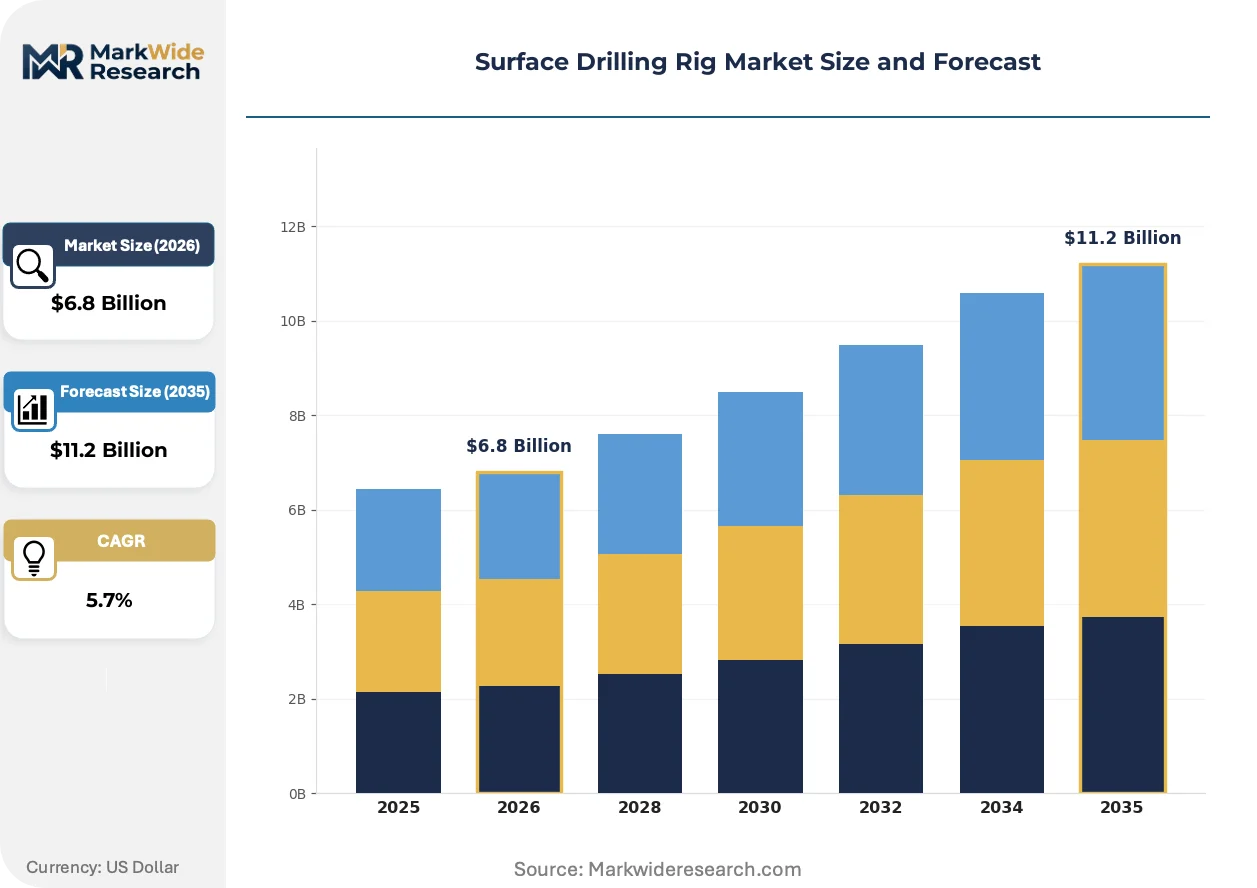
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Drills, DTH Drills, Auger Drills, Hydraulic Push End User: Mining, Construction, Oil & Gas, Geothermal Technology: Automatic, Semi-Automatic, Manual, Remote-Controlled Application: Exploration, Site Preparation, Water Wells, Mineral Extraction |
| Companies Covered | Atlas Copco AB, Komatsu Ltd., Sandvik AB, Furukawa Rock Drill Co., Ltd., Liebherr Group, Epiroc AB, Boart Longyear Ltd., Vermeer Corporation, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Drilling Rig Market Emerging Trajectories
Drill string automation and edge-computing control architectures are redistributing operational intelligence from centralized mine control rooms to rig-mounted processing units. This shift compresses latency for penetration-rate optimization while reducing fiber-dependent infrastructure.
Autonomous drill pattern execution is decentralizing blasthole planning authority from mine engineers to onboard LiDAR and gyroscopic navigation systems. Tier-one copper operators in Chile are deploying these systems at scale. Real-time ore boundary detection is compressing overbreak and reducing downstream processing costs.
EU Stage V emission frameworks are compelling OEMs to certify hybrid-electric architectures or surrender regulated jurisdiction market access. The industrial consequence is a bifurcation between compliant premium platforms and restricted-territory legacy diesel sales. Underground coal and metal mines in Germany and Poland are absorbing the steepest compliance cost increases.
Service contract unbundling is fragmenting traditional full-wrap maintenance agreements into component-level subscriptions. Drill bit and consumable suppliers are capturing direct relationships with mine procurement departments. This pattern is most visible in Australian iron ore operations where contractor drilling services face margin compression from itemized sourcing.
Surface Drilling Rig Market Segmentation
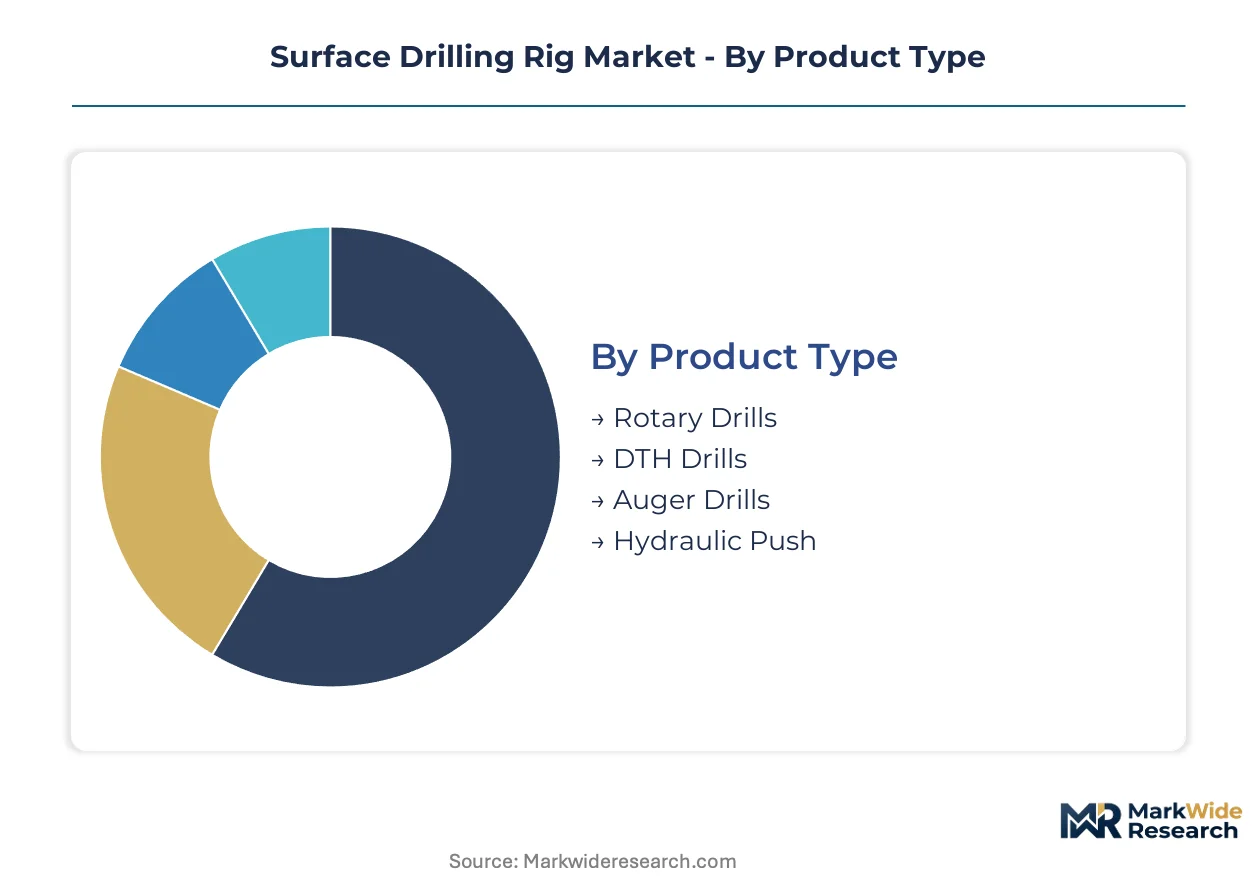
Surface drilling rig segmentation reflects divergent engineering requirements across rock hardness, hole depth, and automation intensity. Procurement patterns fragment between bulk fleet operators prioritizing penetration rate and specialized contractors demanding pattern precision.
Product Type:
Technology specifications differentiate rig architectures through rock-breaking mechanism and energy transmission path.
- Rotary Drills:Tricone or PDC bit rotation delivers continuous cutting action through roller bearing assemblies. Open-pit iron ore operations in Western Australia and coal basins across Wyoming concentrate demand where high-volume, medium-depth blastholes dominate fleet economics.
- DTH Drills:Percussive energy transmits through the drill string to a down-the-hole hammer, achieving superior penetration in hard crystalline formations. Deep-hole applications in Chilean porphyry copper deposits and Swedish iron ore mines drive premium pricing as ore grades decline.
- Auger Drills:Helical flighting extracts soft overburden without fluid circulation. Shallow geotechnical programs and environmental sampling in the US Gulf Coast sedimentary basins absorb most unit placements.
- Hydraulic Push:Static thrust combined with rotation penetrates unconsolidated formations. Water well contractors across the Great Plains and geothermal slim-hole pre-collars in Nevada represent primary end-uses.
Mature deployment sits with Rotary Drills. Newer deployment is concentrated in DTH Drills.
End User:
Customer economics vary dramatically between capital-intensive extraction and project-based contracting.
- Mining:Tier-one operators in the Andean copper-gold belt and Pilbara iron ore region deploy autonomous-capable fleets exceeding 50 units. Fleet standardization reduces spare parts inventory and technician training overhead across dispersed mine sites.
- Construction:Highway foundation piling and dam anchoring programs in Turkey and Colombia absorb mid-size rotary units. Project duration uncertainty compresses rental-versus-purchase decision cycles.
- Oil & Gas:Casing installation and conductor driving for unconventional wells in the Permian Basin and Vaca Muerta formation. Rig mobility requirements exceed mining specifications due to pad-to-pad relocation frequency.
- Geothermal:Slim-hole temperature gradient drilling and production well completion in Iceland and Kenya's Rift Valley. Corrosion-resistant metallurgy commands specification premiums.
Volume concentration rests with Mining. Margin expansion is climbing the fastest in Geothermal.
Technology:
Control architecture sophistication determines labor exposure, shift coverage, and pattern accuracy.
- Automatic:Closed-loop drill pattern execution with LiDAR collision avoidance and real-time ore boundary detection. Chilean copper operators and Australian iron ore majors are scaling deployment where labor scarcity intersects with high-altitude or remote site conditions.
- Semi-Automatic:Operator-supervised rod handling and depth control with automated leveling and mast positioning. This configuration dominates current replacement demand across mid-tier contractors balancing capital constraints against productivity targets.
- Manual:Direct operator control over all drilling parameters. Legacy fleet persistence in developing mining districts and small-scale water well drilling sustains residual demand.
- Remote-Controlled:Teleremote operation from surface control rooms for underground-to-surface applications. Hard-rock iron ore mines in Sweden and Canada are adopting this architecture to eliminate operator exposure to ground fall hazards.
Installed base concentration sits with Semi-Automatic. Technology refresh is accelerating fastest in Automatic.
Application:
Hole purpose dictates diameter range, depth capability, and cuttings handling requirements.
- Exploration:Core recovery and reverse circulation drilling for mineral resource definition. Junior mining companies across Canada's Abitibi belt and Nevada's Carlin trend sustain demand for heli-portable and track-mounted configurations.
- Site Preparation:Blasthole drilling for overburden removal and bench development. Large-diameter rotary drills in South African platinum operations and Indonesian nickel laterite mines define fleet specifications.
- Water Wells:Aquifer development for municipal supply and agricultural irrigation. Rural India and sub-Saharan Africa absorb compact truck-mounted units with mud rotary capability.
- Mineral Extraction:Production blasthole drilling in hard-rock open pits. Fleet scale and automation intensity peak in this application, with single mines operating 30-plus rigs on coordinated patterns.
Revenue concentration sits with Mineral Extraction. Specification complexity is expanding most quickly in Exploration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's copper-gold porphyry deposits anchor the hemisphere's rig demand, with Australian iron ore corridors and South African platinum belts forming complementary demand poles across three continents.
Chile
Declining ore grades in the Andean copper-gold belt force deeper blasthole programs requiring high-pressure DTH capability. The Ministry of Mining's National Mining Policy prioritizes productivity-enhancing equipment imports for state lease compliance. Antofagasta and Calama host concentrated fleet deployments where Codelco and BHP operate autonomous-capable rig fleets exceeding fifty units per site.
Australia
Pilbara iron ore majors pursue labor reduction through teleremote drilling architectures across dispersed open-pit operations. Work Health and Safety Queensland mandates whole-body vibration exposure limits that accelerate cabin redesign cycles. Perth serves as the regional procurement hub where contractor drilling services consolidate maintenance contracts for standardized fleet configurations.
United States
Permian Basin unconventional oil development drives conductor driving and casing installation demand with pad-to-pad mobility requirements exceeding mining specifications. EPA Tier 4 Final emission thresholds restrict diesel-only rig access to federal mining leases, compelling hybrid-electric certification. Wyoming's Powder River Basin coal operations absorb rotary drill placements for medium-depth overburden removal.
Sweden
Kiruna and Malmberget iron ore mines deploy underground-to-surface remote-controlled rigs to eliminate operator exposure to ground fall hazards. The Swedish Work Environment Authority enforces strict noise and vibration limits that shape cabin specification requirements. Sandviken anchors precision manufacturing clusters for drill string automation components serving Nordic and export markets.
Peru
Quellaveco and Las Bambas copper expansions sustain fleet orders for deep-hole capable rigs as stripping ratios increase. The Ministry of Energy and Mines implements equipment traceability regulations for large-scale mining concessions. Arequipa and Cusco regions concentrate exploration contractor activity where junior mining companies deploy heli-portable configurations for resource definition programs.
Surface Drilling Rig Market Vendor Landscape
Global majors compete with regional champions across technology integration depth, with consolidated compressor and hydraulic supply chains favoring vertically integrated incumbents while specialized fabricators capture aftermarket retrofit niches. Market structure tilts toward tiered concentration where captive component production separates premium-platform OEMs from assembly-dependent challengers. Three archetypes dominate: integrated systems houses with captive compressor technology, construction-equipment conglomerates with smart control hardware backward integration, and regional mast-and-chassis fabricators serving price-sensitive contractor segments. Competitive moves concentrate on M&A for autonomy software capabilities and strategic partnerships for battery-electric powerpack development.
Within the integrated systems tier, Atlas Copco AB and Epiroc AB exemplify archetypes anchored by captive air compression and drill string automation expertise. Komatsu Ltd. occupies a distinct position as a construction-equipment conglomerate with in-house smart machine control hardware production. These three entities represent the premium-platform vector where emission compliance and autonomous capability converge.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Komatsu Ltd. |
| Sandvik AB |
| Furukawa Rock Drill Co., Ltd. |
| Liebherr Group |
| Epiroc AB |
| Boart Longyear Ltd. |
| Vermeer Corporation |
| Caterpillar Inc. |
| Others |
Supply Flow & Price Mechanics
Hybrid-electric powertrain certification is compressing cost structures for Tier 4 Final and Stage V compliant rigs while concentrating procurement leverage among OEMs with captive compressor and control system production. Australian and Chilean mining operators now face extended lead times for emission-compliant platforms, forcing price premiums that reflect engineering complexity rather than component scarcity alone.
Pricing Analysis
Service contract unbundling separates drill bit and consumable subscriptions from full-wrap maintenance agreements, fragmenting traditional bundled pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation intensity and emission certification grade. Cost compression in mid-tier semi-automatic rigs is intensifying because contractor drilling services face margin pressure from itemized sourcing. Junior mining companies and small-scale water well contractors exhibit highest price sensitivity, while tier-one copper operators in Chile absorb premium pricing for autonomous-capable fleets without volume negotiation.
Supply Chain Analysis
Dual-sourcing requirements for precision hydraulic components mandate qualification of both South Korean and German piston pump suppliers, though actual procurement concentrates among two dominant sources. Rig mast and chassis fabrication draws from Chinese steel foundries and South Korean hydraulic component makers decoupling from European supply schedules. Single-source vulnerability in precision valves and cold-start aftertreatment systems for high-altitude Andean deployment creates structural risk. Distribution runs through Perth as the regional procurement hub for Australian operations and direct OEM relationships for Chilean state lease compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surface drilling rig market sits in a technology-transition phase where battery-electric powerpacks and autonomous retrofit kits displace legacy diesel-mechanical platforms. This shift rewards stakeholders who anchor positions in emission-compliant architectures and penalizes those tethered to restricted-territory legacy sales.
For Market Incumbents: Deploy backward integration into smart machine control hardware and captive compressor technology to defend against margin erosion from unbundled service contracts. Atlas Copco AB and Komatsu Ltd. exemplify this lever through in-house production of drill string automation and machine control systems. Counter the threat of battery-electric entrants by accelerating hybrid-electric certification across all platform tiers. Channel control through standardized fleet configurations reduces spare parts inventory overhead for tier-one mining operators. For New Entrants and Emerging Players: EU Stage V in Europe opens a window for battery-electric powerpack specialists targeting underground coal and metal mines in Germany and Poland facing steepest compliance cost increases. Autonomous retrofit kits for semi-automatic installed base present white-space opportunity in mid-tier contractor segments balancing capital constraints against productivity targets. Geothermal slim-hole drilling in Iceland and Kenya's Rift Valley offers penetrable entry point where corrosion-resistant metallurgy commands specification premiums. Go-to-market angle should emphasize component-level subscriptions that bypass traditional OEM full-wrap maintenance relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by construction-equipment conglomerates seeking smart control hardware capabilities or integrated systems houses expanding autonomous software depth. Long-term viability favors vertically integrated OEMs with captive supply of compressors and control systems over assembly-dependent challengers. Target acquisition archetype: regional mast-and-chassis fabricators with established mine site relationships but lacking emission-compliant powertrain technology. Signal to watch as inflection indicator: acceleration of lithium-titanate battery system convergence with onboard compressor drives in underground applications.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Software Acquisition | Captures drill pattern execution capabilities that Codelco and BHP are scaling across Chilean operations. |
| Battery-Electric Powerpack Development | Eliminates diesel engines in underground applications where EU Stage V compliance costs peak. |
| Hybrid-Electric Certification Investment | Unlocks access to EPA Tier 4 Final regulated federal and state mining leases in North America. |
| Component-Level Subscription Launch | Fragments traditional full-wrap maintenance agreements that Australian iron ore contractors now reject. |
| Regional Procurement Hub Establishment | Consolidates maintenance contracts for standardized fleet configurations centered on Perth. |
Methodological Framework
Document review covered SEC filings, customs and trade data, mine equipment procurement databases, and EPA emission certification records, complemented by interviews with maintenance directors at Pilbara iron ore operations, OEM procurement teams, aftermarket service heads, and plant engineers at Chilean copper porphyry deposits. Primary fieldwork validated secondary findings through structured conversations with fleet managers and drilling contractors across the Andean region and Western Australia. Bottom-up unit economics and top-down market sizing were triangulated against disclosed fleet deployment figures.
Model outputs span value and volume projections across the analysis window, with segmentation by rock-breaking mechanism, control architecture sophistication, end-user capital intensity, and hole purpose. Drill string automation penetration rates and emission compliance adoption curves served as industry-specific forecast inputs. CAGRs were derived from fitted growth curves against historical replacement cycle compression and autonomous capability diffusion patterns.
The model assumes a particular technology adoption path; alternative pathways for battery-electric powerpacks would alter the outlook if lithium-titanate system costs decline faster than projected. Forecasts reflect assumptions about MSHA whole-body vibration certification timelines and Chinese steel export quota stability. Deviation in EPA enforcement intensity or EU carbon border adjustment mechanism implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Logging Cable Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Continuous Miners Market