
 Hydraulic Intensifiers Market | 2026-2036
Hydraulic Intensifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Intensifiers Market Foresight
Buyer concentration in oil and gas is rebalancing toward integrated service contractors running large-scale pressure-testing programs. Parker Hannifin Corporation leverages its fluid power distribution network to dominate aftermarket parts supply. Bosch Rexroth anchors European demand through localized engineering centers serving automotive pressing lines. Enerpac Tool Group specializes in portable intensifier systems for offshore maintenance crews.
A hydraulic intensifier is a pressure-amplifying device that converts low-pressure hydraulic fluid input into high-pressure output, typically achieving ratios from 10:1 to 100:1 through piston-area differential designs. These units serve critical functions in metal forming, pressure testing, and bolt tensioning where conventional pump systems cannot generate sufficient force. Electric intensifiers are capturing margin pools in precision manufacturing due to programmable pressure curves and energy recovery capabilities. Pneumatic intensifiers retain cost advantages in explosive atmospheres across oil and gas field operations. Custom intensifiers command premium positioning where ASME-certified designs integrate with client-specific manifold configurations.
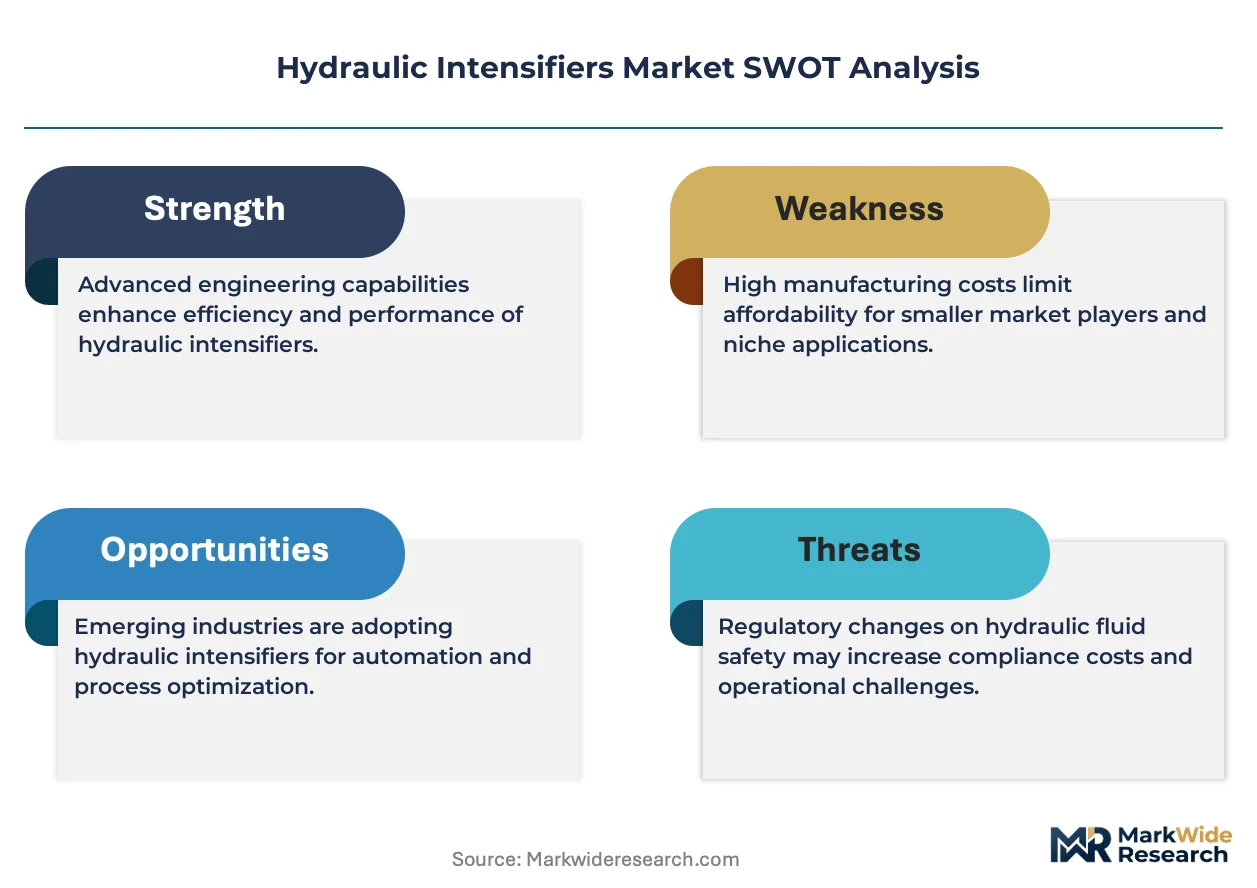
The EPA enforces emissions controls on hydraulic fluid disposal, pushing end users toward biodegradable formulations and sealed-system intensifiers. OSHA mandates pressure vessel certification under its general industry standards, directly shaping product qualification requirements for domestic suppliers. ISO hydraulic cleanliness standards further constrain component sourcing for manufacturers targeting aerospace and defense channels. Stakeholders must monitor how carbon-border adjustments and state-level decarbonization timelines redirect capital toward electrified alternatives versus upgraded hydraulic infrastructure.
Market Dynamics
Subsea infrastructure expansion in the Gulf of Mexico and North Sea is concentrating procurement power among integrated service contractors running continuous pressure-testing programs. This buyer consolidation is reshaping supplier relationships and technical specifications across the supply base.
Growth Catalysts
- EPA Emissions Mandates:Tighter disposal controls on hydraulic fluids are forcing fleet upgrades toward sealed-system intensifier designs, creating replacement demand across petrochemical clusters.
- Subsea Pressure Testing:Deepwater oil and gas operators are expanding high-pressure equipment procurement for wellhead integrity verification at depths exceeding 3,000 meters.
- Biodegradable Formulations:Synthetic ester-based hydraulic fluids compatible with intensifier seals are capturing specification share in environmentally sensitive operating zones.
Market Restraints
- Specialized Alloy Supply:Intensifier pressure vessels require maraging steel grades concentrated among a limited set of European and Japanese metallurgical suppliers.
- ASME Certification Timeline:Pressure vessel qualification cycles stretch 18-24 months, creating working capital intensity for custom design houses.
- Electromechanical Substitution:Servo-electric press systems are displacing hydraulic intensifiers in precision metal forming applications below 5,000 psi requirements.
Strategic Opportunities
- Offshore Maintenance Services:Portable intensifier systems for subsea bolt tensioning represent underpenetrated demand among North Sea and Brazilian deepwater operators.
- Aerospace Testing Applications:ISO cleanliness standards are opening qualification pathways for intensifier manufacturers targeting hydraulic actuator validation programs.
- Carbon Border Adjustments:EU Green Deal mechanisms are redirecting capital toward upgraded hydraulic infrastructure versus full electrification in heavy industrial settings.
Industry Challenges
- Certified Technician Scarcity:ASME Section VIII pressure vessel welding and inspection skills are concentrating among aging workforces in Houston and Aberdeen.
- Legacy System Integration:Retrofitting intensifiers into existing manifold configurations requires custom engineering that compresses margin on smaller contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Intensifiers Market |
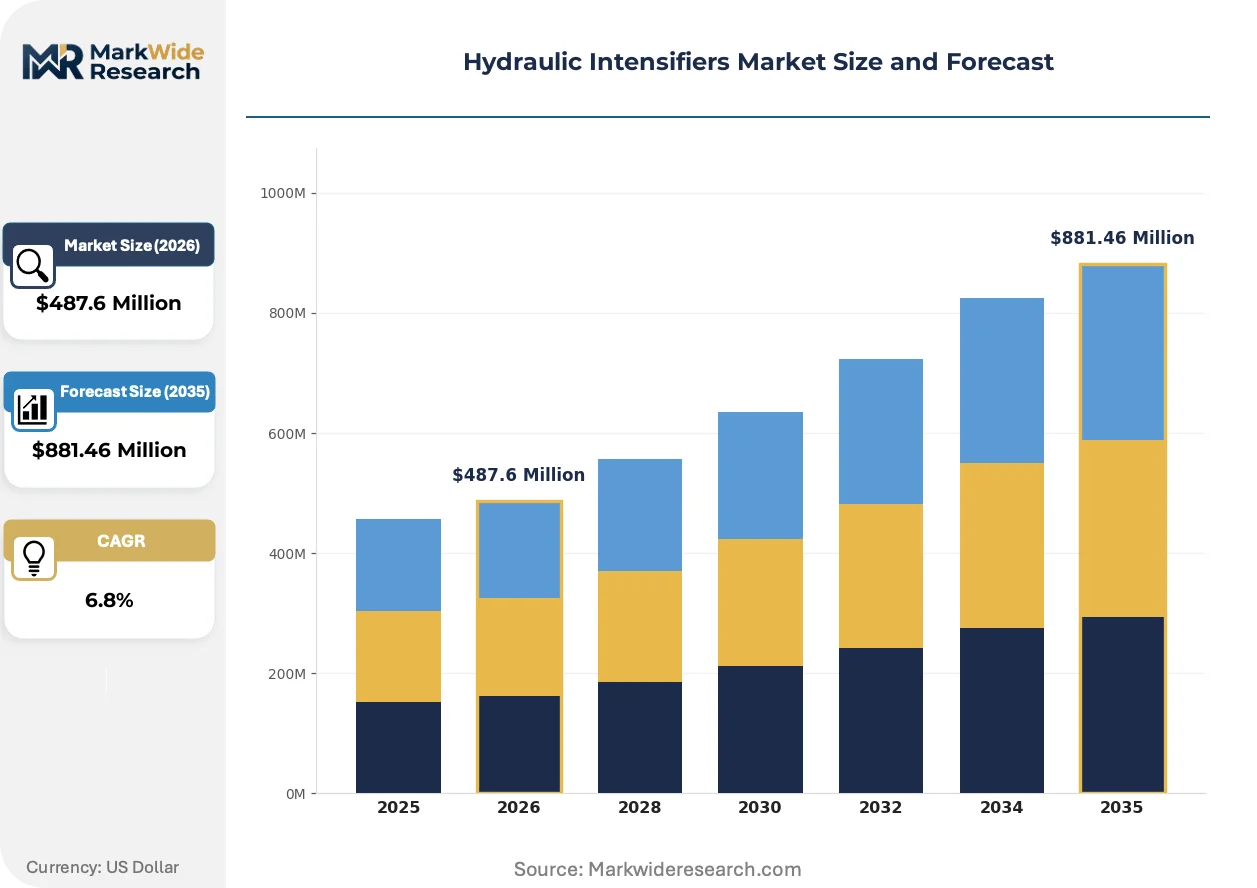
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Intensifiers, Electric Intensifiers, Pneumatic Intensifiers, Custom Intensifiers End User: Aerospace, Automotive, Oil & Gas, Manufacturing Technology: Hydraulic Technology, High-Pressure Technology, Advanced Control Systems, Energy Recovery Systems Application: Pressing, Forming, Testing, Cleaning |
| Companies Covered | Parker Hannifin Corporation, Bosch Rexroth, Enerpac Tool Group, HYDAC International, Eaton Corporation, High Pressure Equipment Company, SC Hydraulic Engineering Corporation, SPX Flow Inc., Maximator GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Intensifiers Market Shifts & Advancements
Digital pressure control architectures are displacing analog relief valve systems across precision manufacturing and testing applications. This shift is compressing calibration cycles while expanding programmable functionality.
Smart sensor arrays embedded in intensifier pressure chambers are integrating real-time condition monitoring with predictive maintenance platforms. Automotive pressing line operators in Germany and Japan are adopting these systems fastest, with pilot programs compressing unplanned downtime by enabling seal-wear detection before failure. The technology is integrating intensifier fleets into broader factory automation architectures, eroding the historical separation between hydraulic and controls procurement.
OSHA general industry standards for pressure vessel certification are tightening documentation requirements for domestic suppliers. The regulation is forcing smaller fabricators toward third-party inspection partnerships, raising fixed cost structures. Gulf Coast petrochemical clusters are responding fastest, with integrated operators demanding certified intensifier packages with complete material traceability.
Service contracting is displacing equipment ownership among offshore maintenance crews. Integrated service providers are bundling portable intensifier systems with technician deployment, unbundling the traditional capital sale model. This pattern is most visible in Norwegian and UK North Sea operations, where platform operators prefer operational expenditure treatment for pressure-testing programs.
Hydraulic Intensifiers Market Segmentation
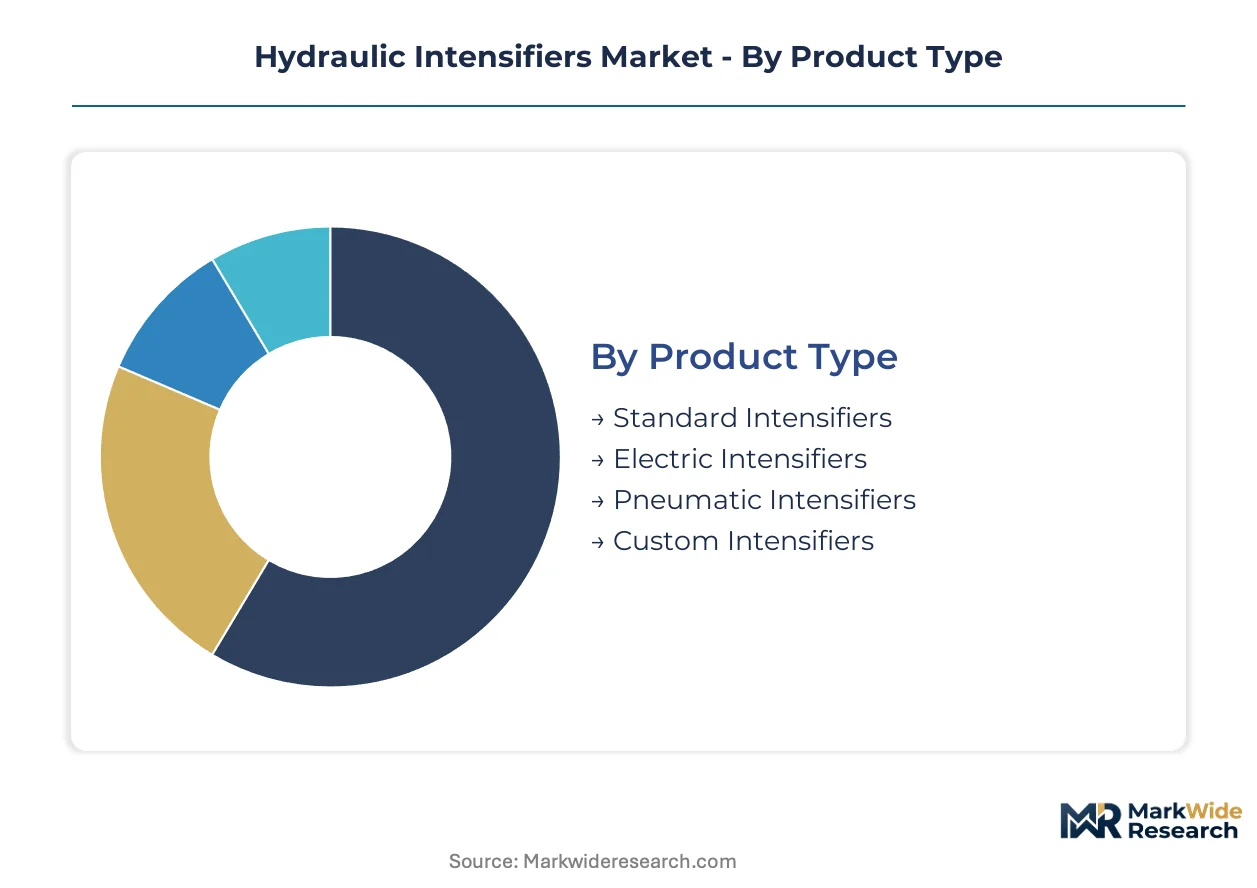
Segmentation in hydraulic intensifiers reveals how pressure-ratio specifications, control architectures, and end-use operating environments fragment procurement patterns. Each dimension carries distinct margin profiles and certification requirements that reshape supplier positioning across industrial channels.
Product Type:
Supply concentration among specialized pressure vessel fabricators concentrates output in standard and custom configurations, while electric and pneumatic variants draw from broader electromechanical supplier bases.
- Standard Intensifiers:Fixed-ratio piston designs with pre-engineered manifold interfaces dominate fleet replacement cycles across Gulf Coast petrochemical facilities. Demand clusters around 10:1 to 50:1 pressure ratios for general pressure testing applications where ASME certification is mandatory.
- Electric Intensifiers:Servo-driven architectures with programmable pressure curves are displacing analog systems in German and Japanese automotive pressing lines. Precision manufacturing operators value energy recovery capabilities and reduced calibration cycles for quality-critical forming operations.
- Pneumatic Intensifiers:Air-driven units retain cost advantages in explosive atmospheres across North Sea and Gulf of Mexico offshore platforms where electrical ignition risks constrain equipment selection.
- Custom Intensifiers:Client-specific manifold integrations with maraging steel pressure vessels serve subsea bolt tensioning programs requiring 100:1 ratios and complete material traceability.
Standard intensifiers absorb the bulk of installed capacity; electric intensifiers are expanding most quickly.
End User:
Application maturity across end-use sectors determines specification stringency and service contracting penetration, with aerospace and oil & gas demanding the most intensive certification documentation.
- Aerospace:ISO cleanliness standards and FAA traceability requirements govern hydraulic actuator validation programs, opening qualification pathways for intensifier manufacturers with certified cleanroom assembly capabilities.
- Automotive:Pressing line operators in Germany and Japan drive smart sensor integration for predictive maintenance, eroding traditional separations between hydraulic and controls procurement.
- Oil & Gas:Deepwater operators in the Gulf of Mexico and North Sea concentrate procurement among integrated service contractors running continuous wellhead integrity verification programs.
- Manufacturing:General metal forming and testing applications span the widest price spectrum, with servo-electric substitution pressuring hydraulic intensifiers below 5,000 psi requirements.
Oil & gas commands the highest per-unit pricing; aerospace represents the steepest expansion trajectory for certified suppliers.
Technology:
Technology layering determines capital intensity and aftermarket revenue potential, with advanced control and energy recovery systems capturing margin pools from traditional hydraulic architectures.
- Hydraulic Technology:Conventional piston-area differential designs with analog relief valves retain installed base dominance in legacy manufacturing infrastructure across US Gulf Coast clusters.
- High-Pressure Technology:Maraging steel pressure vessels and specialized seal configurations enable 50,000+ psi output for subsea applications, sourcing alloys from concentrated European and Japanese metallurgical suppliers.
- Advanced Control Systems:Digital pressure architectures with programmable setpoints are displacing mechanical relief systems in precision testing and forming operations.
- Energy Recovery Systems:Regenerative circuits capturing return-stroke energy reduce operating costs in high-cycle automotive pressing environments.
Hydraulic technology maintains the largest installed base; advanced control systems are gaining share fastest.
Application:
Application-specific duty cycles and safety criticality determine whether intensifiers are specified for continuous production or intermittent service, reshaping supplier service contracting strategies.
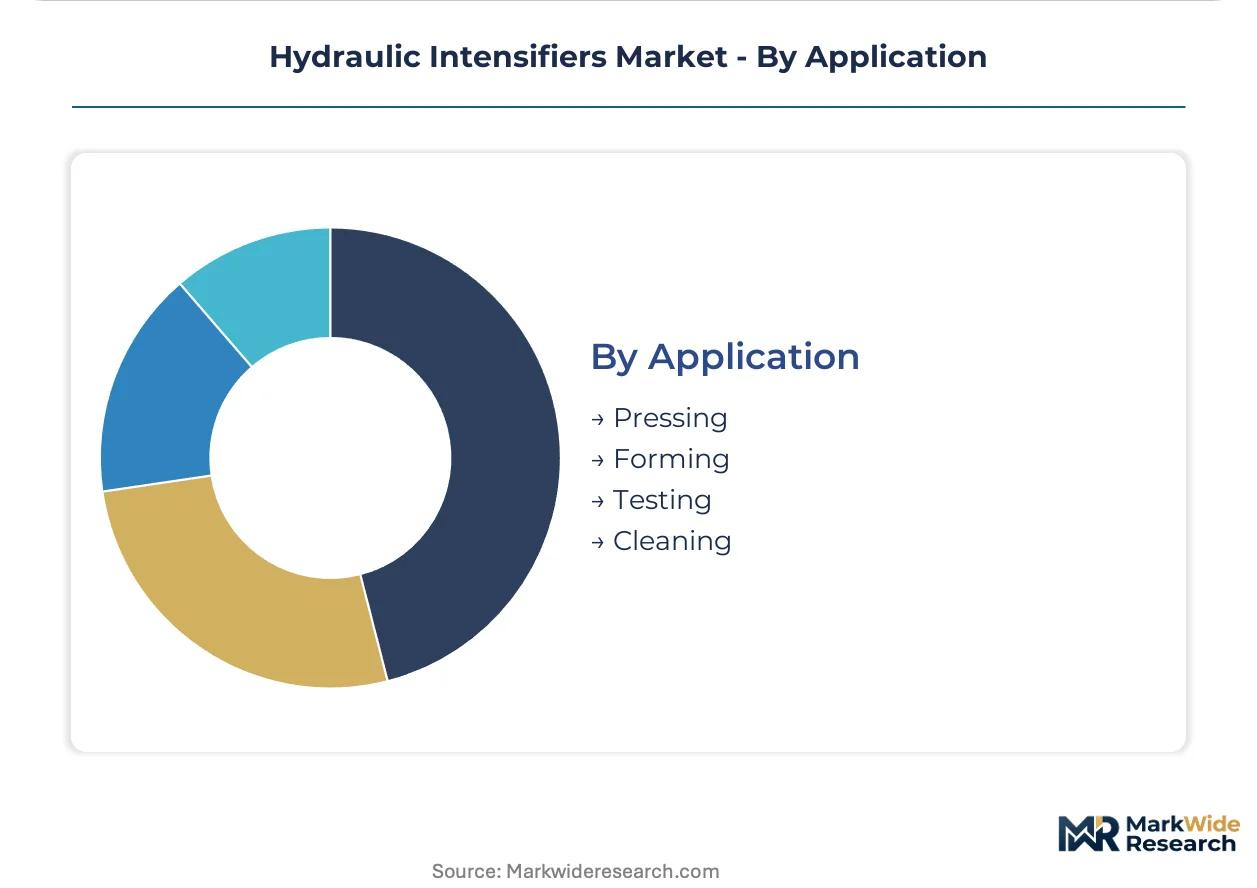
- Pressing:High-force metal forming operations in automotive and appliance manufacturing require sustained pressure holding with minimal drift, favoring electric intensifiers with closed-loop control.
- Forming:Precision metal shaping applications demand programmable pressure curves for complex part geometries, with German automotive OEMs specifying smart sensor integration.
- Testing:Pressure vessel and component validation programs across aerospace and oil & gas require certified calibration documentation and material traceability.
- Cleaning:High-pressure waterjet and surface preparation systems utilize intensifiers for 40,000+ psi output in industrial maintenance and marine applications.
Testing applications absorb the bulk of certified system procurement; forming is climbing the fastest as automotive electrification reshapes pressing line investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement power concentrates in integrated service contractors operating continuous pressure-testing programs across deepwater basins. Gulf Coast petrochemical clusters and North Sea platforms drive specification intensity for certified intensifier packages. Regulatory divergence between EPA mandates and EU Green Deal mechanisms is fragmenting supplier qualification pathways.
United States
Deepwater operators in the Gulf of Mexico are expanding high-pressure equipment procurement for wellhead integrity verification at depths exceeding 3,000 meters. EPA emissions controls on hydraulic fluid disposal are forcing fleet upgrades toward sealed-system intensifier designs. Houston anchors the domestic supplier base, with integrated contractors demanding complete material traceability for ASME-certified packages.
Norway
North Sea platform operators prefer operational expenditure treatment for pressure-testing programs, accelerating service contracting over equipment ownership. EU Green Deal carbon-border adjustments are redirecting capital toward upgraded hydraulic infrastructure versus full electrification. Stavanger and Bergen clusters concentrate procurement among integrated service providers bundling portable intensifier systems with technician deployment.
Germany
Automotive pressing line operators drive smart sensor integration for predictive maintenance, eroding traditional separations between hydraulic and controls procurement. REACH regulations constrain hydraulic fluid formulations, pushing specification shifts toward synthetic ester-based alternatives. Stuttgart and Munich industrial corridors anchor demand for electric intensifiers with programmable pressure curves and energy recovery capabilities.
United Kingdom
Offshore maintenance crews in the UK North Sea are adopting portable intensifier systems for subsea bolt tensioning through service contracting models. OSHA-aligned pressure vessel certification requirements are tightening documentation standards for suppliers serving transatlantic operators. Aberdeen concentrates ASME Section VIII welding and inspection skills among specialized workforces.
Japan
Precision manufacturing operators value energy recovery capabilities and reduced calibration cycles for quality-critical forming operations. METI industrial standards govern hydraulic system efficiency benchmarks, shaping intensifier specification in automotive supply chains. Nagoya and Osaka industrial zones drive adoption of digital pressure control architectures displacing analog relief valve systems.
Hydraulic Intensifiers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue portable systems for offshore service contracting. The supplier base fragments between specialized pressure vessel fabricators holding ASME certification and diversified fluid power conglomerates leveraging distribution scale. Three archetypes dominate: integrated fluid power distributors, precision engineering specialists, and regional fabrication houses. Consolidation pressure is intensifying through strategic partnerships for alloy supply security and technology licensing for digital control architectures.
Among diversified fluid power conglomerates, Parker Hannifin Corporation anchors aftermarket parts supply through its distribution network breadth. Bosch Rexroth exemplifies the precision engineering archetype with localized service capabilities. Enerpac Tool Group occupies a position within the portable systems tier, representing the service-contracting pivot among offshore maintenance specialists.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Bosch Rexroth |
| Enerpac Tool Group |
| HYDAC International |
| Eaton Corporation |
| High Pressure Equipment Company |
| SC Hydraulic Engineering Corporation |
| SPX Flow Inc. |
| Maximator GmbH |
| Others |
Supply & Pricing Matrix
Integrated service contractors consolidating procurement of high-pressure testing equipment for Gulf of Mexico subsea infrastructure are forcing intensifier manufacturers toward ASME-certified custom designs with complete material traceability, compressing margins on standardized units while elevating pricing power for qualified fabricators.
Pricing Analysis
Volume concentrates in standard intensifiers with fixed-ratio piston designs, while margin pools accrue to custom configurations integrating maraging steel pressure vessels and client-specific manifold interfaces. Price differentiation rests on ASME certification tier and after-sales service bundling rather than base hardware specifications. Cost compression in the standard tier is intensifying as electromechanical substitutes displace hydraulic systems below 5,000 psi requirements. Manufacturing operators represent the most price-sensitive segment, whereas deepwater oil and gas contractors exhibit lowest sensitivity due to safety-critical procurement mandates.
Supply Chain Analysis
Refurbishment flows for intensifier pressure vessels concentrate in Houston and Aberdeen service hubs, extending asset life cycles for offshore maintenance contractors. Maraging steel alloys draw from European and Japanese metallurgical suppliers, while specialized seal configurations source from German and US polymer specialists. Single-source vulnerability in certified alloy supply creates exposure to export restriction shocks. Distribution runs through integrated fluid power distributors with aftermarket parts networks and direct contracting for custom fabrication programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA pressure vessel certification timelines stretching 18-24 months erect a cost-of-compliance barrier that rewards incumbents with established ASME qualification pathways and strains working capital for new entrants.
For Market Incumbents: To counter electromechanical substitution in precision metal forming below 5,000 psi, anchor positioning through backward integration into maraging steel supply partnerships with Japanese and European metallurgical suppliers, and deepen certification investment in ISO cleanliness standards for aerospace channel access. For New Entrants and Emerging Players: Launch via portable intensifier service contracting models targeting North Sea and Brazilian deepwater operators preferring operational expenditure treatment, penetrating the underdeveloped offshore maintenance segment through technician-deployment bundling rather than capital equipment sales. For Investors and Strategic Acquirers: The window for entry favors specialized pressure vessel fabricators holding ASME Section VIII certification with cleanroom assembly capabilities, as carbon-border adjustments redirect capital toward upgraded hydraulic infrastructure versus full electrification in heavy industrial settings. Monitor EU Green Deal implementation velocity and state-level decarbonization timelines as inflection signals for electrification substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Investment | Eighteen-to-twenty-four month qualification cycles lock in procurement relationships with Gulf Coast petrochemical operators. |
| Maraging Steel Supply Agreement | Long-term alloy sourcing contracts with European and Japanese metallurgical suppliers mitigate single-source vulnerability. |
| Portable System Service Contracting | Technician-deployment bundling captures operational expenditure preference among North Sea platform operators. |
| Smart Sensor Integration Partnership | Predictive maintenance platform alliances with German automotive pressing line operators erode hydraulic-controls procurement separation. |
| Biodegradable Fluid Compatibility Program | Synthetic ester-based seal specifications align with EPA emissions mandates and REACH regulatory constraints. |
Research Methodology
Independent corroboration across maintenance directors at Gulf Coast petrochemical facilities, procurement leads at integrated oilfield service contractors, and aftermarket service heads at fluid power distributors underwrites the qualitative findings. Primary interviews with plant engineers specifying intensifier systems for automotive pressing lines, OEM procurement teams evaluating supplier qualification pathways, and technical R&D directors developing seal compatibility formulations combined with secondary validation from SEC 10-K filings, customs and trade data on maraging steel imports, and ASME certification registry records. Bottom-up and top-down triangulation reconciled equipment procurement volumes with alloy consumption patterns.
Comparable-period anchoring to historical replacement cycles across Gulf Coast petrochemical clusters and North Sea platform maintenance schedules established the forecast window baseline. The analytical framework modeled pressure ratio specifications, control architecture types, end-use operating environments, and regional regulatory divergence across the projection horizon. CAGRs derived from segment-level intensity factors including subsea infrastructure expansion rates, EPA mandate implementation timelines, and automotive electrification displacement thresholds for hydraulic forming equipment.
The model assumes a particular technology adoption path; alternative pathways for servo-electric press systems would alter the outlook if displacement accelerates below 5,000 psi requirements. Forecasts reflect assumptions regarding certification timeline stability, alloy supply continuity, and carbon-border adjustment implementation scope. Practitioners should monitor OSHA documentation requirement tightening, EU Green Deal capital redirection patterns, and certified technician workforce demographics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
CNC Router Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Europe Ground Penetrating Radar Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Grader Blades Market
Construction Equipment
Concrete Chain Saw Market