
 UAE Construction Market | 2026-2036
UAE Construction Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Construction Market Outlook
Cross-laminated timber and engineered bamboo is shifting cost-performance curves in mid-rise commercial structures across the Emirates. Al Naboodah Construction Group leverages its vertically integrated supply chain to control material flows from fabrication to site delivery. ALEC Engineering & Contracting anchors its competitive position through deep specialization in complex hospitality and healthcare builds. China State Construction Engineering Corporation dominates mega-scale infrastructure awards through state-backed financing capacity and turnkey execution.
Construction in the UAE encompasses the erection, alteration, and repair of buildings and civil works using concrete, steel, glass, and timber assemblies engineered to withstand seismic loads up to 0.15g and extreme thermal cycling exceeding 50°C ambient. Its primary purpose is delivering habitable, operational, and transport infrastructure that supports economic diversification beyond hydrocarbons. Residential project types currently absorb the largest share of executed contract value, though green construction methods are expanding fastest as Estidama Pearl Rating requirements tighten. Concrete remains the dominant material type by tonnage deployed, yet steel framing gains share in commercial towers seeking reduced floor-to-floor heights.
MOHAP enforces fire safety and structural integrity standards through mandatory building permits and occupancy certifications, while the UAE's dual carbon goals push embodied carbon limits into procurement specifications. Dubai Municipality and Abu Dhabi Department of Municipalities and Transport coordinate zoning changes that unlock development capacity in new districts. Stakeholders must monitor how evolving federal procurement rules for local content reshape contractor eligibility and material sourcing obligations.
Market Dynamics
MOHAP building codes and Estidama sustainability standards are compressing project timelines while mandating embodied carbon limits, forcing contractors to requalify material suppliers and redesign delivery sequences around certification checkpoints.
Growth Catalysts
- Estidama Pearl Rating mandates:Abu Dhabi Department of Municipalities and Transport requires minimum Pearl 2 ratings for new builds, accelerating specification of low-carbon concrete and high-performance glazing across hospitality and healthcare verticals.
- Entertainment-led tourism infrastructure:Mega-project pipelines in Dubai's coastal districts are pulling cross-laminated timber and engineered bamboo into mid-rise commercial structures previously dominated by steel-concrete hybrid frames.
- Foreign direct investment concentration:Sovereign wealth-backed development vehicles in Abu Dhabi and Dubai are channeling capital into build-to-suit logistics and data center assets, creating sustained demand for specialized MEP contractors.
Market Restraints
- Steel and cement input volatility:Regional blast furnace capacity constraints and clinker import dependencies expose contractors to margin compression when GCC spot prices spike.
- Specialized subcontractor concentration:Complex facade installation and Building Management System integration capabilities cluster among a narrow base of Dubai-based specialists, creating bottleneck risk on fast-track schedules.
- Technical limitation in high-rise timber:Current cross-laminated timber fire-rating certifications cap usable heights below 12 stories, excluding the material from premium commercial tower cores where floor-to-floor efficiency drives returns.
Strategic Opportunities
- Underpenetrated northern emirates:Ras Al Khaimah and Fujairah lack established contractor ecosystems for complex healthcare builds, creating first-mover advantage for firms willing to pre-position fabrication yards and skilled labor pools.
- Regulatory tailwind from federal procurement rules:Evolving local content thresholds in federal contracts are reshaping eligibility criteria, advantaging contractors with captive steel fabrication or in-house precast concrete production.
- Technology convergence in digital fabrication:Integration of BIM-to-CNC workflows with drone-based site surveying is compressing rework cycles on complex geometries, particularly in hospitality projects where design churn remains elevated.
Industry Challenges
- Certification timeline compression:MOHAP occupancy certificates now require concurrent fire safety and sustainability documentation, extending handover sequences by 8-14 weeks on average builds.
- Skilled MEP commissioning gap:Deep specialization in healthcare-grade HVAC balancing and medical gas systems remains scarce, forcing contractors to import European commissioning engineers at premium cost.
- Legacy system integration friction:Smart building retrofits in 1990s-era commercial stock face incompatible bus protocols and power distribution architectures, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Construction Market |
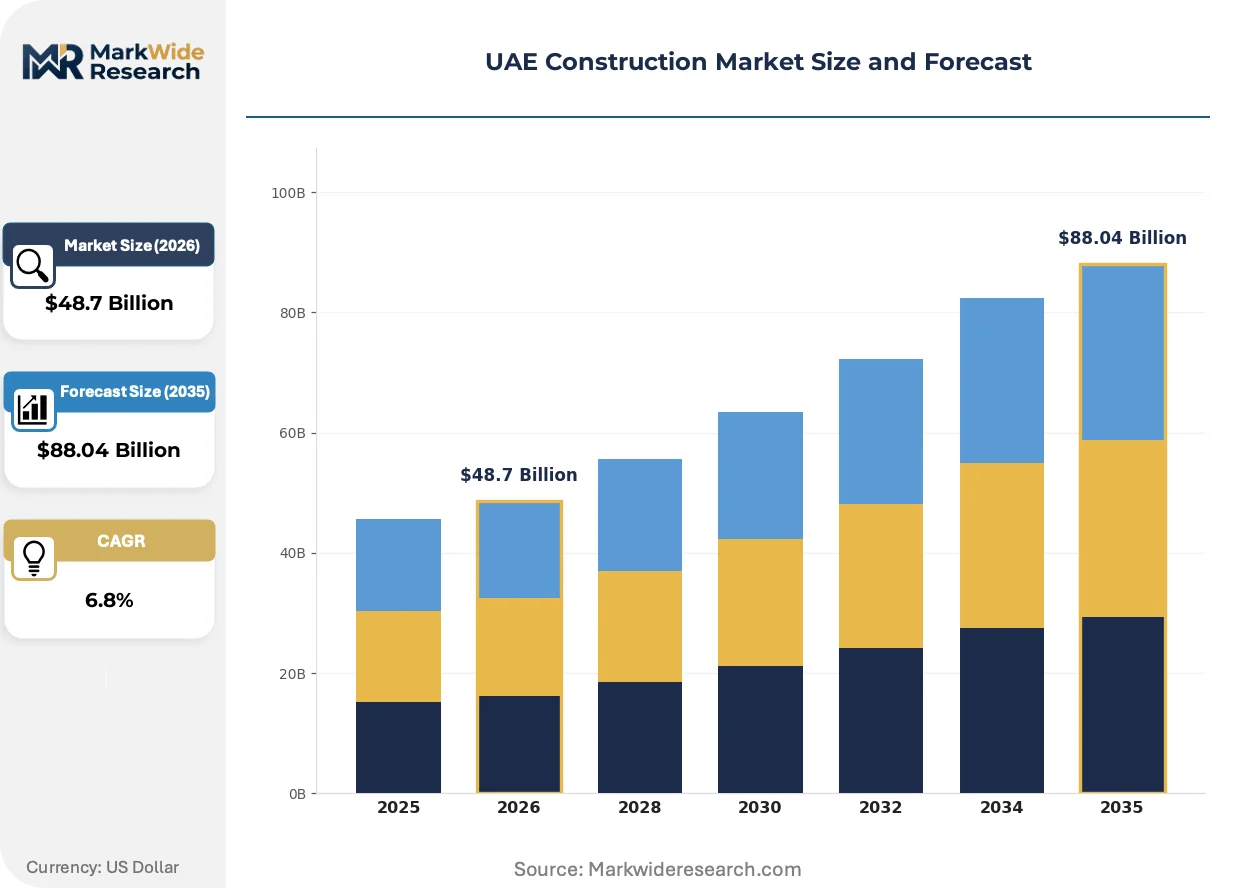
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Infrastructure, Industrial Material Type: Concrete, Steel, Wood, Glass End User: Developers, Government, Contractors, Investors Construction Method: Traditional, Prefabrication, Modular, Green |
| Companies Covered | Al Naboodah Construction Group, ASGC Construction, ALEC Engineering & Contracting, China State Construction Engineering Corporation, Arabian Construction Company, Al Habtoor Group, Khansaheb Civil Engineering, Dutco Construction LLC, Trojan Construction Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Construction Market Strategic Shifts
Digital fabrication workflows and material science advances are compressing traditional construction sequences while regulatory pressure on embodied carbon forces simultaneous redesign of supply chains and specification protocols.
Cross-laminated timber and engineered bamboo composites are absorbing market share in mid-rise commercial and hospitality structures where seismic loads remain moderate and fire-rating requirements permit. Dubai-based developers with entertainment and leisure portfolios are specifying these materials at accelerating pace to meet Estidama Pearl targets. The technology is absorbing project risk by enabling faster enclosure sequences and reducing crane-time dependencies on constrained urban sites.
MOHAP's 2024 updates to fire safety and structural integrity standards have tightened documentation requirements for alternative materials and performance-based designs. Industrial consequence includes mandatory third-party verification of engineered timber assemblies and expanded testing protocols for facade systems. Healthcare and education verticals in Abu Dhabi are responding by front-loading specification reviews and locking supplier qualifications 18-24 months ahead of construction start.
Buyer concentration among sovereign wealth-backed developers is consolidating procurement leverage and compressing contractor margins on repeat-build typologies. Design-build and EPC contracts are displacing traditional design-bid-award sequences on logistics and data center assets. This pattern is most visible in Dubai South and Abu Dhabi's Khalifa Industrial Zone, where single-entity master developers control land release and infrastructure timing.
UAE Construction Market Segmentation
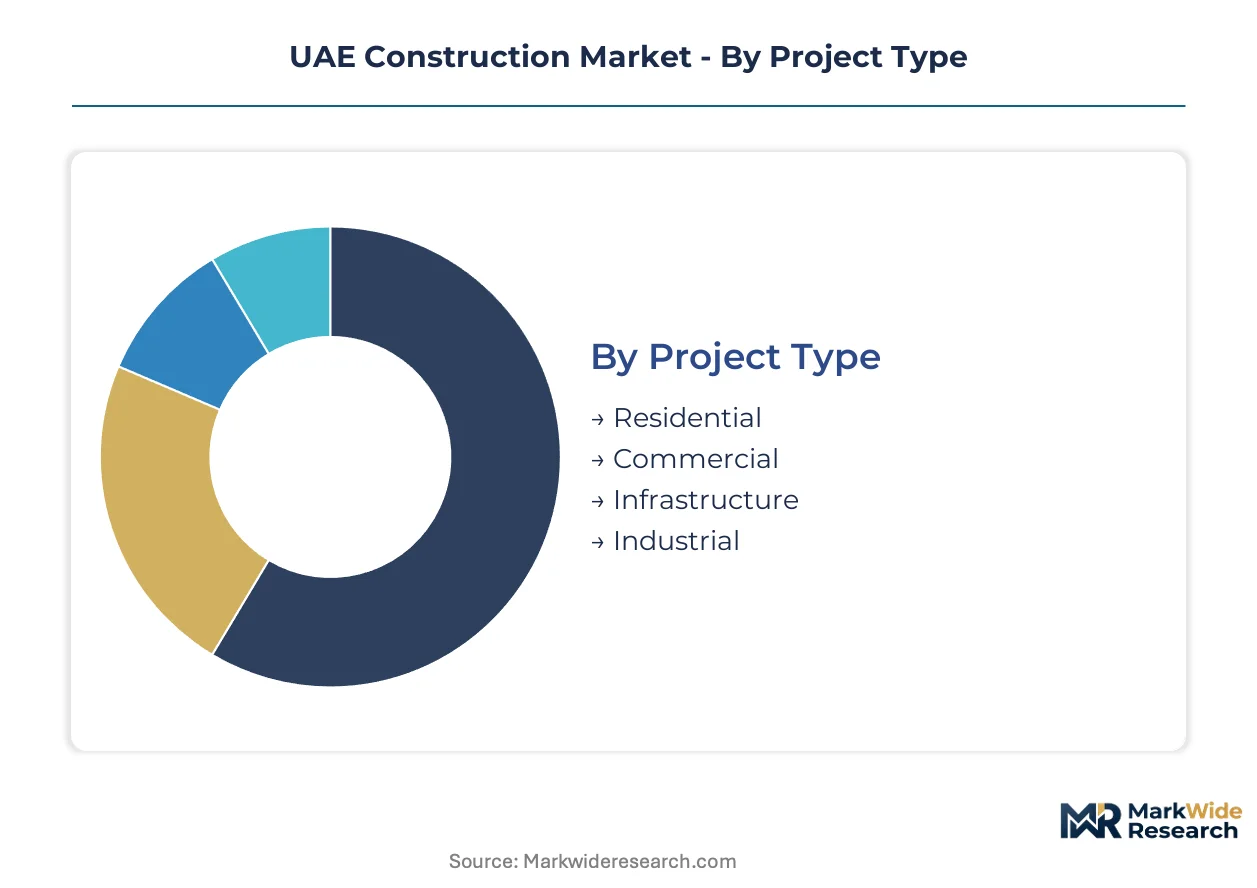
Segmentation in the UAE construction market reveals how procurement power concentrates among sovereign-backed developers while material choices diverge between cost-driven infrastructure and sustainability-weighted commercial assets. Understanding these fault lines exposes where margin pools thicken and where regulatory pressure reshapes specification patterns.
Project Type:
Standalone developments dominate capital deployment, though integrated master-planned communities embed housing within larger mixed-use ecosystems that share infrastructure and certification pathways.
- Residential:High-rise towers and villa compounds absorb the largest share of executed contract value, driven by population growth targets in Dubai and Abu Dhabi. Developers prioritize rapid enclosure sequences to meet handover commitments, favoring precast concrete systems over in-situ methods.
- Commercial:Office towers and retail complexes face intensifying Estidama Pearl Rating mandates, forcing specification of low-carbon concrete and high-performance glazing. Hospitality assets within this segment command premium MEP contracting due to specialized HVAC and fire suppression requirements.
- Infrastructure:Transport corridors and utility networks anchor federal spending, with MOHAP and municipal authorities coordinating permits across multi-jurisdictional sites.
- Industrial:Logistics warehouses and data center shells concentrate in Dubai South and Khalifa Industrial Zone, where single-entity master developers control land release timing.
Residential leads volumes today; Commercial is gaining share fastest as tourism and entertainment mega-projects accelerate specification of complex hospitality builds.
Material Type:
Cost tiers separate commodity bulk materials from engineered alternatives that command specification premiums through sustainability certification or performance guarantees.
- Concrete:Precast and ready-mix formulations dominate by tonnage deployed, with low-carbon variants gaining traction as Estidama embodied carbon limits tighten procurement specifications. Clinker import dependencies expose contractors to GCC spot price volatility.
- Steel:Structural framing and rebar assemblies gain share in commercial towers seeking reduced floor-to-floor heights. Regional blast furnace capacity constraints periodically compress margins when input costs spike.
- Wood:Cross-laminated timber and engineered bamboo penetrate mid-rise hospitality structures where fire-rating caps below 12 stories do not exclude the material from viable use cases.
- Glass:High-performance glazing systems satisfy Pearl Rating thermal performance thresholds while enabling architectural expression in coastal entertainment districts.
Concrete dominates absolute volumes; Wood is expanding most quickly as entertainment-led developers test mass timber alternatives.
End User:
Customer type determines risk allocation, with sovereign-backed entities absorbing long-dated infrastructure exposure while private capital chases shorter-cycle commercial returns.
- Developers:Private and state-linked development vehicles concentrate procurement leverage, compressing contractor margins on repeat-build typologies through design-build contract structures.
- Government:Federal and emirate-level agencies mandate local content thresholds that reshape contractor eligibility and material sourcing obligations.
- Contractors:Tier-1 EPC firms and specialized subcontractors compete for packages differentiated by technical capability in complex facade or MEP integration.
- Investors:Sovereign wealth vehicles and foreign direct investment flows channel capital into build-to-suit logistics and data center assets.
Developers control the largest project pipeline; Government procurement is tightening fastest as federal local content rules evolve.
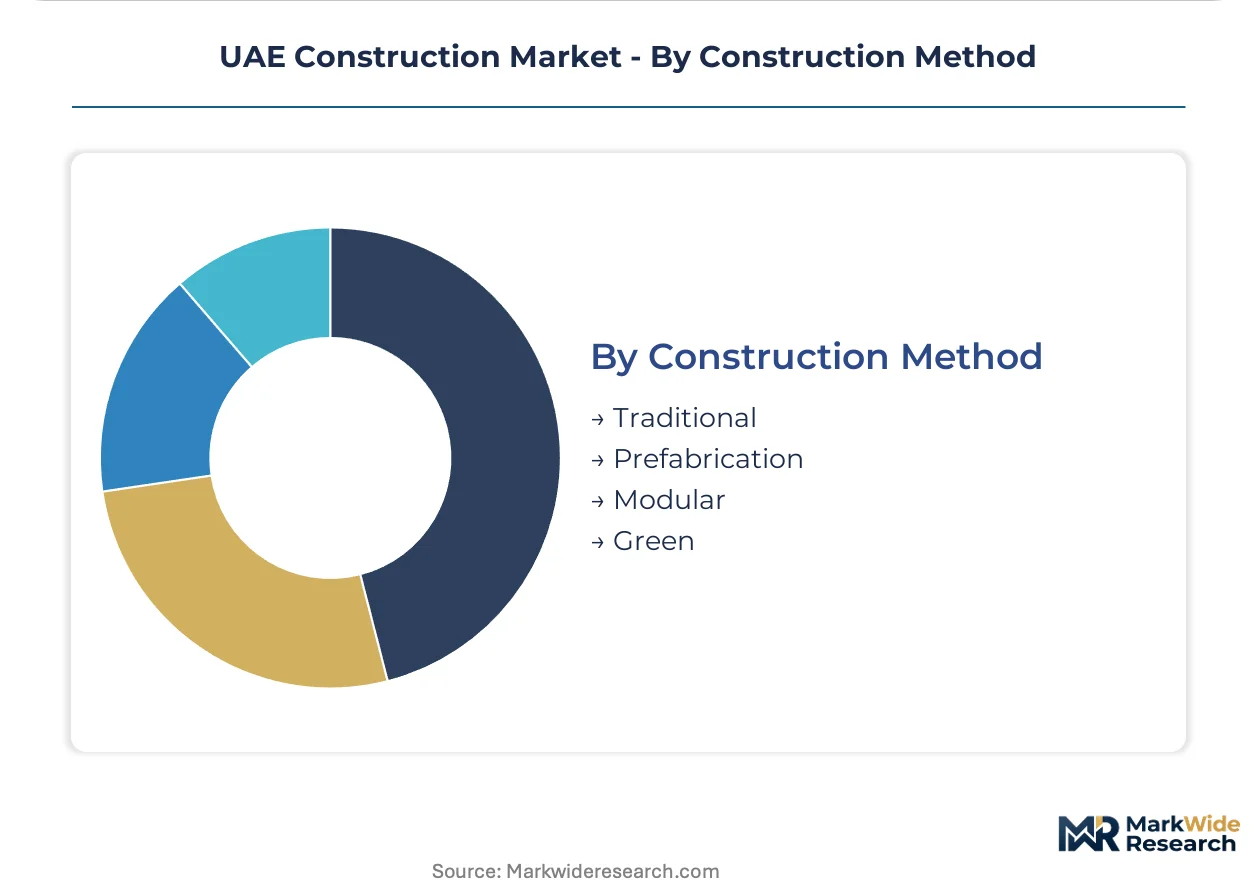
Construction Method:
Maturity curves separate legacy approaches from emerging techniques that compress timelines but require upfront capital investment in fabrication capacity and skilled labor pools.
- Traditional:Cast-in-situ concrete and stick-built steel framing remain prevalent in residential and infrastructure segments where design standardization limits prefabrication economies.
- Prefabrication:Off-site component manufacturing reduces site labor dependencies and accelerates enclosure sequences on constrained urban plots in Dubai's coastal districts.
- Modular:Volumetric construction penetrates hospitality and healthcare verticals where repetitive room modules justify factory capital deployment.
- Green:Estidama-certified methods integrate low-carbon materials, renewable energy systems, and water recycling infrastructure to meet Pearl Rating minimums.
Traditional methods retain the largest installed base; Green construction is climbing the fastest as regulatory mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors construction demand through entertainment-led mega-projects and sovereign wealth-backed infrastructure pipelines. Abu Dhabi concentrates government spending on healthcare and education verticals. Northern Emirates present underdeveloped contractor ecosystems.
Dubai
Entertainment and tourism infrastructure drives cement consumption across coastal districts. Dubai Municipality enforces Estidama-equivalent sustainability benchmarks through Al Sa'fat rating system. Dubai South absorbs logistics warehouse and data center investment from single-entity master developers controlling land release timing.
Abu Dhabi
Healthcare and education builds absorb federal capital allocation under long-term diversification mandates. Abu Dhabi Department of Municipalities and Transport mandates minimum Pearl 2 ratings through Estidama framework. Yas Island and Saadiyat Island concentrate hospitality and cultural asset construction.
Sharjah
Affordable residential development attracts mid-income population spillover from Dubai. Sharjah Urban Planning Council coordinates zoning changes to unlock industrial zone capacity. Hamriyah Free Zone hosts fabrication yards serving northern emirate project pipelines.
Ras Al Khaimah
Tourism and leisure assets leverage lower land costs to compete with Dubai entertainment offerings. Ras Al Khaimah Tourism Development Authority fast-tracks permits for hospitality builds. Al Marjan Island concentrates resort construction with limited local contractor capacity.
Fujairah
Port and logistics infrastructure expands to capture East-West trade corridor volumes. Fujairah Municipality administers building codes aligned with federal MOHAP standards. Dibba and Khor Fakkan industrial zones lack established fabrication capacity for complex healthcare structures.
UAE Construction Market Competitive Environment
Capacity expansion dominates the current landscape as sovereign-backed developers consolidate procurement leverage. The vendor base separates into three tiers: state-linked conglomerates with captive fabrication assets, mid-scale specialists in hospitality and healthcare verticals, and foreign EPC firms with state-backed financing capacity. Strategic archetypes include vertically integrated domestic champions, technology-forward international contractors, and niche MEP specialists. Competitive moves center on backward integration into precast concrete production and geographic pre-positioning in underpenetrated northern emirates.
Among domestic contractors, Al Naboodah Construction Group and ALEC Engineering & Contracting exemplify vertically integrated archetypes with in-house fabrication capabilities. China State Construction Engineering Corporation represents the state-backed international tier, occupying a position defined by turnkey execution capacity and project financing access. These three anchors illustrate how procurement concentration among sovereign wealth vehicles compresses margins while rewarding scale and specialization.
| Leading Market Players |
|---|
| Al Naboodah Construction Group |
| ASGC Construction |
| ALEC Engineering & Contracting |
| China State Construction Engineering Corporation |
| Arabian Construction Company |
| Al Habtoor Group |
| Khansaheb Civil Engineering |
| Dutco Construction LLC |
| Trojan Construction Group |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive precast concrete production anchors both supply security and pricing power for tier-1 UAE contractors bidding on sovereign-backed mega-projects. This upstream control insulates margin positions when GCC clinker spot prices spike, while procurement leverage from concentrated developer buyers compresses pass-through capacity on standardized residential typologies.
Pricing Analysis
Input-cost pass-through from volatile steel and cement spot markets strains contractor margins on fixed-price EPC contracts, particularly when regional blast furnace capacity tightens. Pricing stratifies across Estidama Pearl-certified premium builds, standard commercial structures, and economy-grade residential towers, with certification grade and volume scale as primary differentiation drivers. Cost compression in mid-rise hospitality segments is intensifying because entertainment-led developers are consolidating procurement across repeat-build portfolios. Government-backed master developers exhibit lowest price sensitivity, while private mid-scale residential contractors face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements from MOHAP and municipal authorities mandate multi-supplier qualification for structural steel, engineered timber assemblies, and high-performance glazing systems. Geographic supply concentration draws from China for prefabricated steel components, India for clinker and cementitious materials, and Germany for specialized MEP and medical-grade HVAC equipment. Raw material dependencies rest on GCC clinker imports, Asian rebar shipments, and European commissioning engineer deployment. Single-source vulnerability clusters around Dubai-based facade installation specialists and healthcare MEP integrators. Distribution runs through vertically integrated domestic champions with captive fabrication yards and site logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE construction market operates as a regulatory compounder where Estidama Pearl Rating mandates and evolving federal local content rules continuously reshape contractor eligibility and material specification patterns.
For Market Incumbents: Hedge margin erosion from procurement concentration by locking long-term offtake agreements with clinker suppliers and pre-qualifying alternative timber fabricators ahead of Pearl Rating checkpoints. Anchor competitive position through captive steel fabrication capacity in Khalifa Industrial Zone, insulating against import volatility while satisfying evolving local content thresholds. For New Entrants and Emerging Players: Specialized MEP contractors represent the most penetrable channel partner type for breaking into healthcare and data center verticals where commissioning expertise remains scarce. Target Ras Al Khaimah and Fujairah hospitality pipelines where established contractor ecosystems are underdeveloped, leveraging pre-positioned fabrication yards to capture first-mover advantage on entertainment-led resort builds. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale healthcare and hospitality specialists because fragmented MEP commissioning capabilities and narrow facade installation expertise create scarcity premiums in a market consolidating around sovereign-backed procurement vehicles. Watch for inflection when federal local content rules harden eligibility criteria, advantaging acquirers with captive precast or steel fabrication assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Production | Captive concrete supply secures margin stability against GCC clinker price volatility and satisfies Pearl Rating embodied carbon limits. |
| Geographic Pre-positioning in Northern Emirates | Fabrication yard deployment in Ras Al Khaimah captures underserved hospitality pipeline before incumbent ecosystem formation. |
| Estidama Certification Investment | Pearl 2+ rating capability unlocks Abu Dhabi healthcare and education verticals with mandatory sustainability procurement. |
| Healthcare MEP Specialization Buildout | Deep HVAC balancing and medical gas expertise commands scarcity premiums as sovereign wealth channels capital into hospital assets. |
| BIM-to-CNC Workflow Integration | Digital fabrication compresses rework cycles on complex hospitality geometries where design churn remains elevated. |
Study Parameters
Multiple input streams — structured interviews with EPC contract directors and procurement leads, regulatory filing analysis from MOHAP and Dubai Municipality, and project pipeline tracking across sovereign wealth development vehicles — were reconciled to construct market estimates. Primary fieldwork engaged precast plant managers, facade installation specialists, MEP commissioning engineers, and hospitality developer project directors. Secondary validation drew from federal procurement bulletins, Estidama certification databases, customs import records for clinker and steel, and emirate-level building permit registries. Bottom-up project aggregation and top-down sectoral spend analysis were cross-referenced to anchor volume figures.
Historical contract award patterns were cross-referenced against panel input from contractor bidding teams and developer procurement committees to construct the projection framework. Segmentation modeling spanned project type, material category, construction method, and end-user archetype across the analysis window. CAGRs were derived from trend extrapolation of executed contract values, adjusted for regulatory milestone impacts and capital commitment timelines from announced mega-projects. Forecast inputs incorporated Pearl Rating adoption curves, local content threshold evolution, and entertainment-led tourism infrastructure pipeline acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GCC steel and cement spot price volatility, regulatory acceleration of embodied carbon limits, and sovereign wealth capital reallocation timing. Deviation in federal local content rule implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Middle East Data Center Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
India Commercial Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
US Modular Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
Japan Commercial Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Sweden New Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
France Prefab Homes Market
Building Construction
Europe Prefab Wood Buildings Market