
 Europe Multi Attachment Loaders Market | 2026-2036
Europe Multi Attachment Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Multi Attachment Loaders Market Foresight
Municipal snow removal is decoupling from single-purpose fleet design across Northern Europe. JCB sustains technology leadership through its telehandler-to-loader attachment interoperability. Volvo Construction Equipment anchors Nordic market presence with cold-climate hydraulic specifications. Caterpillar competes on dealer density across German federal state procurement frameworks.
Multi attachment loaders are self-propelled, articulated or rigid-frame machines engineered to accept interchangeable front-mounted implements via standardized quick-coupler interfaces, typically operating at hydraulic pressures between 200 and 350 bar to power buckets, forks, augers, and grapples for material manipulation tasks. Compact track loaders occupy the fastest-growing product category as turf-sensitive landscaping and urban utility contracts expand across Benelux green zones. Loader attachments concentrate margin pools in specialized demolition grapples and high-flow snow blowers where aftermarket parts recurrence exceeds base machine revenue cycles. Direct sales channels dominate municipal and rental fleet transactions, while dealerships retain agricultural customer relationships through seasonal trade-in programs.
CE marking mandates under the EU Machinery Directive govern structural integrity and operator protection for all loader platforms sold within member states, while the EU F-Gas Regulation accelerates electric and hybrid powertrain development by restricting hydrofluorocarbon refrigerants in cab climate systems. Germany's KBA enforces whole-vehicle type approval for roadable loader variants, creating compliance differentiation between construction-only and dual-use equipment suppliers. Stakeholders must monitor battery-electric runtime benchmarks against diesel parity thresholds as rental fleet procurement criteria harden.
Market Dynamics
The EU F-Gas Regulation is compressing diesel powertrain dominance by mandating refrigerant phase-downs that accelerate electric cab climate system adoption, forcing manufacturers to redesign thermal management architectures around battery-electric platforms.
Growth Catalysts
- Benelux Landscaping Contracts:Turf-sensitive urban utility projects in Belgium and the Netherlands are specifying compact track loaders for green zone maintenance, creating equipment refresh cycles that favor multi-attachment versatility over single-purpose machines.
- EU Green Deal Construction Standards:Public procurement frameworks across member states now embed carbon intensity scoring for municipal fleets, directing capital toward electrified loader platforms with standardized quick-coupler interfaces.
- Scandinavian Snow Removal Fleet Modernization:Municipal operators in Norway, Sweden, and Finland are retiring dedicated snowplow trucks in favor of year-round multi-attachment loaders that amortize acquisition costs across four-season utilization schedules.
Market Restraints
- Battery Cell Supply Concentration:European OEMs depend on Asian cell manufacturers for high-energy-density packs, exposing production schedules to maritime logistics volatility and raw material processing bottlenecks in the cathode supply chain.
- High-Voltage Technician Scarcity:Dealer service networks face structural skill gaps in diagnosing 400V+ electrical architectures, extending repair turnaround times and elevating warranty reserve requirements for electrified loader variants.
- Steel Input Cost Volatility:Boom and chassis fabrication depends on hot-rolled coil pricing that fluctuates with energy-intensive smelting economics, compressing gross margins on base machine sales when alloy surcharges spike.
Strategic Opportunities
- Polish Rental Fleet Electrification:Warsaw and Krakow construction markets show underpenetrated battery-electric loader adoption relative to Western European capitals, creating first-mover positioning for OEMs establishing regional service hubs.
- Telematics-Enabled Attachment Monetization:Hydraulic flow monitoring systems allow usage-based billing for high-wear implements like demolition grapples, opening recurring revenue streams that decouple from machine ownership cycles.
- CE Marking Mutual Recognition:Machinery Directive compliance certification for EU member states is expanding into adjacent Eastern European markets through harmonized conformity assessment procedures, reducing duplicate testing costs for cross-border sales.
Industry Challenges
- Dual-Use Vehicle Type Approval Complexity:Germany's KBA roadworthiness certification for street-legal loaders requires separate homologation tracks from construction-only equipment, fragmenting engineering resources and extending product launch timelines.
- Legacy Hydraulic System Integration:Electric powertrains must interface with existing high-flow attachment circuits designed for engine-driven pumps, creating thermal management conflicts that demand redesigned valve architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Multi Attachment Loaders Market |
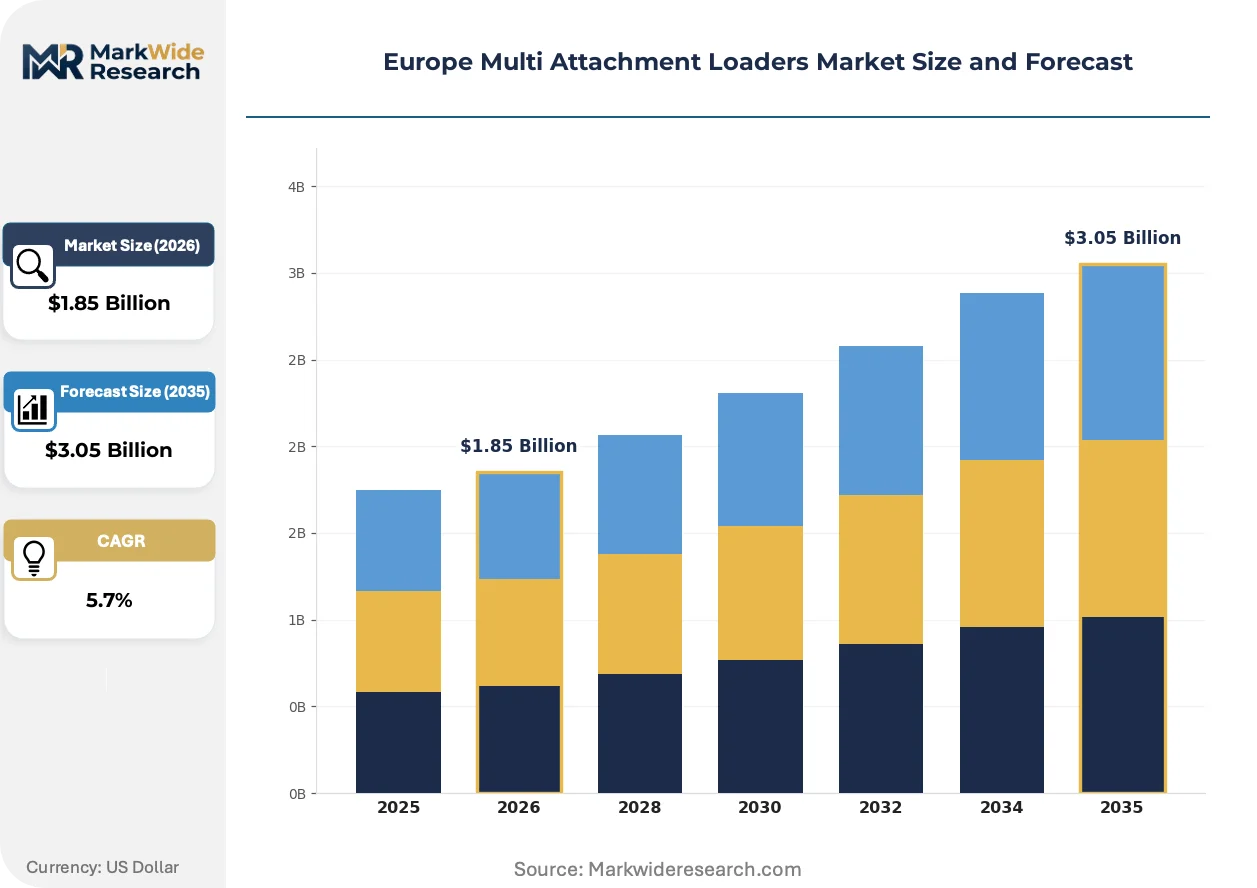
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skid Steer Loaders, Compact Track Loaders, Wheel Loaders, Loader Attachments End User: Agriculture, Construction, Landscaping, Mining Distribution Channel: Direct Sales, Wholesale, Online Retail, Dealerships Application: Excavation, Material Handling, Snow Removal, Demolition |
| Companies Covered | Caterpillar, Volvo Construction Equipment, JCB, CNH Industrial, Komatsu, Liebherr, Bobcat Company, Hitachi Construction Machinery, Wacker Neuson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Multi Attachment Loaders Market Shifts & Advancements
Electrification is restructuring competitive advantage around thermal management and battery packaging rather than engine displacement, while telematics penetration is shifting aftermarket revenue from parts sales toward predictive maintenance subscriptions.
High-flow auxiliary hydraulics is expanding into precision attachment control through electronically modulated valve blocks that match flow rates to implement demand in real time. Municipal fleets in Denmark and Sweden are specifying these systems for snow blower and sweeper interchangeability. The technology is expanding into rental fleet specifications that prioritize operator productivity metrics over base machine acquisition cost.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in mobile air conditioning systems above specific global warming potential thresholds. Loader OEMs must redesign cab climate loops around CO2 or hydrocarbon alternatives, adding thermal system engineering complexity to electrification programs. Nordic markets with extended cold-start requirements are experiencing compressed product validation timelines as dual heating-cooling architectures replace conventional heat pump designs.
Rental channel consolidation is compressing equipment specification diversity as major fleet operators standardize across fewer attachment interface formats. Independent dealers in Southern Europe face margin pressure from direct manufacturer relationships with multi-branch rental groups. Italy and Spain show the most visible channel restructuring, with regional rental cooperatives consolidating procurement volumes to extract pricing concessions previously reserved for national accounts.
Europe Multi Attachment Loaders Market Segmentation
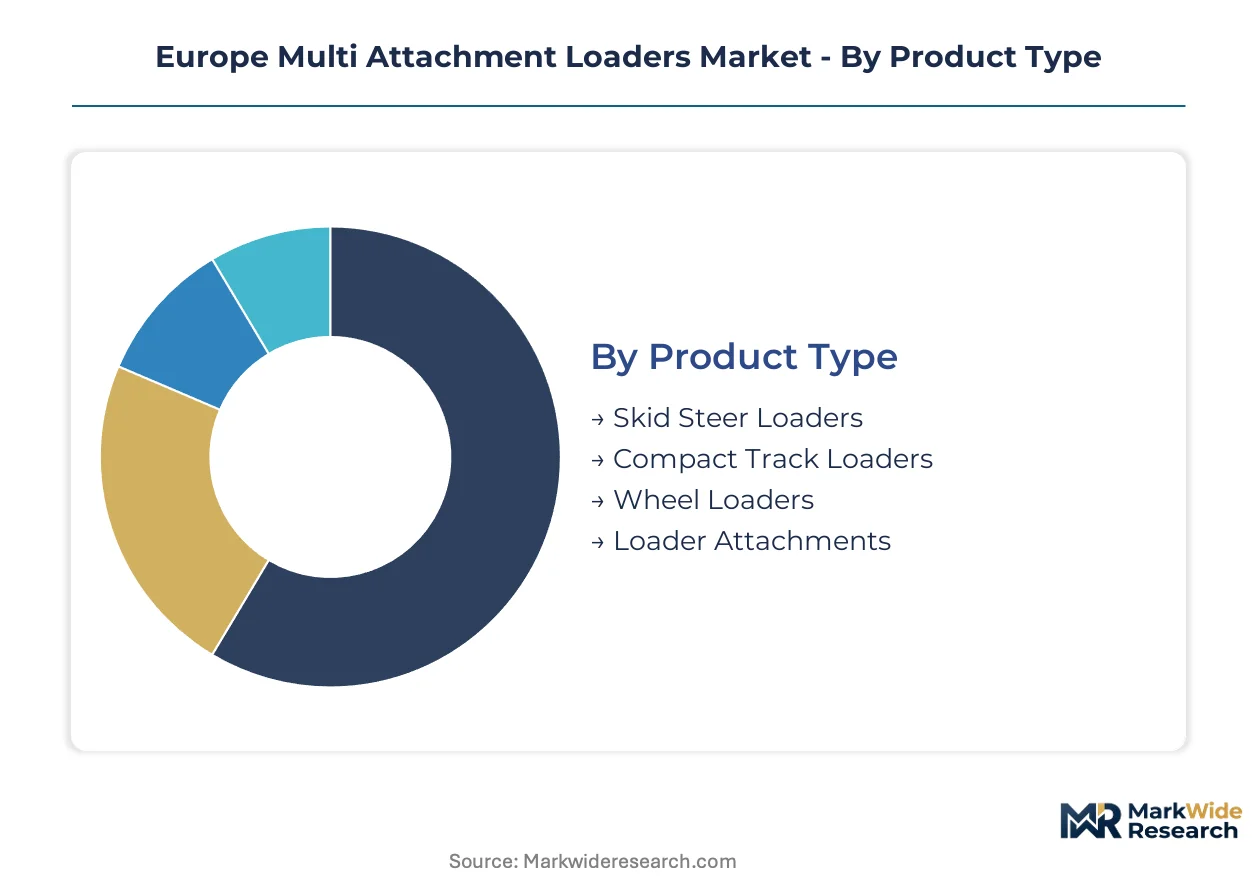
Segmentation in the Europe Multi Attachment Loaders Market reveals distinct equipment specifications across operating environments. Product architecture, end-use intensity, and channel economics each create divergent margin profiles and replacement cycle dynamics.
Product Type:
Standalone loader platforms dominate capital deployment, while attachment ecosystems generate recurring aftermarket revenue through hydraulic interface standardization.
- Skid Steer Loaders:Wheeled platforms with rigid-frame articulation deliver high maneuverability in confined construction sites. German rental fleets in the Rhine-Ruhr corridor specify these for material handling density, though tire wear elevates operating costs on abrasive surfaces.
- Compact Track Loaders:Rubber-tracked undercarriages distribute ground pressure below 4 psi for turf-sensitive applications. Benelux landscaping contracts in Belgium and the Netherlands are concentrating procurement here, driven by urban green zone maintenance mandates and year-round utilization requirements.
- Wheel Loaders:Articulated-frame designs with 1-3 cubic yard buckets serve high-volume earthmoving.
- Loader Attachments:Quick-coupler implements including buckets, forks, augers, and grapples extend machine versatility.
Compact Track Loaders lead volumes today; Skid Steer Loaders is gaining share fastest in electrified variants.
End User:
Customer type determines attachment complexity and service contract structures across seasonal and continuous-use patterns.
- Construction:General contractors and earthmoving specialists demand high-flow hydraulics for demolition grapples and breaker attachments. Poland's Warsaw and Krakow markets show accelerating fleet refresh cycles as EU Green Deal procurement standards harden carbon intensity scoring.
- Agriculture:Livestock and crop operations prioritize bale handling forks and manure buckets with corrosion-resistant finishes. Scandinavian cooperatives amortize acquisition costs across four-season schedules combining snow removal with feed handling.
- Landscaping:Municipal and commercial grounds maintenance specifies low-ground-pressure track systems.
- Mining:Quarry and aggregate extraction requires reinforced boom structures and extended warranty coverage.
Construction commands the largest equipment base; Agriculture is climbing the fastest as seasonal utilization models spread.
Distribution Channel:
Channel selection reflects transaction scale and technical service requirements across fleet and individual buyer segments.
- Direct Sales:Manufacturer-to-fleet relationships dominate municipal and national rental group procurement. Italy and Spain show visible channel restructuring as regional rental cooperatives consolidate volumes to extract pricing concessions.
- Dealerships:Independent networks retain agricultural customer relationships through seasonal trade-in programs and attachment financing. High-voltage technician scarcity in these networks extends repair turnaround times for electrified variants.
- Wholesale:Distributor intermediaries serve smaller construction contractors with standardized specifications.
- Online Retail:Digital platforms facilitate attachment and parts transactions for owner-operators.
Direct Sales captures the steepest expansion trajectory; Dealerships retain the deepest agricultural penetration.
Application:
Task specificity drives hydraulic flow requirements and attachment interchangeability investments.
- Material Handling:Pallet forks, buckets, and grapples constitute the baseline attachment configuration across all loader categories. Denmark and Sweden municipal fleets specify electronically modulated valve blocks for real-time flow matching to implement demand.
- Snow Removal:High-flow snow blowers and angle blades require cold-climate hydraulic specifications with arctic-grade fluids. Norway, Sweden, and Finland are retiring dedicated snowplow trucks in favor of year-round multi-attachment platforms.
- Excavation:Backhoe and trenching attachments demand reinforced quick-coupler interfaces.
- Demolition:Hydraulic breakers and grapples concentrate margin pools through aftermarket parts recurrence exceeding base machine revenue cycles.
Material Handling anchors current deployment; Snow Removal shows the strongest share gain as Nordic fleets modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between national type-approval regimes is concentrating loader production in jurisdictions with streamlined CE marking pathways, while electrification mandates in core markets pull R&D investment toward battery-integrated platforms despite higher compliance costs.
Germany
Rhine-Ruhr construction corridors drive fleet refresh demand as general contractors prioritize high-flow hydraulic specifications for demolition attachments. KBA roadworthiness certification for dual-use loaders creates compliance differentiation between construction-only and street-legal variants, fragmenting engineering resources. Munich and Stuttgart engineering clusters anchor electrification development as OEMs redesign thermal architectures around CO2 climate systems mandated by the EU F-Gas Regulation.
Sweden
Arctic-grade hydraulic specifications dominate municipal procurement as snow removal fleets retire single-purpose plow trucks for year-round multi-attachment platforms. The EU Green Deal embeds carbon intensity scoring in public tenders, directing capital toward electrified loaders with standardized quick-coupler interfaces. Stockholm and Gothenburg municipal operators amortize acquisition costs across four-season utilization schedules combining winter snow handling with summer maintenance.
Poland
Warsaw and Krakow construction markets show underpenetrated battery-electric loader adoption relative to Western European capitals, creating first-mover positioning for OEMs establishing regional service hubs. CE marking mutual recognition through harmonized conformity assessment procedures reduces duplicate testing costs for cross-border sales into adjacent Eastern European markets. Silesian industrial zones concentrate rental fleet procurement as regional cooperatives consolidate volumes to extract pricing concessions.
Netherlands
Benelux landscaping contracts specify compact track loaders for turf-sensitive urban utility projects, with ground pressure requirements below 4 psi driving rubber-tracked platform preference. The EU Machinery Directive governs structural integrity certification for all loader platforms, while national procurement frameworks prioritize carbon intensity metrics. Rotterdam and Amsterdam green zone maintenance mandates create equipment refresh cycles favoring multi-attachment versatility over single-purpose machines.
Italy
Rental channel consolidation compresses equipment specification diversity as multi-branch fleet operators standardize across fewer attachment interface formats. Dealer networks face margin pressure from direct manufacturer relationships with national rental groups. Lombardy and Emilia-Romagna agricultural cooperatives retain seasonal trade-in programs through independent dealerships, though high-voltage technician scarcity extends repair turnaround times for electrified variants.
Europe Multi Attachment Loaders Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line construction equipment OEMs dominating municipal and rental fleet procurement while regional fabricators capture agricultural trade-in volumes through dealer relationships. Market structure concentrates around three strategic archetypes: integrated full-line suppliers with telematics-enabled attachment ecosystems, regional specialists in cold-climate hydraulic specifications, and compact equipment pure-plays leveraging turf-sensitive track technologies. Competitive dynamics center on M&A activity consolidating rental channel relationships and strategic partnerships securing battery cell supply for electrified platform launches.
Among integrated construction equipment groups, Caterpillar, Volvo Construction Equipment, and JCB occupy positions representing distinct competitive vectors. Caterpillar exemplifies scale-driven dealer density advantages across German federal state procurement frameworks. Volvo Construction Equipment anchors Nordic market presence through archetype representation in cold-climate hydraulic engineering. JCB sustains technology leadership positioning through telehandler-to-loader attachment interoperability, occupying a specialist-integration hybrid tier that bridges full-line capabilities with implement-focused innovation.
| Leading Market Players |
|---|
| Caterpillar |
| Volvo Construction Equipment |
| JCB |
| CNH Industrial |
| Komatsu |
| Liebherr |
| Bobcat Company |
| Hitachi Construction Machinery |
| Wacker Neuson |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap German fabricators anchor boom and chassis production, concentrating supply discipline around Rhine-Ruhr engineering clusters while exerting pricing power through KBA roadworthiness certification differentiation for dual-use loaders.
Pricing Analysis
Distributor margin compression in Southern European dealership networks intensifies as direct manufacturer relationships with consolidated rental groups extract volume concessions. Three-tier pricing structure across premium electrified platforms, standard diesel variants, and economy skid-steer configurations stratifies by hydraulic flow specification and CE marking tier. Cost compression in economy tiers reflects steel input volatility from energy-intensive smelting economics. Municipal procurement officers in Scandinavia show lowest price sensitivity, prioritizing four-season utilization amortization over acquisition cost.
Supply Chain Analysis
High-energy-density battery cell supply rests on South Korean and Japanese cathode processing specialists, tethering European OEM electrification timelines to maritime logistics chokepoints through Rotterdam and Hamburg. Hot-rolled coil for boom fabrication draws from German and Turkish rolling mills, while arctic-grade hydraulic fluids source from Scandinavian petrochemical refiners. Single-source vulnerability in 400V+ power electronics concentrates among German semiconductor packaging specialists. Distribution runs through manufacturer-direct fleet contracts for municipal and rental accounts, with independent dealerships retaining agricultural aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Multi Attachment Loaders Market reads as a late-cycle quality story where municipal fleet procurement is hardening carbon intensity scoring, redirecting capital toward electrified platforms with standardized quick-coupler interfaces and extended warranty coverage.
For Market Incumbents: Cement Nordic market presence through cold-climate hydraulic specification investments that match Volvo Construction Equipment's arctic-grade engineering anchor. Prioritize backward integration into battery pack assembly to reduce South Korean cell manufacturer dependency. Defend against emerging compact equipment pure-plays by locking rental channel exclusivity through telematics-enabled attachment monetization contracts.
For New Entrants and Emerging Players: Digital platform distribution routes into Polish rental fleet electrification offer lowest competitive density relative to Western European capitals. Target Warsaw and Krakow construction markets with battery-electric loader variants supported by regional service hub partnerships. Penetrate through telematics-integrated usage-based billing models for high-wear demolition grapples that decouple revenue from machine ownership cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional cold-climate hydraulic specialists with established Scandinavian municipal relationships but limited electrification R&D pipelines. Five-to-ten year viability hinges on thermal management architecture capabilities for CO2 climate systems mandated by EU F-Gas Regulation. Monitor battery-electric runtime benchmark announcements against diesel parity thresholds as rental fleet procurement criteria harden.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Platform Launch | Battery-integrated architectures satisfy EU F-Gas Regulation mandates while opening municipal procurement channels. |
| Telematics-Enabled Attachment Monetization | Hydraulic flow monitoring systems generate recurring revenue streams beyond base machine sales cycles. |
| Regional Service Hub Establishment | Polish hub positioning captures underpenetrated Warsaw and Krakow battery-electric adoption curves. |
| Cold-Climate Hydraulic Specification Investment | Arctic-grade engineering anchors Nordic municipal fleet replacement schedules across four-season utilization. |
| CE Marking Mutual Recognition Expansion | Harmonized conformity assessment procedures reduce duplicate testing costs for Eastern European cross-border sales. |
Research Methodology
Multiple input streams — OEM product development executives, municipal fleet procurement managers, rental group equipment directors, and aftermarket service heads — were reconciled against customs trade data, EU Machinery Directive filing records, SEC construction equipment segment disclosures, and national procurement framework documents. Bottom-up unit shipment estimates triangulated with top-down capital expenditure analysis across the Rhine-Ruhr, Benelux, and Nordic construction corridors.
Historical shipment trajectories cross-referenced against expert panel input on electrification adoption curves shaped volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-use intensity, distribution channel economics, and application-specific hydraulic flow requirements. CAGRs derived from equipment replacement cycle analysis, regulatory compliance cost trajectories, and attachment ecosystem monetization potential.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery integration or hydrogen fuel cell powertrains would alter the outlook for electrified loader penetration. Forecasts reflect assumptions around EU Green Deal procurement standard implementation timelines and F-Gas Regulation enforcement consistency. A small set of triggers — battery cell supply disruptions, KBA type-approval backlog accumulation, and steel alloy surcharge spikes — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Electric Excavators Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Compaction Equipment Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Heavy Construction Equipment Market