
 GCC Mini Cranes Market | 2026-2036
GCC Mini Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Mini Cranes Market Foresight
Saudi Arabia's domestic crane assembly capacity is shifting toward localized production hubs serving Red Sea and NEOM corridor contracts. Maeda Seisakusho Co., Ltd. anchors its GCC presence through specialized spider crane distribution networks across Riyadh and Jeddah. Furukawa UNIC Corporation leverages compact hydraulic engineering to sustain premium positioning in oilfield services segments. Jekko S.r.l. differentiates via remote-control technology leadership for high-precision infrastructure maintenance applications.
Mini cranes are compact lifting machines with rated capacities typically below 10 tonnes, designed for operation in confined spaces through articulated booms, crawler tracks, or outrigger stabilization systems; they perform material hoisting, equipment placement, and structural assembly where conventional tower or mobile cranes cannot access. Spider cranes dominate product type demand due to their deployability on uneven terrain and inside existing structures across Gulf urban renewal sites. Electric drive technology is expanding fastest, driven by municipal noise ordinances and indoor air quality requirements in Dubai and Doha commercial districts. Equipment rental firms represent the largest end user channel, capturing recurring revenue streams from project-based contractors seeking operational flexibility without capital deployment.
MOHAP and Saudi Standards, Metrology and Quality Organization (SASO) enforce machinery safety certifications and operator competency frameworks that determine market access for imported mini crane fleets. The UAE's Ministry of Climate Change and Environment aligns with federal decarbonization targets to restrict diesel-only equipment registration in Emirate-level construction zones. Stakeholders must monitor how Saudi Arabia's Local Content requirements and the UAE's Green Building Regulations reshape procurement criteria for lifting equipment across government-backed developments.
Market Dynamics
Saudi Arabia's giga-project pipeline is compressing deployment timelines for compact lifting equipment, forcing rental fleets to prioritize spider crane configurations that navigate confined Red Sea and NEOM construction zones without site reconfiguration.
Growth Catalysts
- Electric-drive mandates:Dubai and Doha municipal noise ordinances accelerate fleet electrification among equipment rental firms serving indoor commercial districts.
- SASO safety frameworks:Saudi Arabia's machinery certification requirements standardize operator competency, reducing liability exposure for cross-border equipment lessors.
- Spider crane terrain adaptability:Articulated boom configurations with outrigger stabilization penetrate uneven Gulf urban renewal sites where conventional mobile cranes face access constraints.
Market Restraints
- Steel input volatility:Boom arm fabrication costs fluctuate with regional steel supply, compressing margin buffers for crane assemblers operating localized production hubs.
- Import dependency concentration:Hydraulic component sourcing concentrates in East Asian supply chains, exposing GCC distributors to extended lead times and currency hedge costs.
- Diesel equipment registration friction:UAE Ministry of Climate Change and Environment restrictions on diesel-only fleet registration create stranded asset risk for legacy equipment holders.
Strategic Opportunities
- Qatar infrastructure renewal:Post-World Cup commercial repurposing projects generate demand for precision maintenance lifting in existing stadium and hospitality structures.
- Remote-control convergence:Integration of telematics with hydraulic systems enables high-precision infrastructure maintenance applications without operator proximity.
- Kuwait logistics corridor expansion:Northern Gulf port modernization creates material handling requirements for compact crawler configurations in confined berth environments.
Industry Challenges
- Certification timeline compression:MOHAP and SASO concurrent safety audits extend equipment type-approval cycles, delaying fleet deployment for rental operators.
- Telematics integration complexity:Legacy hydraulic control architectures resist seamless retrofit with IoT monitoring systems, fragmenting fleet management standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Mini Cranes Market |
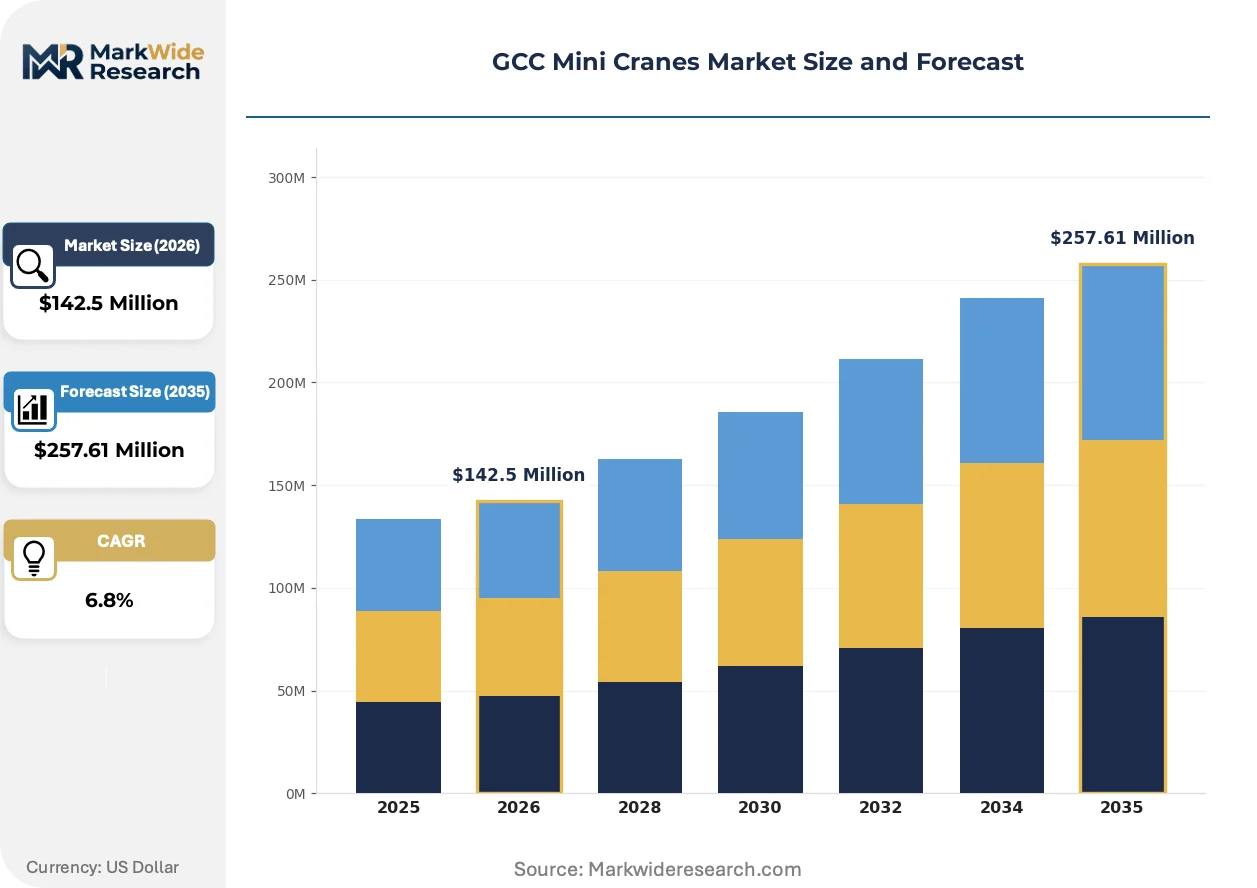
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spider Cranes, Carry Deck Cranes, Hydraulic Truck Cranes, Rough Terrain Cranes, Pick & Carry Cranes Technology: Electric Drive, Diesel Engine, Hybrid Power, Manual Operation, Remote Control Application: Construction, Oilfield Services, Material Handling, Infrastructure Maintenance, Renewable Energy Projects End User: Equipment Rental Firms, Logistics Companies, Shipyards, Facility Management Providers, Mining Operations |
| Companies Covered | Maeda Seisakusho Co., Ltd., Furukawa UNIC Corporation, UNIC Cranes Europe, Hoeflon International B.V., Jekko S.r.l., BG Lift, Valla Cranes, Spydercrane, Linamar Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Mini Cranes Market Shifts & Advancements
Electrification and telematics convergence are reconfiguring equipment specifications across Gulf rental channels, while regulatory pressure on emissions accelerates product development cycles for regional distributors.
Battery-electric powertrains are modularizing crane architecture design. Spider crane manufacturers serving Dubai commercial districts adopt swappable battery packs to comply with indoor air quality mandates. This modularization compresses equipment downtime for rental fleets operating across multiple job sites daily.
UAE Green Building Regulations are tightening embodied carbon thresholds for construction equipment deployed in federal developments. Contractors must now document machinery emissions profiles to secure government-backed contracts. Electric-drive mini crane categories capture preferential procurement scoring in Abu Dhabi and Dubai municipal tenders.
Rental firms are unbundling maintenance contracts from equipment leases. Project-based contractors in Saudi Arabia's giga-project corridor now procure lifting services through hourly-rate structures with performance guarantees. This consumption-pattern shift concentrates fleet investment risk with specialized lessors while transferring operational flexibility to construction managers.
GCC Mini Cranes Market Segmentation
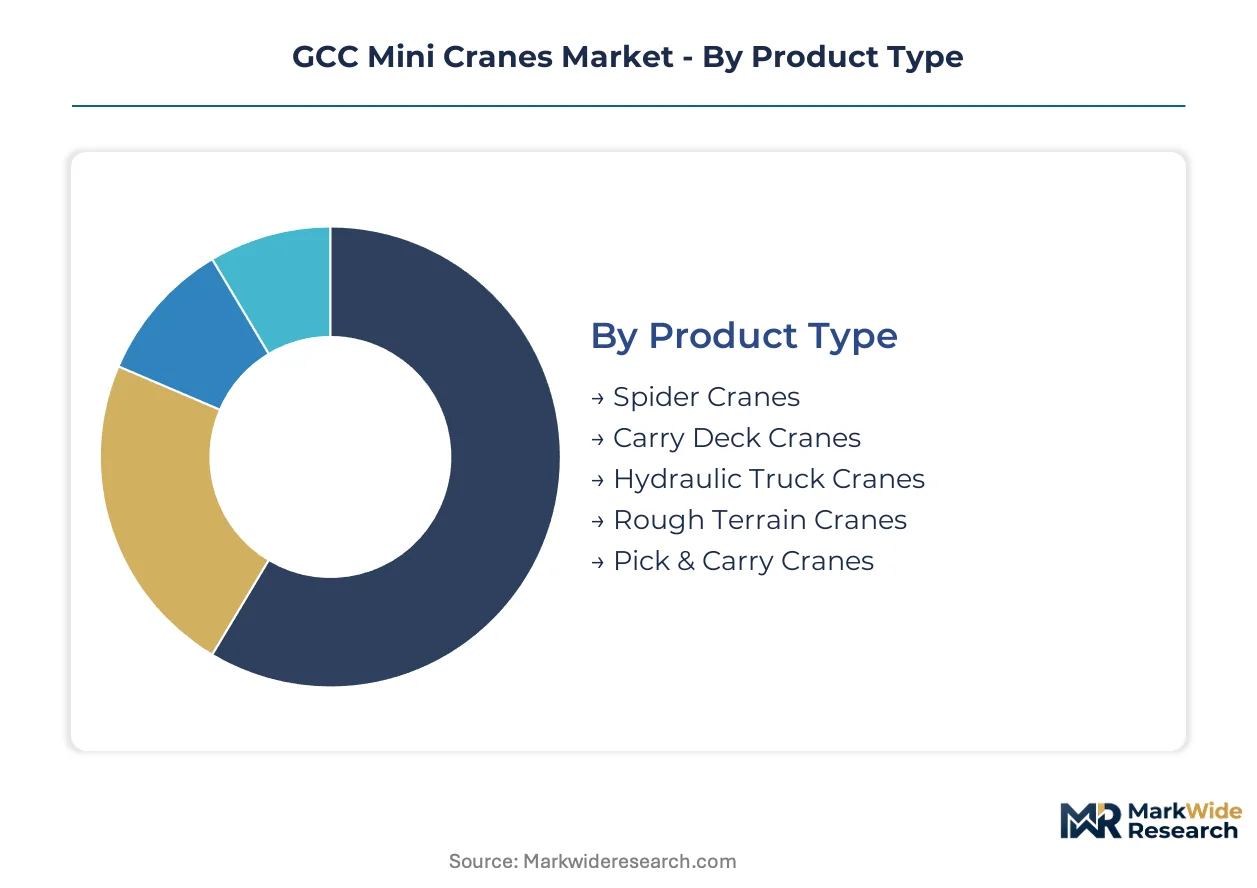
Mini crane procurement patterns diverge sharply across Gulf construction corridors. Equipment lessors configure fleets around terrain constraints, emission mandates, and project duration rather than lifting capacity alone.
Product Type:
Customization intensity spans from fully modular spider configurations to standardized rough-terrain platforms serving repetitive site conditions.
- Spider Cranes:Articulated booms with outrigger stabilization deploy on uneven surfaces and inside existing structures. Demand concentrates across Saudi Arabia's NEOM and Red Sea giga-projects where confined zones prohibit conventional mobile crane access. Rental firms prioritize these configurations for urban renewal sites in Dubai and Doha.
- Carry Deck Cranes:Compact rotating decks with rear-mounted cabs handle material transport and placement in single motions. Oilfield services segments in eastern Saudi Arabia and Kuwait favor these for equipment staging around wellhead infrastructure where space compression limits boom articulation.
- Hydraulic Truck Cranes:Highway-legal carriers with telescoping booms serve rapid-deployment maintenance contracts.
- Rough Terrain Cranes:Four-wheel-drive outrigger systems dominate remote construction camps lacking prepared surfaces.
- Pick & Carry Cranes:Friction-drive crawlers perform repetitive short-radius lifts in precast yard environments.
Leading the category by volume: Spider Cranes. Expanding most quickly: Carry Deck Cranes.
Technology:
Powertrain selection tracks regulatory pressure gradients across Emirate-level construction zones and indoor air quality thresholds.
- Electric Drive:Battery-electric powertrains with swappable modular packs eliminate emissions for indoor commercial work. Dubai and Doha municipal noise ordinances accelerate fleet conversion among rental operators serving enclosed retail and hospitality fit-outs.
- Diesel Engine:Conventional compression-ignition systems retain dominance in remote giga-project phases lacking grid infrastructure. UAE Ministry of Climate Change and Environment restrictions on diesel-only registration are compressing residual demand timelines.
- Hybrid Power:Dual-mode architectures switch between electric and combustion operation based on site proximity to grid connections.
- Manual Operation:Direct hydraulic control persists in cost-sensitive short-term rental segments.
- Remote Control:Radio-frequency and cable-linked systems enable precision placement without operator cabin proximity.
Electric Drive commands premium positioning in municipal procurement scoring. Remote Control is climbing the fastest as infrastructure maintenance contracts specify telematics integration.
Application:
End-use concentration shifts with capital cycle timing across hydrocarbon, real estate, and utility investment waves.
- Construction:Structural steel erection, precast panel placement, and mechanical equipment hoisting in vertical building projects. Saudi Arabia's giga-project pipeline absorbs the majority of spider crane and carry deck deployments through equipment rental firm channels.
- Oilfield Services:Wellhead maintenance, pump replacement, and compression equipment installation. Furukawa UNIC Corporation's compact hydraulic engineering sustains positioning in these segments through distributor networks in Dammam and Abu Dhabi.
- Material Handling:Port and logistics yard operations requiring repetitive lift-and-transport cycles.
- Infrastructure Maintenance:Bridge deck repair, tunnel ventilation system replacement, and overhead utility work.
- Renewable Energy Projects:Solar panel array installation and wind turbine component staging.
Construction dominates absolute unit demand. Renewable Energy Projects show steepest expansion trajectory as Saudi Arabia and UAE utility procurement accelerates.
End User:
Customer structure concentrates risk ownership with specialized lessors while transferring operational flexibility to project-based contractors.
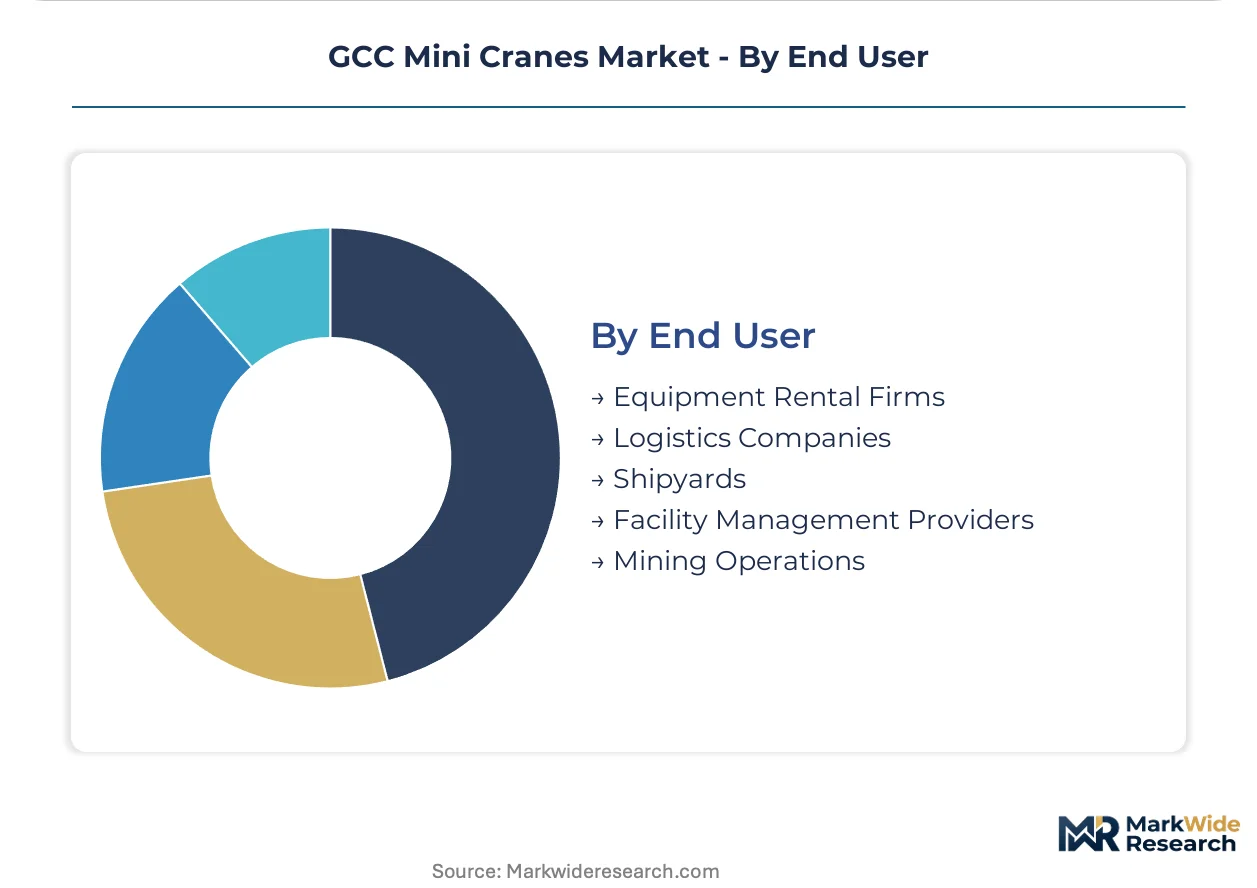
- Equipment Rental Firms:Fleet owners providing hourly-rate lifting services with performance guarantees. These channels capture recurring revenue from Saudi giga-project contractors seeking capital deployment avoidance. Unbundled maintenance contracts now separate from equipment leases.
- Logistics Companies:Port operators and warehouse developers deploying compact crawlers for confined berth material handling. Kuwait's Northern Gulf port modernization is generating demand for crawler configurations in restricted quay environments.
- Shipyards:Vessel repair and outfitting facilities requiring precision placement in drydock environments.
- Facility Management Providers:Building operators performing HVAC replacement and facade maintenance in occupied structures.
- Mining Operations:Extraction and processing sites utilizing rough-terrain configurations for crusher maintenance.
Equipment Rental Firms lead by fleet ownership concentration. Facility Management Providers are gaining share fastest as post-World Cup Qatar commercial repurposing extends precision maintenance demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters in Jubail and Ras Al-Khaimah anchor GCC mini crane assembly capacity. Localized production hubs serve Red Sea and NEOM corridor contracts while reducing import dependency for boom arm components.
Saudi Arabia
NEOM and Red Sea giga-projects compress deployment timelines for spider crane configurations navigating confined construction zones. SASO machinery certification requirements standardize operator competency frameworks for cross-border equipment lessors. Riyadh and Jeddah host specialized distribution networks serving urban renewal and oilfield maintenance segments.
United Arab Emirates
Dubai commercial districts drive battery-electric fleet conversion to comply with municipal noise ordinances and indoor air quality mandates. The UAE Ministry of Climate Change and Environment restricts diesel-only equipment registration in Emirate-level construction zones. Abu Dhabi municipal tenders assign preferential procurement scoring to electric-drive mini crane categories in federal developments.
Qatar
Post-World Cup stadium and hospitality repurposing generates precision maintenance lifting demand in existing structures. The country's national construction regulator enforces machinery safety standards for equipment deployment in occupied buildings. Doha commercial fit-out projects absorb spider crane rentals for enclosed retail and hospitality environments.
Kuwait
Northern Gulf port modernization creates material handling requirements for compact crawler configurations in confined berth environments. The country's logistics infrastructure authority oversees equipment specifications for quay-side operations. Kuwait City and Shuwaikh port clusters concentrate demand for rough-terrain and carry deck crane deployments.
GCC Mini Cranes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and telematics convergence. The vendor base stratifies across Japanese precision engineering specialists, European remote-control technology developers, and regional assembly operations serving localized content requirements. Three archetypes dominate: hydraulic system heritage players, battery-electric modular innovators, and rental fleet service integrators. Competitive intensity centers on M&A activity consolidating distribution networks and strategic partnerships securing hydraulic component supply.
Among Japanese-origin manufacturers, Maeda Seisakusho Co., Ltd. and Furukawa UNIC Corporation occupy positions reflecting hydraulic engineering heritage and oilfield services specialization. Jekko S.r.l. represents the European remote-control technology archetype. These three anchors exemplify how geographic origin and corporate structure map to distinct competitive positioning within GCC procurement channels.
| Leading Market Players |
|---|
| Maeda Seisakusho Co., Ltd. |
| Furukawa UNIC Corporation |
| UNIC Cranes Europe |
| Hoeflon International B.V. |
| Jekko S.r.l. |
| BG Lift |
| Valla Cranes |
| Spydercrane |
| Linamar Corporation |
| Others |
Supply & Pricing Matrix
Battery-electric powertrain modularization simultaneously compresses manufacturing cost curves for crane assemblers and concentrates component sourcing leverage with East Asian battery pack suppliers serving Dubai and Doha commercial districts. This dual restructuring forces rental fleet operators to absorb upfront technology premiums while negotiating service-unbundled contract terms.
Pricing Analysis
Warranty and maintenance bundling now separates from equipment lease rates across Saudi giga-project corridors, with performance-guarantee hourly structures commanding premium positioning over bare-metal rentals. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and telematics integration depth. Cost compression in standard-tier diesel configurations intensifies because UAE registration restrictions strand legacy fleet values. Project-based contractors in NEOM zones exhibit highest price sensitivity, while facility management providers in occupied Doha structures accept premium electric-drive rates.
Supply Chain Analysis
Specialized hydraulic technician shortages in South Korea, Japan, and eastern China constrain boom arm fabrication capacity for GCC-bound crane assemblies. Steel input sourcing draws from Chinese and Indian mill complexes, while precision hydraulic valves rest on German and Japanese component networks. Single-source vulnerability concentrates in battery cell supply for electric-drive conversions. Distribution runs through Jebel Ali and Dammam port clusters into Riyadh and Dubai equipment lessor consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as SASO certification timelines and electric-drive R&D capital requirements force sub-scale distributors toward exit. Surviving players will capture stranded competitor fleet contracts.
For Market Incumbents: Deepen backward integration into boom arm fabrication at Jubail and Ras Al-Khaimah production hubs to offset steel input volatility. Capture stranded asset rental contracts from diesel-only fleet operators facing UAE Ministry of Climate Change and Environment registration restrictions. Certification investment in SASO and MOHAP concurrent audit protocols becomes the critical lever for deployment timeline advantage. For New Entrants and Emerging Players: Equipment rental firms in Qatar's post-World Cup commercial repurposing corridor represent the most penetrable channel partner type for spider crane placement. Target facility management providers performing precision maintenance in occupied stadium and hospitality structures where remote-control specifications dominate procurement. A telematics-integrated service partnership with established lessors offers faster market access than direct fleet ownership. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Japanese-origin manufacturers seeking GCC distribution density. Long-term viability frames around electrification transition completion and localized content compliance maturity. Watch for Abu Dhabi municipal tender scoring shifts toward embodied carbon documentation as the inflection signal for electric-drive fleet valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Production Hub Establishment | Jubail and Ras Al-Khaimah steel clusters reduce import dependency for Red Sea corridor contracts. |
| Electric-Drive Fleet Conversion | Swappable battery pack configurations satisfy Dubai indoor air quality mandates and noise ordinances. |
| Telematics Platform Integration | Remote-control convergence enables high-precision infrastructure maintenance without operator proximity. |
| Certification Pre-Investment | SASO and MOHAP concurrent audit readiness compresses equipment type-approval cycles for rental deployment. |
| Maintenance Contract Unbundling | Hourly-rate performance guarantees transfer fleet investment risk to specialized lessors serving Saudi giga-projects. |
Research Methodology
Trade flow databases, customs records, and equipment registration filings formed the secondary backbone, supplemented by primary interviews with rental fleet managers, OEM procurement teams, aftermarket service heads, and port logistics operators. Bottom-up unit deployment tracking across Saudi giga-project corridors combined with top-down market sizing validation. Cross-referencing SASO certification timelines with MOHAP safety audit protocols anchored regulatory constraint modeling.
Historical trendline analysis of spider crane and carry deck deployment patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, powertrain architecture, end-use application, and customer channel dimensions. CAGRs derived from equipment replacement cycle compression and electrification penetration curves. Steel input cost volatility and hydraulic component lead time fluctuations served as industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including abrupt regulatory acceleration beyond current UAE decarbonization mandates and geopolitical disruption to East Asian battery supply chains. Forecasts reflect documented assumptions regarding SASO certification timeline stability and rental firm consolidation pace. Material deviation in steel price trajectories or hydraulic component sourcing chokepoints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crane Rail Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Global Excavators Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Construction Equipment Tire Market
Construction Equipment
Hydroforming Press Market