
 China Transportation Infrastructure Construction Market | 2026-2036
China Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
China Transportation Infrastructure Construction Market Outlook
A shortage of certified bridge engineers and tunneling specialists is unwinding project timelines across western provinces. China Communications Construction Company Limited leverages its port and marine engineering heritage to dominate coastal infrastructure bids. China State Construction Engineering Corporation sustains unmatched vertical scale across prefabricated building systems. China Railway Group Limited anchors the high-speed rail segment through captive track-laying equipment fleets.
China transportation infrastructure construction encompasses the planning, engineering, and assembly of highways, railways, bridges, and airports using concrete, steel, asphalt, and composite materials with specified compressive strengths and load-bearing capacities designed to move passengers and freight efficiently. The construction method dimension reveals prefabricated techniques gaining share as labor costs rise and quality standardization tightens, while the project scale dimension shows mega projects commanding disproportionate financing access through state-backed credit facilities. Material used segments display steel-intensive bridge and rail applications holding premium margin pools against asphalt highway work.
China's Ministry of Transport, Ministry of Housing and Urban-Rural Development, and SAMR enforce GB standards for structural safety and environmental compliance that filter market access toward state-affiliated contractors with certification depth. The dual carbon goals issued by central planners redirect procurement specifications toward low-emission cement and recycled steel, reshaping supplier qualification criteria. Stakeholders must monitor how provincial debt restructuring affects project financing availability in interior regions.
Market Dynamics
Prefabricated construction methods are compressing traditional cast-in-place timelines as labor costs rise and quality standardization tightens across China's transportation infrastructure sector. This structural shift is redistributing competitive advantage toward contractors with integrated manufacturing capabilities.
Growth Catalysts
- Dual carbon goals:Central procurement mandates now favor low-emission cement and recycled steel, redirecting capital toward certified green suppliers.
- Yangtze River Delta concentration:Megacity cluster spanning Shanghai, Nanjing, and Hangzhou absorbs disproportionate financing for urban rail transit expansion.
- Urban rail networks:Municipal governments prioritize subway and light rail systems over highway expansion to address congestion and air quality targets.
Market Restraints
- Steel price volatility:Input cost swings for structural steel compress margins on bridge and rail contracts with fixed-price terms.
- Western province talent scarcity:Shortage of certified bridge engineers and tunneling specialists unwinds project timelines in Sichuan and Yunnan.
- Provincial debt overhang:Restructuring of local government financing vehicles constrains credit availability for interior region megaprojects.
Strategic Opportunities
- GB standards alignment:Ministry of Transport and SAMR certification requirements filter market access toward contractors with quality management depth.
- Western corridor development:Belt and Road Initiative freight corridors through Xinjiang and Gansu offer first-mover positioning for rail-electrification specialists.
- Digital twin integration:Convergence of BIM platforms with IoT sensor networks enables predictive maintenance contracts on long-life infrastructure assets.
Industry Challenges
- Specialized engineering pipeline:Universities produce insufficient geotechnical and tunneling graduates to match western province project backlogs.
- Legacy system integration:New smart highway and rail signaling systems face interoperability friction with existing SCADA and traffic management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Transportation Infrastructure Construction Market |
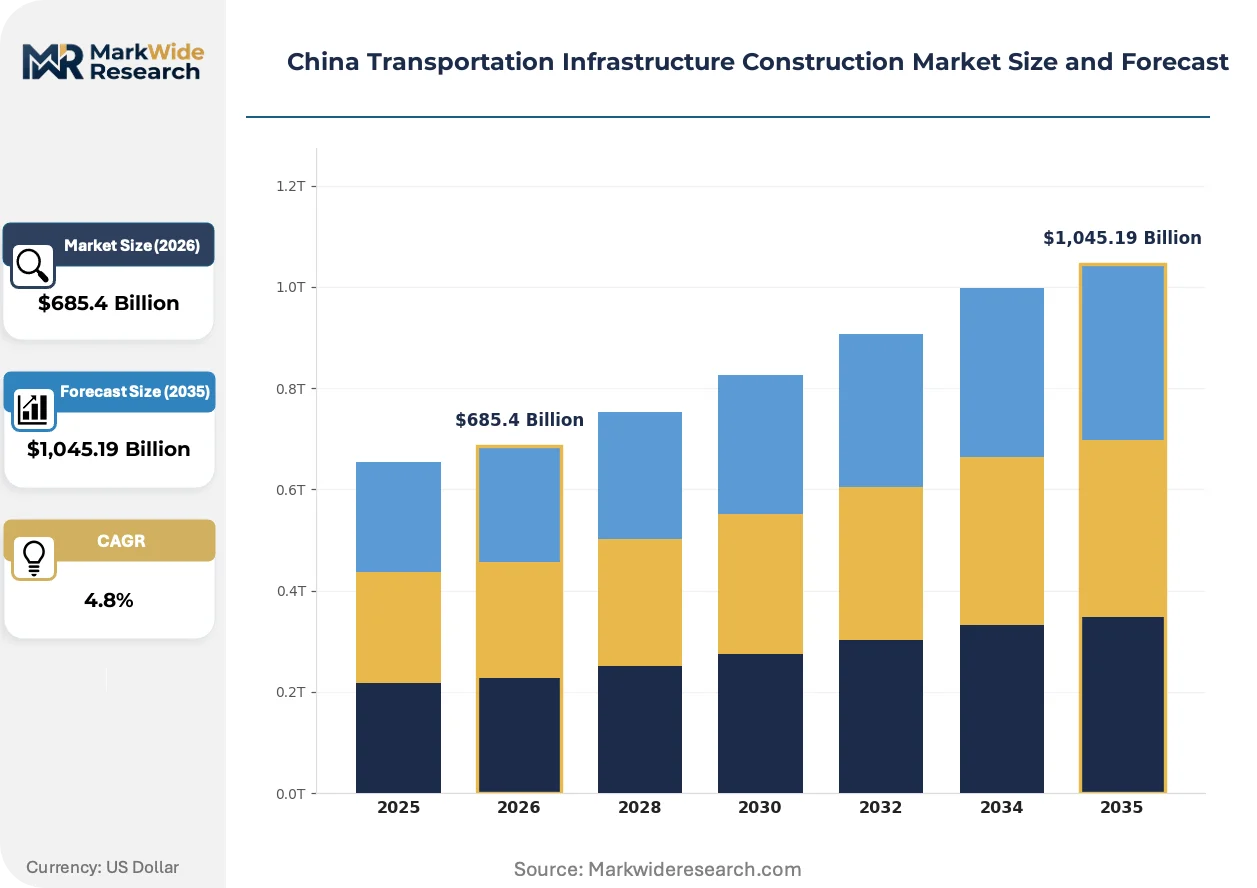
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,045.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Highways, Railways, Bridges, Airports Material Used: Concrete, Steel, Asphalt, Composites Construction Method: Conventional, Prefabricated, Modular, Innovative Project Scale: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | China Communications Construction Company Limited, Shanghai Construction Group, China State Construction Engineering Corporation, China Metallurgical Group Corporation, China Road & Bridge Corporation, China Railway Group Limited, Power Construction Corporation of China, China Gezhouba Group Corporation Limited, China Railway Construction Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Transportation Infrastructure Construction Market Strategic Shifts
Construction methodology is fragmenting as prefabrication, digital fabrication, and on-site robotics compete for capital allocation. Three distinct vectors are reshaping how transportation infrastructure moves from design to operation.
Modular bridge segment manufacturing is decomposing traditional cast-in-place construction by enabling factory-controlled quality and parallel workstreams. Provincial transport bureaus in Jiangsu and Zhejiang now specify precast box girder systems for elevated expressways. This compression of on-site labor dependency is shifting contractor evaluation criteria toward manufacturing scale rather than pure field execution capacity.
GB 55015-2021 energy efficiency standards for buildings are extending to transportation infrastructure through Ministry of Housing and Urban-Rural Development technical circulars. Thermal performance requirements for rail stations and airport terminals now mandate low-carbon envelope materials. Coastal megaprojects in Guangdong and Fujian face accelerated compliance timelines as pilot zones for stricter enforcement.
Public-private partnership structures are fragmenting traditional state-led financing for highway and rail assets. Municipal governments in the Pearl River Delta now bundle operation rights with construction contracts to attract private capital. This shift is most visible in intercity rail links where ridership risk transfer to operators alters contractor selection toward consortiums with operational track records.
China Transportation Infrastructure Construction Market Segmentation
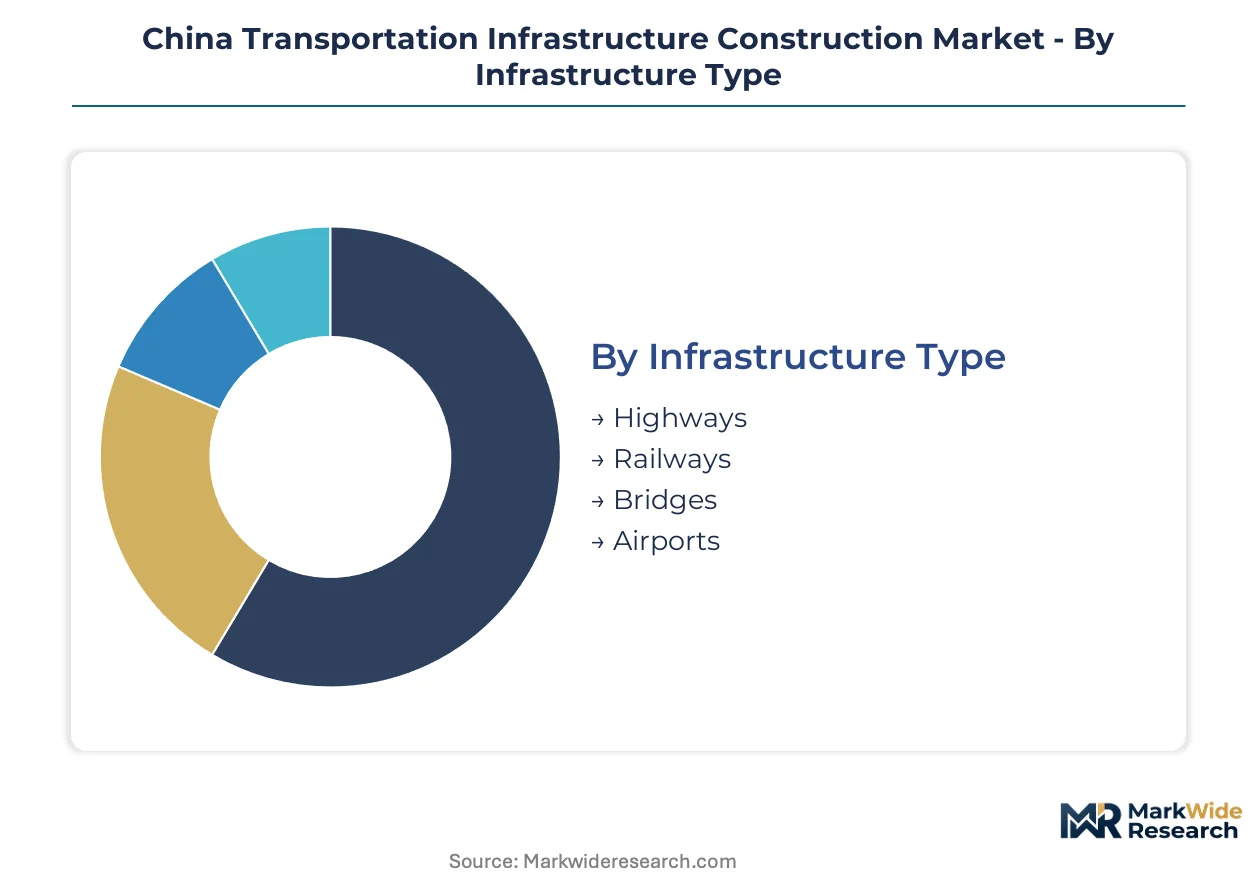
Segmentation reveals how procurement specifications and financing access fragment across China's transportation infrastructure sector. Contractors align capabilities to specific tiers where technical barriers and capital requirements filter competitive intensity.
Infrastructure Type:
Railways face the strongest substitution pressure as urban rail transit absorbs capital that highways once commanded, while airports contend with high-speed rail capture of short-haul passenger volume.
- Railways:High-speed and urban rail networks demand continuous welded track, electrification systems, and tunnel-boring capacity. The Yangtze River Delta cluster spanning Shanghai, Nanjing, and Hangzhou concentrates expansion capital as municipal governments prioritize subway systems over road expansion to meet air quality targets.
- Highways:Expressway and arterial road construction employs asphalt concrete paving and reinforced concrete bridge structures. Western provinces including Sichuan and Yunnan sustain project backlogs despite talent scarcity for complex geotechnical engineering.
- Bridges:Cable-stayed and suspension systems span navigable waterways and deep valleys. Coastal provinces leverage port engineering heritage for marine construction contracts.
- Airports:Terminal buildings, runways, and apron systems require specialized pavement engineering and airside logistics integration. Pearl River Delta municipalities bundle operation rights with construction to attract private capital.
Railways anchor the volume base while urban rail transit gains share at the steepest rate.
Material Used:
Cost tier stratification separates premium-margin steel applications from commodity concrete and asphalt work, with recycled materials climbing the specification ladder under dual carbon procurement mandates.
- Steel:Structural sections, rebar, and bridge cables specified to GB standards for tensile strength and fatigue resistance. Price volatility compresses margins on fixed-price bridge and rail contracts.
- Concrete:Portland cement blends and precast formulations dominate highway and airport pavement construction. Low-emission cement variants gain procurement preference under central planner carbon reduction targets.
- Asphalt:Bituminous binders and polymer-modified surface courses for highway wearing layers. Jiangsu and Zhejiang transport bureaus specify precast alternatives for elevated expressways.
- Composites:Fiber-reinforced polymers and hybrid materials for bridge decks and corrosion-resistant applications. Coastal megaprojects in Guangdong and Fujian pilot stricter GB 55015-2021 thermal performance requirements.
Concrete sustains the broadest application footprint while low-carbon steel variants climb specification priority fastest.
Construction Method:
Application maturity separates legacy cast-in-place dominance from emerging prefabricated and modular systems, with labor cost pressures accelerating methodology transition.
- Prefabricated:Factory-cast bridge segments, tunnel lining rings, and building modules assembled on-site. Parallel workstreams compress timelines as quality standardization tightens across the sector.
- Conventional:Cast-in-place concrete and field-welded steel erection using traditional formwork and scaffolding. Labor dependency rises relative to manufacturing-integrated competitors.
- Modular:Standardized structural units for rapid deployment in remote or constrained sites. Belt and Road Initiative corridors through Xinjiang and Gansu demand rail-electrification specialists with modular installation capacity.
- Innovative:Digital fabrication, 3D printing, and on-site robotics for complex geometries. BIM platform convergence with IoT sensor networks enables predictive maintenance contracting.
Conventional methods retain the largest installed base while prefabricated techniques expand most quickly.
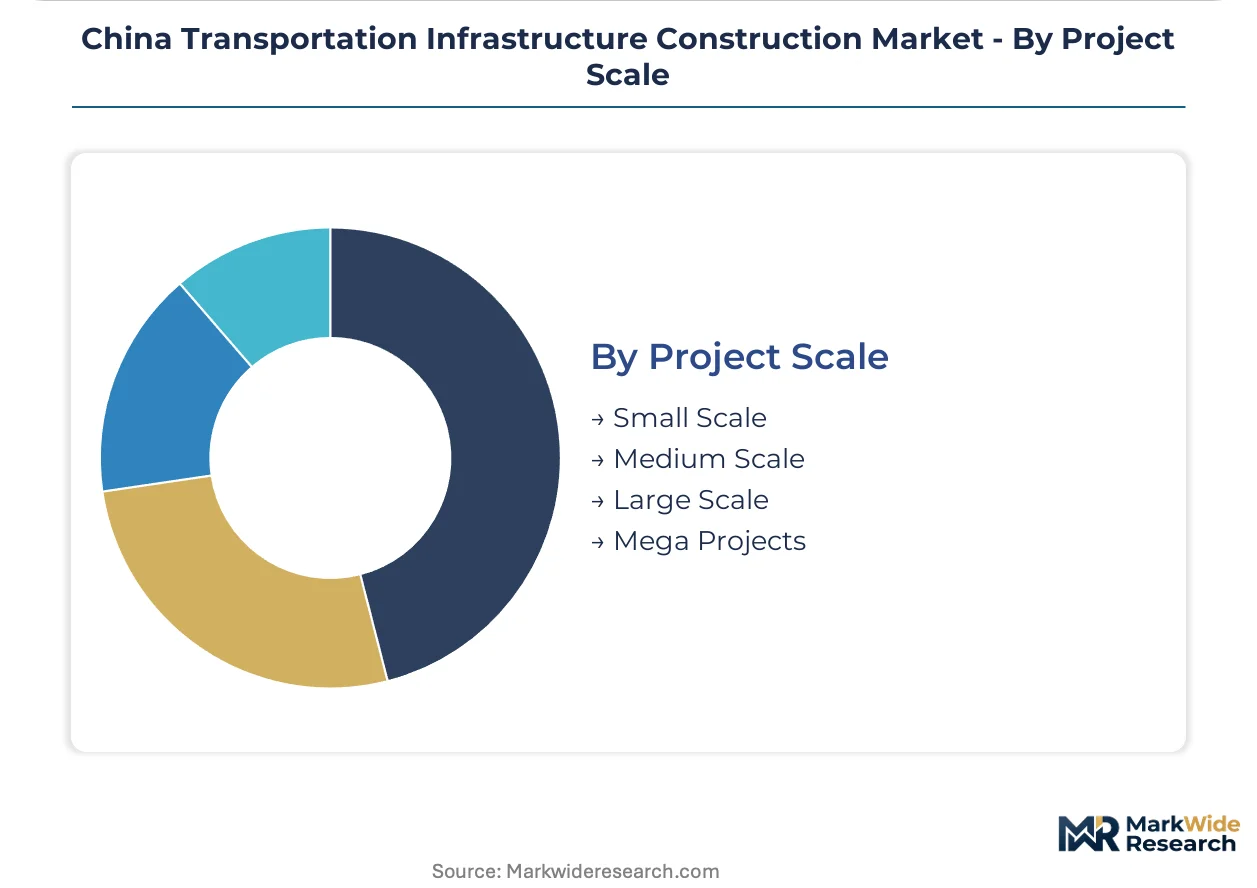
Project Scale:
Customer type stratification channels state-backed credit toward mega projects while municipal governments and private operators populate smaller tiers with fragmented financing structures.
- Mega Projects:Cross-regional high-speed rail lines, international airports, and trans-provincial highway corridors. State-backed credit facilities disproportionately finance these assets.
- Large Scale:Urban ring roads, metro line extensions, and major river crossings. Provincial debt restructuring constrains credit availability in interior regions.
- Medium Scale:District road networks, light rail segments, and municipal bridge replacements. Public-private partnership structures fragment traditional state-led financing in the Pearl River Delta.
- Small Scale:Local access roads, pedestrian infrastructure, and maintenance renewals. Municipal budgets face pressure from LGFV liability management.
Mega projects command the deepest financing pools while medium-scale assets attract the most diversified capital structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards issued by SAMR and the Ministry of Transport anchor procurement specifications across China's transportation infrastructure sector. Provincial governments in the Yangtze River Delta and Pearl River Delta megacity clusters command disproportionate financing access for urban rail expansion. Western provinces face compressed credit availability amid local government financing vehicle restructuring.
Yangtze River Delta
Shanghai, Nanjing, and Hangzhou absorb rising capital commitments for subway and light rail networks as municipal governments prioritize congestion reduction. Dual carbon goals redirect procurement toward low-emission cement and recycled steel specifications. The cluster's transport bureaus now mandate precast box girder systems for elevated expressway construction.
Pearl River Delta
Guangdong and Fujian coastal megaprojects pilot accelerated GB 55015-2021 thermal performance compliance timelines. Municipal governments bundle operation rights with construction contracts to attract private capital for intercity rail links. Shenzhen and Guangzhou lead specification tightening for low-carbon envelope materials in rail stations.
Sichuan-Chongqing
Complex geotechnical engineering demands in mountainous terrain strain the limited pipeline of certified tunneling specialists. Provincial debt overhang constrains credit availability for Belt and Road Initiative freight corridor extensions. Chengdu's urban rail expansion competes with western corridor rail-electrification projects for engineering talent.
Beijing-Tianjin-Hebei
State-backed credit facilities disproportionately finance mega-project rail assets connecting the capital region. Ministry of Housing and Urban-Rural Development technical circulars extend energy efficiency standards to airport terminals and high-speed rail stations. Tianjin's port engineering heritage supports marine infrastructure bids for coastal bridge construction.
Shandong Peninsula
Jiangsu and Zhejiang transport specifications drive prefabricated bridge segment manufacturing adoption across northern coastal provinces. Qingdao and Yantai manufacturing bases supply modular structural units for rapid deployment in constrained sites. Regional contractors face margin compression from steel price volatility on fixed-price highway contracts.
China Transportation Infrastructure Construction Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with state-affiliated contractors dominating mega-project financing access. The structure concentrates capability in firms with captive track-laying equipment fleets and port engineering heritage. Strategic archetypes include vertically integrated construction-manufacturing hybrids, railway-specialized engineering groups, and coastal marine infrastructure specialists. Competitive moves center on prefabrication capacity expansion and digital twin platform partnerships.
Among state-affiliated construction groups, China Communications Construction Company Limited and China State Construction Engineering Corporation exemplify the integrated leader tier with manufacturing-anchored positioning. China Railway Group Limited occupies a specialist position anchored by railway engineering concentration. These entities represent how certification depth under GB standards filters market access toward contractors with quality management scale.
| Leading Market Players |
|---|
| China Communications Construction Company Limited |
| Shanghai Construction Group |
| China State Construction Engineering Corporation |
| China Metallurgical Group Corporation |
| China Road & Bridge Corporation |
| China Railway Group Limited |
| Power Construction Corporation of China |
| China Gezhouba Group Corporation Limited |
| China Railway Construction Corporation |
| Others |
Value Chain & Pricing Dynamics
Low-emission cement substitution for conventional Portland blends simultaneously shifts procurement geography toward certified green suppliers and compresses margin structures on fixed-price highway contracts. Steel price volatility feeds directly into bridge and rail project economics, forcing contractors to renegotiate terms or absorb cost swings.
Pricing Analysis
Coastal megaprojects in Guangdong and Fujian command 15-20% premiums over interior province bids due to stricter GB 55015-2021 compliance timelines and logistics costs. Project-based contract structures dominate, with price differentiation resting on certification depth under Ministry of Transport standards and manufacturing scale for prefabricated components. Cost compression in steel-intensive segments is intensifying because of fixed-price terms against volatile input markets. Municipal governments in the Yangtze River Delta show lowest price sensitivity due to state-backed credit access, while western provincial transport bureaus face acute budget constraints.
Supply Chain Analysis
Steel inventory cycles extending beyond 90 days strain working capital for contractors locked into fixed-price commitments. Domestic supply concentrates in Hebei and Jiangsu for structural steel, with coastal provinces drawing from captive port engineering manufacturing bases. Raw material dependencies center on iron ore imports, coking coal, and low-emission cement clinker. Single-source vulnerability runs through specialized tunnel-boring equipment fleets controlled by China Railway Group Limited. Distribution runs through state-affiliated procurement consortia that filter contractor access based on GB certification depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against prefabricated construction methodologies that displace traditional cast-in-place execution. Incumbents must navigate the shift toward manufacturing-integrated competitors or face margin erosion.
For Market Incumbents: Consolidate prefabrication capacity through backward integration into modular bridge segment manufacturing in Jiangsu and Zhejiang. Deepen GB standards certification under SAMR technical circulars to maintain procurement access as quality barriers tighten. The threat of manufacturing-integrated competitors with captive production assets demands rapid capability acquisition.
For New Entrants and Emerging Players: Differentiate on digital twin integration for predictive maintenance contracting in the Yangtze River Delta urban rail expansion. Target western corridor rail-electrification projects in Xinjiang and Gansu where Belt and Road Initiative freight demand outpaces certified specialist supply. White-space positioning in modular installation for constrained geotechnical sites offers the most penetrable entry path.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with provincial construction groups burdened by local government financing vehicle debt restructuring. Long-term viability hinges on manufacturing scale and certification depth rather than pure field execution capacity. Watch for provincial transport bureau procurement mandate shifts toward precast specifications as the inflection indicator for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Capacity Expansion | Factory-controlled quality compresses timelines as labor costs rise across eastern provinces. |
| GB Standards Certification Investment | SAMR and Ministry of Transport requirements filter market access toward qualified contractors. |
| Digital Twin Platform Partnership | BIM-IoT convergence enables predictive maintenance contracts on long-life rail assets. |
| Western Corridor Rail-Electrification Buildout | Belt and Road Initiative freight corridors through Xinjiang demand specialized installation capacity. |
| Low-Carbon Material Supplier Integration | Dual carbon procurement mandates redirect specifications toward certified green cement and recycled steel. |
Study Parameters
A spread of perspectives from project directors at state-affiliated construction groups, procurement officers at municipal transport bureaus, geotechnical engineering specialists, and steel trading desk analysts converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through Ministry of Transport project disclosure databases, SAMR GB standards filings, provincial statistical yearbooks, and customs records for steel and cement trade flows. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation anchored volume estimates.
Infrastructure type, material specification, construction methodology, and project scale dimensions structured the analytical framework across the projection horizon. CAGRs derived from historical completion trajectories and announced capital commitment pipelines. Forecast inputs incorporated provincial debt restructuring timelines, dual carbon procurement mandate rollout schedules, and certified engineering talent pipeline constraints in western provinces.
Material uncertainties — provincial financing vehicle liquidity crises, steel price volatility spikes, and GB standards enforcement acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about state-backed credit continuity and municipal rail expansion prioritization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Ship Port Infrastructure Market