
 Europe Construction Equipment Market | 2026-2036
Europe Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Construction Equipment Market Analysis
Equipment leasing and project-linked financing is narrowing the capital barrier for mid-tier contractors seeking fleet modernization. Volvo Construction Equipment leverages its electrified excavator line to anchor Nordic infrastructure tenders. Liebherr Group sustains crane dominance through in-house component production and German manufacturing scale. JCB competes aggressively on compact electric loaders aimed at urban demolition restrictions.
Europe construction equipment encompasses self-propelled and towed machinery engineered for earthmoving, lifting, and material placement, with operating weights spanning 1.5 tonnes for mini-excavators to over 800 tonnes for heavy-lift crawler cranes, typically powered by diesel engines or battery-electric drivetrains meeting Stage V emission thresholds. These machines serve civil engineering, building construction, and extractive industries where productivity metrics center on cycle time, fuel efficiency, and uptime availability. Excavators command the largest installed base across European rental fleets, though electric and hybrid technology segments are expanding fastest as urban emission zones proliferate. Earthmoving applications generate steady replacement demand, while material handling equipment captures premium margins in ports and logistics hubs.
The EU Green Deal's carbon border mechanism and Stage V emission standards enforced by national regulators reshape fleet procurement priorities toward lower-carbon alternatives. CE marking under the EU Machinery Directive governs safety compliance, while national construction codes in France, Germany, and Italy dictate specific equipment certifications for public works. Stakeholders must monitor battery supply chain localization and charging infrastructure buildout as electrification transitions from municipal pilot projects to mainstream fleet economics.
Market Dynamics
The EU Green Deal's carbon border adjustments and Stage V emission standards are compressing diesel equipment residual values while accelerating electric and hybrid fleet turnover across German, French, and Nordic civil engineering corridors.
Growth Catalysts
- Renewable energy infrastructure buildout:German offshore wind and Spanish solar installations are expanding crawler crane and heavy-lift equipment deployment cycles.
- EU Green Deal carbon border mechanism:Fleet operators face direct cost pressure on high-emission imports, redirecting procurement toward battery-electric excavators and hybrid loaders.
- Nordic tunneling programs:Norway's Rogfast and Finland's Helsinki-Tallinn link are sustaining demand for specialized boring machinery and ground support equipment.
Market Restraints
- Battery supply chain concentration:European cell manufacturing capacity lags fleet electrification timelines, creating procurement bottlenecks for mid-tier rental companies.
- Stage V compliance costs:Aftertreatment systems and particulate filters add 15-25% to diesel equipment first cost, squeezing margins on compact machinery.
- Skilled operator scarcity:Germany's construction sector reports persistent vacancies for certified crane and tunneling equipment operators, constraining fleet utilization rates.
Strategic Opportunities
- Polish and Romanian highway expansion:EU cohesion fund allocations for Trans-European Transport Network corridors are opening equipment demand outside mature Western markets.
- Telematics-integrated predictive maintenance:OEMs are bundling IoT-enabled uptime guarantees, shifting revenue from unit sales to service contracts.
- Urban emission zone proliferation:Paris, London, and Amsterdam zero-emission zones are creating captive demand for electric compact excavators and wheel loaders.
Industry Challenges
- CE marking timeline compression:Machinery Directive conformity assessments for novel electric drivetrains are extending time-to-market by 6-12 months.
- Legacy fleet interoperability:Mixed diesel-electric job sites require dual maintenance protocols and charging infrastructure, complicating site logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Construction Equipment Market |
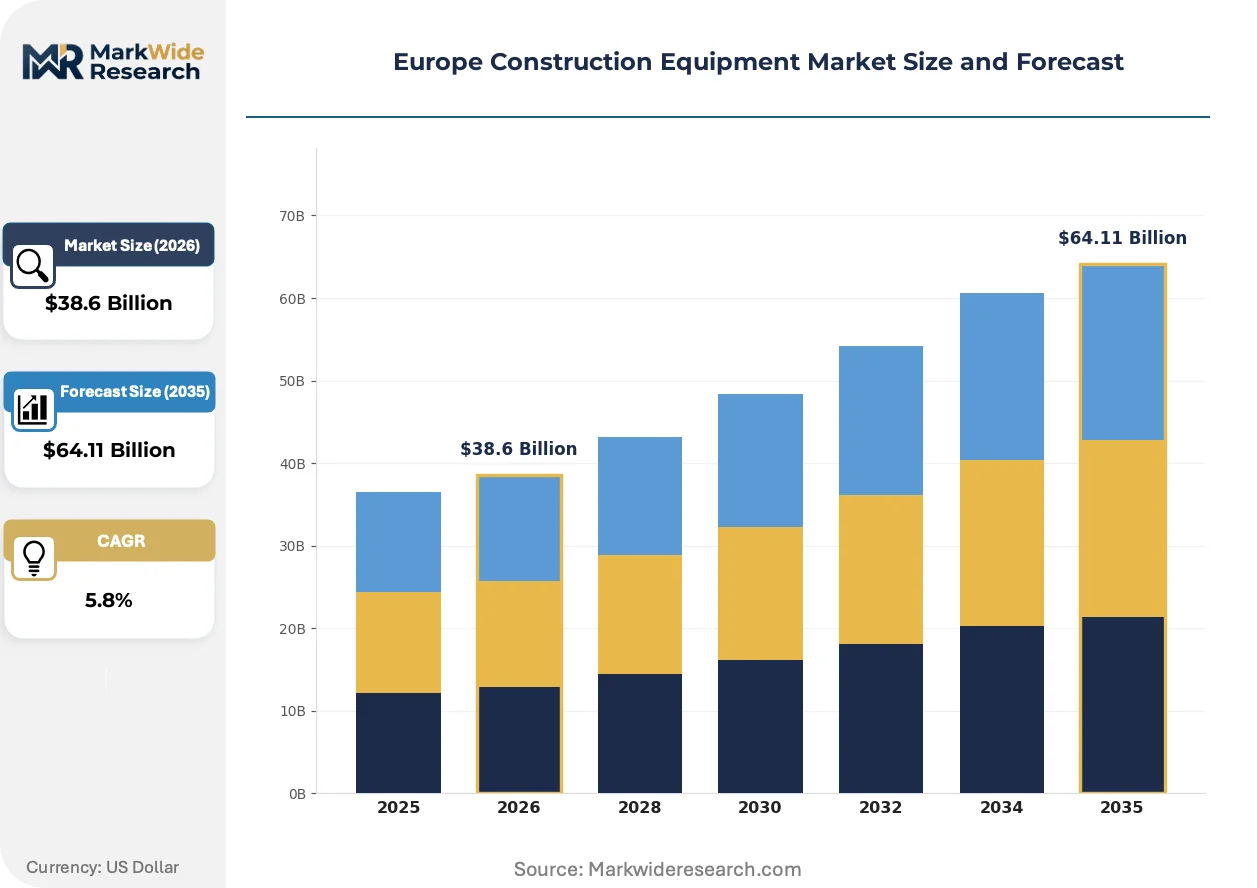
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Cranes, Bulldozers End User: Residential, Commercial, Infrastructure, Industrial Application: Earthmoving, Material Handling, Demolition, Mining Technology: Telematics, Autonomous, Hybrid, Electric |
| Companies Covered | Liebherr Group, Volvo Construction Equipment, Caterpillar Inc., CNH Industrial, JCB, Komatsu Ltd., Wacker Neuson, Manitou Group, Hitachi Construction Machinery, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Construction Equipment Market Emerging Trajectories
Electrification architectures, regulatory compliance automation, and servitization business models are converging to reshape equipment economics and competitive differentiation across European markets.
Battery-electric excavator technology is hybridizing through modular pack designs that allow rapid swap-out for continuous operation on constrained urban sites. German civil engineering contractors are piloting these systems on Berlin and Munich metro extensions, compressing project schedules previously limited by diesel emission curfews and refueling logistics.
The EU Green Deal's carbon border adjustment mechanism is forcing fleet operators to document embedded emissions across supply chains. This regulatory pressure is most acute for imported steel components in crawler cranes and piling rigs, pushing manufacturers toward localized forging partnerships and scrap-based electric arc furnace sourcing.
Rental companies are unbundling maintenance from equipment leases, selling uptime availability rather than machine hours. This model is displacing traditional dry-hire arrangements in UK and Dutch infrastructure tenders, where public sector clients now specify guaranteed availability clauses with penalty structures for downtime exceeding contractual thresholds.
Europe Construction Equipment Market Segmentation
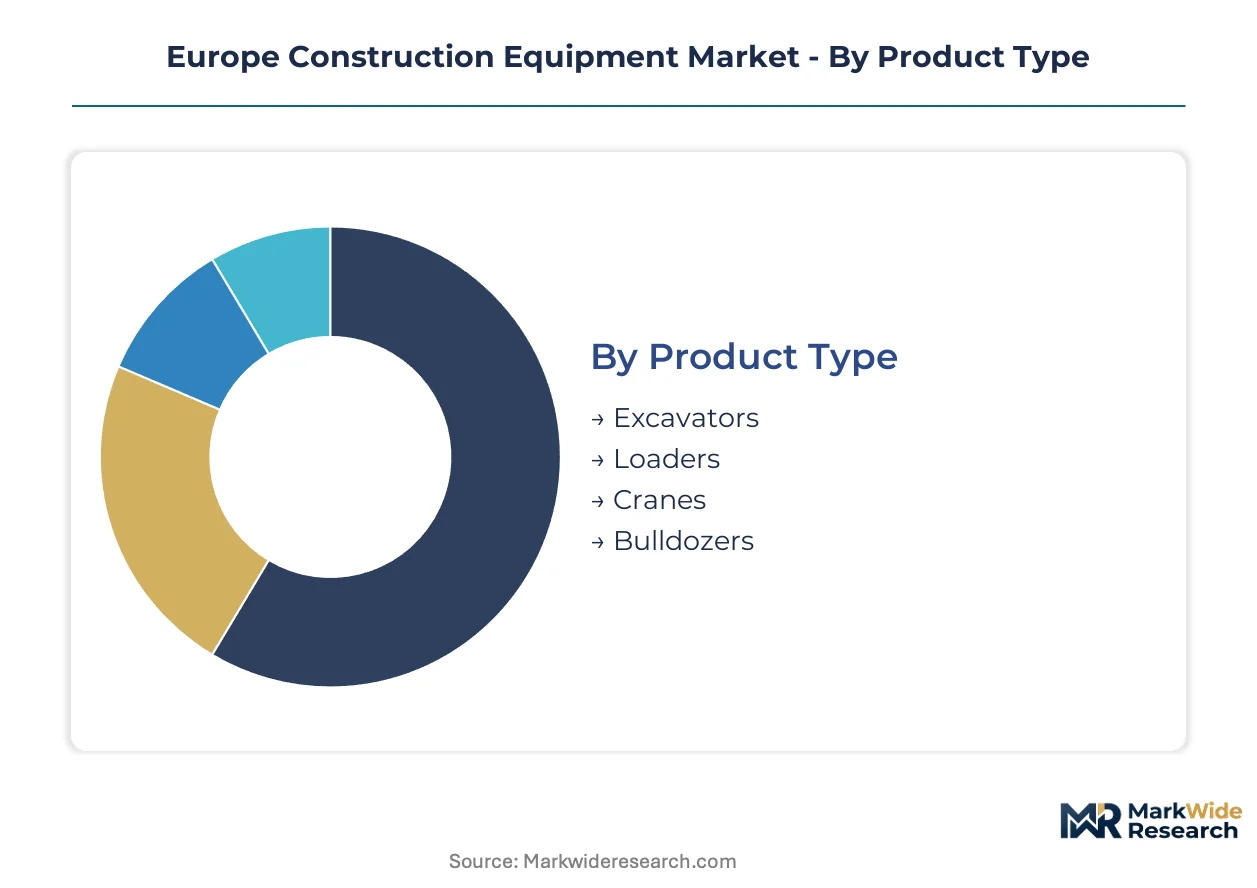
Segmentation reveals how equipment procurement patterns diverge across project scales, regulatory environments, and technology readiness. Each dimension exposes distinct margin structures and replacement cycles that shape manufacturer and rental fleet strategies.
Product Type:
Equipment categories stratify by operating weight, duty cycle intensity, and attachment versatility, creating tiered margin profiles across rental and ownership models.
- Excavators:Hydraulic machines with operating weights from 1.5 tonnes to 90 tonnes, configured with boom-mounted buckets or specialized attachments. German and French civil engineering corridors drive replacement demand as Stage V compliance accelerates fleet turnover in urban emission zones.
- Loaders:Wheeled and tracked configurations for bulk material movement, with articulated steering and variable payload ratings. Nordic tunneling programs and Spanish port logistics sustain premium pricing for high-uptime units with telematics integration.
- Cranes:Mobile all-terrain and crawler configurations for vertical lift operations, spanning 25-tonne to over 800-tonne capacity classes.
- Bulldozers:Tracked dozers with blade attachments for grading and earth push operations, concentrated in mining and large-scale site preparation.
Excavators command the established base. The steepest expansion runs through cranes.
End User:
Customer archetypes differ in financing sophistication, fleet utilization patterns, and sensitivity to total cost of ownership versus upfront capital constraints.
- Residential:Single-family and multi-unit housing developers deploying compact equipment for foundation work and site grading. Amsterdam and Paris zero-emission zones are mandating electric compact excavators, reshaping rental procurement for mid-tier housing contractors.
- Commercial:Office, retail, and hospitality construction requiring medium-duty earthmoving and material placement. German commercial builders are consolidating equipment leases under project-linked financing to preserve working capital for land acquisition.
- Infrastructure:Public works and utility-scale projects with extended timelines and availability-guarantee contracting.
- Industrial:Manufacturing facility construction and process plant maintenance with specialized lifting and precision grading requirements.
Infrastructure commands the established base. The steepest expansion runs through residential.
Application:
Functional use cases determine equipment specification, attachment configuration, and operating environment constraints that shape manufacturer R&D priorities.
- Earthmoving:Bulk soil and aggregate displacement using excavators, dozers, and scrapers with high-duty cycle ratings. Polish and Romanian highway expansion under EU cohesion funding is redirecting earthmoving fleet deployment eastward from saturated Western corridors.
- Material Handling:Port, logistics, and waste transfer operations requiring wheel loaders and telehandlers with rapid cycle characteristics. Rotterdam and Hamburg port electrification mandates are accelerating battery-electric loader pilots with opportunity charging infrastructure.
- Demolition:Decommissioning and site clearance with specialized high-reach excavators and hydraulic attachments.
- Mining:Surface extraction and quarry operations with ultra-class haulage and loading configurations.
Earthmoving commands the established base. Material handling is gaining share fastest.
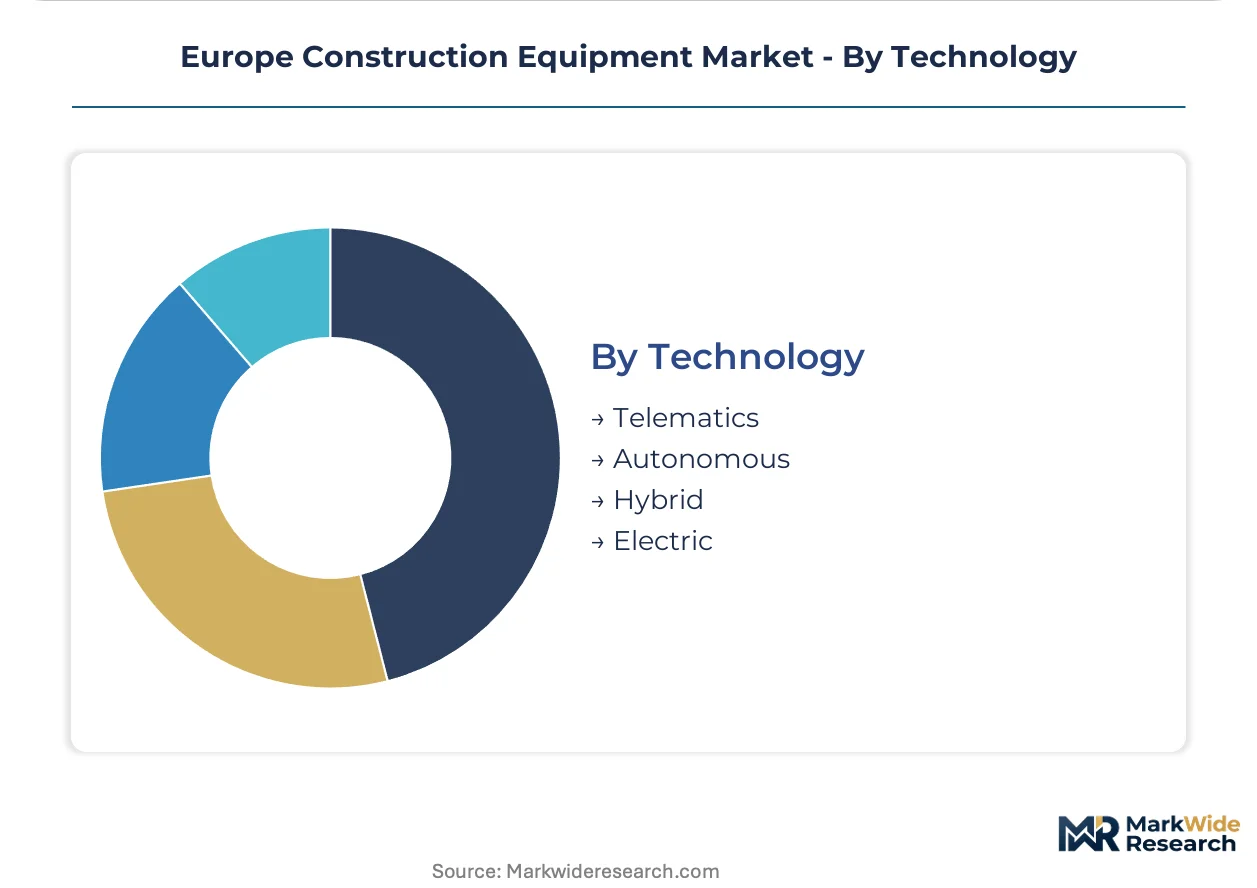
Technology:
Technology tiers segment by data integration depth, automation level, and powertrain architecture, each carrying distinct certification timelines and operator training requirements.
- Telematics:GPS-enabled fleet monitoring with engine diagnostics, geofencing, and utilization tracking transmitted to cloud platforms. UK and Dutch infrastructure tenders now mandate uptime availability clauses backed by real-time telemetry, displacing traditional dry-hire arrangements.
- Electric:Battery-electric drivetrains with zero tailpipe emissions, ranging from compact excavators to mid-size wheel loaders. CE marking timelines for novel electric drivetrains are extending time-to-market, compressing first-mover advantage windows for early entrants.
- Hybrid:Diesel-electric powertrains with energy recovery and engine downsizing for variable load profiles.
- Autonomous:GPS-guided and sensor-fusion operation with remote supervision or programmed mission execution.
Telematics commands the established base. Electric is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's construction equipment trade flows reveal a structural deficit in battery-electric components and specialized attachments, with German and Swedish OEMs exporting high-value cranes and excavators while importing lithium-ion cells and hydraulic systems from Asian suppliers. This import dependency is reshaping procurement timelines and localization strategies across the continent.
Germany
Offshore wind installation contracts in the North Sea are sustaining heavy-lift crawler crane utilization rates above regional averages. The KBA enforces Stage V emission compliance with mandatory periodic technical inspections for diesel-powered equipment operating in urban zones. Bavaria's Munich-Stuttgart corridor hosts concentrated demand for electrified compact excavators driven by municipal emission restrictions and metro expansion projects.
France
Nuclear plant maintenance programs and railway modernization are generating steady demand for specialized lifting and earthmoving fleets. ANSM-aligned safety protocols under the EU Machinery Directive extend certification timelines for autonomous and electric equipment variants. The Île-de-France region around Paris enforces the strictest zero-emission zones, mandating battery-electric compact loaders and excavators for public works contracts.
United Kingdom
HS2 rail infrastructure and offshore wind interconnectors are extending deployment cycles for tunnel boring machinery and heavy-transport systems. The Health and Safety Executive coordinates with CE marking requirements to enforce operator certification standards for crane and piling equipment. The Midlands manufacturing cluster around Birmingham is consolidating equipment rental capacity to serve cross-border infrastructure tenders.
Spain
Utility-scale solar installations across Andalusia and Extremadura are accelerating demand for pile-driving rigs and mobile cranes with rapid site relocation capabilities. National construction codes aligned with EU Green Deal carbon accounting require embedded emissions documentation for imported steel components. The Madrid-Barcelona logistics corridor is piloting opportunity-charging infrastructure for electric wheel loaders serving port and distribution center operations.
Poland
EU cohesion fund allocations for Trans-European Transport Network highways are redirecting earthmoving fleet deployment eastward from saturated Western markets. The country's national construction regulator enforces CE marking conformity for public works equipment with escalating technical documentation requirements. The Silesian and Lower Silesian voivodeships are emerging as equipment distribution hubs serving Baltic corridor infrastructure programs.
Europe Construction Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on hydraulic systems, powertrain modules, and telematics platforms. The European construction equipment sector consolidates around full-line manufacturers with captive distribution networks and specialized attachment producers serving rental fleet customization. Three archetypes dominate: diversified industrial conglomerates with construction divisions, pure-play equipment specialists with regional manufacturing footprints, and technology-forward entrants commercializing electric drivetrains. Competitive intensity centers on electrification speed-to-market and servitization contract structures that displace traditional equipment sales with uptime guarantees.
Within the diversified industrial tier, Liebherr Group and Volvo Construction Equipment exemplify platform integrators with vertically integrated component production and established rental channel relationships. Caterpillar Inc. anchors the multinational machinery archetype with extensive dealer networks spanning European infrastructure corridors. JCB occupies a position within the specialized compact equipment segment, representing mid-market positioning focused on urban emission zone compliance and municipal contracting requirements.
| Leading Market Players |
|---|
| Liebherr Group |
| Volvo Construction Equipment |
| Caterpillar Inc. |
| CNH Industrial |
| JCB |
| Komatsu Ltd. |
| Wacker Neuson |
| Manitou Group |
| Hitachi Construction Machinery |
| Others |
Supply Flow & Price Mechanics
The Silesian manufacturing cluster's hydraulic component capacity determines margin compression thresholds for mid-tier excavator producers across Polish and Romanian highway programs. Battery cell import dependencies from Asian suppliers concentrate pricing power upstream, forcing European OEMs to absorb currency volatility or pass through cost increments to rental fleet operators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered discount ladders. Pricing stratifies across premium, standard, and economy tiers based on Stage V certification grade and telematics integration depth. Cost compression in compact machinery intensifies as aftertreatment system expenses squeeze margins on sub-10-tonne excavators. Municipal contractors exhibit highest price sensitivity due to constrained public procurement budgets, while infrastructure consortiums prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Export control regimes on advanced battery management systems and high-grade hydraulic valves constrain technology transfer from German and Swedish engineering centers to emerging assembly operations. Component sourcing draws from China for lithium-ion cells, South Korea for power electronics, and Germany for precision hydraulics. Single-source vulnerability concentrates in battery pack assembly where European cell manufacturing lags fleet electrification timelines. Distribution runs through captive OEM dealer networks serving rental fleet operators and direct procurement by infrastructure consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
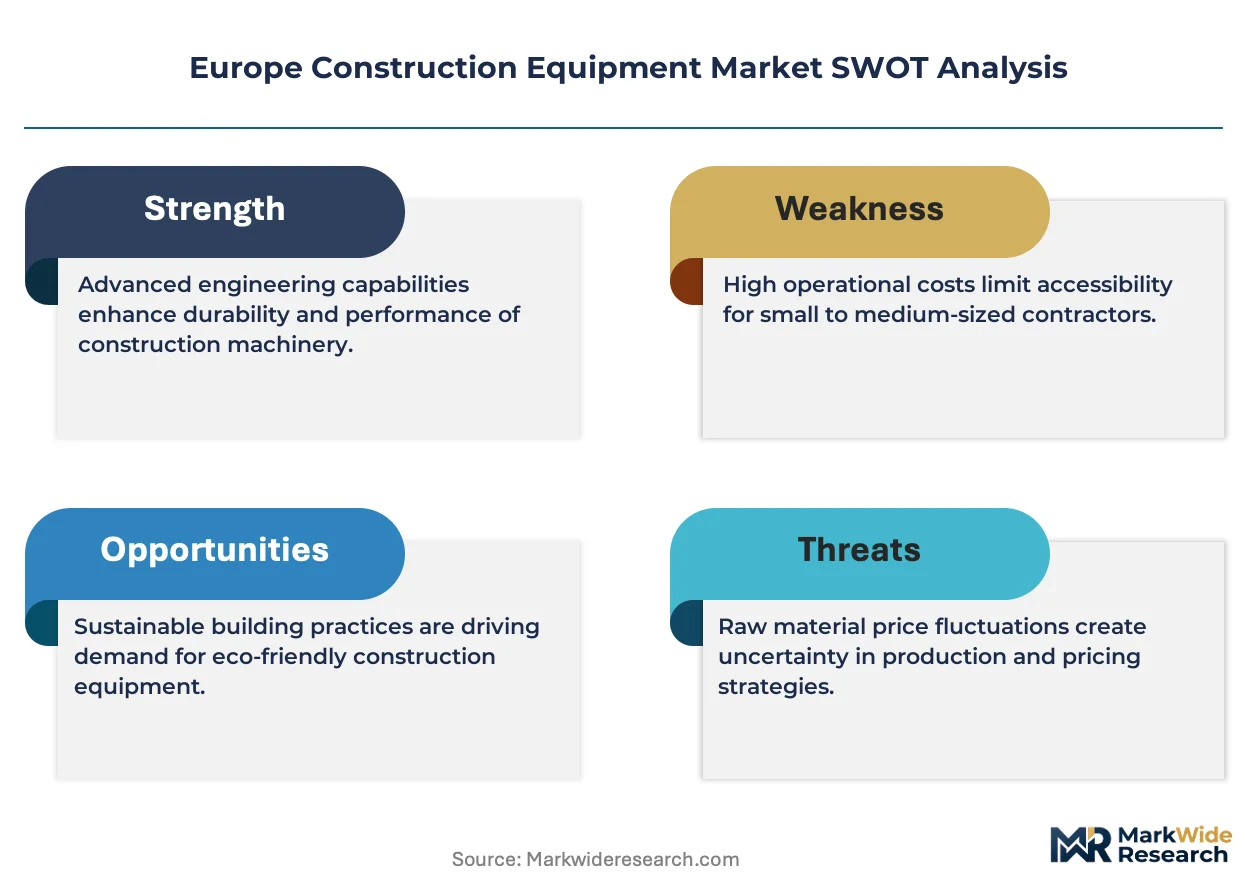
The Europe construction equipment market functions as a defensive-moat arena where regulatory entrenchment around Stage V compliance and CE marking creates durable barriers against unqualified entrants. Switching costs for rental fleet operators rise with telematics integration depth and certified service network coverage.
For Market Incumbents: Build certification moats through accelerated CE marking investment for electric drivetrain variants before regulatory timeline compression widens. Deepen backward integration into battery pack assembly to reduce Asian cell supplier dependency. Threaten margin erosion from Chinese electric excavator entrants targeting municipal procurement. Leverage captive service networks to lock rental operators into uptime-guarantee contracts. For New Entrants and Emerging Players: Romanian and Bulgarian equipment distribution channels remain underpenetrated by full-line OEMs despite EU cohesion fund highway allocations. Target electric compact loader pilots in Amsterdam and Paris zero-emission zones where incumbent diesel legacy fleets face deployment restrictions. Partner with Polish regional banks to structure project-linked financing for mid-tier contractors outside established Western leasing networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with captive hydraulic system production and electric drivetrain engineering capabilities. Long-term viability hinges on servitization contract scaling and battery supply chain localization progress. Acquisition targets include telematics platform developers and battery swap infrastructure providers. Monitor charging infrastructure buildout velocity in German urban emission zones as inflection signal for electric fleet economics mainstreaming.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell volumes from South Korean producers for German excavator electrification programs. |
| Servitization Contract Expansion | Shifts revenue from unit sales to uptime guarantees under UK infrastructure tender requirements. |
| CE Marking Acceleration | Compresses time-to-market for electric drivetrain variants ahead of Machinery Directive timeline extensions. |
| Telematics Platform Integration | Enables predictive maintenance bundling under Dutch availability-guarantee contracting structures. |
| Charging Infrastructure Partnership | Deploys opportunity-charging networks for electric wheel loaders across Rotterdam and Hamburg port operations. |
Methodological Framework
Desk research of EU Machinery Directive filings, customs trade databases, and national construction regulator technical documentation preceded structured interviews with rental fleet procurement directors, OEM aftermarket service heads, and infrastructure project equipment managers. Primary fieldwork captured utilization rate data and replacement cycle intentions across German, French, and Nordic civil engineering corridors. Secondary validation drew from KBA emission inspection records, CE marking conformity assessment registries, and EU cohesion fund allocation disclosures. Bottom-up equipment deployment estimates triangulated against top-down market value reconstruction.
Forecast assumptions held EU Green Deal carbon border mechanism enforcement timelines and Stage V compliance deadlines fixed across the modeling period. Segmentation modeling incorporated product type, end-user archetype, application function, and technology tier dimensions alongside regional regulatory cluster differentiation. CAGRs derived from equipment stock turnover analysis and electrification penetration curve fitting. Industry-specific inputs included offshore wind installation contract awards and tunneling program funding authorizations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese electric equipment manufacturers or accelerated European cell manufacturing localization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Boring Bar Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
North America Mobile Crane Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Truck Crane Market
Construction Equipment
Garage Equipment Market